
 Digital Farming Technology Market | 2026-2036
Digital Farming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Farming Technology Market Insights
Modular sensor-to-cloud bundling is repositioning how mid-size farms evaluate platform economics. Deere & Company leverages its proprietary Operations Center to anchor subscription retention across North American dealer networks. AGCO Corporation competes through Fuse open-architecture partnerships that let third-party devices integrate without proprietary lock-in. Trimble Inc. differentiates via GNSS correction services that sustain centimeter-level accuracy for autosteer applications.
Digital farming technology encompasses hardware, software, and connectivity systems that collect, transmit, and analyze agronomic data to optimize input application and harvest timing. Core specifications include sub-inch RTK-GPS accuracy, multispectral imaging bands from 450-850 nanometers, and edge-computing nodes processing field data at under 50-millisecond latency for real-time implement control. IoT Solutions and Sensors command the installed base due to decade-long depreciation cycles on soil probes and weather stations, while Robotics represents the fastest-expanding margin pool as labor costs escalate in specialty crop sectors. Subscription-Based delivery now dominates enterprise accounts where annual recurring revenue models align technology spend with seasonal cash flows.
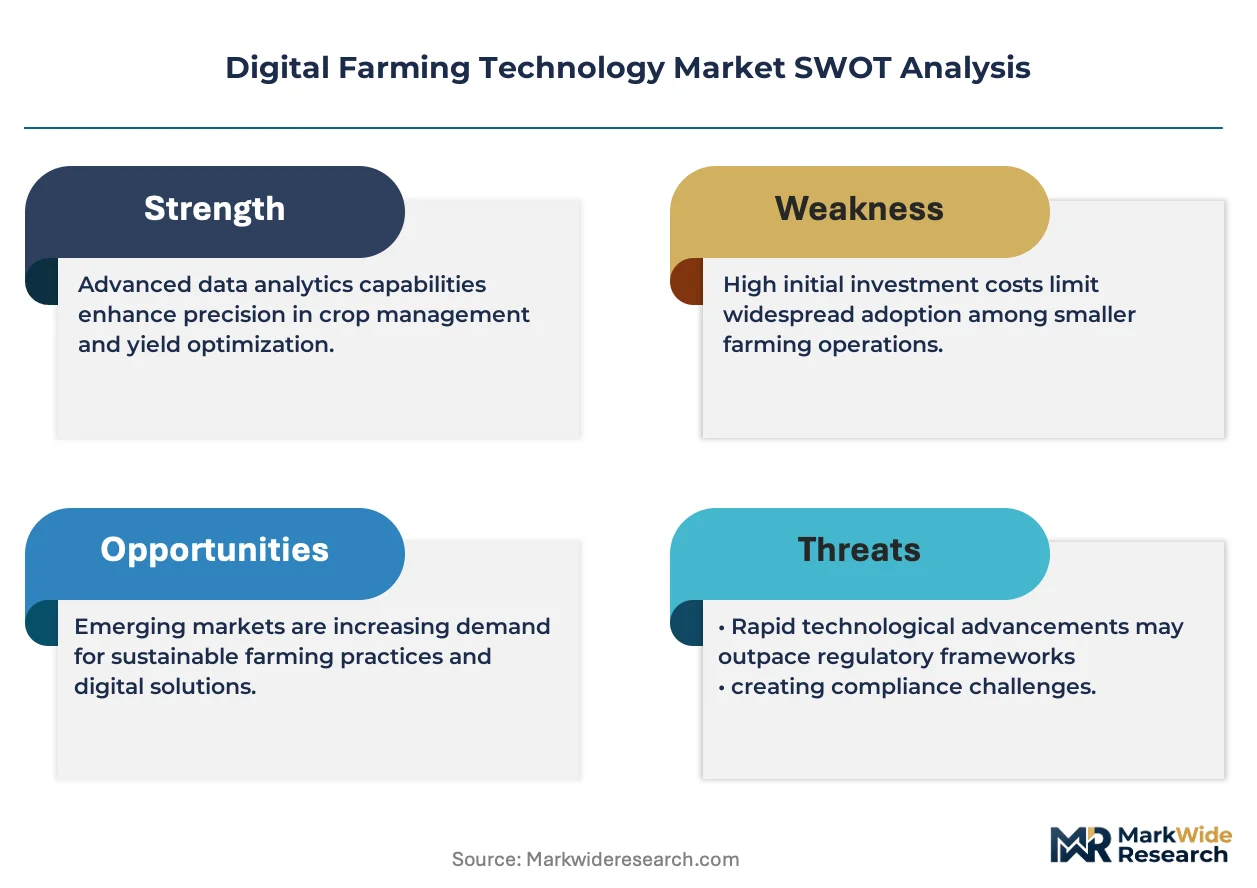
The EPA regulates pesticide application rates that drone-based variable-rate systems must document for compliance, while the USDA's Climate-Smart Agriculture initiative shapes cost-share eligibility for sensor deployments. The EU Green Deal's Farm to Fork strategy mandates 50% pesticide reduction targets that only precision application technologies can realistically achieve, redirecting R&D budgets toward compliance-native platforms. Stakeholders must monitor whether carbon credit verification standards fragment across jurisdictions or converge into tradable protocols that reward documented yield-efficiency improvements.
Market Dynamics
The EU Green Deal's Farm to Fork pesticide reduction mandate is compressing adoption timelines for precision application platforms across input-intensive cropping systems. Compliance-native architectures now determine platform viability before commercial deployment.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The 50% pesticide reduction target redirects capital toward variable-rate application systems that document compliance automatically.
- Mato Grosso Soybean Belt:Commercial operators digitizing harvest logistics generate concentrated demand for integrated fleet management and yield mapping platforms.
- RTK-GPS Correction Networks:Centimeter-level accuracy for autosteer applications reduces overlap waste and input costs in large-scale grain operations.
Market Restraints
- Connectivity Infrastructure Gaps:Rural cellular dead zones in Brazil's interior and Australia's wheat belt limit real-time cloud synchronization for edge-computing nodes.
- Silicon Supply Concentration:Semiconductor fabrication for multispectral imaging sensors concentrates in East Asian foundries, exposing hardware margins to geopolitical disruption.
- Depreciation Cycle Lock-in:Decade-long replacement cycles for soil probes and weather stations delay subscription revenue recognition for platform vendors.
Strategic Opportunities
- USDA Climate-Smart Agriculture Initiative:Cost-share eligibility for sensor deployments creates subsidized entry points for mid-size operators previously priced out of precision platforms.
- Specialty Crop Labor Cost Escalation:California's tree nut and vineyard sectors accelerate robotics adoption as hand-harvesting costs outpace mechanization investment thresholds.
- Carbon Credit Verification Convergence:Documented yield-efficiency improvements may translate into tradable protocols, attaching new revenue streams to platform data.
Industry Challenges
- Interoperability Fragmentation:Proprietary data formats from Deere's Operations Center and AGCO's Fuse architecture force farmers into single-vendor ecosystems or expensive integration middleware.
- Agronomic Data Science Talent Scarcity:Platform vendors compete for scarce specialists capable of translating multispectral imagery bands into actionable nitrogen prescription maps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Farming Technology Market |
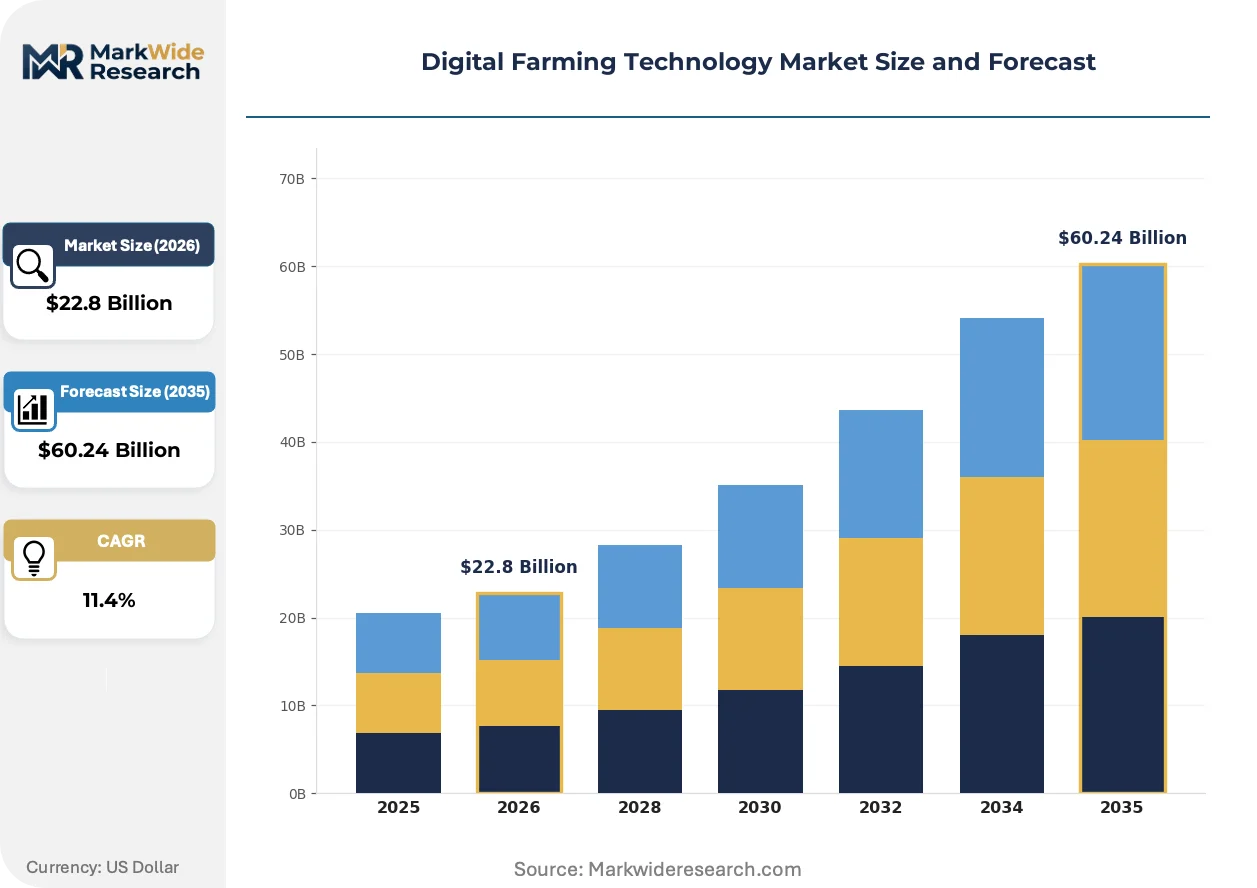
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Drones, Sensors, Robotics Application: Crop Monitoring, Soil Management, Yield Prediction, Pest Control End User: Farmers, Agronomists, Agricultural Cooperatives, Enterprises Delivery Model: Subscription-Based, One-Time Purchase, Freemium, License |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, Trimble Inc., Topcon Corporation, Kubota Corporation, Bayer AG, Syngenta Group, CLAAS KGaA mbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Farming Technology Market Trends and Innovations
Electrification of field machinery is reshaping power architecture requirements for implement control systems. Battery-electric tractors demand redesigned hydraulic interfaces and recalibrated torque curves for precision seeding operations.
Autonomous electric tractors from manufacturers including Monarch and Solectrac are electrifying the powertrain foundation of precision agriculture. Large-scale row-crop operators in California's Central Valley and the Netherlands' greenhouse clusters pilot these platforms for repetitive cultivation passes. The shift is compressing maintenance intervals and enabling continuous 24-hour operation windows that diesel engines cannot match.
The EU AI Act's risk classification framework for agricultural decision-support systems triggers compliance redesigns across European platform vendors. Algorithms generating variable-rate prescriptions now require documented training data provenance and human oversight protocols. German and French precision agriculture providers front-load regulatory documentation to maintain CE marking eligibility ahead of enforcement deadlines.
Consolidated buying cooperatives in the US Midwest now negotiate enterprise-wide platform licenses across multi-state operations. Dealer networks face margin compression as direct manufacturer subscriptions displace traditional equipment financing relationships. Iowa and Illinois grain cooperatives lead this procurement model evolution, bundling sensor hardware with cloud analytics under single annual contracts.
Digital Farming Technology Market Segmentation
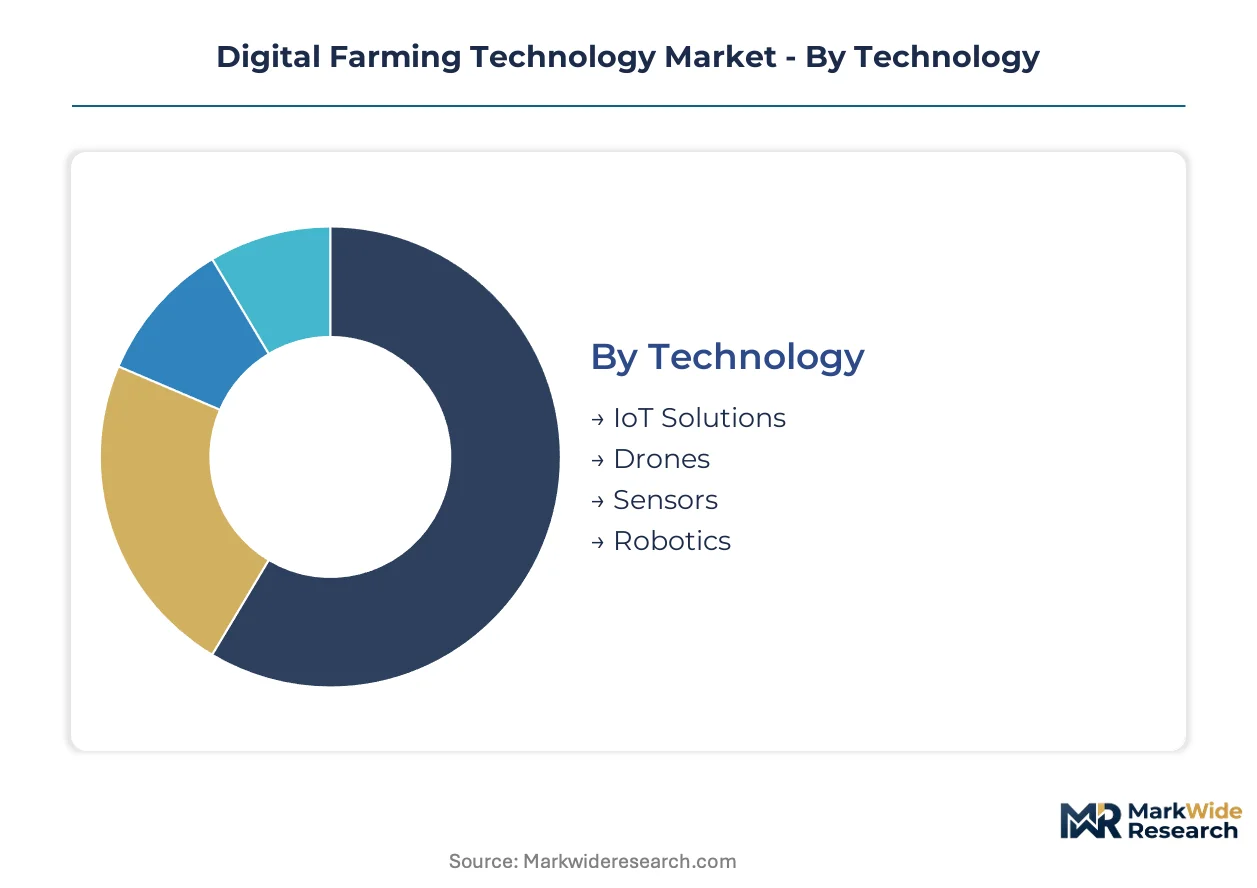
Segmentation in digital farming technology reveals how procurement priorities diverge between capital-constrained mid-size operators and enterprise-scale commercial farms. Technology buyers weigh depreciation cycles against recurring subscription burdens, while application focus shifts with crop type and regulatory compliance pressures.
Technology:
Capital allocation decisions hinge on hardware longevity versus software refresh rates, with buyers balancing upfront equipment costs against recurring platform fees.
- IoT Solutions:Edge-computing nodes and mesh networks process field data at sub-50-millisecond latency for real-time implement control. Demand concentrates in US Midwest grain operations where cellular connectivity supports continuous cloud synchronization. Depreciation cycles extending beyond seven years delay vendor revenue recognition.
- Robotics:Autonomous platforms integrate LiDAR, computer vision, and hydraulic interfaces for cultivation and harvesting operations. California tree nut growers and Dutch greenhouse operators deploy these systems as hand-harvesting labor costs exceed mechanization thresholds. Labor cost escalation in specialty crop sectors accelerates deployment timelines.
- Drones:Multispectral imaging platforms with 450-850 nanometer bands enable variable-rate pesticide application compliant with EPA documentation requirements.
- Sensors:Soil probes and weather stations form the installed base foundation with decade-long replacement cycles.
IoT Solutions leads on scale; Robotics leads on momentum.
Application:
Functional priority follows crop value intensity and input cost exposure, with high-value specialty crops commanding precision investment ahead of commodity grain systems.
- Crop Monitoring:Multispectral and thermal imaging systems track plant health indices across heterogeneous field conditions. Brazil's Mato Grosso soybean belt generates concentrated demand for integrated fleet management platforms that correlate imagery with yield mapping. Commercial operators digitizing harvest logistics require continuous field visibility.
- Pest Control:Drone-based variable-rate application systems document compliance with EPA pesticide rate regulations through automated flight logs and spray records. EU Green Deal Farm to Fork mandates for 50% pesticide reduction redirect R&D budgets toward precision application native to compliance requirements. Regulatory pressure compresses adoption timelines for input-intensive cropping systems.
- Soil Management:Sub-inch RTK-GPS accuracy enables targeted amendment application based on grid-sampled fertility maps.
- Yield Prediction:Machine learning models integrate historical performance with real-time weather data for harvest timing optimization.
Crop Monitoring commands the broadest deployment base; Pest Control exhibits the steepest regulatory tailwind.
End User:
Procurement sophistication scales with operational size and technical staffing capacity, fragmenting vendor go-to-market strategies across customer tiers.
- Enterprises:Consolidated buying cooperatives in Iowa and Illinois negotiate enterprise-wide platform licenses spanning multi-state operations. These organizations bundle sensor hardware with cloud analytics under single annual contracts, displacing traditional dealer financing relationships. Subscription-Based delivery aligns technology spend with seasonal cash flows.
- Agricultural Cooperatives:Member-owned entities aggregate demand across hundreds of mid-size farms to achieve volume pricing on precision platforms. USDA Climate-Smart Agriculture cost-share eligibility creates subsidized entry points previously priced out of individual farm procurement. Federally subsidized sensor deployment lowers adoption barriers for member operations.
- Farmers:Individual owner-operators evaluate modular sensor-to-cloud bundling against proprietary platform lock-in risks.
- Agronomists:Independent crop consultants prescribe variable-rate inputs based on platform-generated prescription maps.
Enterprises dominate current revenue concentration; Agricultural Cooperatives show the fastest membership-driven expansion.
Delivery Model:
Payment structure preference correlates with cash flow seasonality and balance sheet capacity, splitting the market between recurring revenue and capital expenditure models.
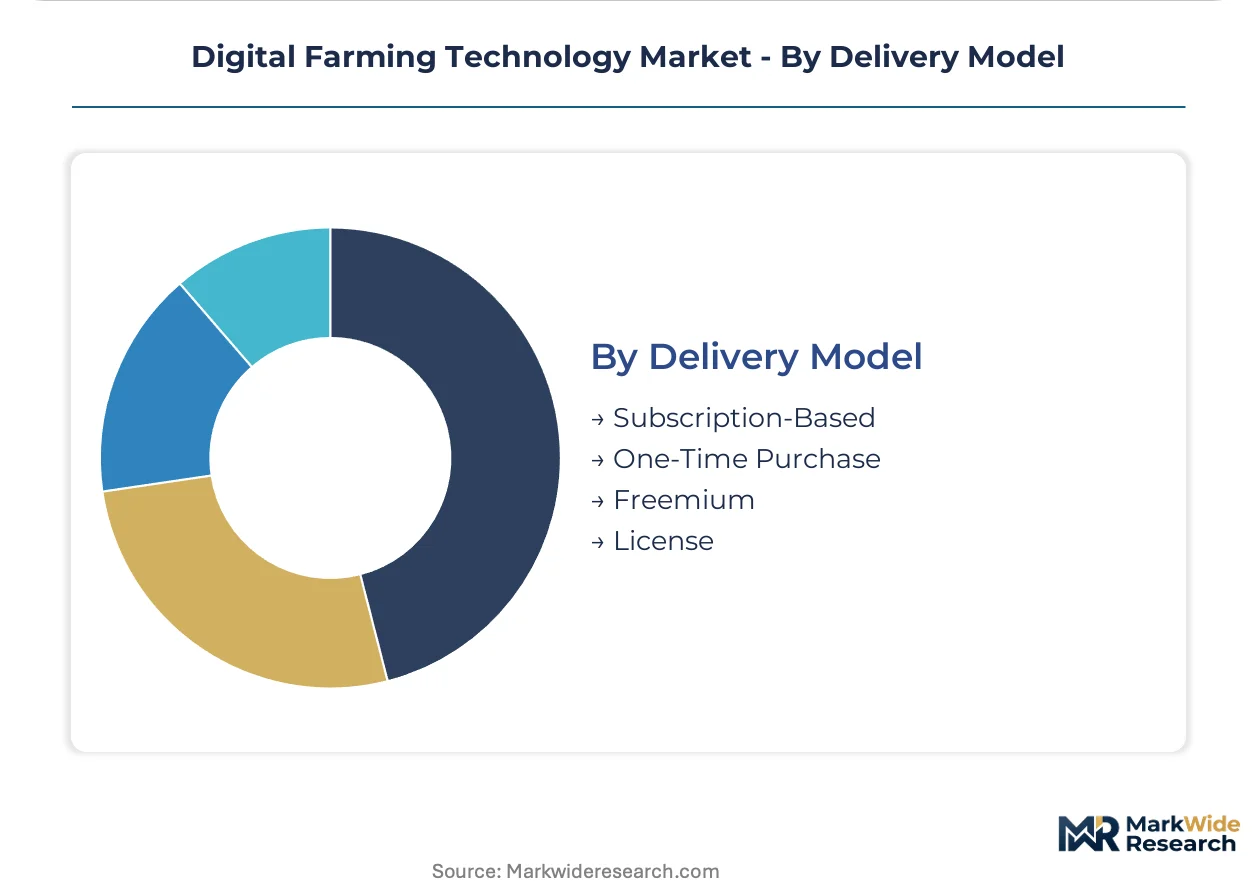
- Subscription-Based:Annual recurring revenue models dominate enterprise accounts where technology spend aligns with seasonal harvest cash flows. Deere & Company leverages its Operations Center to anchor retention across North American dealer networks through continuous feature updates. Vendor preference for predictable revenue streams reinforces subscription pricing.
- One-Time Purchase:Perpetual licenses for hardware-software bundles appeal to mid-size farms with limited working capital flexibility and long equipment holding periods. AGCO Corporation's Fuse open-architecture partnerships enable third-party device integration without proprietary ecosystem lock-in. Capital-constrained buyers prioritize ownership over recurring obligations.
- Freemium:Limited-feature entry tiers convert trial users to paid analytics subscriptions.
- License:Perpetual software rights with annual maintenance fees hybridize ownership and update access.
Subscription-Based leads on vendor revenue predictability; One-Time Purchase retains dominance among mid-size farm capital budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture first achieved commercial scale in the United States during the 1990s, when RTK-GPS guidance systems transformed Midwest grain operations. This technological lineage now diffuses across distinct national regulatory environments and agricultural structures.
United States
Large-scale corn and soybean operations in Iowa and Illinois drive concentrated demand for integrated fleet management platforms. The USDA's Climate-Smart Agriculture initiative provides cost-share eligibility for sensor deployments, subsidizing adoption among mid-size operators previously priced out of precision systems. California's Central Valley pilots autonomous electric tractors for specialty crop cultivation as hand-harvesting labor costs escalate.
Brazil
Commercial operators in Mato Grosso's soybean belt digitize harvest logistics, generating focused demand for yield mapping and grain logistics coordination. ANVISA regulates pesticide application rates that drone-based variable-rate systems must document for compliance. Connectivity infrastructure gaps in the interior limit real-time cloud synchronization for edge-computing nodes.
Germany
Precision application platforms align with EU Green Deal Farm to Fork mandates for 50% pesticide reduction targets. The EU AI Act's risk classification framework triggers compliance redesigns for agricultural decision-support algorithms, requiring documented training data provenance. Bavarian and Lower Saxon precision agriculture providers front-load regulatory documentation to maintain CE marking eligibility.
Netherlands
Greenhouse clusters pioneer autonomous electric tractors for repetitive cultivation passes in high-value controlled-environment agriculture. REACH and RoHS regulations constrain material inputs for sensor hardware deployed in intensive horticultural settings. Wageningen University's research corridor anchors agronomic data science talent development for prescription mapping capabilities.
Australia
Wheat belt operators adopt sub-inch RTK-GPS accuracy systems to reduce overlap waste across vast dryland cropping estates. The country's national agricultural regulator oversees documentation requirements for variable-rate input applications. Cellular dead zones across Western Australia's wheat belt constrain real-time data transmission for cloud-dependent analytics platforms.
Digital Farming Technology Market Competitive Landscape
Premium-margin players sit above commodity-margin players across subscription retention and proprietary data ecosystem dimensions. The vendor base organizes around equipment manufacturers with captive dealer networks, open-architecture platform specialists, and precision navigation service providers. Three archetypes dominate: integrated machinery OEMs bundling hardware with cloud subscriptions, component suppliers enabling third-party system integration, and GNSS correction network operators sustaining centimeter-level accuracy. Competitive moves concentrate on strategic partnerships for interoperability and direct-to-farmer subscription models that displace traditional dealer financing relationships.
Within the integrated machinery tier, Deere & Company and CNH Industrial N.V. occupy positions defined by proprietary platform ecosystems and captive distribution channels. AGCO Corporation exemplifies the open-architecture approach through partnerships that reduce vendor lock-in risks for mid-size farm operators. Trimble Inc. anchors the precision navigation segment, representing the specialist archetype focused on correction services and autosteering accuracy rather than complete equipment systems.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| Trimble Inc. |
| Topcon Corporation |
| Kubota Corporation |
| Bayer AG |
| Syngenta Group |
| CLAAS KGaA mbH |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot indices and rare earth oxide benchmarks cascade through sensor fabrication costs into three distinct pricing tiers for precision agriculture hardware. Equipment OEMs absorb commodity volatility in premium subscription bundles while pushing component cost exposure toward mid-tier hardware buyers.
Pricing Analysis
Annual recurring revenue models dominate enterprise accounts, with subscription tiers separating full Operations Center integration from limited yield-mapping access. Price differentiation rests on RTK-GPS correction precision and multispectral imaging band depth. Cost compression in hardware-only tiers intensifies as AGCO's Fuse open-architecture partnerships reduce proprietary lock-in premiums. Mid-size grain operators in Iowa and Illinois exhibit highest price sensitivity, while California specialty crop enterprises accept premium robotics pricing as hand-harvesting labor costs escalate.
Supply Chain Analysis
Dual-sourcing requirements for multispectral imaging sensors now mandate qualification across Taiwanese foundries and South Korean semiconductor fabricators. Raw material dependencies center on gallium arsenide substrates, silicon carbide wafers, and precision-grade optical glass. Single-source vulnerability concentrates in East Asian lithography equipment, exposing hardware margins to geopolitical disruption. Distribution runs through captive dealer networks for Deere and CNH Industrial, while open-architecture vendors direct-ship through agricultural cooperative procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital farming technology rests on software subscription scaling and carbon credit verification protocols attaching new revenue streams to platform data.
For Market Incumbents: To counter AGCO's Fuse open-architecture threat, Deere & Company should deepen proprietary Operations Center integration with RTK-GPS correction services and expand subscription retention through continuous prescription mapping feature updates. CNH Industrial must accelerate CE marking documentation for EU AI Act compliance to defend European market position against German precision agriculture specialists. For New Entrants and Emerging Players: Begin with USDA Climate-Smart Agriculture cost-share eligibility as the subsidized entry point for mid-size operators previously priced out of precision platforms. Target Brazil's Mato Grosso interior connectivity gaps with edge-computing nodes designed for intermittent cloud synchronization. Deploy direct-to-cooperative sales models that bypass established dealer financing relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where agronomic data science talent scarcity fragments prescription mapping capabilities across regional vendors. Long-term viability favors platforms with documented compliance-native architectures for EU Green Deal Farm to Fork mandates. Watch carbon credit verification standard convergence as the inflection signal for yield-efficiency data monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnerships | Fuse open-architecture alliances reduce vendor lock-in risks for mid-size farm operators. |
| Regulatory Compliance Front-Loading | German providers front-load EU AI Act documentation to maintain CE marking eligibility. |
| Direct-to-Cooperative Subscription Models | Iowa and Illinois grain cooperatives displace traditional dealer financing relationships. |
| Carbon Credit Verification Development | Documented yield-efficiency improvements may translate into tradable protocols. |
| Edge-Computing Node Deployment | Brazil's interior connectivity gaps demand sub-50-millisecond latency without continuous cloud access. |
Research Methodology
Coverage spans North America, Europe, and South America, with primary inputs from each region combined with secondary validation. Interviews incorporated precision agriculture platform executives, agricultural cooperative procurement managers, OEM dealer network operators, and agronomic data science specialists. Secondary sources included USDA Climate-Smart Agriculture program disclosures, EU Green Deal regulatory filings, ANVISA pesticide application documentation, and SEC 10-K equipment manufacturer filings. Bottom-up sensor deployment counts triangulated against top-down addressable farm operator estimates.
Granularity-level modeling segmented the market by technology type, application function, end-user scale, and delivery model across the projection horizon. Deployment trajectories for IoT Solutions, Robotics, Drones, and Sensors were derived from replacement cycle analysis and subscription renewal patterns. Regional regulatory cluster effects shaped adoption timelines, with EU Green Deal mandates and USDA cost-share eligibility treated as discrete scenario inputs. CAGRs emerged from technology-specific penetration curves and seasonal cash flow alignment.
Caveats apply where semiconductor supply disruptions or carbon credit verification standard fragmentation could materially shift the outlook. Forecasts reflect assumptions about cellular infrastructure buildout in Brazil's interior and RTK-GPS network densification. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Global Precision Livestock Farming Market