
 Utility Tractor Market | 2026-2036
Utility Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Tractor Market Analytics
EPA Tier 4 Final and EU Stage V certification is rotating the competitive field toward manufacturers with in-house engine and after-treatment capabilities. Deere & Company leverages its PowerTech engine platform to sustain compliance leadership across North American dealerships. Mahindra & Mahindra Ltd. anchors its position through backward integration into diesel powertrains and an unmatched rural distribution network. AGCO Corporation competes via its Fendt and Massey Ferguson lineups, targeting premium precision-agriculture segments.
A utility tractor designates a mid-range agricultural machine typically delivering 40 to 100 horsepower through a three-point hitch and power take-off system, engineered for tillage, mowing, loader work, and material handling across mixed-use farms and commercial properties. Compact tractors dominate volume in emerging markets where small landholdings and tight capital budgets favor maneuverability over raw output. Standard tractors command the largest revenue pool in North America and Europe as fleet buyers prioritize hydraulic capacity and cab comfort. Electric fuel type variants represent the fastest-growing segment as lithium-ion battery costs decline and European carbon pricing intensifies pressure on diesel dependency.
Federal EPA rules in the United States and EU Stage V standards administered by national type-approval bodies constrain engine architecture and exhaust after-treatment design, raising engineering barriers for new entrants. India's CEA and BIS frameworks govern agricultural equipment efficiency labeling and safety certification, shaping product specifications for sub-continental manufacturers. OEMs must monitor how carbon border adjustments and evolving tailpipe regulations in major markets reshape engine sourcing strategies and electric transition timelines.
Market Dynamics
EPA Tier 4 Final emission standards and EU Stage V requirements are forcing fundamental engine architecture redesigns across the utility tractor sector, concentrating competitive advantage with manufacturers possessing captive after-treatment engineering capabilities.
Growth Catalysts
- Smallholder mechanization programs:India's Punjab and Maharashtra state initiatives accelerate compact tractor penetration among farms under five hectares.
- Commercial grounds maintenance expansion:Landscape contractors multiply fleet purchases as municipal and corporate property management contracts consolidate.
- Lithium-ion cost curves:Declining battery pack economics enable electric variant viability for sub-50 horsepower applications.
Market Restraints
- Diesel after-treatment cost inflation:Selective catalytic reduction and diesel particulate filter hardware adds substantial manufacturing cost per unit.
- Dealer network concentration:Rural distribution in emerging markets remains concentrated through legacy agricultural equipment channels.
- Steel and aluminum input volatility:Chassis and hydraulic component fabrication faces raw material price instability.
Strategic Opportunities
- Brazilian Cerrado expansion:Underpenetrated mid-scale farms present fleet upgrade potential as credit access improves.
- Telematics-integrated leasing:Usage-based financing models reduce capital barriers for seasonal operators.
- EU carbon border adjustments:Import tariff structures incentivize local electric drivetrain assembly within European manufacturing footprints.
Industry Challenges
- Emissions certification timelines:EPA and EU type-approval processes extend product launch cycles by 12-18 months.
- Precision agriculture integration:ISOBUS and variable-rate control system compatibility demands software engineering capacity scarce among traditional manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Tractor Market |
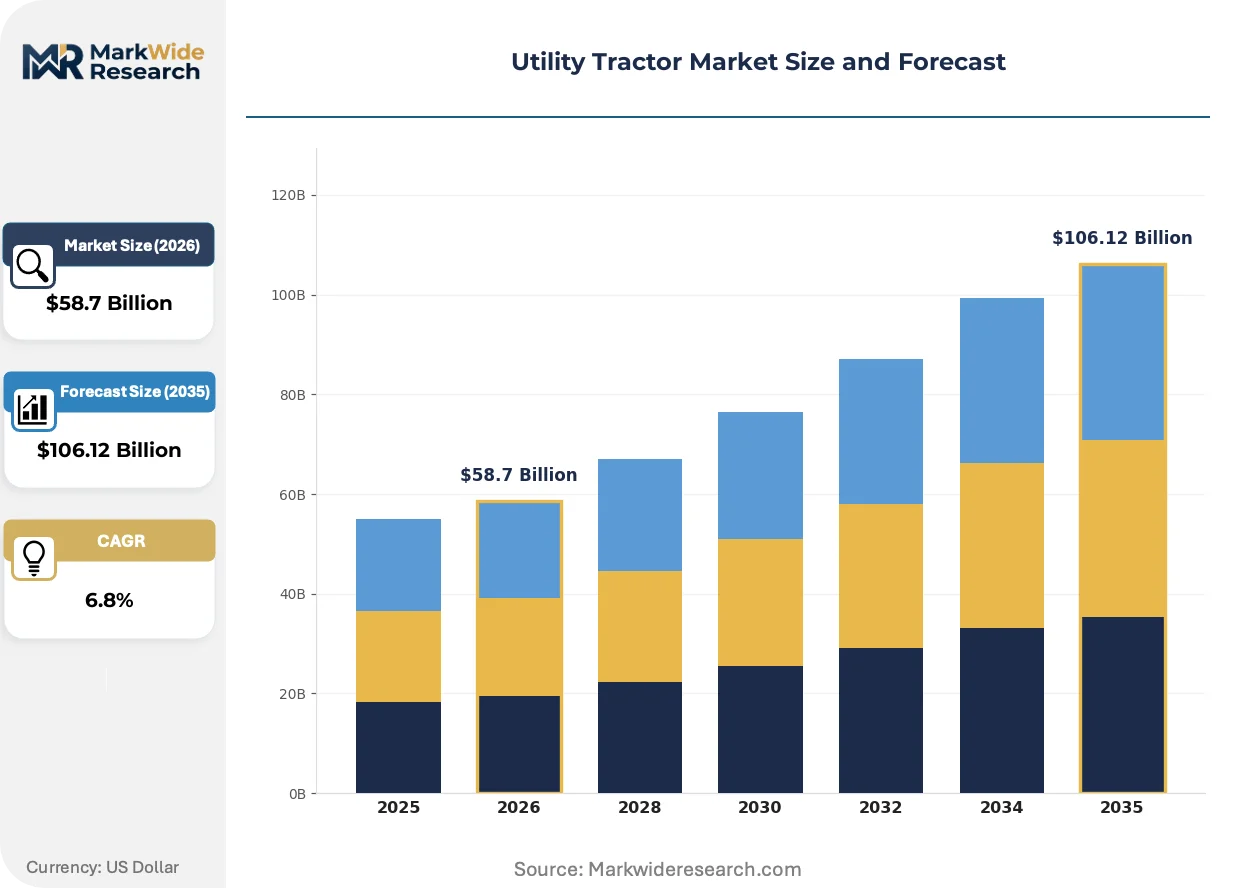
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Standard Tractors, High-Power Tractors, Utility Tractors End User: Agricultural Producers, Landscape Contractors, Government Agencies, Recreational Users Application: Tilling, Mowing, Material Handling, Snow Removal Fuel Type: Diesel, Gasoline, Electric, Biodiesel |
| Companies Covered | Kubota Corporation, Claas Group, Deere & Company, Yanmar Holdings, SDF Group, CNH Industrial N.V., Mahindra & Mahindra Ltd., Buhler Industries, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Tractor Market Evolving Landscape
Electrification trajectories, precision agriculture integration, and service model restructuring are converging to redefine competitive positioning across horsepower segments and geographic markets.
Electric drivetrain architectures are supplanting mechanical power transmission in sub-60 horsepower categories. European vineyard and orchard operators lead adoption, prioritizing zero-emission compliance in emission-restricted zones. Battery-swapping configurations are compressing total cost of ownership calculations against diesel equivalents.
EU Stage V and EPA Tier 4 Final standards are tightening particulate matter and nitrogen oxide thresholds. Engine manufacturers must integrate diesel oxidation catalysts, selective catalytic reduction, and diesel particulate filters into compact chassis designs. North American fleet buyers now specify after-treatment durability as a procurement criterion equal to hydraulic performance.
Rental and short-term lease arrangements are fragmenting traditional equipment ownership patterns. Landscape contractors and municipal fleets increasingly source tractors through agricultural equipment dealers offering seasonal usage programs. This shift concentrates most visibly in Germany and the Netherlands where environmental compliance costs accelerate capital avoidance strategies.
Utility Tractor Market Segmentation
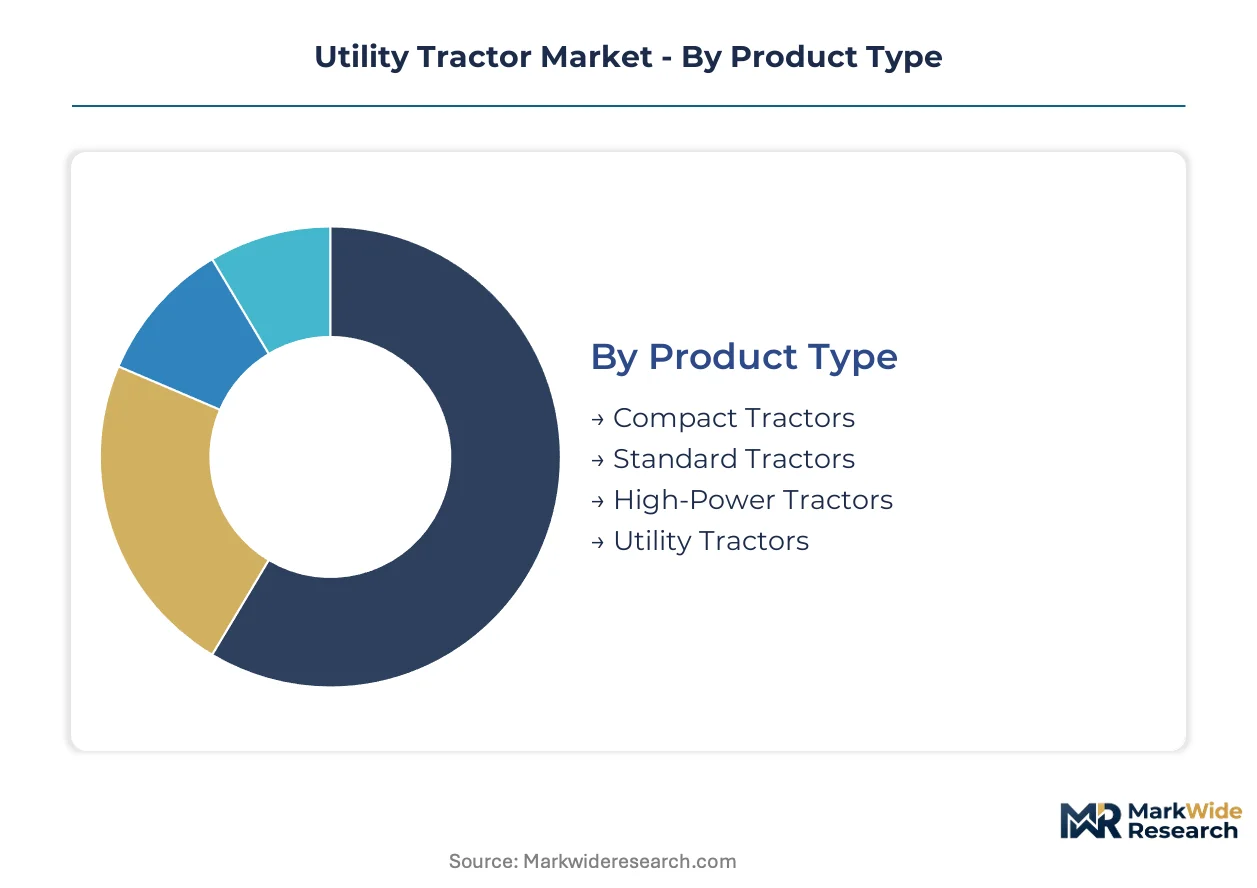
Utility tractor segmentation reveals distinct channel economics and customer workflows. Product configuration, end-use intensity, and power source each create separate margin pools and aftermarket attachment opportunities.
Product Type:
Dealer networks and direct sales forces route different tractor classes through divergent fulfillment paths. Compact units move through rural multi-brand outlets. High-power machines require factory-direct specification and field service contracts.
- Compact Tractors:These machines deliver 20-40 horsepower through hydrostatic transmissions, optimized for maneuverability in confined spaces. Demand concentrates among India's smallholder farms in Punjab and Maharashtra where state mechanization subsidies reduce capital barriers. Dealer density and spare parts availability determine purchase decisions more than specification sheets.
- Standard Tractors:Mid-range platforms spanning 40-100 horsepower with three-point hitch and PTO systems anchor commercial farm operations. North American fleet buyers prioritize hydraulic flow rates and cab ergonomics over base engine power. These units generate the largest revenue pool through premium configurations and extended warranty packages.
- High-Power Tractors:Specialized machines exceeding 100 horsepower for heavy tillage and row-crop applications.
- Utility Tractors:General-purpose chassis designed for mixed-use farms requiring loader work, mowing, and light material handling versatility.
Standard tractors dominate installed base. Compact tractors are where expansion concentrates.
End User:
Customer archetypes separate by utilization intensity and financing sophistication. Agricultural producers amortize equipment over production cycles. Government agencies mandate compliance-heavy procurement protocols.
- Agricultural Producers:Commercial farming operations spanning grain, livestock, and specialty crop sectors represent the core volume base. These buyers evaluate total cost of ownership across depreciation schedules, fuel consumption, and maintenance intervals. Credit access and seasonal cash flow patterns shape replacement timing.
- Landscape Contractors:Commercial grounds maintenance firms operate equipment under severe duty cycles with high hourly utilization. Municipal and corporate contract consolidation is multiplying fleet purchase orders. These customers prioritize uptime guarantees and rapid parts availability over initial acquisition cost.
- Government Agencies:Federal, state, and municipal entities managing public lands, parks, and infrastructure maintenance.
- Recreational Users:Hobby farmers, estate owners, and rural property holders with intermittent, low-intensity equipment needs.
Agricultural producers anchor volume throughput. Landscape contractors are gaining share fastest.
Application:
Task-specific configurations drive attachment sales and hydraulic specification. Seasonal demand patterns vary dramatically by use case.
- Tilling:Primary soil preparation operations requiring high draft capacity and sustained engine load. These applications command the most powerful configurations within each horsepower tier. European vineyard operators are specifying electric drivetrains for emission-restricted cultivation zones.
- Mowing:Vegetation management across pastures, rights-of-way, and commercial properties. Mid-range horsepower dominates this segment with emphasis on PTO efficiency and deck hydraulic lift. Landscape contractors specify this configuration most frequently.
- Material Handling:Loader work and lift operations demanding hydraulic flow priority over traction power.
- Snow Removal:Seasonal applications requiring front-mount blades and blowers with cold-start reliability.
Tilling commands specification premiums. Mowing shows steepest expansion trajectory.
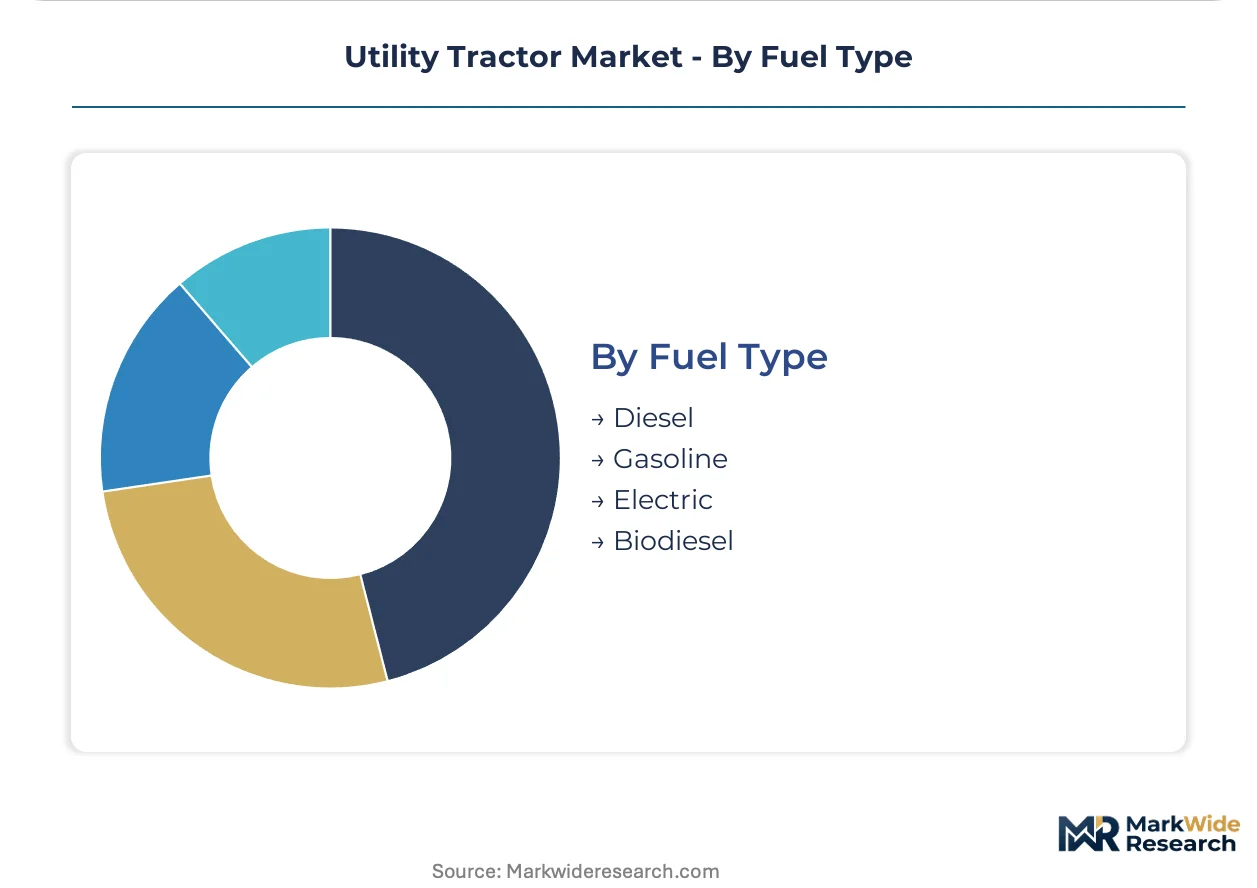
Fuel Type:
Power source selection reflects regulatory pressure, energy cost structures, and refueling infrastructure availability. Carbon pricing and emission zones are accelerating technology transitions.
- Diesel:Compression-ignition engines with established supply chains and service infrastructure. EPA Tier 4 Final and EU Stage V requirements have forced selective catalytic reduction and particulate filter integration. After-treatment durability now equals hydraulic performance in procurement criteria.
- Electric:Battery-electric drivetrains with lithium-ion packs declining in cost per kilowatt-hour. European vineyard and orchard operators lead adoption for zero-emission compliance. Battery-swapping configurations are compressing total cost calculations against diesel equivalents.
- Gasoline:Spark-ignition engines for light-duty recreational and homeowner applications.
- Biodiesel:Renewable fuel compatibility for agricultural producers with captive feedstock supply.
Diesel retains installed base dominance. Electric variants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in the United States and India concentrate procurement volume, while European vineyard operators and Brazilian mid-scale farms present divergent specification requirements. State-level mechanization programs and emission zone enforcement reshape demand patterns across each geography.
United States
Commercial grounds maintenance contractors and large-scale grain operations drive replacement cycles. EPA Tier 4 Final standards mandate selective catalytic reduction and diesel particulate filter integration. Midwest agricultural clusters in Iowa and Illinois prioritize hydraulic capacity and cab ergonomics in procurement decisions.
India
Smallholder farms under five hectares in Punjab and Maharashtra accelerate compact tractor uptake through state subsidy programs. CEA and BIS frameworks govern agricultural equipment efficiency labeling and safety certification. Mahindra's dealer density across rural districts determines purchase accessibility more than technical specifications.
Germany
Vineyard and orchard operators in the Mosel and Rhine regions specify electric drivetrains for emission-restricted cultivation zones. EU Stage V standards administered by the KBA constrain engine architecture and after-treatment design. Precision agriculture integration demands ISOBUS compatibility from manufacturers serving Baden-Württemberg equipment fleets.
Brazil
Mid-scale farms in the Cerrado biome present fleet upgrade potential as credit access improves through national agricultural finance programs. ANVISA and national type-approval bodies shape import and local assembly requirements. São Paulo state distributors concentrate service infrastructure for commercial operators.
France
Landscape contractors and municipal fleets multiply equipment orders as property management contracts consolidate. EU Stage V requirements and carbon pricing intensify pressure on diesel dependency. The Île-de-France region concentrates rental and short-term lease arrangements through agricultural equipment dealers.
Utility Tractor Market Competitive Landscape
Player mix skews toward vertically integrated engine manufacturers with captive after-treatment engineering capabilities. The competitive field rotates around manufacturers possessing in-house diesel powertrain production and dense rural distribution networks. Strategic archetypes include integrated engine-chassis producers, premium precision-agriculture specialists, and emerging electric drivetrain entrants. Dominant competitive moves encompass backward integration into powertrain components and telematics-integrated service model restructuring.
Among integrated manufacturers, Deere & Company and Mahindra & Mahindra Ltd. exemplify divergent geographic anchoring strategies. AGCO Corporation occupies a position within the premium-tier precision-agriculture segment through its Fendt and Massey Ferguson lineups. These three manufacturers represent the structural concentration of competitive advantage around captive engine platforms and distribution density.
| Leading Market Players |
|---|
| Kubota Corporation |
| Claas Group |
| Deere & Company |
| Yanmar Holdings |
| SDF Group |
| CNH Industrial N.V. |
| Mahindra & Mahindra Ltd. |
| Buhler Industries |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day engine component lead times compress pricing power for manufacturers lacking captive diesel powertrain production, while steel and aluminum input volatility feeds directly into chassis cost-plus contract negotiations across North American and Indian procurement channels.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate procurement between OEMs and tier-one chassis fabricators. Price differentiation rests on after-treatment durability certification and hydraulic specification tiers, with EPA Tier 4 Final compliance hardware commanding procurement premiums. Pricing pressure intensifies in the compact tractor segment as Mahindra's dealer density in Punjab and Maharashtra forces margin compression among regional assemblers. Agricultural producers exhibit highest price sensitivity due to seasonal cash flow constraints, while landscape contractors prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Inbound logistics costs through Nhava Sheva and Shanghai-Ningbo corridors constrain just-in-time engine delivery schedules for European and North American assembly plants. Manufacturing concentration centers on India, China, and Germany for diesel powertrain components, with lithium-ion cell supply anchored in South Korea and China. The supply chain draws from specialized steel grades, aluminum castings, and selective catalytic reduction substrate materials. Single-source vulnerability in particulate filter ceramic substrates presents structural risk. Distribution runs through captive dealer networks in mature markets and multi-brand rural outlets in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility tractor demand sits in early-cycle expansion as smallholder mechanization programs in India and electric drivetrain adoption in European vineyards accelerate penetration beyond traditional diesel replacement cycles.
For Market Incumbents: Consolidate backward integration into diesel powertrains and after-treatment systems to defend margin position against emerging electric entrants. Expand field service contract coverage in landscape contractor segments where uptime guarantees command pricing premiums. Prioritize ISOBUS software engineering capacity to maintain precision agriculture compatibility leadership. For New Entrants and Emerging Players: Differentiate on battery-swapping configurations for sub-50 horsepower vineyard and orchard applications where emission zone restrictions create compliance-driven demand. Target Brazilian Cerrado mid-scale farms with telematics-integrated leasing models that reduce capital barriers. Pursue white-label manufacturing partnerships with established distribution networks rather than dealer network buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electric drivetrain sub-segments as lithium-ion pack economics improve and modular assembly reduces tooling requirements. Long-term viability favors manufacturers with hybrid diesel-electric platform flexibility and dense rural service infrastructure. Acquisition targets should demonstrate captive engine or battery pack sourcing and established type-approval pathways. Watch EPA and EU regulatory timeline acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Components | Captive diesel engine and after-treatment production secures EPA Tier 4 Final compliance leadership against import-dependent competitors. |
| Telematics-Integrated Leasing Models | Usage-based financing reduces capital barriers for seasonal operators in Brazil and Indian smallholder segments. |
| ISOBUS Software Platform Development | Precision agriculture compatibility becomes procurement criterion equal to hydraulic performance among North American fleet buyers. |
| Battery-Swapping Infrastructure Partnership | European vineyard operators prioritize zero-emission compliance in emission-restricted Mosel and Rhine cultivation zones. |
| Dealer Network Density Expansion | Rural parts availability and service accessibility determine purchase decisions in Punjab and Maharashtra state subsidy programs. |
Research Methodology
Desk research of customs trade databases, EPA and EU type-approval filings, and agricultural equipment registration records preceded structured interviews with OEM platform engineers, dealer network managers, and landscape contractor fleet procurement directors. Primary fieldwork with maintenance directors at commercial farming operations and aftermarket service heads validated secondary demand estimates. Analysis combined bottom-up unit shipment modeling with top-down value aggregation across horsepower and fuel type segments.
Variance decomposition across product type, end user archetype, application intensity, and fuel technology architecture shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate reconciliation against macroeconomic agricultural output indicators and mechanization penetration benchmarks. Forecast inputs incorporated lithium-ion cost curve trajectories, emission regulatory phase-in schedules, and state-level subsidy program allocations.
The analysis sits within stated boundaries; outcomes outside sustained steel price stability, intact EU carbon border adjustment mechanisms, or uninterrupted smallholder credit access would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and battery chemistry cost reduction continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market