
 Asia-Pacific Haying and Forage Machinery Market | 2026-2036
Asia-Pacific Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Haying and Forage Machinery Market Outlook
Leasing and project finance for agricultural contractors is rewriting competitive dynamics across the Asia-Pacific haying sector. Kubota Corporation leverages its dense dealer financing networks to place rotary mowers with mid-scale dairy operators in Vietnam and Thailand. Deere & Company anchors premium market tiers through captive leasing programs that bundle precision balers with seasonal service contracts. Lovol Heavy Industry competes on stripped-down baler configurations suited to China's fragmented farm structure, where outright purchase capacity remains limited.
Asia-Pacific haying and forage machinery encompasses equipment engineered to cut, condition, dry, rake, and compress grass, legume, and cereal crops into storable feed forms. Rotary mower conditioners operate at ground speeds exceeding 15 km/h with cutterbar widths spanning 2.5 to 4.0 meters, producing uniform windrows that accelerate field drying for silage and haylage preservation. Balers dominate value capture within the product type dimension, as large square and round configurations command replacement premiums tied to twine and net-wrap automation. Conventional technology still occupies volume leadership across South Asian smallholdings, though rotary systems generate disproportionate margin pools where contractor fleets consolidate operations in Australia and New Zealand.
India's BIS certification requirements for farm machinery safety and China's GB standards for agricultural equipment emissions shape product compliance costs and market access timelines. Australia's ACCC enforcement of consumer guarantees on imported machinery creates aftermarket service obligations that favor established distributor networks. Japan's METI energy-efficiency labeling for agricultural engines is narrowing the technology gap between domestic and imported power units. Stakeholders must monitor how subsidy eligibility rules evolve across national agricultural departments, as machinery registration and local content thresholds increasingly determine which equipment configurations qualify for concessional financing.
Market Dynamics
Leasing penetration among agricultural contractors is restructuring equipment acquisition patterns across Southeast Asia and eastern China, compressing replacement cycles and elevating service bundling over asset ownership.
Growth Catalysts
- India's PLI scheme for farm mechanization:Production-linked incentives for precision balers and disc mowers are accelerating domestic manufacturing scale and reducing import dependency for dairy cooperatives.
- Contractor fleet consolidation in Australia and New Zealand:Large-scale forage operations are driving rotary system adoption that outpaces conventional technology replacement rates.
- Alfalfa expansion in Shandong and Henan provinces:Eastern China's large-scale hay operations generate sustained demand for high-capacity rotary equipment with automated windrow formation.
Market Restraints
- Steel and hydraulics input volatility:Fluctuating commodity costs for cutterbar alloys and high-pressure hydraulic systems compress OEM margin buffers on rotary mower production.
- Dealer network concentration in Vietnam and Thailand:Dense financing-linked distribution ties create barriers for independent equipment suppliers lacking captive credit infrastructure.
- Conventional technology lock-in across South Asian smallholdings:Fragmented farm structures sustain demand for lower-cost baler configurations that delay rotary system penetration.
Strategic Opportunities
- Underpenetrated dairy mechanization in Indonesia and Philippines:Nascent cooperative structures present first-mover positioning for seasonal leasing programs with bundled maintenance.
- Net-wrap automation convergence with twine systems:Hybrid baler configurations combining both binding technologies address transitional operator preferences in China's mixed-scale markets.
- Japan's METI energy-efficiency labeling:Agricultural engine certification standards create differentiated positioning for imported power units meeting domestic emission benchmarks.
Industry Challenges
- Precision baler technician scarcity:Automated knotting and net-wrap calibration systems require specialized service capabilities that outpace vocational training pipeline expansion.
- China's GB standards compliance timelines:Agricultural equipment emission certification delays product registration and market entry for new rotary mower introductions.
- Aftermarket parts interoperability:Proprietary cutterbar designs and hydraulic coupling specifications complicate third-party service provision across contractor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Haying and Forage Machinery Market |
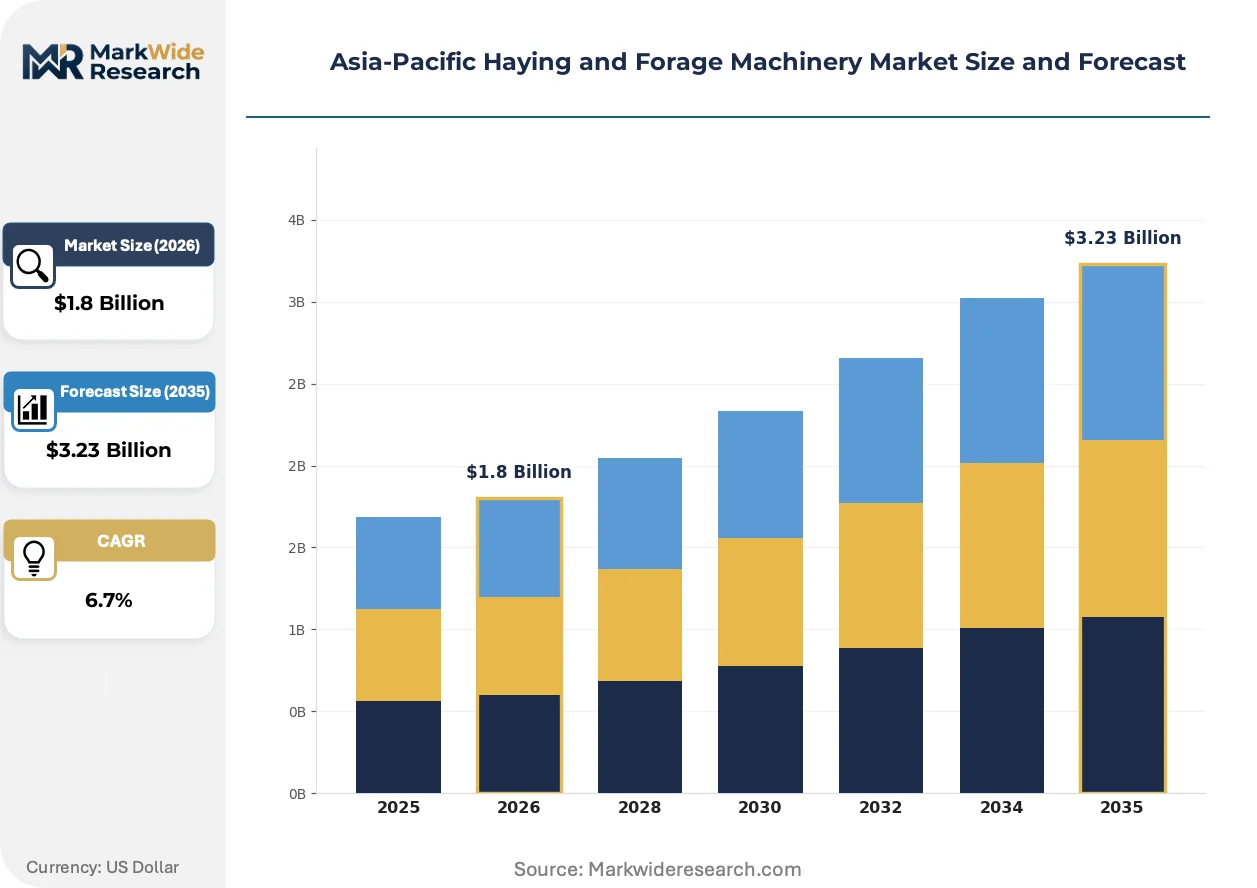
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balers, Mowers, Tedders, Rakes Technology: Conventional, Rotary, Disc, Vertical End User: Farmers, Agricultural Contractors, Cooperatives, Research Organizations Deployment: On-Farm, Retail, Wholesale, Others |
| Companies Covered | Deere & Company, Kubota Corporation, CNH Industrial, AGCO Corporation, CLAAS, Mahindra Group, Lovol Heavy Industry, China National Machinery Industry Corporation, Krone, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Haying and Forage Machinery Market Strategic Shifts
Digital control systems and precision agriculture integration are redefining equipment functionality, shifting competitive advantage from mechanical reliability to data-enabled operational optimization.
Conditioner roll designs with adjustable gap settings and rubber-on-steel configurations are rendering obsolete fixed-gap steel-flail systems that deliver inconsistent drying performance. Dairy contractors in New South Wales and Victoria are retrofitting existing mower platforms with aftermarket conditioning kits to compress field-to-silage timelines. The technology is rendering obsolete the traditional 48-hour wilting window that constrained harvest scheduling flexibility.
China's GB standards for agricultural equipment emissions are tightening particulate matter limits on diesel power units above 37 kilowatts. Domestic manufacturers must integrate selective catalytic reduction or exhaust gas recirculation systems to maintain market access. Rotary mower imports from Japan and South Korea face accelerated homologation requirements that favor established distributors with regulatory compliance infrastructure.
Seasonal service contracts are displacing outright purchase as the dominant transaction structure among Vietnamese dairy cooperatives. Kubota's dealer financing networks bundle preventive maintenance with equipment placement, compressing customer acquisition costs for mid-scale operators. This shift is most visible in the Mekong Delta, where contractor fleets prioritize uptime guarantees over asset depreciation schedules.
Asia-Pacific Haying and Forage Machinery Market Segmentation
Equipment configuration in Asia-Pacific haying markets fragments across operational scale, power source, and service model. Segmentation reveals how technology adoption diverges between consolidated contractor fleets and fragmented smallholdings.
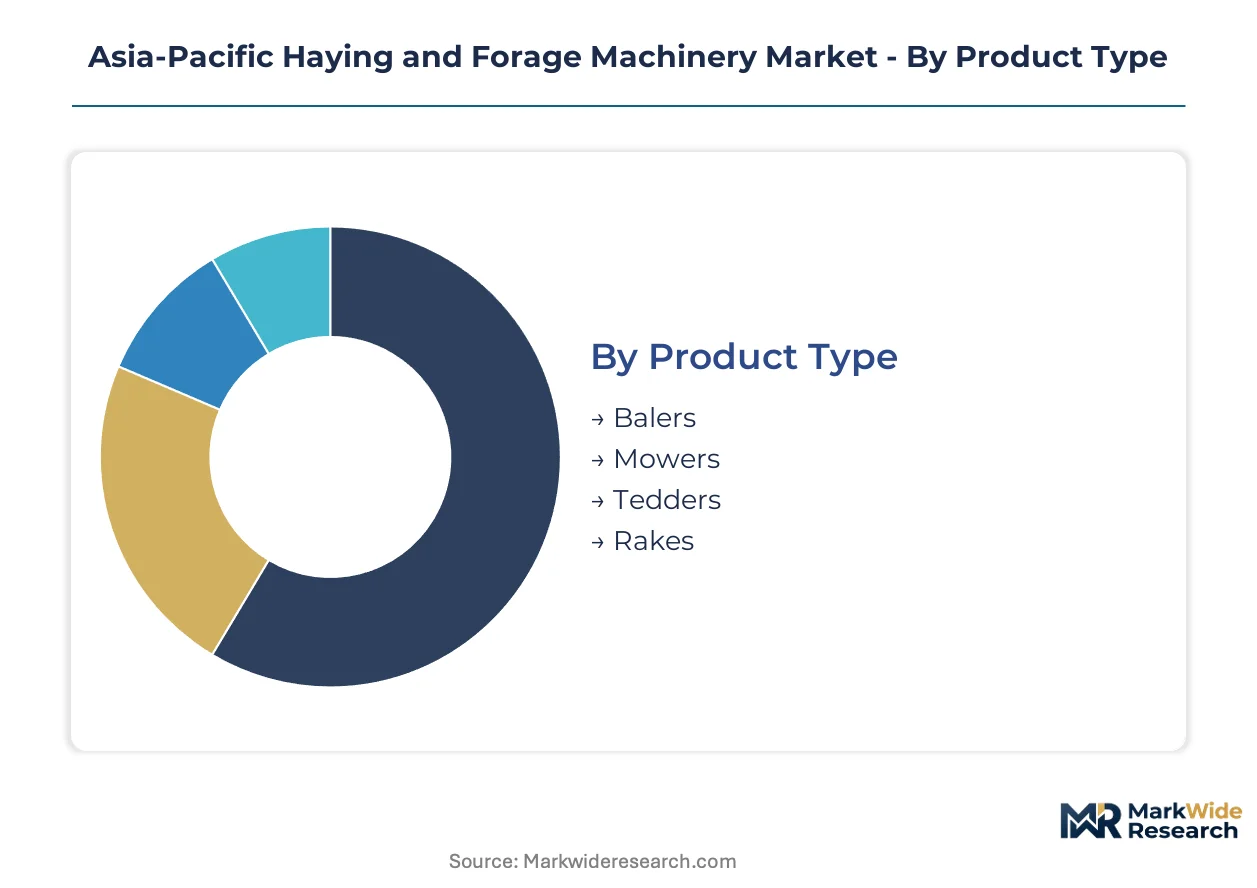
Product Type:
Cost tier separation across haying equipment reflects capital intensity and replacement cycle length. Premium rotary systems command financing-linked placement, while conventional configurations sustain cash-constrained demand.
- Balers:Large square and round configurations dominate value capture through twine and net-wrap automation. Dairy cooperatives across Vietnam and Thailand prioritize these units for year-round feed security, with replacement premiums tied to binding system sophistication.
- Mowers:Rotary mower conditioners operate at ground speeds exceeding 15 km/h with cutterbar widths spanning 2.5 to 4.0 meters. Eastern China's Shandong and Henan provinces drive demand for high-capacity units with automated windrow formation.
- Tedders:Spreading equipment accelerates field drying through uniform crop distribution. Australian contractor fleets in New South Wales and Victoria deploy these systems to compress harvest-to-silage timelines.
- Rakes:Windrow consolidation equipment completes the conditioning sequence. South Asian smallholdings sustain demand for lower-cost configurations that delay precision system penetration.
Balers command the established base. The steepest expansion runs through Mowers.
Technology:
Application intensity varies by crop type, terrain, and operational consolidation. Rotary systems concentrate where contractor fleets achieve scale economies, while conventional technology persists in fragmented ownership structures.
- Conventional:Fixed-gap steel-flail systems deliver baseline cutting performance at reduced capital outlay. India's BIS certification requirements for farm machinery safety shape compliance costs for these legacy configurations.
- Rotary:Conditioner roll designs with adjustable gap settings and rubber-on-steel configurations render obsolete fixed-gap alternatives. Dairy contractors in Australia and New Zealand drive adoption that outpaces conventional replacement rates.
- Disc:Cutterbar technology with independent blade protection suits undulating terrain. India's PLI scheme for farm mechanization accelerates domestic production of these precision units.
- Vertical:Upright cutting systems address specialty forage and biomass applications. Research organizations in Japan evaluate these configurations under METI energy-efficiency labeling protocols.
Conventional technology anchors volume leadership. Rotary systems generate the fastest margin pool expansion.
End User:
Customer type determines acquisition financing, service bundling, and technology upgrade cadence. Leasing penetration concentrates among contractors with seasonal cash flow patterns, while cooperatives prioritize uptime guarantees.
- Farmers:Owner-operators with fragmented landholdings favor stripped-down baler configurations suited to limited outright purchase capacity. China's GB standards for agricultural equipment emissions constrain power unit selection for this segment.
- Agricultural Contractors:Fleet operators drive rotary system adoption through financing-linked equipment placement. Dense dealer networks in Vietnam and Thailand compress customer acquisition costs for mid-scale operators.
- Cooperatives:Dairy collective structures across Southeast Asia expand mechanized forage harvesting to secure feed supply. Seasonal service contracts displace outright purchase as the dominant transaction structure.
- Research Organizations:Institutional evaluators test emerging configurations under national certification protocols. Japan's METI labeling and Australia's ACCC enforcement create aftermarket service obligations that favor established distributor relationships.
Agricultural Contractors command the premium technology base. Cooperatives represent the fastest-expanding demand channel.
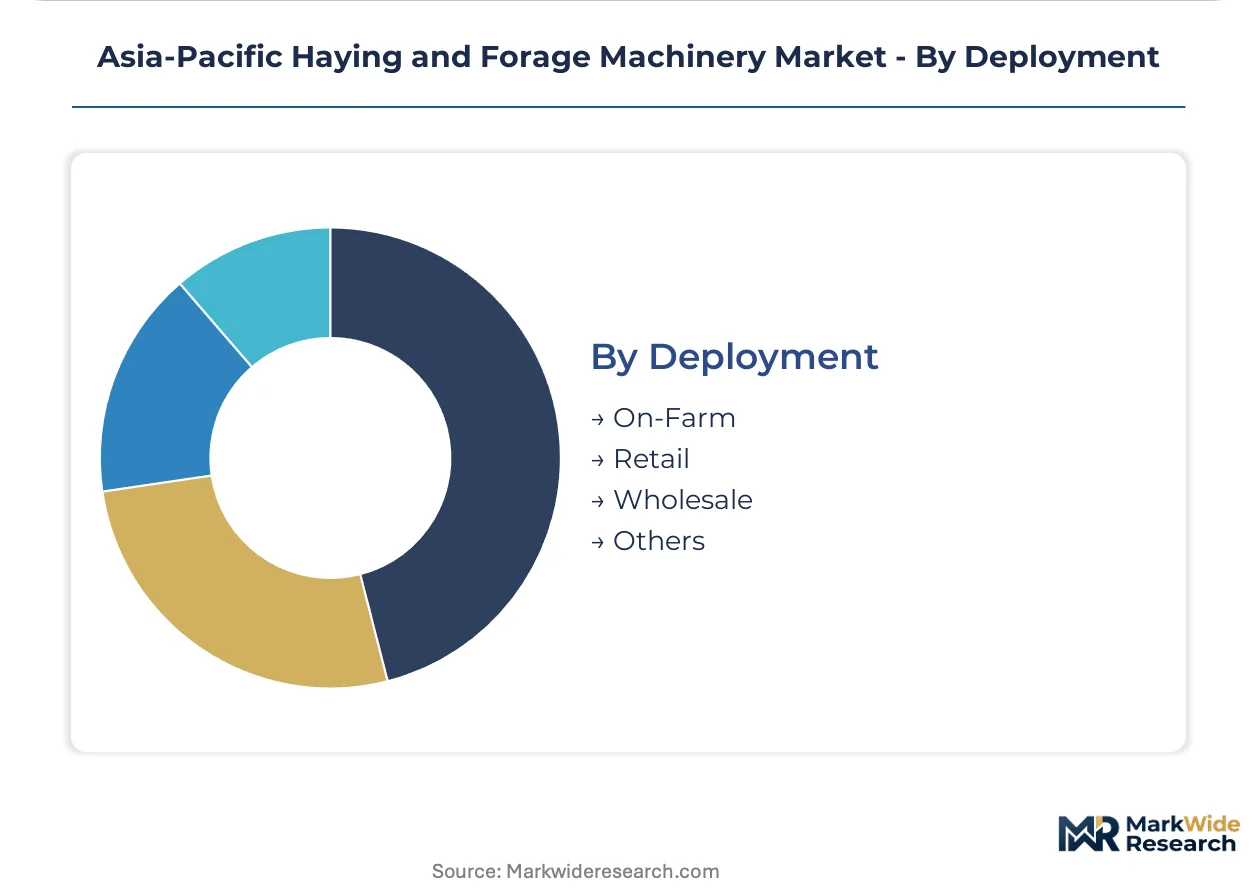
Deployment:
Supply channel configuration reflects regional infrastructure maturity and financing ecosystem development. Direct placement concentrates where dealer networks integrate credit provision, while wholesale channels sustain parts and service distribution.
- On-Farm:Direct equipment placement with bundled maintenance contracts. Australia's ACCC consumer guarantee enforcement creates service obligations that favor established networks.
- Retail:Dealer-mediated sales with captive leasing programs. Kubota Corporation leverages dense financing networks across Southeast Asia for rotary mower placement.
- Wholesale:Volume distribution to secondary markets and independent service providers. Aftermarket parts interoperability challenges complicate third-party provision across contractor fleets.
- Others:Government procurement and development program channels. Subsidy eligibility rules across national agricultural departments determine qualification for concessional financing.
Retail channels command the established revenue base. On-Farm deployment shows the steepest trajectory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in Asia-Pacific haying equipment tilt toward machinery imports from Japan and Germany balanced against rising domestic production in China and India. Trade patterns concentrate capital-intensive rotary systems in developed markets while conventional configurations dominate intraregional South Asian commerce.
China
Shandong and Henan provinces anchor alfalfa mechanization through large-scale hay operations demanding high-capacity rotary equipment. GB standards for agricultural equipment emissions constrain diesel power unit certification timelines for new market entrants. Zhengzhou machinery clusters drive domestic baler production serving fragmented farm structures with stripped-down configurations.
India
Dairy cooperatives across Gujarat and Maharashtra expand mechanized forage harvesting to secure year-round feed supply security. BIS certification requirements for farm machinery safety elevate compliance costs for precision baler introductions. Punjab's agricultural equipment manufacturing corridor accelerates disc mower production under PLI scheme incentives.
Japan
METI energy-efficiency labeling for agricultural engines differentiates domestic power units against imported rotary mower competition. Precision agriculture integration in Hokkaido dairy operations drives conditioner roll upgrades with adjustable gap settings. Osaka-based fabrication networks supply rubber-on-steel components to Southeast Asian assembly operations.
Australia
Contractor fleet consolidation in New South Wales and Victoria compresses harvest-to-silage timelines through rotary system retrofit programs. ACCC enforcement of consumer guarantees on imported machinery creates aftermarket service obligations favoring established distributor relationships. Queensland biomass evaluation projects test vertical cutting configurations under research organization protocols.
Vietnam
Mekong Delta dairy cooperatives displace outright purchase with seasonal service contracts bundling preventive maintenance. Dense dealer financing networks compress customer acquisition costs for mid-scale rotary mower placement. National agricultural department subsidy eligibility rules determine machinery registration thresholds for concessional financing access.
Asia-Pacific Haying and Forage Machinery Market Competitive Environment
On the supply side, the industry is tiered across premium rotary system specialists, mid-scale financing-linked distributors, and stripped-down configuration fabricators serving cost-constrained smallholdings. Strategic archetypes include captive leasing program operators, dense dealer network owners, and domestic content-optimized manufacturers. Competitive moves concentrate on bundling service contracts with equipment placement and backward integration into cutterbar alloy supply.
Within the premium-tier vector, Deere & Company and Kubota Corporation occupy positions defined by financing infrastructure depth. Lovol Heavy Industry anchors the domestic-optimized archetype. These three exemplify how regulatory compliance capability and credit provision infrastructure separate sustainable market presence from transactional equipment supply.
| Leading Market Players |
|---|
| Deere & Company |
| Kubota Corporation |
| CNH Industrial |
| AGCO Corporation |
| CLAAS |
| Mahindra Group |
| Lovol Heavy Industry |
| China National Machinery Industry Corporation |
| Krone |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Nagoya maritime corridor carries cutterbar alloys and hydraulic assemblies that feed rotary mower production clusters, with freight cost volatility translating directly into tiered equipment pricing across Southeast Asian dairy cooperatives and Chinese alfalfa operations. Steel price swings in this lane compress margin buffers for OEMs serving cost-constrained smallholdings while amplifying differentiation leverage for premium system suppliers with captive alloy sourcing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with premium rotary systems commanding financing-linked placement and stripped-down baler configurations sustaining cash-constrained demand. Price differentiation rests on certification grade under India's BIS safety requirements and after-sales service bundling density. Cost compression in the economy tier is intensifying because steel and hydraulics input volatility pressures fabricators lacking backward integration into cutterbar supply. Agricultural contractors show least price sensitivity due to uptime guarantee prioritization, while fragmented farmers in South Asian smallholdings exhibit highest elasticity.
Supply Chain Analysis
Japan's METI energy-efficiency labeling and associated technology controls restrict flows of certain precision engine configurations, shaping component sourcing patterns for rotary mower assemblers. Manufacturing gravity centers on China, Japan, and South Korea, with Zhengzhou machinery clusters and Osaka fabrication networks supplying rubber-on-steel conditioner components. Raw material dependencies encompass high-grade steel alloys, high-pressure hydraulic systems, and precision-engineered cutterbar blades. Single-source vulnerability concentrates in specialized knotting mechanisms for automated balers. Distribution runs through dense dealer financing networks that bundle credit provision with preventive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision agriculture platforms that disintermediate mechanical equipment through data-enabled operational optimization, requiring defensive repositioning around service integration and captive financing infrastructure.
For Market Incumbents: Insulate core placement relationships by deepening backward integration into cutterbar alloy supply and expanding seasonal service contract penetration among Vietnamese dairy cooperatives. The threat of autonomous forage monitoring systems demands counterinvestment in telemetry-enabled equipment platforms. Certification investment under China's GB emission standards represents the critical compliance lever for market access retention.
For New Entrants and Emerging Players: Mid-scale dairy operations in Indonesia and the Philippines represent the most penetrable entry point, where nascent cooperative structures lack established financing relationships and seasonal cash flow patterns favor leasing over ownership. Hybrid baler configurations combining net-wrap and twine binding technologies address transitional operator preferences in China's mixed-scale markets. A go-to-market angle anchored by maintenance bundling rather than asset sale bypasses incumbent credit infrastructure advantages.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic-optimized manufacturers with regulatory compliance infrastructure and established distributor relationships over pure-play equipment fabricators. Long-term viability across the projection horizon rests on service revenue attachment rates rather than unit shipment volumes. The signal to watch is consolidation velocity among Australian contractor fleets, where rotary system retrofit penetration indicates technology transition maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutterbar Supply | Captive alloy sourcing insulates margin buffers against steel price volatility in the Shanghai-Nagoya lane. |
| Seasonal Service Contract Expansion | Maintenance bundling with equipment placement compresses customer acquisition costs for mid-scale dairy operators. |
| GB Standards Compliance Investment | Emission certification infrastructure accelerates product registration timelines for rotary mower introductions. |
| Telemetry Platform Development | Data-enabled operational optimization counters substitution pressure from precision agriculture software platforms. |
| Hybrid Baler Configuration Launch | Dual binding technology addresses transitional preferences in China's fragmented farm structure. |
Study Parameters
The analysis maps baler automation tiers, mower conditioner specifications, and deployment channel configurations, each validated through equipment procurement directors at dairy cooperatives, aftermarket service managers at dealer networks, regulatory compliance officers at OEMs, and fleet operations heads at agricultural contractors. Primary intelligence combined structured interviews with secondary validation against customs records, BIS certification filings, GB standards registration databases, and METI energy-efficiency labeling disclosures. Bottom-up shipment data triangulated against top-down equipment financing flow analysis across the projection horizon.
Assumptions held fixed include India's PLI scheme incentive continuity, China's GB emission tier enforcement timelines, and Southeast Asian dairy cooperative formation velocity, while steel alloy pricing and hydraulic component availability were modeled as variable inputs. Segmentation dimensions encompassed product type, technology tier, end-user archetype, and deployment channel, with CAGRs derived from replacement cycle compression rates and fleet consolidation trajectories. Industry-specific forecast inputs incorporated alfalfa expansion acreage in Shandong and Henan provinces and contractor fleet penetration rates in New South Wales and Victoria.
Practitioners should monitor subsidy eligibility rule changes across national agricultural departments and METI labeling protocol revisions for early signals of demand trajectory shifts. Forecasts reflect these documented assumptions regarding regulatory stability and commodity input availability. Material shifts in India's PLI scheme scope or China's GB standards certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market