
 Agriculture Drone Mapping and Analytics Market | 2026-2036
Agriculture Drone Mapping and Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Drone Mapping and Analytics Market Insights
Chinese sensor manufacturing clusters are expanding output of multispectral imaging modules for agricultural UAV platforms. DJI leverages its Shenzhen supply base to dominate consumer and prosumer drone hardware, while Trimble Inc. anchors its position through precision agriculture software integration with existing farm management systems. Parrot Drone SAS differentiates through specialized crop-scouting sensors designed for European vineyard and orchard environments.
Agriculture drone mapping and analytics encompasses the collection, processing, and interpretation of geospatial crop data via unmanned aerial vehicles equipped with RGB, multispectral, or thermal cameras operating at altitudes typically between 50 and 400 feet, with ground sample distances reaching sub-inch resolution for targeted intervention planning. The primary commercial purpose centers on converting raw imagery into actionable agronomic intelligence—nitrogen stress maps, prescription zones, and yield predictions—that reduces input waste and improves harvest outcomes. Multirotor drones lead current deployment volumes due to vertical takeoff flexibility and lower operator skill barriers, though fixed-wing platforms sustain relevance across broad-acre cereal operations where flight endurance and coverage speed determine per-acre economics. Software solutions represent the fastest-expanding margin pool as recurring subscription models for cloud-based analytics displace one-time hardware purchases among farmer end users.
The FAA's Part 107 framework in the United States governs commercial drone operations including pilot certification, airspace restrictions, and beyond-visual-line-of-sight waivers that directly shape service scalability for agricultural providers. EASA's specific category regulations under EU Regulation 2019/947 impose operational risk assessments and design standards that influence equipment procurement decisions across European farming cooperatives. Stakeholders must monitor evolving counter-drone and data sovereignty legislation, as cross-border imagery storage restrictions and remote identification mandates will determine which analytics platforms retain market access.
Market Dynamics
The agriculture drone mapping sector pivots on a fundamental tension between hardware commoditization and software value capture, as cloud-based analytics subscriptions displace one-time equipment purchases and reshape vendor economics.
Growth Catalysts
- Variable-rate application technology:Large-scale row-crop operations in Brazil generate prescription maps from drone imagery to optimize fertilizer and pesticide placement, cutting input costs while boosting yields.
- Part 107 certification framework:The FAA's remote pilot standards in the United States create predictable compliance pathways that expand the certified operator pool and reduce insurance friction for agricultural service providers.
- Multispectral sensor proliferation:Chinese manufacturing clusters in Shenzhen and Guangdong are scaling output of crop-health imaging modules, driving down unit costs for NDVI-capable UAV platforms.
Market Restraints
- Sensor supply concentration:Dependence on Shenzhen-based component suppliers exposes equipment manufacturers to geopolitical trade restrictions and semiconductor allocation volatility.
- Flight endurance limitations:Lithium-polymer battery energy density caps multirotor coverage to 20-40 minutes per sortie, forcing frequent battery swaps that erode per-acre economics on broad-acre cereal operations.
- EASA operational risk assessments:EU Regulation 2019/947 mandates case-by-case SORA evaluations for agricultural flights over populated areas, extending deployment timelines and raising compliance costs for European cooperatives.
Strategic Opportunities
- Water-stressed wheat regions:Australia's wheat belt presents concentrated demand for precision irrigation analytics, where drone-based moisture mapping commands premium subscription pricing from deficit-hedging growers.
- AI-driven yield prediction:Machine learning models trained on multi-season imagery archives are converging with ground-truth harvest data to generate revenue-share advisory contracts tied to outcome performance.
- Direct-to-grower SaaS channels:Bypassing traditional equipment dealers, analytics vendors are building recurring revenue through mobile-first platforms that deliver field-specific prescriptions without hardware ownership.
Industry Challenges
- Remote pilot skill gaps:Part 107 certification requires aviation knowledge testing that excludes many agronomists and farm managers, creating a bottleneck between imagery demand and qualified flight operations.
- Legacy farm management integration:Proprietary data formats from drone analytics platforms resist seamless ingestion into established FMIS systems, forcing manual translation or expensive API development.
- Beyond-visual-line-of-sight waiver delays:FAA BVLOS approvals for large contiguous acreages stretch 90-180 days, compressing the operational window for time-critical crop monitoring applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Drone Mapping and Analytics Market |
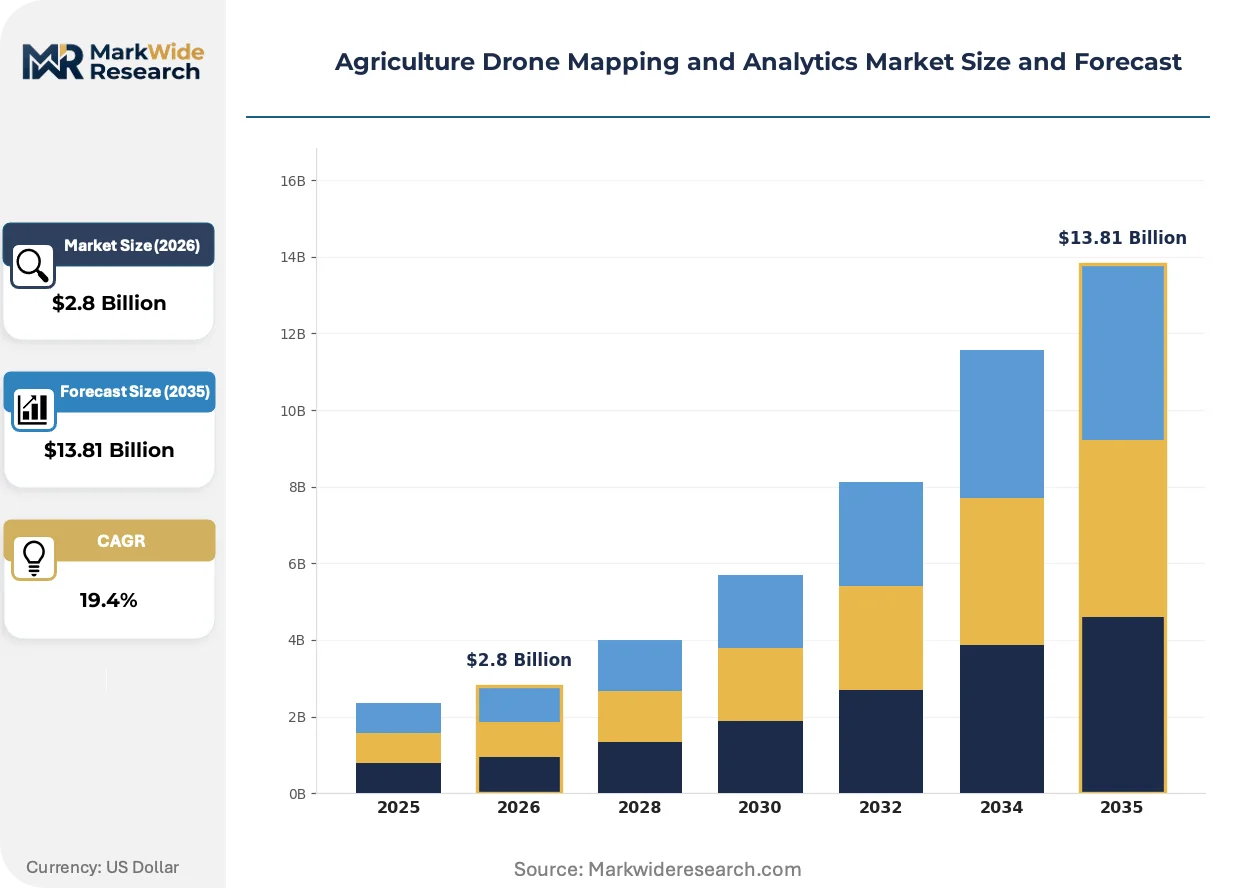
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multirotor Drones, Hybrid Drones, Software Solutions Application: Precision Agriculture, Crop Monitoring, Soil Analysis, Livestock Management End User: Farmers, Agricultural Consultants, Agronomists, Research Institutions Technology: Remote Sensing, GIS Mapping, Data Analytics, AI |
| Companies Covered | DJI, Trimble Inc., Parrot Drone SAS, Yamaha Motor Co., Ltd., AgEagle Aerial Systems Inc., PrecisionHawk, AeroVironment, Inc., DroneDeploy, Pix4D SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Drone Mapping and Analytics Market Trends and Innovations
Three interconnected developments are compressing the value chain and reallocating margin from hardware manufacturers to data platforms: sensor miniaturization, regulatory clarity on autonomous flight, and shifting procurement preferences among commercial farming operations.
Hyperspectral imaging payloads are overtaking standard multispectral configurations in high-value specialty crop applications. Vineyard and orchard operators in France and Italy adopt 200+ band sensors to detect early-stage fungal stress and water infiltration patterns invisible to RGB or four-band alternatives. This capability compression is enabling outcome-based pricing models where analytics vendors capture value tied to spray reduction or quality premiums rather than per-acre flight fees.
Remote identification mandates from the FAA and parallel EASA requirements are forcing equipment retrofit cycles and platform consolidation. Manufacturers must embed broadcast modules that transmit position, altitude, and operator identity, adding hardware cost but reducing liability exposure for fleet operators. Agricultural service providers in the United States are responding by standardizing on platforms with pre-certified RID compliance, narrowing the vendor shortlist and accelerating replacement of legacy 2018-2020 hardware generations.
Farming cooperatives and mid-scale operators are abandoning capital-intensive drone ownership in favor of subscription-based imagery services delivered by regional flight networks. This unbundling shifts balance sheet risk to service providers while giving growers access to sensor upgrades and analytics refreshes without depreciation exposure. The model is gaining fastest traction in Brazil's Mato Grosso soybean belt and Australia's Murray-Darling irrigation districts, where seasonal imagery frequency demands exceed the utilization economics of owned equipment.
Agriculture Drone Mapping and Analytics Market Segmentation
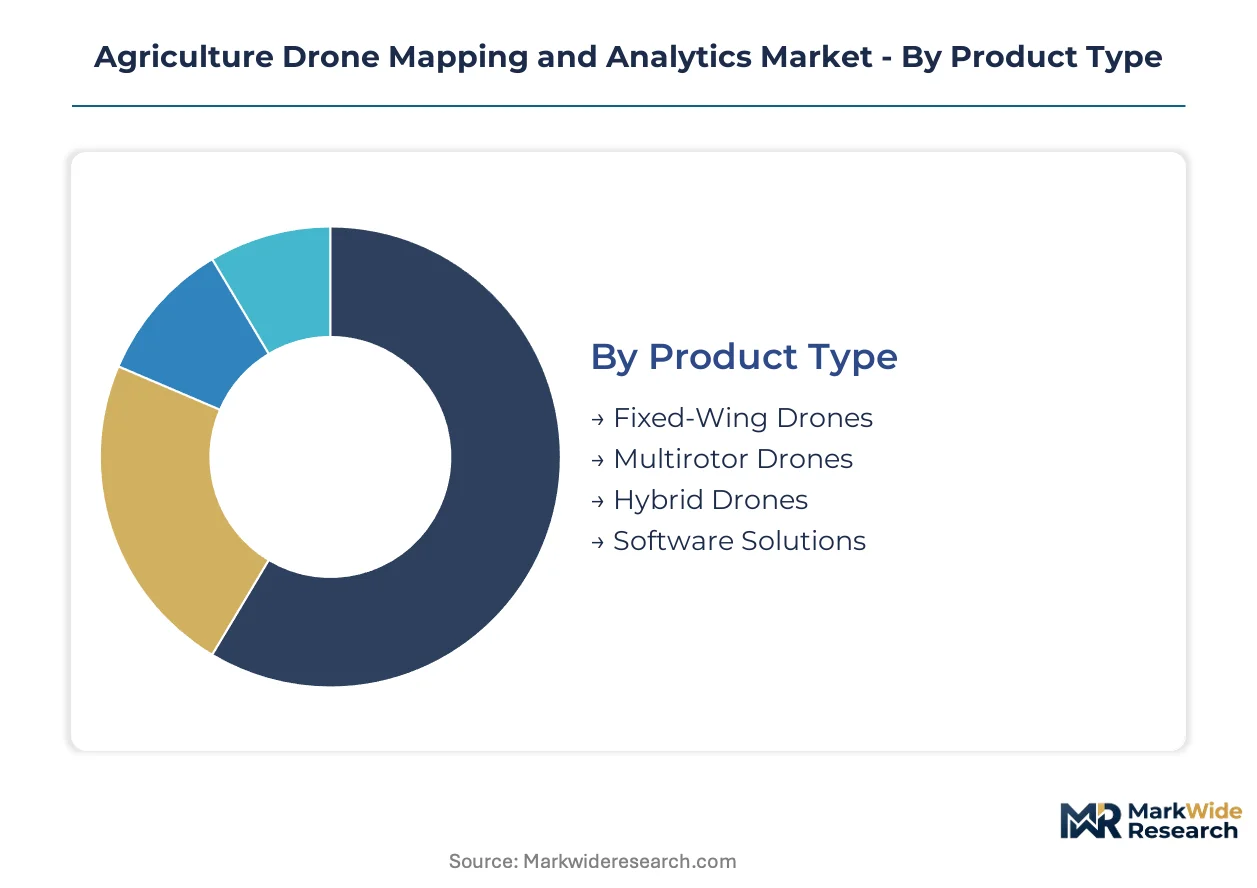
Equipment refresh cycles and software subscription renewals create distinct revenue rhythms across product categories. Application segmentation reveals which agronomic workflows command premium analytics pricing.
Product Type:
Upgrade momentum concentrates where battery chemistry improvements and sensor miniaturization justify fleet replacement.
- Fixed-Wing Drones:Extended flight endurance of 90-120 minutes suits broad-acre cereal operations across Brazil's Mato Grosso soybean belt. Brazilian cooperatives favor these platforms for variable-rate prescription mapping where coverage speed determines per-acre service economics.
- Multirotor Drones:Vertical takeoff flexibility and sub-$15,000 entry pricing dominate smallholder adoption in fragmented European vineyard parcels. Australia's wheat belt operators deploy these for precision irrigation scouting where maneuverability around infrastructure matters more than endurance.
- Hybrid Drones:VTOL configurations with fixed-wing cruise efficiency address the coverage-flexibility tradeoff for mid-scale operations.
- Software Solutions:Cloud-based analytics subscriptions displace perpetual licenses as farmers prioritize outcome-based advisory over hardware ownership.
Multirotor drones sit at the top of the volume ranking, with software solutions climbing the fastest.
Application:
Commercial value concentrates where imagery translates directly into input cost reduction or yield protection.
- Precision Agriculture:Variable-rate application maps generated from NDVI imagery enable targeted fertilizer and pesticide placement. Large-scale Brazilian row-crop operations generate the densest demand for prescription zoning that cuts input waste.
- Crop Monitoring:Early stress detection through multispectral indices supports insurance documentation and harvest timing decisions. Australian wheat growers facing water scarcity pay premium subscription rates for moisture deficit alerts.
- Soil Analysis:Electromagnetic conductivity mapping from drone-mounted sensors supplements grid sampling for variable-depth tillage planning.
- Livestock Management:Thermal imaging for herd location and health monitoring expands in extensive grazing systems where labor coverage is sparse.
Precision agriculture commands the revenue concentration, with crop monitoring expanding most quickly.
End User:
Procurement authority and technical sophistication determine subscription pricing power and hardware ownership preference.
- Farmers:Direct-to-grower SaaS channels bypass equipment dealers, with mobile-first platforms delivering field-specific prescriptions. Mid-scale Australian irrigators favor subscription imagery services over capital-intensive fleet ownership.
- Agricultural Consultants:Multi-client service models justify sensor upgrade investments that individual growers cannot amortize. European vineyard advisors aggregate demand across small parcels to achieve platform utilization thresholds.
- Agronomists:Technical fluency with spectral indices supports premium advisory fees tied to outcome performance.
- Research Institutions:Long-term imagery archives train machine learning models for yield prediction algorithms.
Farmers represent the largest addressable base, with agricultural consultants capturing margin fastest.
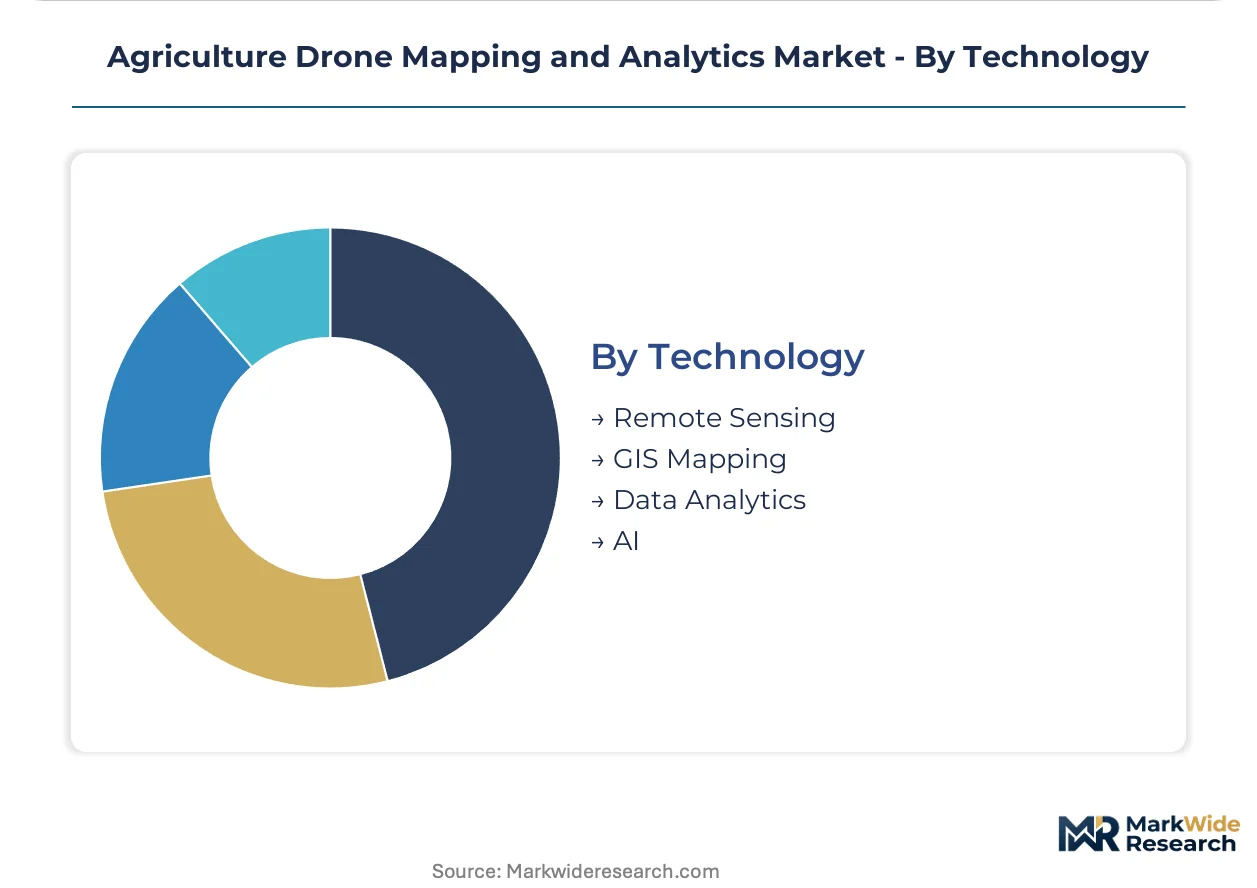
Technology:
Capability layering determines which data streams command recurring subscription value versus one-time processing fees.
- Remote Sensing:Multispectral and thermal camera payloads capture crop health signatures invisible to standard RGB imaging. Chinese manufacturing clusters in Shenzhen drive down sensor costs for NDVI-capable modules.
- GIS Mapping:Georeferenced orthomosaics integrate with farm management information systems for prescription generation. Proprietary data formats from drone platforms resist seamless FMIS ingestion, forcing API development investments.
- Data Analytics:Cloud processing pipelines convert raw imagery into actionable agronomic intelligence within 24-hour turnaround windows.
- AI:Machine learning models trained on multi-season archives converge with ground-truth harvest data for predictive yield advisory.
Remote sensing anchors current deployment, with AI representing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt generates denser prescription mapping demand than Australia's wheat regions, though water scarcity in the latter commands steeper per-acre analytics premiums.
United States
The FAA's Part 107 certification framework expands the commercial operator pool across Midwest corn-soy operations. Beyond-visual-line-of-sight waivers remain bottlenecked at 90-180 day approval windows, compressing seasonal deployment windows for time-critical crop monitoring. California's Central Valley irrigation districts cluster drone service providers offering subscription-based imagery to deficit-conscious almond and pistachio growers.
Brazil
Large-scale row-crop cooperatives in Mato Grosso and Goiás drive variable-rate fertilizer application from drone-generated NDVI maps. ANVISA's agrochemical registration timelines indirectly shape flight scheduling around restricted application windows. São Paulo state's precision agriculture technology corridor hosts equipment distributors integrating Chinese-manufactured multispectral sensors with local agronomic advisory networks.
Australia
Murray-Darling Basin irrigators facing allocation cuts pay premium subscription rates for moisture deficit alerts and precision irrigation zoning. The Civil Aviation Safety Authority's standard operating conditions for commercial drones below 400 feet enable rapid deployment across broad-acre wheat and barley operations. Queensland's sugarcane regions concentrate thermal imaging demand for irrigation system leak detection in water-stressed coastal districts.
China
Shenzhen and Guangdong manufacturing clusters scale output of NDVI-capable multispectral modules, driving down sensor costs for domestic and export UAV platforms. The Civil Aviation Administration of China's pilot licensing requirements for commercial operations above 120 meters shape fleet operator certification investments. Yangtze River Delta rice producers adopt drone-based yield prediction services to optimize procurement timing for state grain reserve sales.
France
Bordeaux and Champagne vineyard operators deploy hyperspectral sensors for early fungal stress detection, commanding outcome-based pricing tied to spray reduction guarantees. EASA's specific category risk assessments under EU Regulation 2019/947 extend deployment timelines for flights over populated wine tourism areas. Occitanie's cereal cooperatives aggregate smallholder demand to achieve platform utilization thresholds for shared drone service networks.
Agriculture Drone Mapping and Analytics Market Competitive Landscape
Chinese producers anchor the hardware tier through Shenzhen-based component manufacturing and integrated platform assembly; European and North American specialists hold the analytics and software integration tier through farm management system partnerships. The vendor structure concentrates around three strategic archetypes: vertically integrated hardware-software conglomerates, pure-play analytics platforms, and specialized sensor manufacturers. Competitive maneuvering centers on backward integration into sensor supply chains and forward integration into outcome-based advisory contracts.
Within the hardware-dominant tier, DJI leverages its Shenzhen supply base to capture volume across consumer and prosumer UAV platforms. Trimble Inc. and Parrot Drone SAS occupy positions emphasizing precision agriculture software integration and specialized crop-scouting sensors respectively. These three represent contrasting geographic and strategic anchors: Chinese manufacturing scale, American enterprise software heritage, and European specialized application focus.
| Leading Market Players |
|---|
| DJI |
| Trimble Inc. |
| Parrot Drone SAS |
| Yamaha Motor Co., Ltd. |
| AgEagle Aerial Systems Inc. |
| PrecisionHawk |
| AeroVironment, Inc. |
| DroneDeploy |
| Pix4D SA |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up regional flight networks in Australia's Murray-Darling Basin and Brazil's Mato Grosso are consolidating procurement power to compress sensor costs and standardize per-acre subscription pricing for deficit-hedging growers and large-scale cooperatives.
Pricing Analysis
Capacity additions in Shenzhen sensor manufacturing clusters are reshaping price floors for NDVI-capable multispectral modules. Pricing stratifies across premium hyperspectral configurations for European vineyard fungal detection, standard four-band crop health packages, and economy RGB-only tiers for basic scouting. Cost compression in economy tiers is intensifying because Chinese manufacturing scale is flooding export markets with sub-$2,000 camera payloads. Smallholder vineyard operators in fragmented European parcels exhibit highest price sensitivity, while Australian irrigation districts facing water allocation cuts show lowest sensitivity to subscription rates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Brazilian cooperatives and Australian service networks, bypassing traditional agricultural equipment dealers. Component manufacturing concentrates in China, South Korea, and Taiwan, with Shenzhen supplying multispectral imagers, Seoul providing lithium-polymer battery cells, and Hsinchu delivering semiconductor logic for flight controllers. The chain draws from rare earth elements for magnet production, silicon wafers for sensor fabrication, and cobalt compounds for battery cathodes. Single-source vulnerability around Shenzhen-based imager suppliers exposes equipment assemblers to geopolitical trade restrictions. Distribution runs through regional agronomic advisory partnerships that bundle flight services with prescription analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agriculture drone mapping and analytics functions as a stable compounder, with recurring SaaS subscription revenue from precision irrigation and variable-rate application services generating predictable cash flow visibility across seasonal farming cycles.
For Market Incumbents: Acquire specialized hyperspectral sensor developers to lock in vineyard and orchard differentiation before European competitors consolidate this tier. Secure backward integration into Chinese imager supply through exclusive offtake agreements with Shenzhen manufacturing clusters to defend margin position against hardware commoditization. Counter the threat of pure-play analytics platforms bypassing equipment ownership by embedding proprietary AI yield prediction into farm management information system partnerships. For New Entrants and Emerging Players: Enter via direct-to-grower mobile platforms targeting mid-scale Australian irrigators who have abandoned capital-intensive fleet ownership. White-space concentrates in AI-driven outcome-based advisory contracts tied to harvest performance, particularly in water-stressed wheat regions where deficit alerts command premium pricing. Brazil's Mato Grosso soybean belt presents the most penetrable geography for subscription imagery services delivered through regional agronomic consultant partnerships rather than equipment dealer channels. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play analytics platforms lacking hardware manufacturing exposure but possessing multi-season imagery archives for machine learning training. Long-term viability centers on recurring revenue durability as farming cooperatives shift from ownership to service models. Target acquisition archetypes are regional flight networks with established FAA Part 107 operator pools and exclusive territory coverage in high-value specialty crop districts. Monitor FAA beyond-visual-line-of-sight waiver approval velocity as the critical inflection signal for scalable service economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with FMIS | Seamless data ingestion into Trimble and John Deere systems reduces manual translation friction for agronomists. |
| Acquisition of Specialist Sensor Developers | Hyperspectral capability acquisition targets European vineyard markets where fungal detection commands outcome-based pricing. |
| Geographic Expansion via Regional Flight Networks | Service coverage buildout in Queensland sugarcane districts addresses irrigation leak detection demand. |
| Strategic Partnership with Chinese Component Suppliers | Exclusive offtake agreements with Shenzhen imager manufacturers secure supply priority during semiconductor allocation volatility. |
| Product Launch: AI Yield Prediction Module | Machine learning advisory contracts tied to harvest performance capture value from multi-season imagery archives. |
Research Methodology
Bottom-up farmer and agricultural consultant modeling reconciled against top-down sensor manufacturing and flight service provider tracking forms the analytical core. Primary interviews with precision agriculture directors at Brazilian cooperatives, irrigation managers in Australia's Murray-Darling Basin, vineyard technology officers in France, FAA Part 107 certified operators, and agronomic software product managers were validated against secondary sources including FAA regulatory filings, EASA operational guidance documents, ANVISA agrochemical registration timelines, Civil Aviation Safety Authority standard operating conditions, and equipment distributor shipment data from São Paulo state's precision agriculture corridor.
Input-output matrices connect sensor unit economics, flight hour utilization rates, and subscription renewal patterns to segment-level revenue estimates across the projection horizon. Segmentation dimensions modeled include drone platform type, agronomic application workflow, end-user procurement authority, imaging technology tier, and regional regulatory framework cluster. CAGRs were derived from fitted growth curves anchored to equipment refresh cycles and software subscription adoption S-curves. Industry-specific forecast inputs incorporate lithium-polymer battery energy density improvement trajectories and machine learning model accuracy convergence with ground-truth harvest data.
The model holds under stable regulatory clarity for commercial drone operations; deviation in FAA BVLOS waiver timelines or EASA specific category risk assessment stringency would shift service scalability assumptions. Forecasts reflect documented base conditions around sensor cost decline rates and farming cooperative SaaS conversion velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Global Precision Livestock Farming Market