
 Telemetry-Linked Smart Fertilizer Program Market | 2026-2036
Telemetry-Linked Smart Fertilizer Program Market Size, Share, and Industry Trends Forecast 2026-2036
Telemetry-Linked Smart Fertilizer Program Market Insights
Subscription bundling of hardware, cloud analytics, and agronomic advisory is shifting how commercial growers evaluate total cost of ownership against piecemeal procurement. Nutrien leverages its retail distribution network to anchor telemetry-enabled programs across North American farm operations. Yara International competes through deep specialization in nitrogen optimization algorithms tied to its existing fertilizer manufacturing footprint. Bayer differentiates by extending its digital agriculture platform into integrated seed-nutrient protocols that bundle genetic performance data with fertility recommendations.
Telemetry-linked smart fertilizer programs combine soil-mounted IoT sensors, wireless data transmission infrastructure, and cloud-based analytics engines to deliver variable-rate nutrient prescriptions with spatial resolution below one hectare; these systems primarily reduce input waste while maintaining yield targets through real-time canopy feedback loops. IoT sensor deployments dominate current program revenue due to established hardware margins and recurring calibration service contracts. Satellite imaging represents the fastest-expanding technology segment as constellation providers drive down per-acre imagery costs and machine-learning pipelines shorten prescription turnaround from days to hours. Data analytics programs capture disproportionate margin pools because advisory subscriptions renew at higher rates than equipment leases and carry minimal physical logistics overhead.
The EPA enforces Clean Water Act nutrient management plans that mandate documented fertilizer application rates near watersheds, while the USDA channels conservation compliance incentives toward verified precision agriculture adoption. ISO 11783 and IEEE 802.15.4 standards govern interoperability between tractor-mounted controllers and third-party sensor networks, reducing vendor lock-in and lowering grower switching costs. Stakeholders must monitor whether emerging state-level carbon intensity scoring for agricultural commodities creates preferential market access for farms with auditable telemetry records.
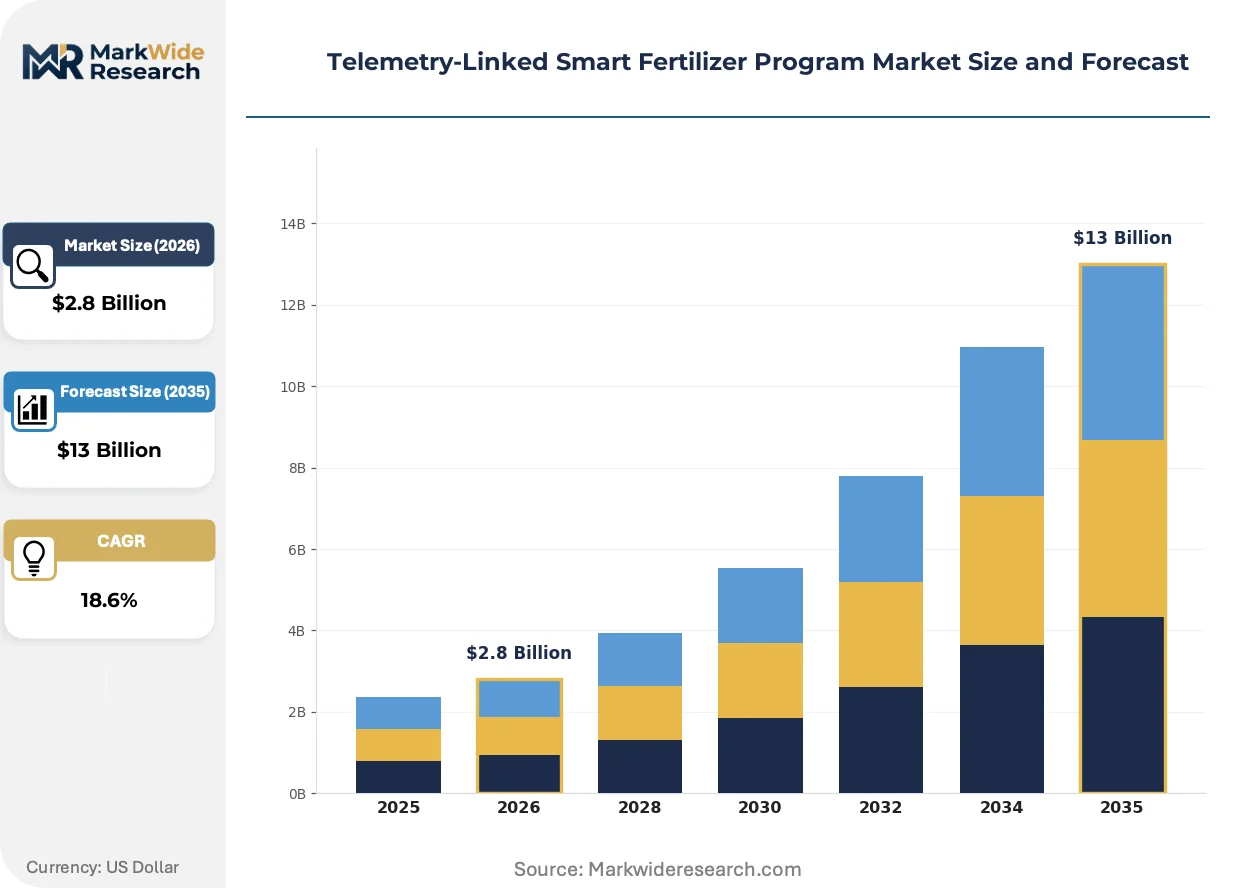
Market Dynamics
Subscription bundling of hardware, cloud analytics, and agronomic advisory is compressing procurement cycles and locking in multi-year revenue streams for program providers across the Corn Belt and comparable precision agriculture clusters.
Growth Catalysts
- EPA Clean Water Act enforcement:Documented fertilizer application rates near watersheds now carry mandatory telemetry verification, compelling commercial growers toward auditable nutrient management systems.
- USDA conservation compliance incentives:Verified precision agriculture adoption unlocks cost-share payments that offset program subscription fees for operations exceeding 500 contiguous acres.
- Machine learning pipelines:Prescription turnaround compression from days to hours is absorbing grower tolerance for advisory delays and expanding addressable acreage.
Market Restraints
- Sensor hardware cost volatility:Semiconductor supply concentration in East Asian foundries creates procurement uncertainty for soil-mounted IoT device manufacturers.
- Wireless infrastructure gaps:Rural cellular dead zones in Nebraska and Kansas plains fragment program coverage and force redundant private network investments.
- Labor substitution limitations:Agronomic advisory services require certified crop consultants whose training pipelines operate on 3-4 year cycles.
Strategic Opportunities
- Carbon intensity scoring regimes:Emerging state-level protocols for agricultural commodities create preferential market access for farms with auditable telemetry records.
- Satellite-IoT convergence:Constellation providers integrating canopy spectral data with ground sensor networks enable hybrid prescription models at sub-hectare resolution.
- Cooperative procurement channels:Grain elevator networks and regional farm supply cooperatives are absorbing program distribution from direct manufacturer sales.
Industry Challenges
- ISO 11783 interoperability gaps:Tractor-mounted controller firmware fragmentation forces custom API development for each equipment manufacturer integration.
- Data sovereignty compliance:Cross-border cloud storage restrictions complicate program delivery for Canadian growers operating near the US border.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemetry-Linked Smart Fertilizer Program Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Satellite Imaging, Automated Drones, Wireless Networks, Data Analytics Application: Cereal Crops, Horticulture, Turf Management, Specialty Farming, Arboriculture, Greenhouse Cultivation End User: Commercial Growers, Agricultural Cooperatives, Organic Farms, Research Institutions, Urban Farming Initiatives Program Model: Subscription Service, Pay-Per-Use, Customized Fertilizer Management, Data-Driven Advisory, Remote Monitoring |
| Companies Covered | Nutrien, Bayer, Corteva, Syngenta Group, Yara International, Trimble, BASF, ICL Group, The Mosaic Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemetry-Linked Smart Fertilizer Program Market Trends and Innovations
Machine learning inference at the edge is compressing prescription latency while satellite constellation densification is collapsing per-acre imagery costs below the threshold for mid-scale commercial adoption.
Satellite imaging is absorbing prescription generation workflows previously dominated by soil-mounted sensor networks. Large-scale row-crop operations in Illinois and Iowa are deploying hybrid systems that weight satellite-derived canopy indices against ground-truth moisture readings. The structural consequence is that hardware-centric revenue pools are shifting toward analytics-heavy subscription tiers as imagery becomes commoditized.
The EPA's nutrient management plan documentation requirements are mandating timestamped application records with geospatial verification. Commercial growers within 50 miles of impaired watersheds must submit telemetry-linked proof of variable-rate compliance. Corn Belt operations are responding by pre-purchasing three-year program bundles that bundle audit-ready data archiving with agronomic advisory.
Cooperative procurement through grain elevator networks is displacing direct manufacturer relationships for programs serving operations under 2,000 acres. These intermediaries aggregate demand across 15-40 member farms to negotiate volume-tiered pricing and shared agronomist access. The pattern is most visible across eastern Nebraska and western Iowa, where elevator consolidation has created three-to-five dominant local buyers with sufficient scale to command custom program configurations.
Telemetry-Linked Smart Fertilizer Program Market Segmentation
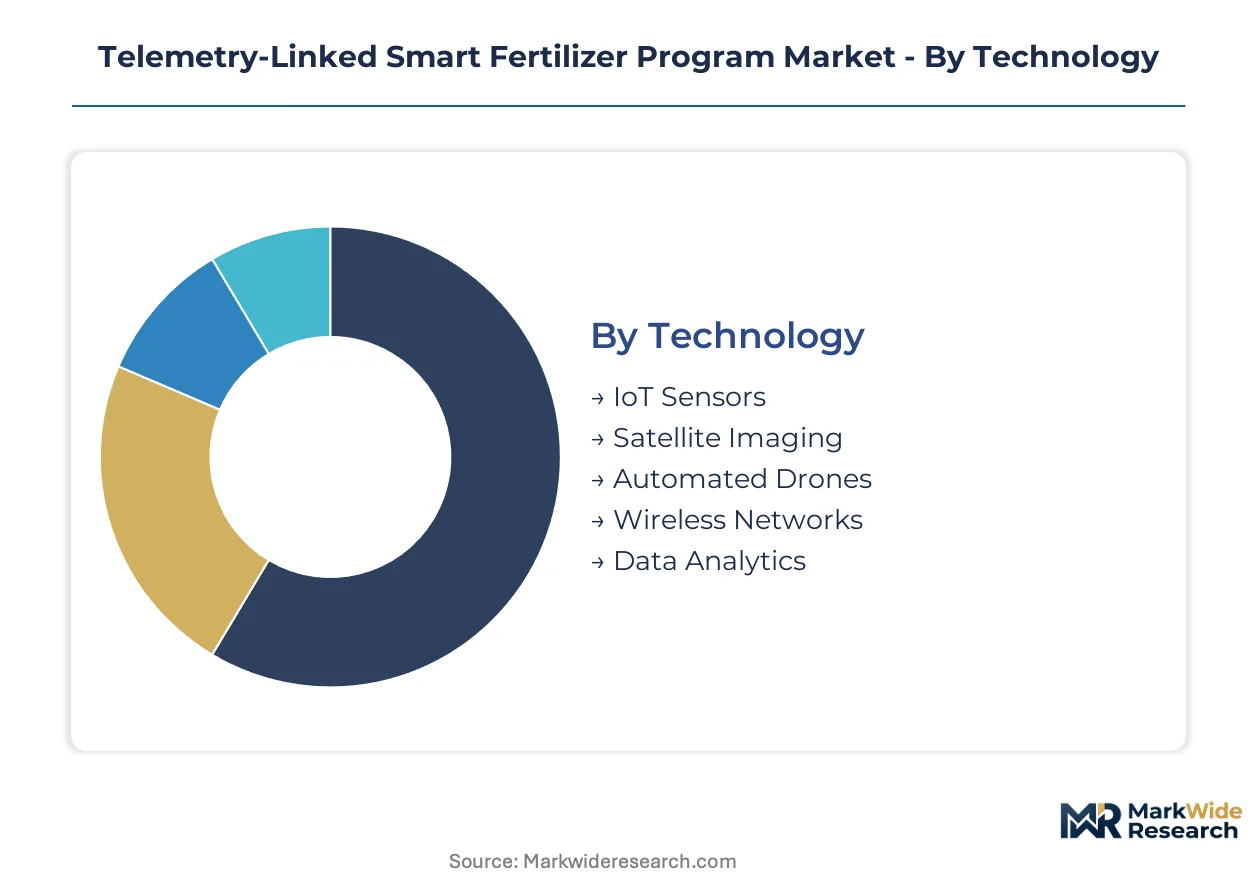
Commercial growers evaluate telemetry-linked fertilizer programs through multiple lenses simultaneously—technology performance, crop compatibility, procurement flexibility, and total cost structure. Each segmentation dimension reveals distinct buyer priorities that shape vendor positioning and program design across the Corn Belt and comparable precision agriculture clusters.
Technology:
Hardware reliability and prescription latency dominate procurement decisions as growers weigh upfront capital against recurring service value.
- IoT Sensors:Soil-mounted devices measure moisture, nitrogen, and electrical conductivity at 15-minute intervals, transmitting via LoRaWAN or cellular modems. Corn Belt operations above 2,000 acres standardize on these units for sub-hectare zone management, though semiconductor supply volatility creates procurement uncertainty for device manufacturers dependent on East Asian foundries.
- Satellite Imaging:Constellation providers now deliver multispectral canopy data at sub-meter resolution with turnaround below six hours. Illinois and Iowa row-crop operations are absorbing these services fastest as per-acre imagery costs collapse below the threshold for mid-scale commercial adoption.
- Automated Drones:UAV-mounted sensors enable targeted scouting across irregular field geometries with on-board edge computing for immediate anomaly flagging.
- Wireless Networks:Private LTE and mesh infrastructure bridge cellular dead zones in Nebraska and Kansas plains where public coverage fragments program delivery.
- Data Analytics:Cloud-based prescription engines integrate multi-source inputs into variable-rate application maps with machine learning model retraining on seasonal yield outcomes.
IoT Sensors leads on scale; Satellite Imaging leads on momentum.
Application:
Crop value per acre and input cost sensitivity determine technology investment intensity across different cultivation types.
- Cereal Crops:Corn and soybean operations across the US Corn Belt generate the dominant revenue base for telemetry programs, with variable-rate nitrogen application delivering documented compliance for EPA Clean Water Act nutrient management plans near impaired watersheds.
- Horticulture:High-value vegetable and fruit operations in California's Central Valley and Florida's ridge districts absorb precision fertigation systems with greenhouse-grade sensor density.
- Turf Management:Golf courses and municipal parks deploy moisture-linked irrigation-fertilizer integration to minimize runoff liability and labor inputs.
- Specialty Farming:Vineyards and orchards utilize canopy spectral monitoring for targeted bloom-stage nutrient interventions.
- Arboriculture:Tree crop operations leverage deep-soil moisture probes paired with foliar analysis for perennial nutrient cycling optimization.
- Greenhouse Cultivation:Controlled-environment agriculture deploys closed-loop hydroponic nutrient monitoring with real-time ion-selective electrode arrays.
Cereal Crops anchors program volume; Horticulture commands the steepest expansion trajectory as per-acre technology economics improve.
End User:
Scale and organizational structure shape procurement channel preferences and service customization requirements.
- Commercial Growers:Operations exceeding 500 contiguous acres standardize on three-year subscription bundles that combine audit-ready data archiving with agronomic advisory, particularly within 50 miles of impaired watersheds where EPA mandates telemetry verification.
- Agricultural Cooperatives:Grain elevator networks across eastern Nebraska and western Iowa aggregate demand across 15-40 member farms to negotiate volume-tiered pricing and shared certified crop consultant access.
- Organic Farms:Certification compliance drives adoption of documented input tracking with blockchain-anchored application records for audit trails.
- Research Institutions:University extension programs and USDA experiment stations utilize high-density sensor grids for cultivar-nutrient interaction studies.
- Urban Farming Initiatives:Vertical and rooftop operations deploy compact IoT-enabled fertigation systems with cloud dashboards for distributed site management.
Commercial Growers represents the installed base; Agricultural Cooperatives are gaining share fastest through consolidated procurement channels.
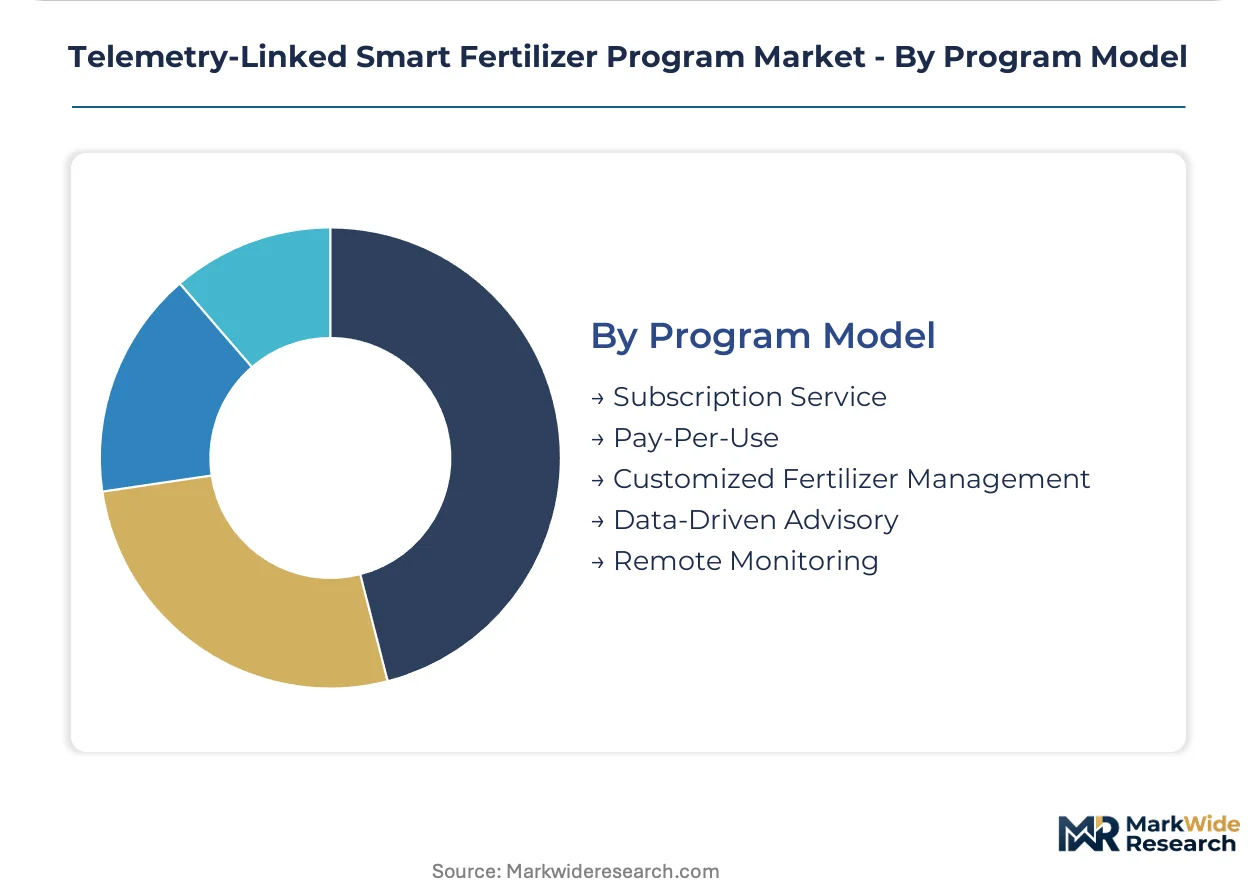
Program Model:
Revenue recognition and customer lifetime value hinge on contractual structure and service bundling depth.
- Subscription Service:Annual or multi-year contracts bundle hardware leasing, cloud analytics access, and agronomic advisory into predictable per-acre fees that lock in grower relationships across multiple cropping cycles.
- Pay-Per-Use:Transactional pricing for imagery-derived prescriptions or sensor calibration services appeals to smaller operations testing precision agriculture viability without capital commitment.
- Customized Fertilizer Management:Tailored nutrient protocols integrate soil testing, tissue analysis, and seasonal adjustment with dedicated agronomist assignment.
- Data-Driven Advisory:Standalone analytics subscriptions without hardware provision target growers with existing sensor infrastructure seeking prescription optimization.
- Remote Monitoring:Alert-only services notify growers of threshold breaches without full prescription generation, serving as entry-tier offerings for price-sensitive adopters.
Subscription Service dominates revenue concentration; Pay-Per-Use climbs fastest as cooperative procurement lowers trial barriers for smaller operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture telemetry originated in the United States Corn Belt during the 1990s, where grid soil sampling and early GPS guidance first merged into commercial nutrient management protocols.
United States
Commercial corn and soybean operations above 2,000 contiguous acres drive program adoption across Illinois and Iowa. The EPA enforces Clean Water Act nutrient management plans within 50 miles of impaired watersheds, mandating timestamped application records with geospatial verification. Eastern Nebraska grain elevator networks now aggregate demand across 15-40 member farms for volume-tiered subscription pricing.
Brazil
Soybean expansion in Mato Grosso and Goiás creates demand for variable-rate phosphorus and potassium application at scale. The national agricultural research corporation Embrapa validates precision agriculture protocols for tropical soil conditions. Mato Grosso farm operations exceeding 5,000 hectares standardize on three-year telemetry bundles with Portuguese-language agronomic advisory.
Canada
Prairie canola and wheat producers adopt subscription services to document environmental farm plan compliance for export market access. Health Canada and PMRA coordinate pesticide-fertilizer interaction monitoring near the Great Lakes watershed. Saskatchewan's agricultural extension network distributes cooperative procurement channels for operations under 1,500 acres.
Germany
Sugar beet and potato growers in Lower Saxony deploy sensor networks to meet EU Nitrates Directive application windows. The German Fertilizer Ordinance mandates documented nutrient balances for farms above certain livestock thresholds. Bavarian dairy-crop integrated operations lead adoption of closed-loop manure-chemical fertilizer blending with telemetry verification.
Australia
Broadacre wheat and barley operations in Western Australia address phosphorus stratification through variable-rate deep placement. The national sustainable agriculture initiative channels cost-share payments toward verified precision adoption. New South Wales Riverina irrigation districts deploy hybrid satellite-ground sensor systems for cotton nutrient scheduling.
Telemetry-Linked Smart Fertilizer Program Market Competitive Landscape
The competitive structure tilts toward integrated input manufacturers with captive distribution networks. Three to five conglomerates anchor program delivery through multi-year subscription bundles, while specialized sensor hardware vendors and regional analytics boutiques occupy niche positions. Strategic moves concentrate on retail network consolidation and cloud platform interoperability rather than standalone technology differentiation.
Among North American input manufacturers, Nutrien, Bayer, and Corteva occupy positions that exemplify the integrated-agronomy archetype. Nutrien leverages its retail distribution infrastructure to anchor telemetry-enabled programs across commercial farm operations. Bayer extends its digital agriculture platform into seed-nutrient protocol bundling. Corteva represents the mid-tier challenger position, competing through crop protection integration rather than standalone fertilizer specialization.
| Leading Market Players |
|---|
| Nutrien |
| Bayer |
| Corteva |
| Syngenta Group |
| Yara International |
| Trimble |
| BASF |
| ICL Group |
| The Mosaic Company |
| Others |
Pricing and Supply Chain Analysis
Family-owned farm supply cooperatives across the Corn Belt anchor downstream distribution, compressing margins for direct manufacturer sales while reinforcing multi-year subscription pricing discipline through volume aggregation.
Pricing Analysis
Three-year subscription bundles across premium analytics, standard sensor leasing, and economy advisory tiers dominate commercial procurement. Price differentiation hinges on audit-ready data archiving depth and dedicated agronomist access hours. Cost compression in economy tiers is intensifying because cooperative procurement channels aggregate demand across 15-40 member farms. Mid-scale operations under 2,000 acres exhibit highest price sensitivity; large-scale growers above 5,000 contiguous acres prioritize compliance assurance over per-acre fees.
Supply Chain Analysis
Semiconductor supply for soil-mounted IoT devices rests on Taiwanese and South Korean foundries, with Chinese packaging houses feeding final assembly. LoRaWAN radio modules, nitrogen-selective electrodes, and cellular modems constitute critical component dependencies. Single-source vulnerability in 5G modem chipsets creates procurement uncertainty when foundry capacity shifts to consumer electronics. Distribution runs through grain elevator networks and regional farm supply cooperatives that displace direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
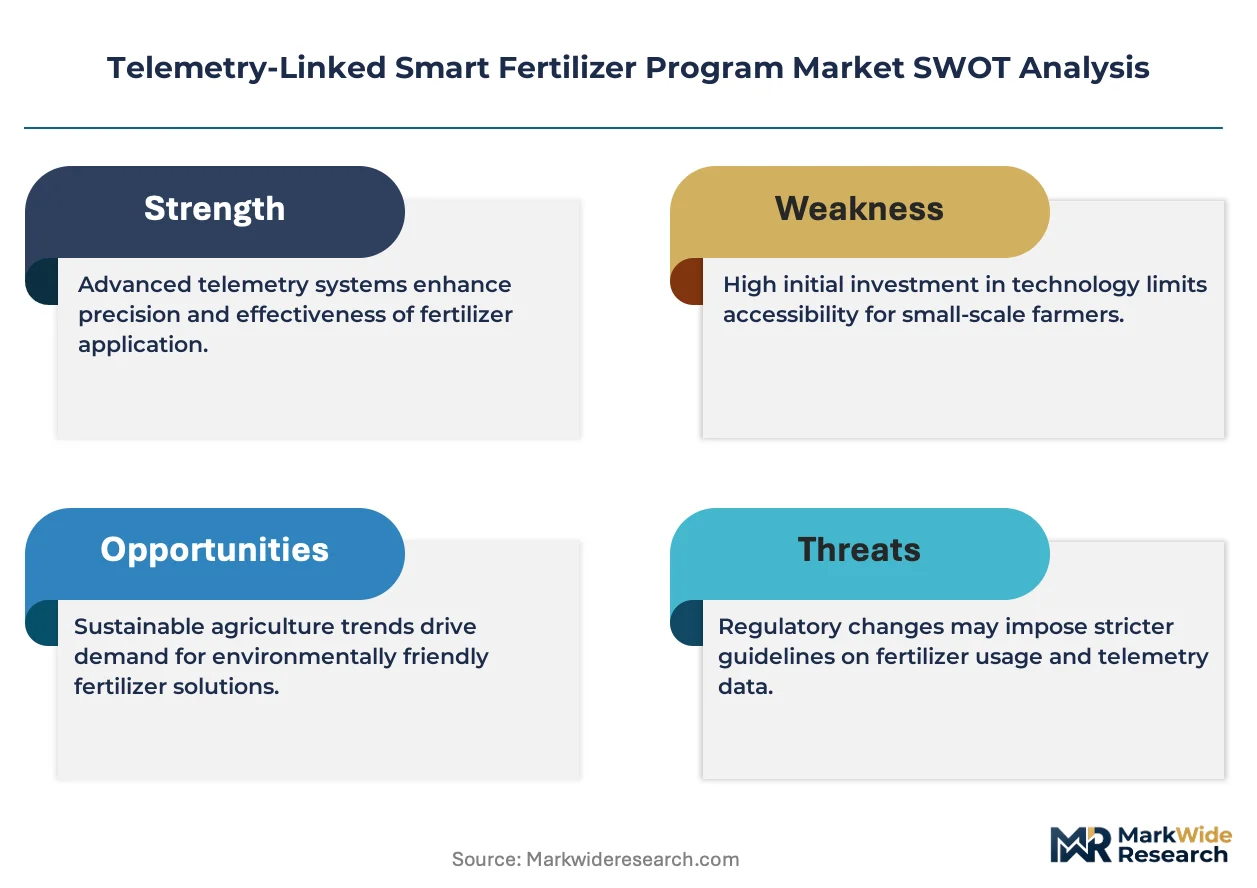
Analyst Recommendations
Telemetry-linked smart fertilizer programs compound steadily as regulatory compliance mandates harden across watershed jurisdictions, embedding recurring revenue streams into agricultural input procurement.
For Market Incumbents: Lock in cooperative procurement exclusivity across eastern Nebraska and western Iowa elevator networks before regional consolidation completes. Anchor three-year subscription bundles with audit-ready data archiving to defend against satellite-imaging pure-plays eroding hardware-centric revenue pools. Prioritize ISO 11783 interoperability certification to reduce grower switching costs and entrench platform stickiness. For New Entrants and Emerging Players: Mid-scale commercial growers between 500-2,000 acres represent the most penetrable buyer archetype underserved by direct manufacturer sales teams. Target Saskatchewan canola operations and Australian wheat broadacre systems where cooperative procurement channels remain fragmented. Deploy pay-per-use imagery prescriptions as low-friction entry tier before upselling to full subscription bundles. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized sensor hardware vendors facing margin compression as satellite imagery commoditizes prescription generation. Long-term viability favors analytics-heavy platforms with agronomist advisory subscriptions renewing above equipment lease rates. Watch for state-level carbon intensity scoring protocols as inflection indicator that would re-rate farms with auditable telemetry records.| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Procurement Exclusivity | Elevator networks in Nebraska and Iowa aggregate demand across 15-40 member farms, locking in multi-year subscription volumes. |
| Satellite-IoT Convergence Development | Hybrid prescription models integrating constellation canopy data with ground sensor networks enable sub-hectare resolution at collapsed imagery costs. |
| Agronomic Advisory Certification Pipeline | Certified crop consultant training cycles spanning 3-4 years create capability scarcity that entrenches incumbent advisory subscription renewals. |
| Carbon Intensity Scoring Compliance | Auditable telemetry records unlock preferential market access under emerging state-level agricultural commodity protocols. |
| ISO 11783 Interoperability Investment | Standardized tractor-mounted controller integration reduces vendor lock-in and accelerates grower platform switching. |
Research Methodology
Coverage spans the United States Corn Belt, Canadian Prairie provinces, Brazilian Cerrado, and Australian wheatbelt, with primary inputs from each. The study combines interviews with certified crop consultants, grain elevator procurement managers, precision agriculture platform engineers, and EPA regional compliance officers with secondary validation from USDA conservation program databases, state environmental agency nutrient management filings, and customs records for IoT sensor hardware imports. Bottom-up acreage adoption estimates triangulate against top-down input manufacturer revenue disclosures.
Rate-of-change decomposition across the analysis window separates hardware deployment velocity from analytics subscription renewal trajectories. Segmentation dimensions modeled include technology type, crop application, end-user scale tier, and program contractual structure. CAGRs derive from acreage penetration curves weighted by per-acre subscription pricing tiers and validated against conservation cost-share payment disbursement trends.
Underlying measurement precision varies by segment; satellite imaging adoption carries tighter precision than automated drone deployment given constellation provider disclosure practices. Forecasts reflect assumptions about EPA enforcement continuity, semiconductor supply normalization, and cooperative procurement channel consolidation. A small set of triggers—state carbon scoring mandate timing, cellular infrastructure buildout pace in Kansas plains, and agronomist certification pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Agricultural Mapping Services Market