
 Agricultural Sensors Market | 2026-2036
Agricultural Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Sensors Market Insights
Silicon photonics is repositioning optical sensor economics by displacing legacy fiber-optic assemblies in greenhouse spectral monitoring. Deere & Company leverages its precision agriculture platform to anchor North American on-field deployment networks. AGCO Corporation competes through deep manufacturer-dealer channel control in row-crop sensor integration. Texas Instruments sustains component supply advantages through in-house production of ultra-low-power analog front-ends for soil moisture probes.
Agricultural sensors are electromechanical or optoelectronic transducers that convert biophysical variables—soil electrical conductivity, canopy reflectance, ambient vapor pressure deficit—into processable signals, typically operating across temperature ranges of −40°C to +85°C with IP67 ingress protection for sustained field exposure. Their primary purpose is to generate actionable data streams that optimize input application timing, irrigation scheduling, and crop protection interventions. Soil moisture sensors occupy the largest installed base among product types due to decades of proven return-on-investment in irrigated row-crop systems, while image sensors represent the fastest-expanding category as drone-mounted multispectral units penetrate mid-size farm operations. IoT-based technology leads deployment architecture by enabling edge-to-cloud data pipelines, though acoustic sensors in livestock monitoring command premium pricing through specialized signal-processing requirements.
The EPA regulates pesticide application timing systems that integrate sensor data, while the EU Green Deal and F-Gas Regulation mandate emissions-transparent greenhouse operations that require continuous environmental sensing. USDA conservation programs shape demand by cost-sharing precision irrigation hardware that embeds soil moisture and weather sensors. Stakeholders must monitor whether EU CSRD sustainability disclosure rules will mandate sensor-verified carbon intensity reporting for agricultural supply chains.
Market Dynamics
Silicon photonics is consolidating optical sensor economics by displacing legacy fiber-optic assemblies, while EU F-Gas Regulation and the Green Deal mandate continuous emissions monitoring in Dutch greenhouse clusters, compressing deployment timelines for environmental sensing infrastructure.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates emissions-transparent greenhouse operations across member states, forcing continuous environmental sensing upgrades in Dutch and Spanish glasshouse facilities.
- Precision livestock tracking:North American dairy and feedlot operations deploy real-time biometric sensors for animal health monitoring, reducing mortality rates and veterinary intervention costs.
- Silicon photonics:This fabrication platform replaces discrete optical components in spectral monitoring systems, collapsing bill-of-materials costs for greenhouse gas analyzers.
Market Restraints
- Input cost volatility:Rare earth elements in magnetostrictive soil probes face price instability tied to Chinese export quotas, squeezing margin structures for probe manufacturers.
- Supply concentration risk:Analog front-end semiconductors for ultra-low-power soil sensors concentrate in Taiwanese foundry capacity, exposing lead times to geopolitical friction.
- Technical limitation:Salinity interference degrades electrical conductivity sensor accuracy in coastal irrigation districts, limiting deployment in Mediterranean and Southeast Asian delta regions.
Strategic Opportunities
- Underpenetrated geography:Brazilian cerrado soybean operations lack soil moisture sensor density relative to US Corn Belt benchmarks, presenting whitespace for calibrated probe networks.
- Technology convergence:Edge AI chips fused with hyperspectral imaging enable real-time crop stress classification without cloud latency, opening mid-size farm segments previously priced out of drone analytics.
- Regulatory tailwind:EU CSRD sustainability disclosure rules will likely mandate sensor-verified carbon intensity reporting, creating compliance-driven demand for supply chain monitoring hardware.
Industry Challenges
- Field calibration expertise:Soil moisture sensors require site-specific calibration against gravimetric reference methods, and agronomy-trained technicians remain scarce in emerging agricultural regions.
- Legacy system integration:Greenhouse climate controllers from prior decades use proprietary analog protocols, forcing costly gateway hardware to bridge modern IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Sensors Market |
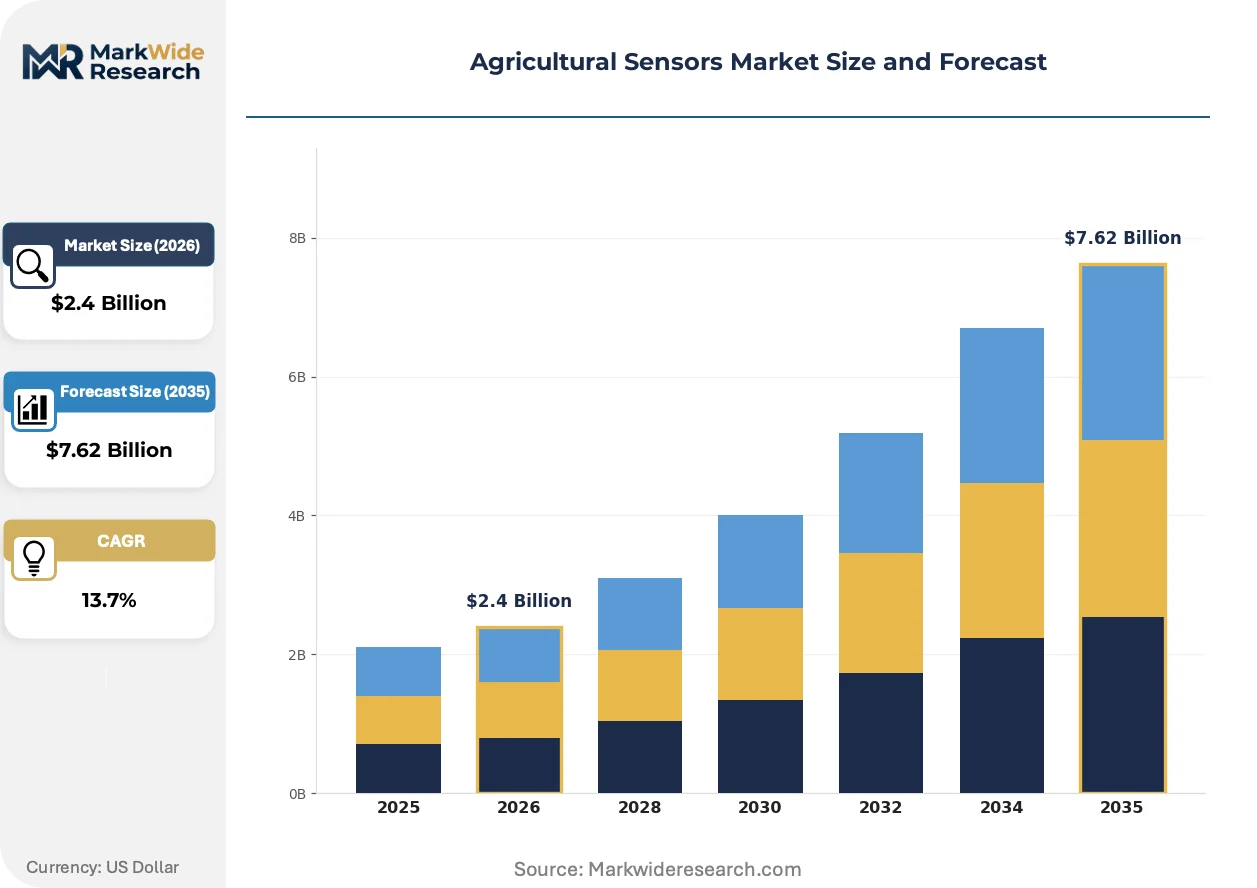
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Moisture Sensors, Weather Sensors, Image Sensors, Pressure Sensors End Use Industry: Agronomy, Horticulture, Greenhouse Management, Livestock Monitoring Technology: IoT-based, Acoustic Sensors, RFID Technology, Optical Sensors Deployment: On-field, In-field, Greenhouse, Remote Sensing |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Trimble Inc., CropX Inc., METER Group, Sentera, Pycno, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Sensors Market Trends and Innovations
Three intersecting developments are compressing sensor deployment economics: photonic integration collapsing optical subsystem costs, regulatory mandates accelerating replacement cycles, and procurement models shifting from hardware ownership to data-subscription structures.
Silicon photonics is consolidating greenhouse gas monitoring by embedding spectrometers onto single chips, eliminating fiber coupling losses and temperature drift. Dutch glasshouse operators now specify solid-state optical sensors for ethylene and CO2 tracking, displacing tunable diode laser assemblies that required frequent alignment. The technology is consolidating vendor landscapes as semiconductor fabs capture value previously distributed across optical component suppliers.
The EU Green Deal's Farm to Fork strategy tightens pesticide residue thresholds, compelling French and German arable farms to integrate real-time weather and disease-pressure sensors into spray decision systems. EPA parallel requirements for buffer zone documentation in the United States drive similar sensor adoption in Midwest corn-soy rotations. Regulatory compliance now functions as the primary sales catalyst where yield optimization alone proved insufficient.
Sensor-as-a-service contracts are displacing capital purchase models among mid-size specialty crop growers in California's Central Valley and Italy's Po Valley. Buyers lease soil moisture and canopy imaging hardware while paying per-acre data fees, transferring obsolescence risk to vendors. This restructuring concentrates procurement authority with agricultural data platforms rather than equipment dealerships, reshaping channel economics across Mediterranean and North American irrigated districts.
Agricultural Sensors Market Segmentation
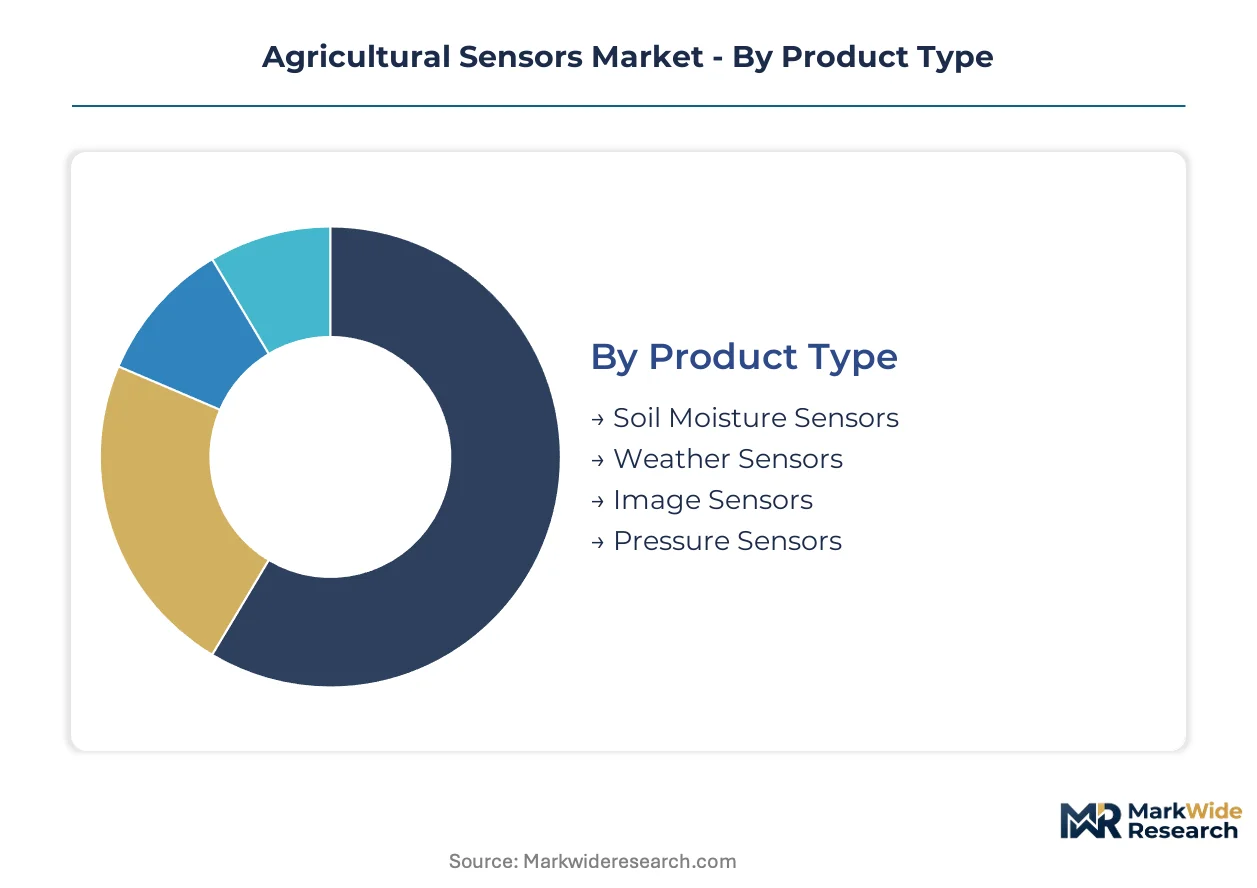
Agricultural sensors fragment across four distinct taxonomies that reflect divergent technical requirements and buyer economics. Product type captures the physical sensing modality, while end-use orientation determines specification rigor and channel access. Technology architecture and deployment topology further stratify procurement decisions across irrigated row-crop, controlled-environment, and pastoral livestock systems.
Product Type:
Volume concentrates in proven moisture detection hardware, while premium economics accrue to imaging systems with expanding drone integration.
- Soil Moisture Sensors:Capacitance, tensiometric, and time-domain reflectometry probes measure volumetric water content across root zones. Demand clusters in US Corn Belt center-pivot districts and Australian Murray-Darling Basin operations where irrigation scheduling automation delivers immediate water cost savings. USDA conservation cost-share programs accelerate replacement of legacy neutron probe installations.
- Image Sensors:Multispectral and RGB camera modules mounted on UAV platforms capture canopy reflectance indices for nitrogen stress and disease detection. California Central Valley almond and grape producers drive uptake as drone service providers bundle analytics subscriptions. Edge AI processing is collapsing per-acre survey costs below manual scouting benchmarks.
- Weather Sensors:Compact stations combining temperature, humidity, wind, and precipitation measurement support spray timing and frost protection decisions. Viticulture operations in France's Champagne region and Germany's Mosel Valley specify vineyard-specific microclimate monitoring.
- Pressure Sensors:Piezoresistive and capacitive transducers monitor irrigation line pressure, tank levels, and pneumatic seeder distribution. Brazilian soybean operations in Mato Grosso deploy network-connected pressure nodes for remote pivot monitoring.
Today's leader: Soil Moisture Sensors. Tomorrow's challenger: Image Sensors.
End Use Industry:
Application maturity spans decades-old irrigated agronomy to nascent biometric livestock tracking with divergent margin profiles.
- Agronomy:Large-scale row-crop operations in Iowa, Illinois, and Nebraska integrate soil moisture and weather sensors into variable-rate input application systems. Deere Operations Center and Climate FieldView platforms consolidate data streams from mixed-vendor sensor networks.
- Livestock Monitoring:Ear-tag accelerometers, rumen boluses, and video analytics track animal health, estrus, and feeding behavior. North American dairy operations in Wisconsin and New York deploy real-time biometric alerts to reduce veterinary intervention lag. Acoustic signal processing for respiratory disease detection commands hardware premiums exceeding standard environmental sensors.
- Greenhouse Management:Dutch Venlo glasshouse clusters drive dense sensor deployment for climate, irrigation, and crop physiological monitoring. EU F-Gas Regulation mandates continuous emissions sensing for CO2 enrichment system integrity.
- Horticulture:Specialty crop producers in Spain's Almería and Italy's Sicily deploy substrate moisture and EC sensors for soilless berry and vegetable production. Premium pricing reflects smaller farm scale and higher crop value per hectare.
Agronomy commands installed base dominance. Livestock Monitoring climbs the fastest as biometric analytics penetrate commercial dairy and feedlot operations.
Technology:
Connectivity architecture determines data latency, power autonomy, and integration complexity across field conditions.
- IoT-based:Low-power wide-area networks and cellular LPWAN modules enable edge-to-cloud telemetry from distributed field nodes. LoRaWAN deployments in Australian broadacre wheatbelts and French cereal regions demonstrate multi-kilometer range with decade-long battery autonomy.
- Optical Sensors:Silicon photonics spectrometers and photodiode arrays displace legacy fiber-optic assemblies in greenhouse gas monitoring. Dutch ethylene and CO2 sensing specifications now favor solid-state optical subsystems over tunable diode lasers.
- Acoustic Sensors:Microphone arrays and vibration transducers detect livestock respiratory patterns, feeding behavior, and equipment mechanical faults. Signal processing algorithm development concentrates value capture with specialized veterinary analytics vendors.
- RFID Technology:Passive and active radio-frequency identification supports animal identification, equipment tracking, and automated milking parlor sequencing. Mandatory cattle traceability regulations in Canada and Australia sustain baseline demand.
IoT-based systems anchor current deployment volume. Optical Sensors gain share fastest as photonic integration collapses spectral monitoring costs.
Deployment:
Physical installation topology constrains sensor specification, maintenance access, and data transmission reliability.
- On-field:Above-ground installations including weather stations, camera masts, and gateway equipment require robust enclosure ratings for sustained exposure. Midwest US corn-soy operations prioritize IP67-rated hardware with cellular backhaul redundancy.
- In-field:Buried or surface-placed soil probes and root-zone sensors demand corrosion-resistant materials and biological fouling resistance. Salinity interference limits electrical conductivity sensor accuracy in coastal Mediterranean and Southeast Asian delta districts.
- Greenhouse:Controlled-environment installations specify sensors for high-humidity, chemical vapor exposure with standardized 4-20mA or digital protocol outputs. Legacy climate controller integration forces costly gateway hardware for modern IoT sensor networks.
- Remote Sensing:Satellite and aerial platforms deliver hyperspectral and thermal imagery without ground hardware ownership. Brazilian soybean operations leverage commercial satellite subscriptions where ground sensor density remains below US benchmarks.
On-field deployment dominates capital expenditure. Remote Sensing expands most quickly as subscription imagery penetrates mid-size farm segments previously priced out of drone analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch greenhouse clusters in the Netherlands anchor sensor deployment intensity through EU-mandated emissions transparency and precision horticulture automation.
United States
Midwest corn-soy belt operations in Iowa and Illinois integrate soil moisture and weather sensors into variable-rate input systems. EPA buffer zone documentation requirements and USDA conservation cost-share programs accelerate hardware procurement. California's Central Valley specialty crop producers deploy drone-mounted multispectral imaging for almond and grape monitoring.
Netherlands
Venlo glasshouse operators specify solid-state optical sensors for ethylene and CO2 tracking under EU F-Gas Regulation mandates. The country's horticulture technology corridor drives dense environmental sensing infrastructure for climate-controlled berry and vegetable production. Wageningen University partnerships accelerate spectral monitoring algorithm development.
Brazil
Cerrado soybean operations in Mato Grosso and Goiás lack soil moisture sensor density relative to US benchmarks, presenting whitespace for calibrated probe networks. ANVISA traceability regulations and exporter sustainability certification requirements pressure farms toward documented input optimization. Remote pivot monitoring via pressure sensors expands across center-irrigation districts.
Germany
Rhineland-Palatinate and Mosel Valley viticulture operations specify vineyard-specific microclimate monitoring for frost protection and disease pressure tracking. EU Green Deal Farm to Fork pesticide residue thresholds compel real-time weather sensor integration into spray decision systems. Bavarian precision livestock farms deploy biometric ear-tags for dairy herd health optimization.
Australia
Murray-Darling Basin irrigators automate water scheduling through capacitance and time-domain reflectometry probes, delivering immediate cost savings against metered allocation prices. TGA-aligned agricultural data governance frameworks shape platform interoperability requirements. LoRaWAN deployments in Western Australian wheatbelts demonstrate multi-kilometer telemetry range with decade-long battery autonomy.
Agricultural Sensors Market Competitive Landscape
Global majors compete with regional champions across platform integration and channel control dimensions. The vendor base stratifies between full-stack agricultural equipment conglomerates, specialized sensor hardware fabricators, and semiconductor component suppliers. Three archetypes dominate: precision agriculture platform owners with embedded sensor networks, independent IoT sensor specialists with data-subscription models, and analog semiconductor suppliers with captive front-end production. Competitive moves concentrate on strategic partnerships with drone service providers and backward integration into optical component fabrication.
Within the equipment-integrated tier, Deere & Company and AGCO Corporation represent platform-centric positioning where sensor hardware serves as a data pipeline anchor for farm management software. Among component suppliers, Texas Instruments Incorporated exemplifies semiconductor-level value capture through in-house production of ultra-low-power analog front-ends. Independent specialists including CropX Inc. and METER Group occupy positions between hardware ownership and data-as-a-service procurement models, transferring obsolescence risk from growers to vendors through leased sensor networks.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Trimble Inc. |
| CropX Inc. |
| METER Group |
| Sentera |
| Pycno |
| Texas Instruments Incorporated |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation and EU Green Deal compliance mandates gate qualified supply access for greenhouse gas monitoring sensors, restricting premium-tier pricing to vendors with certified solid-state optical subsystems and documented emissions-transparency protocols.
Pricing Analysis
Input-cost pass-through from rare earth element volatility in magnetostrictive soil probes compresses margin structures for mid-tier manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates silicon photonics-enabled spectral monitors from legacy fiber-optic assemblies and basic capacitance probes. Pricing pressure stems from Taiwanese foundry concentration for ultra-low-power analog front-ends. Brazilian soybean operations exhibit highest price sensitivity; Dutch greenhouse clusters show lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Deere and AGCO platform integrations, while independent IoT specialists distribute through agricultural data platform partnerships. Component supply concentrates in Taiwan for analog front-end semiconductors, China for rare earth processing, and the Netherlands for silicon photonics fabrication. Raw material dependencies include neodymium for magnetostrictive probes, silicon-on-insulator wafers for photonic chips, and lithium for battery-powered field nodes. Single-source vulnerability in Taiwanese foundry capacity exposes lead times to geopolitical friction. Distribution runs through equipment dealership networks in North American row-crop regions and direct platform subscriptions in European greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural sensors market functions as a stable compounder anchored by regulatory mandates that institutionalize replacement cycles and compliance-driven procurement.
For Market Incumbents: Acquire optical component fabrication capabilities to capture value previously distributed across discrete suppliers. Silicon photonics integration threatens legacy fiber-optic vendors with cost displacement. Prioritize backward integration into semiconductor fab partnerships or captive spectral chip production to defend margin position against photonic consolidation.
For New Entrants and Emerging Players: Drone service provider partnerships offer the lowest-friction channel for hyperspectral imaging penetration. Brazilian cerrado soybean operations present whitespace for calibrated soil moisture networks against sparse US Corn Belt benchmarks. Target mid-size specialty crop growers in California's Central Valley with sensor-as-a-service contracts that transfer obsolescence risk from buyers.
For Investors and Strategic Acquirers: Roll-up economics work for independent IoT sensor specialists because platform procurement authority is concentrating procurement decisions with agricultural data platforms rather than equipment dealerships. Five-to-ten-year viability hinges on regulatory tailwinds from EU CSRD sustainability disclosure rules. Monitor EU CSRD implementation timelines as the inflection signal for compliance-driven hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Semiconductor fabs capture optical value previously distributed across component suppliers. |
| Sensor-as-a-Service Contracts | Data-subscription models transfer obsolescence risk from growers to vendors in California and Italy. |
| Greenhouse Emissions Monitoring | EU F-Gas Regulation mandates continuous CO2 and ethylene sensing in Dutch glasshouse clusters. |
| Livestock Biometric Expansion | North American dairy operations deploy real-time ear-tag accelerometers for health monitoring. |
| Edge AI Fusion | Hyperspectral imaging with on-chip processing opens mid-size farm segments to drone analytics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research engaged precision agriculture platform executives, greenhouse climate control engineers, semiconductor component procurement managers, and agricultural data platform operators. Secondary validation drew from EPA pesticide application documentation, EU F-Gas Regulation implementation guidance, USDA conservation program cost-share disclosures, and customs trade data for sensor component flows. Bottom-up sensor deployment estimates triangulated against top-down agricultural equipment production benchmarks.
Comparable-period anchoring linked projection assumptions to historical replacement cycles in irrigated row-crop systems and greenhouse infrastructure upgrade patterns. Segmentation modeling spanned product type, end-use industry, technology architecture, and deployment topology dimensions. CAGRs were derived from installed base expansion rates and unit economics trajectories across soil moisture, image, weather, pressure, and biometric sensor categories. Forecast inputs incorporated silicon photonics cost curves, EU regulatory compliance timelines, and Brazilian soybean operation sensor density gaps.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics integration would alter the outlook for legacy optical component vendors. Forecasts reflect assumptions about regulatory enforcement consistency, foundry capacity allocation, and agronomist technician availability for field calibration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Agriculture Analytics Market