
 Global Thermally Modified Wood Market | 2026-2036
Global Thermally Modified Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermally Modified Wood Market Outlook
Premium-grade thermally modified timber is reorganizing competitive positioning across exterior applications. Kebony leverages its proprietary wood modification process to sustain leadership in high-durability cladding segments. Stora Enso anchors Nordic supply chains through integrated forest-to-product operations spanning Finland and Sweden. Lunawood differentiates via specialized thermowood production focused on resinous softwood species with enhanced dimensional stability.
Thermally modified wood undergoes controlled high-temperature treatment between 160°C and 260°C in oxygen-reduced environments, altering cellular chemistry to improve decay resistance and reduce hygroscopicity without chemical preservatives. Its primary commercial purpose centers on delivering durable exterior building materials that meet stringent environmental certification requirements. Decking and siding segments capture dominant volume flows as residential and commercial builders prioritize low-maintenance facade solutions. Direct sales channels occupy concentrated margin pools through project-specified bulk contracts, while distributor networks extend reach into fragmented landscaping and renovation segments.
REACH regulations in Europe restrict traditional wood preservative chemicals, redirecting specification toward thermally modified alternatives that bypass hazardous substance classifications. The EU Green Deal and F-Gas Regulation create overlapping compliance frameworks that favor low-embodied-carbon building materials in public procurement. The US EPA and USDA bio-preferred programs similarly elevate certified sustainable wood products in federal construction standards. Stakeholders must monitor evolving lifecycle assessment methodologies that increasingly weight end-of-phase recyclability alongside initial performance metrics.
Market Dynamics
REACH regulations and the EU Green Deal are redirecting specification standards away from chemically treated lumber, compressing demand cycles for thermally modified alternatives while Nordic producers expand capacity to capture displaced volume.
Growth Catalysts
- REACH chemical restrictions:The European regulation's ban on traditional wood preservatives eliminates competing products from specification lists in public procurement and residential construction across Germany, France, and the Netherlands.
- USDA BioPreferred program:Federal construction standards in the United States elevate certified sustainable wood products, creating specification pull-through for thermally modified timber in government buildings and military housing.
- Resinous softwood processing:Advanced thermowood techniques applied to Scandinavian pine and spruce species deliver enhanced dimensional stability that meets facade engineering requirements in maritime climates.
Market Restraints
- Energy input cost volatility:Natural gas and electricity prices for thermal modification ovens fluctuate with European energy market instability, compressing margins at treatment facilities in Finland and Sweden.
- Supply concentration risk:Premium-grade feedstock depends on Nordic forest-to-product operations, creating vulnerability to harvest restrictions or logistics disruptions across Baltic Sea shipping routes.
- Substitution threat from modified softwood:Acetylated wood products bypass thermal energy intensity while delivering comparable decay resistance, attracting specification in high-humidity applications.
Strategic Opportunities
- Underpenetrated Japanese market:METI building standards and JIS certification frameworks for exterior wood materials remain open to thermally modified timber entry, particularly in seismic-resistant low-rise construction.
- Emerging interior flooring applications:Residential developers in Denmark and Norway specify thermowood for radiant-heated floor systems where dimensional stability reduces gapping and cupping failures.
- EU F-Gas Regulation overlap:The framework's emphasis on low-embodied-carbon materials in HVAC and building envelope procurement creates tailwinds for thermally modified wood in integrated facade systems.
Industry Challenges
- Thermal process engineering talent scarcity:Facilities require operators who understand oxygen-reduced environment controls across 160°C to 260°C treatment windows, with limited vocational training programs addressing this specialization.
- PEFC and FSC chain-of-custody certification timelines:New market entrants face 12-to-18-month audit cycles before achieving the certifications mandatory for EU public procurement eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermally Modified Wood Market |
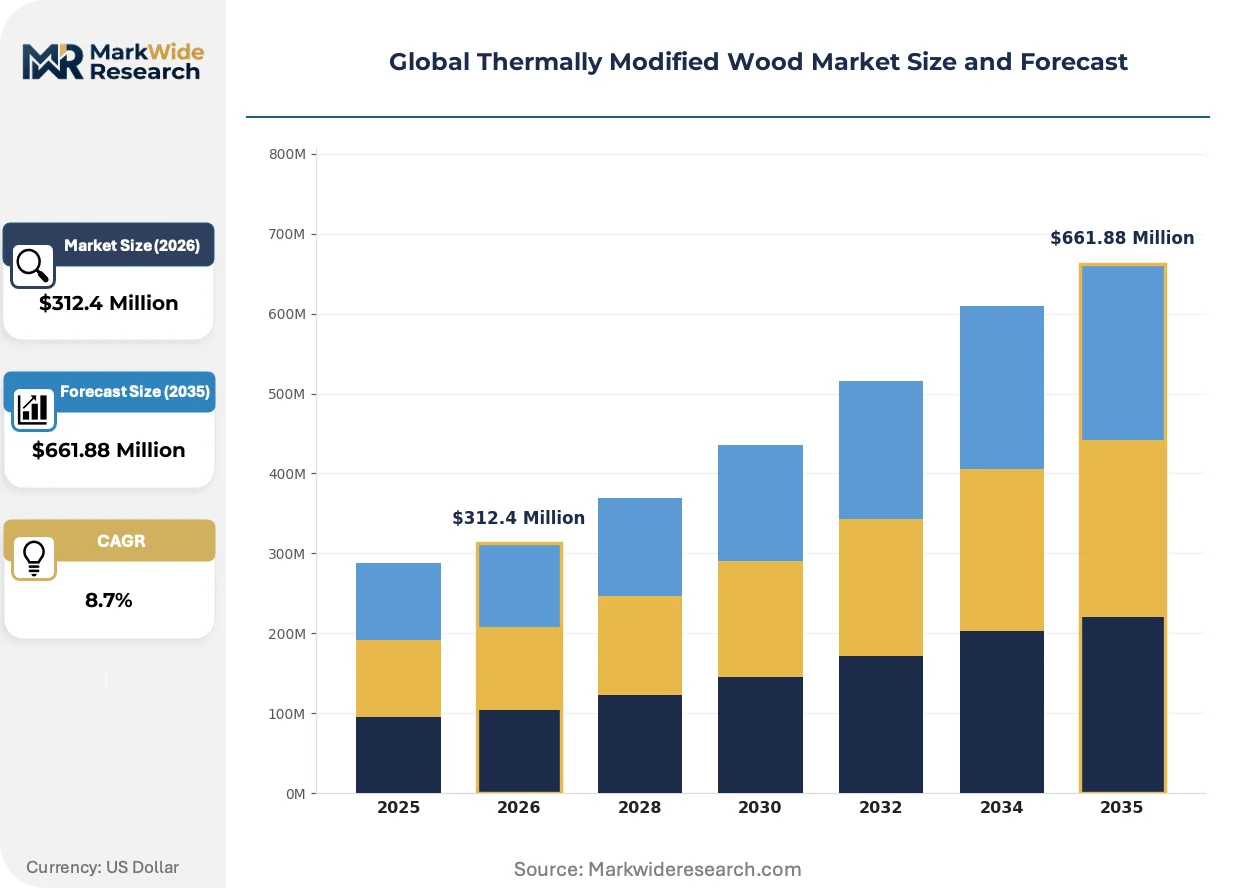
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decking, Siding, Flooring, Fencing End Use: Residential, Commercial, Industrial, Landscaping Grade: Premium, Standard, Economy, Specialty Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Thermory, Stora Enso, Kebony, Lunawood, Arbor Wood, Novawood, SWM-Wood, Thermoarena, Accsys Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermally Modified Wood Market Strategic Shifts
Process intensification and digital quality control systems are compressing treatment cycle times while expanding species compatibility, enabling producers to serve specification niches previously reserved for tropical hardwoods or engineered composites.
Plasma-assisted thermal modification is decomposing lignin structures at lower temperatures than conventional ovens, reducing energy consumption per cubic meter. Swedish treatment facilities pilot this technology for spruce cladding destined for Dutch residential projects. The process is decomposing cost barriers that previously excluded mid-market builders from premium-grade exterior materials.
The EU Green Deal's embodied carbon reporting requirements through CSRD are forcing lifecycle assessment disclosure across construction material supply chains. German facade engineers now specify thermally modified timber to meet operational carbon targets in commercial buildings. Nordic exporters accelerate third-party verified EPD documentation to capture specification momentum in Hamburg and Munich markets.
Specification decisions increasingly bypass distributor networks as direct project contracts concentrate volume with integrated forest-product companies. Large-scale residential developers in Finland and commercial facade contractors in Belgium negotiate bulk supply agreements that disintermediate traditional building material wholesalers. This channel compression is most visible in cladding segments where volume certainty justifies captive production capacity commitments.
Global Thermally Modified Wood Market Segmentation
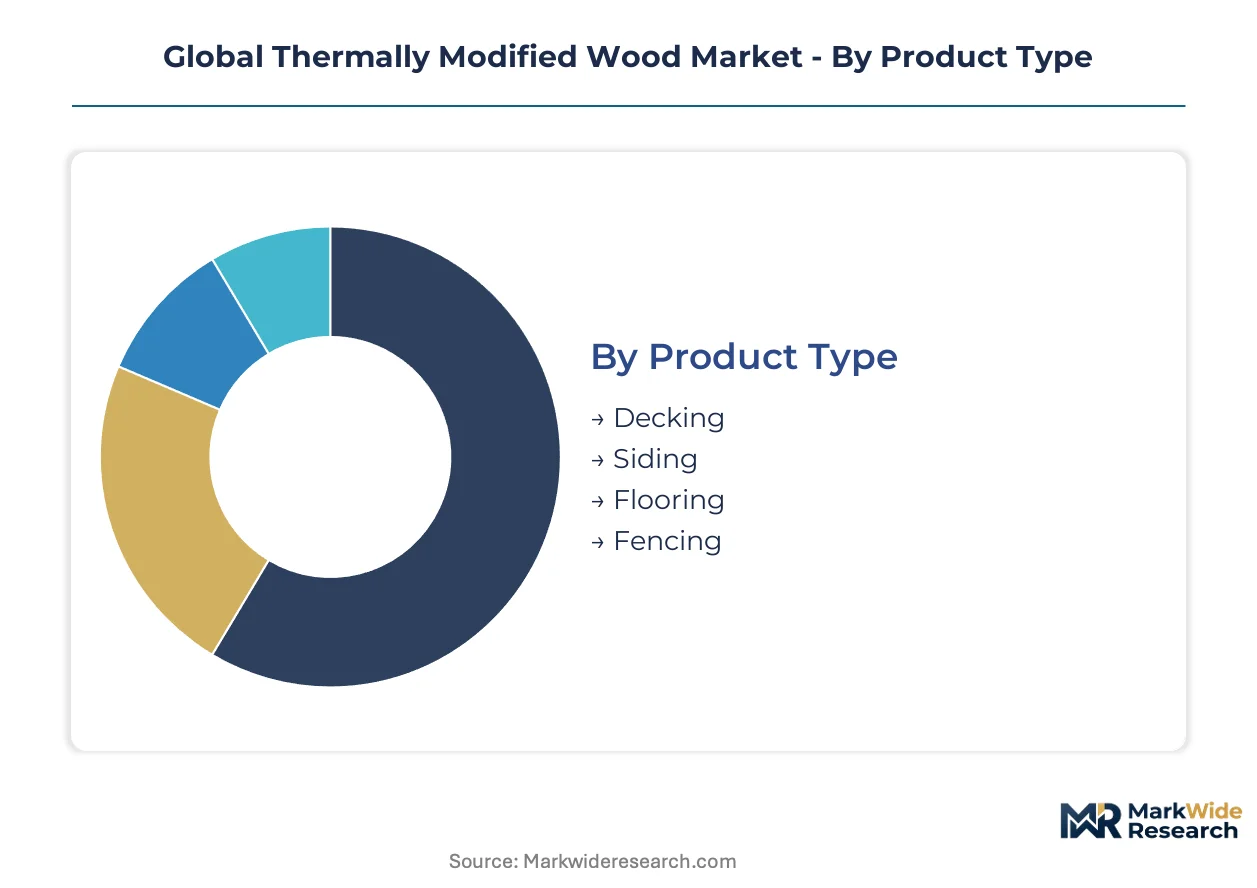
Thermally modified wood segments reflect divergent supply chain configurations, with some categories serving concentrated export markets while others anchor domestic renovation demand. Specification standards vary sharply across product types and end uses, creating distinct margin pools and certification requirements.
Product Type:
Export-led segments dominate Nordic producer portfolios, while domestic markets absorb volume in weather-exposed applications.
- Decking:High-traffic exterior platforms require dimensional stability across freeze-thaw cycles. German and Dutch residential developers specify thermally modified pine for marina walkways and pool surrounds where slip resistance and decay immunity outweigh first-cost premiums.
- Siding:Vertical and horizontal cladding panels undergo surface brushing to enhance grain exposure. Finnish producers ship containerized volumes to Belgian facade contractors pursuing CSRD-compliant embodied carbon targets in commercial envelopes.
- Flooring:Interior radiant-heat applications in Danish and Norwegian homes leverage reduced hygroscopicity to prevent gapping.
- Fencing:Landscaping contractors in Sweden favor lower-grade thermowood for perimeter barriers where aesthetic uniformity matters less than ground-contact durability.
Siding holds the largest share; momentum sits with flooring as residential heating system compatibility expands addressable volume.
End Use:
Cost tier stratification separates specification-grade commercial projects from price-sensitive landscaping procurement.
- Residential:Single-family exterior renovations in the Netherlands and Germany drive cladding specification through architect-led design processes. Homeowners prioritize 25-year service life guarantees over initial material cost.
- Commercial:Office and hospitality facades in Hamburg and Munich require third-party verified EPD documentation under EU Green Deal procurement rules. General contractors bundle thermally modified timber with HVAC envelope upgrades.
- Industrial:Warehouse and logistics facilities specify treated softwood for loading dock enclosures and equipment shelters.
- Landscaping:Municipal parks departments in Finland and Sweden source fencing and boardwalk materials through competitive tender with compressed lead times.
Commercial commands premium pricing; residential is expanding most quickly as renovation tax incentives activate across German federal states.
Grade:
Volume concentration sits with standard grades, while specialty tiers capture project-specific engineering requirements.
- Premium:Select-grade boards with minimal knot content and uniform coloration serve visible commercial facades. Swedish producers reserve kiln capacity for yacht harbor pavilions and embassy architecture where specification failure carries reputation risk.
- Standard:Medium-knot pine and spruce grades balance treatability with structural performance. Finnish sawmills run continuous batches for Dutch housing association maintenance programs.
- Economy:Higher-defect boards with color variation acceptable for concealed structural applications and temporary construction.
- Specialty:Custom density profiles and modified hardwood species address seismic-resistant low-rise construction in Japanese markets awaiting METI certification alignment.
Standard grade anchors volume throughput; specialty is climbing the fastest as export diversification accelerates.
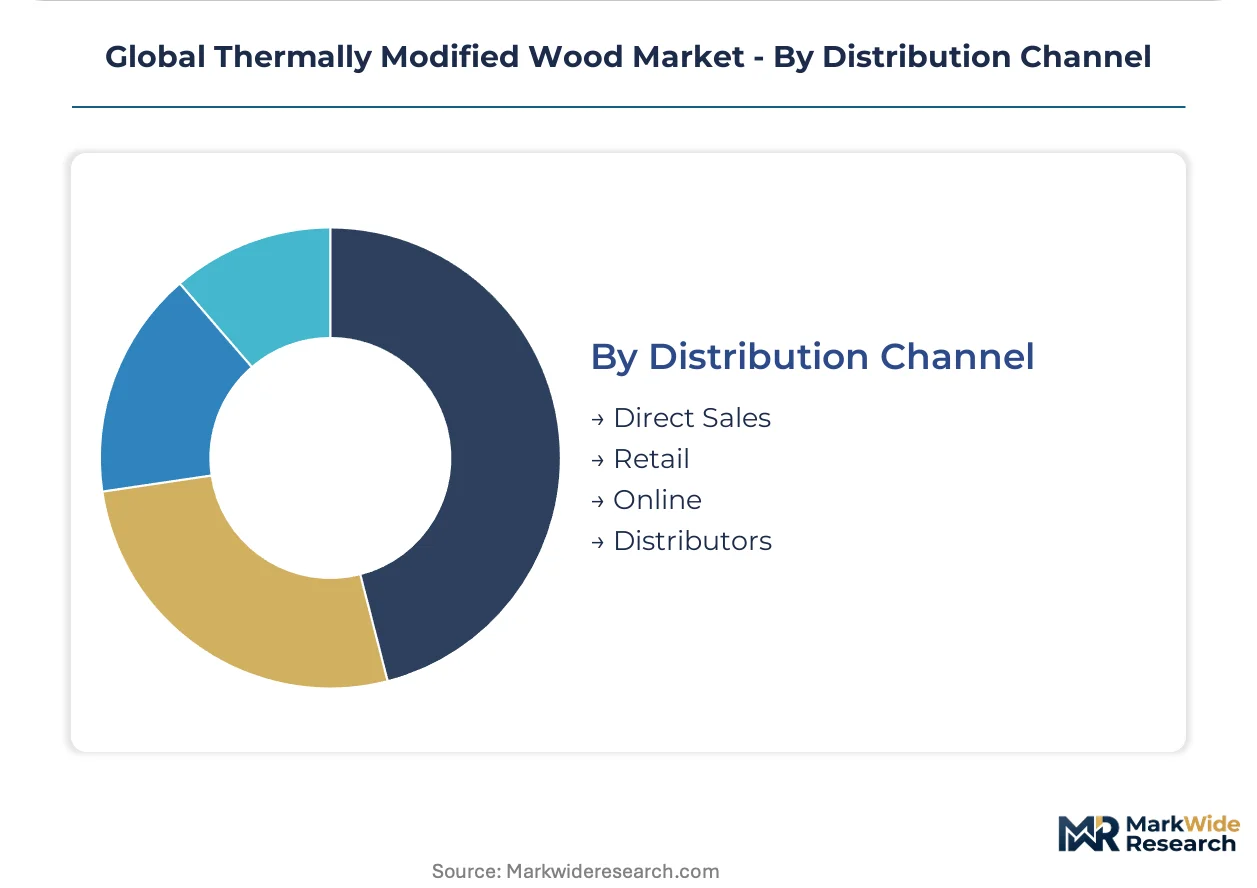
Distribution Channel:
Customer type fragmentation separates bulk project contractors from fragmented renovation consumers.
- Direct Sales:Integrated forest-product companies negotiate multi-year supply agreements with Belgian and Finnish developers. Volume certainty justifies captive treatment capacity and eliminates distributor margin stacking.
- Distributors:Regional building material wholesalers stock standard-grade siding and decking for Dutch and German contractor pickup. Inventory risk concentrates with distributors facing seasonal demand swings.
- Retail:Big-box home improvement chains in Sweden and Norway display thermowood samples for consumer-directed renovation projects.
- Online:Digital platforms aggregate small-lot orders from landscaping architects and independent builders, though shipping costs constrain viable order minimums.
Direct sales captures the dominant margin pool; online is gaining share fastest as specification tools migrate to digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Nordic treatment facilities dominate international trade, while import-dependent markets in Western Europe and North America absorb premium volumes for facade and decking applications.
Finland
Stora Enso's integrated forest-to-product operations anchor national capacity, supplying thermowood cladding to German commercial developers pursuing CSRD-compliant embodied carbon targets. The EU Green Deal redirects public procurement specifications toward low-embodied-carbon materials. Helsinki-based producers ship containerized siding volumes to Belgian facade contractors in Antwerp and Ghent.
Sweden
Resinous softwood processing expertise concentrates in sawmill clusters serving Dutch housing association maintenance programs and marina walkway projects. REACH chemical restrictions eliminate competing preservative-treated products from specification lists. Kebony's proprietary modification operations in central Sweden supply yacht harbor pavilions and embassy architecture across Northern Europe.
Germany
Hamburg and Munich commercial envelope contractors bundle thermally modified timber with HVAC upgrades to meet operational carbon targets under federal procurement rules. The EU F-Gas Regulation overlaps with Green Deal frameworks to favor low-carbon building materials. Bavarian residential developers activate renovation tax incentives specifying 25-year service life guarantees for exterior cladding.
Netherlands
German and Dutch residential developers specify thermally modified pine for marina walkways and pool surrounds where slip resistance outweighs first-cost premiums. Architect-led design processes in Amsterdam and Rotterdam drive single-family exterior renovation demand. Distributor networks in Randstad cities stock standard-grade siding for contractor pickup.
United States
Federal construction standards through the USDA BioPreferred program elevate certified sustainable wood products in government buildings and military housing. EPA procurement guidelines reinforce specification pull-through for thermally modified timber. Pacific Northwest and Northeast corridor projects concentrate early adoption among residential builders seeking alternatives to chemically treated lumber.
Global Thermally Modified Wood Market Competitive Environment
Listed leaders compete with private specialists across integrated production depth, creating a tiered structure where scale advantages clash with proprietary technology differentiation. The vendor base spans Nordic forest-product conglomerates, specialized modification technology firms, and regional treatment cooperatives. Two strategic archetypes dominate: integrated forest-to-product operators controlling feedstock supply, and technology licensors monetizing patented modification processes. Capacity expansion and direct sales channel development represent the dominant competitive moves as producers bypass distributor margins.
Within the integrated operator tier, Stora Enso exemplifies scale-driven positioning through captive Nordic forest assets, while Kebony occupies a technology-specialist position with proprietary modification intellectual property. Lunawood represents the focused thermowood producer archetype concentrating on resinous softwood species processing. These three anchors demonstrate how geographic concentration in Finland and Sweden produces divergent strategic postures despite shared regional feedstock access.
| Leading Market Players |
|---|
| Thermory |
| Stora Enso |
| Kebony |
| Lunawood |
| Arbor Wood |
| Novawood |
| SWM-Wood |
| Thermoarena |
| Accsys Technologies |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Nordic thermal modification facilities shapes both supply concentration and price floors for exterior-grade timber. Treatment ovens running at scale in Finland and Sweden compress per-unit energy costs while REACH compliance investments lock in certification premiums across German and Dutch specification markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for commercial facade projects. Three-tier pricing structure across premium, standard, and economy levels separates select-grade cladding with PEFC chain-of-custody certification from medium-knot maintenance grades and higher-defect structural boards. Cost compression in standard tiers intensifies because energy input volatility squeezes treatment facility margins. Landscaping contractors exhibit highest price sensitivity, while Belgian commercial envelope developers prioritize embodied carbon documentation over first-cost optimization.
Supply Chain Analysis
Finland and Sweden anchor integrated forest-to-product operations for resinous softwood feedstock. Thermal modification draws from Scandinavian pine and spruce harvests, natural gas and electricity inputs for oxygen-reduced oven environments, and PEFC/FSC certification audit cycles. Single-source vulnerability concentrates in Baltic Sea shipping routes connecting sawmill clusters to Rotterdam and Hamburg ports. Distribution runs through direct sales channels for bulk project contracts and regional building material wholesalers for fragmented renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification digitization and CSRD-aligned lifecycle assessment disclosure are creating platform-economics inflection, where EPD-verified product data interoperability determines procurement eligibility across EU public construction frameworks.
For Market Incumbents: Compound captive treatment capacity advantages by locking multi-year supply agreements with Belgian and Finnish developers before acetylated wood substitution accelerates in high-humidity applications. Deepen upstream control over PEFC-certified forest assets to compress certification timelines for new market entrants. Prioritize plasma-assisted thermal modification R&D to decompose energy cost barriers excluding mid-market builders. For New Entrants and Emerging Players: PEFC chain-of-custody fast-track programs open specification access in underpenetrated Japanese exterior wood markets awaiting METI certification alignment. Target seismic-resistant low-rise construction segments where custom density profiles command specialty grade premiums. Pursue digital platform aggregation of small-lot landscaping orders to bypass distributor inventory risk concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated operators with proprietary modification intellectual property and captive Nordic forest assets over pure-play treatment cooperatives. Five-to-ten year viability hinges on EU Green Deal procurement rule permanence and embodied carbon accounting standardization. Watch for plasma-assisted process patent filings as inflection indicator for energy cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Assisted Process Scale-Up | Swedish pilot facilities demonstrate 20-30% energy reduction for spruce cladding exports to Dutch residential projects. |
| Direct Sales Channel Expansion | Finnish producers bypass distributor margins by negotiating bulk supply agreements with Hamburg commercial facade contractors. |
| PEFC/FSC Certification Investment | Twelve-to-eighteen month audit cycles remain mandatory for EU public procurement eligibility under REACH-aligned frameworks. |
| Japanese METI Certification Pursuit | JIS standard alignment unlocks specification in seismic-resistant low-rise construction segments with limited domestic competition. |
| EPD Documentation Acceleration | Third-party verified lifecycle assessment disclosure captures CSRD-compliant procurement momentum in Munich and Hamburg markets. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with thermal modification facility operators, commercial facade contractors, and PEFC certification auditors; and secondary validation through customs/trade data, EU EPD registry filings, and SEC disclosures from listed forest-product conglomerates. Bottom-up volume triangulation across treatment facility capacity and top-down demand segmentation across residential, commercial, and landscaping end uses anchored forecast integrity.
Across the analysis window, the quantitative framework modeled product type, end use, grade tier, and distribution channel dimensions. CAGRs derived from regression analysis of historical capacity expansion patterns and specification shift elasticities to REACH chemical restrictions. Forecast inputs incorporated energy cost volatility scenarios for natural gas-dependent oven operations and plasma-assisted technology adoption curves.
Decision-makers should treat outputs as directional under sustained EU Green Deal procurement enforcement and Nordic forest harvest stability; material deviation in either would warrant model refresh. Specific risks include acetylated wood substitution acceleration, Baltic Sea logistics disruptions, and CSRD reporting requirement delays. Recalibration cycles align with material shifts in EU F-Gas Regulation implementation scope and METI certification framework finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Briquetting Press Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
High Modulus Polyethylene Rope Market