
 Fiberglass Tanks Market | 2026-2036
Fiberglass Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Tanks Market Analysis
Saudi Arabia is reconfiguring its fiberglass manufacturing footprint to serve petrochemical and desalination demand across the Middle East. Xerxes leverages its underground storage specialization to dominate North American petroleum containment. NOV anchors its position through upstream oilfield fiberglass pressure vessel supply. Belding Tank Technologies competes on custom corrosion-resistant designs for chemical processors.
Fiberglass tanks are reinforced thermoset polymer vessels fabricated through filament winding or contact molding, typically using E-glass fibers embedded in vinyl ester or isophthalic resin matrices to achieve specific gravity ratings from 1.5 to 1.9 and corrosion resistance thresholds exceeding carbon steel. Their primary purpose is storing aggressive chemicals, petroleum products, and treated water without metallic degradation. Storage tanks lead product type demand due to broad industrial applicability, while wastewater tanks represent the fastest-expanding segment as municipal infrastructure ages. The oil and gas end user category sustains premium pricing through API specification compliance, though water treatment applications are displacing legacy concrete and steel installations.
EPA underground storage tank regulations and NSF/ANSI 61 drinking water system standards govern material safety and installation protocols in the United States. The EU F-Gas Regulation and REACH chemical compliance frameworks shape import requirements and resin formulation choices for European market access. Stakeholders must monitor evolving state-level environmental mandates and resin raw material availability to secure specification approvals before infrastructure procurement cycles finalize.
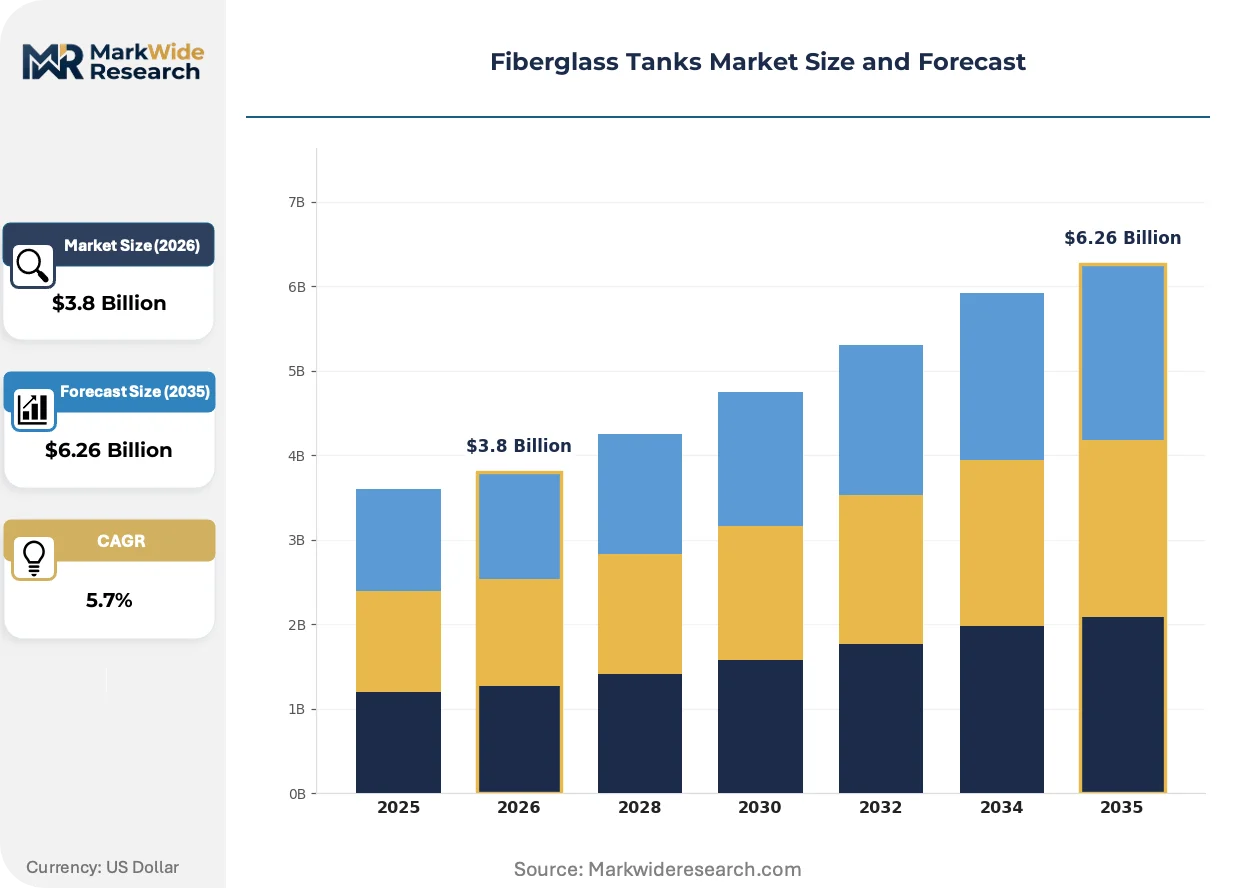
Market Dynamics
Municipal infrastructure replacement cycles and EPA corrosion mandates are forcing utilities toward fiberglass alternatives, compressing procurement timelines and elevating specification stringency for storage vessel suppliers.
Growth Catalysts
- EPA Underground Storage Tank Regulations:Federal mandates for corrosion-resistant petroleum containment are accelerating fiberglass adoption at retail fueling stations across the United States.
- Desalination Expansion:Saudi Arabia's petrochemical and water treatment buildout is generating regional demand for large-diameter fiberglass storage vessels.
- NSF/ANSI 61 Certification:Drinking water safety standards are disqualifying legacy concrete tanks from municipal procurement, favoring vinyl ester fiberglass systems.
Market Restraints
- Resin Input Volatility:Vinyl ester and isophthalic resin prices fluctuate with petrochemical feedstock costs, compressing manufacturer margins unpredictably.
- Filament Winding Equipment Concentration:Advanced winding machinery suppliers cluster in Germany and Italy, creating supply bottlenecks for capacity expansion.
- Concrete Substitution in Bulk Storage:Large-volume water utilities retain concrete for above-ground applications exceeding 50,000 gallons.
Strategic Opportunities
- Hydrogen Storage Infrastructure:Emerging hydrogen fueling networks require specialized pressure-rated fiberglass vessels for high-purity containment.
- EU F-Gas Regulation:Refrigerant containment mandates are opening specification windows for fiberglass alternatives to steel in HVAC applications.
- Modular Wastewater Systems:Decentralized treatment adoption in rural Texas and California is creating demand for skid-mounted fiberglass tank packages.
Industry Challenges
- Filament Winding Technician Shortage:Specialized composite fabrication skills are scarce in North American manufacturing labor pools.
- API Specification Compliance Timelines:Oilfield pressure vessel certification cycles extend 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Tanks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Tanks, Wastewater Tanks, Chemical Tanks, Pressure Tanks Application: Agricultural, Industrial, Residential, Commercial Design Type: Vertical, Horizontal, Conical, Custom End User: Manufacturing, Food Processing, Oil & Gas, Water Treatment |
| Companies Covered | Xerxes, Belco Manufacturing Company, KBK Industries, NOV, Industrial Plastic Systems, GSC Tank, Augusta Fiberglass, Marjan Factory Company, Belding Tank Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Tanks Market Emerging Trajectories
Digital integration of manufacturing quality systems and predictive maintenance platforms is compressing specification cycles and reshaping how utilities evaluate tank lifecycle costs.
Embedded sensor arrays and IoT connectivity are digitizing fiberglass tank monitoring, enabling real-time structural health assessment. Water treatment utilities in California are piloting these systems for seismic resilience verification. This capability is digitizing procurement evaluation criteria, shifting buyer focus from upfront capital to total lifecycle analytics.
REACH chemical compliance frameworks in Europe are restricting certain resin formulations, forcing reformulation investments for market access. Manufacturers serving EU desalination projects must validate alternative catalyst systems. Chemical processing end-uses face the steepest compliance adaptation requirements.
Integrated service contracts bundling installation, inspection, and recoating are displacing transactional tank sales in municipal segments. Engineering-procurement-construction firms in Texas are consolidating vendor relationships under multi-year maintenance agreements. This restructuring concentrates specification influence with turnkey providers rather than component suppliers.
Fiberglass Tanks Market Segmentation
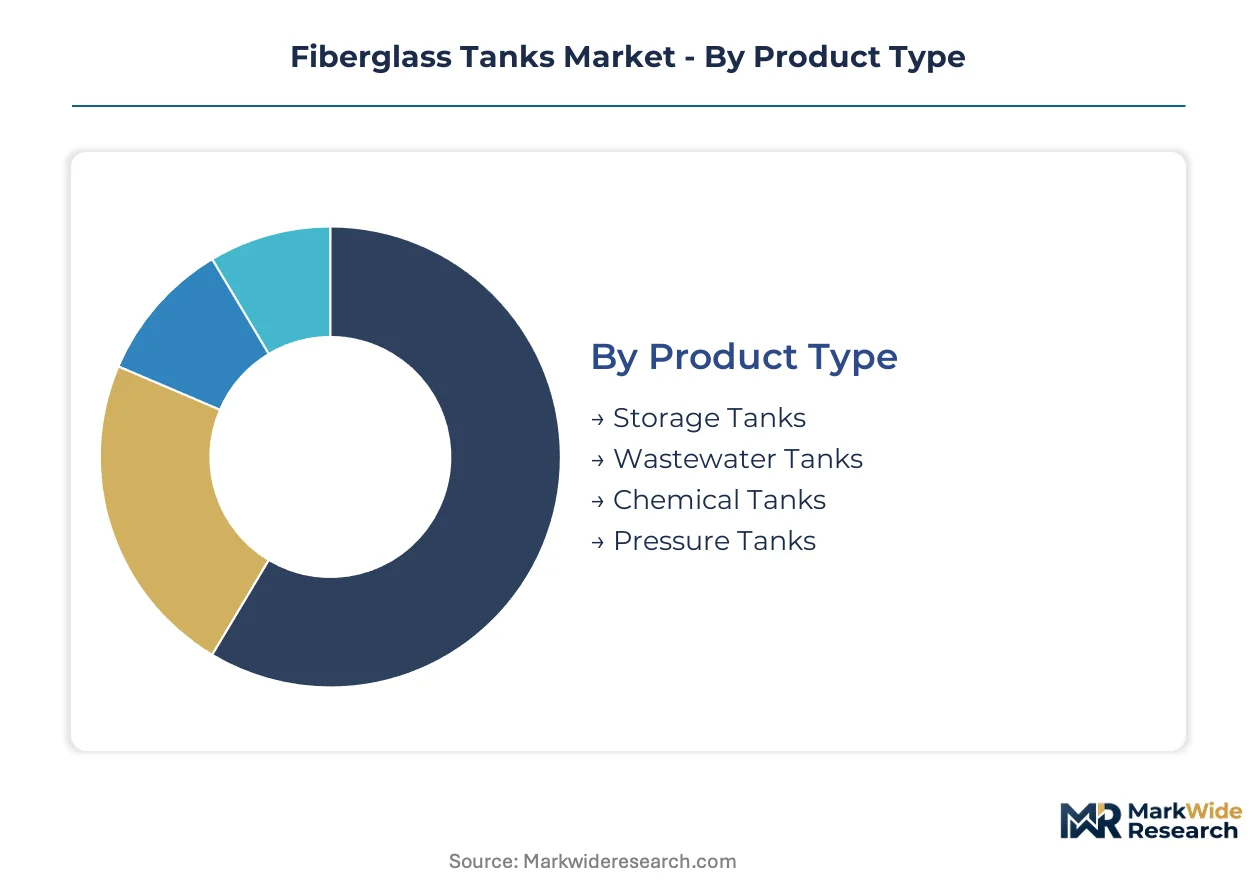
Fiberglass tank procurement decisions cascade through four intersecting dimensions that determine resin formulation, fabrication method, and compliance burden. Specification engineers weight product type against chemical aggression, application context against installation constraints, and end-user requirements against certification timelines. Understanding how these categories interlock reveals where margin concentrates and where commoditization threatens.
Product Type:
Mature utility storage applications coexist with emerging pressure-rated systems demanding advanced filament winding protocols.
- Storage Tanks:These vessels employ E-glass reinforcement in vinyl ester matrices for above-ground and underground containment of water, petroleum, and benign chemicals. Municipal utilities in Texas and California specify these for NSF/ANSI 61-compliant drinking water infrastructure as concrete replacement cycles accelerate. Storage tanks retain volume leadership; wastewater tanks hold the steepest expansion curve.
- Wastewater Tanks:Designed with enhanced corrosion barriers and leak detection integration, these systems handle aggressive effluent and septage. Decentralized treatment adoption in rural California is generating demand for skid-mounted fiberglass packages that displace legacy concrete digesters.
- Chemical Tanks:Isophthalic and vinyl ester resin systems achieve specific gravity ratings up to 1.9 for acid and caustic containment. Chemical processors specify these for sulfuric acid and sodium hydroxide storage where carbon steel fails.
- Pressure Tanks:Filament-wound vessels rated for internal pressure service in oilfield and hydrogen applications. API specification compliance extends certification timelines to 18-24 months, compressing supplier margins.
Storage tanks retain volume leadership; wastewater tanks hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive industrial installations from price-sensitive residential procurement.
- Industrial:Large-diameter vessels exceeding 50,000 gallons serve manufacturing and petrochemical facilities with integrated monitoring systems. Saudi Arabia's desalination buildout is concentrating demand for corrosion-resistant process storage.
- Commercial:Retail fueling stations and HVAC facilities specify fiberglass for EPA underground storage tank compliance and EU F-Gas refrigerant containment mandates. Turnkey installation contracts dominate procurement.
- Agricultural:Fertilizer and irrigation water storage employs lower-specification contact-molded tanks. Price competition from polyethylene limits fiberglass penetration in this segment.
- Residential:Septic tanks and rainwater harvesting systems represent the most price-elastic demand category. Concrete and plastic alternatives capture majority share below 1,000-gallon capacities.
Industrial applications command premium pricing; commercial compliance mandates are expanding specification windows fastest.
Design Type:
Volume scale and site constraints dictate orientation selection across municipal and industrial deployments.
- Vertical:Cylindrical upright vessels optimize footprint efficiency for above-ground water treatment and chemical storage. California utilities specify these for seismic resilience verification with embedded sensor arrays.
- Horizontal:Low-profile configurations suit underground petroleum containment and space-constrained industrial sites. Xerxes specializes in this design category for North American retail fueling infrastructure.
- Conical:Sloped-bottom tanks facilitate solids discharge in wastewater and slurry applications. Food processors specify these for sanitary cleanout requirements.
- Custom:Engineered-to-order vessels address non-standard dimensions, nozzle configurations, and pressure ratings. Chemical processors and oilfield operators drive this specification-intensive segment.
Vertical designs dominate municipal procurement; custom engineering captures the highest margin premiums.
End User:
Customer type differentiation separates specification-influential engineering-procurement-construction firms from component-driven procurement.
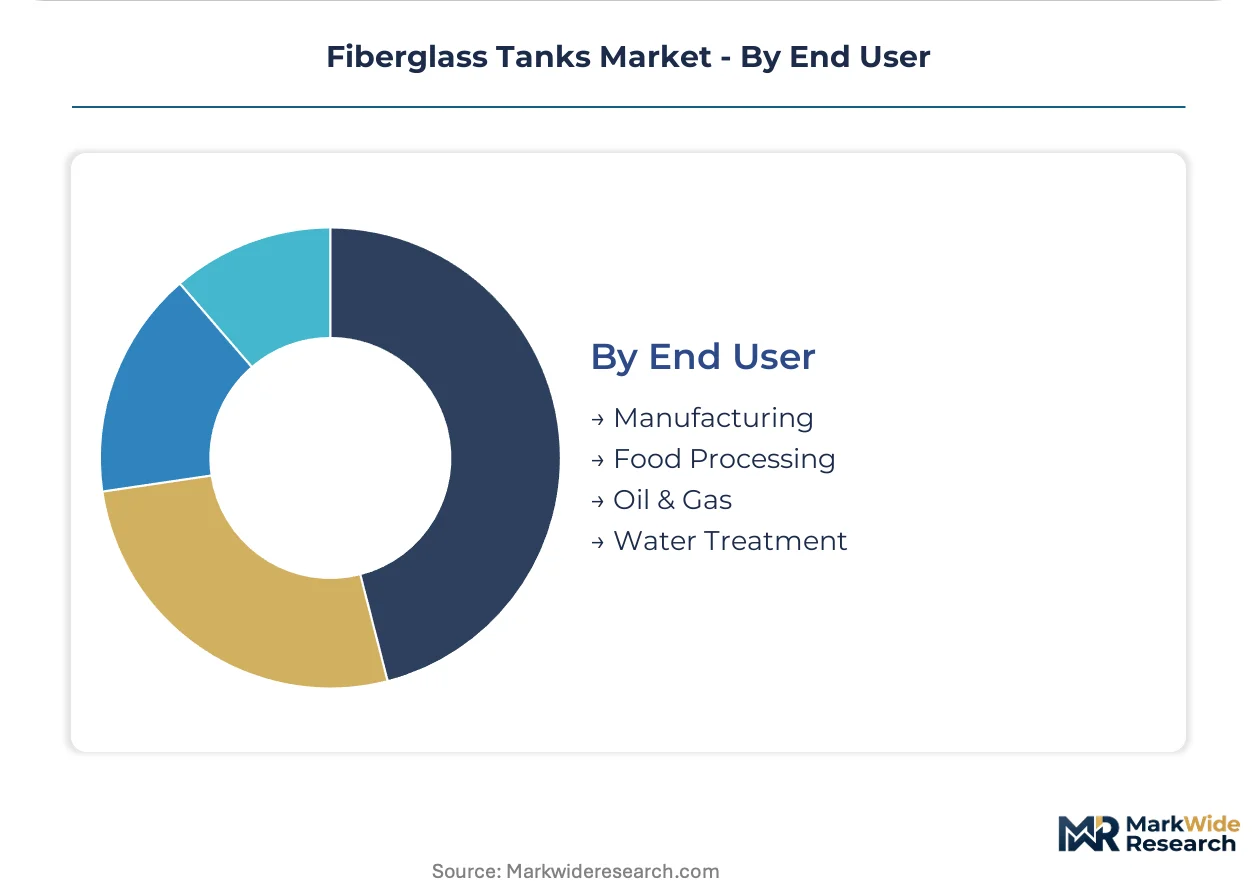
- Water Treatment:Municipal utilities and desalination plants drive NSF/ANSI 61 and EPA compliance requirements. Aging infrastructure replacement in Texas and California is displacing concrete and steel with vinyl ester fiberglass systems.
- Oil & Gas:Upstream operators and retail fueling networks require API-compliant pressure vessels and underground storage. Certification cycles and corrosion mandates sustain premium pricing in this segment.
- Manufacturing:Chemical processors and general industrial users specify corrosion-resistant containment for process chemicals and waste streams. REACH compliance in Europe is forcing resin reformulation for market access.
- Food Processing:Sanitary-grade tanks with FDA-compliant resin systems handle potable water, ingredients, and waste. Cleanout accessibility and surface finish specifications distinguish this application.
Water treatment commands the broadest volume base; oil and gas sustains the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA underground storage tank regulations anchor North American specification standards, while Saudi desalination buildout and European REACH compliance reshape regional procurement priorities across fiberglass tank markets.
United States
Texas and California utilities drive municipal infrastructure replacement cycles for NSF/ANSI 61-certified drinking water storage. EPA corrosion protection mandates accelerate fiberglass adoption at retail fueling stations nationwide. Houston-area petrochemical clusters specify vinyl ester systems for aggressive chemical containment.
Saudi Arabia
Desalination plant expansion and petrochemical capacity buildout generate demand for large-diameter fiberglass vessels. The country's national water regulator enforces stringent material specifications for potable water infrastructure. Eastern Province industrial cities concentrate procurement for process storage and brine handling applications.
Germany
EU F-Gas Regulation refrigerant containment mandates open specification windows for HVAC fiberglass alternatives. ECHA REACH compliance frameworks restrict certain resin formulations, forcing catalyst system validation. Bavarian industrial machinery clusters source corrosion-resistant tanks for chemical process integration.
India
Bureau of Indian Standards certification requirements tighten material specifications for water treatment infrastructure. Central government urban mission programs accelerate municipal storage tank replacement in tier-2 cities. Gujarat chemical processing corridors specify fiberglass containment for acid and caustic storage.
Japan
METI industrial efficiency standards promote corrosion-resistant storage for chemical and electronics manufacturing. JIS certification requirements govern pressure vessel specifications for industrial applications. Osaka-Kobe manufacturing belt procurement concentrates on high-purity process water containment systems.
Fiberglass Tanks Market Vendor Landscape
Capability concentration sits with custom engineering specialists; scale advantage sits with standardized storage fabricators. The vendor base organizes around three strategic archetypes: underground petroleum containment specialists, upstream oilfield pressure vessel suppliers, and custom corrosion-resistant designers. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek specification influence with turnkey engineering-procurement-construction providers.
Among North American fabricators, Xerxes represents the underground storage specialization archetype, while NOV occupies a position within upstream oilfield equipment supply. Belding Tank Technologies exemplifies the custom corrosion-resistant design tier serving chemical processing end-users. These three anchors illustrate how geographic proximity to petrochemical clusters and regulatory stringency shape competitive positioning across the fiberglass tank value chain.
| Leading Market Players |
|---|
| Xerxes |
| Belco Manufacturing Company |
| KBK Industries |
| NOV |
| Industrial Plastic Systems |
| GSC Tank |
| Augusta Fiberglass |
| Marjan Factory Company |
| Belding Tank Technologies |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese filament winding equipment is pressuring European machinery suppliers to discount, compressing capital expenditure timelines for fiberglass tank fabricators while elevating buyer leverage in contract negotiations.
Pricing Analysis
Geographic price spreads widen significantly between North American NSF/ANSI 61-certified systems and Asian contact-molded alternatives. Three-tier pricing structure across premium API-compliant, standard industrial-grade, and economy agricultural tiers separates oilfield pressure vessels from municipal water storage from farm irrigation tanks. Pricing pressure stems from resin input volatility tied to petrochemical feedstock costs. Agricultural buyers exhibit highest price sensitivity, while oil and gas operators absorb premiums for corrosion-resistant certification.
Supply Chain Analysis
Export control regimes restricting advanced composite manufacturing technology to certain Middle Eastern markets are fragmenting equipment procurement channels. Supply concentrates in Germany, Italy, and China for filament winding machinery, with vinyl ester resin production anchored in the United States and Saudi Arabia. Raw material dependencies include E-glass fiber from China, isophthalic resin from petrochemical complexes, and specialized catalyst systems. Single-source vulnerability runs through German-Italian equipment suppliers. Distribution runs through engineering-procurement-construction firms consolidating vendor relationships under multi-year service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
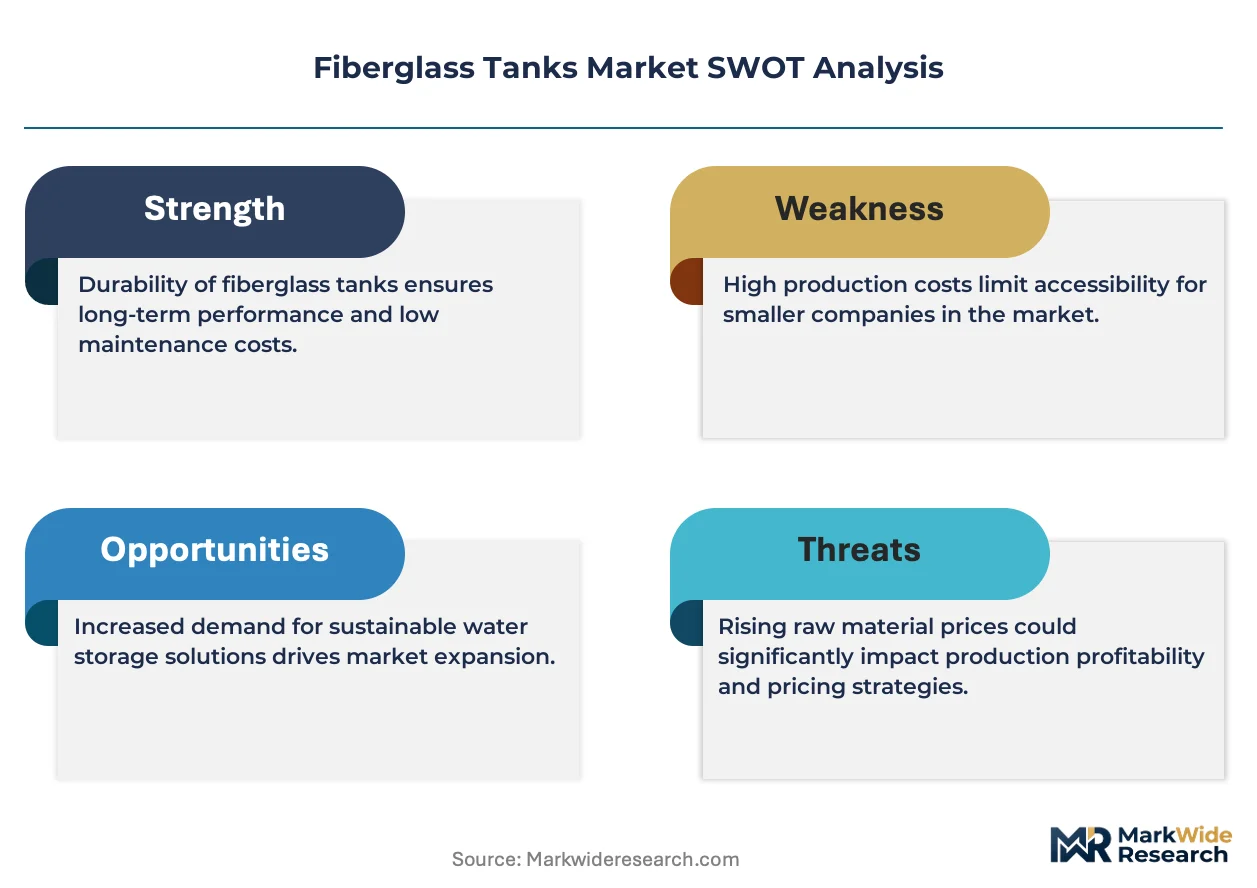
This market functions as a defensive-moat opportunity where regulatory entrenchment creates durable switching costs. EPA and NSF certification timelines lock in incumbent specification relationships.
For Market Incumbents: Insulate specification position by deepening backward integration into vinyl ester resin production and expanding capacity in Texas petrochemical corridors. Cement turnkey installation capabilities to capture multi-year municipal maintenance contracts before procurement cycles consolidate. Threat: Modular polyethylene tank systems are eroding agricultural share.
For New Entrants and Emerging Players: Build out hydrogen storage pressure vessel capabilities ahead of fueling infrastructure buildout, targeting California and Texas utility pilots. White-space concentrates in skid-mounted wastewater packages for decentralized rural treatment. Go-to-market angle: Partner with regional EPC firms lacking fiberglass fabrication expertise.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across API-certified pressure vessel segments as certification timelines extend. Long-term viability favors custom engineering specialists with captive resin formulation capabilities. Acquisition target archetype: Regional fabricators with established NSF/ANSI 61 approvals and underutilized winding capacity. Signal to watch: State-level environmental mandate acceleration in water-stressed jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive vinyl ester supply insulates margin from petrochemical feedstock volatility. |
| API Specification Certification Investment | Eighteen-month compliance cycles lock in oilfield pressure vessel procurement relationships. |
| Turnkey Installation Capability Buildout | Multi-year municipal service contracts displace transactional tank sales in Texas and California. |
| Hydrogen Storage Pressure Vessel Development | Specialized containment for high-purity hydrogen opens specification windows in emerging fueling networks. |
| EU REACH Compliance Reformulation | Alternative catalyst validation secures market access for European desalination project bids. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, NSF certification databases, and petrochemical trade publications. Interviews with municipal procurement officers, filament winding plant managers, EPC contract directors, and resin formulation chemists informed demand-side and supply-side dynamics. Secondary sources include customs data on E-glass fiber imports, SEC disclosures from listed equipment manufacturers, and state-level infrastructure budget appropriations. Bottom-up tank shipment data triangulates against top-down end-use industry capacity estimates.
Forecast inputs incorporate resin price indices, municipal infrastructure replacement cycle timing, and regulatory compliance timeline shifts. Segmentation modeling spans product type, application tier, design orientation, and end-use industry across the projection horizon. CAGRs derive from regression analysis of historical shipment volumes against explanatory variables including water utility capital expenditure trends and oilfield activity indicators. Hydrogen infrastructure deployment assumptions and EU F-Gas refrigerant containment mandate phasing inform scenario-weighted outputs.
Sensitivities concentrate around resin raw material availability disruptions and state-level environmental mandate acceleration. Forecasts reflect assumptions on EPA enforcement continuity and Saudi desalination project commitment levels. Material shifts in filament winding equipment trade flows or REACH catalyst restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Tooling Board Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Global Melamine Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
Couplings Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Shock Mat Market