
 India Steel Market | 2026-2036
India Steel Market Size, Share, and Industry Trends Forecast 2026-2036
India Steel Market Outlook
Aluminum in automotive body panels is decoupling lightweighting economics from traditional steel-intensive designs, yet high-strength advanced grades retain cost advantages in structural chassis applications. Tata Steel sustains leadership through integrated operations spanning captive iron ore to coated flat products. JSW Steel anchors western India capacity with its Dolvi and Vijayanagar complexes, while Jindal Steel and Power dominates long-product and rail-specialized output from Angul.
India steel comprises iron-carbon alloys with manganese, silicon, and trace sulfur-phosphorus limits, produced via blast furnace-basic oxygen furnace or electric arc furnace routes to yield tensile strengths from 250 MPa to over 550 MPa for load-bearing structures. Flat steel commands the dominant value pool through hot-rolled coil and galvanized sheet supply to automotive OEMs and appliance makers, while long steel and bars accelerate fastest from National Infrastructure Pipeline execution across highways, railways, and urban transit. Electric Arc Furnace and Direct Reduced Iron technology segments expand scrap-based and gas-based production, reducing coke-dependent emissions intensity.
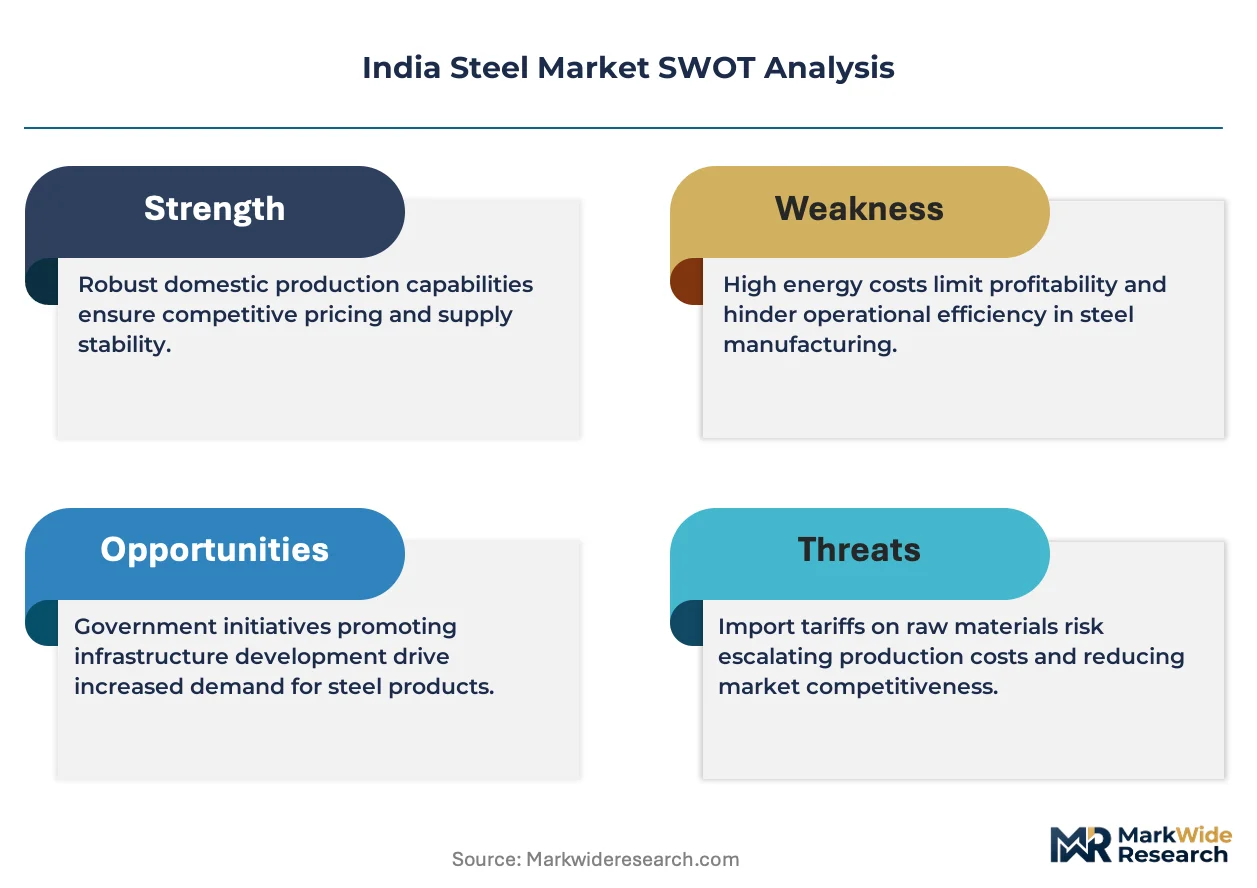
BIS certification mandates under the Steel Quality Control Order shape product standards and market access, while the Ministry of Steel's PLI scheme for specialty grades redirects capacity toward value-added output. State pollution control boards enforce MEE emissions norms on coke ovens and sinter plants, raising compliance capital requirements. Stakeholders must monitor green hydrogen pilot integrations at DRI units and evolving carbon border adjustment mechanisms affecting export competitiveness.
Market Dynamics
The National Infrastructure Pipeline is concentrating long steel demand into discrete project bundles, compressing procurement timelines and favoring integrated mills with captive ore and logistics control over merchant suppliers.
Growth Catalysts
- PLI Scheme for Specialty Grades:The Ministry of Steel's production-linked incentive redirects capacity toward coated flat products and high-strength automotive steels, pulling investment away from commodity rebar.
- Port-Linked Integrated Clusters:Concentration of blast furnace capacity in Odisha, Gujarat, and Maharashtra creates feedstock-to-ship economies that absorb iron ore from captive mines and coastal deposits.
- Electric Arc Furnace Expansion:Scrap-based melting capacity is accelerating in western India, decoupling production growth from coke oven bottlenecks and imported coking coal exposure.
Market Restraints
- Coking Coal Import Dependence:Blast furnace operations rely on Australian and Russian metallurgical coal, exposing margins to currency volatility and freight rate spikes.
- BIS Certification Friction:The Steel Quality Control Order mandates third-party testing for every product variant, extending time-to-market for new grades and specialized dimensions.
- Aluminum Substitution in Automotive Panels:OEM lightweighting programs are displacing cold-rolled sheet in hood and door applications where crash standards permit.
Strategic Opportunities
- Green Hydrogen DRI Pilots:Direct reduced iron units in coastal states are trialing hydrogen injection to reduce carbon intensity ahead of EU carbon border adjustments.
- Rail and Metro Specialization:Dedicated rail mill capacity for head-hardened rails and high-strength fish plates captures premium pricing from Dedicated Freight Corridor and urban transit expansion.
- Scrap Aggregation Platforms:Digital marketplaces for shredded auto and industrial scrap are emerging in Maharashtra and Tamil Nadu, disintermediating informal collectors and standardizing input quality.
Industry Challenges
- MEE Emissions Compliance:State pollution control boards are enforcing minimum emission standards on sinter plants and coke ovens, requiring bag filters and desulfurization capex that merchant mini-mills avoid.
- Blast Furnace Refractory Expertise:The specialized workforce for hot metal trough maintenance and taphole clay management is aging, with limited apprenticeship pipelines replacing retiring technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Steel Market |
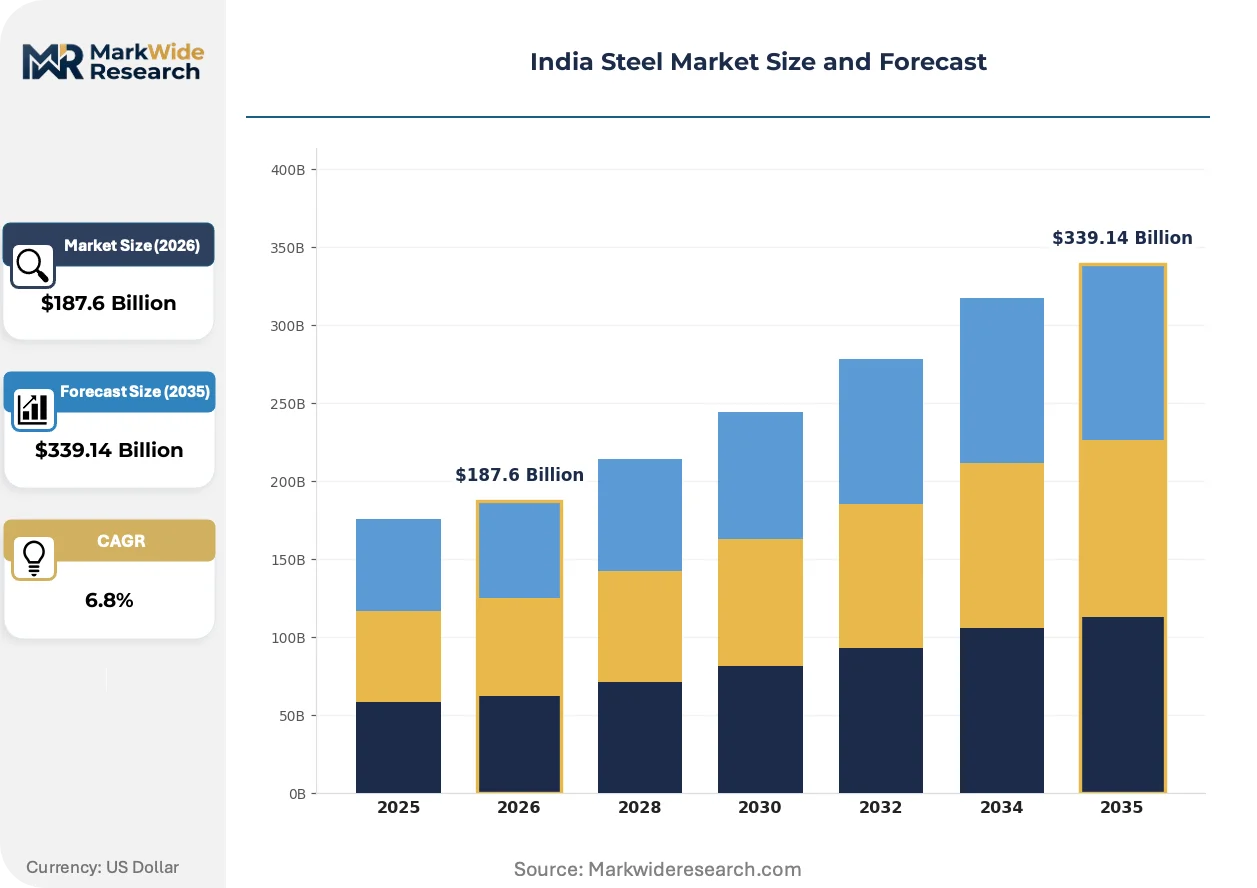
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Steel, Long Steel, Bars, Rods End User: Construction, Automotive, Shipbuilding, Energy Technology: Electric Arc Furnace, Basic Oxygen Furnace, Direct Reduced Iron, Induction Furnace Application: Infrastructure, Machinery, Consumer Goods, Heavy Equipment |
| Companies Covered | Steel Authority of India Limited (SAIL), JSW Steel, Tata Steel, Jindal Steel and Power, ArcelorMittal Nippon Steel India, Jindal Stainless, APL Apollo Tubes, Rashtriya Ispat Nigam Limited, NMDC Steel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Steel Market Strategic Shifts
Process digitization and hydrogen metallurgy are compressing the traditional blast furnace value chain, enabling smaller batch sizes and faster grade transitions that respond to just-in-time automotive schedules.
Green hydrogen injection at direct reduced iron units is modularizing the upstream steelmaking architecture. Pilot installations at coastal complexes are separating reduction from melting, allowing gas-based shaft furnaces to scale independently of blast furnace rebuild cycles. Automotive OEMs are qualifying hydrogen-reduced sponge iron for exposed panel grades ahead of Scope 3 reporting deadlines.
BIS certification mandates under the Steel Quality Control Order are tightening traceability requirements across the value chain. Every heat must now link to mill test certificates with QR-coded compliance records, forcing secondary rerollers to upgrade laboratory capabilities or exit branded product segments. Export-oriented flat steel producers are absorbing the cost fastest, integrating spectroscopy and mechanical testing into continuous casting lines.
Consolidation of construction procurement through infrastructure development corporations is compressing supplier bases and unbundling after-sales technical support. Large highway and metro contractors are mandating on-site welding supervision and batch testing as contract conditions, displacing the traditional stockist-distributor channel in Maharashtra and Gujarat. Integrated mills are responding with embedded project teams that manage logistics and quality assurance directly at construction sites.
India Steel Market Segmentation
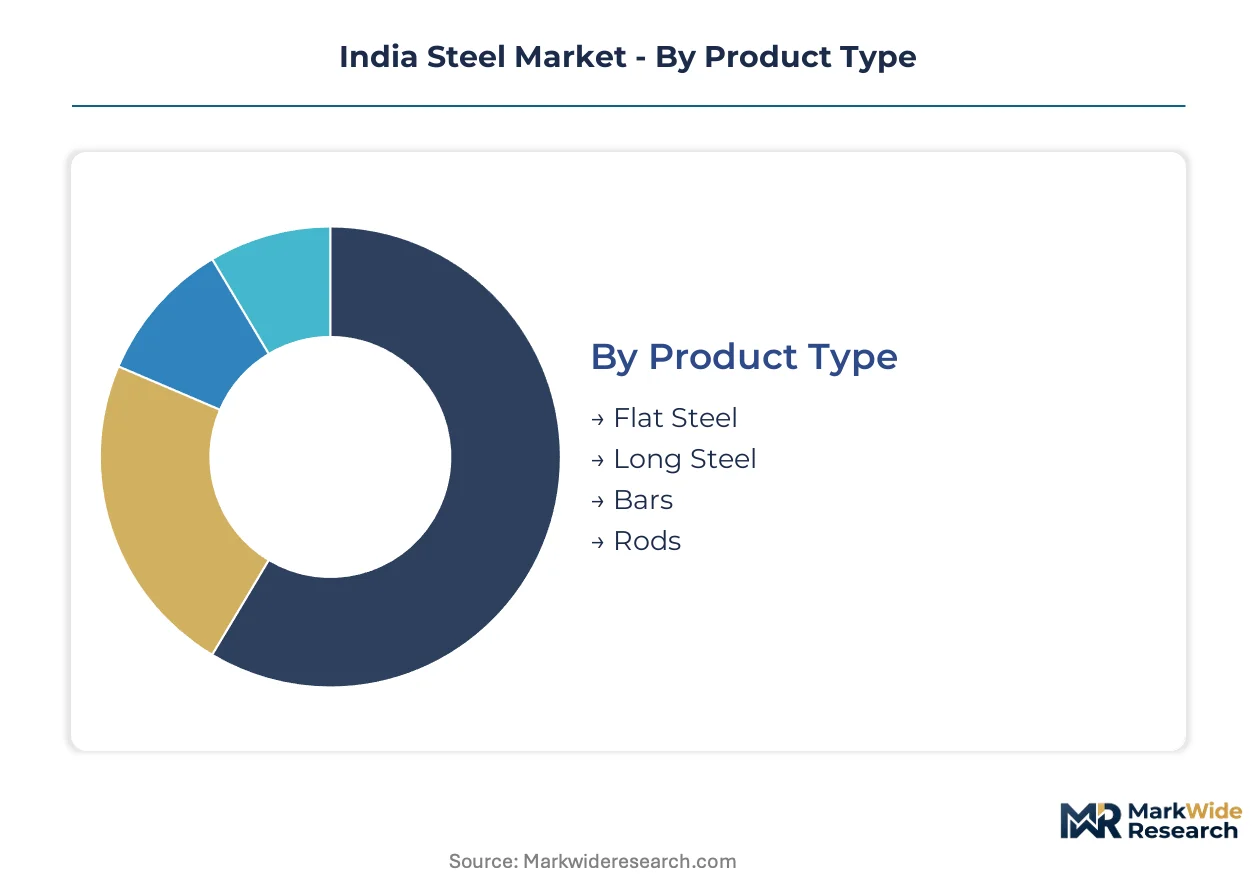
Steel demand in India fragments across product geometries, melting technologies, and end-use specifications that dictate margin structures and capital intensity. Each segmentation axis reveals distinct competitive dynamics between integrated blast furnace operators and emerging scrap-based producers.
Product Type:
Flat steel commands the premium value pool through coated automotive grades, while long steel and bars absorb the volume surge from infrastructure execution.
- Flat Steel:Hot-rolled coil and cold-rolled sheet with galvanized or color-coated finishes serve automotive OEMs and appliance manufacturers. Demand concentrates in Maharashtra and Gujarat where port-linked mills supply just-in-time sequences to Maruti Suzuki and Tata Motors assembly plants.
- Long Steel:Structural sections, beams, and channels for commercial construction and industrial frames. Odisha and Chhattisgarh integrated plants feed the National Infrastructure Pipeline's bridge and power transmission projects through direct contractor relationships.
- Bars:Thermo-mechanically treated reinforcement bars with 500D and 550D grades for seismic-resistant concrete. BIS certification mandates govern every heat, compressing informal reroller participation in branded segments.
- Rods:Wire rods drawn into fasteners, cables, and welding electrodes. Gujarat and Tamil Nadu mills supply the automotive component and engineering goods clusters.
Mature deployment sits with flat steel. Newer deployment is concentrated in long steel and bars from infrastructure acceleration.
End User:
Construction absorbs the dominant tonnage share, while automotive and energy applications extract premium pricing through specification stringency.
- Construction:Reinforcement bars, structural sections, and prefabricated building systems for highways, metros, and commercial real estate. State infrastructure development corporations in Maharashtra and Karnataka are consolidating procurement into single-source contracts.
- Automotive:High-strength low-alloy grades for chassis and exposed body panels. OEM lightweighting programs are qualifying advanced high-strength steels above 980 MPa tensile strength for crash-critical applications.
- Shipbuilding:Ship-quality plates and bulb flats for defense and commercial vessel construction. Cochin Shipyard and Mazagon Dock demand grade AH36 and DH36 certified to Bureau of Indian Standards and Lloyd's Register.
- Energy:Line pipe grades for oil and gas transmission, and boiler tubes for thermal power. Reliance Industries and NTPC specify API 5L X70 and SA 210 grades with full traceability.
Construction represents the fastest-growing trajectory from National Infrastructure Pipeline execution. Automotive maintains the steepest premium capture through grade specialization.
Technology:
Blast furnace-basic oxygen furnace routes dominate flat steel quality, while electric melting technologies are expanding scrap-based capacity in western India.
- Electric Arc Furnace:Scrap-based melting with 30-60 ton furnaces producing long products and billets. Maharashtra and Tamil Nadu clusters are aggregating shredded auto scrap through digital platforms to feed this capacity.
- Basic Oxygen Furnace:Hot metal refining from blast furnaces yielding deep-drawing grades and automotive exposed panels. Odisha's integrated complexes anchor this technology with captive iron ore.
- Direct Reduced Iron:Gas-based and coal-based sponge iron feeding electric furnaces or as blast furnace coolant. Gujarat and Karnataka plants are piloting hydrogen injection to reduce carbon intensity.
- Induction Furnace:Scrap and sponge iron melting for construction-grade billets and rebar. BIS certification requirements are forcing laboratory upgrades or exit from branded product segments.
Basic oxygen furnace deployment is mature in flat steel. Electric arc furnace and direct reduced iron are expanding most quickly as scrap availability improves and hydrogen pilots advance.
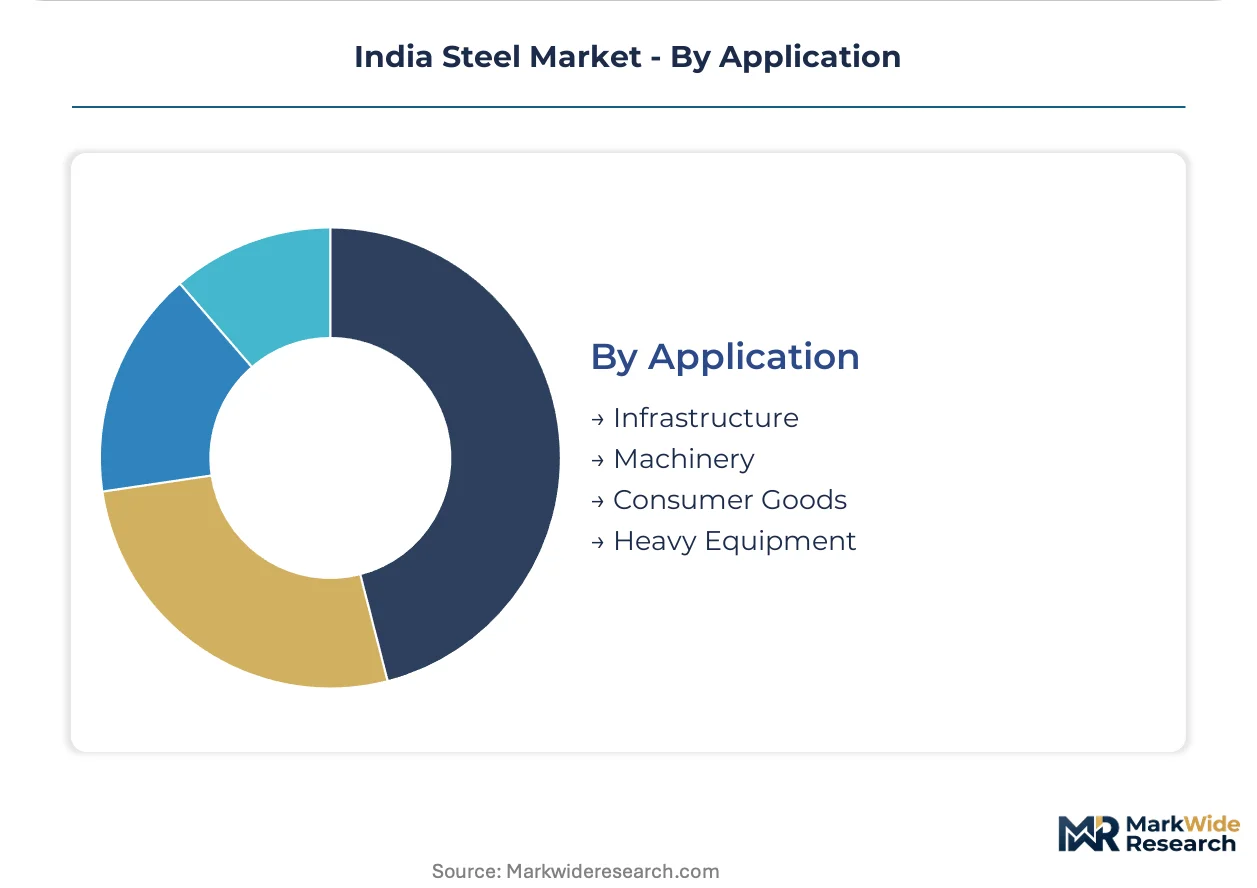
Application:
Infrastructure applications concentrate volume demand into project bundles, while machinery and consumer goods extract value through precision tolerances.
- Infrastructure:Dedicated freight corridor rails, metro viaducts, and highway bridges requiring certified weldability and fatigue resistance. Large contractors now mandate on-site welding supervision as contract conditions.
- Machinery:Engineering steels for machine tools, agricultural equipment, and industrial gear. Punjab and Gujarat manufacturing clusters source forged and rolled blanks with controlled hardenability.
- Consumer Goods:Cold-rolled and coated sheets for appliances, furniture, and packaging. Whirlpool and Voltas specify zero-spangle galvanized finishes for refrigerator panels.
- Heavy Equipment:Quenched and tempered plates for mining trucks, excavators, and cranes. Bharat Earth Movers and Larsen & Toubro demand 690 MPa yield strength grades with through-thickness toughness.
Infrastructure commands mature deployment at scale. Machinery and heavy equipment are gaining share fastest from capital goods indigenization and mining expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal Special Economic Zones in Odisha, Gujarat, and Maharashtra concentrate integrated steel capacity near captive iron ore deposits and deep-water export berths.
Odisha
The Paradip and Angul industrial corridors absorb iron ore from the Barbil-Koira belt for blast furnace feedstock. State pollution control boards enforce MEE emissions norms on coke ovens and sinter plants. Rourkela and Angul host integrated complexes producing long steel for the National Infrastructure Pipeline.
Gujarat
Hazira port-linked plants supply flat steel to automotive OEMs in Pune and Sanand. BIS certification mandates under the Steel Quality Control Order govern every heat shipped to construction contractors. The Mundra and Hazira clusters anchor western India capacity with direct reduced iron integration.
Maharashtra
Mumbai-Pune industrial demand concentrates procurement for metro viaducts and highway bridges. State infrastructure development corporations consolidate rebar contracts into single-source agreements. The Dolvi complex and Thane district rerollers serve the construction boom with TMT bars.
Karnataka
The Bellary-Hospet iron ore belt feeds electric arc furnace and induction furnace units in Bangalore and Hubli-Dharwad. Scrap aggregation platforms are emerging in Tamil Nadu border districts to feed western Karnataka melting capacity. The PLI scheme for specialty grades redirects investment toward coated flat products.
Tamil Nadu
Salem and Chennai host specialized rail and wire rod mills serving the engineering goods cluster. Port-based direct reduced iron units trial hydrogen injection to reduce carbon intensity. State pollution control boards monitor emissions from coke ovens supplying the Salem steel plant.
India Steel Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated blast furnace operators commanding flat steel premiums while scrap-based mini-mills capture construction rebar volume. The market structures around three tiers: captive ore integrated majors, port-linked coastal complexes, and regional induction furnace rerollers. Archetypes include ore-to-metal vertical integrators, scrap-based circular economy players, and alloy-grade specialists. Competitive moves concentrate on green hydrogen pilot investments and rail-specific capacity additions.
Among integrated ore-to-metal operators, Steel Authority of India Limited and JSW Steel exemplify the captive resource archetype with blast furnace-basic oxygen furnace configurations. Tata Steel occupies a position bridging flat steel automotive supply and long product infrastructure execution. Jindal Steel and Power represents the long-product specialization vector with Angul-based rail and structural capacity.
| Leading Market Players |
|---|
| Steel Authority of India Limited (SAIL) |
| JSW Steel |
| Tata Steel |
| Jindal Steel and Power |
| ArcelorMittal Nippon Steel India |
| Jindal Stainless |
| APL Apollo Tubes |
| Rashtriya Ispat Nigam Limited |
| NMDC Steel |
| Others |
Value Chain & Pricing Dynamics
National Infrastructure Pipeline contractors concentrate procurement into single-source agreements, compressing supplier bases and forcing a contract-based long-term offtake pricing model that rewards integrated mills with captive ore and logistics control.
Pricing Analysis
Short lead-time premiums dominate spot procurement for urgent highway and metro projects, while contract volumes trade at discounts tied to BIS certification grade and volume scale. Price differentiation separates automotive-grade coated flats from construction rebar, with the former capturing brand premiums for OEM sequences. Cost compression in commodity bars is intensifying because scrap-based electric arc furnace capacity is expanding in western India. State infrastructure development corporations exhibit the highest price sensitivity, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Scrap return flows from demolished structures and end-of-life vehicles are aggregating through digital marketplaces in Maharashtra and Tamil Nadu, feeding electric arc furnace capacity and reducing dependence on imported coking coal. Raw material sourcing draws from the Barbil-Koira iron ore belt in Odisha, Australian metallurgical coal, and shredded auto scrap from western India clusters. Single-source vulnerability sits with coking coal imports from Australia and Russia, exposing margins to currency volatility. Distribution runs through direct mill-to-project logistics for infrastructure bundles and just-in-time sequences to automotive OEMs in Pune and Sanand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India steel is transitioning from blast furnace-dominated production to hydrogen-ready direct reduced iron and scrap-based electric melting, with green hydrogen pilots replacing coke-dependent reduction in coastal complexes.
For Market Incumbents: Extend captive ore advantages by embedding project teams at National Infrastructure Pipeline sites to manage logistics and quality assurance directly, neutralizing merchant mini-mill price competition. Accelerate hydrogen injection trials at direct reduced iron units ahead of EU carbon border adjustments, securing automotive OEM qualification for Scope 3 reporting compliance.
For New Entrants and Emerging Players: Scrap aggregation platforms serving western India electric arc furnace clusters represent the most penetrable entry point, disintermediating informal collectors and standardizing input quality. Target rail and metro specialization with dedicated head-hardened rail capacity, leveraging premium pricing from Dedicated Freight Corridor expansion and urban transit buildouts.
For Investors and Strategic Acquirers: The window for entry favors port-linked integrated complexes with backward integration into captive iron ore and coastal hydrogen infrastructure. Long-term viability hinges on carbon intensity reduction credentials ahead of evolving trade barriers. Monitor BIS certification enforcement intensity as the inflection indicator for informal reroller exit rates and branded segment margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen DRI Pilot | Positions coastal complexes for EU carbon border adjustment compliance ahead of automotive OEM deadlines. |
| Rail Mill Specialization | Captures premium pricing from Dedicated Freight Corridor and metro expansion with head-hardened rail capacity. |
| Scrap Aggregation Platform | Disintermediates informal collectors in Maharashtra and Tamil Nadu, standardizing electric arc furnace feedstock quality. |
| Embedded Project Teams | Consolidates National Infrastructure Pipeline contractor relationships through on-site welding supervision and logistics control. |
| BIS Certification Integration | Forces secondary reroller laboratory upgrades or exit, concentrating branded rebar share among integrated mills. |
Study Parameters
Multi-period observation of blast furnace operating rates, electric arc furnace capacity additions, and BIS certification compliance rates anchored the trend analysis, supplemented by interviews with steel plant operations directors, procurement leads at state infrastructure development corporations, automotive OEM platform engineers, and merchant reroller owners. Secondary validation drew from Ministry of Steel PLI scheme disclosures, BIS quality control order amendments, customs coking coal import data, and National Infrastructure Pipeline project tracking databases. Bottom-up capacity modeling and top-down demand projection triangulation ensured cross-verification.
Input-output matrices mapped iron ore availability, coking coal import exposure, and scrap generation rates against end-use demand from construction, automotive, and energy sectors across the analysis window. Segmentation dimensions included product geometry, melting technology, and application intensity. CAGRs derived from production capacity commissioning schedules, infrastructure project execution timelines, and automotive production forecasts. Hydrogen pilot progression and carbon border adjustment mechanism developments informed scenario weighting.
Revisions become necessary when Ministry of Steel policy shifts, BIS enforcement intensity changes, or EU carbon border adjustment implementation timelines materialize differently than modeled. Practitioners should monitor green hydrogen cost curves, scrap availability in western India, and infrastructure project disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Ultra Fine Copper Powder Market
Metals
GCC Aluminium Powder Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Clutch Spring Wires Market
Metals
Metal Coil Lamination Market
Metals
Colloidal Metal Particles Market
Metals
High Purity Pig Iron Market
Metals
Global Copper Cathode Market
Metals
Medium Carbon Steel Market
Metals
Gold Smelting Market
Metals
Global Steel Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Titanium Mill Products Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
High Purity Tungsten Market
Metals
Armour Steel Plate Market