
 Wire Hoods Market | 2026-2036
Wire Hoods Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Hoods Market Outlook
Automotive electrification is broadening the end-use vertical mix for wire hoods as high-voltage architectures multiply connection points per vehicle. Labconco leverages its contamination-control expertise to anchor supply relationships with specialty vehicle manufacturers. Sentry Air Systems, Inc. competes through localized production configurations that reduce lead times for North American automotive clients.
Wire hoods are protective enclosures fabricated from plastic, metal, or composite substrates, typically engineered to precise tolerances for thermal resistance and dielectric strength, serving primarily to shield wiring assemblies from moisture, abrasion, and electromagnetic interference. Standard hoods dominate volume production for mass-market automotive platforms where cost engineering governs procurement decisions, while specialty hoods command premium positioning in aerospace applications requiring flame-retardant certifications and extreme-temperature performance. Composite materials represent the fastest-growing material category as manufacturers seek to reduce weight without sacrificing chemical resistance.
EPA emissions guidelines and NHTSA safety standards in the United States, alongside REACH chemical restrictions in Europe, are tightening material disclosure requirements and accelerating substitution of legacy PVC formulations. China's GB standards and SAMR quality certifications add parallel compliance layers for suppliers serving domestic automotive OEMs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification costs.
Market Dynamics
Automotive electrification is restructuring wire hood demand as high-voltage architectures multiply connection points per vehicle and OEMs prioritize thermal management in battery compartments.
Growth Catalysts
- Electric vehicle production:Battery electric and hybrid platforms require 40% more wiring protection points than internal combustion architectures, expanding addressable volume for hood suppliers serving automotive OEMs.
- REACH chemical restrictions:ECHA's phased limitations on halogenated flame retardants are redirecting European procurement toward halogen-free polyamide compounds, creating specification upgrade cycles.
- GB standards alignment:China's SAMR quality certifications for automotive wiring assemblies are tightening domestic supply qualification thresholds, consolidating demand toward certified tier-1 manufacturers.
Market Restraints
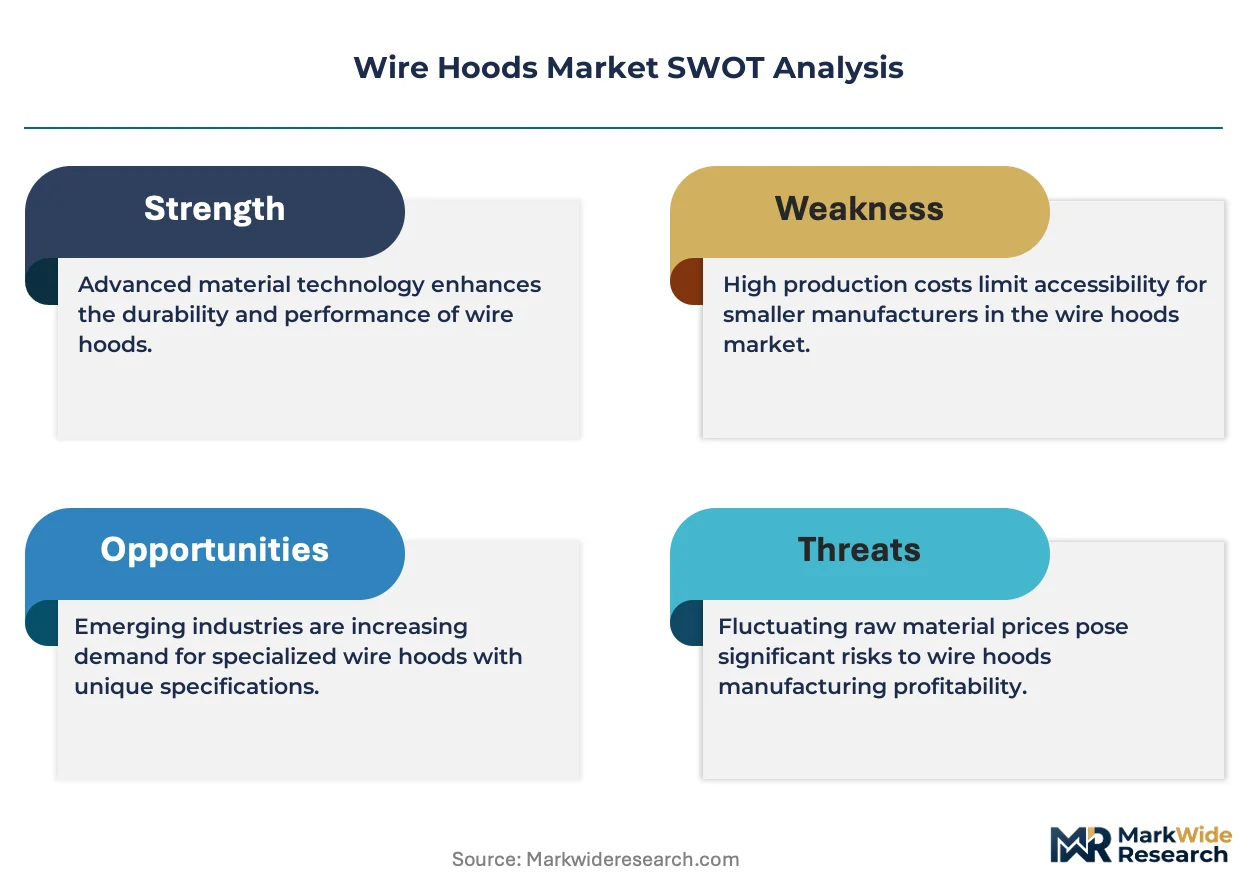
- Resin cost volatility:Engineering-grade polyamide and polypropylene compounds face input price swings tied to crude oil derivatives, compressing margin predictability for hood fabricators.
- Supplier concentration:Specialty composite substrate production clusters in Germany and Japan, exposing buyers to single-source risk for aerospace-grade flame-retardant formulations.
- Technical limitation:Current thermoplastic formulations struggle to maintain dielectric strength above 150°C continuous operating temperature, constraining deployment in next-generation 800V EV architectures.
Strategic Opportunities
- Underpenetrated India:Domestic automotive wiring harness capacity is expanding under PLI scheme incentives, creating first-mover positioning for hood suppliers establishing local compounding operations.
- Regulatory tailwind:The EU Green Deal's circular economy requirements are mandating recyclable content thresholds, favoring suppliers with validated closed-loop polyamide recovery processes.
- Technology convergence:Integration of EMI shielding layers with structural hood bodies is enabling single-component solutions that reduce assembly labor for wiring system integrators.
Industry Challenges
- Certification timeline compression:OEMs are collapsing product development cycles from 36 to 24 months, straining hood suppliers' validation throughput for thermal cycling and chemical resistance testing.
- Skill gap in composite processing:Shortage of technicians trained in continuous fiber thermoplastic molding is limiting capacity expansion for lightweight hood production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Hoods Market |
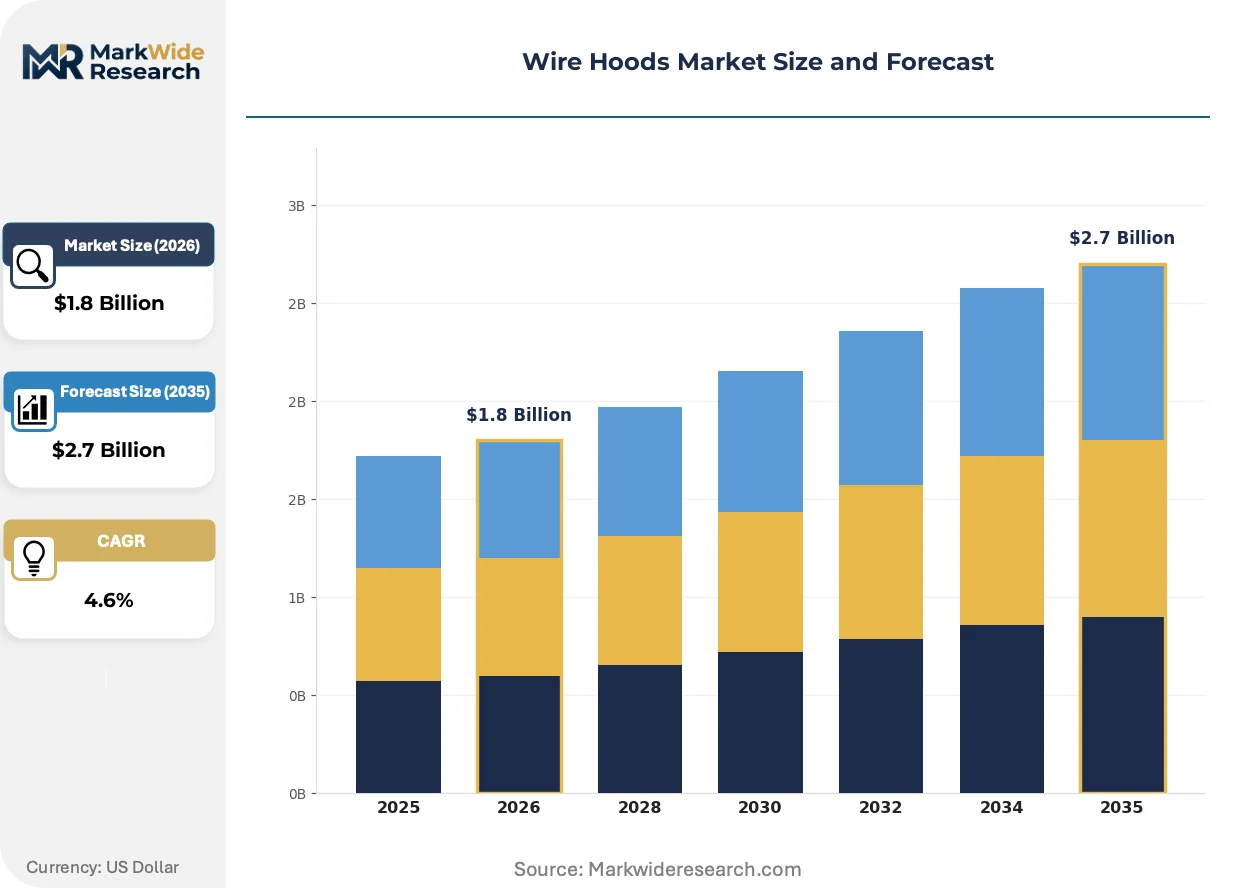
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hoods, Adjustable Hoods, Specialty Hoods, Custom Hoods Material: Plastic, Metal, Rubber, Composite End User: Automotive, Aerospace, Telecommunications, Electrical Appliances Application: Wiring Protection, Environmental Sealing, Insulation, Safety Management |
| Companies Covered | Labconco, Sentry Air Systems, Inc., AirClean Systems, Inc., Elica S.P.A, Bionics Scientific Technologies, NuAire, Inc., Mystaire, Inc., Faber S.P.A, Terra Universal, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Hoods Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape wire hood formulation roadmaps and procurement specifications across automotive and aerospace verticals.
Continuous fiber-reinforced thermoplastic composites are integrating metal-grade stiffness with polymer processability for under-hood applications. Tier-1 wiring system manufacturers in Germany and the United States are qualifying these materials for battery pack cable routing. The technology is integrating structural and electromagnetic functions into single molded components, reducing part count and assembly time for high-voltage architectures.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing reformulation of legacy PVC-based wire hood compounds across European supply chains. Compounders must validate alternative plasticizer systems without sacrificing low-temperature flexibility. Specialty automotive grades face the steepest compliance burden, with OEMs now requiring full material disclosure to 0.1% threshold for SVHC substances.
Long-term supply agreements are displacing spot purchasing for engineered resin compounds as automotive OEMs seek price stability amid raw material volatility. Wiring harness manufacturers in China and Germany are locking in multi-year polyamide supply contracts with indexed pricing mechanisms. This pattern is most pronounced in electric vehicle platforms where hood specifications are frozen earlier in development cycles to support homologation timelines.
Wire Hoods Market Segmentation
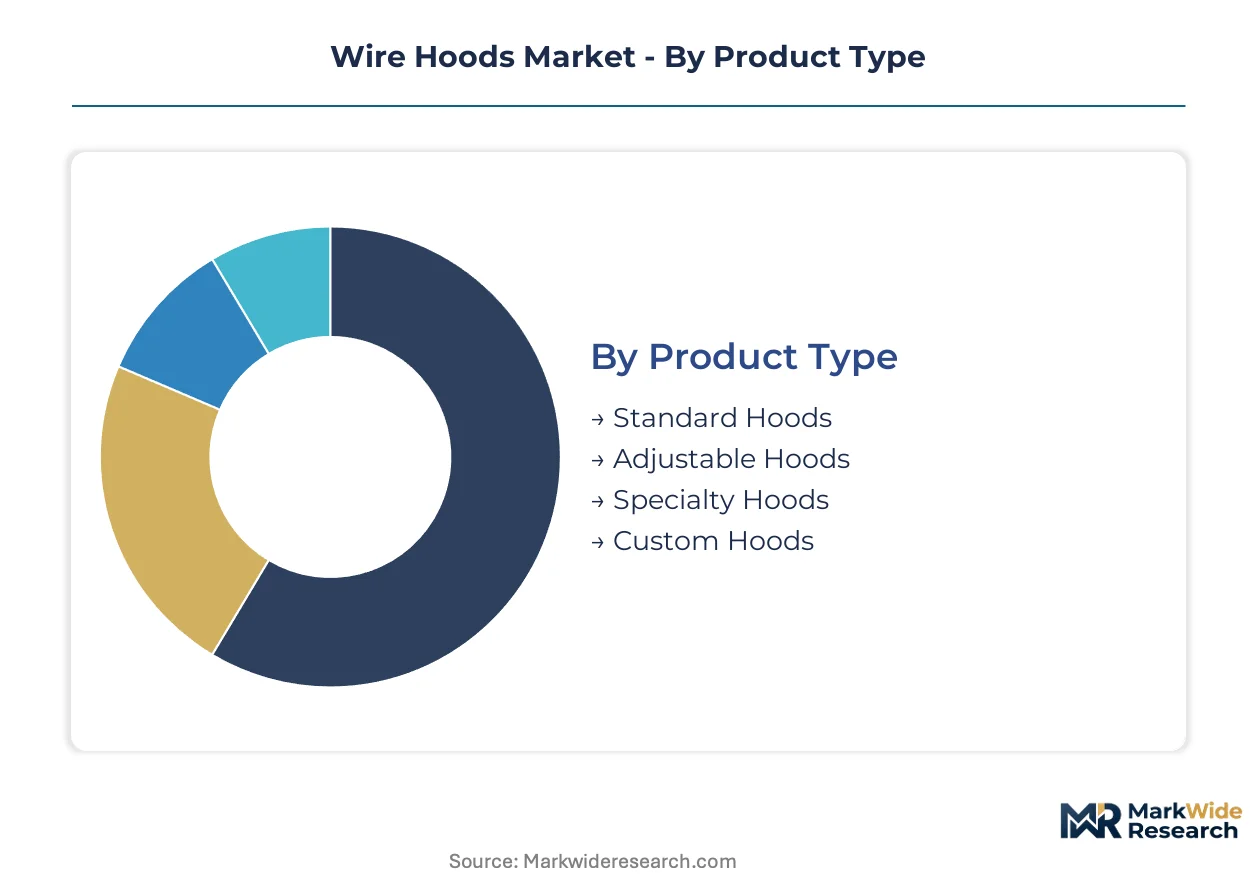
Wire hood procurement decisions split across four intersecting dimensions. Product type governs unit economics for automotive tier-1 suppliers. Material selection determines compliance pathways under REACH and GB standards. End-user concentration in electric vehicle manufacturing is redirecting R&D budgets toward high-temperature formulations.
Product Type:
Automotive OEMs select hood configurations based on platform volume and specification freeze timing.
- Standard Hoods:Injection-molded polyamide or polypropylene units produced to SAE and ISO dimensional tolerances for mass-market vehicle platforms. Procurement concentrates at wiring harness manufacturers serving Chinese and German OEMs where cost engineering governs supplier qualification.
- Specialty Hoods:Engineered from halogen-free flame-retardant compounds with validated dielectric strength above 600V for aerospace and high-voltage EV battery compartments. Demand clusters at tier-1 suppliers in the United States and Germany pursuing FAA and EASA certifications.
- Adjustable Hoods:Modular designs accommodating variable cable diameters through integrated clamp mechanisms, favored in aftermarket repair channels and low-volume specialty vehicle production.
- Custom Hoods:Application-specific geometries tooled for proprietary connector interfaces, typical in telecommunications infrastructure and defense electronics where interoperability standards are absent.
Standard hoods lead on scale; specialty hoods lead on momentum.
Material:
Compound selection is restructuring around regulatory chemistry restrictions and thermal load requirements.
- Composite:Continuous fiber-reinforced thermoplastic laminates combining polyamide matrices with glass or carbon fiber. German tier-1 wiring manufacturers are qualifying these for 800V battery pack cable routing where metal-grade stiffness must coexist with polymer processability.
- Plastic:Engineering-grade polyamide 6/6 and polypropylene dominate volume production, though REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing reformulation cycles across European supply chains.
- Metal:Stamped aluminum and stainless steel hoods retain niche positioning in aerospace fire zones and heavy-duty commercial vehicles where impact resistance exceeds polymer capabilities.
- Rubber:EPDM and silicone formulations serve environmental sealing applications in outdoor telecommunications enclosures, constrained by compression set limitations above 125°C continuous operation.
Plastic retains volume leadership; composite claims the steepest expansion trajectory.
End User:
Customer concentration patterns follow automotive electrification investment cycles and aerospace production backlogs.
- Automotive:Battery electric and hybrid platforms require expanded wiring protection footprints, with Chinese and German OEMs specifying hood quantities per vehicle at 40% above internal combustion benchmarks.
- Aerospace:Flame-retardant certification requirements under FAA and EASA regulations sustain premium pricing for qualified suppliers, though production volumes remain constrained by airframe delivery schedules.
- Telecommunications:5G infrastructure deployment is generating demand for weather-resistant hooding at fiber-to-the-antenna connection points across United States and Chinese network buildouts.
- Electrical Appliances:Consumer white goods manufacturers specify cost-optimized polypropylene hoods for internal power cord management, with procurement concentrated at appliance OEMs in China and Mexico.
Automotive commands revenue concentration; telecommunications is gaining share fastest.
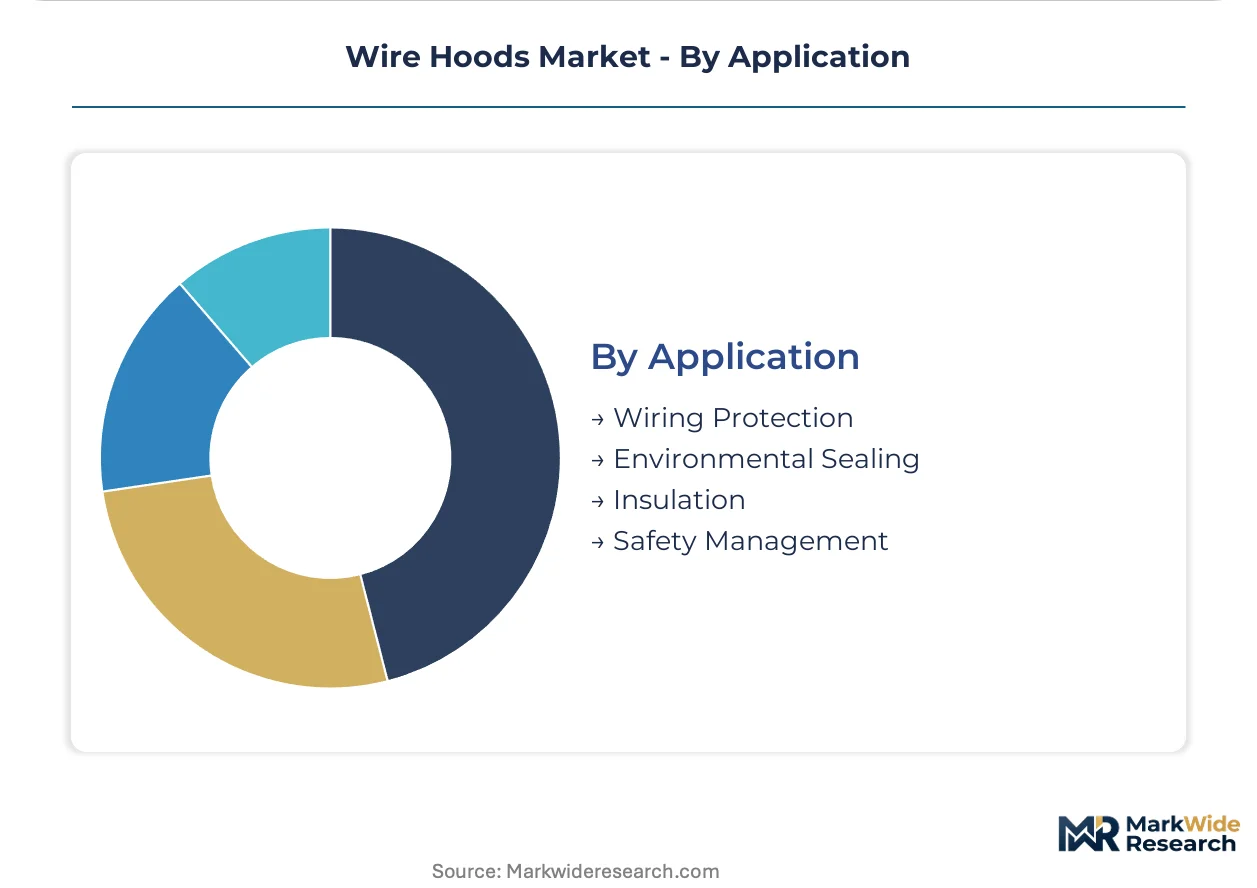
Application:
Functional requirements determine material specification tiers and testing protocol intensity.
- Wiring Protection:Abrasion and moisture shielding for harness routing through vehicle chassis and engine compartments, representing the foundational use case across all material categories.
- Environmental Sealing:IP-rated ingress protection for underhood and underbody zones exposed to pressure washing, salt spray, and thermal cycling, prevalent in electric vehicle battery pack architectures.
- Insulation:Dielectric isolation between high-voltage and low-voltage circuits in 400V and 800V EV platforms, requiring validated tracking resistance and comparative tracking indices.
- Safety Management:Fire containment and arc flash mitigation in aerospace power distribution and industrial electrical cabinets, governed by UL and IEC flame-spread standards.
Wiring protection anchors volume; environmental sealing is climbing the fastest on electrification tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting wire hood production toward jurisdictions with lower compliance costs, even as end-use demand clusters in high-standard automotive markets. Manufacturers balance REACH-mandated reformulation expenses in Europe against China's GB standard alignment costs and the United States' NHTSA safety certification requirements.
China
Domestic electric vehicle production is expanding wiring harness capacity under MIIT industrial policy directives. SAMR quality certifications for automotive wiring assemblies are tightening supplier qualification thresholds, consolidating procurement toward certified tier-1 manufacturers. Shanghai and Shenzhen host the densest concentrations of automotive OEMs and wiring system integrators.
Germany
High-voltage EV architectures from BMW and Volkswagen are multiplying connection points per vehicle. ECHA's REACH Annex XVII restrictions on halogenated flame retardants are redirecting procurement toward halogen-free polyamide compounds. Bavaria and Baden-Württemberg anchor specialty composite substrate development for aerospace-grade formulations.
United States
EPA emissions guidelines and NHTSA safety standards are tightening material disclosure requirements for automotive suppliers. Battery electric platform launches by Detroit automakers are expanding addressable volume for hood fabricators. Michigan and Ohio retain production gravity for tier-1 wiring harness manufacturers serving North American OEMs.
Japan
METI industrial standards for automotive electrical systems are converging with international thermal management specifications. Continuous fiber thermoplastic composite development is concentrating near Nagoya's automotive supplier corridor. Toyota and Honda electrification roadmaps are accelerating qualification timelines for high-temperature hood formulations.
India
PLI scheme incentives are expanding domestic automotive wiring harness capacity, creating first-mover positioning for hood suppliers establishing local compounding operations. BIS quality certifications are raising entry barriers for imported components. Maharashtra and Tamil Nadu are attracting tier-1 manufacturing investments from global wiring system integrators.
Wire Hoods Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with automotive procurement favoring scale-certified suppliers while aerospace maintains qualification-driven concentration. The vendor base organizes into three tiers: integrated material compounders with captive hood fabrication, specialized wiring protection fabricators, and regional contract molders serving aftermarket channels. Two dominant competitive moves are reshaping positioning: backward integration into polyamide compounding to secure resin supply, and geographic expansion through joint ventures in high-growth EV manufacturing clusters.
Among contamination-control specialists, Labconco exemplifies the premium-tier archetype through its positioning with specialty vehicle manufacturers. Sentry Air Systems, Inc. occupies a distinct position among North American fabricators competing through localized production configurations. AirClean Systems, Inc. represents the engineering-focused segment serving regulated industrial environments.
| Leading Market Players |
|---|
| Labconco |
| Sentry Air Systems, Inc. |
| AirClean Systems, Inc. |
| Elica S.P.A |
| Bionics Scientific Technologies |
| NuAire, Inc. |
| Mystaire, Inc. |
| Faber S.P.A |
| Terra Universal, Inc. |
| Others |
Value Chain & Pricing Dynamics
Continuous fiber-reinforced thermoplastic molding adoption is compressing unit economics for lightweight hood production while simultaneously concentrating qualified supplier capacity in Germany and Japan. This technology transition simultaneously elevates capital requirements for new entrants and tightens procurement leverage for automotive OEMs able to commit volume.
Pricing Analysis
Distributor margin layers vary significantly across channel structures, with direct-to-OEM contracts commanding 15-20 point discounts versus aftermarket distribution. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified specialty hoods from mass-market automotive grades and unbranded replacement parts. Cost compression in standard polyamide formulations is intensifying because of crude derivative volatility, with wiring harness manufacturers in China exhibiting highest price sensitivity while German aerospace buyers prioritize qualification certainty over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from BMW and Volkswagen are forcing tier-1 wiring manufacturers to qualify secondary compounders for halogen-free polyamide supply. Production concentrates in China, Germany, and the United States, with raw material supply drawing from Saudi Arabian petrochemical feedstocks, Belgian specialty additive producers, and Japanese carbon fiber weavers. Single-source vulnerability persists for aerospace-grade flame-retardant formulations certified under FAA and EASA standards. Distribution runs through tier-1 wiring system integrators rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wire hood procurement functions as a regulatory compounder where REACH Annex XVII phased restrictions on halogenated flame retardants are mandating specification upgrades across European automotive supply chains.
For Market Incumbents: Acquire captive polyamide compounding assets to secure resin supply against engineering-grade polymer price volatility. Expand high-temperature formulation capacity in Baden-Württemberg to capture 800V EV architecture qualification cycles. Defend against specialty composite entrants by accelerating FAA and EASA certification timelines for existing flame-retardant portfolios.
For New Entrants and Emerging Players: Direct-to-OEM digital procurement platforms offer bypass routes around entrenched tier-1 wiring harness relationships. Target India's PLI scheme-supported automotive wiring capacity expansion in Maharashtra and Tamil Nadu as the most penetrable geography. Lead with localized compounding operations rather than imported finished hoods to satisfy BIS quality certification requirements.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap specialty hood fabricators because customer qualification databases represent non-replicable intangible assets with decade-long renewal cycles. Over a five-to-ten year window, prioritize targets with validated closed-loop polyamide recovery processes aligned to EU Green Deal circular economy mandates. Monitor ECHA substance restriction announcements as the critical inflection signal for forced specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Compounding | Secures resin supply against oil derivative volatility for German automotive tier-1s. |
| High-Temperature Formulation R&D Investment | Enables qualification for 800V battery pack architectures at BMW and Volkswagen. |
| Joint Venture in Indian Manufacturing Cluster | Captures PLI scheme incentives and BIS certification proximity for domestic OEM supply. |
| Closed-Loop Polyamide Recovery Process Validation | Satisfies EU Green Deal recyclable content thresholds for European procurement. |
| EMI Shielding Integration Technology Development | Reduces part count for wiring system integrators serving high-voltage EV platforms. |
Study Parameters
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market gathered through structured interviews with tier-1 wiring harness procurement directors, automotive OEM platform engineers, polyamide compounder technical R&D leads, and aftermarket distribution channel managers. Secondary validation draws from SAMR quality certification databases, ECHA REACH restriction announcements, MIIT industrial policy directives, vehicle production registries, and SEC filings from listed automotive suppliers. Bottom-up demand modeling triangulates against top-down market sizing across material categories and end-use verticals.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions include product type tier, material substrate category, end-user industry vertical, and regional regulatory cluster. CAGRs derive from trend extrapolation of electric vehicle production forecasts, specification upgrade cycle timing, and substitution elasticity between material categories. Industry-specific inputs incorporate battery electric vehicle wiring protection point multipliers, REACH compliance cost pass-through coefficients, and GB standards alignment timelines for Chinese domestic supply qualification.
The model assumes a particular technology adoption path for continuous fiber-reinforced thermoplastics; alternative pathways for metal-to-polymer substitution in 800V architectures would alter the outlook for composite material penetration. Deviation in ECHA substance restriction timelines or MIIT industrial policy incentive structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Cork Material Market
Industrial Materials
Paint Knife Market