
 Southeast Asia Industrial Flooring Market | 2026-2036
Southeast Asia Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Industrial Flooring Market Analytics
Aftermarket service revenue from floor recoating, joint repair, and topcoat refresh cycles is reshaping margin distribution across the value chain. Sika AG leverages its applicator certification network to sustain recurring maintenance contracts in Thailand's automotive assembly plants. BASF SE anchors its position through captive resin supply and in-house production of hardener systems for epoxy formulations. Sherwin-Williams Company competes via color-matching laboratories in Singapore that serve pharmaceutical cleanroom specifications across the region.
Southeast Asia industrial flooring comprises resinous, cementitious, and polymer-modified surface systems engineered to withstand mechanical abrasion, chemical attack, thermal cycling, and electrostatic discharge, with thickness specifications typically ranging from 2 mm for light-duty coatings to 12 mm for heavy-duty screeds. These installations protect concrete substrates while enabling hygiene compliance, operational safety, and process-specific performance in manufacturing environments. Epoxy formulations dominate current specification volumes due to cost efficiency and chemical resistance, though polyurethane segments are gaining share in thermal shock applications such as food processing blast freezers. Cementitious systems occupy a mature niche in wet-process chemicals and battery manufacturing facilities where fire resistance and conductive properties are mandated. Installation method selection increasingly stratifies by project scale, with self-leveling systems preferred in large-format warehousing and trowel-applied builds specified for precision gradient control in pharmaceutical operations.
Malaysia's Department of Occupational Safety and Health, Thailand's Ministry of Industry, and Singapore's Building and Construction Authority collectively enforce surface safety, emissions, and structural load standards that determine product qualification for industrial tenders. Vietnam's Ministry of Construction has adopted GB-influenced fire-resistance classifications for factory flooring, creating compliance barriers for uncertified imported systems. Stakeholders must monitor diverging national certification timelines and pre-qualify installation partners ahead of capital expenditure cycles in Indonesia's emerging battery materials sector.
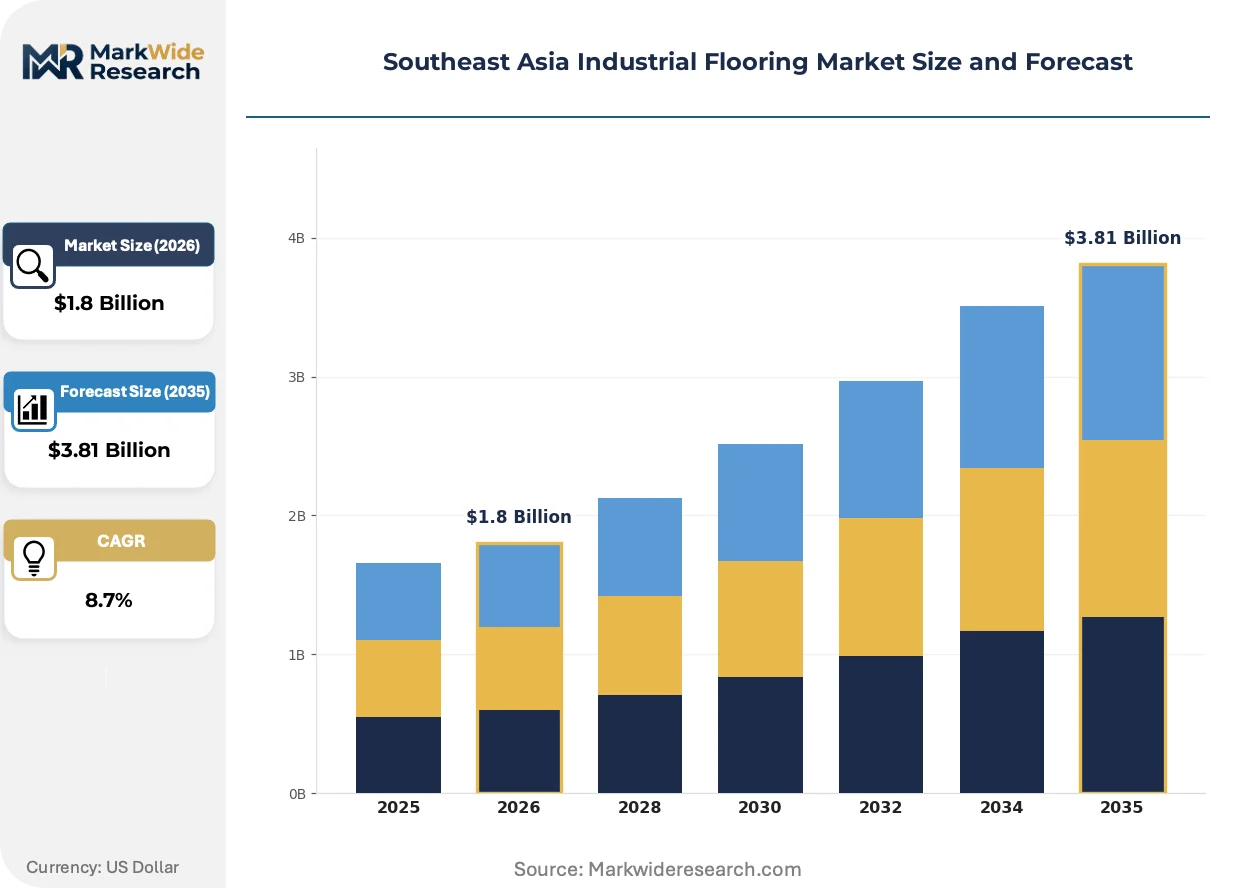
Market Dynamics
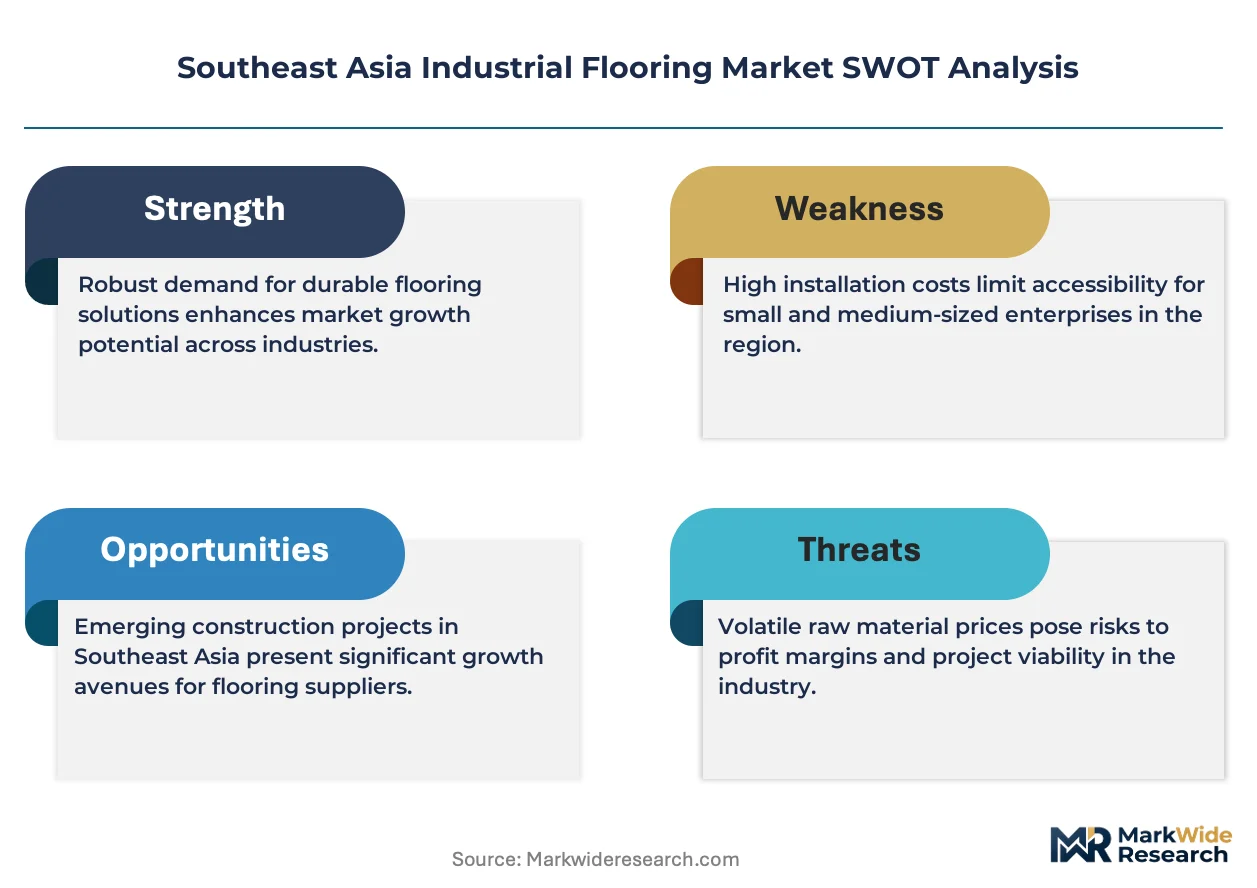
Resin-based flooring systems are displacing bare concrete specifications across Southeast Asian manufacturing and logistics facilities, driven by tightening occupational safety mandates and process-specific performance requirements from multinational anchor tenants.
Growth Catalysts
- Malaysia's Department of Occupational Safety and Health mandates:Anti-slip and chemical-resistant surface requirements in food processing zones accelerate polyurethane and epoxy system replacements of conventional concrete.
- Samsung Electronics supplier ecosystem:ESD-compliant and heavy-load-bearing floor specifications in Vietnam's northern manufacturing corridor create specification pull-through for resinous systems.
- Cold-storage infrastructure expansion:E-commerce fulfillment and perishable logistics operators across Indonesia, Malaysia, and Vietnam specify thermal-shock-resistant polyurethane formulations for blast freezer environments.
Market Restraints
- Petrochemical input volatility:Epoxy resin and isocyanate hardener prices fluctuate with regional refinery output, compressing applicator margins on fixed-price contracts.
- Import certification fragmentation:Vietnam's Ministry of Construction GB-influenced fire-resistance classifications create compliance barriers for uncertified imported systems from non-Chinese suppliers.
- Skilled applicator scarcity:Self-leveling and trowel-applied system installation requires certified technicians that concentrate in Thailand and Singapore, limiting project velocity in emerging Indonesian markets.
Strategic Opportunities
- Indonesia's battery materials sector:Emerging cathode and precursor manufacturing facilities require conductive, fire-resistant cementitious flooring systems with specialized installation protocols.
- Aftermarket service unbundling:Recoating, joint repair, and topcoat refresh cycles create recurring revenue streams separate from initial capital expenditure procurement channels.
- Singapore's pharmaceutical cleanroom specifications:Color-matching and contamination-control requirements drive premium system specifications that command pricing differentiation across regional projects.
Industry Challenges
- Certification timeline compression:Pre-qualification requirements for installation partners must complete ahead of capital expenditure cycles in fast-track battery and semiconductor facility projects.
- Substrate condition variability:Existing concrete slab quality across aging Southeast Asian industrial stock requires unpredictable remediation scope, complicating project bidding and margin forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Industrial Flooring Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Cementitious, Vinyl Application: Manufacturing, Warehousing, Food Processing, Pharmaceuticals Installation Method: Self-Leveling, Trowel Applied, Roll-On, Broadcast End User: Logistics, Healthcare, Automotive, Chemicals |
| Companies Covered | MBCC Group, Sherwin-Williams Company, Sika AG, BASF SE, Tremco Incorporated, RPM International Inc., Akzo Nobel N.V., 3M, Nippon Paint Holdings Co. Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Industrial Flooring Market Evolving Landscape
Material science advances and specification digitization are compressing traditional procurement cycles while elevating performance thresholds for thermal, chemical, and electrostatic properties across industrial flooring categories.
Polyurethane cement hybrid systems are collapsing the performance gap between epoxy coatings and thick cementitious screeds in thermal shock applications. Food processing operators in Malaysia and Thailand specify these formulations for blast freezer-to-ambient transitions that would fracture conventional epoxy. The technology is collapsing specification tiers that previously required separate material selections for temperature cycling zones.
Singapore's Building and Construction Authority surface safety standards and Thailand's Ministry of Industry emissions frameworks now require documented volatile organic compound content and slip-resistance testing for industrial tender qualification. These mandates compress the addressable market to pre-certified system portfolios. Pharmaceutical and electronics manufacturing segments respond by embedding compliance documentation into early-stage specification development rather than post-bid verification.
Facility operators increasingly unbundle installation from material supply and maintenance contracts, creating discrete procurement events for each project phase. General contractors in Vietnam's northern corridor now source resin systems separately from applicator labor, reversing traditional single-source contracting. This pattern concentrates in automotive and electronics verticals where multinational owners dictate vendor qualification lists independent of local construction procurement.
Southeast Asia Industrial Flooring Market Segmentation
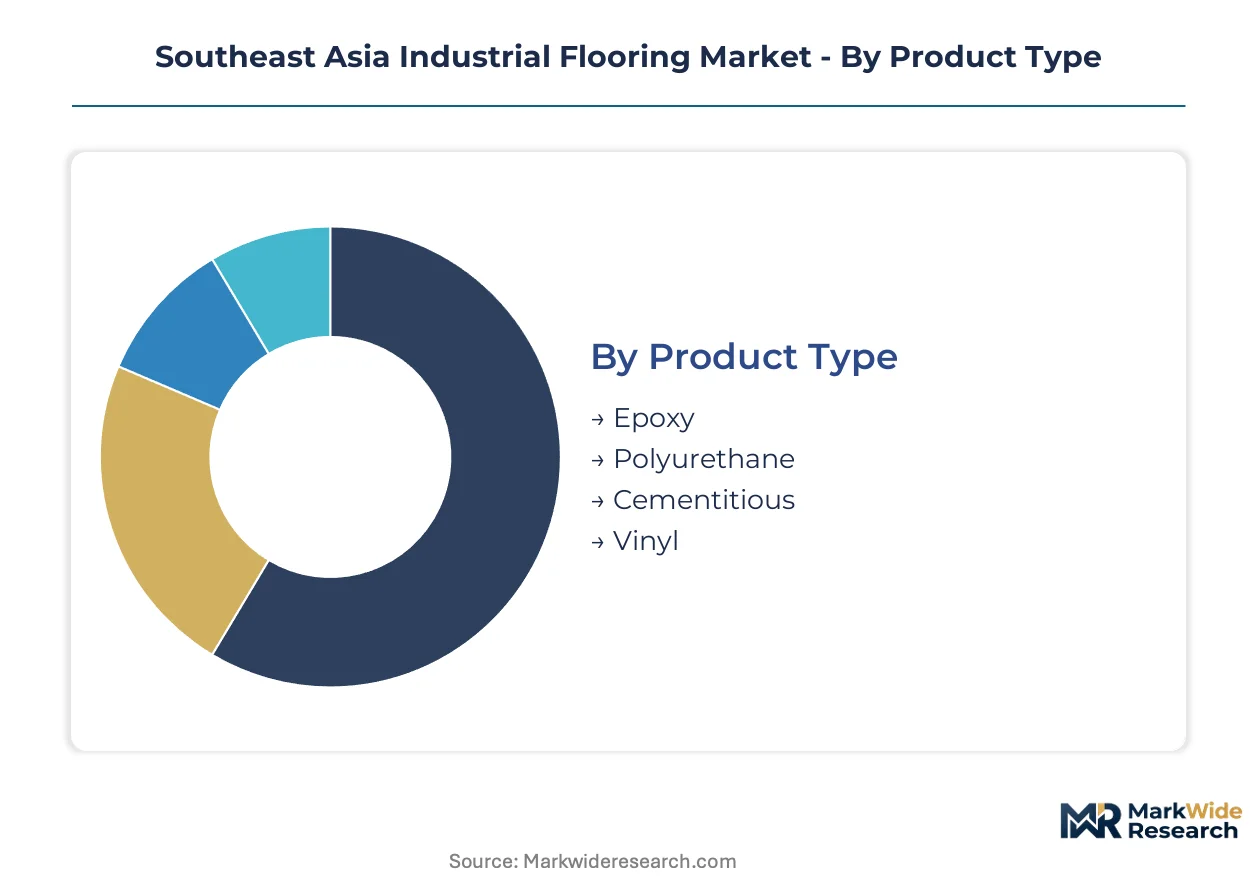
Resinous, cementitious, and polymer-modified systems serve distinct performance requirements across Southeast Asian manufacturing environments. Specification selection hinges on thermal cycling tolerance, chemical exposure profiles, and substrate conditions rather than cost alone.
Product Type:
Mature epoxy formulations dominate current specification volumes while polyurethane segments accelerate in thermal shock applications.
- Epoxy:Thermosetting polymer systems deliver chemical resistance and mechanical durability at competitive installed cost. Malaysian food processing operators specify these for ambient production zones under Department of Occupational Safety and Health mandates.
- Polyurethane:Elastomeric formulations absorb thermal expansion stresses that fracture rigid alternatives. Vietnam's northern manufacturing corridor specifies these for blast freezer transitions in Samsung Electronics supplier facilities.
- Cementitious:Magnesium oxychloride and calcium aluminate binders provide fire resistance and conductive properties for battery manufacturing.
- Vinyl:Homogeneous and heterogeneous sheet goods serve light-duty warehousing and cleanroom environments requiring rapid installation.
Epoxy handles the majority of throughput; polyurethane is the fastest mover on share.
Application:
End-use requirements stratify by load-bearing demands, hygiene protocols, and regulatory compliance intensity.
- Manufacturing:Heavy-duty screeds withstand forklift traffic and machinery vibration in automotive assembly plants. Thailand's Ministry of Industry emissions frameworks mandate low-VOC formulations for electronics manufacturing qualification.
- Warehousing:Thin-film coatings protect concrete substrates from abrasion in high-bay storage facilities. Indonesian e-commerce fulfillment operators specify these for rapid project turnover.
- Food Processing:Thermal shock-resistant systems bridge blast freezer and ambient zones. Singapore's Building and Construction Authority surface safety standards enforce slip-resistance testing for tender qualification.
- Pharmaceuticals:Seamless, coved installations enable contamination control in cleanroom environments. Color-matching requirements from Singapore laboratories drive premium specifications across regional projects.
Manufacturing absorbs the largest installed base; pharmaceuticals commands the steepest expansion trajectory.
Installation Method:
Project scale and precision requirements determine application technique selection.
- Self-Leveling:Fluid-applied systems create uniform surfaces across large-format warehousing footprints. These dominate Indonesian cold-storage infrastructure expansion where rapid coverage rates compress construction schedules.
- Trowel Applied:Hand-finished builds achieve precise gradient control for drainage and equipment leveling. Pharmaceutical cleanrooms in Singapore specify these for coved base integration and seamless wall transitions.
- Roll-On:Thin-film coatings apply efficiently over prepared substrates in light-duty manufacturing.
- Broadcast:Aggregate-embedded systems enhance slip resistance in wet-process chemical handling areas.
Self-leveling commands volume leadership; trowel applied captures premium pricing differentiation.
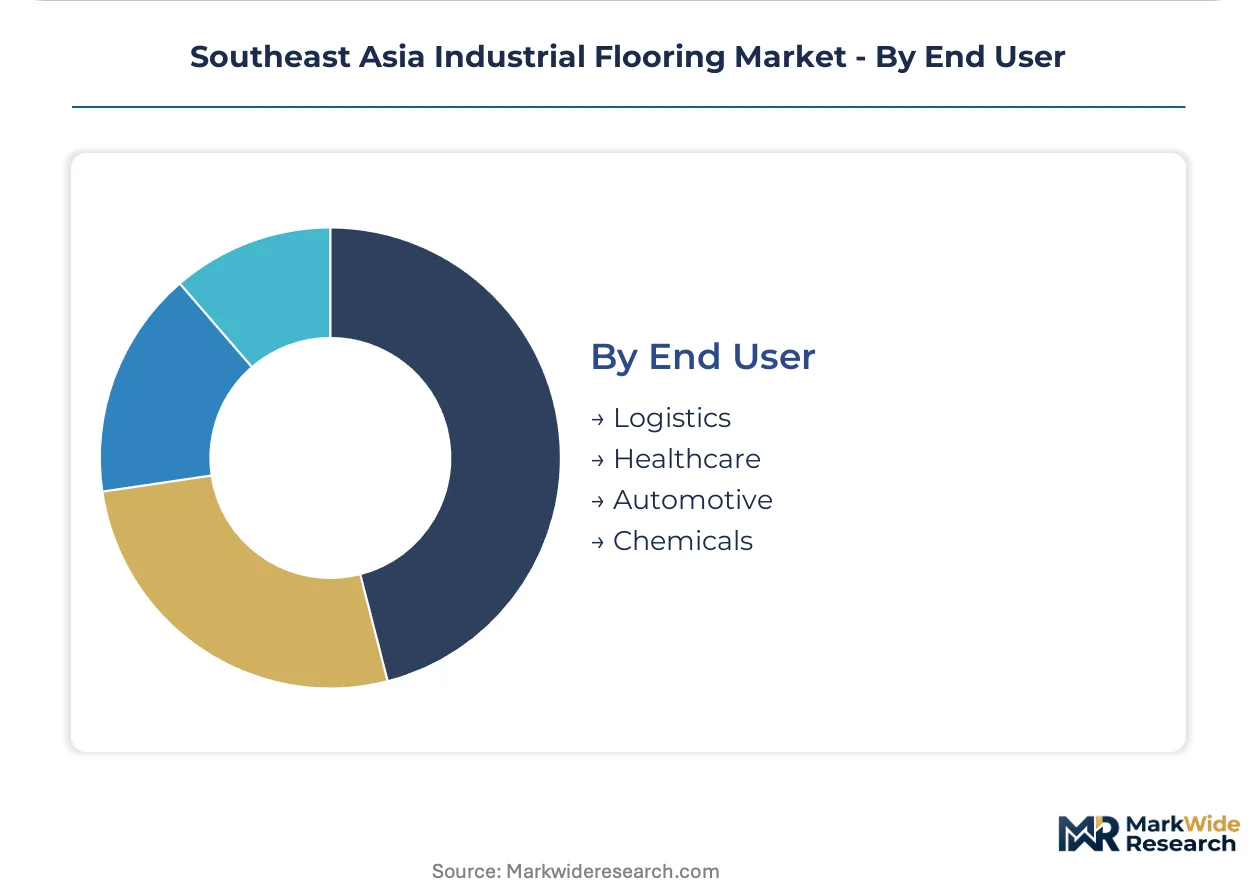
End User:
Vertical-specific performance standards drive specification divergence across procurement channels.
- Logistics:E-commerce fulfillment and cold-storage operators across Indonesia, Malaysia, and Vietnam specify thermal-shock-resistant polyurethane for perishable handling infrastructure.
- Healthcare:Infection control and seamless hygiene surfaces dominate hospital and laboratory specifications.
- Automotive:ESD-compliant and heavy-load-bearing floors protect sensitive electronics assembly in Vietnam's northern corridor supplier parks.
- Chemicals:Chemical-resistant epoxy and cementitious systems withstand aggressive spill exposure in process manufacturing.
Logistics drives the broadest geographic deployment; automotive concentrates specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian buyers exhibit the sharpest price elasticity, squeezing margins on commodity epoxy specifications, while Singaporean pharmaceutical operators absorb premium pricing for contamination-control compliance. Malaysia and Vietnam occupy intermediate positions where regulatory mandates override pure cost minimization. Thailand's automotive sector demonstrates demand inelasticity for certified applicator networks.
Indonesia
E-commerce fulfillment and battery materials plants drive specification upgrades from bare concrete to resin systems. The Ministry of Industry's emerging fire-resistance protocols for cathode manufacturing facilities create compliance pre-qualification requirements. Java-based cold-storage operators in Bekasi and Cikarang industrial corridors specify polyurethane formulations for rapid installation schedules.
Malaysia
Food processing zones and electronics manufacturing anchor demand for chemical-resistant and ESD-compliant surfaces. The Department of Occupational Safety and Health mandates anti-slip specifications that disqualify uncertified imported systems. Penang's Free Industrial Zone concentrates Samsung Electronics supplier facilities requiring heavy-load-bearing epoxy screeds.
Vietnam
Samsung Electronics supplier ecosystems and domestic automotive tier-1 plants pull through premium resin specifications. The Ministry of Construction's GB-influenced fire-resistance classifications erect barriers for non-Chinese imported systems. Bac Ninh and Thai Nguyen provinces in the northern manufacturing corridor concentrate blast freezer installations specifying thermal-shock-resistant polyurethane.
Singapore
Pharmaceutical cleanrooms and precision manufacturing command the region's steepest pricing premiums for seamless, coved installations. The Building and Construction Authority enforces surface safety standards requiring documented slip-resistance testing for tender qualification. Tuas Biomedical Park facilities drive color-matching specifications that propagate across regional projects.
Thailand
Automotive assembly plants and food processing operators sustain recurring maintenance contract volumes. The Ministry of Industry's emissions frameworks mandate low-VOC formulations for electronics manufacturing qualification. Rayong's Eastern Economic Corridor concentrates certified applicator networks serving Japanese-owned manufacturing facilities.
Southeast Asia Industrial Flooring Market Competitive Landscape
Integrated resin producers and specialized applicator networks split the market along the material-versus-service boundary. The structure concentrates around three strategic archetypes: captive resin manufacturers controlling hardener supply chains, certification-heavy applicator organizations locking in maintenance cycles, and regional coating specialists leveraging color-matching laboratories. Dominant competitive moves include backward integration into resin production and geographic expansion of certified installation partnerships.
Within the integrated-manufacturer tier, Sika AG and BASF SE exemplify archetypes anchored in captive supply control. Sika's certification network sustains recurring maintenance positions in automotive assembly environments. BASF's in-house hardener production for epoxy formulations secures margin capture upstream. Sherwin-Williams Company occupies a differentiated position through Singapore-based color-matching capabilities serving pharmaceutical specifications across regional deployment.
| Leading Market Players |
|---|
| MBCC Group |
| Sherwin-Williams Company |
| Sika AG |
| BASF SE |
| Tremco Incorporated |
| RPM International Inc. |
| Akzo Nobel N.V. |
| 3M |
| Nippon Paint Holdings Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Rayong's Eastern Economic Corridor concentrates certified applicator networks that serve Japanese-owned automotive assembly plants, creating localized pricing power for resin system installers while compressing margins on commodity epoxy specifications in price-elastic Indonesian markets. This geographic asymmetry in supply capability directly shapes three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Aftermarket service revenue from floor recoating, joint repair, and topcoat refresh cycles drives lifetime value across installation contracts. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with Singaporean pharmaceutical operators absorbing premium pricing for contamination-control compliance while Indonesian e-commerce fulfillment buyers squeeze commodity epoxy margins. Cost compression in standard-tier epoxy specifications is intensifying because petrochemical input volatility from regional refinery output fluctuations erodes applicator margins on fixed-price contracts. Logistics verticals demonstrate the sharpest price sensitivity, whereas automotive and semiconductor manufacturing segments exhibit demand inelasticity for certified applicator networks.
Supply Chain Analysis
Vietnam's Ministry of Construction GB-influenced fire-resistance classifications function as de facto export-control barriers limiting flows of uncertified imported systems from non-Chinese suppliers. Resin formulation supply draws from China, Germany, and Singapore for epoxy resin, isocyanate hardener, and specialty additive inputs. Single-source vulnerability concentrates in certified applicator networks tethered to Thailand and Singapore, constraining project velocity in emerging Indonesian battery materials markets. Distribution runs through applicator certification networks that lock in recurring maintenance contracts alongside initial material supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward general contractors and multinational facility operators who now unbundle installation from material supply, fragmenting procurement channels that previously favored single-source contracting. This consolidation of specification authority among anchor tenants in Vietnam's northern manufacturing corridor and Indonesia's emerging battery sector reshapes vendor qualification requirements.
For Market Incumbents: Pre-empt specification displacement by embedding compliance documentation into early-stage pharmaceutical and electronics tender development before post-bid verification windows close. Anchor captive resin supply through backward integration into hardener production or long-term offtake agreements with regional petrochemical refineries to defend against margin compression from input volatility. Certification investment in Vietnam's GB-influenced fire-resistance classifications creates switching costs for multinational anchor tenants in battery and semiconductor facilities.
For New Entrants and Emerging Players: Build out certified applicator partnerships in Indonesia's emerging cathode and precursor manufacturing corridors where conductive cementitious flooring demand outpaces qualified installation capacity. Target aftermarket service unbundling in Thailand's automotive assembly maintenance cycles, where recurring recoating and joint repair contracts separate from initial capital expenditure procurement. A go-to-market angle through Singapore-based color-matching laboratories serves pharmaceutical cleanroom specifications that propagate across regional deployment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among applicator certification networks that sustain maintenance contracts in automotive and food processing verticals. Long-term viability over a five-to-ten year horizon favors integrated resin producers controlling hardener supply chains and captive formulation capacity. Acquisition target archetypes include regional coating specialists with Singapore-based technical laboratories or Indonesian applicator networks pre-qualified for battery materials sector certification. The signal to watch is Ministry of Industry fire-resistance protocol adoption timelines in Indonesia's cathode manufacturing zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Applicator Network Expansion | Locks in recurring maintenance contracts in Thailand's automotive assembly plants. |
| Backward Integration into Hardener Production | Secures margin capture upstream from epoxy resin formulation supply. |
| Color-Matching Laboratory Investment | Captures pharmaceutical cleanroom specifications propagating from Singapore. |
| GB-Influenced Fire-Resistance Certification | Creates compliance barriers protecting market position in Vietnam. |
| Aftermarket Service Unbundling | Separates recoating and joint repair revenue from initial installation procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors at automotive and electronics facilities, procurement leads at general contractors, resin formulation technical directors, and certified applicator network managers. Secondary validation drew from Building and Construction Authority tender documentation, Ministry of Industry emissions framework filings, customs and trade data on resin imports, and SEC disclosures from integrated coating manufacturers. Bottom-up project pipeline tracking across Indonesia, Malaysia, Vietnam, Singapore, and Thailand was triangulated against top-down market sizing from construction expenditure databases.
Calibration anchored volume and value outputs to observed specification rates in Samsung Electronics supplier facilities, cold-storage infrastructure buildouts, and pharmaceutical cleanroom deployments across the analysis window. Segmentation dimensions modeled include resin type, installation method, end-use vertical, and geographic regulatory cluster. CAGRs were derived from fitted growth curves against historical project completion data. Industry-specific forecast inputs incorporated Ministry of Construction certification timeline assumptions and petrochemical input price trajectory scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese resin producers or accelerated applicator certification programs by new entrants would shift outcomes. Material shifts in Indonesia's battery materials sector fire-resistance protocol adoption or Vietnam's GB-influenced import certification enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Industrial Films Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Welding Consumables Market