
 Gaskets and Seals Market | 2026-2036
Gaskets and Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Gaskets and Seals Market Intelligence
A demand shift toward Aftermarket Suppliers from traditional OEM channels is redrawing the competitive landscape for gaskets and seals. Freudenberg Sealing Technologies leverages its extensive material science expertise to serve both segments effectively. Parker Hannifin Corporation sustains its market position through a vast distribution network catering to maintenance, repair, and operations needs. Meanwhile, Trelleborg AB specializes in engineered polymer solutions for demanding industrial applications.
Gaskets and seals are mechanical components designed to prevent leakage between two or more mating surfaces under compression. They function by creating a static or dynamic barrier, critical for maintaining pressure, preventing contamination, and ensuring operational integrity in equipment. While standard Nitrile Rubber and EPDM materials command significant volume, high-performance materials like PTFE and fluoroelastomers offer superior margin opportunities. The mature power plant application segment contrasts with the expanding requirements of the chemical processing and marine industries.
Material selection and product design are heavily influenced by environmental and safety regulations. Compliance with frameworks such as the EU's REACH directive, emissions standards from the US EPA, and China's GB standards for industrial products governs market access. Navigating the complex interplay between material innovation and evolving international environmental mandates will determine long-term vendor success.
Market Dynamics
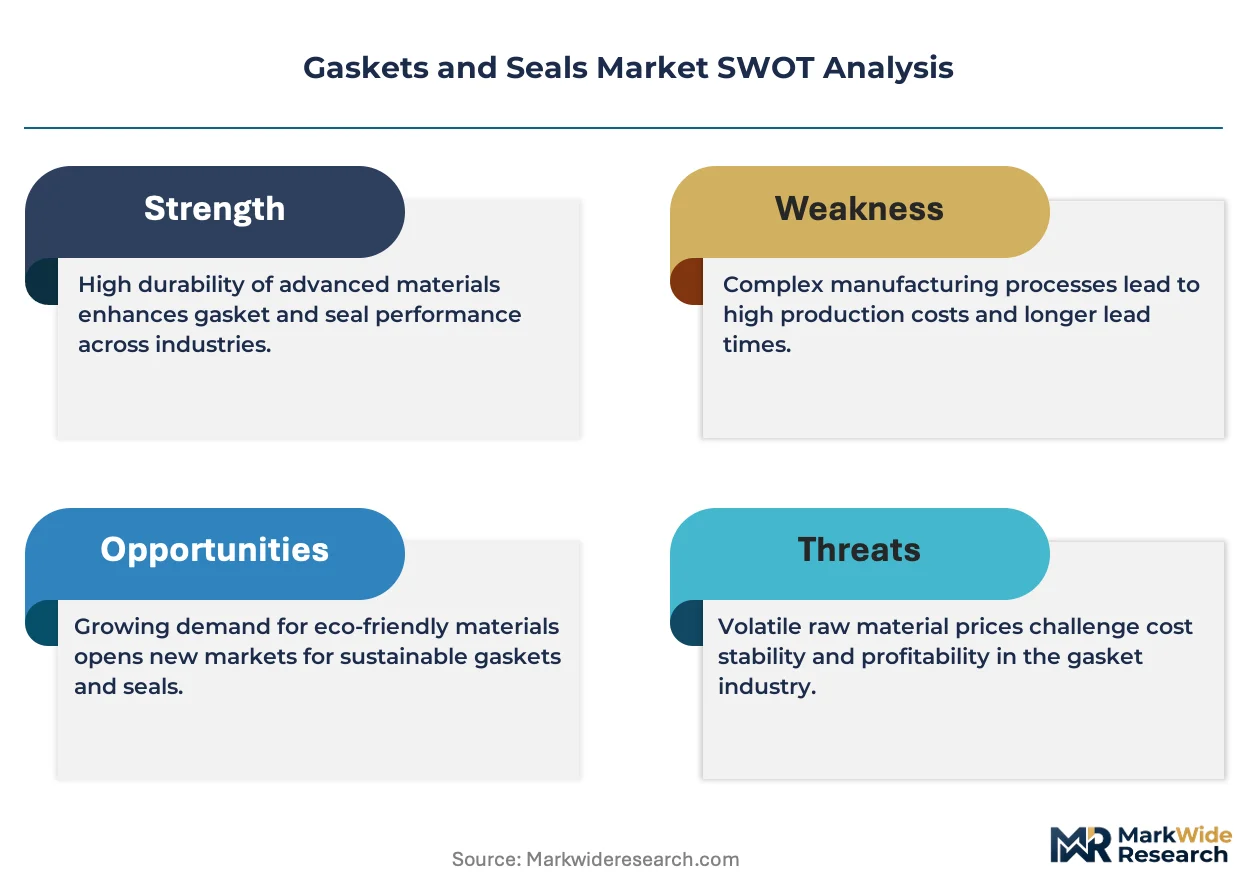
The market's evolution is shaped by dual pressures: stringent environmental regulations like the EU's REACH directive and escalating performance demands from heavy industries. This dynamic forces innovation in polymer science to meet compliance without sacrificing operational integrity in critical applications.
Growth Catalysts
- Stringent Emissions Standards:Regulations from the US EPA and China's MEE mandate lower fugitive emissions from industrial facilities, compelling the adoption of high-integrity gaskets and seals in chemical processing and oil and gas sectors.
- Marine Industry Expansion:Increased shipbuilding and retrofitting activities, particularly for vessels using alternative fuels like LNG, require specialized sealing solutions capable of handling cryogenic temperatures and higher pressures, driving demand for advanced material-based products.
- Advanced Fluoroelastomers:The development of new-generation fluoroelastomer compounds provides superior chemical and thermal resistance, opening applications in aggressive chemical manufacturing environments and high-temperature automotive systems previously limited by material performance.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of key raw materials, particularly fluoropolymers and specialty elastomers derived from petrochemical feedstocks, create margin pressure and complicate long-term pricing strategies for manufacturers.
- Substitution by Formed-in-Place Gaskets:The adoption of liquid, formed-in-place (FIP) sealants in automated assembly lines, especially within the automotive and electronics industries, presents a substitution threat to traditional pre-cut mechanical gaskets.
- Complex Regulatory Compliance:Navigating the fragmented and evolving landscape of material regulations, such as the EU's REACH and China's GB standards, increases compliance costs and can delay market entry for new products.
Strategic Opportunities
- Hydrogen Economy Infrastructure:The build-out of hydrogen production, storage, and transport infrastructure creates a significant opportunity for specialized seals designed to handle the challenges of hydrogen embrittlement and high-pressure containment.
- Digital Aftermarket Platforms:Developing e-commerce platforms and digital catalogs for maintenance, repair, and operations (MRO) customers can capture the growing aftermarket segment by simplifying procurement and improving access to technical specifications.
- Water Treatment Modernization:Upgrades to aging water and wastewater treatment facilities in markets like India and Brazil require durable, chemically resistant seals, creating an opportunity for products compliant with local water quality standards.
Industry Challenges
- Application Engineering Talent Scarcity:A shortage of application engineers with deep expertise in both material science and specific end-use industry requirements hinders the development and deployment of custom, high-performance sealing solutions for clients.
- Managing High-Mix, Low-Volume Production:The demand for customized gasket and seal designs for niche applications creates significant operational complexity in production scheduling, inventory management, and maintaining cost-efficiency across a vast portfolio of SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaskets and Seals Market |
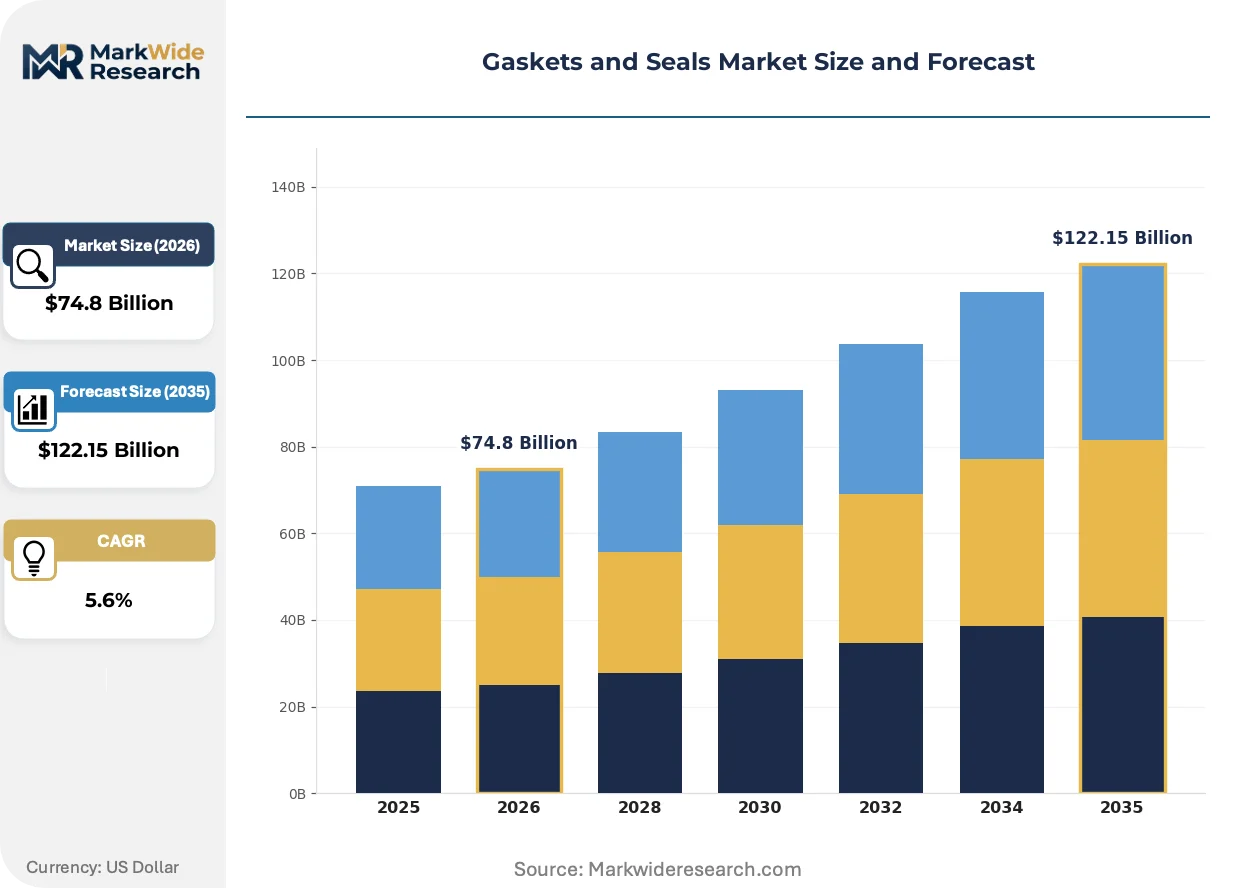
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $122.15 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiral Wound, Ring, Self-Adhesive, Die-Cut, Compression, Foam Material: Nitrile Rubber, Silicone, PTFE, Neoprene, EPDM, Fluoroelastomer Application: Oil & Gas, Power Plants, Chemical Processing, HVAC Systems, Water Treatment, Marine End User: OEMs, Aftermarket Suppliers, Industrial Manufacturers, Equipment Fabricators |
| Companies Covered | Dana Incorporated, Garlock Sealing Technologies, Freudenberg Sealing Technologies, Flowserve Corporation, ElringKlinger AG, Trelleborg AB, SKF, John Crane, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaskets and Seals Market Strategic Shifts & Innovations
Material science advancements and the digitalization of industrial maintenance are transforming gaskets and seals from simple components into engineered systems. This evolution prioritizes long-term reliability and data-driven performance over initial component cost.
Smart seals integrating embedded sensors represent a significant product evolution, providing real-time data on pressure, temperature, and wear. High-value sectors like aerospace and chemical processing are adopting this technology for critical, hard-to-access joints. This capability is displacing reactive and scheduled maintenance protocols with predictive, condition-based asset management strategies, reducing unplanned downtime.
The European Union's F-Gas Regulation, aimed at phasing down fluorinated greenhouse gases, is creating significant material formulation challenges. It restricts the use of specific high-GWP fluids and precursor chemicals integral to some fluoroelastomer production processes. Consequently, manufacturers serving the HVAC and refrigeration sectors are compelled to accelerate development of sealing solutions compatible with new low-GWP refrigerants and HFO-based materials.
A notable demand-side shift involves industrial buyers increasingly sourcing MRO components through multi-brand distributors rather than captive OEM channels. This pattern favors suppliers who offer extensive product catalogs, cross-referencing capabilities, and rapid fulfillment. The trend is highly visible within the commercial vehicle repair and general industrial maintenance segments across Europe and North America.
Gaskets and Seals Market Segmentation
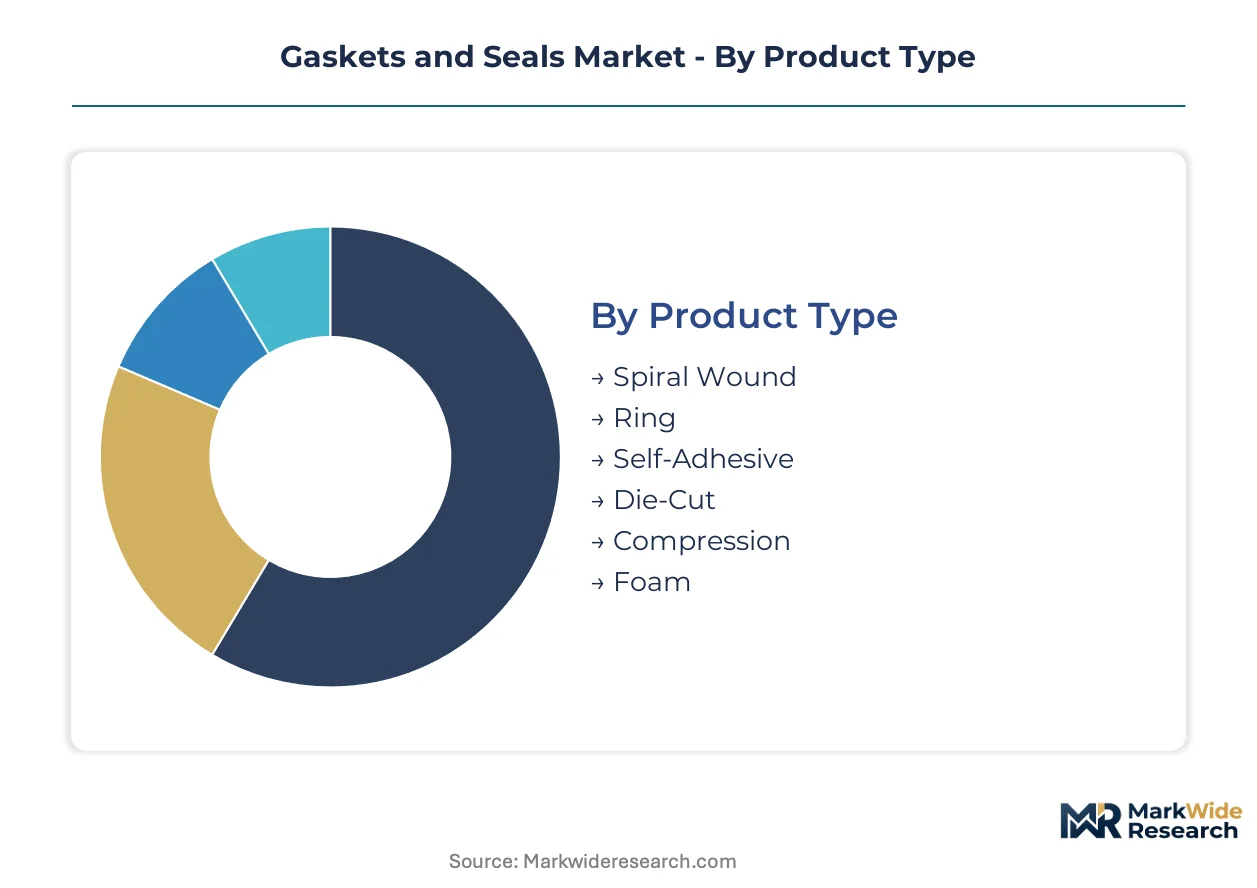
The Gaskets and Seals market is highly diversified, with segmentation providing a granular view of demand drivers and competitive dynamics. Understanding these distinct segments allows manufacturers to tailor product development, material science investments, and distribution strategies effectively. This detailed analysis highlights areas of concentrated demand and emerging opportunities across the value chain.
Product Type:
Regulatory mandates for fugitive emissions in chemical processing differentiate product type demand, influencing material choices and design specifications across industrial applications.
- Spiral Wound:These components feature alternating layers of metal and soft filler material, providing robust sealing under fluctuating temperatures and pressures. Demand concentrates in the oil and gas sector, particularly for high-pressure valve and flange applications, driven by stringent safety standards.
- Die-Cut:These gaskets are precisely cut from sheet materials like rubber or fiber, offering cost-effective and versatile sealing solutions. Demand concentrates in general industrial manufacturing across Germany and China, supporting assembly lines requiring consistent, standardized components.
- Ring:Solid or hollow rings of various materials, often used in pipeline flanges and pressure vessels for reliable static sealing.
- Self-Adhesive:These gaskets feature an adhesive backing for easy installation, commonly found in electronics and HVAC systems.
- Compression:Designed to be compressed between two surfaces, these seals prevent leakage in less dynamic applications.
- Foam:Lightweight and flexible, foam gaskets provide dust and moisture sealing in enclosures and automotive applications.
Established volume favors Die-Cut gaskets; emerging adoption favors Spiral Wound for high-performance applications.
Material:
Diverse application demands dictate material selection for gaskets and seals, from general industrial uses to highly corrosive environments.
- Fluoroelastomer:These high-performance polymers offer superior chemical and thermal resistance, critical in aggressive chemical processing and high-temperature automotive systems. Demand concentrates in industries requiring compliance with stringent emissions standards, such as those from the US EPA.
- PTFE:Polytetrafluoroethylene provides excellent chemical inertness and low friction, suitable for pharmaceutical and food processing equipment. Demand concentrates in sectors with strict hygiene and non-contaminating requirements, including those adhering to EU food contact regulations.
- Nitrile Rubber:Common for oil and fuel resistance, Nitrile Rubber finds extensive use in automotive and hydraulic systems.
- Silicone:Known for extreme temperature resistance and flexibility, Silicone is preferred in medical devices and high-temperature sealing.
- Neoprene:This synthetic rubber offers good weather and ozone resistance, often used in outdoor and marine applications.
- EPDM:Ethylene Propylene Diene Monomer provides excellent resistance to weathering and steam, suitable for HVAC and water treatment.
Cost-effectiveness drives volume in Nitrile Rubber; specialized performance drives value in Fluoroelastomer and PTFE.
Application:
Maintaining operational integrity and preventing leakage across various industrial settings defines the segmentation by application.
- Chemical Processing:This segment demands seals resistant to a wide array of corrosive chemicals and extreme temperatures, crucial for plant safety and efficiency. Demand concentrates in industrial manufacturing centers like China and Germany, driven by continuous production and strict environmental regulations.
- Marine:Seals for marine applications must withstand saltwater corrosion, varied temperatures, and high pressures, particularly in shipbuilding and retrofitting. Demand concentrates in new vessel construction, especially those using alternative fuels like LNG, requiring specialized cryogenic sealing solutions.
- Oil & Gas:High-pressure and high-temperature environments in exploration and refining require robust, reliable sealing components.
- Power Plants:Critical for steam turbines and cooling systems, seals in power plants must endure high heat and pressure.
- HVAC Systems:These systems require seals for air ducts and fluid lines, focusing on energy efficiency and leak prevention.
- Water Treatment:Durable, chemically resistant seals are essential for pumps and pipes in municipal water and wastewater facilities.
High-risk environments drive innovation in Chemical Processing; infrastructure modernization expands opportunities in Water Treatment.
End User:
Distinct procurement patterns and service requirements characterize the end-user segments within the gaskets and seals market.
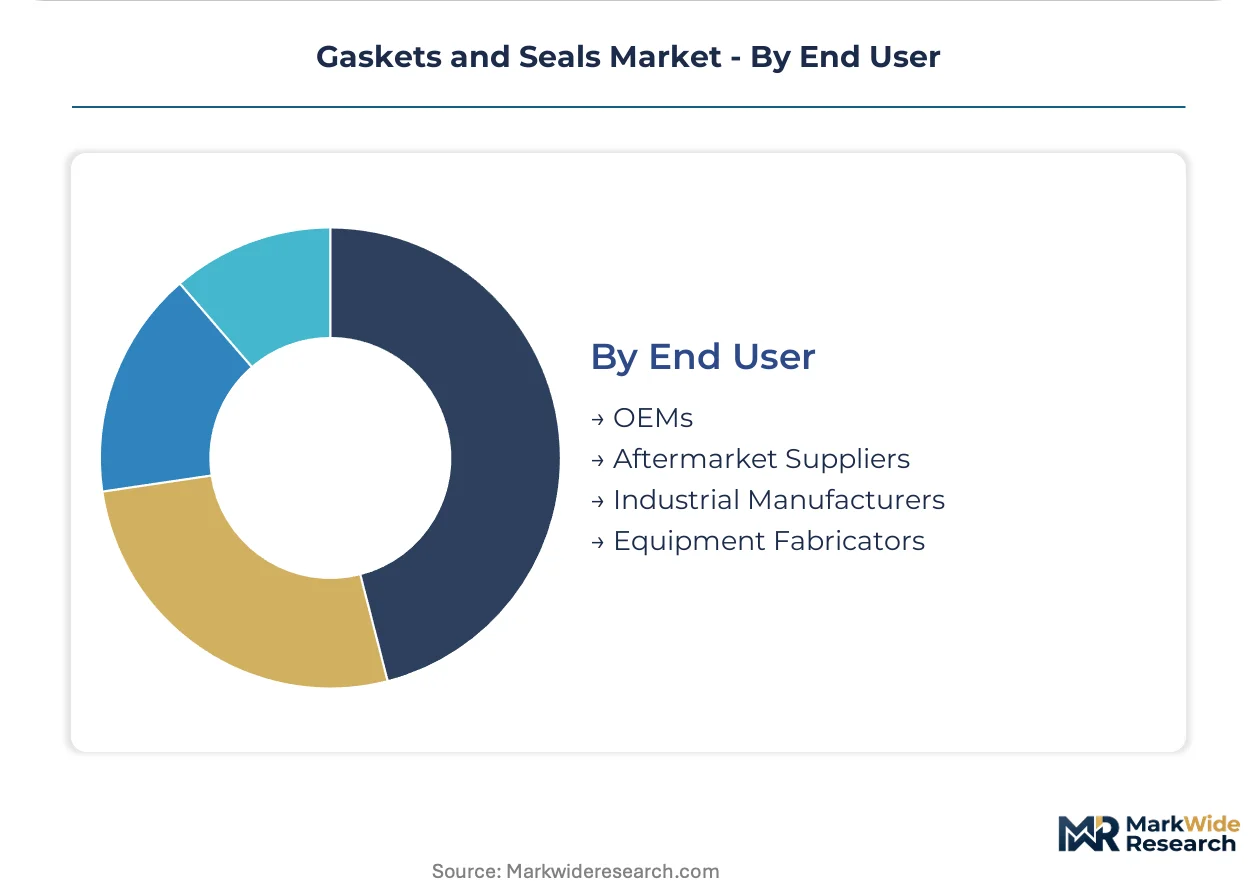
- Aftermarket Suppliers:These entities provide replacement parts and MRO solutions, catering to ongoing maintenance and repair needs. Demand concentrates in regions with extensive industrial infrastructure like Europe and North America, driven by the need for rapid fulfillment and diverse product catalogs.
- OEMs:Original Equipment Manufacturers integrate gaskets and seals into new machinery and systems during the initial assembly phase. Demand is heavily influenced by new equipment sales cycles across various industries, requiring custom-engineered solutions and reliable supply chains.
- Industrial Manufacturers:These users directly integrate seals into their production processes and machinery for operational continuity.
- Equipment Fabricators:Companies that build specialized equipment require seals tailored to their unique design and performance specifications.
Volume procurement defines OEMs; specialized support differentiates Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipments of specialized sealing components from industrial manufacturing hubs like Germany to Asian markets are influencing regional demand dynamics. The global gaskets and seals market is shaped by diverse industrial activity and evolving regulatory environments. Key countries are driving innovation and adoption across various application segments.
China
China's robust chemical processing and general industrial manufacturing sectors drive significant demand for high-performance seals. The country's MEE (Ministry of Ecology and Environment) emissions standards compel industries to adopt advanced sealing solutions. Industrial clusters in the Yangtze River Delta, particularly around Shanghai, are centers for both demand and production of these components.
Germany
Germany's advanced automotive and chemical industries necessitate precision-engineered gaskets and seals. Compliance with the EU's REACH directive and F-Gas Regulation influences material selection and product development. The North Rhine-Westphalia region, with its dense concentration of heavy industries, remains a crucial hub for sealing technology innovation.
United States
The United States sees strong demand from its oil & gas and chemical processing sectors, alongside a substantial aftermarket for MRO parts. US EPA emissions standards mandate reliable sealing to prevent fugitive emissions in industrial facilities. The Gulf Coast region, encompassing Texas and Louisiana, represents a significant market for specialized gaskets and seals in petrochemical operations.
India
India's expanding industrial base and infrastructure modernization projects, particularly in water treatment, fuel demand for durable seals. The BIS (Bureau of Indian Standards) sets quality benchmarks for industrial products, guiding material specifications. Maharashtra, with its diverse manufacturing base and ongoing urban development, is a growing market for sealing solutions.
South Korea
South Korea's dominant shipbuilding industry, especially in LNG carrier construction, requires advanced cryogenic and high-pressure sealing solutions. Local environmental protection acts and international maritime regulations influence product design for marine applications. The Busan-Ulsan region anchors the country's heavy industry and marine manufacturing, creating concentrated demand for specialized seals.
Gaskets and Seals Market Key Industry Players
Player mix skews toward a blend of large diversified industrial conglomerates and specialized material science firms. The market structure features both global players with extensive product portfolios and niche providers focusing on high-performance applications. Strategic partnerships for technology development and geographic expansion into emerging industrial markets represent common competitive moves among market participants.
Diversified industrial conglomerates like Parker Hannifin Corporation leverage vast distribution networks to serve maintenance, repair, and operations (MRO) needs across numerous industries. Specialists in engineered polymer solutions, such as Trelleborg AB, focus on demanding industrial applications requiring superior material properties. Freudenberg Sealing Technologies occupies a position characterized by extensive material science expertise, serving both OEM and aftermarket segments effectively.
| Leading Market Players |
|---|
| Dana Incorporated |
| Garlock Sealing Technologies |
| Freudenberg Sealing Technologies |
| Flowserve Corporation |
| ElringKlinger AG |
| Trelleborg AB |
| SKF |
| John Crane |
| Parker Hannifin Corporation |
| Others |
Cost & Logistics Intelligence
Rapid fulfillment lead times for aftermarket components directly influence inventory strategies across the gaskets and seals value chain. This dynamic shapes pricing power, particularly for suppliers managing diverse material portfolios and extensive distribution networks.
Pricing Analysis
Next-generation smart seals command premium pricing due to integrated sensor technology and predictive maintenance capabilities. The market operates on a hybrid model, blending contract-based OEM agreements with transactional aftermarket sales and value-based pricing for specialized high-performance materials. Price differentiation stems from material performance and compliance with stringent environmental regulations like the EU's REACH directive. Pricing softness runs through standard Nitrile Rubber products due to raw material price volatility, making general industrial manufacturers highly price-sensitive compared to chemical processing buyers.
Supply Chain Analysis
Inventory optimization remains a critical challenge for manufacturers facing high-mix, low-volume production across the gaskets and seals market. Geographic supply concentration for finished goods centers on industrial hubs in Germany and China, while raw material inputs like fluoropolymers and specialty elastomers originate globally. Commodity price volatility for petrochemical feedstocks presents a significant structural risk. Downstream distribution primarily occurs through multi-brand distributors for aftermarket sales and direct channels for original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense as incumbents navigate the increasing adoption of formed-in-place gaskets. Manufacturers must protect their traditional pre-cut mechanical gasket segments from this liquid sealant alternative.
For Market Incumbents: Compound investments in advanced material science R&D to counter the threat of formed-in-place gasket adoption. Deepen vertical integration into critical fluoropolymer production to mitigate raw material price volatility. Strengthen aftermarket distribution networks through digital platforms to maintain customer loyalty against emerging MRO channels. Prioritize compliance expertise for evolving regulations like the EU's F-Gas Regulation.
For New Entrants and Emerging Players: Specialized application engineering support represents a significant service-layer gap where incumbents under-serve. Target niche high-performance segments such as hydrogen economy infrastructure or advanced marine cryogenic sealing solutions. The water treatment modernization segment in India offers a penetrable entry point for durable, chemically resistant seals. Leverage certification expertise to differentiate products compliant with local water quality standards.
For Investors and Strategic Acquirers: Long-term, this sits as a resilient industrial component play because gaskets and seals are critical for operational integrity across heavy industries. Target vertically integrated mid-cap specialists with strong intellectual property in advanced fluoroelastomers or PTFE materials. Acquisition archetypes include firms possessing deep application engineering talent for niche high-pressure or cryogenic applications. The signal to watch is the accelerated build-out of hydrogen production and transport infrastructure, indicating new high-value seal demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Fluoroelastomers | Addresses growing demand from chemical processing industries for high-performance sealing solutions. |
| Joint Venture for Digital Aftermarket Platforms | Captures the expanding MRO segment by simplifying procurement for industrial buyers. |
| R&D Investment in Smart Seals | Shifts maintenance protocols to predictive, condition-based strategies, reducing unplanned downtime. |
| Acquisition of Cryogenic Sealing Specialist | Penetrates the advanced LNG marine market requiring specialized high-pressure containment. |
| Green Manufacturing Transition | Ensures compliance with stringent regulations like the EU's REACH directive for market access. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry association reports. This study integrated insights from interviews with plant managers, OEM procurement leads, material scientists, and aftermarket MRO buyers. The approach employed both bottom-up market sizing and top-down validation to ensure data integrity. Triangulation across diverse sources informed the market landscape.
Product Type, Material, Application, End User, and regional regulatory compliance defined the segmentation dimensions modeled across the analysis window. Compound Annual Growth Rates were derived from historical trends and future demand projections. The analytical framework integrated macroeconomic indicators with industry-specific growth catalysts. Industrial output growth and the increasing stringency of emissions regulations served as key forecast inputs.
Forecasts assume regulatory continuity in EU, US, and China; material policy shifts would require re-modeling. Unforeseen raw material supply disruptions or accelerated technological substitution represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Investment Casting Market
Industrial Materials
Metal Molds Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Fly Ash Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Metal Stamping Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Steel Processing Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Tension Spring Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Petrochemical Fasteners Market