
 Wood Protein Market | 2026-2036
Wood Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Protein Market Analytics
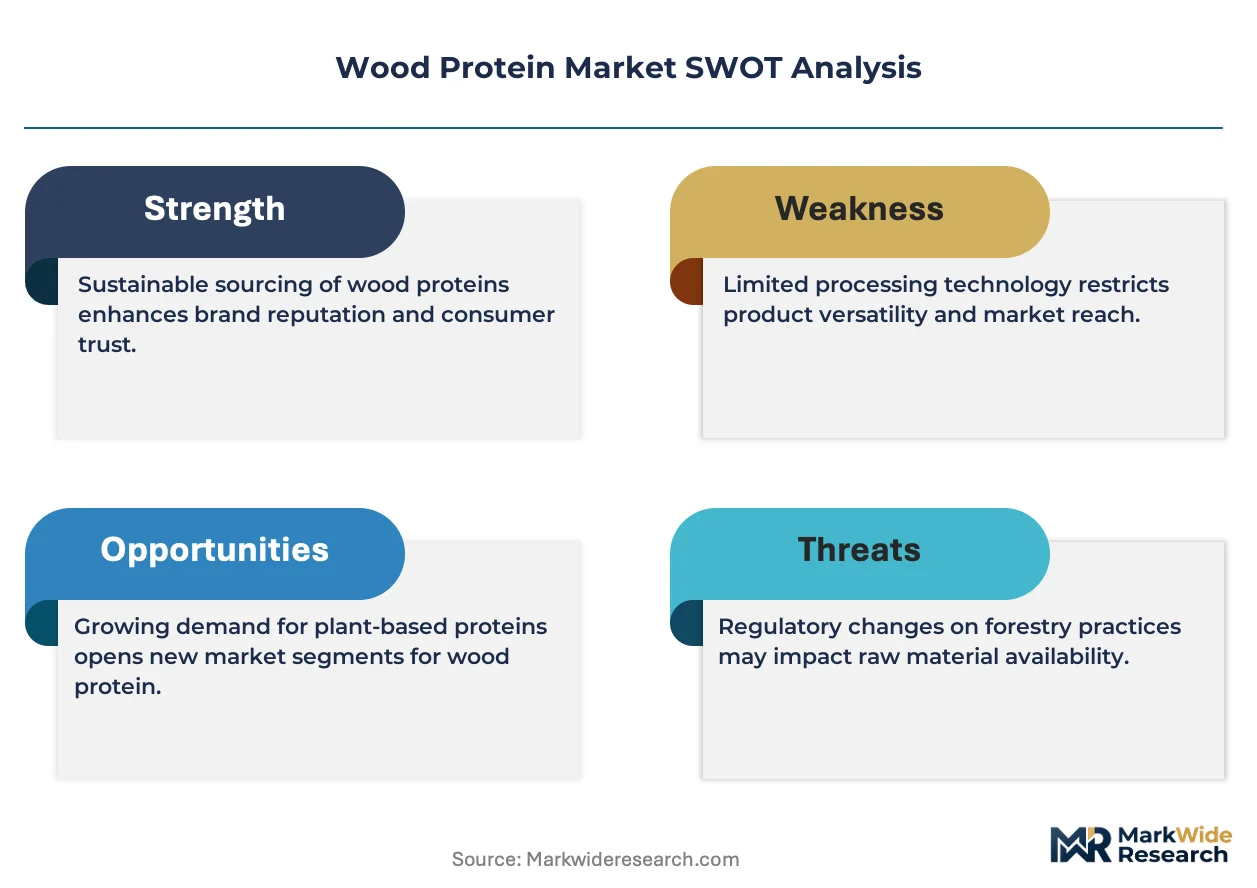
Finnish biorefinery operators is hardening the upstream supply base for wood-derived protein fractions. Weyerhaeuser leverages its Pacific Northwest timber holdings to secure consistent feedstock flows for protein extraction partners. Stora Enso anchors its position through integrated pulp-to-protein pilot lines at its Sunila facility. Arbiom Corporation differentiates via enzymatic hydrolysis platforms that yield higher amino acid completeness than conventional mechanical separation.
Wood protein denotes proteinaceous compounds extracted from lignocellulosic biomass, typically comprising 1-7% crude protein by dry weight depending on species and extraction method, with alkaline or enzymatic processing used to isolate functional fractions for industrial use. Protein extracts command premium positioning in nutraceutical formulations due to superior digestibility scores versus whole wood meal, while bioplastics applications sustain faster volume growth as brand owners seek non-food-competing feedstocks. The powder form dominates current commercial transactions, though liquid concentrates are gaining traction in adhesive formulations where uniform dispersion reduces curing variability.
EMA novel food approval pathways govern wood protein entry into European nutraceutical applications, while EPA biomass boiler emissions standards indirectly shape feedstock availability through co-location economics. The EU Green Deal sustainability certification requirements are forcing traceability investments back to forest management units. Stakeholders must monitor evolving ISO standards for alternative protein labeling claims that could either accelerate or constrain consumer acceptance trajectories.
Market Dynamics
The EU Green Deal's biomass sustainability criteria are forcing traceability investments back to forest management units, while enzymatic hydrolysis platforms compress extraction costs and unlock food-grade applications previously blocked by amino acid incompleteness.
Growth Catalysts
- EMA novel food approval frameworks:Clearer regulatory pathways in Europe accelerate nutraceutical applications, reducing time-to-market for wood-derived protein isolates in functional foods and dietary supplements.
- Bioplastics feedstock substitution:Brand owners facing Scope 3 emissions targets actively source non-food-competing proteins for polymer formulations, diverting demand from soy and pea isolates.
- German industrial biotech corridor:Concentrated pilot infrastructure around Leipzig and Hamburg creates cluster economies that lower scale-up risks for extraction technology providers.
Market Restraints
- Feedstock concentration risk:Softwood supply chains concentrate in Nordic and Pacific Northwest timber basins, exposing processors to pulp market competition and seasonal harvesting constraints.
- Protein recovery yield ceilings:Current enzymatic methods achieve 40-60% extraction efficiency from lignocellulosic matrices, leaving substantial value unrecovered versus oilseed processing economics.
- ISO alternative protein labeling uncertainty:Pending international standards for novel protein claims create compliance ambiguity that delays consumer-facing product launches.
Strategic Opportunities
- Underpenetrated Asian nutraceutical markets:Japan's PMDA and South Korea's MFDS are establishing novel food review frameworks that will open regulatory pathways for wood protein entrants.
- Adhesive liquid concentrate formats:Uniform dispersion properties in wood protein hydrolysates address curing variability in industrial bonding applications, displacing formaldehyde-based resins.
- EU Green Deal certification premiums:Third-party verified sustainable forest management credentials command price premiums in European procurement specifications.
Industry Challenges
- Bioprocess engineering talent scarcity:Specialized expertise in lignocellulose fractionation and protein purification concentrates in Nordic academic institutions, creating recruitment bottlenecks for scale-up facilities.
- Co-location capex requirements:Economical wood protein production requires integrated biorefinery infrastructure with shared utilities, demanding capital commitments exceeding standalone extraction plant economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Protein Market |
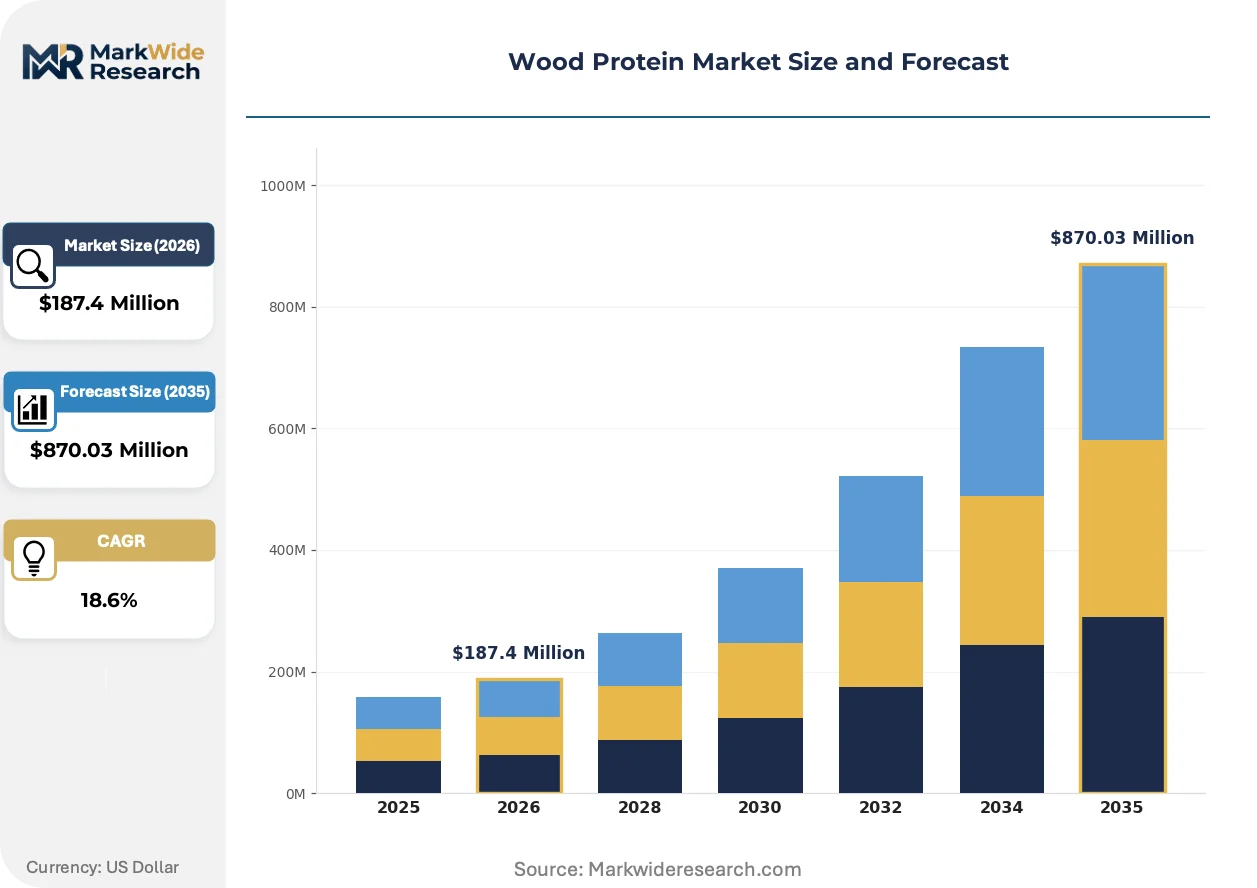
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Meal, Wood Flour, Protein Extracts, Wood Chips Application: Animal Feed, Bioplastics, Nutraceuticals, Adhesives End Use: Food Industry, Construction, Pharmaceutical, Chemical Form: Powder, Granules, Pellets, Liquid |
| Companies Covered | Arbiom Corporation, Cargill Incorporated, Corbion, Danone Limited, Glanbia, Kerry Group, Wilmar International, Weyerhaeuser, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Protein Market Evolving Landscape
Enzymatic hydrolysis platforms are compressing extraction costs while regulatory tailwinds in Europe and Asia-Pacific create parallel commercialization tracks for food-grade and industrial applications.
Enzymatic hydrolysis platforms using tailored cellulase and protease cocktails are isolating functional protein fractions from softwood biomass with superior amino acid profiles versus mechanical separation. Food manufacturers in Germany and Finland are piloting these isolates at commercial scale for plant-based meat extenders. The technology is absorbing premium positioning in nutraceutical formulations by delivering digestibility scores that justify ingredient cost premiums over commodity plant proteins.
REACH registration requirements for novel biomass-derived substances are tightening purity and toxicology documentation standards for wood protein entrants to European industrial markets. Bioplastics compounders must now demonstrate full substance characterization to maintain polymer import authorization. This regulatory compression most affects adhesive and composite applications where wood protein hydrolysates substitute for petroleum-based binders, forcing reformulation investments.
Certification-driven procurement specifications are displacing price-only sourcing in European food and materials sectors. Buyers now require chain-of-custody documentation linking protein fractions to certified sustainable forest management units. This behavioral shift concentrates demand among integrated biorefinery operators with captive timber supply, disadvantaging merchant extraction facilities without backward control over feedstock provenance. Germany's industrial buyers are most advanced in implementing these verification requirements.
Wood Protein Market Segmentation
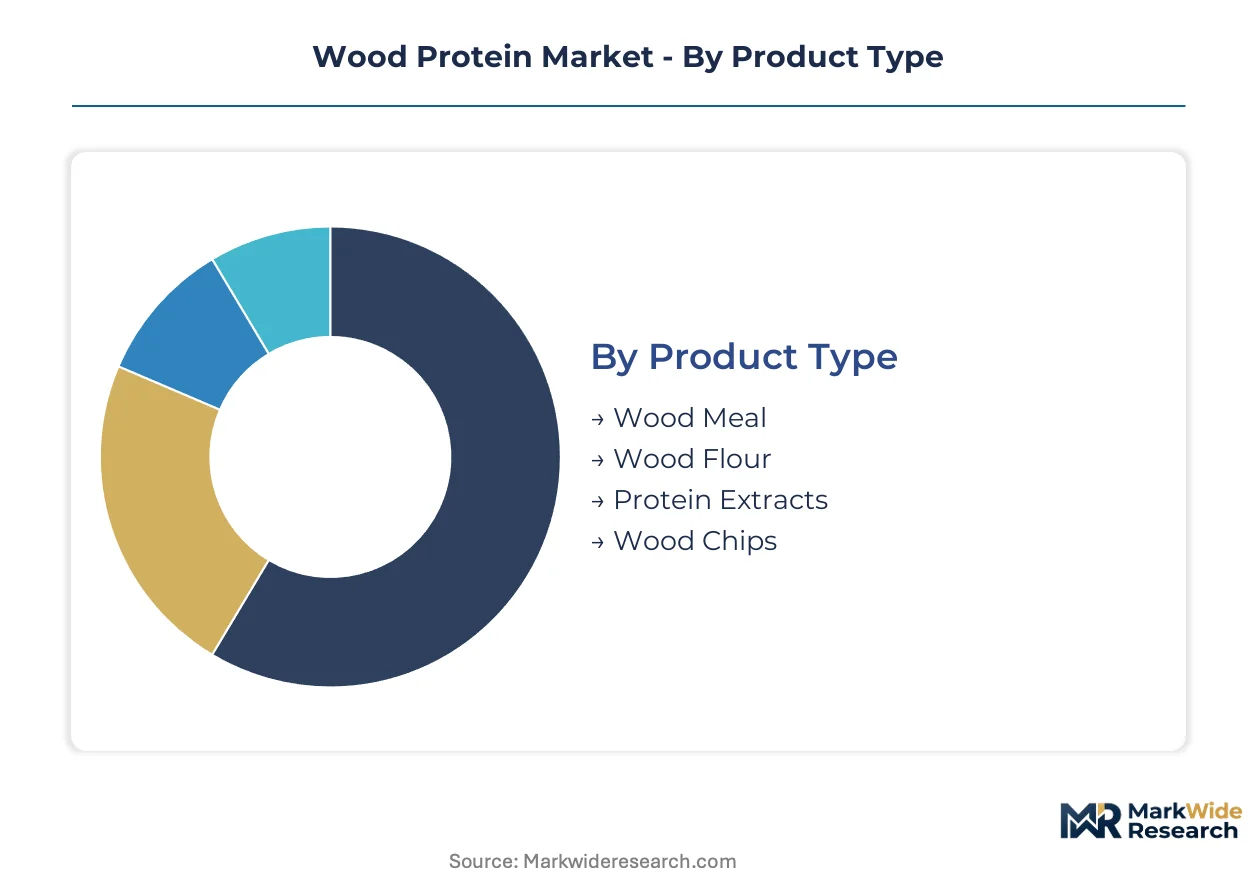
Wood protein segmentation reveals how extraction technology maturity and end-use performance requirements partition commercial value. Product format and application specifications determine which processors capture margin premiums versus commodity positioning.
Product Type:
Upgrade cycles from whole biomass to refined protein fractions reshape procurement economics across food and industrial sectors.
- Protein Extracts:Refined isolates containing concentrated amino acid fractions achieve digestibility scores above 85% in clinical evaluations. German nutraceutical compounders and Finnish biorefinery operators anchor demand for these food-grade isolates, though EMA novel food compliance costs filter out smaller processors.
- Wood Meal:Coarsely ground lignocellulosic material retains 1-3% crude protein with minimal processing investment. Animal feed blenders in the Nordic timber basins absorb volume here, constrained by amino acid incompleteness that blocks human food applications.
- Wood Flour:Finely milled cellulose-lignin matrices serve composite manufacturers seeking fiber reinforcement with incidental protein content. Construction sector procurement runs through German and Austrian panel producers.
- Wood Chips:Unprocessed biomass fractions with variable protein distribution supply pulp-to-protein integrated facilities. Stora Enso's Sunila pilot line and similar Nordic installations dominate captive consumption.
Protein extracts sit at the top of the volume ranking, with wood meal climbing the fastest as feed sector price sensitivity intensifies.
Application:
Cost tier stratification separates premium-positioned nutraceutical formulations from commodity bioplastics feedstock substitution.
- Bioplastics:Wood protein hydrolysates substitute for petroleum-derived binders in polymer compounding, with REACH registration requirements forcing full substance characterization. Brand owners facing Scope 3 targets in Germany and France actively source these non-food-competing proteins.
- Nutraceuticals:High-purity isolates command ingredient cost premiums based on superior digestibility versus commodity plant proteins. EMA novel food approval pathways concentrate development activity among Finnish and German operators with pilot-scale enzymatic platforms.
- Animal Feed:Whole wood meal and lower-grade protein fractions enter ruminant and aquaculture nutrition, limited by palatability challenges and amino acid profile gaps versus oilseed meals.
- Adhesives:Liquid protein hydrolysates enable uniform dispersion in industrial bonding applications, displacing formaldehyde-based resins in German furniture and construction panel manufacturing.
Bioplastics applications hold the largest volume position, while nutraceuticals gain share fastest on regulatory tailwinds and margin expansion.
End Use:
Customer type concentration determines whether specifications prioritize purity certification or feedstock cost minimization.
- Food Industry:Plant-based meat extender and functional food applications demand food-grade protein isolates with complete toxicology documentation. German industrial biotech corridor facilities around Leipzig and Hamburg supply these formulations.
- Construction:Adhesive and composite applications absorb wood flour and hydrolyzed protein fractions, with procurement specifications increasingly requiring EU Green Deal sustainability certification.
- Pharmaceutical:Nutraceutical and dietary supplement manufacturers source highest-purity extracts, constrained by EMA and emerging PMDA review frameworks that extend development timelines.
- Chemical:Bioplastics compounders and specialty polymer formulators purchase protein hydrolysates as petroleum binder replacements, with REACH compliance costs filtering merchant market entrants.
The food industry represents the dominant volume sink, with pharmaceutical end use expanding most quickly on novel food approval progress.
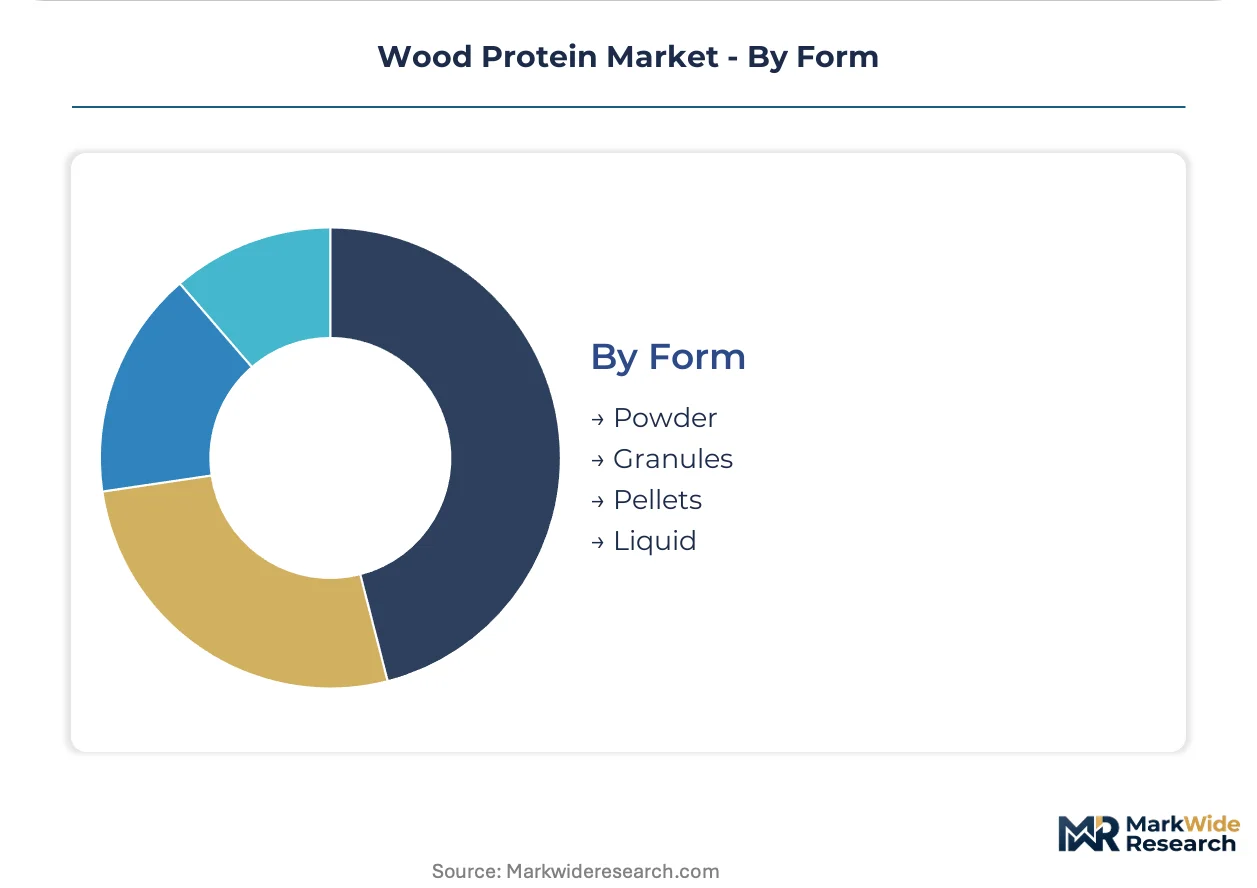
Form:
Supply concentration in powder processing infrastructure shapes regional availability of alternative formats.
- Powder:Dried protein isolates and meals dominate commercial transactions, with spray-drying capacity concentrated at Nordic and German integrated biorefinery sites. Shelf stability and transport economics favor this format for cross-border trade.
- Liquid:Protein hydrolysates in aqueous solution enable uniform dispersion in adhesive formulations, reducing curing variability that plagues powder-based resins. German construction panel manufacturers pilot these concentrates.
- Granules:Intermediate moisture formats suit specific feed compounding applications where dust control matters, though limited dedicated production constrains scale.
- Pellets:Densified forms facilitate bulk handling in integrated pulp-to-protein facilities, with captive consumption at Stora Enso and similar operators limiting merchant market development.
Powder form commands the volume lead, with liquid concentrates gaining traction fastest on adhesive sector technical validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between jurisdictions with established novel food frameworks and emerging markets with lower compliance costs is redistributing wood protein production capacity. EMA approval pathways in established European markets impose documentation burdens that smaller processors avoid by locating pilot facilities in jurisdictions with streamlined review timelines.
Germany
Industrial biotech infrastructure around Leipzig and Hamburg anchors enzymatic protein extraction scale-up. EMA novel food compliance requirements filter merchant market entrants toward integrated biorefinery operators with captive toxicology documentation capabilities. The Hamburg cluster concentrates pilot-to-commercial transition facilities for food-grade protein isolates.
Finland
Nordic timber basins supply softwood feedstock to pulp-to-protein integrated facilities. EU Green Deal sustainability certification requirements concentrate procurement among operators with chain-of-custody documentation back to forest management units. Stora Enso's Sunila facility exemplifies captive consumption models that dominate national production economics.
United States
Pacific Northwest timber holdings provide consistent softwood flows for protein extraction partnerships. EPA biomass boiler emissions standards indirectly shape feedstock availability through co-location economics that favor integrated pulp and protein operations. Washington and Oregon timber basins concentrate merchant extraction facility development.
Japan
PMDA novel food review framework establishment is opening regulatory pathways for wood protein nutraceutical entrants. METI industrial biotechnology programs subsidize pilot-scale enzymatic hydrolysis platform deployment. The Kanto region around Tokyo concentrates formulation partnerships between domestic food manufacturers and Nordic technology licensors.
South Korea
MFDS emerging novel food guidelines are creating compliance templates for wood-derived protein market entry. Government green bioeconomy initiatives under the Korean New Deal direct capital toward lignocellulose fractionation infrastructure. The Daejeon-Sejong corridor hosts public research institutes transferring enzymatic extraction technology to private compounders.
Wood Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue food-grade certification and enzymatic platform differentiation. The vendor base stratifies across integrated forest products companies with captive timber supply, specialized biorefinery operators, and ingredient distributors seeking backward integration. Strategic archetypes include pulp-to-protein integrated operators, enzymatic technology licensors, and nutraceutical formulation partners. Dominant competitive moves encompass pilot facility capacity expansion in the German industrial biotech corridor and strategic partnerships between timber holders and extraction technology providers.
Within the integrated forest products tier, Weyerhaeuser and Stora Enso exemplify operators leveraging captive timber holdings to secure feedstock flows. Arbiom Corporation occupies a position among enzymatic technology specialists pursuing differentiation through hydrolysis platform completeness. These three entities represent distinct strategic vectors: geographic feedstock control, integrated biorefinery economics, and processing technology specialization.
| Leading Market Players |
|---|
| Arbiom Corporation |
| Cargill Incorporated |
| Corbion |
| Danone Limited |
| Glanbia |
| Kerry Group |
| Wilmar International |
| Weyerhaeuser |
| Stora Enso |
| Others |
Value Network & Pricing Analysis
Specialized bioprocess engineering talent concentrated in Nordic academic institutions widens labor-cost spreads between enzymatic extraction platforms and commodity mechanical separation, compressing margins at the standard tier while premium food-grade isolates sustain pricing power.
Pricing Analysis
Distributor margins on food-grade protein extracts absorb EMA novel food documentation costs, widening spreads between certified premium isolates and industrial-grade hydrolysates. Three-tier pricing structure across premium, standard, and economy levels separates EMA-compliant nutraceutical ingredients from REACH-registered industrial fractions and unprocessed wood meal. Cost compression in the standard tier intensifies as Nordic pulp market competition diverts softwood feedstock. Animal feed blenders exhibit highest price sensitivity, while German pharmaceutical compounders accept ingredient premiums for digestibility-validated isolates.
Supply Chain Analysis
EU Green Deal chain-of-custody certification gates procurement participation, filtering merchant extraction facilities without backward control over forest management units. Feedstock supply anchors in Finland, Germany, and the United States Pacific Northwest, drawing from spruce, pine, and Douglas fir timber basins. Enzymatic hydrolysis platforms rest on cellulase and protease cocktail supply concentrated with Nordic biotechnology suppliers. Single-source vulnerability runs through softwood harvesting seasons that constrain year-round protein recovery operations. Distribution runs through integrated biorefinery operators with captive spray-drying capacity rather than merchant market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wood protein has entered a late-cycle quality phase where EMA novel food approval progress redirects procurement toward certified isolates, displacing price-only sourcing in European nutraceutical formulations.
For Market Incumbents: Cement feedstock security through long-term forest management unit contracts in Nordic timber basins, insulating against pulp market competition that diverts softwood supply. Expand captive toxicology documentation capabilities to filter merchant market entrants unable to bear EMA compliance costs. Prioritize enzymatic platform yield improvements that compress extraction economics versus emerging mechanical separation entrants.
For New Entrants and Emerging Players: Capture adhesive liquid concentrate formats where German construction panel manufacturers pilot wood protein hydrolysates as formaldehyde resin replacements. Target South Korean nutraceutical markets where MFDS novel food guidelines are creating first-mover compliance templates. Pursue technology licensing partnerships with Nordic enzymatic platform specialists rather than greenfield extraction facility investment.
For Investors and Strategic Acquirers: Valuations sit cheapest among integrated forest products operators with underutilized pulp-to-protein pilot infrastructure. Long-term viability hinges on enzymatic hydrolysis yield improvements that close the gap with oilseed processing economics. Monitor EMA novel food approval timelines for wood-derived protein isolates as the signal indicating inflection toward food-grade market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Scale-Up | Finnish and German pilot facilities compress extraction costs while unlocking EMA food-grade compliance. |
| Backward Integration into Timber Holdings | Weyerhaeuser and Stora Enso secure feedstock flows that merchant extraction facilities cannot match. |
| EMA Novel Food Approval Investment | German nutraceutical compounders gain procurement preference through validated toxicology documentation. |
| Adhesive Format Technical Validation | Liquid concentrate development addresses curing variability in German furniture panel manufacturing. |
| Asian Regulatory Pathway Establishment | Japan PMDA and South Korea MFDS frameworks open parallel commercialization tracks beyond Europe. |
Research Methodology
Bottom-up nutraceutical and bioplastics end-use modeling reconciled against top-down Nordic and German extraction capacity tracking forms the analytical core of this study. Primary interviews with biorefinery plant managers, EMA regulatory consultants, German food manufacturer procurement leads, and enzymatic platform R&D directors combined with secondary validation from EU Green Deal certification databases, EMA novel food submission records, Nordic timber trade statistics, and REACH registration filings. Triangulation across stakeholder perspectives and documentary sources anchored volume and value estimates.
Historical trendline analysis of lignocellulosic protein extraction efficiency improvements informed projection assumptions across the analysis window. Segmentation modeling incorporated product type tiers, application specifications, end-use industry requirements, and geographic regulatory cluster variations. CAGR derivation weighted enzymatic hydrolysis platform adoption curves against pulp market feedstock competition dynamics. Forecast inputs included EMA approval timeline probabilities and German industrial biotech corridor capacity expansion announcements.
Underlying measurement precision varies by segment; EMA-compliant nutraceutical isolates carry tighter precision than industrial adhesive fractions where REACH registration status remains fluid. Forecasts reflect documented assumptions regarding enzymatic yield improvement trajectories and EU Green Deal certification penetration rates. A model refresh is warranted upon material change in EMA novel food approval timelines for wood-derived protein categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Tension Spring Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Injection Molding Market
Industrial Materials
Neoprene Foam Market