
 Metal Based Safety Gratings Market | 2026-2036
Metal Based Safety Gratings Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Based Safety Gratings Market Foresight
The capital-intensity divergence between integrated mills and fabricators is collapsing as laser-cutting automation and robotic welding compress the minimum efficient scale for custom grating production. Nucor Grating leverages its captive steel supply to control raw material cost volatility across North American projects. Meiser anchors its European position through specialized serrated-bar manufacturing for offshore oil platforms. Ohio Grating competes on rapid-turn engineered-to-order capabilities for industrial retrofit contracts.
Metal based safety gratings are engineered load-bearing surfaces fabricated from steel, aluminum, or stainless steel through welding, swaging, or expansion processes, designed to support personnel and equipment while permitting drainage, ventilation, and light transmission in elevated industrial environments. Bar grating dominates commercial specifications due to its open-grid structure and high strength-to-weight ratio for heavy-traffic walkways. Welded grating commands premium positioning in petrochemical and marine applications where structural integrity under dynamic loading is non-negotiable. Slip-resistant grating is gaining specification share as facility operators prioritize fall-prevention compliance in wet-process environments.
OSHA mandates minimum coefficient-of-friction thresholds for elevated walkways, directly shaping product design and testing protocols for domestic suppliers. ISO 14122 machinery safety standards and ASTM E-136 fire-performance classifications further constrain material selection and surface treatment options for international project bids. Buyers must monitor evolving carbon-border adjustment mechanisms and scrap-content traceability rules as sustainability criteria penetrate industrial procurement frameworks.
Market Dynamics
Laser-cutting automation and robotic welding are collapsing the minimum efficient scale for custom grating production, eroding the historical cost advantage of integrated steel mills over specialized fabricators.
Growth Catalysts
- OSHA walkway mandates:Elevated platform safety requirements in oil and gas facilities are tightening coefficient-of-friction thresholds for slip-resistant surfaces. Domestic suppliers must redesign testing protocols to maintain specification access.
- China infrastructure retrofit cycles:Aging industrial facilities across the Yangtze River Delta are accelerating replacement demand for load-bearing gratings in chemical processing plants.
- Swaged aluminum grating:Lightweight fabrication processes are expanding addressable applications in offshore wind turbine maintenance platforms where corrosion resistance and weight reduction converge.
Market Restraints
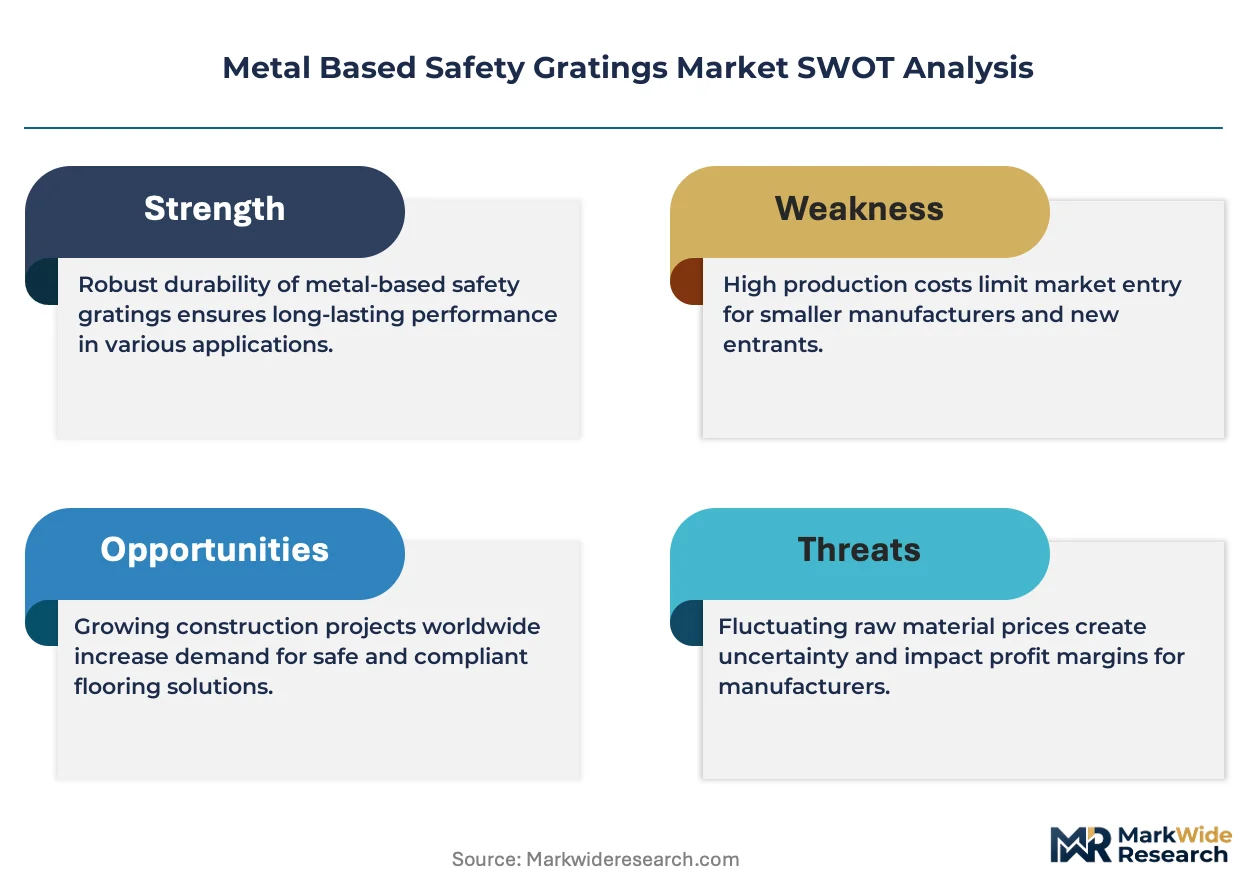
- Scrap steel price volatility:Electric arc furnace operators face margin compression when ferrous scrap markets spike, directly transmitting cost pressure to grating fabricators without long-term raw material hedges.
- European supply concentration:Specialized serrated-bar production for offshore oil platforms clusters in German and Dutch fabrication hubs, creating single-source vulnerability for North Sea project timelines.
- Fiber-reinforced polymer substitutes:Composite walkway systems in marine environments are capturing specification share where electrolytic corrosion concerns override metal's structural advantages.
Strategic Opportunities
- India petrochemical expansion:Greenfield refinery construction along the Gujarat coast is generating specification demand for fire-rated welded gratings under BIS certification pathways.
- EU carbon border adjustments:CBAM implementation on imported steel products is creating first-mover advantage for domestic European fabricators with verified scrap-content traceability.
- Digital twin integration:BIM-compatible grating libraries are enabling engineered-to-order workflows that compress design-to-installation cycles for industrial retrofit contractors.
Industry Challenges
- Certification timeline compression:ISO 14122 machinery safety documentation requirements are extending bid-to-award cycles, straining working capital for project-based fabricators.
- Welding automation skill gaps:Robotic programming expertise for complex serrated-bar joints remains scarce in legacy fabrication workforces across the US Midwest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Based Safety Gratings Market |
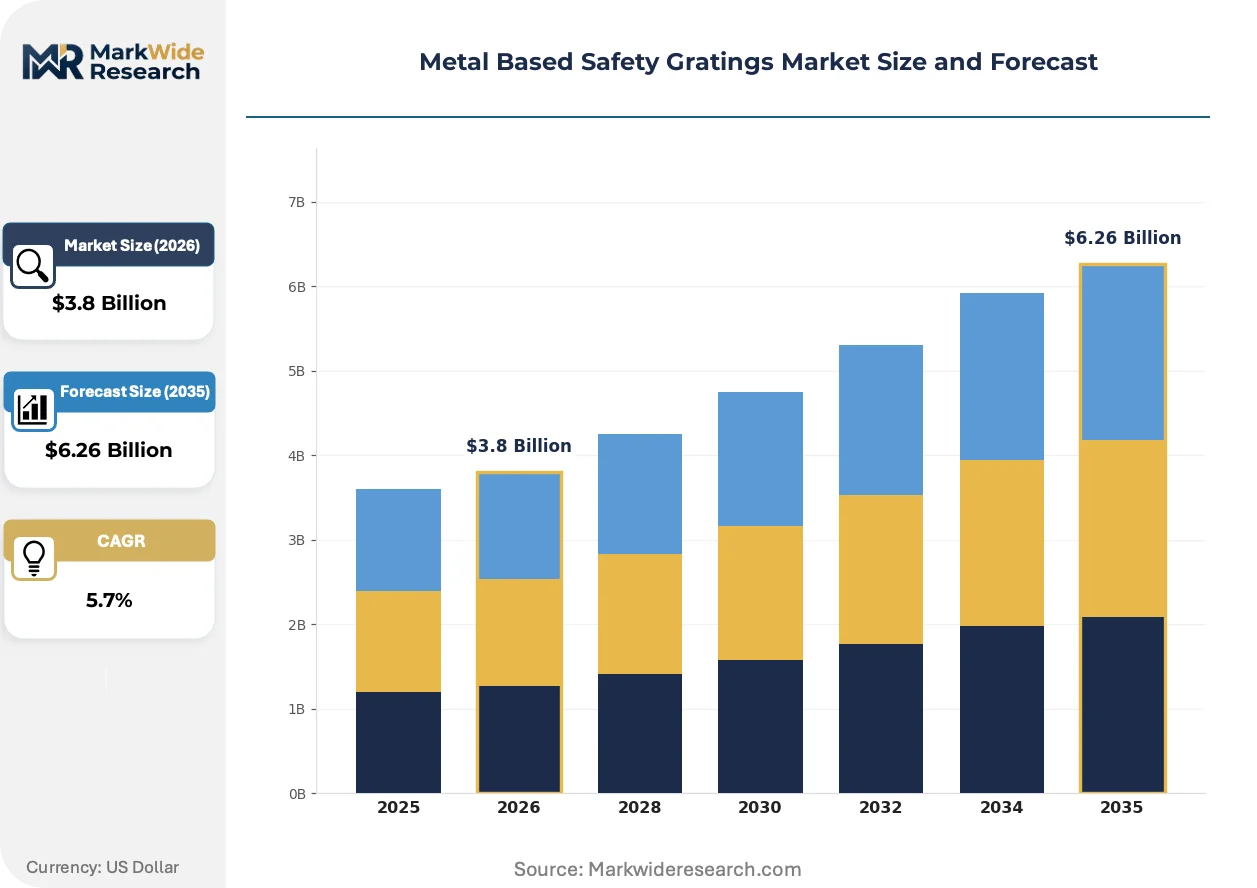
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bar Grating, Expanded Grating, Slip-Resistant Grating, Welded Grating Material: Steel, Aluminum, Stainless Steel, Carbon Steel Application: Industrial Facilities, Walkways, Platforms, Drainage End User: Construction, Transportation, Oil & Gas, Manufacturing |
| Companies Covered | Nucor Grating, McNichols Company, Ohio Gratings, Grating Pacific, AMICO, Fisher & Ludlow, Meiser, Webforge, The Peddinghaus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Based Safety Gratings Market Shifts & Advancements
Specification-grade grating is fragmenting into performance-tiered categories as facility operators demand documented compliance with evolving safety and sustainability frameworks.
Laser-cut perforation technology is displacing traditional punched-bar fabrication in high-precision architectural applications. Museum and transit station designers are specifying custom aperture patterns for aesthetic daylighting control. This capability is compressing the price premium between industrial and architectural-grade products.
ASTM E-136 fire-performance classifications are constraining material selection for international project bids. Specifiers must document surface treatment flame-spread indices alongside structural load tables. Marine and petrochemical segments are absorbing the longest compliance verification cycles.
Consolidated procurement through engineering-procurement-construction firms is displacing fragmented distributor purchasing in large-scale infrastructure projects. EPC technical teams are embedding grating specifications into master construction packages. This concentration is most visible in German industrial retrofit contracts where single-source accountability reduces site coordination risk.
Metal Based Safety Gratings Market Segmentation
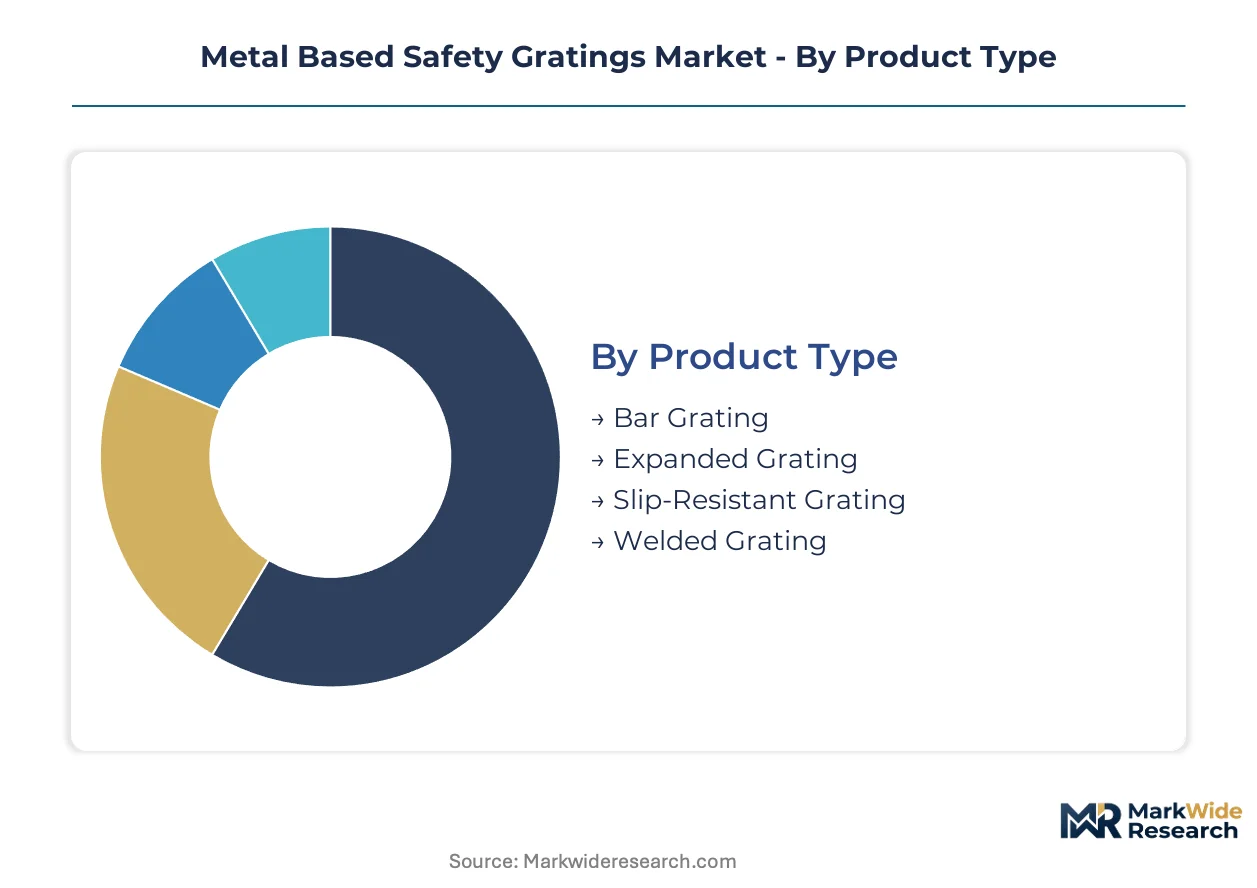
Segmentation in metal safety gratings reveals how specification-grade requirements diverge across industrial environments. Material selection and fabrication method determine compliance pathways for OSHA walkway mandates and ISO machinery safety standards. Understanding these splits exposes where composite substitutes threaten metal's specification share versus where structural load-bearing demands protect incumbent technologies.
Product Type:
Slip-resistant and expanded grating face the most acute substitution pressure from fiber-reinforced polymer walkways in coastal marine applications, while welded and bar grating retain structural moats in heavy-load petrochemical environments.
- Bar Grating:Fabricated from bearing bars and cross rods in open-grid configurations, bar grating delivers the highest strength-to-weight ratio for elevated industrial walkways. Demand concentrates in United States oil and gas facilities where OSHA coefficient-of-friction thresholds mandate documented slip resistance for platforms above six feet.
- Welded Grating:Fusion-welded bearing and cross bars create permanent joints capable of withstanding dynamic loading without mechanical fastener fatigue. Petrochemical refineries along the Texas Gulf Coast specify welded construction for fire-rated egress platforms under NFPA 101 compliance pathways.
- Slip-Resistant Grating:Serrated or abrasive-coated surfaces engineered for wet-process environments where fall prevention overrides pure load-bearing optimization.
- Expanded Grating:Slit-and-stretched metal sheet forming diamond-patterned openings, offering lower cost per square foot for light-duty maintenance access.
Bar grating retains volume leadership; slip-resistant grating holds the steepest expansion curve as facility operators prioritize documented OSHA compliance.
Material:
Cost tier stratification separates commodity carbon steel from premium stainless grades, with aluminum occupying a mid-tier position where weight reduction justifies material premium.
- Steel:Hot-rolled carbon and alloy grades dominate high-load industrial specifications where raw material cost sensitivity shapes procurement decisions. Chinese Yangtze River Delta chemical plants absorb the largest steel grating volumes for aging facility retrofits.
- Aluminum:Swaged and extruded aluminum alloys enable corrosion-resistant specifications at roughly one-third the density of steel equivalents. Offshore wind turbine maintenance platforms in the North Sea specify aluminum for helicopter landing pad gratings where weight limits constrain structural design.
- Stainless Steel:Austenitic and duplex grades command specification in food processing and pharmaceutical cleanrooms where surface contamination protocols prohibit carbon steel oxidation.
- Carbon Steel:Plain and pickled-and-oiled grades serve budget-constrained projects with protective coating requirements rather than intrinsic corrosion resistance.
Steel maintains the broadest specification base; aluminum is climbing fastest on offshore energy infrastructure demand.
Application:
Application segmentation tracks how load-bearing requirements and environmental exposure dictate grating selection across facility zones.
- Industrial Facilities:Process plant flooring, mezzanines, and equipment access platforms requiring engineered load tables and documented deflection limits. German industrial retrofit contracts concentrate procurement through engineering-procurement-construction firms seeking single-source accountability.
- Walkways:Elevated personnel circulation paths subject to OSHA minimum width and guardrail integration standards. United States manufacturing plants drive replacement cycles as pre-2010 installations fall below current coefficient-of-friction thresholds.
- Platforms:Fixed and modular work surfaces for maintenance, inspection, and production operations.
- Drainage:Trench covers and sump gratings where open-area percentage determines hydraulic flow capacity.
Industrial facilities anchor volume demand; walkways are expanding most quickly on regulatory retrofit mandates.
End User:
End-user concentration reveals which capital expenditure cycles transmit demand volatility to fabricator order books.
- Oil & Gas:Upstream platforms, midstream terminals, and downstream refineries specify fire-rated welded gratings under API and OSHA joint compliance frameworks. Greenfield refinery construction along India's Gujarat coast generates specification demand for BIS-certified load-bearing surfaces.
- Construction:Commercial and infrastructure projects where grating specification sits within broader structural steel packages. Transit station designers in United States metropolitan areas are specifying laser-cut perforation patterns for aesthetic daylighting control.
- Transportation:Airport hangars, rail maintenance facilities, and port cargo handling infrastructure.
- Manufacturing:Automotive assembly lines, food processing plants, and general industrial production floors.
Oil and gas commands the highest specification intensity; construction delivers the most variable demand cyclicality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb specification-grade premiums without elasticity, while procurement teams in China and India negotiate aggressively on carbon steel volumes for retrofit budgets.
United States
OSHA walkway mandates are accelerating replacement cycles for pre-2010 elevated platforms in Gulf Coast petrochemical facilities. The Department of Labor enforces coefficient-of-friction thresholds above six feet. Houston-area fabricators report order backlogs for fire-rated welded gratings under NFPA 101 compliance pathways.
Germany
Industrial retrofit contracts concentrate procurement through engineering-procurement-construction firms seeking single-source accountability. EU carbon border adjustments favor domestic fabricators with verified scrap-content traceability. The Ruhr Valley and North Rhine-Westphalia host specialized serrated-bar production clusters for offshore oil platform specifications.
China
Aging chemical processing plants across the Yangtze River Delta are driving replacement demand for load-bearing steel gratings. GB standards and evolving machinery safety protocols constrain imported product access. Shanghai and Jiangsu province fabrication hubs absorb the largest retrofit volumes as infrastructure upgrade cycles accelerate.
India
Greenfield refinery construction along the Gujarat coast generates specification demand for BIS-certified welded gratings. The Bureau of Indian Standards mandates fire-performance documentation for petrochemical load-bearing surfaces. Reliance Industries and state-owned oil majors are consolidating procurement through integrated EPC contractors.
United Arab Emirates
Offshore platform maintenance and port infrastructure expansion sustain demand for corrosion-resistant aluminum gratings. The country's national standards body aligns with ISO 14122 machinery safety frameworks for international project bids. Dubai and Abu Dhabi fabrication yards serve as regional supply nodes for North Sea and West African offshore contracts.
Metal Based Safety Gratings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the metal safety gratings market. Integrated steel producers leverage captive raw material supply to compress fabrication costs for high-volume industrial contracts. Specialized fabricators compete on engineered-to-order responsiveness and certification documentation speed. The vendor base fragments across three strategic tiers: mill-integrated producers, regional custom fabricators, and architectural-grade specialists. Dominant competitive moves include robotic welding automation investments and BIM-compatible digital twin libraries for design-to-installation compression.
Among North American fabricators, Nucor Grating anchors the mill-integrated tier with captive steel supply advantages. Ohio Gratings exemplifies the rapid-turn engineered-to-order specialist archetype for industrial retrofit contracts. Meiser occupies a position within the European premium tier through specialized serrated-bar manufacturing capabilities for offshore oil platform specifications.
| Leading Market Players |
|---|
| Nucor Grating |
| McNichols Company |
| Ohio Gratings |
| Grating Pacific |
| AMICO |
| Fisher & Ludlow |
| Meiser |
| Webforge |
| The Peddinghaus Corporation |
| Others |
Supply & Pricing Matrix
Fiber-reinforced polymer walkway systems replacing metal gratings in North Sea marine applications are simultaneously shifting procurement geography toward composite fabrication clusters in Denmark and the Netherlands while compressing pricing premiums for corrosion-resistant aluminum grades. This substitution dynamic forces traditional metal fabricators to defend specification share through accelerated certification documentation rather than pure cost competition.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value for engineered-to-order grating suppliers. Project-based pricing dominates transactional flows, with differentiation anchored in ISO 14122 certification tier and documented load-table accuracy. Cost compression in standard welded carbon steel grades is intensifying because electric arc furnace operators transmit scrap volatility without hedging. EPC contractors demonstrate lowest price sensitivity; municipal retrofit buyers exhibit highest elasticity.
Supply Chain Analysis
Germany and the Netherlands anchor specialized serrated-bar production for offshore oil platform specifications. Raw material flows draw from Turkish ferrous scrap markets, Chinese hot-rolled coil, and Russian semi-finished steel. Single-source vulnerability clusters in North Sea fabrication hubs serving North Sea project timelines. Distribution runs through engineering-procurement-construction firms consolidating procurement for large-scale industrial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate fiber-reinforced polymer substitution in coastal marine environments where electrolytic corrosion concerns override metal's structural advantages. Defense requires specification-grade certification investments that composite alternatives cannot replicate.
For Market Incumbents: Consolidate robotic welding automation investments to compress minimum efficient scale for custom serrated-bar production. Captive steel supply through backward integration insulates margin position against scrap price spikes. Accelerate BIM-compatible digital twin libraries to defend engineered-to-order responsiveness against regional fabricators.
For New Entrants and Emerging Players: BIS certification fast-track for fire-rated welded gratings unlocks greenfield refinery construction along India's Gujarat coast. Target aluminum swaged grating for offshore wind turbine maintenance platforms where weight reduction commands specification premium. Partner with EPC technical teams embedding grating specifications into master construction packages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators lacking robotic automation infrastructure. Five-to-ten year viability hinges on certification documentation speed and scrap-content traceability for EU carbon border adjustment compliance. Watch for inflection when CBAM implementation accelerates domestic European fabricator margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Welding Automation | Compresses minimum efficient scale for custom serrated-bar production below integrated mill thresholds. |
| Scrap-Content Traceability Program | Enables EU carbon border adjustment compliance for domestic fabricators against imported steel. |
| BIM-Compatible Digital Twin Library | Accelerates design-to-installation cycles for industrial retrofit contractors specifying engineered-to-order gratings. |
| BIS Certification Fast-Track Investment | Unlocks greenfield refinery construction demand along India's Gujarat coast under Bureau of Indian Standards mandates. |
| Swaged Aluminum Capacity Expansion | Captures offshore wind turbine maintenance platform specifications where weight limits constrain structural design. |
Research Methodology
A standing panel of plant engineers, EPC procurement leads, grating fabrication technical directors, and aftermarket service heads provided ongoing calibration across the primary research phase. Secondary validation drew from OSHA enforcement databases, ASTM standard revision records, customs trade flows for ferrous scrap and finished grating, and SEC filings from integrated steel producers. Bottom-up volume modeling triangulated against top-down industrial construction spend allocations.
Consistency checks validated volume and value outputs against external benchmarks including regional industrial retrofit contract awards and petrochemical facility maintenance expenditure surveys. Segmentation dimensions spanned product type, material grade, fabrication method, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to annual specification demand estimates, with cross-reference to oil and gas capital expenditure cycles and infrastructure retrofit timelines.
Underlying assumptions cover OSHA coefficient-of-friction threshold stability, scrap steel price mean-reversion, and composite substitution rates in marine environments, with deviation risk concentrated in EU carbon border adjustment implementation timing and India petrochemical project sanctioning delays. Recalibration cycles align with material shifts in regulatory enforcement intensity and raw material cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Fly Ash Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Shock Mat Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Flat Enameled Wires Market