
 Asia-Pacific Industrial Flooring Market | 2026-2036
Asia-Pacific Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Flooring Market Outlook
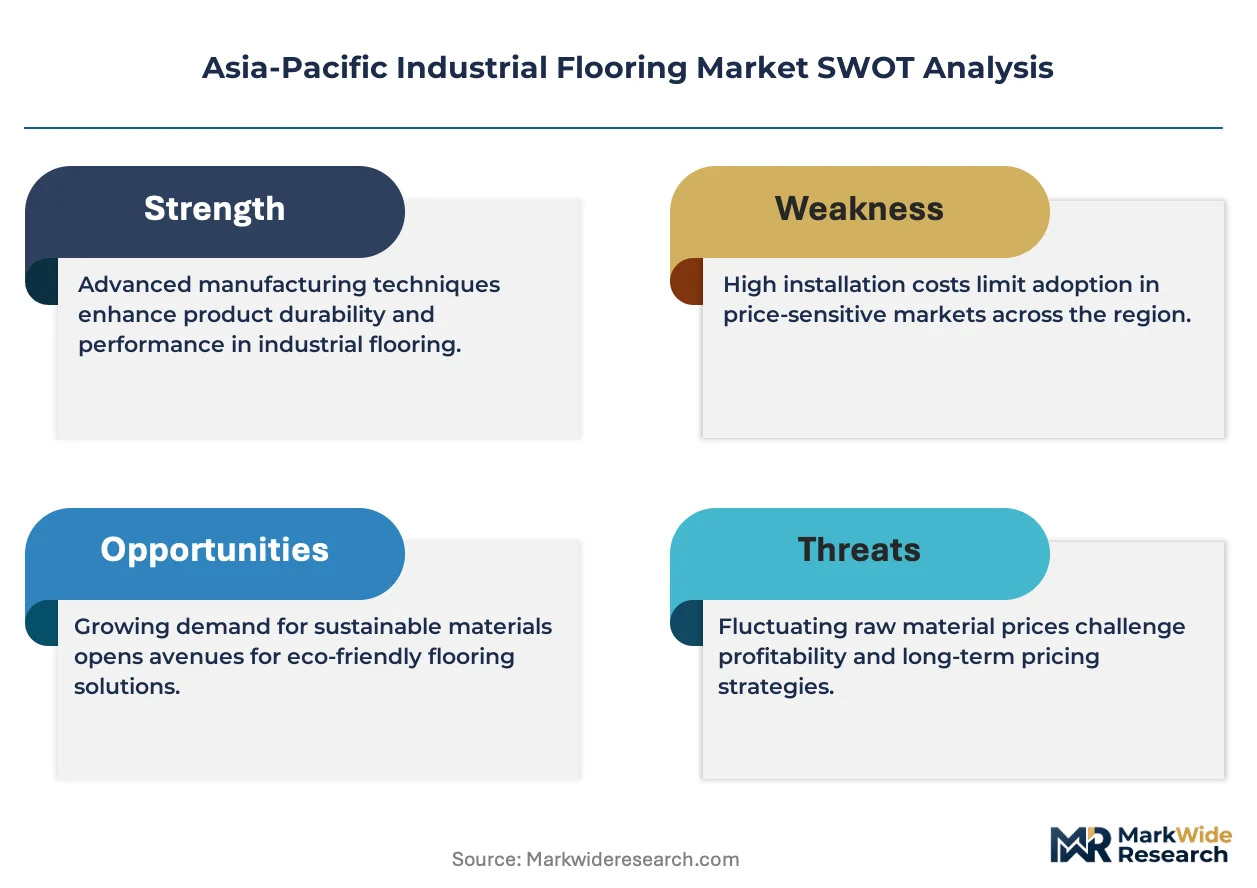
Capital-intensity divergence between multinational resin formulators and regional applicators is collapsing as scale requirements for VOC-compliant formulations rise. Sika AG sustains integrated supply chains across Southeast Asian manufacturing zones. Nippon Paint Holdings Co. Ltd. dominates Japan's specification-driven pharmaceutical and electronics flooring segments. Akzo Nobel N.V. leverages its marine coatings heritage to transfer high-performance binder technology into heavy-duty industrial surfaces.
Asia-Pacific industrial flooring encompasses resinous, cementitious, and hybrid surface systems engineered to withstand mechanical abrasion, chemical attack, and thermal cycling in commercial and industrial environments. Epoxy formulations typically achieve compressive strengths exceeding 80 MPa and bond to concrete substrates through amine-cured crosslinking chemistry. Epoxy systems anchor the installed base across mature manufacturing economies, while polyurethane segments capture expansion in cold-storage warehousing and food processing applications where thermal shock resistance proves critical. Cementitious overlays occupy the value tier for cost-sensitive infrastructure projects, though margin pools concentrate in specialized self-leveling installations for pharmaceutical cleanrooms.
China's SAMR enforces GB standards for volatile organic compound emissions in industrial coatings, directly shaping reformulation investments by imported and domestic suppliers. Japan's METI promotes JIS-compliant low-carbon building material specifications that influence public procurement criteria for industrial construction. India's BIS certification mandates for construction chemicals create market access barriers for uncertified imports. Stakeholders must monitor how Australia's TGA-equivalent building code harmonization with ASEAN technical regulations reshapes cross-border product registration requirements.
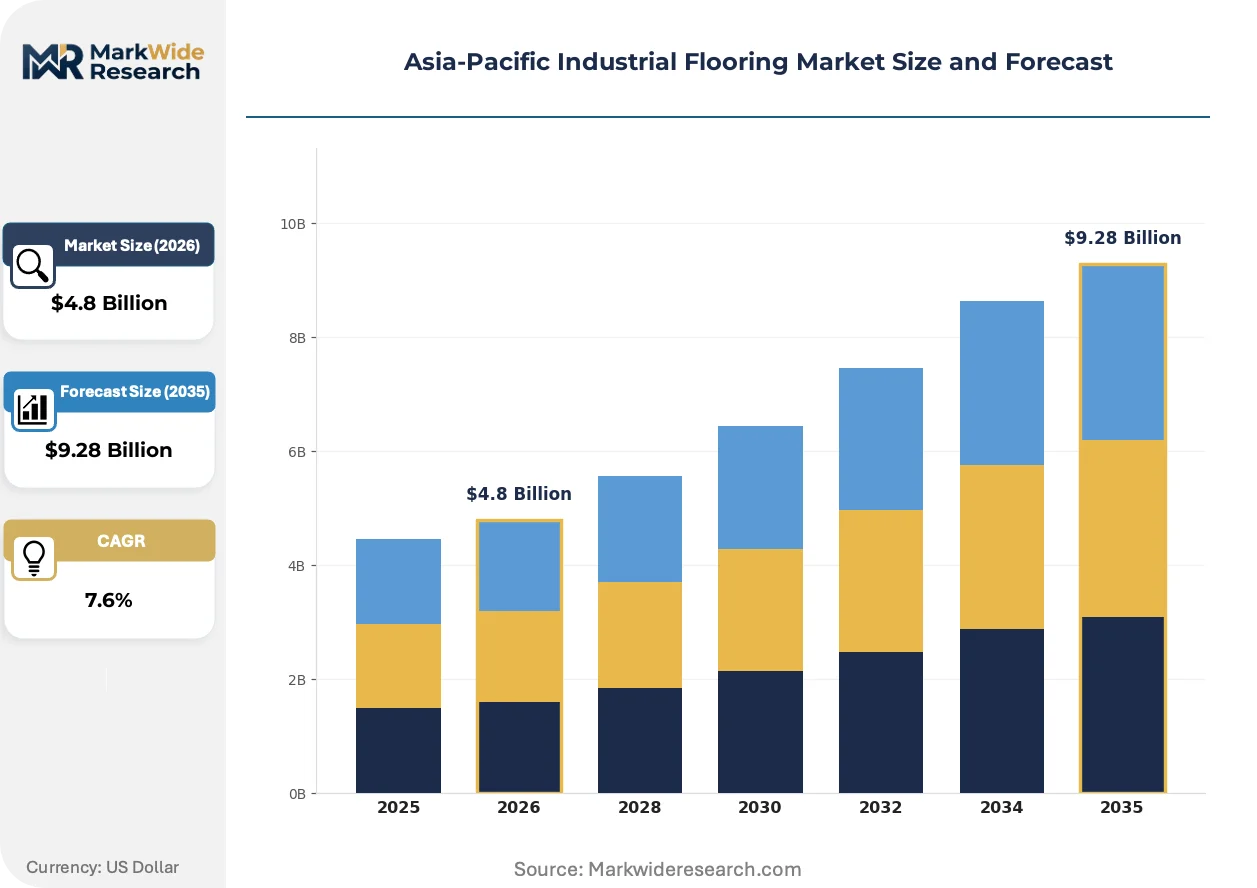
Market Dynamics
China's GB standards for volatile organic compound emissions are forcing wholesale reformulation of resin systems across the Asia-Pacific region, collapsing the historical cost advantage of solvent-based epoxies and redistributing margin pools toward compliant waterborne and high-solids alternatives.
Growth Catalysts
- India's PLI scheme for pharmaceutical manufacturing:The production-linked incentive scheme is expanding cleanroom-grade flooring specifications across Hyderabad and Ahmedabad manufacturing corridors.
- Cold-chain infrastructure buildout:Southeast Asian food processing and logistics operators are specifying polyurethane thermal-shock-resistant systems for freezer warehousing applications.
- Japan's JIS-compliant low-carbon specifications:METI's building material procurement criteria are accelerating demand for cementitious overlays with reduced embodied carbon in public industrial construction.
Market Restraints
- Petrochemical input volatility:Bisphenol A and epoxy resin precursor costs fluctuate with naphtha cracking margins, compressing applicator margins on fixed-price contracts.
- Import certification timelines:India's BIS mandatory certification for construction chemicals creates 12-18 month market access barriers for uncertified foreign suppliers.
- Cementitious substitution in cost-sensitive segments:Basic polymer-modified cement overlays capture specification share in Indian and Indonesian infrastructure projects where resin systems exceed budget thresholds.
Strategic Opportunities
- Vietnam's northern industrial zones:Electronics manufacturing relocation from China is generating greenfield demand for ESD-dissipative flooring in Bac Ninh and Hai Phong provinces.
- Hybrid system convergence:Polyurethane-modified epoxy chemistries combine chemical resistance with thermal cycling performance, opening specification share in multi-use food and beverage facilities.
- Australia-ASEAN technical harmonization:Building code alignment initiatives are streamlining cross-border product registration for suppliers with established Australian TGA-equivalent certification.
Industry Challenges
- Skilled applicator scarcity:Self-leveling resin installation requires certified technicians with moisture testing and substrate preparation expertise, creating bottlenecks in rapidly scaling Southeast Asian markets.
- Legacy substrate compatibility:Existing oil-contaminated or deteriorated concrete floors in aged Indian and Chinese manufacturing facilities demand costly remediation before resin system adhesion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Flooring Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPOXY, POLYURETHANE, CEMENTITIOUS, ACRYLIC Application: Manufacturing, Warehousing, Automotive, Food Processing Installation Type: Self-Leveling, Trowel-Applied, Roll-On, Injection End User: Construction, Retail, Pharmaceuticals, Aerospace |
| Companies Covered | Akzo Nobel N.V., Sherwin-Williams Company, Sika AG, CoGri Group Ltd., 3M, Nippon Paint Holdings Co. Ltd., MBCC Group, Lubrizol Corporation, RPM International Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Flooring Market Strategic Shifts
Material science advances and procurement model evolution are restructuring competitive advantage in Asia-Pacific industrial flooring, separating suppliers capable of integrated specification support from commodity resin distributors.
Polyaspartic aliphatic polyurea technology is supplanting conventional epoxy topcoats in high-traffic warehousing applications across Japan and South Korea. Logistics operators with 24-hour operational windows specify these rapid-cure systems for minimized downtime during facility retrofit. The technology is compressing installation cycle times from seven days to under 48 hours, eroding the labor-cost advantage of slower-curing alternatives.
China's SAMR enforcement of GB 30981-2020 VOC limits in industrial coatings is mandating waterborne epoxy and high-solids solvent-free formulations for imported and domestic suppliers alike. Domestic resin manufacturers with captive amine hardener production are capturing specification share previously held by imported systems. Japanese and South Korean electronics manufacturers with China-based facilities are accelerating supplier qualification timelines to maintain GB-compliant installed bases.
Asset-owner procurement teams are consolidating flooring specification authority from regional facility managers to centralized engineering functions, particularly among Japanese pharmaceutical and South Korean semiconductor multinationals. Third-party technical auditing of applicator workmanship is displacing self-certified contractor warranties in high-value cleanroom installations. This concentration is most visible in Singapore's biomedical manufacturing hub, where owner-specified master agreements with Sika and Nippon Paint applicator networks override local contractor selection.
Asia-Pacific Industrial Flooring Market Segmentation
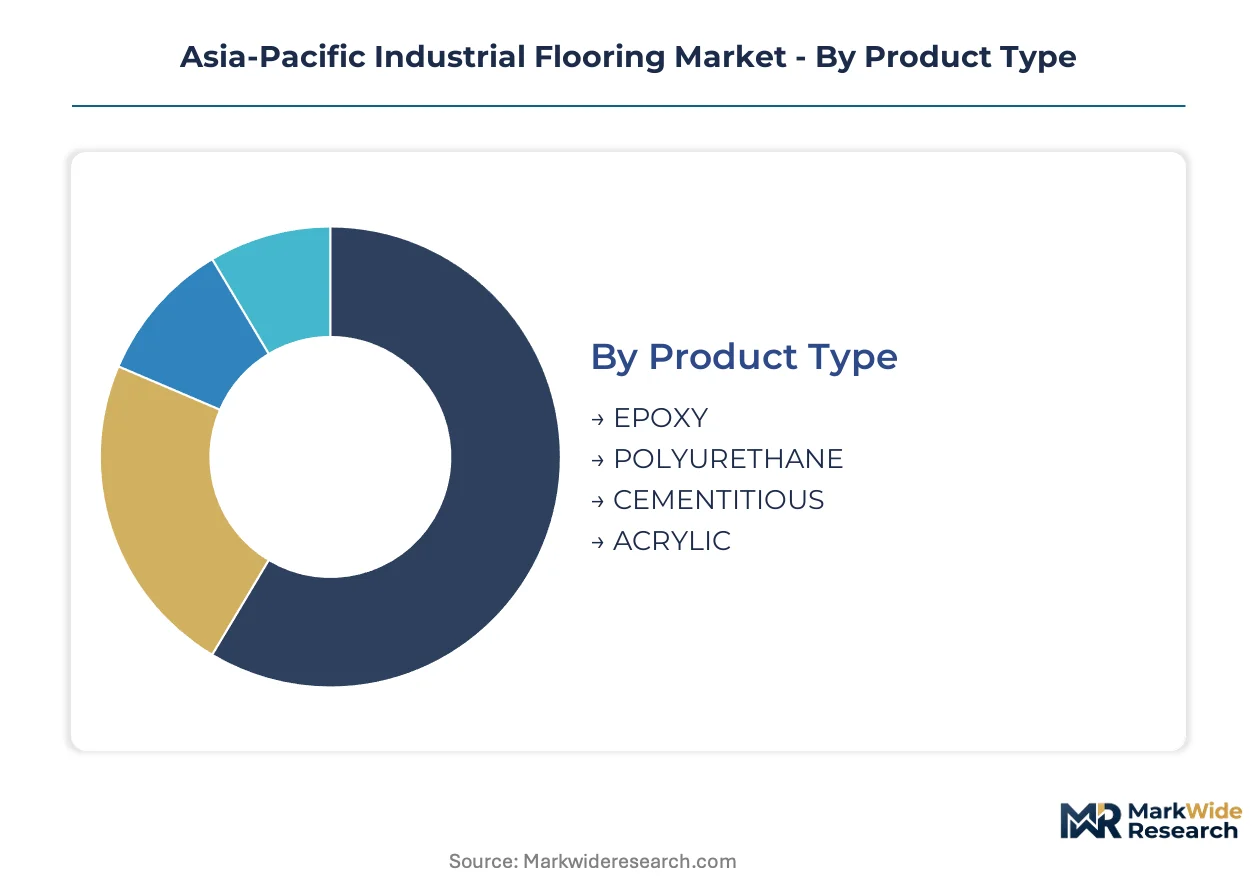
Asia-Pacific industrial flooring procurement decisions split across performance specifications, installation constraints, and compliance requirements. Margin concentration varies sharply between commodity cementitious overlays and specialized resin systems for regulated environments.
Product Type:
Epoxy and polyurethane formulations capture the deepest margin pools through specification complexity and technical support requirements.
- Epoxy:Amine-cured crosslinking systems achieve compressive strengths exceeding 80 MPa with superior chemical resistance. Demand concentrates in China's electronics manufacturing zones around Shenzhen and Suzhou, where GB 30981-2020 VOC compliance is forcing wholesale reformulation of legacy solvent-based formulations.
- Polyurethane:Aliphatic and aromatic isocyanate systems deliver thermal shock resistance critical for freezer warehousing. Southeast Asian cold-chain operators in Thailand and Vietnam specify these for temperature cycling between -25°C ambient and 25°C loading docks.
- Cementitious:Polymer-modified Portland cement overlays serve cost-sensitive infrastructure in India and Indonesia where resin budgets prove prohibitive.
- Acrylic:Methyl methacrylate rapid-cure systems address 24-hour operational windows in Japanese logistics retrofit applications.
Epoxy retains the dominant installed base, while polyurethane is expanding share fastest through cold-storage specification.
Application:
Volume leadership sits with high-throughput logistics facilities, though pharmaceutical and food processing command premium pricing through contamination-control requirements.
- Manufacturing:Electronics and automotive assembly plants specify ESD-dissipative and chemical-resistant systems. Vietnam's Bac Ninh and Hai Phong industrial zones generate greenfield demand as manufacturing relocates from China.
- Warehousing:Polyaspartic topcoats with 48-hour cure windows minimize downtime in Japan and South Korean distribution centers operating continuous shifts.
- Automotive:Heavy-duty urethane concrete systems withstand hot tire pickup and battery acid exposure in EV assembly expansion across China and Thailand.
- Food Processing:Thermal shock-resistant polyurethane coving and flooring dominate Southeast Asian seafood and poultry processing facilities under HACCP protocols.
Warehousing generates the largest project volumes, though food processing shows the steepest specification upgrade trajectory.
Installation Type:
Technical complexity and skilled labor requirements determine margin distribution, with self-leveling systems commanding substantial premiums over manual application methods.
- Self-Leveling:High-build resinous screeds achieve 3-5mm thickness with laser-guided flatness tolerances. India's pharmaceutical corridors around Hyderabad and Ahmedabad specify these for FDA-equivalent cleanroom certification under the PLI scheme.
- Trowel-Applied:Heavy-duty mortar systems with aggregate loading address impact resistance in Chinese steel fabrication and heavy machinery facilities.
- Roll-On:Thin-film coatings serve maintenance refresh cycles in Australian and New Zealand industrial facilities with established substrate integrity.
- Injection:Pressure-injected epoxy and polyurethane grouts remediate substrate voids and cracks in aged Indian and Chinese manufacturing floors prior to overlay installation.
Self-leveling installations dominate value capture, while injection methods are expanding fastest from substrate remediation backlog.
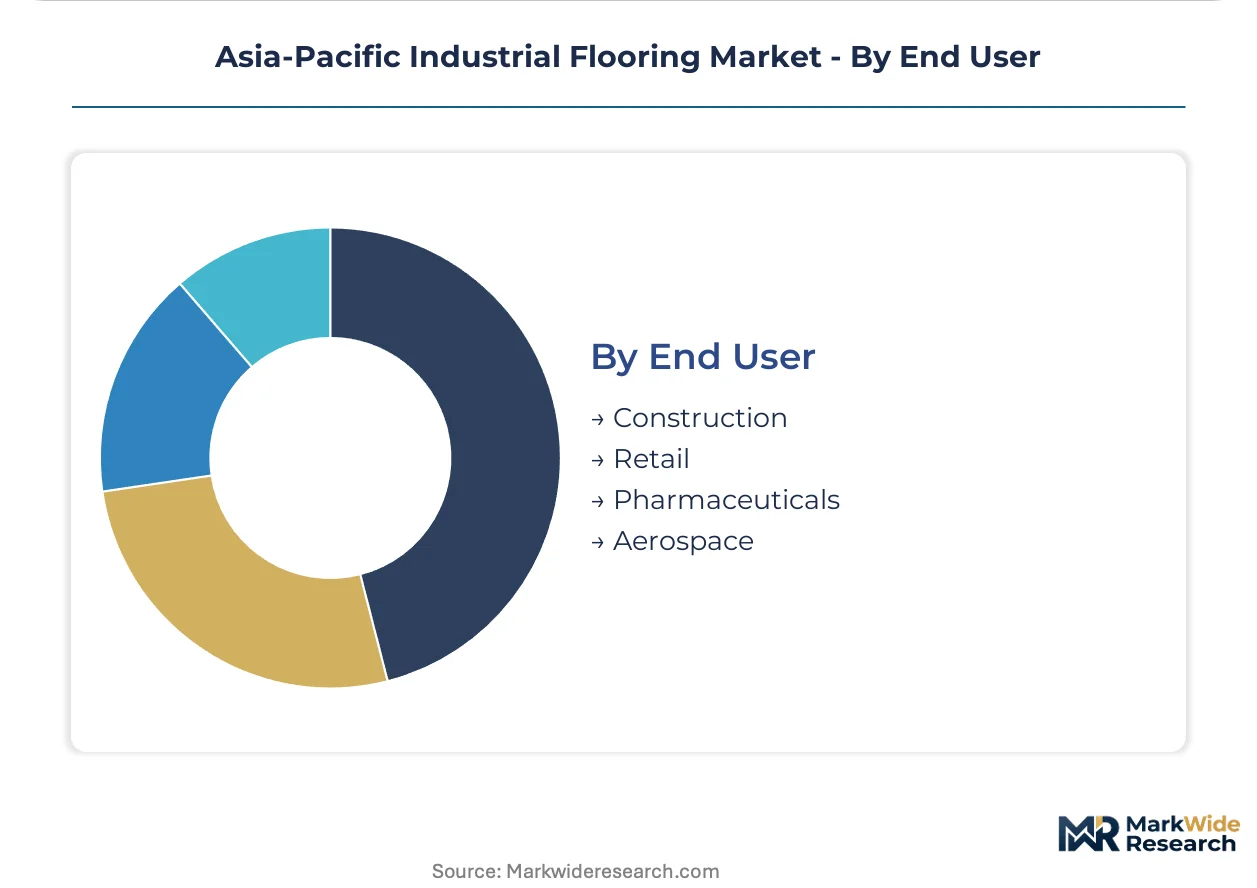
End User:
Regulatory intensity and asset longevity requirements separate high-specification segments from price-driven construction procurement.
- Construction:General industrial building contractors select cost-optimized cementitious and thin-film epoxy systems for speculative warehouse development across Indonesia and Malaysia.
- Retail:Big-box and distribution center operators balance aesthetic requirements with forklift traffic durability in Australia's supermarket chain expansion.
- Pharmaceuticals:cGMP-compliant flooring with integral coving and seamless drainage dominates Singapore's biomedical manufacturing hub and India's CDMO expansion.
- Aerospace:Hangar and MRO facilities specify fuel-resistant novalac epoxy systems in Japan and South Korea with defense and commercial aviation maintenance concentration.
Pharmaceutical end-use commands the highest specification intensity, while construction sector procurement shows the widest price elasticity range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Indonesia exhibit extreme price elasticity, driving cementitious overlay specifications, while pharmaceutical and electronics manufacturers in Japan and Singapore accept substantial premiums for certified resin systems.
China
Electronics manufacturing clusters in Shenzhen and Suzhou generate sustained epoxy demand for ESD-dissipative flooring. SAMR enforcement of GB 30981-2020 VOC limits forces wholesale reformulation of legacy solvent-based systems. Domestic resin manufacturers with captive amine hardener production capture specification share from imported alternatives in these coastal manufacturing zones.
India
Pharmaceutical manufacturing corridors around Hyderabad and Ahmedabad expand cleanroom-grade flooring specifications under the PLI scheme. BIS mandatory certification for construction chemicals creates 12-18 month market access barriers for uncertified foreign suppliers. Infrastructure projects in cost-sensitive segments specify basic polymer-modified cement overlays where resin budgets prove prohibitive.
Japan
Pharmaceutical and electronics segments command premium pricing through specification-driven procurement. METI promotes JIS-compliant low-carbon building material specifications that influence public procurement criteria for industrial construction. Logistics operators in the Kanto region specify polyaspartic rapid-cure systems to minimize downtime during 24-hour facility retrofit windows.
Vietnam
Electronics manufacturing relocation from China generates greenfield demand for ESD-dissipative flooring in Bac Ninh and Hai Phong provinces. Cold-chain infrastructure buildout drives polyurethane thermal-shock-resistant specifications for freezer warehousing applications. Foreign suppliers face compressed qualification timelines as Japanese and South Korean electronics manufacturers accelerate supplier onboarding.
Australia
Supermarket chain expansion drives demand for aesthetic-durability balanced systems in distribution centers. Building code harmonization initiatives with ASEAN technical regulations streamline cross-border product registration for suppliers with established TGA-equivalent certification. Established substrate integrity in mature industrial facilities supports thin-film coating maintenance refresh cycles rather than full system replacement.
Asia-Pacific Industrial Flooring Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale requirements for VOC-compliant formulations collapsing historical capital-intensity divergence. The structure concentrates margin pools in specification support capabilities rather than commodity resin distribution. Two strategic archetypes dominate: multinational formulators with captive raw material integration and regional applicators with certified installation networks. Competitive moves center on M&A for applicator network control and technology licensing for rapid VOC-compliant formulation deployment.
Within the integrated multinational tier, Sika AG and Akzo Nobel N.V. exemplify formulators with cross-regional manufacturing presence and marine coatings heritage transferrable to heavy-duty industrial surfaces. Nippon Paint Holdings Co. Ltd. occupies a specification-driven position in Japan's pharmaceutical and electronics segments. Among these anchors, geographic origin and corporate structure signal divergent strategic positioning: Swiss-incorporated Sika AG represents supply chain integration across Southeast Asian manufacturing zones, Netherlands-based Akzo Nobel N.V. leverages coatings technology adjacencies, and Tokyo-listed Nippon Paint Holdings Co. Ltd. exemplifies domestic specification authority in a procurement-concentrated market.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Sherwin-Williams Company |
| Sika AG |
| CoGri Group Ltd. |
| 3M |
| Nippon Paint Holdings Co. Ltd. |
| MBCC Group |
| Lubrizol Corporation |
| RPM International Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day resin formulation lead times from captive amine hardener producers in China compress pricing power for imported epoxy systems, concentrating margin capture among domestic suppliers with backward integration into precursor chemistry and regional applicators with certified installation networks.
Pricing Analysis
After-sales technical auditing and warranty administration now generate lifetime value exceeding initial material margins for specification-grade resin systems. Three-tier pricing structure across premium, standard, and economy levels separates cGMP-certified pharmaceutical flooring from basic warehouse epoxy and polymer-modified cement overlays. Cost compression in economy-tier cementitious systems is intensifying because Indian infrastructure contractors bid fixed-price projects with minimal resin content. Pharmaceutical end-users in Singapore and Japan show the least price sensitivity, while Indonesian warehouse developers exhibit extreme elasticity to specification upgrades.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Singapore-Jakarta trade lanes elevates inbound logistics costs for European and North American resin formulators without regional blending facilities. Raw material supply concentrates in China, South Korea, and Japan for bisphenol A, aliphatic isocyanates, and specialty amine hardeners. Formulation draws from petrochemical feedstocks tethered to naphtha cracking margins, creating margin volatility for fixed-price contract applicators. Single-source vulnerability sits with amine hardener supply from coastal Chinese chemical parks facing environmental compliance shutdowns. Distribution runs through certified applicator networks rather than commodity distributors for specification-grade installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and extended warranty programs now expand faster than base resin sales, reframing industrial flooring as a recurring-revenue service business anchored to substrate condition monitoring and scheduled refurbishment cycles.
For Market Incumbents: Compound specification authority by acquiring certified applicator networks in Vietnam's Bac Ninh corridor and India's Hyderabad pharmaceutical zone, while investing in captive waterborne epoxy formulation capacity to meet China's GB 30981-2020 VOC limits without margin-eroding reformulation costs. Cementitious substitution in Indonesian infrastructure projects threatens volume share in cost-sensitive segments. For New Entrants and Emerging Players: BIS certification fast-track programs for construction chemicals unlock 12-18 month market access timelines previously blocking uncertified imports into India's pharmaceutical manufacturing corridors. Target cold-storage polyurethane specifications in Vietnam's Hai Phong province, where Japanese electronics manufacturers accelerate supplier qualification with compressed technical onboarding. Lead with rapid-cure polyaspartic systems that minimize facility downtime against incumbent epoxy alternatives. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because scale requirements for VOC-compliant formulation chemistry and certified installation networks are collapsing the historical fragmentation between multinational resin suppliers and regional applicators. Acquisition focus centers on mid-cap applicators with established pharmaceutical cleanroom credentials and captive relationships with Japanese or South Korean electronics manufacturers. Monitor BIS certification approval velocity for foreign construction chemicals as an inflection indicator for competitive entry cost structures in India's expanding pharmaceutical flooring market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Hardener Production | Captive precursor supply insulates margin compression from naphtha volatility and GB 30981-2020 compliance costs. |
| Certified Applicator Network Acquisition | Control over installation quality displaces self-certified contractor warranties in Singapore's biomedical manufacturing hub. |
| Waterborne Epoxy Formulation Scale-Up | Domestic production in China's coastal zones captures specification share from imported solvent-based legacy systems. |
| Polyaspartic Rapid-Cure Technology Licensing | 48-hour installation windows command premium positioning in Japan's 24-hour logistics retrofit market. |
| Long-Term Technical Service Agreements | Recurring substrate monitoring and scheduled refurbishment contracts extend customer lifetime value beyond initial material sales. |
Study Parameters
The analysis maps epoxy, polyurethane, cementitious, and hybrid flooring systems, each validated through plant engineers at electronics and pharmaceutical facilities, procurement leads at cold-chain logistics operators, certified applicator network managers, and resin formulation technical directors. Primary interviews triangulate with secondary validation from customs and trade data on resin precursor imports, SEC 10-K filings of listed coatings companies, ACC and regional chemical association reports, and building code harmonization documentation between Australia's TGA-equivalent framework and ASEAN technical regulations. Bottom-up project pipeline assessment and top-down manufacturing capacity analysis cross-validate volume estimates.
Consistency checks against external benchmarks validate volume and value outputs across the analysis window. The analytical framework models product type, installation complexity, end-use regulatory intensity, and regional compliance cluster as segmentation dimensions. CAGRs derive from fitted growth curves applied to disclosed capacity expansion announcements and pharmaceutical manufacturing investment tracking under India's PLI scheme. Forecast inputs incorporate substrate remediation backlog estimates for aged Indian and Chinese industrial facilities and cold-chain warehouse buildout timelines in Southeast Asia.
Underlying assumptions cover sustained enforcement of China's GB 30981-2020 VOC limits, continued pharmaceutical manufacturing relocation to Vietnam and India, and stable petrochemical feedstock availability, with deviation risk concentrated in BIS certification timeline extensions for foreign suppliers and unexpected environmental compliance shutdowns at Chinese amine hardener production facilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Extruders Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Metal Molds Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Static Mixer Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Global Polyurethane Screen Panels Market