
 Industrial Round Wood Market | 2026-2036
Industrial Round Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Round Wood Market Foresight
Modular log sourcing and bundled timber supply contracts is broadening procurement flexibility for large-scale buyers. Stora Enso Oyj leverages its integrated Nordic forest-to-mill network to secure consistent fiber supply. West Fraser Timber Co. Ltd. dominates western Canadian spruce-pine-fir markets through scale advantages in sawmilling and remanufacturing. Weyerhaeuser Company anchors its position across the US South with extensive timberland holdings and direct-to-mill logistics control.
Industrial round wood comprises unprocessed or minimally processed tree stems harvested for mechanical or chemical processing into lumber, veneer, pulp, or engineered products, with diameters, lengths, and species specifications determining end-use suitability. Its primary commercial purpose centers on supplying raw fiber for construction materials, paper manufacturing, and value-added wood products. The lumber segment leads value capture due to structural-grade demand from residential and commercial building, while wood chips sustain volume flows into pulp and pellet markets. Plywood competes in specialized applications requiring dimensional stability, and the packaging end-user channel is expanding fastest as e-commerce drives crate and pallet consumption.
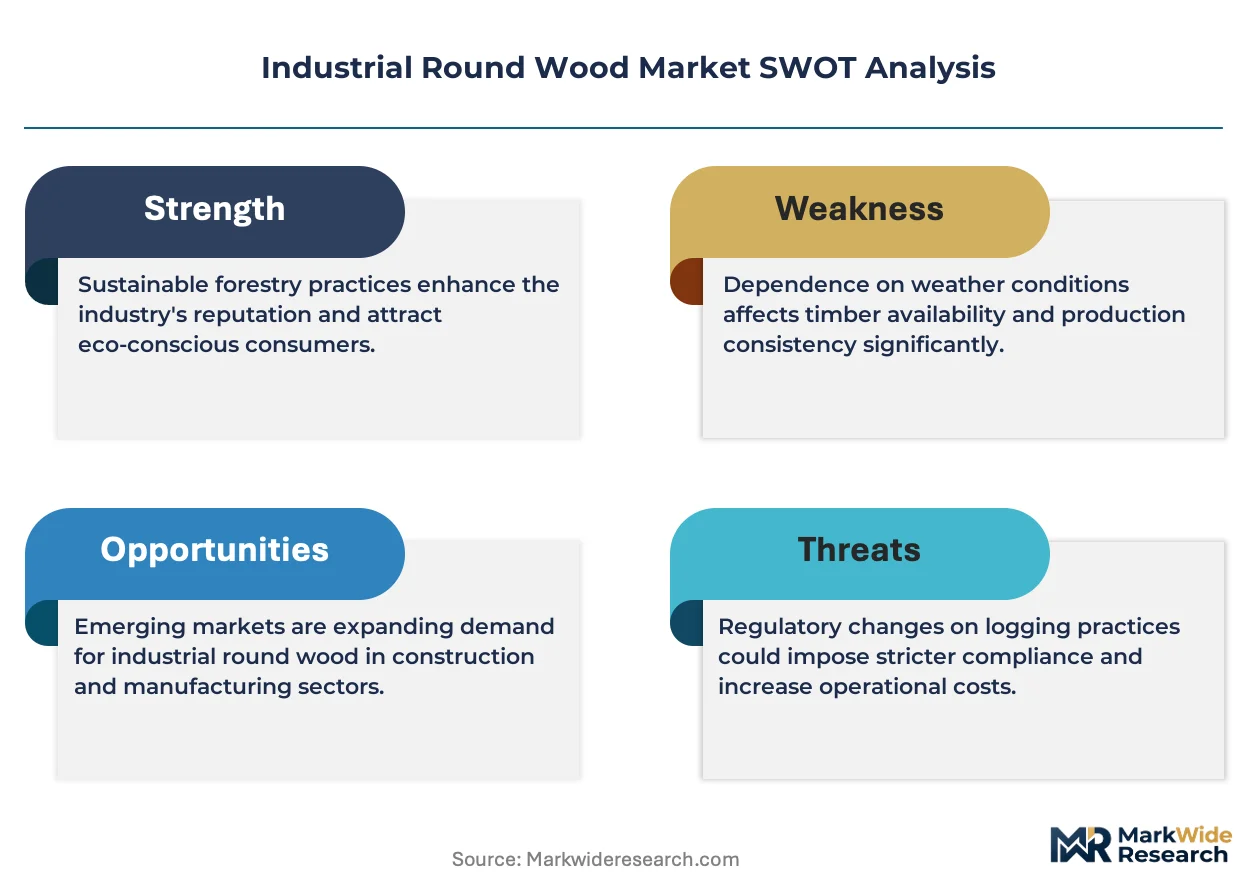
The EU Deforestation Regulation, US Lacey Act amendments, and FSC chain-of-custody standards collectively tighten traceability mandates, forcing exporters to document harvest origin and legality. EMA and national forest service audits in Europe now intersect with ESG disclosure rules under CSRD, raising compliance costs for uncertified suppliers. Buyers must monitor evolving border-adjustment mechanisms and certification tier gaps to secure supply continuity.
Market Dynamics
The EU Deforestation Regulation and US Lacey Act amendments are forcing exporters to rebuild traceability infrastructure, while mass timber construction redirects fiber demand toward engineered products and away from commodity lumber grades.
Growth Catalysts
- Mass Timber Construction:Cross-laminated timber and glulam specifications in commercial building codes are redirecting sawlog demand toward structural-grade fiber. Architects in Nordic markets specify engineered wood for mid-rise projects.
- E-commerce Packaging:Crate and pallet consumption from warehouse fulfillment networks is expanding demand for lower-grade roundwood previously directed to pulp markets. Third-party logistics providers now specify ISPM-15 compliant heat-treated material.
- EU Deforestation Regulation:Due diligence mandates for harvest origin documentation are creating competitive separation between certified and uncertified suppliers. FSC chain-of-custody holders capture price premiums in German and French procurement.
Market Restraints
- Fiber Cost Volatility:Diesel prices and logging contractor availability swing delivered log costs in remote Russian Far East and Indonesian concessions. Fuel surcharges now dominate spot contract negotiations.
- Supply Concentration Risk:Brazilian eucalyptus plantations and Russian taiga softwood together account for disproportionate export volume. Political instability or export duty shifts in either jurisdiction compress global availability.
- Steel and Concrete Substitution:Fire-rated steel framing and carbon-capture concrete formulations compete for commercial structural applications. Building code committees in several US states maintain material-neutral specifications.
Strategic Opportunities
- Underpenetrated African Supply:Gabonese and Congolese hardwood concessions remain underdeveloped relative to Asian demand for veneer and furniture stock. Chinese importers are financing port infrastructure in Pointe-Noire.
- Biomass Co-firing Mandates:Japanese and South Korean renewable portfolio standards designate wood pellets as qualifying feedstock. Industrial pellet contracts now absorb residual chips from sawmill operations.
- Blockchain Traceability:Distributed ledger verification of harvest-to-mill chain-of-custody intersects with EU Deforestation Regulation documentation requirements. Technology providers are piloting satellite-linked geofencing for concession monitoring.
Industry Challenges
- Harvest Contractor Shortage:Mechanized felling equipment operators and log truck drivers are aging out of the workforce in Pacific Northwest and Baltic regions. Training programs cannot replace retirement velocity.
- Certification Timeline Compression:FSC and PEFC audit backlogs extend compliance timelines beyond EU Deforestation Regulation enforcement dates. Smallholder cooperatives in Indonesia lack capital for group certification.
- Legacy Mill Configuration:Existing sawmilling lines optimized for dimensional lumber struggle to retool for mass timber feedstock dimensions. Capital requirements for resaw and finger-joint equipment strain mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Round Wood Market |
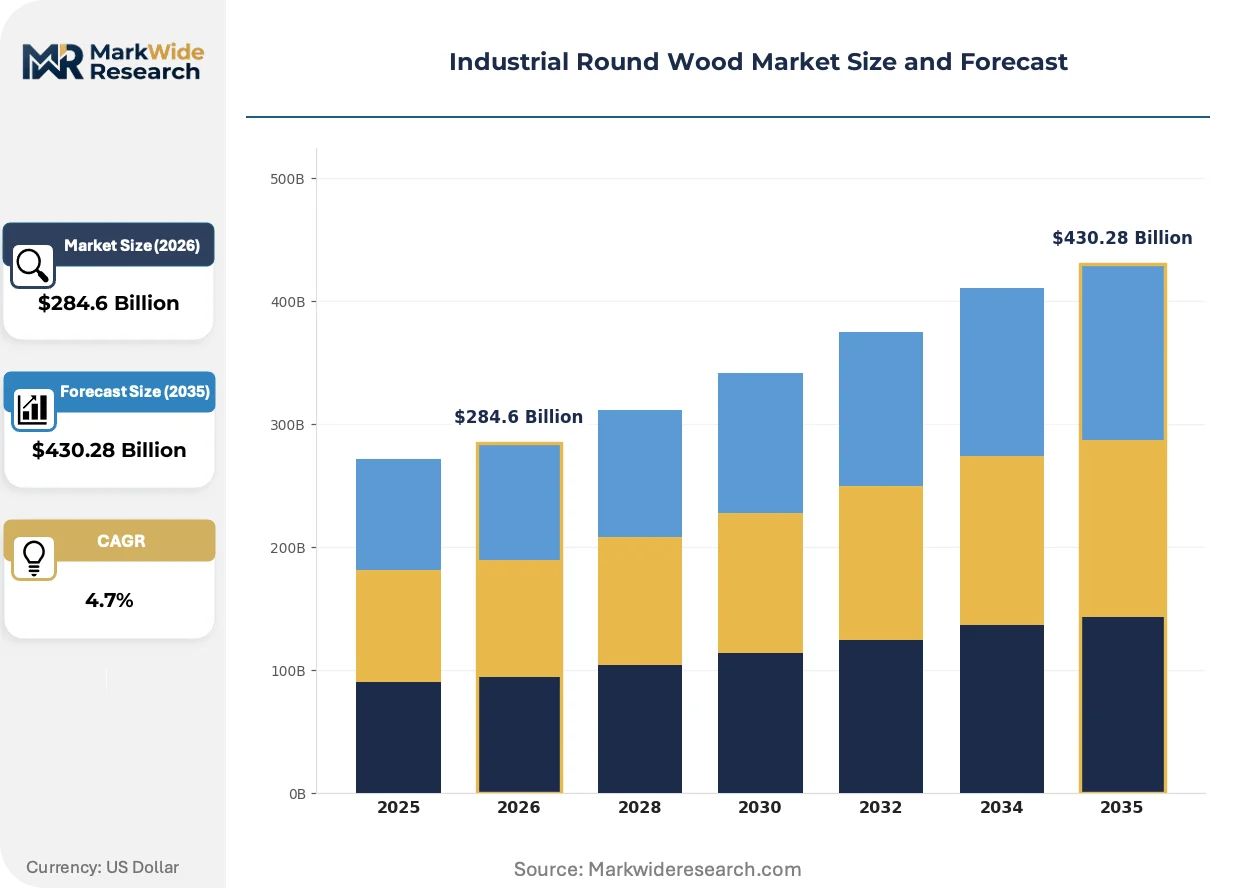
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $430.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lumber, Logs, Wood Chips, Plywood End User: Construction, Furniture, Paper, Packaging Technology: Sawing, Planing, Laminating, Treatment Grade: Structural, Appearance, Industrial, Others |
| Companies Covered | Stora Enso Oyj, Interfor Corporation, West Fraser Timber Co. Ltd., Boise Cascade Company, Arauco, Weyerhaeuser Company, Sierra Pacific Industries, Georgia-Pacific LLC, Canfor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Round Wood Market Shifts & Advancements
Digital traceability systems and automated sorting technologies are compressing the information lag between forest inventory and mill procurement decisions, while regulatory pressure accelerates capital deployment into verification infrastructure.
Machine-learning log scaling systems using LiDAR and computer vision are absorbing quality-assessment functions previously performed by manual graders. Nordic sawmills deploy these systems at infeed decks to optimize bucking patterns in real time. The technology is absorbing labor cost pressure while improving fiber recovery rates from variable-diameter stems.
EU Deforestation Regulation due diligence requirements mandate geolocation data for every harvest batch entering European supply chains. Exporters to Rotterdam and Hamburg must integrate satellite verification and customs pre-declaration systems. Brazilian and Indonesian suppliers are consolidating concessions to reduce traceability complexity.
Long-term fiber supply agreements are displacing spot market purchases among major European and North American buyers. Mass timber producers in Austria and British Columbia now contract directly with forest owners for 10-15 year supply security. This contracting pattern is visible where project finance for engineered wood plants requires feedstock certainty.
Industrial Round Wood Market Segmentation
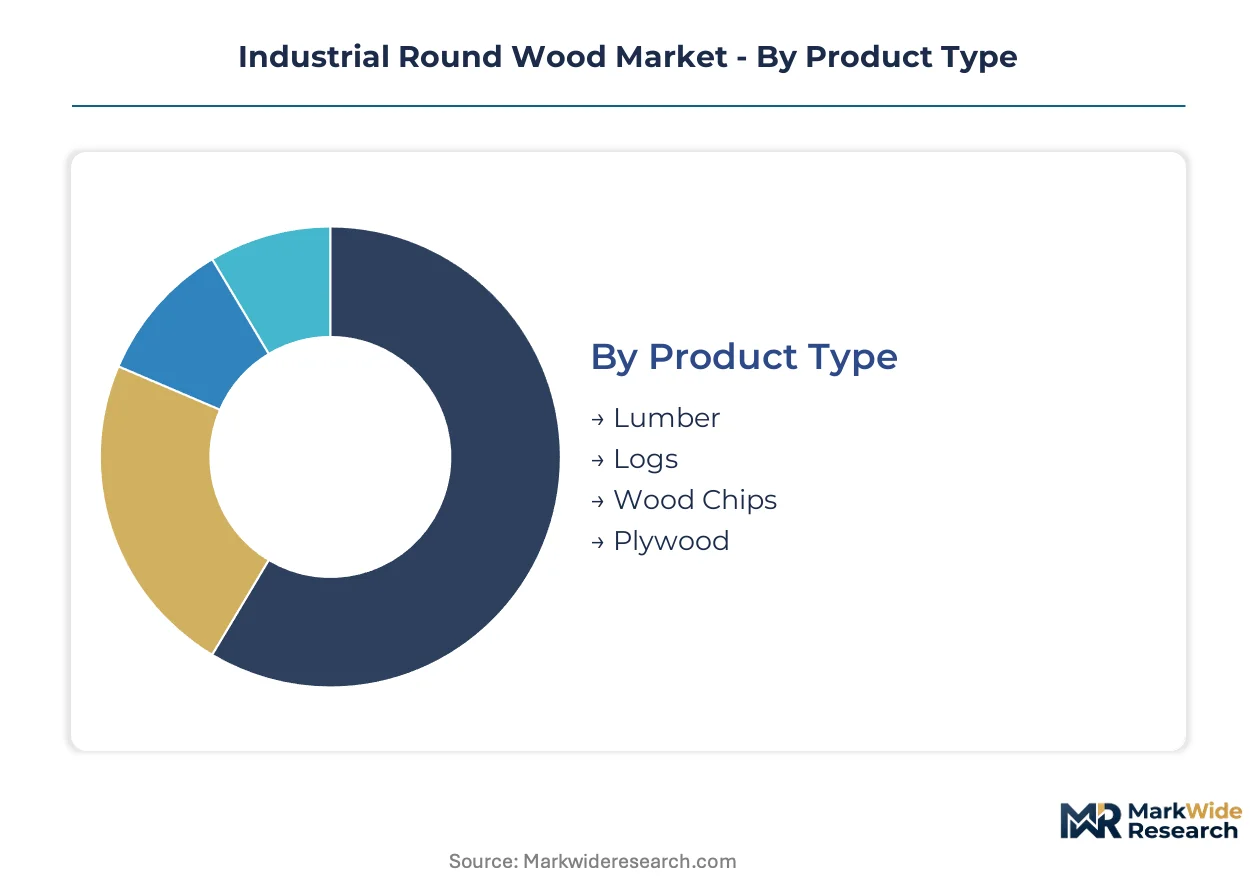
Segmentation in industrial round wood reveals how fiber specifications cascade through divergent processing paths and end-use specifications. Each dimension—product form, application, processing technology, and grade tier—carries distinct margin profiles and sourcing requirements that reshape procurement strategies.
Product Type:
Upgrade cycles in sawmill equipment and shifting construction material specifications are redirecting capital allocation across product categories.
- Lumber:Dimensional softwood and hardwood boards processed through primary breakdown and resaw operations. Structural-grade spruce-pine-fir from western Canada feeds mid-rise residential framing in the US, while European whitewood serves German and Austrian mass timber plants facing certified fiber shortages.
- Logs:Unprocessed or minimally bucked tree stems delivered to mills for primary conversion. Russian Far East taiga softwood and Brazilian eucalyptus plantations dominate export flows to Chinese sawmills and Indian plywood manufacturers, though EU Deforestation Regulation traceability mandates now filter sourcing decisions.
- Wood Chips:Residual fiber from sawmill operations and dedicated harvesting for pulp and pellet markets. Japanese biomass co-firing mandates and South Korean renewable portfolio standards absorb increasing volumes from Pacific Northwest and Southeast US suppliers.
- Plywood:Cross-laminated veneer panels bonded for dimensional stability in concrete forming and marine applications. Indonesian and Malaysian mills face consolidation pressure as European buyers demand FSC chain-of-custody documentation for tropical hardwood cores.
Volume placements concentrate in Lumber; the faster expansion belongs to Wood Chips.
End User:
Cost tier differentiation separates commodity fiber buyers from premium-grade purchasers with stringent certification requirements.
- Construction:Structural framing, mass timber systems, and concrete forming consume the largest fiber volumes. Nordic architects specify cross-laminated timber for commercial mid-rise projects, while US South residential builders optimize for cost-per-board-foot in single-family housing.
- Furniture:Appearance-grade hardwoods for case goods and millwork demand clear, defect-free surfaces. Italian and Vietnamese manufacturers source white oak and walnut from US Appalachian and French forest regions, paying premiums for long-length, knot-free material.
- Paper:Mechanical and chemical pulping operations absorb lower-grade hardwood and softwood residuals. Brazilian eucalyptus pulp mills achieve superior fiber yield per hectare compared to northern temperate species, concentrating investment in Mato Grosso do Sul.
- Packaging:Crate, pallet, and dunnage manufacturing from lower-grade fiber expands with e-commerce fulfillment networks. Third-party logistics providers in Germany and the Netherlands now mandate ISPM-15 compliant heat-treated material for cross-border shipments.
Construction commands the dominant volume position; Packaging is climbing the fastest as warehouse automation multiplies pallet throughput requirements.
Technology:
Application-specific processing requirements determine capital intensity and recovery rates across conversion methods.
- Sawing:Primary and secondary breakdown of logs into dimensional lumber through band or circular sawlines. Nordic mills deploy machine-learning bucking optimization at infeed decks to maximize value recovery from variable stem geometry.
- Planing:Surfacing and dimensioning of rough lumber to finished specifications with uniform thickness. German and Austrian producers integrate planing lines directly after kilns to serve just-in-time mass timber feedstock contracts.
- Laminating:Adhesive bonding of dimension lumber into structural glued laminated timber and cross-laminated panels. Austrian and British Columbia plants now contract directly with forest owners for 10-15 year supply security to underwrite project finance.
- Treatment:Pressure impregnation with preservatives or fire retardants for outdoor and structural applications. US South treaters face EPA regulatory review of copper-based formulations, accelerating interest in micronized alternatives.
Sawing retains the highest volume throughput; Laminating shows the steepest expansion trajectory as building codes recognize mass timber structural performance.
Grade:
Customer type separation between structural engineers, architects, and industrial buyers creates distinct pricing bands and certification demands.
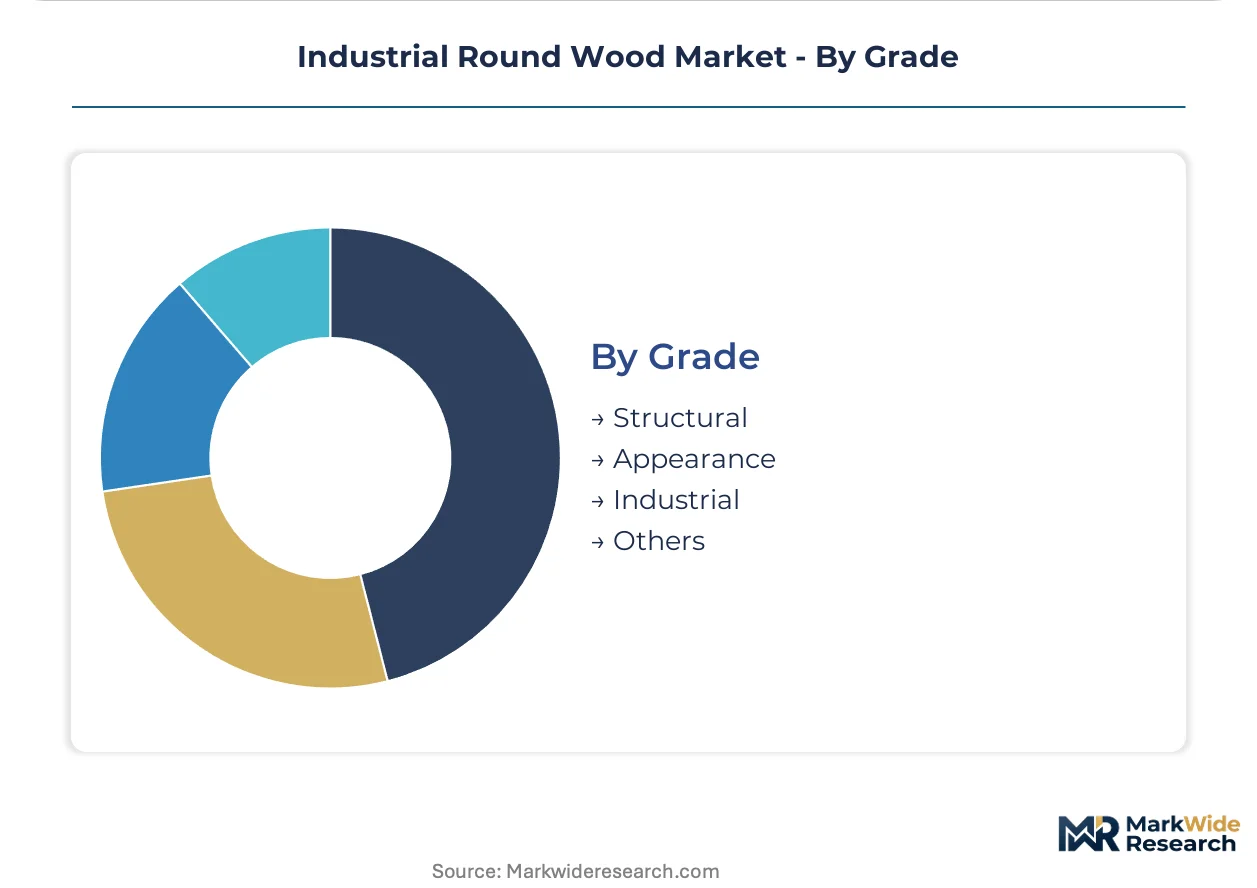
- Structural:Fiber graded for load-bearing capacity with defined strength and stiffness properties. Canadian spruce-pine-fir and European whitewood dominate engineered wood product specifications for mid-rise commercial construction.
- Appearance:Clear, stain-grade material selected for visual uniformity in furniture, millwork, and interior finishes. Appalachian white oak and French oak command premiums from Italian and Asian furniture manufacturers.
- Industrial:Utility-grade fiber acceptable for pallets, crating, and non-structural applications with minimal grading constraints. Russian Far East and Indonesian suppliers compete on delivered cost to Chinese and Indian processors.
- Others:Specialty grades including fire-retardant treated, marine-certified, and acoustic-rated material for niche specifications. Japanese post-and-beam construction maintains demand for large-section traditional grades.
Structural grade absorbs the greatest volume; Appearance grade is gaining share fastest as premium interior finishes command widening price spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gabon and concession consolidation in Indonesia concentrate tropical hardwood flows, while Nordic timberland investment trusts and Brazilian plantation REITs channel institutional capital into fiber supply security.
United States
Mass timber construction codes in Oregon and Washington redirect Pacific Northwest sawlog demand toward cross-laminated timber feedstock specifications. The USDA Forest Service timber sale programs intersect with state-level carbon credit frameworks in California. The US South industrial cluster around Georgia and Alabama anchors domestic softwood lumber capacity expansion.
Brazil
Eucalyptus plantation expansion in Mato Grosso do Sul supplies pulp mills achieving superior fiber yield per hectare against northern temperate competitors. The Brazilian Forest Code enforcement through IBAMA satellite monitoring shapes concession compliance costs. Port infrastructure development in Santos and Paranaguá accelerates roundwood export velocity to Asian markets.
Russia
Taiga softwood harvesting in the Far East feeds Chinese sawmill demand despite EU Deforestation Regulation exclusion effects on European-bound flows. Rosleskhoz forest registry digitization intersects with export duty volatility in policy uncertainty. The Khabarovsk and Primorsky Krai logging contractor networks face diesel price surge compression on delivered log economics.
Indonesia
Tropical hardwood concession consolidation reduces traceability complexity for EU-bound plywood and veneer shipments. The Ministry of Environment and Forestry SVLK legality verification system intersects with FSC group certification backlogs for smallholder cooperatives. Kalimantan mills face consolidation pressure as European buyers demand chain-of-custody documentation.
Germany
Whitewood structural-grade demand from Austrian and domestic mass timber plants strains certified fiber availability in Bavarian and Baden-Württemberg forest regions. The EU Deforestation Regulation due diligence mandates through customs authorities in Hamburg and Bremen filter sourcing decisions. The Black Forest sawmilling cluster retools for engineered wood feedstock dimensions under long-term supply contracts.
Industrial Round Wood Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fiber procurement, processing scale, and end-market access. The vendor base stratifies into three tiers: integrated forest-to-mill operators controlling timberland and logistics, independent sawmillers dependent on spot market log purchases, and plantation managers supplying pulp-grade fiber under long-term offtake agreements. Strategic moves center on concession consolidation for traceability compliance and direct contracting with mass timber producers for supply security.
Among Nordic integrated operators, Stora Enso Oyj exemplifies the forest-to-mill archetype through extensive timberland holdings and direct logistics control. West Fraser Timber Co. Ltd. and Weyerhaeuser Company occupy positions as North American scale leaders with differentiated geographic footprints across western Canadian and US South fiber basins. These three represent the dominant competitive positioning vectors: Nordic sustainability certification integration, North American scale-driven cost leadership, and timberland REIT structural access to institutional capital.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Interfor Corporation |
| West Fraser Timber Co. Ltd. |
| Boise Cascade Company |
| Arauco |
| Weyerhaeuser Company |
| Sierra Pacific Industries |
| Georgia-Pacific LLC |
| Canfor Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FSC chain-of-custody holders and uncertified suppliers manifests in both delivered log premiums and procurement network configurations, as EU Deforestation Regulation due diligence mandates force buyers to segment sourcing relationships by traceability tier.
Pricing Analysis
Short lead-time premiums for certified structural-grade fiber command spreads over spot inventory in German and Austrian mass timber procurement, while contract-based long-term offtake agreements dominate Nordic and North American fiber flows. Price differentiation rests on certification tier and geographic delivery cost, with Baltic and Russian Far East suppliers facing compression from diesel surcharge volatility. Margins are tightening for uncertified Indonesian and Brazilian exporters as Hamburg and Rotterdam customs authorities enforce documentation timelines. Third-party logistics providers in e-commerce packaging show highest price sensitivity; engineered wood product manufacturers exhibit lowest.
Supply Chain Analysis
Workforce availability constraints in mechanized felling and log truck operations across Pacific Northwest and Baltic regions are compressing contractor networks and extending harvest-to-mill intervals. Supply concentrates in Brazil, Russia, and Indonesia for export flows, while the US South and Nordic regions anchor integrated domestic processing. Raw material dependencies span diesel fuel, steel cutting components, and adhesive formulations for engineered products. Single-source vulnerability runs through Brazilian eucalyptus plantations and Russian taiga softwood for Asian-bound volumes. Distribution runs through direct mill procurement, long-term fiber supply agreements, and consolidated concession structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Deforestation Regulation erects a cost-of-compliance moat that advantages incumbent certification holders while filtering marginal suppliers from European procurement channels.
For Market Incumbents: To counter certification audit backlog delays, accelerate FSC and PEFC group certification programs for smallholder cooperatives in Indonesia and consolidate concession holdings to reduce traceability complexity. Deploy backward integration into satellite-linked geofencing systems to automate harvest origin documentation for Rotterdam and Hamburg customs pre-declaration. For New Entrants and Emerging Players: Mass timber producers in Austria and British Columbia represent the most penetrable buyer segment given their 10-15 year supply security requirements for project finance. Target underpenetrated African hardwood concessions in Gabon and Congo for veneer and furniture stock flows to Asian markets. Pursue direct contracting archetypes with Japanese and South Korean biomass pellet offtakers under renewable portfolio standards. For Investors and Strategic Acquirers: Re-rating potential sits with integrated forest-to-mill operators given EU Deforestation Regulation enforcement creating certified fiber scarcity premiums. Long-term viability frames around timberland REIT structural access to institutional capital and concession consolidation synergies. Watch FSC chain-of-custody audit velocity as inflection indicator for supply security pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Consolidation | Reduces traceability complexity for EU Deforestation Regulation compliance in Indonesian and Brazilian supply bases. |
| Long-term Supply Agreement | Mass timber producers in Austria and British Columbia contract directly with forest owners for feedstock certainty. |
| Backward Integration | Sawmills deploy machine-learning bucking optimization and satellite geofencing to control fiber recovery and documentation. |
| Certification Investment | FSC and PEFC audit programs capture price premiums in German and French procurement under due diligence mandates. |
| Geographic Expansion | Chinese importers finance port infrastructure in Pointe-Noire to access underdeveloped Gabonese hardwood concessions. |
Research Methodology
Trade flow databases, forest service harvest statistics, and customs declaration records formed the secondary backbone, supplemented by primary interviews with sawmill procurement directors, logging contractor network managers, mass timber plant engineers, and certification audit body representatives. Bottom-up and top-down triangulation validated volume and value estimates across product type, end user, processing technology, and grade tier segmentation.
Bottom-up modeling anchored projections across the analysis window through log supply-demand balances by regional fiber basin, while top-down cross-checks incorporated macro construction activity indices and pulp capacity expansion timelines. CAGRs derived from segmented growth rate assumptions for lumber, wood chips, plywood, and logs against mass timber code adoption curves and e-commerce packaging throughput. Industry-specific inputs included EU Deforestation Regulation enforcement phase-ins and Japanese biomass co-firing mandate implementation.
Caveats apply where Russian export duty volatility, Indonesian smallholder certification backlogs, or Pacific Northwest harvest contractor retirement velocity could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement timelines and mass timber building code committee decisions. A small set of named triggers—diesel price surge compression, FSC audit capacity constraints, and Chinese port infrastructure financing velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Machined Seals Market
Industrial Materials
Modified Wood Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Noise Reduction Plastic Gear Market