
 Global Polycarbonate Sheets Market | 2026-2036
Global Polycarbonate Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polycarbonate Sheets Market Foresight
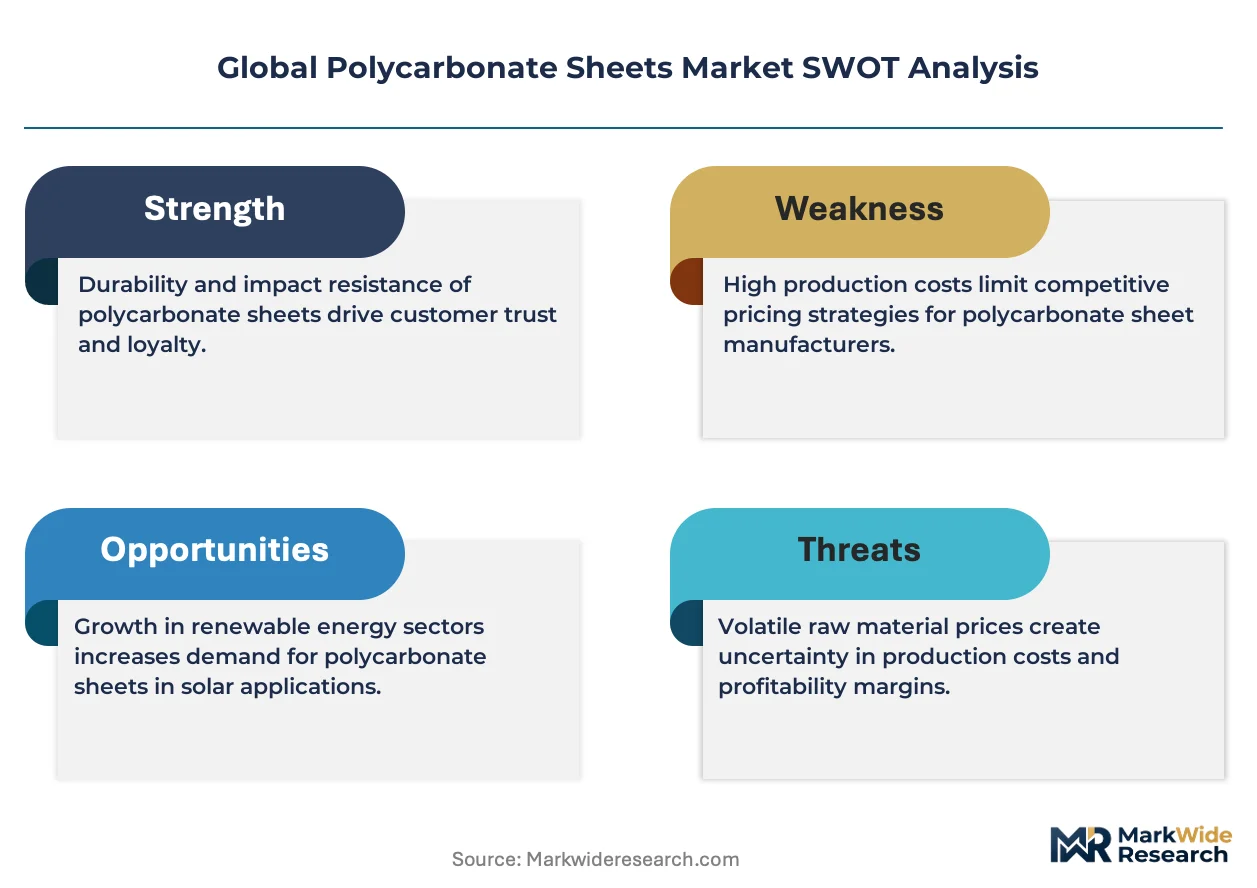
Performance-based coating and tinting subscription services is repositioning how polycarbonate sheet value gets captured in commercial construction. Covestro AG leverages its polymer science depth to sustain specification-grade supply chains across European facade projects. SABIC anchors Middle Eastern and Asian distribution through integrated resin-to-sheet manufacturing. Plazit Polygal Group specializes in agricultural greenhouse systems, competing on light-diffusion engineering rather than commodity tonnage.
Polycarbonate sheets are thermoplastic panels produced through extrusion of bisphenol A-derived resin, offering impact resistance up to 250 times that of glass alongside optical clarity tunable from transparent to diffused. Their primary commercial purpose spans protective glazing, architectural roofing, electronic display shields, and controlled-environment agriculture where weight reduction and thermal insulation converge. Multiwall sheet configurations command premium positioning in energy-efficient building envelopes, while solid sheets dominate safety and security barrier applications where ballistic or vandal resistance matters. Extrusion technology leads production scale, though thermoforming is gaining traction in complex-curve transportation and signage components.
REACH and RoHS frameworks in Europe restrict certain flame-retardant additives, pushing reformulation toward halogen-free chemistry that meets ECHA substance scrutiny. FDA food-contact and USDA greenhouse material standards in North America shape product certification pathways for agricultural and food-processing deployments. China's GB standards and MIIT industrial policy directives influence local production specifications and import substitution dynamics. Stakeholders must monitor evolving building code harmonization between EU Green Deal efficiency targets and national fire-safety regulations to anticipate specification shifts ahead of procurement cycles.
Market Dynamics
EU Green Deal building efficiency mandates are compressing specification timelines for polycarbonate sheet suppliers. REACH compliance deadlines force simultaneous reformulation of flame-retardant chemistry across multiple product lines.
Growth Catalysts
- Construction sector modernization:Lightweight glazing demand accelerates as Germany, China, and the United States advance infrastructure programs. Multiwall configurations capture premium positioning in energy-efficient envelopes.
- REACH and RoHS frameworks:Halogen-free chemistry requirements push technical differentiation among suppliers capable of ECHA-compliant reformulation. Certification barriers filter commoditized competitors.
- Controlled-environment agriculture:Greenhouse operators in arid climates specify light-diffusion engineering for crop yield optimization. Agricultural deployment outpaces conventional construction uptake in select Middle Eastern markets.
Market Restraints
- Bisphenol A feedstock volatility:Petrochemical input costs fluctuate with crude price cycles, compressing margin predictability for extrusion-dependent producers.
- Substitution threat from tempered glass:Safety glazing applications in high-visibility architectural projects occasionally revert to glass where optical perfection outweighs weight constraints.
- Supply concentration in resin production:Integrated polymer manufacturers control upstream bisphenol A supply, constraining independent sheet extruders' negotiating leverage.
Strategic Opportunities
- Performance-based coating subscriptions:Commercial construction clients seek tinting and UV-protection services decoupled from initial sheet purchase. Recurring revenue models capture lifetime value.
- India's agricultural infrastructure:Protected cultivation expansion under national horticulture missions creates demand for diffused-light greenhouse panels. Local production partnerships bypass import logistics.
- Transportation thermoforming:Complex-curve components for rail and aerospace interiors converge extrusion base stock with precision forming capabilities. Design integration contracts lock in multi-year supply.
Industry Challenges
- Halogen-free certification timelines:ECHA substance scrutiny extends product validation cycles. Laboratories face backlog in flame-retardant performance testing.
- Extrusion-to-thermoforming skill transfer:Workforce proficient in flat-sheet production requires retraining for three-dimensional forming operations. Technical education programs lag industry need.
- Building code harmonization friction:EU Green Deal efficiency targets conflict with national fire-safety regulations in multiple member states. Specification uncertainty delays procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polycarbonate Sheets Market |
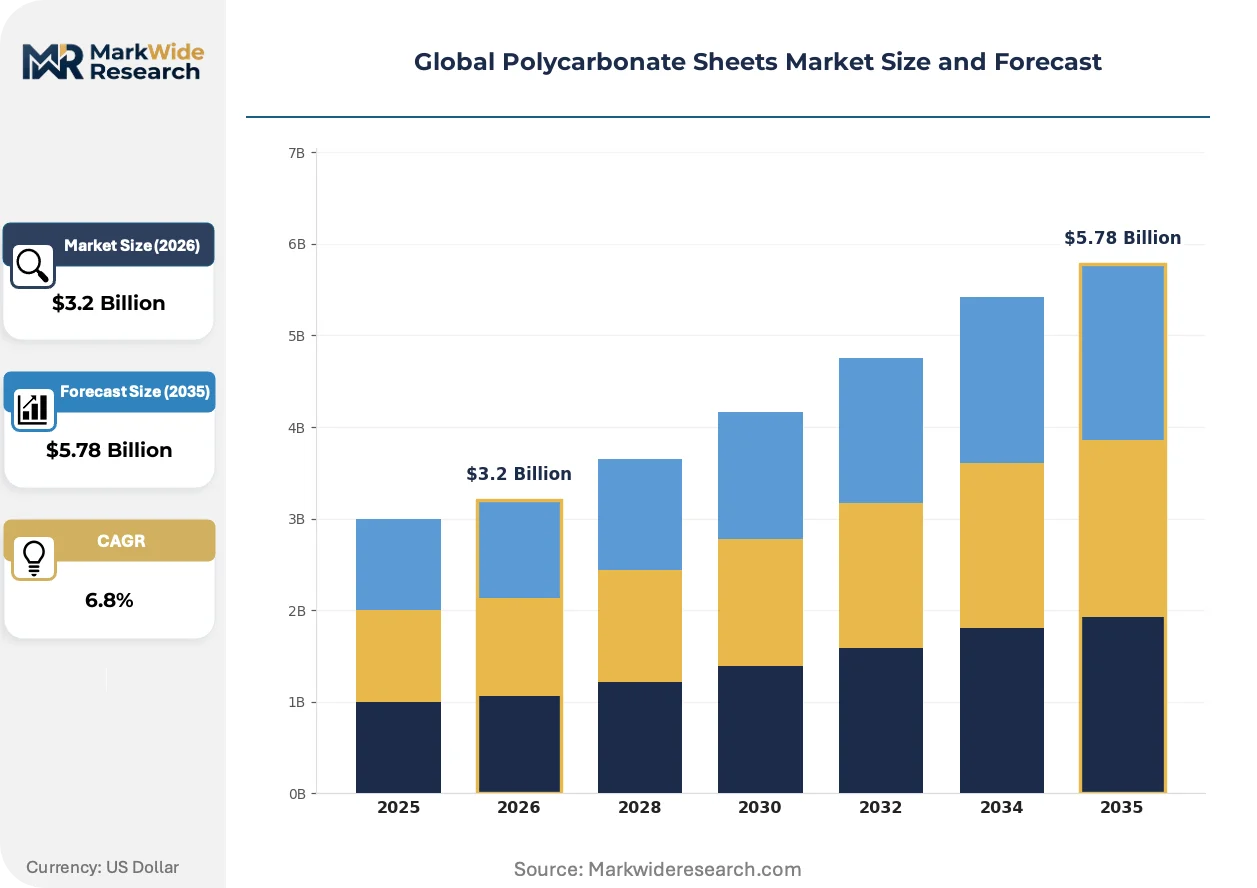
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Sheets, Multiwall Sheets, Corrugated Sheets, Embossed Sheets, Textured Sheets Technology: Extrusion, Injection Molding, Thermoforming, Calendering, Compression Molding Application: Construction, Electrical & Electronics, Transportation, Signage & Display, Agriculture End User: Manufacturers, Fabricators, Distributors, Retailers |
| Companies Covered | Palram Industries Ltd., Brett Martin Ltd., SABIC, 3A Composites GmbH, Trinseo S.A., Covestro AG, Plazit Polygal Group, Arla Plast AB, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polycarbonate Sheets Market Shifts & Advancements
Active coating technologies and digital specification tools are compressing traditional procurement cycles. Suppliers now compete on embedded service value rather than tonnage throughput alone.
Co-extruded UV-barrier layers are electrifying durability expectations for outdoor architectural applications. Façade engineers in Germany and the United Arab Emirates specify these multi-layer configurations for 25-year service life guarantees. The technology is compressing replacement cycles and shifting supplier selection criteria toward predictive performance modeling.
REACH authorization procedures for flame-retardant additives tighten substance scrutiny across European manufacturing. Reformulation toward phosphorus-based chemistry increases R&D allocation but opens specification access to public procurement. Agricultural greenhouse deployments face the steepest compliance cost adjustments.
Buyers increasingly unbundle sheet supply from installation and maintenance services. Commercial construction procurement teams in China negotiate performance guarantees separately from material purchase. This fragmentation pressures distributors to develop in-house technical service capabilities or cede margin to specialized contractors.
Global Polycarbonate Sheets Market Segmentation
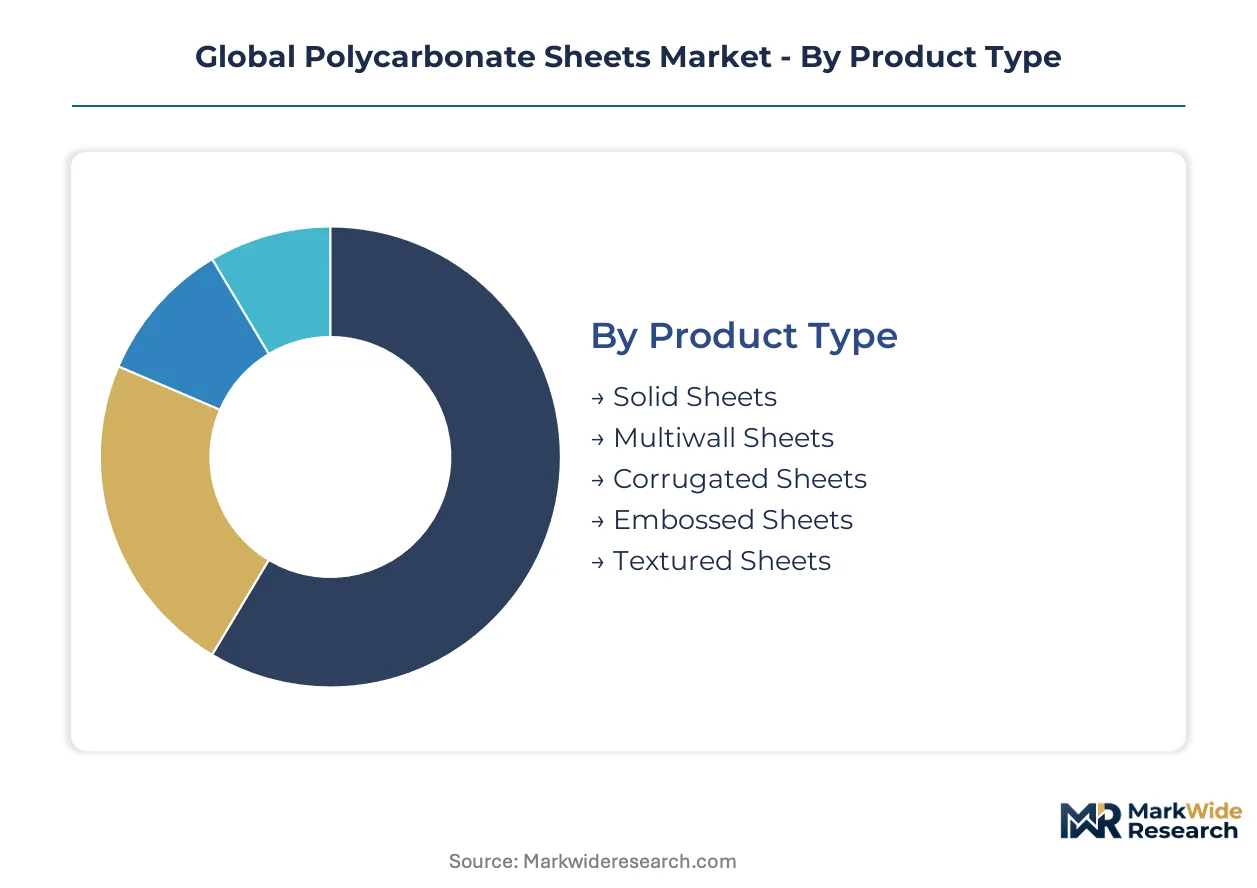
Polycarbonate sheet specifications diverge sharply across thermal performance, optical clarity, and forming complexity. Procurement teams select configurations based on load-bearing requirements, climate exposure, and downstream fabrication methods.
Product Type:
Standardization dominates commodity glazing while custom diffusion profiles command premium positioning in controlled-environment agriculture.
- Solid Sheets:Monolithic panels deliver maximum impact resistance for security barriers and machine guarding. German automotive suppliers specify these for transparent protective shields in assembly line automation. Ballistic-rated grades capture pricing premiums in embassy and financial institution glazing.
- Multiwall Sheets:Internal rib structures create insulating air chambers that reduce thermal transfer in building envelopes. Chinese infrastructure programs specify these for stadium roofing and transit shelter canopies where weight reduction intersects with energy code compliance. The configuration dominates European Green Deal retrofit specifications.
- Corrugated Sheets:Profiled geometry suits agricultural cladding and industrial roofing with simplified fastening requirements.
- Embossed Sheets:Surface patterning diffuses light transmission for privacy screens and decorative architectural elements.
- Textured Sheets:Matte finishes reduce glare in electronic display housings and interior partition systems.
Most installed capacity flows through Multiwall Sheets. Expansion is steepest in Solid Sheets.
Technology:
Volume scale concentrates in continuous extrusion while thermoforming captures margin in complex-curve transportation components.
- Extrusion:Continuous flat-sheet production achieves lowest unit costs through high-speed line operation. Covestro AG and SABIC operate integrated resin-to-sheet extrusion across Germany, China, and Saudi Arabia. The process dominates construction and agriculture volume.
- Thermoforming:Heat-and-vacuum shaping converts extruded base stock into three-dimensional components for rail interiors and aerospace cabin modules. UAE-based fabricators are expanding thermoforming capacity for Gulf region transportation projects.
- Injection Molding:Precision molding produces electronic device housings and optical lens components.
- Calendering:Roll-pressing achieves tight thickness tolerances for display and lighting applications.
- Compression Molding:Batch processing suits thick-section industrial parts and prototype development.
Extrusion retains the largest equipment base. Thermoforming is climbing the fastest as transportation OEMs source curved interior panels.
Application:
Construction absorbs standard grades while agriculture and transportation segments drive specification innovation.
- Construction:Façade glazing, skylights, and cladding systems specify multiwall and solid configurations based on thermal and structural requirements. German building efficiency mandates accelerate multiwall uptake in commercial envelope retrofits.
- Agriculture:Greenhouse operators in the Netherlands and Israel prioritize light-diffusion engineering over commodity pricing. Arid-climate protected cultivation in Saudi Arabia and the UAE specifies high-end diffused panels for crop yield optimization.
- Electrical & Electronics:Display shields and device housings demand optical clarity and flame-retardant compliance.
- Transportation:Rail and aerospace interiors specify thermoformed components for weight reduction.
- Signage & Display:Illuminated advertising and retail fixtures balance transparency with UV durability.
Construction commands the greatest volume throughput. Agriculture is gaining share fastest as protected cultivation expands in water-stressed regions.
End User:
Channel structure fragments between specification-direct manufacturers and service-oriented fabricators.
- Manufacturers:Integrated resin-to-sheet producers control formulation and extrusion scale. These entities supply specification-grade material directly to large construction and automotive OEMs.
- Fabricators:Cut-to-size and thermoforming specialists add dimensional customization and assembly services. Chinese and Indian fabricators are consolidating to offer bundled installation and maintenance contracts.
- Distributors:Inventory-holding intermediaries serve regional construction and agriculture markets with standard grades.
- Retailers:Hardware and building supply chains move commodity solid and corrugated sheets to small contractors and DIY end users.
Manufacturers and fabricators capture the greatest value-add. Distributors face margin compression as procurement teams unbundle material purchase from technical services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China pursue diverging paths in polycarbonate sheet deployment. German procurement teams prioritize multiwall configurations for envelope retrofits under EU Green Deal mandates. Chinese infrastructure programs favor solid and corrugated grades for rapid stadium and transit shelter construction.
United States
Commercial glazing contractors specify solid sheets for embassy and financial institution security barriers. FDA food-contact certification shapes agricultural greenhouse material selection in California's Central Valley. Midwest fabricators expand thermoforming capacity for rail interior components.
Germany
Façade engineers in Munich and Frankfurt specify co-extruded UV-barrier multiwall sheets for 25-year service guarantees. ECHA substance scrutiny under REACH authorization procedures drives phosphorus-based flame-retardant reformulation. Covestro AG anchors specification-grade supply chains from Leverkusen.
China
Stadium roofing and transit shelter canopies absorb multiwall sheet volume under MIIT industrial policy directives. GB standards influence local production specifications and import substitution dynamics. Yangtze River Delta extruders scale output for domestic infrastructure modernization.
Saudi Arabia
Arid-climate protected cultivation drives demand for high-end diffused-light greenhouse panels. SFDA and national building codes shape material certification for food-security projects. NEOM construction clusters specify lightweight cladding systems for energy-efficient envelopes.
India
National horticulture missions expand protected cultivation infrastructure across Maharashtra and Gujarat. BIS standards and PLI scheme incentives attract local production partnerships. Fabricators in Delhi-NCR consolidate to offer bundled installation contracts bypassing import logistics.
Global Polycarbonate Sheets Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Integrated resin-to-sheet producers control upstream bisphenol A supply and capture specification-grade positioning in European façade projects. Independent extruders compete on cut-to-size services and regional inventory proximity. Dominant competitive moves include backward integration into captive resin production and geographic expansion through distribution partnerships in water-stressed agricultural markets.
Among integrated polymer manufacturers, Covestro AG and SABIC exemplify contrasting geographic anchoring strategies. Covestro AG occupies a position within European specification-grade supply chains, while SABIC represents Middle Eastern and Asian distribution integration. Plazit Polygal Group sits within the agricultural specialization tier, competing on light-diffusion engineering rather than commodity tonnage scale.
| Leading Market Players |
|---|
| Palram Industries Ltd. |
| Brett Martin Ltd. |
| SABIC |
| 3A Composites GmbH |
| Trinseo S.A. |
| Covestro AG |
| Plazit Polygal Group |
| Arla Plast AB |
| Teijin Limited |
| Others |
Supply & Pricing Matrix
Bisphenol A resin costs transmit directly from petrochemical feedstock indices through to extrusion-dependent producers, with pricing tiers separating integrated polymer manufacturers from independent sheet extruders who absorb margin volatility without upstream hedging.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity multiwall and solid sheet grades. Three-tier pricing structure across specification-grade, standard construction, and economy agricultural levels separates Covestro AG and SABIC's premium positioning from regional extruders competing on cut-to-size services. Cost compression in economy tiers is intensifying because Yangtze River Delta producers scale output for domestic infrastructure programs. Agricultural greenhouse operators in India and Saudi Arabia exhibit the highest price sensitivity, while German façade engineers prioritize 25-year service guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and Saudi Arabia anchor hub-and-spoke patterns for construction and agriculture markets. Upstream bisphenol A production concentrates in Germany, China, and Saudi Arabia, drawing from crude-derived phenol and acetone inputs. Single-source vulnerability in flame-retardant additive supply creates exposure as ECHA substance scrutiny extends certification timelines. Distribution runs through specification-direct manufacturers for large OEMs and consolidated fabricators offering bundled installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement teams across German commercial construction now specify co-extruded UV-barrier multiwall sheets with predictive performance modeling rather than commodity tonnage.
For Market Incumbents: Deploy phosphorus-based flame-retardant reformulation to maintain REACH-compliant access to European public procurement. Deepen captive resin production control to offset bisphenol A feedstock volatility threatening margin predictability. Independent extruders without backward integration face displacement as integrated manufacturers scale specification-grade output. For New Entrants and Emerging Players: EU Green Deal building efficiency mandates in Germany open a window for thermoforming specialists serving rail and aerospace interior curves. India's protected cultivation expansion under national horticulture missions presents the most penetrable white-space, with local production partnerships bypassing import logistics and BIS certification complexity. Target design integration contracts with transportation OEMs seeking multi-year supply commitments. For Investors and Strategic Acquirers: Consolidation pressure builds where independent extruders lack REACH-compliant formulation capabilities and struggle with ECHA certification backlogs. Five-to-ten-year viability favors integrated resin-to-sheet producers with agricultural specialization or transportation thermoforming expertise. Watch halogen-free certification timelines as the inflection indicator—laboratory testing backlogs signal which mid-cap extruders face specification lockout.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol A | Covestro AG and SABIC secure captive feedstock supply against crude price cycles. |
| Phosphorus-Based Flame-Retardant Reformulation | ECHA-compliant chemistry unlocks European public procurement and Green Deal retrofit specifications. |
| Local Production Partnerships in India | BIS certification and PLI scheme incentives bypass import logistics for protected cultivation demand. |
| Thermoforming Capacity Expansion | UAE fabricators capture Gulf region rail and aerospace interior component contracts. |
| Performance-Based Coating Subscriptions | Commercial construction clients unbundle tinting and UV-protection services from initial sheet purchase. |
Research Methodology
Direct dialogue with plant managers at extrusion facilities, procurement leads at construction OEMs, distribution channel partners, and technical R&D directors grounded qualitative assessment in operational reality. Secondary validation drew from customs and trade data, SEC 10-K filings of listed polymer manufacturers, Cefic industry reports, and ECHA substance authorization databases. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across product configurations.
Market value outputs trace from extrusion line throughput assumptions through regional pricing differentials across the analysis window. Segmentation dimensions modeled include sheet configuration type, end-use industry, thermal performance tier, and regional regulatory cluster. CAGRs derive from historical demand elasticity analysis projected against infrastructure program announcements and building code adoption timelines. Bisphenol A feedstock cost indices and ECHA authorization schedules served as primary forecast inputs.
Revisions become necessary when ECHA extends flame-retardant substance scrutiny timelines, when crude price volatility disrupts phenol-acetone input costs, or when EU member states diverge on Green Deal fire-safety harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Couplings Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Wire Mesh Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
Global Melamine Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Industrial Gaskets Market