
 Uncoated Fine Paper Market | 2026-2036
Uncoated Fine Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Uncoated Fine Paper Market Analytics
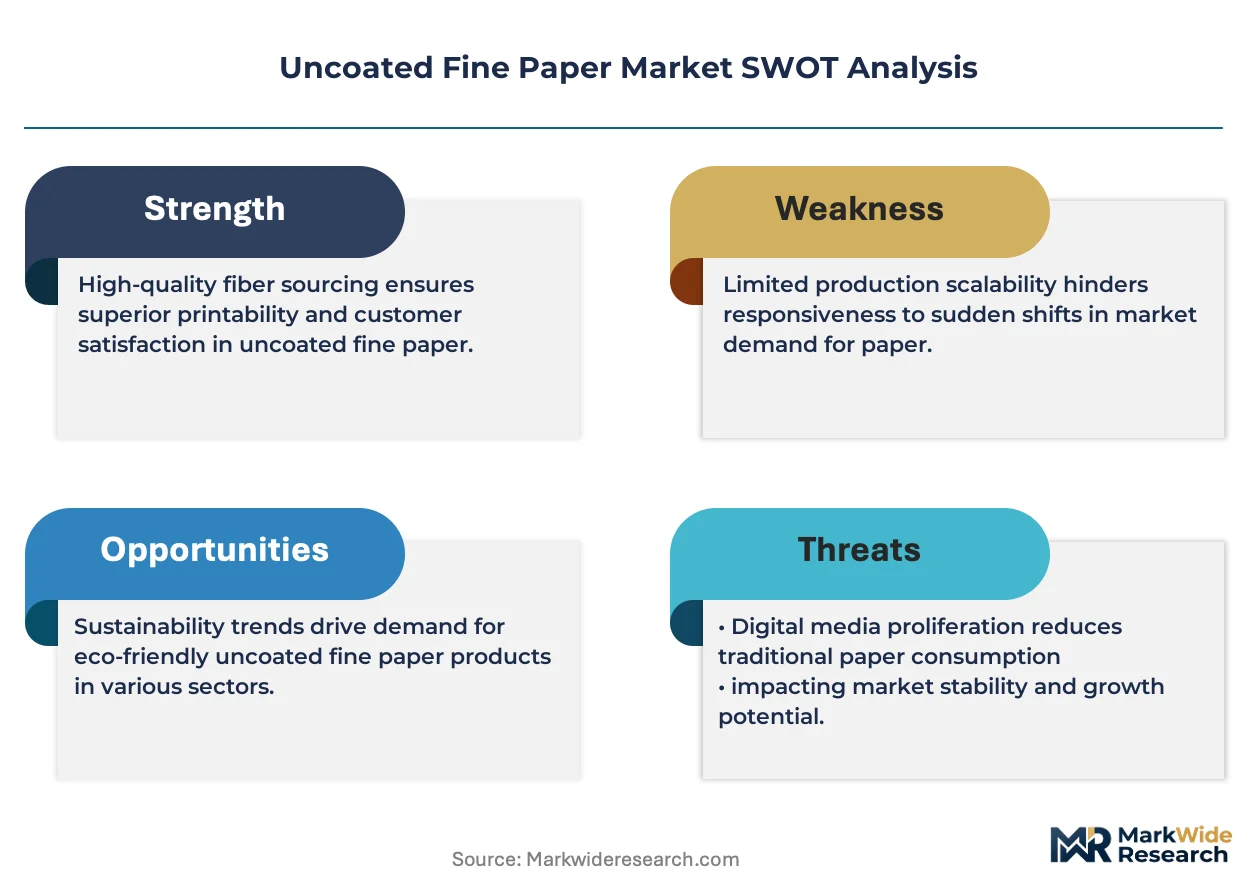
Corporate procurement departments is bifurcating from traditional publishing houses as the dominant volume buyers of uncoated fine paper. International Paper Company leverages its North American pulp integration to sustain cost-advantaged positions in bond and writing grades. UPM-Kymmene Corporation anchors its competitive stance through controlled forestry certification and specialized print paper production for European corporate clients. Stora Enso Oyj differentiates via bioproduct mill integration, converting wood residues into co-products alongside uncoated fine paper output.
Uncoated fine paper consists of woodfree or mechanical pulp sheets without mineral coating, typically manufactured in basis weights from 60 to 120 gsm on Fourdrinier or gap-former machines for high ink absorption in laser and inkjet printing. The product serves commercial printing, business correspondence, and educational publishing where surface texture and writability outweigh gloss requirements. Bond paper occupies the mature core of the market, sustaining steady replacement demand from legal and financial documentation workflows. Specialty paper represents the fastest-growing product category, capturing margin pools from archival, security, and premium stationery applications where fiber purity and caliper precision command price premiums. Writing paper competes with digital alternatives in education segments, though notebook and stationery applications in the arts end-user category retain resilient physical-format loyalty.
The EU Green Deal and EUDR timber regulation reshape pulp traceability requirements for mills supplying European corporate buyers, while EPA emissions standards govern US manufacturing facility permits and effluent discharge limits. FSC and PEFC chain-of-custody certification has become a de facto market access condition for tenders from multinational corporate and education sector purchasers. Stakeholders must monitor how digital workflow penetration in corporate communications interacts with sustainability-driven paper premiumization to determine volume and mix strategies.
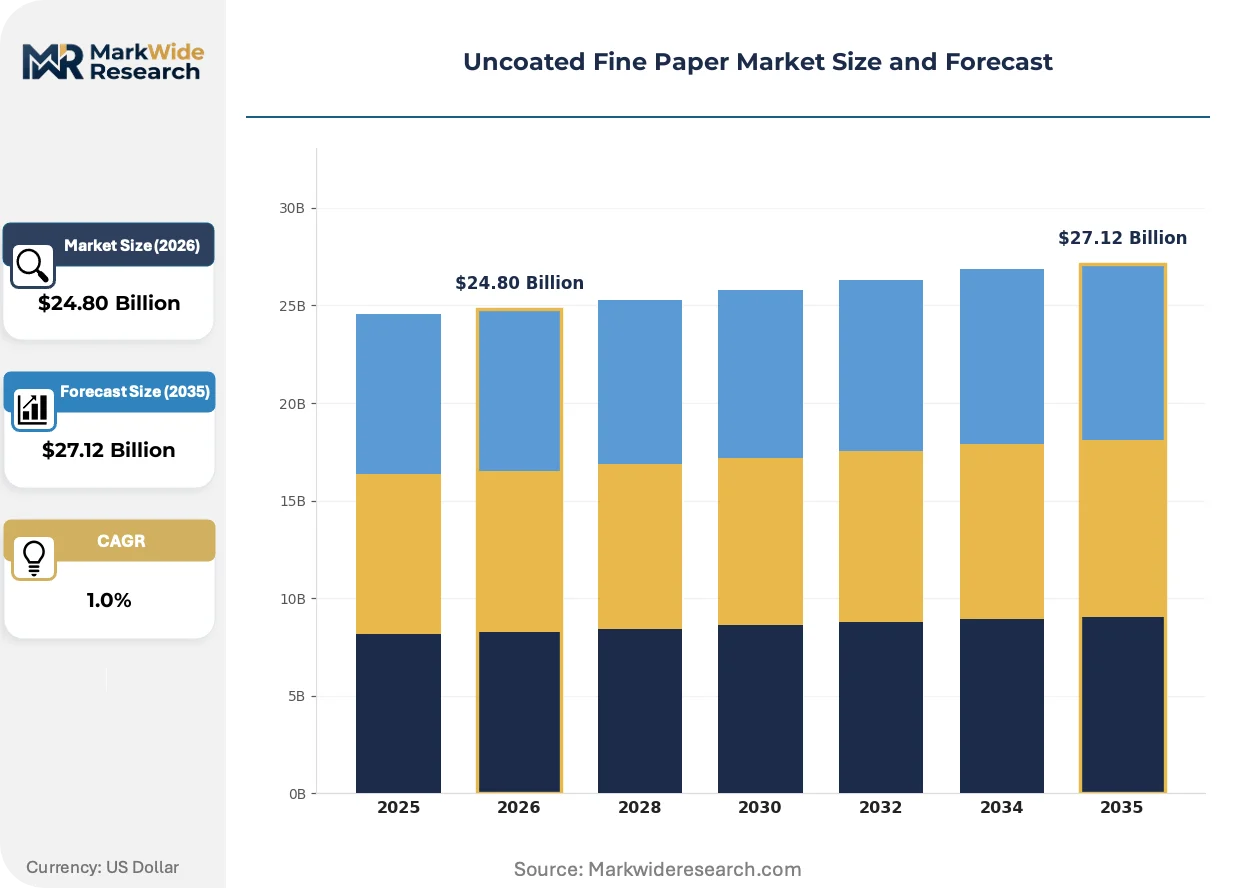
Market Dynamics
Corporate procurement departments are bifurcating from traditional publishing houses as dominant volume buyers, while EU Green Deal compliance timelines force mills to restructure pulp sourcing strategies and certification portfolios.
Growth Catalysts
- EUDR timber traceability mandates:European mills investing in chain-of-custody systems capture tenders from multinational corporate buyers requiring documented sustainable sourcing.
- Specialty paper applications:Archival, security, and premium stationery segments command price premiums where fiber purity and caliper precision differentiate suppliers.
- German printing clusters:Above-average per-capita consumption of uncoated fine grades in corporate documentation workflows sustains replacement demand for bond and writing papers.
Market Restraints
- Mechanical pulp cost volatility:Energy-intensive refining processes expose margins to electricity price swings in Nordic and Central European mill locations.
- Digital workflow substitution:Electronic documentation platforms compress volume in legal and financial correspondence segments historically dependent on physical bond paper.
- FSC certification friction:Small and mid-sized mills face capital barriers to achieving chain-of-custody accreditation required for education sector tenders.
Strategic Opportunities
- Bioproduct mill integration:Converting wood residues into lignin, tall oil, and bioenergy co-products alongside uncoated fine paper output diversifies revenue streams.
- Arts and stationery loyalty:Notebook and premium writing applications retain resilient physical-format demand from creative professionals and gift markets.
- EPA emissions compliance:US facilities achieving effluent discharge limits ahead of enforcement timelines position for corporate buyer preference shifts.
Industry Challenges
- Fourdrinier machine reconfiguration:Legacy gap-former and Fourdrinier assets require substantial capital to adapt basis weight ranges for specialty grade production.
- Chain-of-custody audit complexity:Multinational corporate tenders demand simultaneous FSC and PEFC certification maintenance across integrated pulp and paper operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncoated Fine Paper Market |
| Market Size in 2026 | $24.80 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bond Paper, Print Paper, Writing Paper, Specialty Paper End User: Publishing, Education, Corporate, Arts Thickness: Lightweight, Standard, Heavyweight, Extra Heavyweight Application: Books, Stationery, Notebooks, Brochures |
| Companies Covered | International Paper Company, UPM-Kymmene Corporation, Stora Enso Oyj, Domtar Corporation, Mondi Group, Sappi Limited, Oji Holdings Corporation, Nippon Paper Industries Co., Ltd., WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncoated Fine Paper Market Evolving Landscape
Digital workflow penetration intersects with sustainability-driven paper premiumization to reshape volume and mix strategies across mill portfolios.
Digital printing compatibility formulations are fragmenting traditional uncoated fine paper specifications. Laser and inkjet-optimized surface treatments now command dedicated production runs. Commercial print shops in Germany and France are adopting these grades at accelerated replacement cycles. This technology is fragmenting the historical uniformity of bond paper specifications into application-specific performance tiers.
EU Green Deal carbon border adjustments are restructuring pulp import economics. Mills sourcing from non-EU timber suppliers face additional documentation burdens and cost layers. European corporate procurement departments are responding by consolidating volumes toward mills with controlled forestry certification and EU-sourced fiber.
Corporate sustainability scorecards now weight paper procurement decisions. Multinational buyers are unbundling historical bundled supply contracts to source certified grades through direct mill relationships. This behavioral shift is most visible in German financial services and professional services verticals where ESG reporting requirements elevate supply chain transparency.
Uncoated Fine Paper Market Segmentation
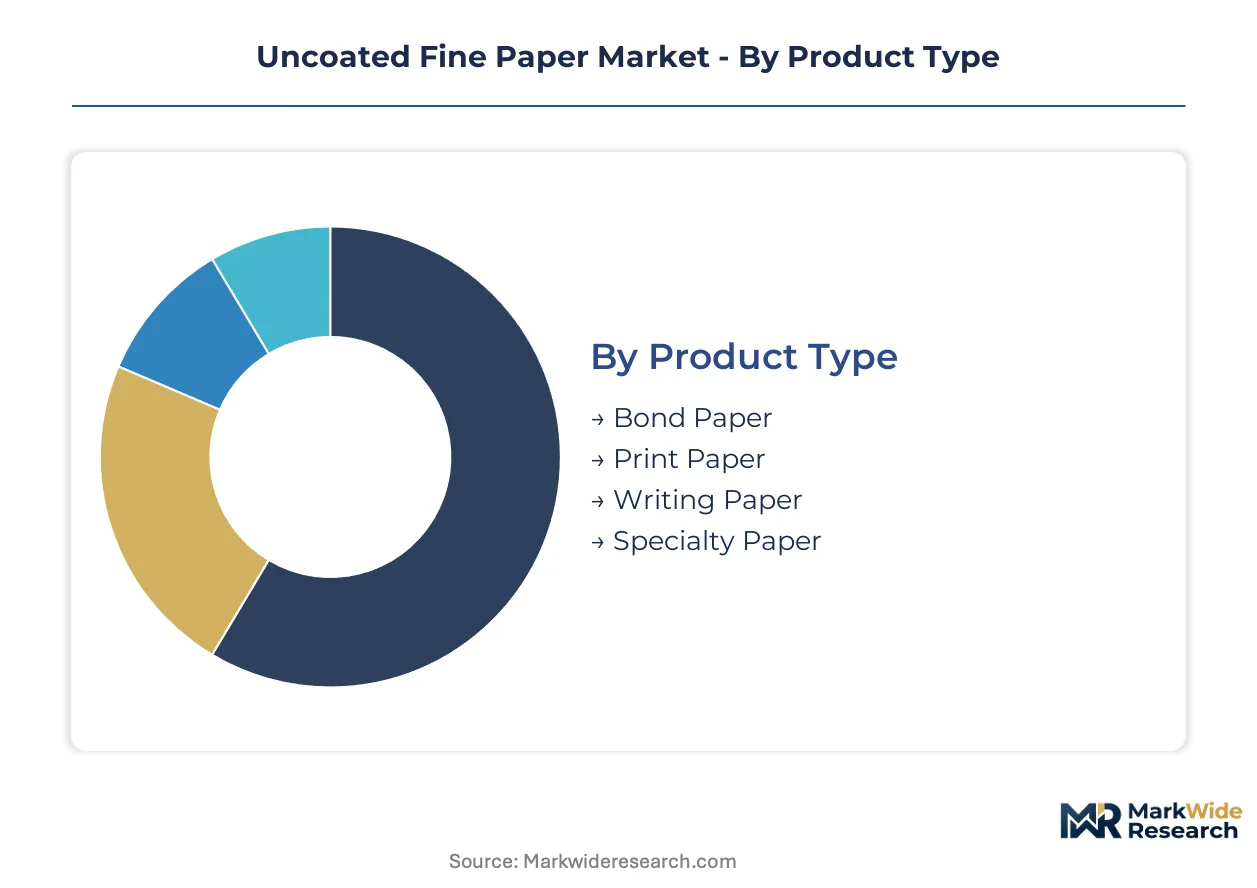
Segmentation in uncoated fine paper reveals divergent sourcing strategies across procurement channels. Corporate buyers prioritize certified bond and specialty grades while education and arts segments sustain demand for writing papers and premium stationery weights.
Product Type:
Domestic consumption concentrates bond and writing grades in German and French corporate clusters, while specialty and print papers flow disproportionately toward export-led premium channels in Nordic markets.
- Bond Paper:Woodfree pulp sheets in 60-90 gsm basis weights serve laser printing and financial documentation workflows. German legal services and insurance sectors in Frankfurt and Munich sustain above-average per-capita consumption despite digital encroachment.
- Specialty Paper:Archival, security, and premium stationery grades command price premiums through fiber purity and caliper precision. EU Green Deal procurement mandates are redirecting multinational corporate tenders toward FSC-certified specialty producers with controlled forestry documentation.
- Print Paper:Uncoated woodfree sheets optimized for high ink absorption in commercial offset applications.
- Writing Paper:Mechanical and woodfree blends for fountain pen and ballpoint compatibility in education and correspondence.
Bond paper commands the established base. The steepest expansion runs through specialty paper.
End User:
Cost tier stratification separates premium-certified corporate procurement from price-sensitive education bulk purchasing.
- Corporate:Procurement departments unbundle historical supply contracts to source certified grades through direct mill relationships. ESG reporting requirements in German financial services elevate supply chain transparency to tender prerequisites.
- Education:Bulk purchasing of writing and notebook grades faces compression from digital textbook platforms. Notebook and stationery applications in arts curricula retain resilient physical-format loyalty against tablet substitution.
- Publishing:Commercial print houses in Paris and Milan sustain demand for uncoated fine grades in illustrated books and catalogs.
- Arts:Creative professionals and gift markets drive premium caliper specifications for sketchbooks and archival portfolios.
Corporate procurement commands the established base. The steepest expansion runs through arts applications.
Thickness:
Application requirements dictate weight selection across documentation, publishing, and premium stationery channels.
- Standard:70-90 gsm weights dominate corporate correspondence and educational workbooks. German DIN standards and US EPA-labeled procurement specifications converge on this midpoint for laser printer compatibility.
- Heavyweight:100-120 gsm grades serve premium letterhead, certificates, and archival documentation. EU Green Deal carbon border adjustments favor EU-sourced fiber in heavyweight production for reduced documentation burdens.
- Lightweight:60-70 gsm for high-volume internal correspondence and religious text printing.
- Extra Heavyweight:Above 120 gsm for art papers, presentation folders, and luxury packaging inserts.
Standard weight commands the established base. The steepest expansion runs through heavyweight grades.
Application:
Volume concentration in books and stationery contrasts with margin concentration in premium notebook and brochure specifications.
- Stationery:Letterhead, envelopes, and correspondence cards sustain replacement demand in German professional services. FSC and PEFC chain-of-custody certification has become de facto market access for multinational corporate tenders.
- Notebooks:Premium bound journals and sketchbooks retain resilient physical-format loyalty from creative professionals. Moleskine-style brands and independent stationery houses in Milan and Copenhagen drive specification innovation.
- Books:Trade paperbacks and educational texts face volume pressure from digital distribution platforms.
- Brochures:Marketing collateral demand fluctuates with corporate advertising cycles and sustainability-driven print reduction policies.
Stationery commands the established base. The steepest expansion runs through notebooks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish and Swedish mills export uncoated fine grades to German corporate buyers under EU Green Deal compliance frameworks. This trade corridor concentrates premium specialty volumes while North American producers supply bond paper to US financial services clusters.
Germany
Frankfurt and Munich legal services sustain above-average per-capita consumption of bond paper for documentation workflows. EUDR timber traceability mandates redirect procurement toward FSC-certified domestic and Nordic suppliers. The Rhine-Main printing cluster maintains specialized commercial print capacity for corporate correspondence grades.
United States
New York and Chicago financial services drive replacement demand for heavyweight bond paper in legal documentation. EPA emissions standards govern effluent discharge limits at manufacturing facilities in the Southeast and Pacific Northwest. The Mid-Atlantic corridor concentrates corporate procurement decision-making for certified sustainable grades.
Finland
Nordic pulp integration supports cost-advantaged positions in specialty and print paper exports. EU Green Deal carbon border adjustments favor controlled forestry certification for European corporate tenders. The Kymi River industrial zone anchors bioproduct mill operations converting wood residues into co-products.
Japan
Tokyo and Osaka corporate headquarters sustain demand for premium writing papers and archival grades. METI industrial standards govern paper quality specifications for official documentation. The Kanto region concentrates stationery distribution networks serving creative professional segments.
France
Paris commercial print houses sustain demand for uncoated fine grades in illustrated books and luxury catalogs. REACH chemical regulations influence surface treatment formulations for inkjet-optimized papers. The Île-de-France region hosts specialized finishing operations for premium stationery exports.
Uncoated Fine Paper Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The market structure consolidates around integrated pulp-and-paper groups with controlled forestry assets, while mid-sized regional mills occupy specialty niches. Three archetypes dominate: Nordic bioproduct-integrated majors, North American scale-driven producers, and Asian precision-grade specialists. Competitive moves concentrate on bioproduct mill conversion and direct corporate procurement relationships bypassing traditional distribution.
Among Nordic integrated groups, International Paper Company, UPM-Kymmene Corporation, and Stora Enso Oyj exemplify the bioproduct-integrated archetype. These entities anchor competitive positioning through captive pulp supply and controlled forestry certification. International Paper represents North American scale advantages in bond paper production. UPM-Kymmene occupies a position linking Finnish fiber resources to European corporate sustainability procurement. Stora Enso exemplifies the bioproduct mill model converting process residues into lignin and bioenergy co-products alongside uncoated fine paper output.
| Leading Market Players |
|---|
| International Paper Company |
| UPM-Kymmene Corporation |
| Stora Enso Oyj |
| Domtar Corporation |
| Mondi Group |
| Sappi Limited |
| Oji Holdings Corporation |
| Nippon Paper Industries Co., Ltd. |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
Mechanical pulp displacement by woodfree alternatives in German corporate procurement is simultaneously concentrating supply geography around Nordic integrated mills and compressing pricing power among Central European mechanical producers unable to absorb electricity cost volatility.
Pricing Analysis
Fourdrinier machine generation gaps separate pricing tiers across legacy gap-former assets, modern hybrid configurations, and next-generation bioproduct-integrated lines. Three-tier pricing structure across FSC-certified specialty, standard bond, and economy writing grades reflects certification investment recovery and fiber purity differentials. Pricing pressure stems from digital workflow substitution in legal documentation segments. Education bulk purchasers exhibit highest price sensitivity while German financial services procurement departments prioritize certified grades over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate corporate procurement behavior as EUDR compliance timelines force advance fiber documentation and certification verification before tender participation. Pulp supply concentrates in Finland, Sweden, and Germany where controlled forestry certification anchors mill competitiveness. Production draws from woodfree pulp, mechanical pulp, and lignin co-product streams. Single-source vulnerability runs through Nordic pulp integration dependencies for European specialty grades. Distribution runs through direct mill relationships bypassing traditional merchant channels for multinational corporate buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through unbundled supply contracts as multinational procurement departments bypass distributors for direct mill relationships with documented chain-of-custody certification.
For Market Incumbents: Compound certification portfolio depth to capture EUDR-compliant tender volumes from corporate procurement departments consolidating supplier bases. Deepen captive pulp supply through controlled forestry asset expansion in Finland and Sweden. Accelerate bioproduct mill conversion to lignin and tall oil co-production before electricity cost volatility erodes mechanical pulp margins. For New Entrants and Emerging Players: Lead with specialty archival and security paper specifications where fiber purity requirements create defendable margin pools against commodity bond paper competition. Target arts and stationery segments in Milan and Copenhagen where premium caliper specifications retain physical-format loyalty against digital substitution. Pursue direct relationships with independent stationery houses and creative professional distributors rather than corporate procurement channels. For Investors and Strategic Acquirers: The market sits at a sustainability-premium phase that favors bioproduct-integrated majors with captive fiber supply and FSC certification infrastructure. Long-term viability over the next decade hinges on conversion flexibility between uncoated fine paper and biochemical co-product streams. Acquisition candidates should demonstrate EU Green Deal compliance positioning and direct corporate procurement relationships. Watch EUDR enforcement stringency as the inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Bioproduct Mill Conversion | Lignin and tall oil co-production diversifies revenue beyond commoditized bond paper at Finnish integrated sites. |
| Controlled Forestry Certification | FSC chain-of-custody accreditation secures access to multinational corporate tenders under EU Green Deal procurement mandates. |
| Direct Mill Relationship Development | Bypassing merchant channels captures margin from procurement departments unbundling historical supply contracts in Germany. |
| Specialty Grade Capacity Reconfiguration | Fourdrinier machine adaptation for archival and security specifications commands price premiums in premium stationery channels. |
| EUDR Compliance Infrastructure | Timber traceability systems position mills for carbon border adjustment advantages over non-EU pulp competitors. |
Research Methodology
Cross-validation between primary mill operator interviews and secondary trade flow data anchors the qualitative findings on pulp sourcing strategy shifts. Conversations with corporate procurement managers, commercial print house operators, paper merchant distribution heads, and forestry certification auditors combined with customs records, EU ETS emissions disclosures, and FSC chain-of-custody databases. Bottom-up volume estimates from grade-level production data triangulate against top-down demand modeling from end-use sector consumption patterns.
Sensitivity analysis on electricity price trajectories and digital substitution rates frames the analytical approach across the projection horizon. Segmentation dimensions include product type, end-user vertical, basis weight tier, and application channel with regional regulatory cluster overlays. CAGRs derive from historical volume trend extrapolation adjusted for structural breakpoint identification. Forecast inputs incorporate EUDR compliance timeline phasing and corporate sustainability scorecard weighting evolution in procurement decisions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated digital workflow penetration would require recalibration. Forecasts reflect documented assumptions on certification adoption curves and pulp cost pass-through elasticity. Revision becomes warranted when EUDR documentation burden thresholds trigger supplier consolidation beyond modeled rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Americas Stone Paper Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
North America Thermal Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Woodfree Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Greaseproof Paper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Plywood Market
Paper Products
Paper Doilies Market
Paper Products
Global Thin Papers Market