
 Self Locking Nuts Market | 2026-2036
Self Locking Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Self Locking Nuts Market Intelligence
The dependency on an aging cohort of precision machinists with deep metallurgical expertise is unwinding as automation and digital twinning technologies enter production floors. Nord-Lock International AB leverages its proprietary wedge-locking technology to secure a premium position in high-vibration applications. Bossard Group differentiates through its comprehensive smart factory logistics and engineering services. Penn Engineering specializes in fastening solutions for the electronics and automotive sectors, providing customized components for compact assemblies.
Self-locking nuts, also known as locknuts, are fasteners designed to resist loosening under conditions of vibration and torque. Their functionality relies on features like a nylon insert, a deformed thread profile, or a serrated flange that creates friction against the mating bolt. Stainless steel variants command a significant share due to corrosion resistance, essential for construction and marine applications. Within product types, insert nuts see increased use in aerospace assemblies where component integrity is paramount.
Product quality and performance are governed by stringent standards, including FAA regulations for aerospace components in the United States and CE marking requirements in Europe for construction products. Conformance to ISO and JIS standards is also critical for market access in industrial sectors across Japan and other developed economies. Navigating the material qualification process for new alloys and composites will be a central challenge for manufacturers seeking to serve next-generation vehicle and aircraft platforms.
Market Dynamics
The imperative to reduce vehicle and aircraft weight without compromising joint integrity under extreme vibration is the central structural force in the self-locking nuts market. This creates a direct tension between material science innovation and the stringent, non-negotiable safety certification frameworks.
Growth Catalysts
- Aerospace Modernization:Demand from the aerospace sector for fasteners that resist loosening in high-vibration engine and airframe environments, driven by fleet upgrades and new aircraft programs, provides a primary catalyst.
- Automotive Electrification:The transition to electric vehicles, particularly in manufacturing hubs like Germany and Japan, necessitates specialized locking nuts for battery pack assemblies and motor mounts where vibrational security is critical.
- Stricter Building Codes:Heightened safety standards in the construction industry, including CE marking requirements in Europe, mandate the use of certified high-performance locknuts for critical structural steel and infrastructure connections.
Market Restraints
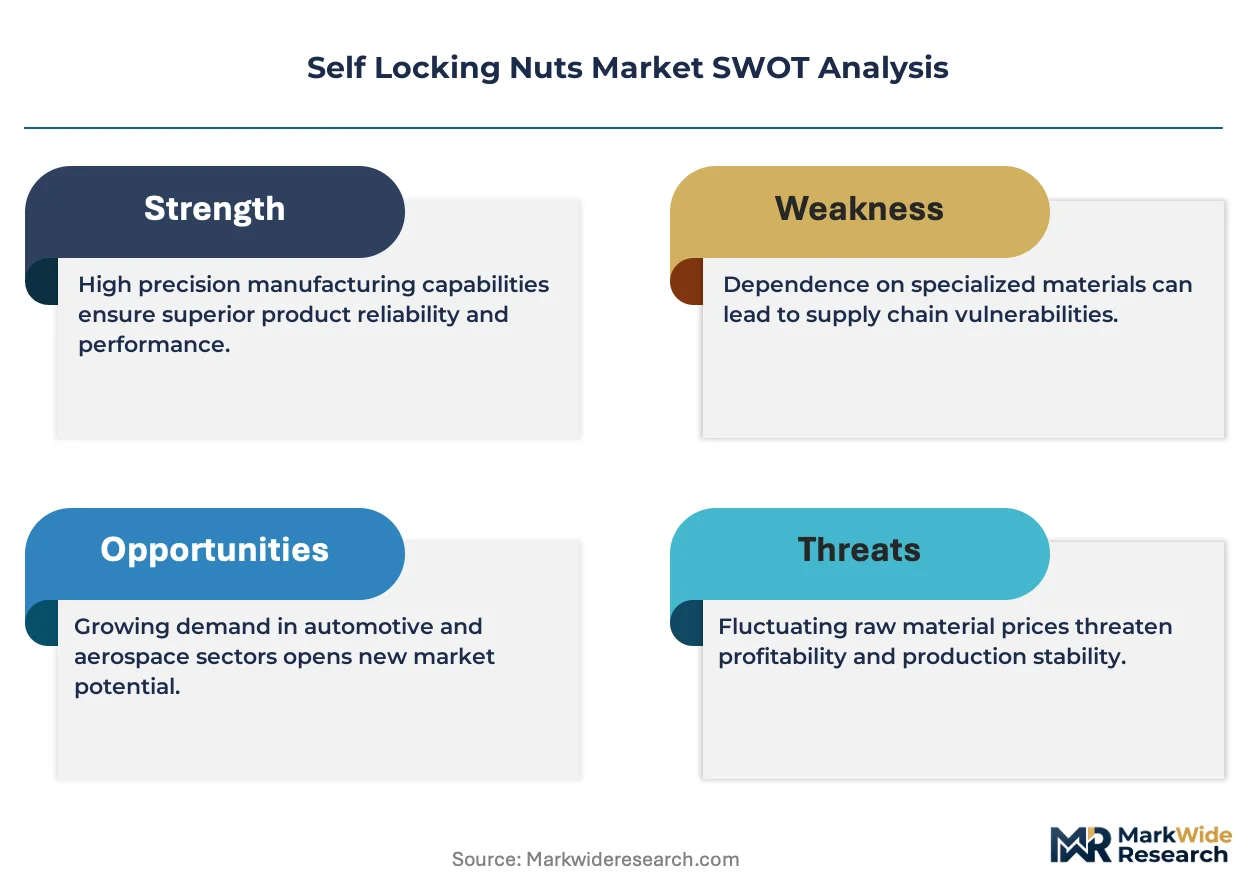
- Raw Material Cost Volatility:The price and availability of high-performance materials such as titanium, nickel alloys, and high-grade stainless steel are subject to global supply chain fluctuations, impacting production costs.
- Threat from Chemical Adhesives:In non-critical, lower-stress applications, liquid thread-locking compounds present a lower-cost and easier-to-apply substitution threat, limiting market penetration in some industrial assembly segments.
- Complex Qualification Processes:Introducing new materials or designs requires lengthy and expensive qualification and certification against standards from bodies like the FAA or KBA, creating a barrier to rapid innovation.
Strategic Opportunities
- Renewable Energy Infrastructure:The global expansion of wind energy presents an opportunity for large-diameter, high-strength locknuts for securing turbine blades, towers, and foundations against constant operational stress and environmental factors.
- Smart Fastener Development:Integrating miniature sensors into locknuts to create "smart bolts" that can monitor preload and structural integrity in real-time opens new applications in critical infrastructure and aerospace.
- Medical Device Miniaturization:The demand for miniature, biocompatible self-locking fasteners for use in surgical instruments and orthopedic implants represents a high-margin niche, particularly with materials like medical-grade stainless steel.
Industry Challenges
- Precision Machining Skills Gap:A shrinking pool of experienced precision machinists and metallurgists poses a challenge to producing complex, tight-tolerance locknuts, especially those made from exotic alloys.
- Standardization Across Composites:The lack of universal standards for fastening into new composite materials forces manufacturers to develop and validate bespoke solutions for each unique application, increasing engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Locking Nuts Market |
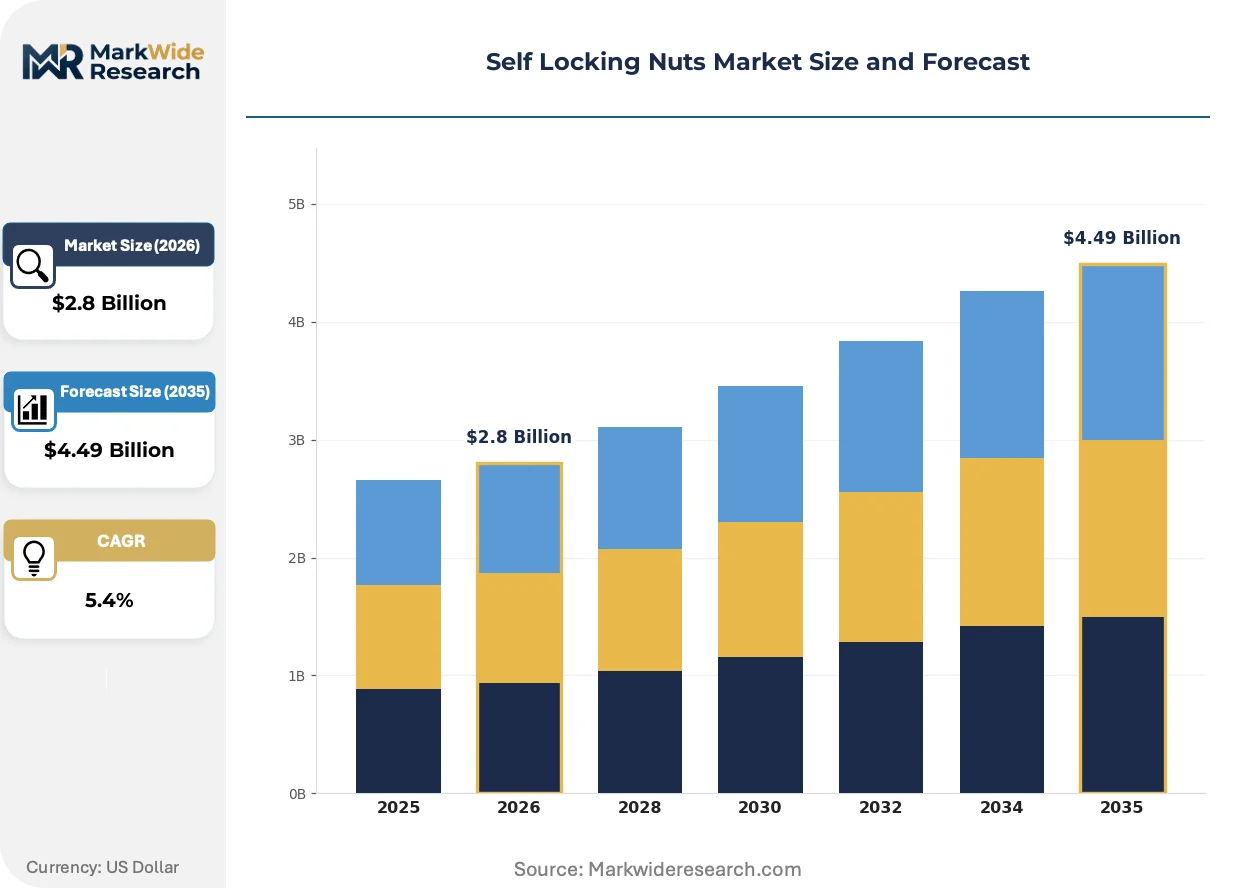
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hexagonal, Round, Square, Insert Material: Stainless Steel, Nylon, Brass, Aluminum Application: Aerospace, Automotive, Construction, Electronics End User: Manufacturers, Distributors, Retailers, Aftermarket Providers |
| Companies Covered | Bossard Group, Penn Engineering, Nord-Lock International AB, Würth Industrie Service, HARD LOCK INDUSTRY CO., LTD., Accu Limited Company, National Bolt & Nut Corp., Chin Hsing Precision Industry Co., Ltd, Huyett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Locking Nuts Market Strategic Shifts & Innovations
The convergence of digital manufacturing technologies with advanced material science is redefining fastener performance. This shift moves the value proposition from a simple component to an engineered system integral to asset reliability and safety, especially in high-consequence applications.
Digital twinning allows for the creation of virtual models of fastened joints. Aerospace and automotive engineers are adopting this technology to simulate performance under vibration, thermal cycling, and torque loads before any physical parts are made. This advanced simulation capability is supplanting reliance on costly and time-consuming physical prototyping, dramatically accelerating the validation of new designs.
European Union regulations, particularly the CE marking framework for construction products, are formalizing performance and traceability requirements. This mandate compels manufacturers to provide extensive documentation and verified data on tensile strength, corrosion resistance, and locking performance for fasteners used in structural applications. Compliance is essential for market access, impacting producers in the United States and Japan who export to the region.
A clear behavioral change is evident as major OEMs shift from transactional component purchasing to forming strategic supply partnerships. These relationships prioritize suppliers that offer integrated engineering services, vendor-managed inventory, and smart factory logistics over those competing solely on unit price. This trend is most pronounced in the German automotive sector, where supply chain optimization is a core competitive strategy.
Self Locking Nuts Market Segmentation
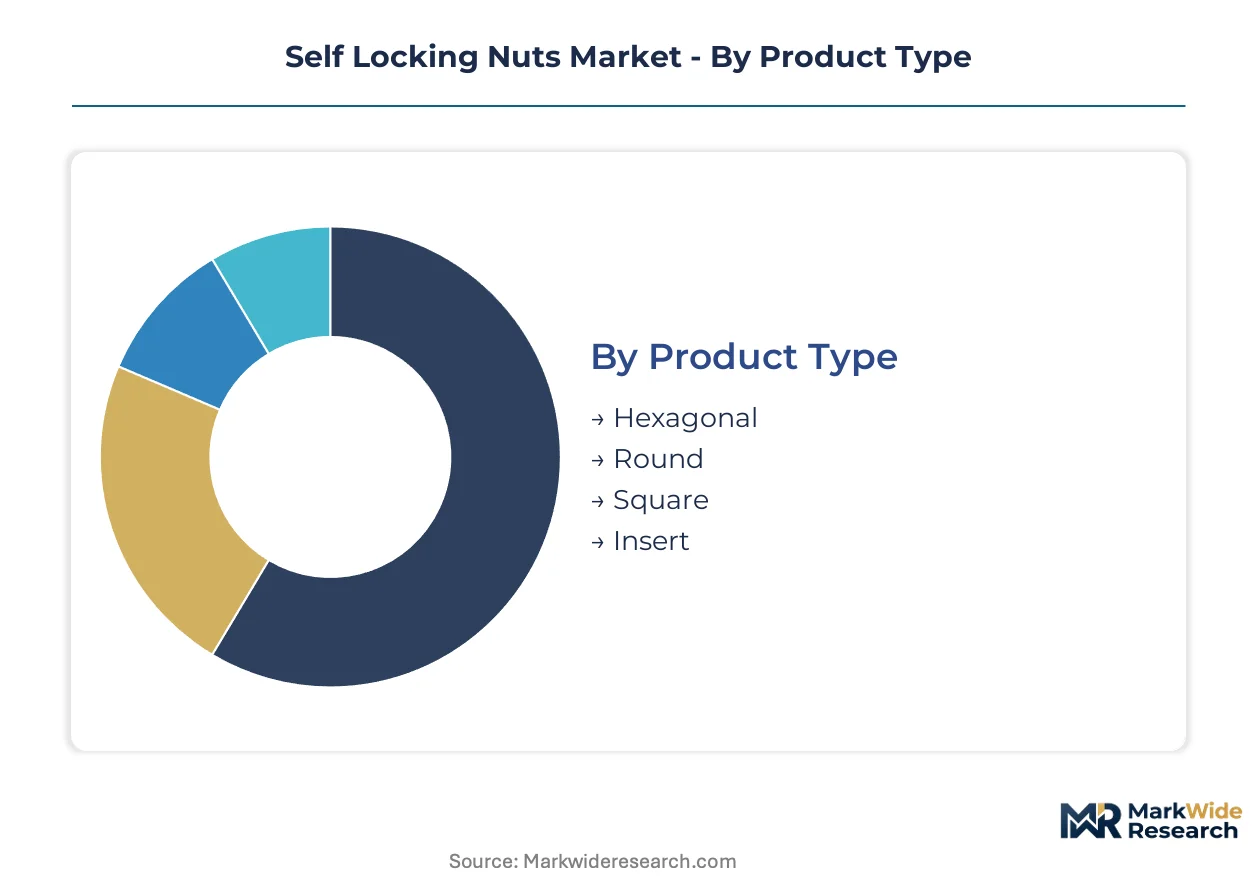
The self-locking nuts market segments across diverse product types, materials, applications, and end-users, reflecting varied engineering demands and supply chain structures. Understanding these distinct segments provides clarity on where demand originates and how specialized solutions are integrated into complex systems.
Product Type:
The distribution channels for self-locking nuts vary significantly based on product type, influencing procurement strategies across industries.
- Hexagonal:These standard fasteners feature six sides, providing multiple wrenching positions for easy installation and removal. Demand for hexagonal self-locking nuts is concentrated in general industrial machinery and construction, where high-volume, reliable connections are essential.
- Insert:Insert nuts incorporate a non-metallic (often nylon) or metallic element that deforms around the bolt threads, creating friction and preventing loosening. Aerospace assemblies and critical automotive components increasingly rely on insert nuts for paramount component integrity under severe vibration.
- Round:Round self-locking nuts typically offer a lower profile and are often used in applications where space is constrained or aesthetic considerations are present. Their use is common in consumer electronics and certain specialized machinery.
- Square:Square nuts provide a larger bearing surface than hexagonal nuts, often used in conjunction with square-headed bolts in heavy-duty structural applications. Construction projects and agricultural equipment frequently utilize square self-locking nuts.
Hexagonal nuts dominate the installed base for general industrial applications. Insert nuts are where engineering innovation and high-performance expansion concentrates.
Material:
Material selection for self-locking nuts is primarily driven by the specific application environment, dictating performance requirements and cost structures.
- Stainless Steel:Stainless steel variants offer superior corrosion resistance and strength, making them indispensable in harsh environments like marine, chemical processing, and outdoor construction. Demand for stainless steel locknuts remains robust in infrastructure projects requiring long-term durability.
- Nylon:Nylon is frequently used for the insert element in self-locking nuts, providing excellent vibration resistance and electrical insulation. Automotive battery pack assemblies and consumer electronics utilize nylon-based solutions for their lightweight properties and secure fastening.
- Brass:Brass self-locking nuts provide good corrosion resistance and electrical conductivity, making them suitable for electrical and plumbing applications. They are also valued for their aesthetic qualities in certain consumer goods.
- Aluminum:Aluminum locknuts offer a significant weight advantage, crucial for aerospace and high-performance automotive applications where mass reduction is critical. Their use is expanding in next-generation vehicle platforms.
Stainless steel maintains a strong presence due to its inherent corrosion resistance. Nylon is gaining share fastest in weight-sensitive and electrical applications.
Application:
Demand volume for self-locking nuts is heavily influenced by the end-use application, with specific sectors dictating fastener specifications and certification needs.
- Aerospace:The aerospace sector demands fasteners with extreme resistance to vibration, fatigue, and temperature fluctuations for engine mounts, airframe structures, and control systems. FAA regulations mandate highly certified self-locking nuts for flight safety and component reliability.
- Automotive:Automotive applications, particularly in electric vehicles, require specialized self-locking nuts for battery packs, motor mounts, and chassis components to withstand constant vibration and thermal cycling. German and Japanese automotive manufacturers prioritize secure fastening solutions for vehicle performance.
- Construction:The construction industry utilizes self-locking nuts for critical structural connections in bridges, buildings, and infrastructure projects, ensuring stability and safety. CE marking requirements in Europe drive the adoption of certified high-performance locknuts.
- Electronics:Miniature self-locking fasteners are crucial in electronics for securing compact assemblies and preventing loosening under operational vibration. Consumer electronics and industrial control systems are key end-users.
Aerospace applications demand the most stringent performance standards. Automotive electrification represents the steepest expansion trajectory for specialized solutions.
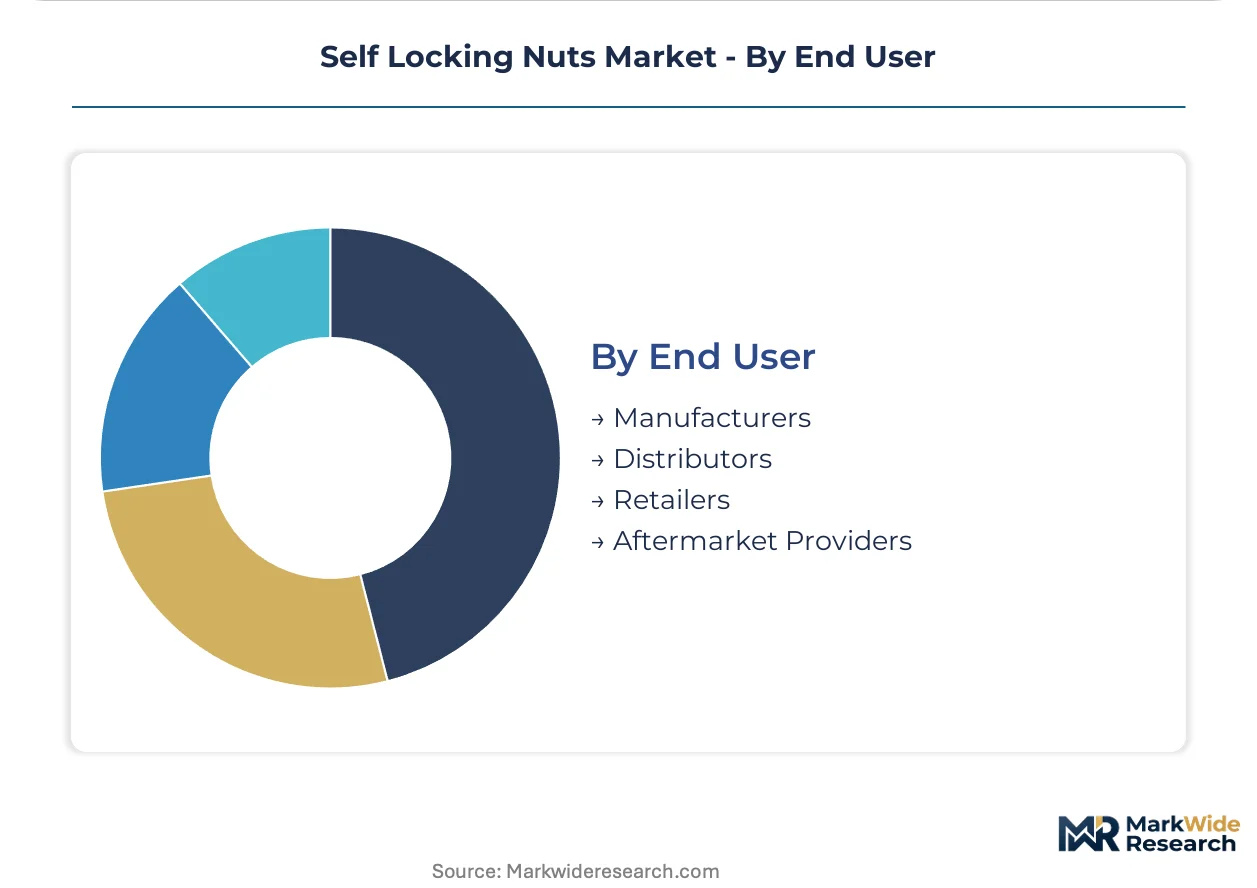
End User:
The type of end-user dictates the purchasing volume and service requirements for self-locking nuts, ranging from large-scale OEM procurement to individual aftermarket sales.
- Manufacturers:Original equipment manufacturers (OEMs) in aerospace, automotive, and heavy machinery represent the largest direct purchasers, integrating self-locking nuts into their production lines. Their procurement emphasizes long-term contracts and technical support.
- Distributors:Distributors serve as intermediaries, supplying a wide range of self-locking nuts to various industrial clients, smaller manufacturers, and maintenance operations. They offer inventory management and logistical support.
- Retailers:Retailers cater to smaller businesses, DIY enthusiasts, and general repair needs, offering a selection of common self-locking nut types. Their focus is on accessibility and convenience.
- Aftermarket Providers:Aftermarket providers supply replacement parts for repair and maintenance across diverse industries, ensuring operational continuity for existing equipment. This segment requires broad product availability and quick delivery.
Manufacturers account for the largest direct procurement volumes. Aftermarket providers are experiencing strong growth in replacement and repair markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA regulations in the United States anchor demand for high-performance self-locking nuts in the aerospace sector. This market requires fasteners capable of extreme vibration resistance and component integrity. Automotive electrification also drives demand for specialized solutions in battery pack assemblies.
United States
Aerospace modernization and fleet upgrades drive demand for self-locking nuts in the United States. FAA regulations mandate rigorous testing and certification for all fasteners used in aircraft components. The Seattle aerospace cluster and Detroit's automotive manufacturing centers are key areas for advanced locknut adoption.
Germany
German automotive manufacturers require specialized self-locking nuts for electric vehicle battery packs and motor mounts. KBA standards for vehicle safety and performance influence fastener selection in critical applications. The Stuttgart region, a hub for automotive engineering, concentrates demand for these advanced components.
Japan
Japanese industrial sectors, particularly automotive and electronics, seek high-precision self-locking nuts for compact assemblies. JIS standards ensure product quality and interchangeability across various manufacturing processes. The Tokyo metropolitan area, with its robust electronics and automotive supply chains, sees significant demand.
China
Chinese infrastructure projects and a rapidly expanding electric vehicle production base necessitate large volumes of self-locking nuts. GB standards dictate performance requirements for construction and automotive fasteners. The Yangtze River Delta region, a major manufacturing and construction hub, consumes substantial quantities.
United Kingdom
UK construction standards, including those influenced by CE marking requirements, drive the adoption of certified high-performance locknuts for structural integrity. Aerospace component manufacturing in regions like the Southwest also contributes to demand for specialized fasteners. London's infrastructure development and aerospace clusters require reliable fastening solutions.
Self Locking Nuts Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the self-locking nuts market. This structure supports both high-volume standardized products and bespoke engineered solutions. Strategic archetypes include premium technology providers, comprehensive service integrators, and niche application specialists. Technology innovation and strategic partnerships are dominant competitive moves.
Specialists in advanced fastening solutions include Nord-Lock International AB, which leverages its proprietary wedge-locking technology for high-vibration applications. Bossard Group differentiates through comprehensive smart factory logistics and engineering services. Penn Engineering exemplifies a focus on customized components for compact assemblies within the electronics and automotive sectors.
| Leading Market Players |
|---|
| Bossard Group |
| Penn Engineering |
| Nord-Lock International AB |
| Würth Industrie Service |
| HARD LOCK INDUSTRY CO., LTD. |
| Accu Limited Company |
| National Bolt & Nut Corp. |
| Chin Hsing Precision Industry Co., Ltd |
| Huyett |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing scale economies in standard hexagonal nuts drive supply concentration among major players and establish competitive price floors. This dynamic contrasts sharply with specialized, low-volume applications.
Pricing Analysis
Significant geographic price spreads exist for self-locking nuts, influenced by regional certification requirements like FAA standards in the United States and CE marking in Europe. The dominant pricing structure for high-performance applications is contract-based long-term offtake, while transactional per-unit sales serve general industrial needs. Price differentiation stems from material grade, such as titanium versus stainless steel, and the level of customization for specific assemblies. Pricing softness in standard product categories results from intense competition and raw material cost fluctuations. Aerospace and medical device manufacturers exhibit low price sensitivity, prioritizing performance, while construction and general industrial buyers are highly price-sensitive.
Supply Chain Analysis
Germany and Japan anchor the production of high-precision self-locking nuts for advanced automotive and electronics sectors. China contributes substantial volumes of standard and mid-range fasteners for infrastructure projects and its expanding electric vehicle market. The supply chain for self-locking nuts draws from critical raw materials including high-grade stainless steel, titanium, and specialized nylon inserts. Raw material cost volatility represents a significant structural risk, impacting production economics globally. Distribution runs primarily through direct OEM procurement for large-scale projects and a network of specialized distributors for MRO and smaller industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-locking nuts market presents a fragmentation opportunity, driven by the shift towards advanced lightweight composites in automotive and aerospace manufacturing. This evolution creates specialized niches for innovative fastening solutions.
For Market Incumbents:
Compound existing advantages by investing heavily in digital twinning capabilities and advanced material qualification for new alloys. Nord-Lock International AB can leverage its wedge-locking technology to address new composite fastening challenges. Strategic partnerships with major OEMs, particularly in the German automotive sector, will mitigate the threat from chemical adhesives in high-stress applications. Deepening engineering services capabilities, similar to Bossard Group, enhances customer stickiness and reinforces premium positioning.
For New Entrants and Emerging Players:
Expedited certification pathways, such as securing CE marking for construction products, offer a viable entry point for new manufacturers. Focus on underserved, high-margin niches like miniature biocompatible fasteners for medical devices or large-diameter locknuts for renewable energy infrastructure. Developing smart fastener solutions with integrated sensors represents a white-space target. A go-to-market angle emphasizing customized solutions for specific composite material applications, rather than generic products, can capture early market share.
For Investors and Strategic Acquirers:
Niche technology providers specializing in advanced materials or smart fastening solutions represent attractive acquisition targets for long-term growth (5-10 year window). These firms often possess unique intellectual property or critical certification expertise. Penn Engineering's focus on customized components highlights the value of specialized engineering capabilities. A signal to watch is the increasing R&D spending by major aerospace and automotive OEMs on next-generation fastening methods. Investing in companies with robust material qualification processes for new vehicle platforms offers significant upside.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Smart Fasteners | Integrating sensors into locknuts enables real-time monitoring of structural integrity in critical aerospace applications. |
| Advanced Material Qualification | Securing FAA and KBA certifications for new alloys expands market access for next-generation vehicle platforms. |
| Strategic OEM Partnerships | Collaborating with German automotive manufacturers ensures early integration into electric vehicle battery pack designs. |
| Expansion into Renewable Energy | Developing large-diameter, high-strength locknuts addresses the growing demand from wind turbine infrastructure projects. |
| Digital Twinning Capabilities | Simulating fastened joint performance under extreme conditions accelerates product validation and reduces physical prototyping costs. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. Interviews were conducted with aerospace engineers, automotive procurement leads, construction project managers, and material scientists. Secondary data sources included FAA regulations, CE marking documentation, ISO and JIS standards, and industry association reports. A robust bottom-up and top-down triangulation approach ensured data consistency and accuracy across all market segments.
Sensitivity analysis underpins the quantitative forecasts, modeling market dynamics over the projection horizon. The analytical framework segmented the market by product type, material, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected demand drivers, and expert consultations. Key industry-specific forecast inputs included new aircraft program schedules and electric vehicle production forecasts across Germany and Japan.
Decision-makers should treat outputs as directional under current raw material pricing and regulatory stability assumptions; material deviation would warrant model refresh. Forecasts reflect a comprehensive understanding of market forces at the time of analysis. Geopolitical trade disruptions or significant shifts in aerospace safety standards represent specific risk factors. Recalibration cycles align with material shifts in these named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Steel Cord Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Extruders Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Argon Knife Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Industrial Round Wood Market