
 United States Graphite Electrodes Market | 2026-2036
United States Graphite Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Graphite Electrodes Market Intelligence
Aftermarket electrode refurbishment and technical service revenue is tilting toward suppliers with captive needle coke production. GrafTech International leverages its vertical integration into petroleum needle coke to secure raw material cost advantages. Graphite India Limited anchors its U.S. presence through specialized ultra high power product lines tailored to domestic EAF operators. Tokai Carbon competes by sustaining long-term supply contracts with major steel producers across the Midwest and Southeast.
Graphite electrodes are cylindrical carbon conductors manufactured from petroleum needle coke and coal tar pitch binder, then baked to temperatures exceeding 2,400 degrees Celsius to achieve the electrical conductivity and thermal shock resistance required for steel melting operations. Their primary commercial purpose is to conduct the massive electrical currents—ranging from 35,000 to 140,000 amperes—that generate arc temperatures sufficient to melt scrap steel in electric arc furnaces. Ultra high power electrodes command the dominant margin pool due to their superior current-carrying capacity and extended campaign life in demanding EAF operations. The electric arc furnace application segment leads volume absorption as domestic steelmakers continue retiring blast furnace capacity in favor of lower-emission melting routes.
EPA enforcement under the Clean Air Act shapes electrode demand by penalizing integrated mill emissions and incentivizing EAF conversion, while OSHA workplace exposure limits affect handling protocols and protective equipment requirements at U.S. steel facilities. NHTSA fuel economy standards indirectly support electrode demand by stimulating domestic electric vehicle steel consumption, which EAF producers increasingly supply. Stakeholders must monitor the pace of EPA carbon intensity rules and corresponding state renewable energy mandates that determine the economics of scrap-based steelmaking versus competing primary production methods.
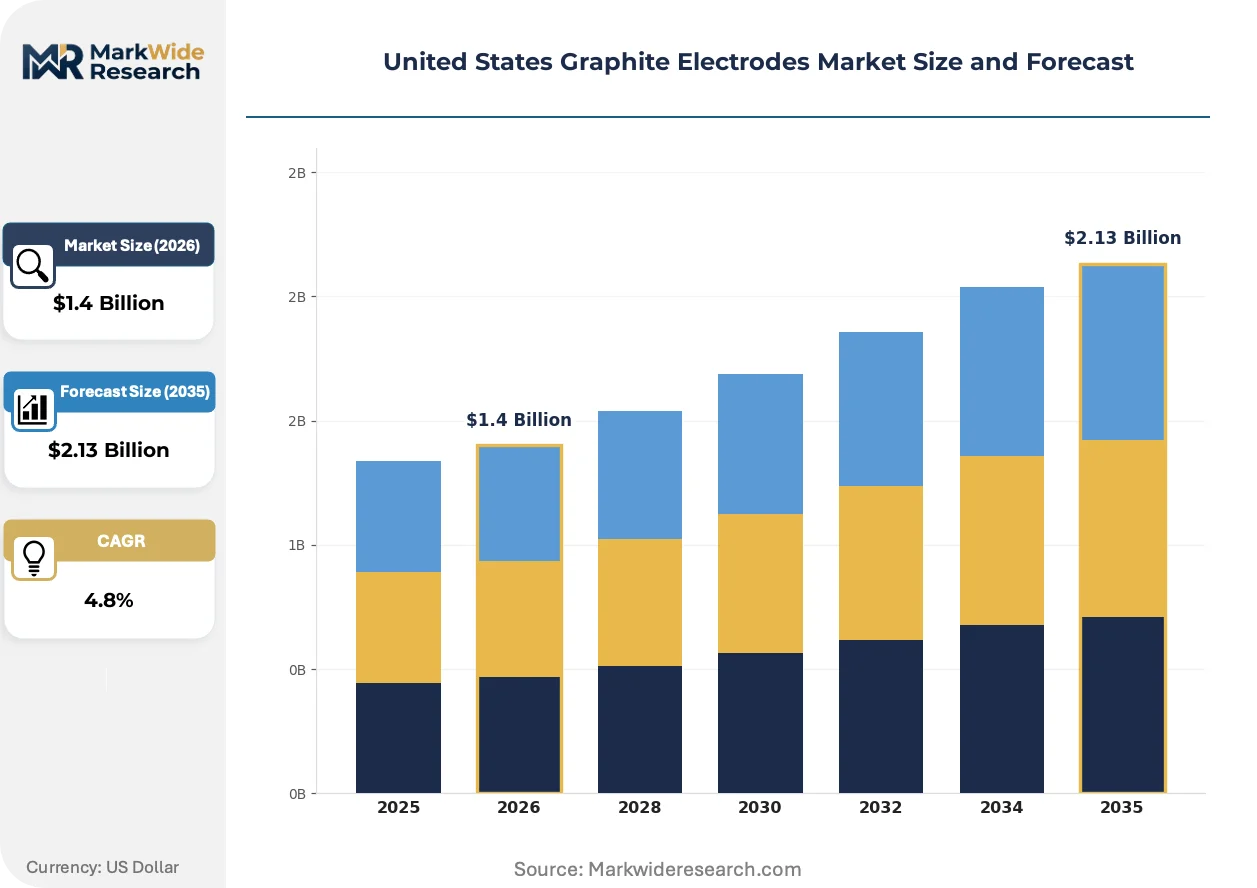
Market Dynamics
EPA carbon intensity rules and corresponding state renewable energy mandates are compressing the economics of blast furnace steelmaking while amplifying electric arc furnace adoption. This regulatory pressure is concentrating electrode demand around the Great Lakes industrial corridor where scrap availability and port infrastructure align.
Growth Catalysts
- EPA Clean Air Act enforcement:Penalties on integrated mill emissions accelerate EAF conversion timelines across Ohio, Indiana, and Pennsylvania steel corridors.
- Domestic mini-mill capacity expansion:Steel producers in Texas, Alabama, and Arizona are commissioning new electric arc furnace complexes requiring ultra high power electrode supply.
- Petroleum needle coke supply security:Captive production of this critical raw material insulates electrode manufacturers from import volatility and price spikes.
Market Restraints
- Petroleum needle coke cost volatility:Feedstock prices fluctuate with oil refining economics and decarbonization-driven coker unit closures.
- Chinese supply concentration:A limited cohort of Asian producers controls global needle coke export volumes, creating import dependency exposure.
- Graphitization furnace capacity limits:Achieving 2,400°C baking temperatures requires specialized equipment with multi-year lead times for expansion.
Strategic Opportunities
- Ohio River Valley EAF clustering:Kentucky and West Virginia locations offer combined scrap access, power grid capacity, and barge logistics for new steel capacity.
- NHTSA fuel economy standards:Electric vehicle steel consumption stimulates demand for EAF-produced flat products serving automotive stamping operations.
- Electrode refurbishment services:Technical service revenue pools expand as steelmakers seek campaign life extension through tip rethreading and surface conditioning.
Industry Challenges
- Graphite machining specialist scarcity:CNC programming and precision turning skills for large-diameter electrode manufacturing face generational workforce gaps.
- OSHA silica exposure compliance:Workplace monitoring and respiratory protection requirements add operational complexity to electrode handling and installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Graphite Electrodes Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra High Power, High Power, Regular Power, Intermediate Power End User: Steel Manufacturers, Foundries, Aerospace, Automotive Application: Electric Arc Furnace, Steel Melting, Casting, Secondary Metallurgy Form: Round, Square, Hexagonal, Custom Shapes |
| Companies Covered | GrafTech International, Graphite India Limited, HEG Limited, Tokai Carbon, Showa Denko K.K., Fangda Carbon New Material, Resonac Holdings Corporation, SGL Carbon SE, Nippon Carbon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Graphite Electrodes Market Strategic Shifts & Innovations
Digital process controls and predictive maintenance systems are penetrating electrode manufacturing and EAF operations simultaneously. These converging innovations compress downtime and reshape supplier-customer technical service relationships.
Needle coke blending algorithms paired with real-time graphitization furnace monitoring are virtualizing quality assurance in electrode production. U.S. EAF operators are adopting these digitally instrumented electrodes to optimize current loading and predict end-of-campaign failure. This virtualization is compressing the traditional trial-and-error approach to furnace parameter setting.
EPA carbon intensity benchmarking under evolving Clean Air Act interpretations tightens emissions disclosure requirements for steel production. Integrated mills face escalating compliance costs while EAF operators capture regulatory preference in federal procurement and state clean energy mandates. The Southeast and Texas markets are responding fastest, with new EAF capacity announcements accelerating.
Steelmakers are consolidating electrode procurement through multi-year technical service agreements rather than spot purchasing. This bundles consumables supply with campaign optimization consulting and on-site machining support. The Midwest industrial corridor shows this behavioral shift most visibly, with major producers locking in dedicated supplier engineering teams.
United States Graphite Electrodes Market Segmentation
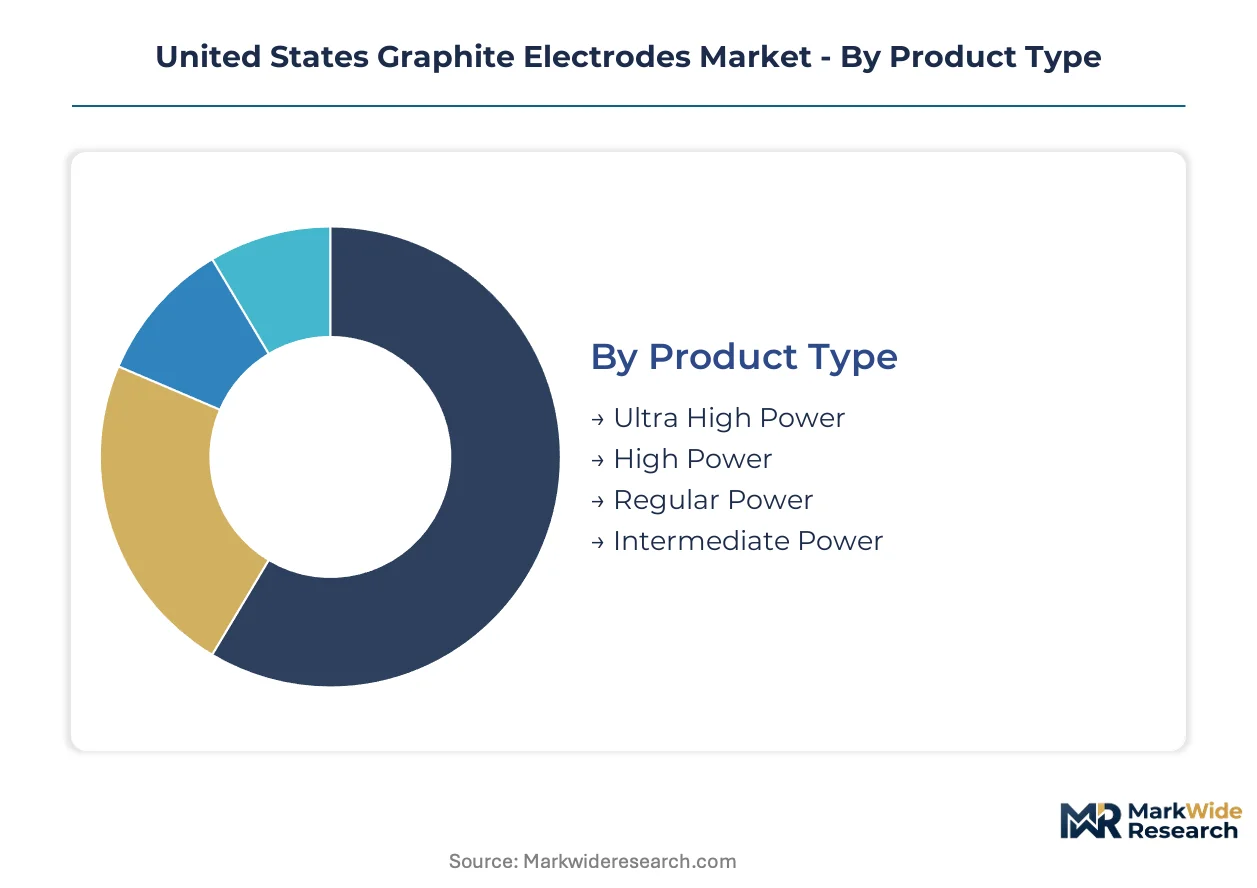
Graphite electrode procurement patterns diverge sharply across power ratings, end-use metallurgy, and furnace configurations. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Power rating tiers separate electrode portfolios by current-carrying capacity and thermal endurance, directly mapping to furnace intensity and campaign economics.
- Ultra High Power:Manufactured from premium petroleum needle coke with dense grain structure, these electrodes sustain current loads exceeding 100,000 amperes. Demand concentrates in Great Lakes EAF complexes where extended campaign life offsets per-ton electrode consumption. EPA carbon intensity rules amplify procurement as steelmakers maximize furnace productivity per electrode set.
- High Power:Intermediate needle coke grades deliver balanced performance for mid-size EAF operations running 60,000–90,000 amperes. Texas and Alabama mini-mills favor this tier for new capacity commissioning where furnace parameters remain unoptimized.
- Regular Power:Coal tar pitch-based formulations serve foundry and secondary metallurgy applications with lower thermal stress requirements.
- Intermediate Power:Blended formulations bridge cost-performance gaps for specialty steel producers in Ohio and Pennsylvania corridors.
Ultra High Power commands the established base. The steepest expansion runs through High Power as Southeast capacity ramps.
End User:
Customer type determines volume concentration, technical service intensity, and contract structure preferences across the electrode value chain.
- Steel Manufacturers:Electric arc furnace operators absorb the dominant volume share, with procurement consolidating through multi-year technical service agreements bundling electrodes with campaign optimization support. NHTSA fuel economy standards stimulating EV steel consumption reinforce this segment's expansion trajectory.
- Foundries:Smaller-batch ferrous and non-ferrous melting operations drive demand for standard and intermediate power grades with shorter campaign requirements.
- Aerospace:Specialty alloy producers require precision-machined electrodes for vacuum arc remelting and critical material applications.
- Automotive:Tier-1 stamping suppliers source EAF-produced flat products, creating indirect electrode demand through steel manufacturer procurement.
Steel Manufacturers anchor volume absorption. Aerospace climbs fastest on specialty alloy intensity.
Application:
Furnace process stage dictates electrode diameter, threading specification, and thermal shock resistance requirements.
- Electric Arc Furnace:Primary melting application consuming ultra high power electrodes in 24–32 inch diameters. Ohio River Valley clustering around Kentucky and West Virginia scrap access points intensifies regional demand concentration.
- Steel Melting:Encompasses ladle furnace and secondary refining operations requiring smaller-diameter electrodes with precise arc stability characteristics.
- Casting:Foundry pouring applications with intermittent arc cycling and lower continuous thermal loading.
- Secondary Metallurgy:Vacuum degassing and ladle treatment stations demanding specialized electrode geometries for controlled chemistry operations.
Electric Arc Furnace holds the volume core. Secondary Metallurgy gains share on quality-grade steel intensity.
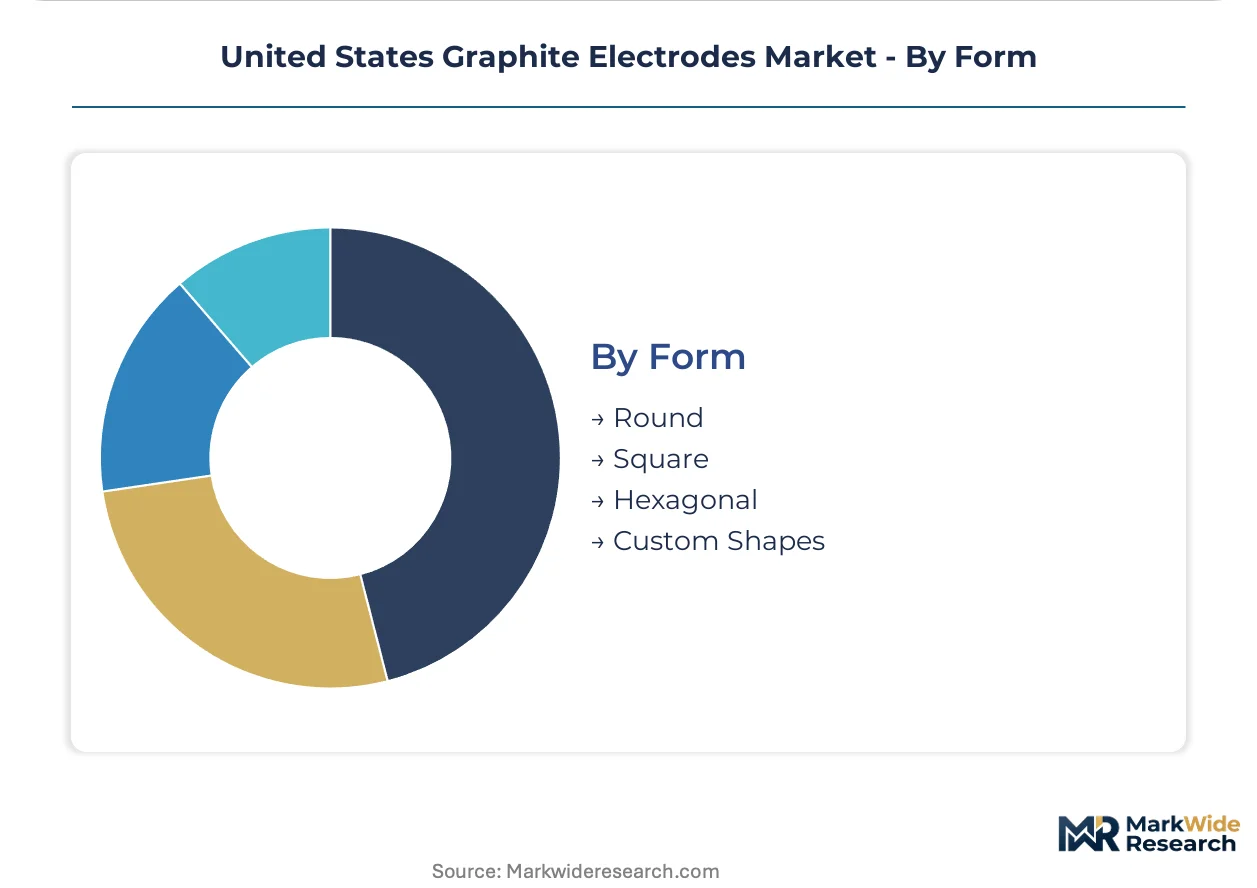
Form:
Physical geometry shapes machining complexity, shipping logistics, and furnace-specific installation protocols.
- Round:Dominant industry standard with standardized threading systems enabling rapid electrode column extension. Great Lakes port infrastructure optimizes bulk round electrode distribution.
- Square:Niche applications in specialized furnace designs requiring modified arc pattern distribution.
- Hexagonal:Limited adoption in experimental furnace configurations seeking optimized current density distribution.
- Custom Shapes:Engineered geometries for proprietary furnace technologies and repair scenarios requiring on-site machining adaptation.
Round dominates installed base. Custom Shapes expand fastest on furnace technology diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Ohio River Valley exhibit the highest price elasticity, squeezing margins on standard power electrodes, while Great Lakes EAF operators absorb premium pricing for ultra high power grades where campaign life drives total cost economics.
Great Lakes Industrial Corridor
Ultra high power electrode demand concentrates around Detroit, Cleveland, and Gary where legacy automotive stamping operations source EAF-produced flat-rolled steel. EPA Clean Air Act enforcement accelerates integrated mill conversions in Indiana and Ohio. Chicago port infrastructure enables efficient bulk electrode distribution to Calumet Region furnace complexes.
Southeast Steel Belt
New EAF capacity announcements in Alabama, Georgia, and South Carolina drive high power electrode procurement for commissioning-phase furnace operations. State renewable energy mandates in North Carolina and Tennessee favor scrap-based steelmaking in utility procurement decisions. Mobile and Savannah port access supports electrode import logistics for Gulf Coast mini-mill expansions.
Texas and Southwest
Electric arc furnace complexes in Houston and Corpus Christi benefit from abundant scrap generation from oilfield equipment decommissioning. ERCOT grid dynamics influence power cost structures that determine EAF operating economics relative to imported billet. Permian Basin industrial growth generates localized steel demand for pipeline and pressure vessel fabrication.
Ohio River Valley
Kentucky and West Virginia locations combine barge-accessible scrap supply, competitive power rates, and EPA regulatory preference for lower-emission melting routes. Huntington and Ashland furnace operations anchor regional electrode consumption. Appalachian natural gas abundance supports direct-reduction iron trials that may hybridize with EAF feedstock strategies.
Pacific Northwest
Specialty steel producers in Portland and Seattle serve aerospace and precision manufacturing with vacuum arc remelting applications requiring precision-machined electrode geometries. Washington State clean energy mandates accelerate EAF adoption for construction-grade rebar serving Seattle commercial development. Columbia River hydropower offers carbon-intensity advantages for steel export to California markets.
United States Graphite Electrodes Market Key Industry Players
Backward-integrated needle coke producers and specialized electrode fabricators split the market into distinct capability tiers. Three strategic archetypes dominate: petroleum coke-integrated manufacturers securing raw material cost advantages, regional specialists optimizing logistics for specific furnace corridors, and diversified carbon material conglomerates leveraging cross-product technical expertise. Competitive moves center on captive needle coke supply expansion and multi-year technical service contracting that bundles electrodes with campaign optimization support.
Among North American-anchored suppliers, GrafTech International exemplifies the backward-integrated archetype through its captive petroleum needle coke production. Graphite India Limited and Tokai Carbon occupy positions within the specialized fabricator tier, with the former representing Indian-origin supply diversification and the latter exemplifying Japanese precision manufacturing heritage. These three companies anchor the competitive structure through distinct geographic and integration strategies rather than undifferentiated commodity positioning.
| Leading Market Players |
|---|
| GrafTech International |
| Graphite India Limited |
| HEG Limited |
| Tokai Carbon |
| Showa Denko K.K. |
| Fangda Carbon New Material |
| Resonac Holdings Corporation |
| SGL Carbon SE |
| Nippon Carbon |
| Others |
Cost & Logistics Intelligence
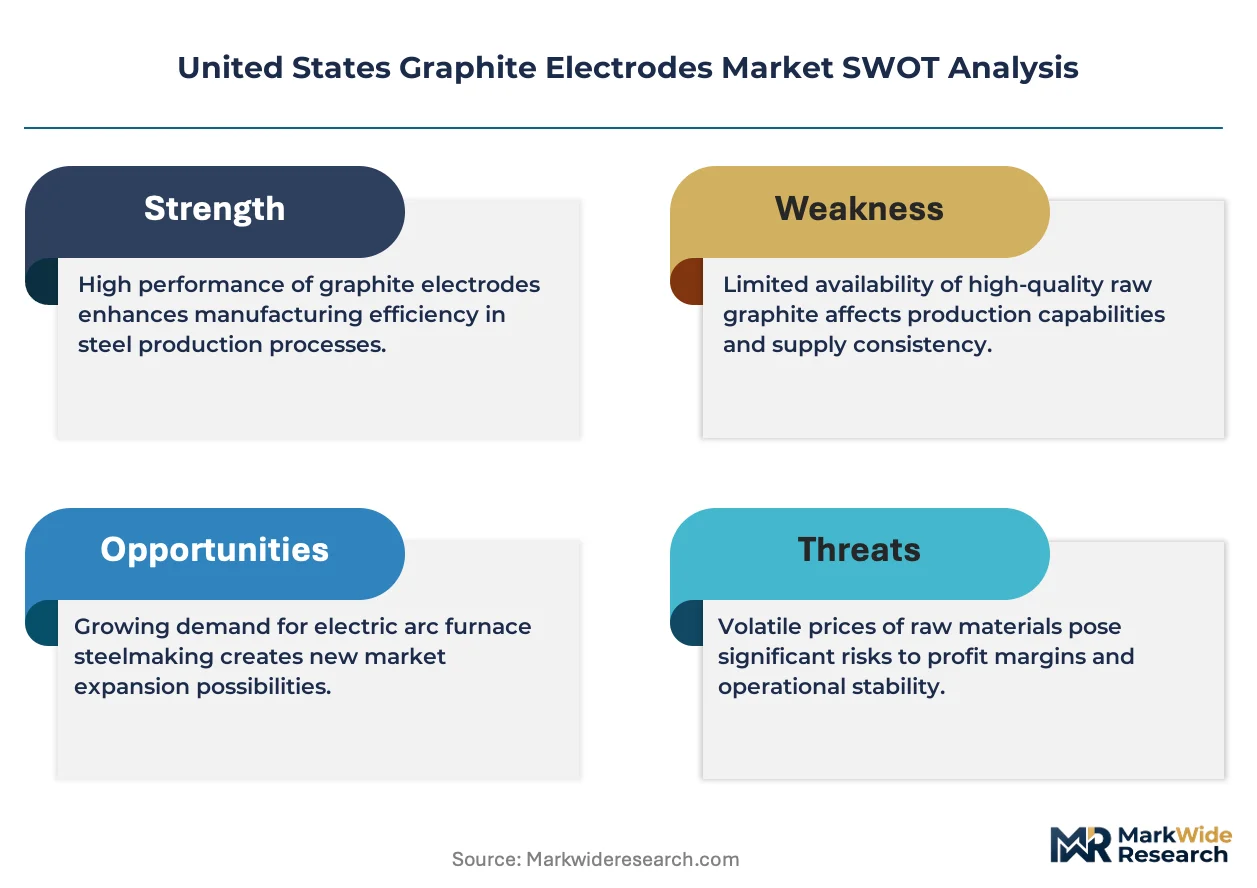
Great Lakes barge corridors and Ohio River Valley rail networks concentrate electrode logistics costs, amplifying price differentiation between captive needle coke producers and import-dependent fabricators while compressing margins on spot-traded standard power grades.
Pricing Analysis
Aftermarket technical service and electrode refurbishment contracts now drive lifetime value capture more than per-ton electrode sales. Three-tier pricing structure across premium ultra high power, standard high power, and economy regular power levels reflects needle coke grade differentiation and campaign life guarantees. Pricing pressure stems from Chinese needle coke export volatility and domestic mini-mill procurement consolidation. Foundry operators in the Ohio River Valley exhibit highest price sensitivity, while Great Lakes automotive-integrated EAF complexes absorb premium pricing for extended campaign life.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for needle coke importers. Raw material sourcing draws from petroleum needle coke production in the United States, Japan, and China, with coal tar pitch binder supplies concentrated in domestic coking operations. Single-source vulnerability persists for ultra high power needle coke grades where Japanese and Chinese producers control export volumes. Distribution runs through Great Lakes port terminals and Ohio River barge terminals serving Kentucky, Indiana, and Ohio furnace complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where electrode digital instrumentation and predictive maintenance software interoperability reshape supplier-customer technical service relationships into recurring revenue ecosystems.
For Market Incumbents: Entrench backward integration into petroleum needle coke through captive coker unit investments or long-term offtake agreements with domestic refiners. Lock in multi-year technical service contracts bundling electrode supply with campaign optimization software to defend against Asian import price pressure. Prioritize CNC machining specialist workforce development to address generational skill gaps threatening precision electrode fabrication capacity.
For New Entrants and Emerging Players: Establish a beachhead in electrode refurbishment and on-site machining services for existing EAF installations rather than competing on greenfield electrode manufacturing. Target Kentucky and West Virginia furnace corridors where barge logistics and scrap access support new EAF capacity commissioning. Lead with digital process controls integration and predictive maintenance software partnerships to differentiate from commodity electrode suppliers.
For Investors and Strategic Acquirers: Regional electrode fabricators with established Great Lakes logistics relationships and technical service teams represent priority acquisition targets. Long-term viability hinges on EPA carbon intensity rule durability and EAF capacity expansion pace across Ohio River Valley and Southeast corridors. Monitor needle coke price spreads and Chinese export license policy as inflection indicators for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | Captive petroleum needle coke production insulates electrode manufacturers from import price volatility and supply disruption. |
| Multi-Year Technical Service Agreements | Bundled electrode supply with campaign optimization consulting locks in customer relationships beyond commodity spot transactions. |
| Digital Process Controls Integration | Real-time graphitization furnace monitoring and predictive electrode failure systems compress downtime and extend campaign life. |
| Electrode Refurbishment Service Expansion | Tip rethreading and surface conditioning services capture aftermarket revenue from existing EAF installations seeking cost optimization. |
| CNC Machining Workforce Development | Precision turning skills for large-diameter electrode manufacturing address generational workforce gaps threatening production capacity. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with EAF operations managers, electrode procurement leads at steel manufacturers, needle coke supply specialists, and technical service directors; and secondary validation through EPA enforcement databases, EIA electricity pricing data, SEC filings from electrode manufacturers, and customs import records for needle coke volumes. Bottom-up electrode consumption modeling triangulated against top-down EAF capacity expansion announcements across Texas, Alabama, Ohio, and Indiana.
Forecast inputs incorporated power rating segmentation by ultra high power, high power, and regular power tiers; end-use metallurgy differentiation between carbon steel and specialty alloy producers; and furnace configuration variables including diameter specifications and campaign intensity parameters. CAGRs were derived from regression analysis of historical electrode consumption against EAF steel production volumes, adjusted for EPA regulatory scenario probabilities and needle coke supply elasticity assumptions.
Sensitivities concentrate around EPA carbon intensity rule enforcement pace, Chinese needle coke export license restrictions, and ERCOT grid pricing volatility affecting Texas EAF operating economics. Forecasts reflect documented assumptions regarding EAF capacity commissioning timelines and scrap steel availability in Great Lakes and Ohio River Valley corridors. Macroeconomic steel demand fluctuation, regulatory interpretation shifts, or needle coke supply disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Catalyst Bins Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Industrial Films Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Wood Protein Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Couplings Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Industrial Kiln Market