
 Magnet Rings Market | 2026-2036
Magnet Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Magnet Rings Market Analysis
China's rare earth processing corridor is narrowing the gap between raw material extraction and finished magnet ring fabrication. Arnold Magnetic Technologies leverages vertical integration across sintering and machining stages to sustain alloy consistency for aerospace-grade samarium cobalt rings. Dura Magnetics anchors its position through captive neodymium supply chains, while Temper Corporation specializes in thin-walled ring geometries for sensor applications.
Magnet rings are toroidal permanent magnet or electromagnetic assemblies, typically composed of neodymium-iron-boron, ferrite, or samarium cobalt alloys, manufactured through powder metallurgy sintering or bonded compression molding to generate radial, axial, or multipole magnetic fields for torque transmission, position sensing, or frictionless suspension. Permanent magnet rings dominate motor construction applications due to their energy density and operational stability without external excitation, whereas electromagnetic rings retain niche positioning in variable-field magnetic bearings where flux modulation is required. Ferrite rings occupy cost-sensitive consumer electronics segments with thinner margin pools, while samarium cobalt rings command premium positioning in aerospace end uses where thermal tolerance exceeds neodymium performance thresholds.
FDA oversight of magnetic resonance imaging equipment constrains field uniformity standards for diagnostic magnet rings, while EPA rare earth extraction rules raise compliance costs for domestic processors. China's MEE enforces wastewater discharge limits on sintering operations, and REACH compliance in Europe mandates full material disclosure for imported magnetic assemblies. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate certification bottlenecks and relocate finishing capacity accordingly.
Market Dynamics
Drivetrain electrification is compressing procurement cycles for high-performance permanent magnet rings as automakers lock in multi-year supply agreements to secure rare earth alloy allocations. This demand surge is reshaping sintering capacity allocation across East Asian manufacturing clusters and forcing fabricators to choose between automotive volume contracts and aerospace margin retention.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement of wastewater discharge limits on sintering operations is accelerating consolidation toward compliant mega-facilities with captive rare earth processing.
- Magnetic bearing adoption:Oil-free turbomachinery in hydrogen liquefaction plants is driving demand for multipole ring geometries with sub-micron tolerance specifications.
- Sensor miniaturization:Thin-walled ferrite rings for position sensing in robotic joint actuators are displacing Hall-effect alternatives in cost-sensitive automation deployments.
Market Restraints
- Dysprosium price volatility:Heavy rare earth alloying elements for high-temperature neodymium grades expose motor manufacturers to spot market swings exceeding 40% quarterly variance.
- Single-source sintering:Japanese precision magnet fabricators control 70% of aerospace-grade samarium cobalt ring capacity, creating chokepoint risk for Western tier-one suppliers.
- REACH material disclosure:European importers face 18-month certification timelines for full supply chain rare earth provenance documentation.
Strategic Opportunities
- Indian PLI scheme:Domestic content requirements for electric two-wheeler motors are incentivizing localized bonded ferrite ring production for cost-optimized drivetrains.
- Wind turbine direct-drive generators:10+ MW offshore units require segmented ring architectures that bypass monolithic magnet handling constraints.
- Additive manufacturing convergence:Laser powder bed fusion of soft magnetic composites enables topology-optimized flux paths impossible through conventional sintering.
Industry Challenges
- Magnetizer technician scarcity:Multipole magnetization of complex ring geometries requires specialized field mapping expertise concentrated among retiring Japanese engineers.
- ISO 19434 certification timelines:Aerospace suppliers face 24-month qualification periods for samarium cobalt traceability under new magnet alloy standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnet Rings Market |
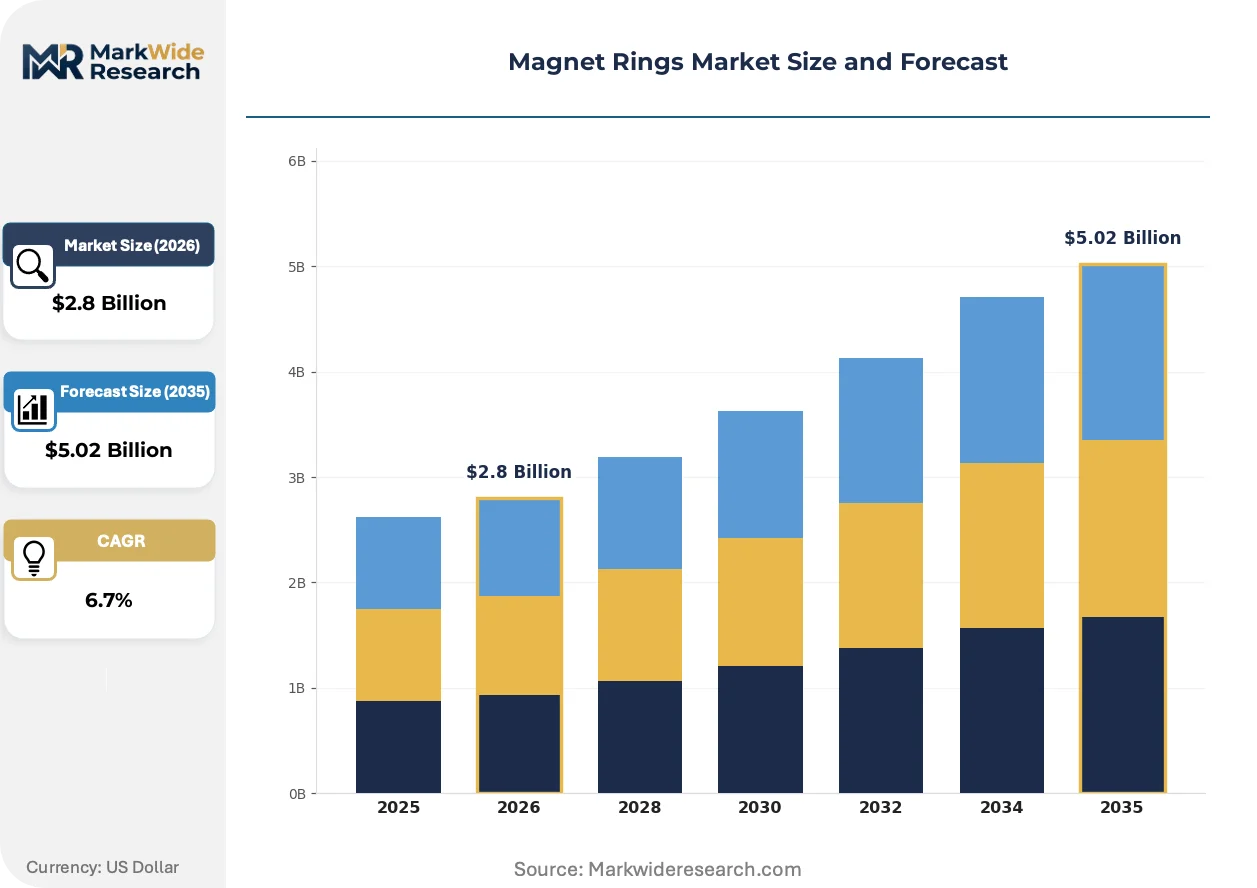
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet Rings, Electromagnetic Rings, Ferrite Rings, Samarium Cobalt Rings Application: Motor Construction, Magnetic Bearings, Sensors, Magnetic Levitation End User: Automotive, Industrial Machinery, Consumer Electronics, Aerospace Size: Small, Medium, Large, Custom |
| Companies Covered | National Imports LLC dba Magcraft, supermagnete, FIRST4MAGNETS, HUTCHINSON, Temper Corporation, Arnold Magnetic Technologies, Dura Magnetics, Master Magnetics, K&J Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnet Rings Market Emerging Trajectories
Digital thread integration across powder metallurgy workflows is compressing design-to-sintering lead times while enabling real-time magnetic field simulation. These advances are reshaping how fabricators compete on customization velocity versus unit economics.
Grain boundary diffusion engineering is digitizing the performance optimization of neodymium-iron-boron rings by enabling localized heavy rare earth deposition without bulk alloying. Tier-one automotive suppliers are adopting this process for 800V traction motors requiring 180°C operating thresholds. The technology is digitizing quality control protocols through inline EBSD mapping that replaces destructive batch testing.
REACH SVHC candidate list expansion is forcing European importers to substitute samarium cobalt in certain medical imaging applications due to cobalt compound scrutiny. The regulation is triggering reformulation programs among precision fabricators serving diagnostic equipment OEMs. German KBA type-approval requirements for automotive magnet assemblies are now mandating full material passport documentation that exceeds baseline EU compliance.
Automotive OEMs are consolidating magnet ring suppliers from 12-vendor panels to 3-4 strategic partnerships with dedicated capacity allocations. This concentration is eliminating spot-market purchasing for critical drivetrain components and transferring inventory carrying costs upstream to fabricators. The shift is most pronounced in South Korean battery-electric vehicle programs where Hyundai-Kia suppliers have adopted vendor-managed inventory models with 90-day demand visibility.
Magnet Rings Market Segmentation
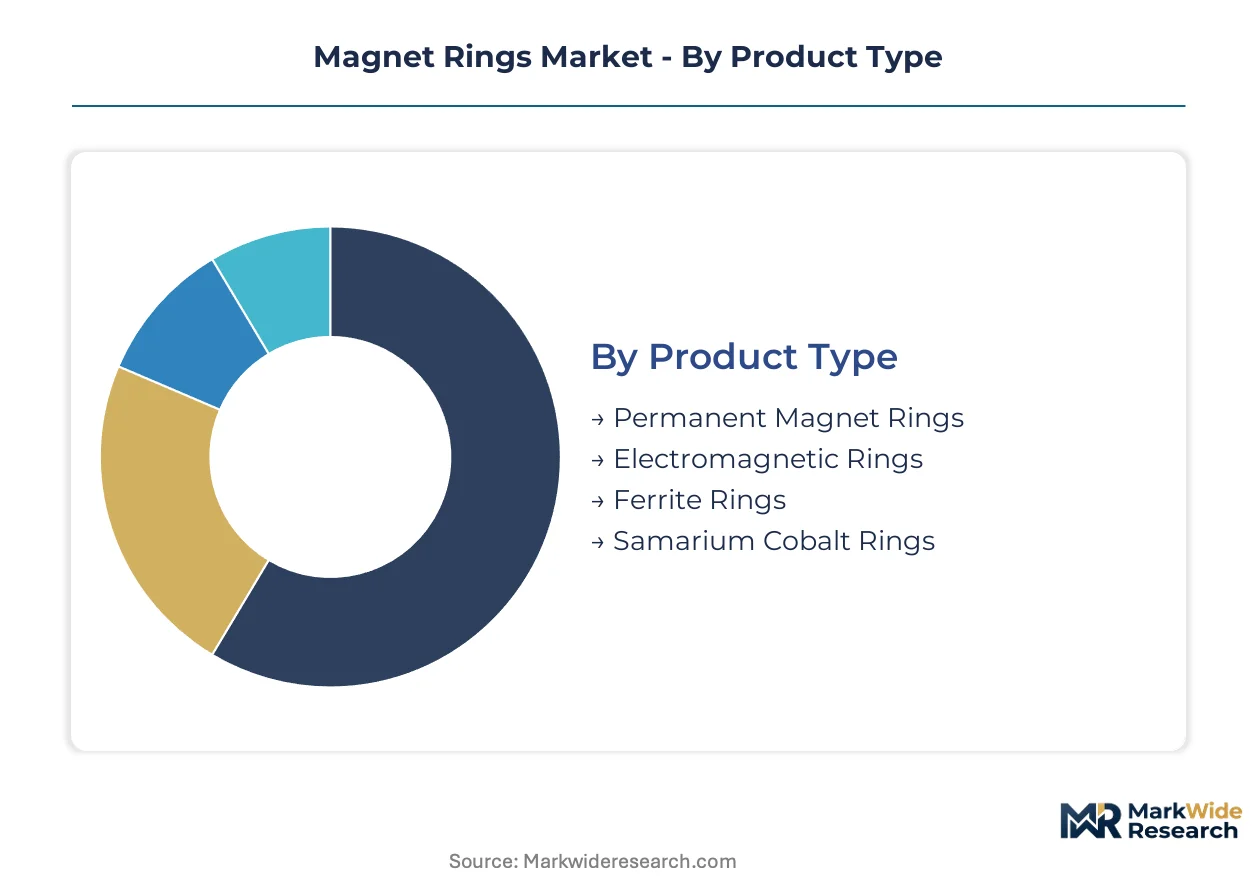
Magnet ring procurement cycles vary dramatically across segments, from quarterly ferrite orders for consumer electronics to multi-year samarium cobalt contracts for aerospace platforms. Understanding these velocity differentials helps fabricators allocate sintering capacity and working capital across divergent demand rhythms.
Product Type:
Permanent magnet rings turn inventory fastest in automotive traction motor programs, while samarium cobalt rings sit on aerospace qualification timelines stretching 18-24 months.
- Permanent Magnet Rings:Neodymium-iron-boron alloys deliver radial and multipole magnetic fields without external excitation. Procurement is compressing toward 90-day cycles as South Korean battery-electric vehicle programs adopt vendor-managed inventory with dedicated capacity allocations.
- Samarium Cobalt Rings:These high-temperature alloys maintain magnetic performance above 300°C where neodymium degrades. Japanese precision fabricators control the bulk of aerospace-grade capacity, creating chokepoint risk for Western tier-one suppliers seeking traceability certification under ISO 19434.
- Electromagnetic Rings:Copper-wound toroidal assemblies enable variable flux modulation for magnetic bearing applications in hydrogen liquefaction turbomachinery.
- Ferrite Rings:Cost-optimized ceramic magnets serve position sensing in robotic joint actuators, displacing Hall-effect alternatives in automation deployments.
Permanent magnet rings dominate installed base. Samarium cobalt rings are where expansion concentrates for thermal-critical applications.
Application:
Cost tier stratification separates high-volume motor construction from premium magnetic bearing installations requiring sub-micron tolerance geometries.
- Motor Construction:Radial-field rings integrate into traction motors, servo drives, and industrial pumps. Chinese dual carbon enforcement is accelerating consolidation toward compliant mega-facilities with captive rare earth processing for this segment.
- Magnetic Bearings:Oil-free suspension systems demand multipole ring architectures with precise pole pitch control. Offshore wind turbine direct-drive generators above 10 MW require segmented ring designs that bypass monolithic magnet handling constraints.
- Sensors:Thin-walled ferrite geometries enable contactless position detection in automotive steering and braking systems.
- Magnetic Levitation:Axial-field configurations support frictionless transport and precision positioning in semiconductor fabrication equipment.
Motor construction commands the volume base. Magnetic bearings represent the steepest expansion trajectory as oil-free turbomachinery penetrates process industries.
End User:
Customer concentration patterns split between automotive OEMs consolidating supplier panels and aerospace primes demanding dedicated qualification programs.
- Automotive:Drivetrain electrification is compressing procurement cycles as manufacturers lock in multi-year supply agreements to secure rare earth alloy allocations. Hyundai-Kia suppliers have adopted vendor-managed inventory models with 90-day demand visibility.
- Aerospace:Thermal tolerance requirements exceed neodymium thresholds, mandating samarium cobalt for turbine actuators and flight control systems. Suppliers face 24-month qualification periods under new magnet alloy standards.
- Industrial Machinery:Factory automation and process equipment utilize rings across the full performance spectrum from bonded ferrite to sintered rare earth grades.
- Consumer Electronics:Miniature speakers, vibration motors, and magnetic connectors drive high-volume, thin-margin demand for bonded compression-molded rings.
Automotive dominates current procurement volume. Aerospace is where margin retention concentrates despite extended sales cycles.
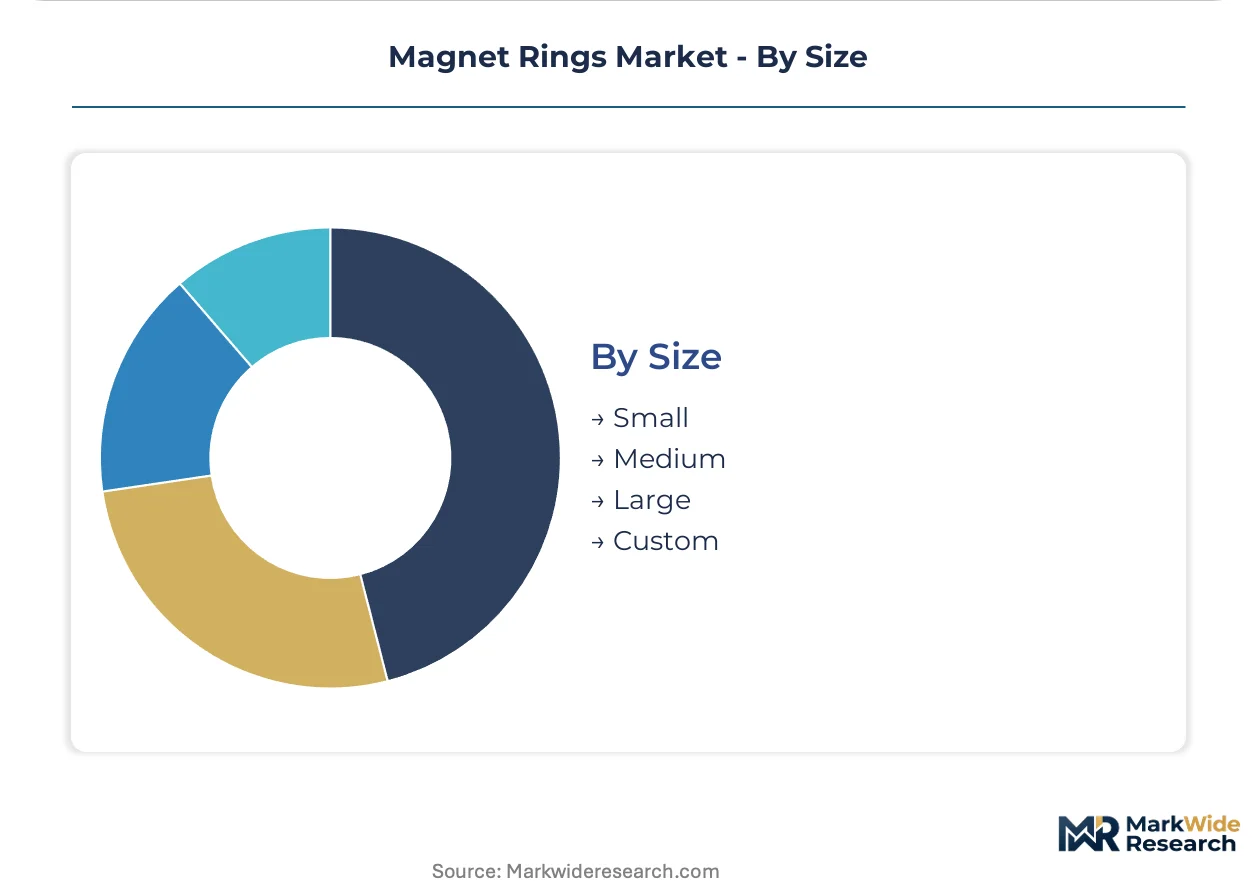
Size:
Supply chain configuration favors standard small and medium rings with tooled dies, while custom geometries require dedicated machining centers with longer lead times.
- Small:Diameters under 50 mm serve sensor applications and miniature motors. These rings achieve fastest cycle times through automated pressing and continuous sintering furnaces.
- Medium:50-200 mm ranges cover the bulk of industrial motor and automotive traction applications. Volume concentration enables grain boundary diffusion engineering adoption for 180°C operating thresholds.
- Large:Segmented architectures for wind turbine generators exceed 500 mm, requiring specialized handling equipment and magnetization fixtures.
- Custom:Non-standard geometries for magnetic levitation and specialized bearing applications demand CNC machining of sintered blanks or near-net-shape additive manufacturing.
Medium rings dominate production throughput. Custom geometries are where technical differentiation concentrates for premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing corridors concentrate magnet ring fabrication in three East Asian economies, with Japanese precision fabricators and South Korean automotive tier-one suppliers anchoring high-performance output. Chinese mega-facilities absorb volume demand as dual carbon enforcement consolidates compliant capacity. Western supply chains face chokepoint exposure from single-source sintering dependencies.
China
Dual carbon goals and MEE wastewater discharge limits are consolidating sintering operations toward compliant mega-facilities with captive rare earth processing. The dual carbon framework accelerates backward integration from extraction to finished magnet fabrication. Manufacturing clusters in Jiangxi and Inner Mongolia now host vertically integrated corridors that narrow the gap between raw material and precision ring output.
Japan
Japanese precision magnet fabricators control approximately 70% of aerospace-grade samarium cobalt ring capacity, creating concentrated chokepoint risk for Western tier-one suppliers. METI industrial policy supports domestic sintering expertise through targeted R&D subsidies for high-temperature alloy applications. The Chubu region around Nagoya anchors specialized magnetizer technician training programs that sustain sub-micron tolerance capabilities.
South Korea
Battery-electric vehicle programs from Hyundai-Kia are compressing procurement cycles toward 90-day vendor-managed inventory models with dedicated capacity allocations. Domestic suppliers face pressure to qualify under KBA type-approval requirements for full material passport documentation. The Gyeonggi-do cluster around Seoul houses automotive tier-one suppliers transitioning from spot-market purchasing to strategic partnerships with fabricators.
United States
EPA rare earth extraction rules raise compliance costs for domestic processors attempting to rebuild upstream magnet supply chains. FDA oversight of MRI equipment constrains field uniformity standards for diagnostic-grade ring imports. The Mountain Pass processing facility in California represents the sole domestic rare earth extraction node, though finishing capacity remains concentrated abroad.
Germany
KBA type-approval requirements now mandate full material passport documentation for automotive magnet assemblies, exceeding baseline EU REACH compliance timelines. ECHA REACH SVHC candidate list expansion is triggering reformulation programs among precision fabricators serving diagnostic equipment OEMs. The Baden-Württemberg industrial corridor hosts specialized machining centers for custom ring geometries serving magnetic bearing applications.
Magnet Rings Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with alloy consistency and tolerance expertise as their differentiation vectors. The vendor base organizes around three strategic archetypes: vertically integrated rare earth processors, precision machining specialists, and bonded compression molders serving cost-optimized segments. Consolidation pressure favors automotive volume contracts over aerospace margin retention, while REACH compliance timelines force portfolio rationalization among European-serving fabricators. Dominant competitive moves include captive supply chain construction and multi-year capacity reservation agreements with electric vehicle motor manufacturers.
Among North American distributors, National Imports LLC dba Magcraft and Master Magnetics occupy positions within the catalog-and-fulfillment archetype, serving maintenance-repair-operations demand and prototype engineering workflows. Arnold Magnetic Technologies and Temper Corporation exemplify the precision-fabrication tier, with the former representing vertically integrated sintering-to-machining capabilities and the latter specializing in thin-walled geometries for sensor applications. Dura Magnetics anchors the captive-neodymium-supply archetype, reflecting backward integration strategies that mitigate heavy rare earth price volatility exposure.
| Leading Market Players |
|---|
| National Imports LLC dba Magcraft |
| supermagnete |
| FIRST4MAGNETS |
| HUTCHINSON |
| Temper Corporation |
| Arnold Magnetic Technologies |
| Dura Magnetics |
| Master Magnetics |
| K&J Magnetics |
| Others |
Supply Flow & Price Mechanics
Jiangxi Province's rare earth processing corridor concentrates sintering capacity for neodymium-iron-boron ring fabrication, transferring upstream pricing power to compliant mega-facilities with captive alloy supply. Automotive OEMs face compressed negotiation leverage as South Korean battery-electric vehicle programs lock in multi-year offtake agreements with dedicated capacity allocations.
Pricing Analysis
China's MEE wastewater discharge limits dictate the pricing tier structure across environmental compliance grades. Three-tier pricing structure across aerospace-certified, automotive-grade, and consumer electronics tiers separates samarium cobalt rings with ISO 19434 traceability from bonded ferrite alternatives. Cost compression in consumer-grade ferrite runs through Indian PLI scheme incentives for domestic two-wheeler motor content. Tier-one automotive suppliers exhibit lowest price sensitivity due to qualification lock-in, while consumer electronics buyers drive spot-market volatility.
Supply Chain Analysis
Upstream rare earth oxide feedstock draws from Chinese extraction corridors in Inner Mongolia and Jiangxi, with Japanese precision fabricators and South Korean automotive tier-one suppliers commanding downstream finishing. Dysprosium and terbium heavy rare earth elements, copper winding stock for electromagnetic rings, and specialized magnetization fixtures constitute critical input dependencies. Single-source sintering vulnerability concentrates in Japanese aerospace-grade samarium cobalt capacity. Distribution runs through vendor-managed inventory models with 90-day demand visibility for automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnet ring procurement fragmentation creates niche entry points as drivetrain electrification splits demand between thermal-critical aerospace grades and high-volume automotive traction specifications.
For Market Incumbents: Insulate aerospace margin retention through dedicated samarium cobalt qualification programs as automotive volume contracts compress sintering capacity allocation. Backward integration into captive rare earth processing mitigates heavy rare earth price volatility exposure from spot market swings. For New Entrants and Emerging Players: Indian electric two-wheeler motor supply chains represent the most penetrable entry point for bonded ferrite ring production under PLI scheme domestic content requirements. Hydrogen liquefaction turbomachinery for oil-free magnetic bearings offers secondary white-space targeting. Technical partnerships with retiring Japanese magnetizer technicians enable sub-micron tolerance capability acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a supply security play because rare earth processing consolidation under China's dual carbon framework is narrowing Western access to finished magnet fabrication. Acquisition targets should emphasize precision machining specialists with established aerospace qualification timelines. The signal to watch is KBA type-approval enforcement breadth for automotive material passport documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Rare Earth Processing Integration | Backward control over dysprosium supply insulates automotive contract margins from quarterly spot volatility. |
| Grain Boundary Diffusion Engineering Adoption | Localized heavy rare earth deposition enables 180°C operating thresholds for 800V traction motors without bulk alloying costs. |
| Vendor-Managed Inventory Partnership | Hyundai-Kia supplier models with 90-day demand visibility transfer inventory carrying costs upstream to fabricators. |
| ISO 19434 Certification Investment | Aerospace samarium cobalt traceability standards create 24-month qualification barriers against commoditized competitors. |
| Segmented Ring Architecture Development | 10+ MW offshore wind turbine designs bypass monolithic magnet handling constraints for direct-drive generator deployment. |
Methodological Framework
Operator-level perspectives from sintering plant managers, automotive Tier 1 procurement leads, aerospace qualification engineers, and rare earth trading desk analysts anchored the qualitative base. Primary interview findings triangulated against customs export records for neodymium-iron-boron alloys, SEC filings from magnetic material processors, EPA rare earth extraction compliance databases, and METI industrial policy subsidy disclosures. Bottom-up demand modeling across motor construction, magnetic bearing, and sensor applications converged with top-down rare earth consumption forecasts.
Scenario-bracketing around China's dual carbon enforcement intensity and REACH SVHC candidate list expansion framed the projection horizon. Segmentation dimensions spanned alloy composition, thermal performance tier, pole geometry complexity, and end-use regulatory cluster. CAGRs derived from installed base replacement cycles and electrification penetration curves. Forecast inputs incorporated sintering capacity utilization rates and magnetizer technician pipeline constraints.
Macroeconomic conditions sit as an overlay; deviation in rare earth oxide spot prices, automotive production schedules, or wind turbine deployment pipelines would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and alloy substitution elasticity. Cross-checking against EIA energy transition benchmarks and IEA critical mineral supply security indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Bamboo Products Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Global Melamine Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Stainless Steel Cable Ties Market