
 Wear-Resistant Welding Wire Market | 2026-2036
Wear-Resistant Welding Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Wear-Resistant Welding Wire Market Insights
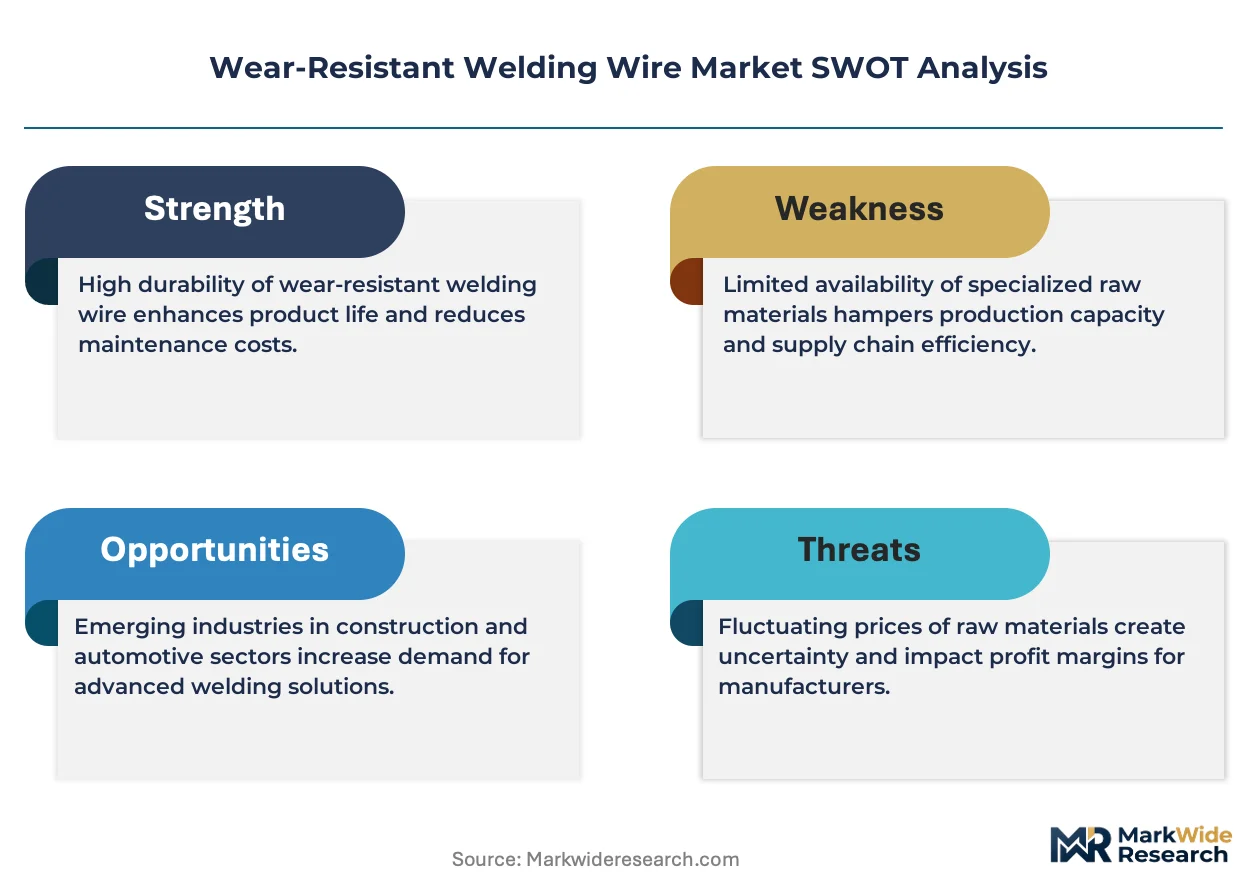
Preventive maintenance contracts and software-controlled deposition monitoring is shifting how welding wire gets sold to heavy fabricators. Lincoln Electric Holdings, Inc. leverages its RedZone digital platform to bundle wire supply with real-time arc-parameter tracking. ESAB Corporation anchors its position through captive R&D centers in Cleveland and Gothenburg that specialize in chromium-manganese formulations. voestalpine Böhler Welding dominates European demand for cobalt-based wire through direct mill relationships in Austria and Germany.
Wear-resistant welding wire is a metal filler material engineered with hardness values exceeding 50 HRC after deposition, typically alloyed with chromium, nickel, or cobalt carbides to resist abrasion and impact in extreme-service environments. Manufacturers draw or cast these wires to precise diameters between 0.8 mm and 3.2 mm, then layer them via MIG, TIG, or submerged arc processes onto worn industrial surfaces to extend component life. Flux-cored wire leads volume in mining equipment repair because self-shielded formulations eliminate gas-bottle logistics at remote pit sites. Chromium-based material compositions capture the fastest expansion as fabricators substitute away from cobalt formulations facing REACH supply-chain scrutiny. Solid wire remains the mature margin pool for automated heavy-duty fabrication lines where deposition-rate consistency outweighs per-kilogram cost.
EPA hazardous air pollutant standards under NESHAP for secondary metals production shape wire alloy selection and fume-extraction requirements at US fabrication shops. The EU REACH regulation and ECHA candidate list restrictions on cobalt compounds force reformulation investments across European supply chains. China's GB standards for welding consumables and MEE enforcement of industrial emissions controls tighten quality certification for export-oriented wire mills. Stakeholders must monitor how alloy-substitution timelines interact with deposition-hardness specifications that end users will not relax.
Market Dynamics
Preventive maintenance contracts bundled with deposition-monitoring software are restructuring how welding wire suppliers capture value from heavy fabricators, compressing transactional spot sales into multi-year performance agreements.
Growth Catalysts
- EU F-Gas Regulation:Tightened disclosure mandates for cobalt-containing consumables accelerate chromium-based substitution programs across European fabrication shops.
- Mining equipment repair:Bucket-lip restoration demand in Australia's Pilbara region and Canada's oil sands drives chromium wire procurement at remote pit sites.
- Flux-cored wire formulations:Self-shielded products eliminate gas-bottle logistics for field repair crews, expanding addressable service territory for consumables distributors.
Market Restraints
- Cobalt price volatility:REACH candidate-list scrutiny restricts supply-chain flexibility for carbide-formulation mills dependent on African concentrate.
- Hebei province concentration:Integrated steel-welding clusters in China's northern industrial corridor create single-source vulnerability for export-oriented OEMs.
- Deposition hardness ceiling:Chromium-manganese formulations struggle to match cobalt-based performance in high-impact abrasion environments without process-parameter tradeoffs.
Strategic Opportunities
- Submerged arc automation:Heavy fabrication lines in Germany and Austria seek wire-diameter standardization to reduce changeover downtime.
- Real-time arc monitoring:Digital platforms that bundle consumable supply with parameter tracking open recurring-revenue streams beyond commodity wire sales.
- India's mining expansion:Domestic iron ore and coal extraction projects create first-mover positioning for chromium-wire technical support networks.
Industry Challenges
- Welding procedure qualification:ASME Section IX and EN ISO 15614 certification timelines delay alloy-substitution approvals at pressure-equipment fabricators.
- Fume-extraction retrofit costs:EPA NESHAP compliance for secondary metals production demands capital outlays at US job shops with legacy ventilation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wear-Resistant Welding Wire Market |
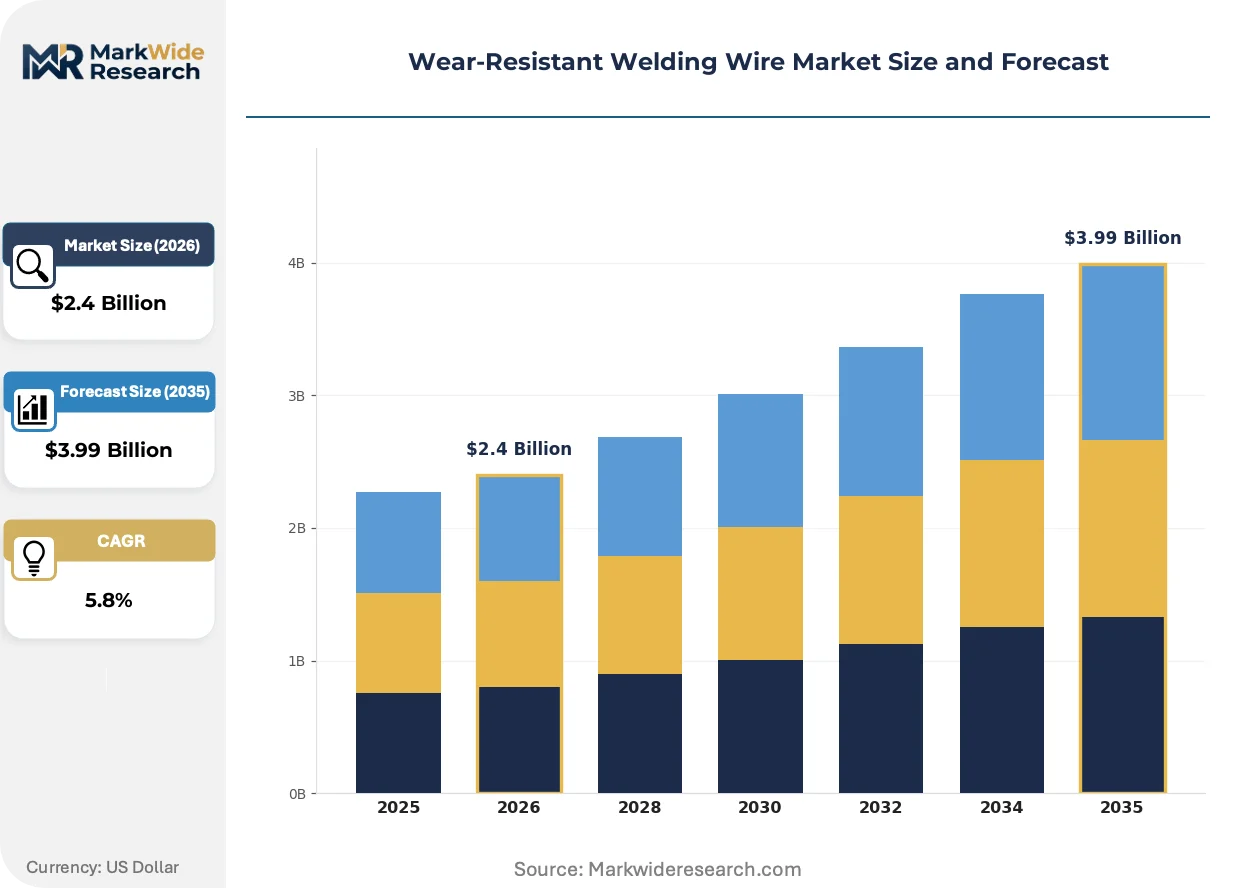
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flux-Cored, Solid Wire, Metal-Cored, Aluminum Wire, Stainless Steel Wire Material Composition: Nickel-Based, Cobalt-Based, Chromium-Based, Iron-Based, Manganese-Based Application: Mining Equipment, Construction Machinery, Agricultural Tools, Heavy-Duty Fabrication, Shipbuilding End User: Fabricators, Tier-1 Suppliers, Shipyards, Manufacture Plants, Equipment Assemblers |
| Companies Covered | Lincoln Electric Holdings, Inc., ESAB Corporation, voestalpine Böhler Welding, Illinois Tool Works Inc., Welding Alloys Group, Tianjin Golden Bridge Welding Materials Group, Oerlikon Metco, Castolin Eutectic, Waldun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wear-Resistant Welding Wire Market Trends and Innovations
Digital deposition control and alloy reformulation are compressing the traditional separation between consumable supply and welding process optimization, forcing wire manufacturers to embed sensing capabilities directly into delivery systems.
Flux-cored wire with integrated micro-alloying capsules is modularizing how fabricators adjust hardness profiles without switching spools. Mining contractors in Western Australia deploy these formulations to match bucket-lip wear patterns across ore-body transitions. The technology is modularizing inventory management at remote sites where logistics costs exceed material value.
EU REACH restrictions on cobalt compounds entered full enforcement phase for welding consumables, compelling reformulation investments across Austrian and German supply chains. ECHA candidate-list updates now trigger automatic supply-chain audits for downstream fabricators. Chromium-manganese wire categories absorb the displacement as end-users relax hardness specifications only where abrasion severity permits.
Service-contract bundling now dominates procurement at integrated steel mills, displacing spot purchasing for high-volume repair applications. Lincoln Electric's RedZone platform exemplifies the shift, embedding wire supply within arc-parameter telemetry. China's Hebei province clusters show the densest concentration of this model, where domestic mining OEMs demand uptime guarantees rather than per-kilogram pricing.
Wear-Resistant Welding Wire Market Segmentation
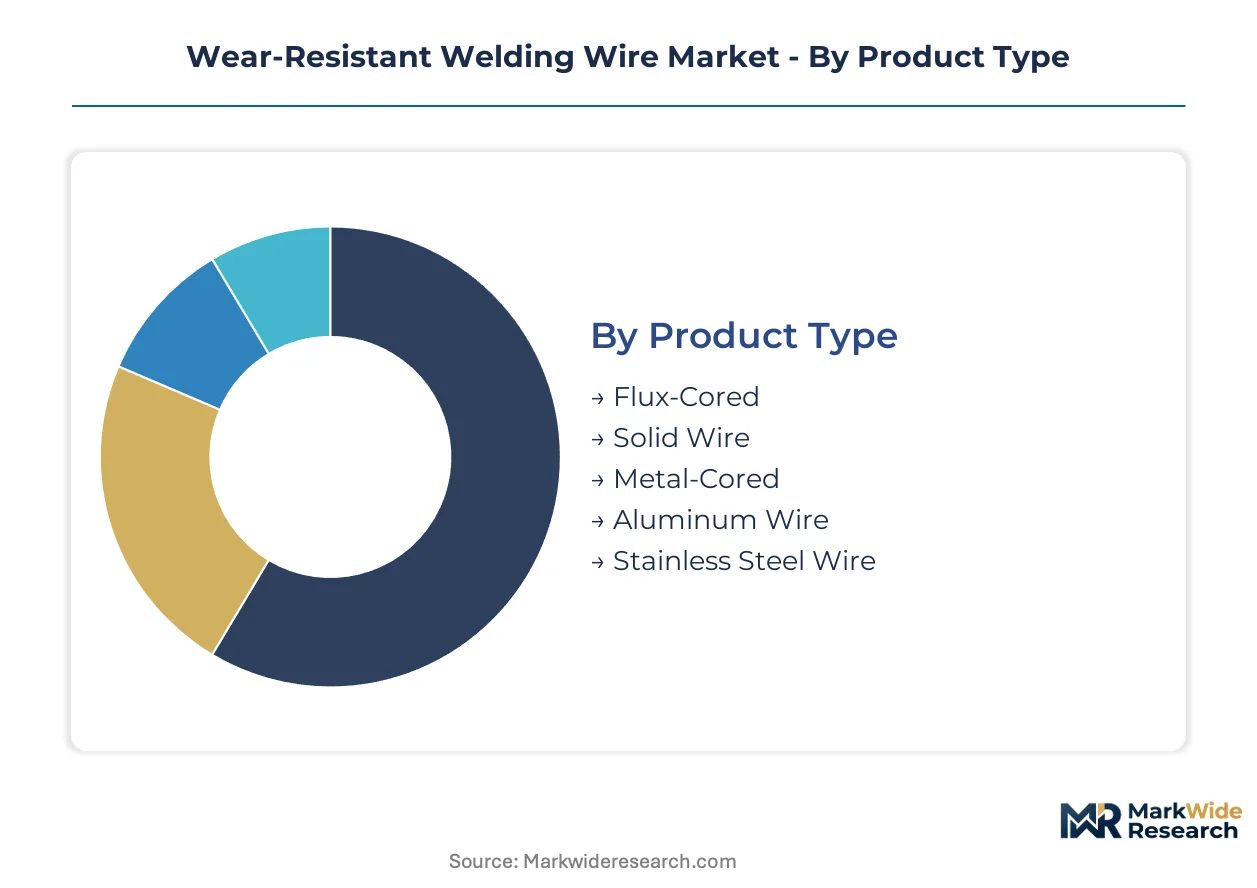
Segmentation in wear-resistant welding wire separates procurement behaviors shaped by field logistics, regulatory compliance burdens, and deposition performance requirements. Buyers across mining, construction, and marine sectors prioritize different trade-offs between hardness specifications, fume extraction needs, and supply chain reliability.
Product Type:
Cost tier and operational flexibility differentiate buyers in this category, with remote-site logistics driving self-shielded preferences and automated lines favoring deposition consistency.
- Flux-Cored:Self-shielded formulations eliminate external gas-bottle dependencies, making them indispensable for bucket-lip restoration at Australia's Pilbara pit sites and Canada's oil sands. Mining contractors absorb higher per-kilogram costs to avoid logistics complexity at remote locations where transport exceeds material value.
- Solid Wire:Precise diameter control and minimal spatter suit submerged arc automation at German and Austrian heavy fabrication lines. Deposition-rate consistency justifies premium positioning where automated changeover downtime carries substantial throughput penalties.
- Metal-Cored:Combines solid wire deposition efficiency with flux-cored alloy flexibility for mixed-mode fabrication environments.
- Aluminum Wire:Serves lightweight structural repair applications where corrosion resistance outweighs hardness requirements.
- Stainless Steel Wire:Targets chemical processing equipment facing simultaneous abrasion and corrosive exposure.
Volume sits with Solid Wire in automated heavy fabrication; growth tilts toward Flux-Cored as remote mining maintenance contracts expand.
Material Composition:
Regulatory pressure and performance ceilings split buyers between REACH-compliant reformulation and legacy cobalt retention where hardness specifications are non-negotiable.
- Chromium-Based:Absorbs displacement from restricted cobalt formulations across European fabrication shops subject to ECHA candidate-list audits. Chromium-manganese variants match moderate abrasion environments while satisfying EU REACH disclosure mandates that trigger automatic supply-chain scrutiny.
- Cobalt-Based:Retains dominance in high-impact abrasion applications where chromium alternatives face deposition-hardness ceiling constraints. African concentrate supply volatility and REACH restrictions compress procurement flexibility for carbide-formulation mills serving pressure-equipment fabricators.
- Nickel-Based:Balances toughness and corrosion resistance for chemical processing and marine environments.
- Iron-Based:Economy positioning for non-critical wear surfaces where hardness requirements fall below 50 HRC.
- Manganese-Based:Work-hardens under impact loading for railway and earthmoving applications.
Volume concentrates in Chromium-Based formulations amid regulatory displacement; expansion remains steepest where hardness specifications permit substitution without process-parameter tradeoffs.
Application:
Geographic concentration of extractive industries and infrastructure investment cycles determine regional demand patterns across end-use sectors.
- Mining Equipment:Bucket-lip restoration and crusher component hardfacing dominate procurement in Australia's Pilbara region and Canada's oil sands. Preventive maintenance contracts now bundle wire supply with deposition monitoring, compressing spot purchasing into multi-year performance agreements.
- Construction Machinery:Earthmoving blade and bucket repair cycles track infrastructure investment intensity in China's Hebei province clusters. Domestic mining OEMs demand uptime guarantees rather than per-kilogram pricing.
- Agricultural Tools:Seasonal replacement demand for tillage and harvesting equipment faces margin pressure from commodity grain pricing.
- Heavy-Duty Fabrication:Integrated steel mills and pressure-vessel shops require ASME Section IX and EN ISO 15614 certification timelines that delay alloy-substitution approvals.
- Shipbuilding:Marine classification society rules and fume-extraction retrofit costs shape procurement at legacy yards.
Revenue concentrates in Mining Equipment; Construction Machinery climbs fastest as China's integrated steel-welding clusters deepen captive supply relationships.
End User:
Technical capability and certification burden separate transactional buyers from those requiring embedded process support and compliance documentation.
- Fabricators:Job shops with legacy ventilation infrastructure face EPA NESHAP compliance capital outlays for secondary metals production. Fume-extraction retrofit costs disadvantage smaller operators against consolidated competitors.
- Tier-1 Suppliers:Direct mill relationships in Austria and Germany anchor cobalt-based wire procurement for European mining OEMs demanding material disclosure documentation.
- Shipyards:Classification society welding procedure qualifications and marine environment corrosion requirements impose extended approval cycles.
- Manufacture Plants:Captive maintenance operations at integrated steel mills favor bundled service contracts with real-time arc-parameter telemetry.
- Equipment Assemblers:Original equipment manufacturers in China's Hebei province source through clustered supply relationships that create single-source vulnerability for export-oriented procurement.
Procurement volume aggregates at Fabricators; Tier-1 Suppliers expand fastest as OEMs outsource hardfacing competence to certified specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of wear-resistant welding wire while Australia and Canada consume disproportionate volumes for mining equipment maintenance. Production clusters in Hebei province supply domestic OEMs and export markets. Demand concentrates at remote extraction sites where logistics costs dominate procurement decisions.
Australia
Pilbara iron ore operators drive chromium wire consumption for bucket-lip restoration at remote pit sites. EPA and state mining regulators enforce fume-extraction standards at fabrication workshops serving the extractive sector. Perth-based distributors bundle preventive maintenance contracts with real-time deposition monitoring for Rio Tinto and BHP contractors.
Canada
Oil sands mining in Alberta generates demand for self-shielded flux-cored wire that eliminates gas-bottle logistics at remote locations. Health Canada and provincial occupational safety bodies regulate welding fume exposure at Fort McMurray repair facilities. Edmonton and Calgary house technical service networks supporting Suncor and Canadian Natural Resources hardfacing programs.
China
Hebei province's integrated steel-welding clusters manufacture chromium-based formulations for domestic mining OEMs and export markets. MEE enforces GB standards for welding consumables and industrial emissions controls at wire mills. Tangshan and Handan concentrate production capacity serving XCMG and Sany captive procurement relationships.
Germany
Ruhr Valley heavy fabrication lines demand solid wire with precise diameter control for submerged arc automation. ECHA REACH restrictions on cobalt compounds trigger supply-chain audits and reformulation investments across North Rhine-Westphalia. Düsseldorf and Essen anchor voestalpine Böhler Welding's direct mill relationships with European mining OEMs.
United States
EPA NESHAP standards for secondary metals production shape alloy selection and fume-extraction requirements at fabrication shops. Ohio and Pennsylvania house Lincoln Electric's RedZone platform development and captive R&D for chromium-manganese formulations. Cleveland-based technical centers bundle wire supply with arc-parameter telemetry for integrated steel mill maintenance contracts.
Wear-Resistant Welding Wire Market Competitive Landscape
Capital-heavy wire producers compete with asset-light technical service specialists across distinct value-capture models. The vendor base separates between integrated manufacturers controlling alloy formulation and captive distribution, and regional fabricators sourcing commodity wire for spot repair contracts. Three archetypes dominate: diversified industrial conglomerates with welding divisions, specialized consumables manufacturers with captive R&D centers, and integrated steel-welding clusters serving domestic OEMs. Competitive moves concentrate on M&A for digital platform capabilities and strategic partnerships bundling consumable supply with process monitoring software.
Among diversified industrial conglomerates, Lincoln Electric Holdings, Inc. and Illinois Tool Works Inc. exemplify the integrated model combining wire manufacturing with technical service networks. ESAB Corporation and voestalpine Böhler Welding occupy positions within the specialized consumables tier, with European-registered suffixes indicating regional anchoring in welding technology development. Tianjin Golden Bridge Welding Materials Group represents the China-based cluster archetype, with geographic naming signaling production concentration in northern industrial corridors serving domestic mining equipment manufacturers.
| Leading Market Players |
|---|
| Lincoln Electric Holdings, Inc. |
| ESAB Corporation |
| voestalpine Böhler Welding |
| Illinois Tool Works Inc. |
| Welding Alloys Group |
| Tianjin Golden Bridge Welding Materials Group |
| Oerlikon Metco |
| Castolin Eutectic |
| Waldun Group |
| Others |
Pricing and Supply Chain Analysis
Integrated steel mill maintenance directors in Germany and Austria anchor contract-based procurement, converting per-kilogram spot purchasing into multi-year performance agreements bundled with deposition monitoring. This buyer concentration compresses margin pools for transactional distributors while rewarding wire manufacturers with captive technical service networks.
Pricing Analysis
Cost-down pressure on standard-grade solid wire accelerates as Hebei province clusters flood export channels with chromium-manganese formulations. Three-tier pricing structure across premium cobalt-based, standard chromium-manganese, and economy iron-based levels separates ASME-certified fabricators from commodity job shops. Price differentiation rests on REACH disclosure documentation and real-time arc-parameter telemetry bundling. Mining contractors in Australia's Pilbara region show lowest price sensitivity, absorbing logistics premiums for self-shielded flux-cored delivery to remote pit sites.
Supply Chain Analysis
Refurbishment flows for worn crusher components and bucket lips create secondary material loops that feed raw alloy recovery back into wire mills. Manufacturing concentrates in China, Germany, and Austria, with Hebei province drawing from domestic ferrochrome and Tangshan steel mill byproducts. Raw material dependencies center on African cobalt concentrate, Ukrainian ferroalloys, and Australian chromite. Single-source vulnerability intensifies around REACH-compliant chromium-manganese formulation mills. Distribution runs through technical service networks anchored in Cleveland, Düsseldorf, and Tangshan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH candidate-list restrictions on cobalt compounds erect compliance moats that favor incumbent wire manufacturers with established ECHA audit documentation and reformulation R&D.
For Market Incumbents: Acquire digital deposition monitoring platforms to bundle consumable supply with arc-parameter telemetry, converting transactional sales into recurring revenue streams. Deepen captive supply relationships with Hebei province mining OEMs demanding uptime guarantees. Defend against cobalt-substitute displacement by accelerating chromium-manganese hardness ceiling research at Cleveland and Gothenburg technical centers. For New Entrants and Emerging Players: The premium-economy price gap in flux-cored self-shielded formulations opens positioning for mid-tier technical service specialists. India's mining expansion presents the most penetrable geography, with domestic iron ore projects lacking established hardfacing support networks. Enter through welding procedure qualification partnerships that compress ASME Section IX approval timelines for alloy-substitution approvals. For Investors and Strategic Acquirers: The window for entry favors specialized consumables manufacturers with captive R&D centers and direct mill relationships. Long-term viability hinges on regulatory compliance capabilities that compound across successive ECHA candidate-list updates. Watch cobalt price volatility and African concentrate supply disruptions as inflection signals for chromium-based substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Supply | Captive ferrochrome sourcing insulates voestalpine Böhler Welding from Ukrainian supply disruptions. |
| Digital Platform Integration | Lincoln Electric's RedZone telemetry bundles embed wire supply within predictive maintenance contracts. |
| REACH Compliance Certification | ECHA audit documentation creates switching costs for European mining OEM procurement committees. |
| Remote Site Technical Service Networks | Perth and Fort McMurray service hubs capture preventive maintenance contract renewals from Pilbara operators. |
| Alloy Reformulation Partnership | Chromium-manganese hardness ceiling research displaces cobalt in moderate abrasion environments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving welding consumables procurement managers, hardfacing application engineers, mining maintenance directors, and EHS compliance officers at fabrication shops. ECHA candidate-list updates, EPA NESHAP enforcement records, and China MEE emissions disclosure databases supplied regulatory boundary conditions. Bottom-up spool shipment data from Hebei province clusters reconciled with top-down mining equipment maintenance spend estimates.
Data-stream reconciliation across product type, material composition, application severity, and end-user certification tier produced volume and value outputs across the projection horizon. CAGRs derived from alloy-substitution elasticity models calibrated to REACH compliance timelines and cobalt price volatility scenarios. Forecast inputs included welding procedure qualification approval rates, fume-extraction retrofit capital cycles, and submerged arc automation adoption curves at German heavy fabrication lines.
Inputs from ECHA enforcement disclosures and China GB standard revision notices were available through the study window; gaps in real-time mining contractor maintenance contract terms introduce uncertainty bands around bundled service revenue projections. Practitioners should monitor ECHA candidate-list expansion triggers and African concentrate supply disruptions for early signals of chromium-based substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Silica Fume Market
Industrial Materials
Industrial Films Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Steel Processing Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Tension Spring Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Industrial Drum Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Battery Separator Materials Market