
 Power Transmission Lines and Towers Market | 2026-2036
Power Transmission Lines and Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transmission Lines and Towers Market Analysis
India's green energy corridor build-out is reshaping procurement patterns for extra-high-voltage hardware. KEC International dominates domestic tower fabrication through captive galvanizing capacity and railway logistics integration. Prysmian Group leverages submarine cable expertise to compete for offshore wind interconnector contracts. ZTT International anchors Asia-Pacific supply through vertically integrated conductor and optical ground wire operations.
Power transmission lines and towers encompass conductive cables, supporting structures, and insulating hardware engineered to carry electrical energy across distances from 11 kV to 800 kV and beyond, with aluminum-conductor steel-reinforced (ACSR) and aluminum-conductor alloy-reinforced (ACAR) compositions dominating due to strength-to-weight ratios. Underground cables now capture premium margin pools in dense urban corridors where right-of-way constraints and aesthetic regulations prevent overhead routing. AC transmission still occupies the bulk of installed capacity, yet DC transmission leads growth for long-distance renewable integration spanning desert solar fields to coastal demand centers.
The US Federal Energy Regulatory Commission and India's Central Electricity Authority both mandate dynamic line rating and vegetation management standards that tighten product certification requirements. China's GB standards and the EU's F-Gas Regulation further constrain material selection for insulators and gas-insulated lines. Stakeholders must monitor how carbon-border adjustment mechanisms and domestic-content rules in multiple jurisdictions reshape sourcing strategies for steel lattice towers and composite conductors.
Market Dynamics
Grid decarbonization mandates are forcing utilities to reconduct existing corridors with high-capacity composite conductors rather than building new rights-of-way, compressing project timelines while elevating material performance requirements.
Growth Catalysts
- Renewable integration mandates:India's Central Electricity Authority requires transmission upgrades for green corridor absorption, accelerating extra-high-voltage tower procurement.
- Conductor efficiency standards:China's MIIT tightened aluminum alloy specifications, pushing utilities toward ACAR and high-temperature low-sag alternatives.
- Offshore wind build-out:Coastal demand centers in Germany and the United Kingdom require submarine interconnectors, expanding addressable market for cable-lay specialists.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing consumes 15-20% of tower fabrication costs, exposing margins to London Metal Exchange fluctuations.
- Specialized steel concentration:High-strength angle production concentrates among a limited set of rolling mills, creating bottleneck risk for lattice tower fabricators.
- Right-of-way scarcity:Dense urban corridors in Japan and South Korea prevent overhead routing, capping addressable volume for traditional tower products.
Strategic Opportunities
- Gas-insulated line penetration:The EU's F-Gas Regulation is compressing SF6 alternatives development, opening market for vacuum-interrupter and clean-air technologies in urban substations.
- Dynamic line rating adoption:FERC Order 881 mandates real-time thermal monitoring, creating aftermarket sensor and analytics demand across US transmission operators.
- Desert solar interconnection:Saudi Arabia and Morocco require ultra-long-distance DC links, favoring suppliers with converter station and submarine cable integration capabilities.
Industry Challenges
- Welding certification timelines:AWS D1.1 and ISO 3834 compliance for high-strength steel lattice fabrication extends qualification periods for new manufacturing entrants.
- Legacy SCADA integration:Digital twin and predictive maintenance platforms must interface with decades-old control systems, complicating smart grid retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transmission Lines and Towers Market |
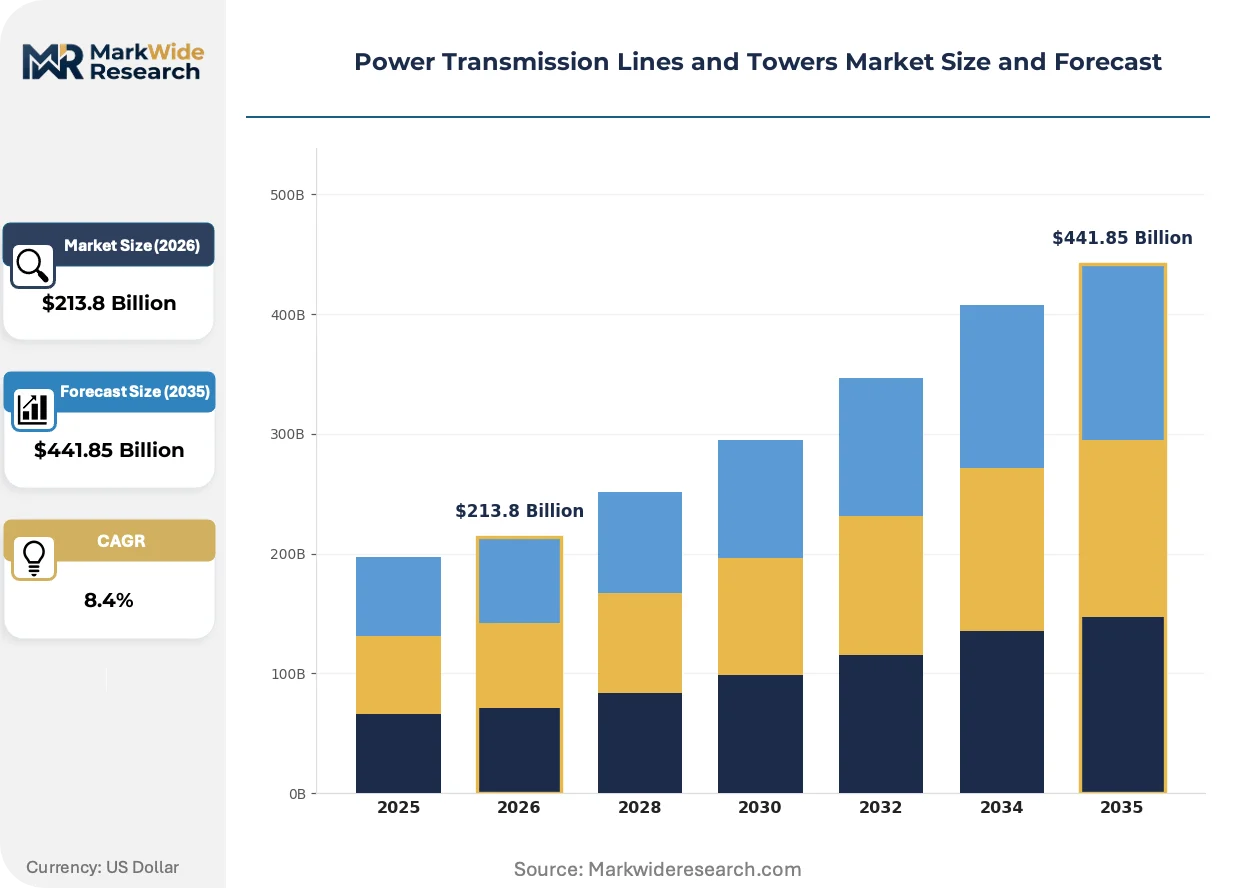
| Market Size in 2026 | $213.8 Billion |
| Market Size in 2035 | $441.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overhead Lines, Underground Cables, Transmission Towers, Accessories Technology: AC Transmission, DC Transmission, High Voltage, Medium Voltage End Use Industry: Utilities, Industrial, Commercial, Renewable Energy Installation Type: New Installation, Upgrade, Maintenance, Replacement |
| Companies Covered | Prysmian Group, Skipper Limited, ZTT International, Bekaert, Lamifil, Sumitomo Electric Industries, KEC International, CTC Global, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transmission Lines and Towers Market Emerging Trajectories
Material science advances and digital instrumentation are converging to transform static transmission infrastructure into adaptive, data-generating assets that optimize capacity without physical expansion.
Carbon fiber composite core conductors are virtualizing traditional steel-reinforced designs by enabling double the ampacity within existing tower clearances. US utilities facing FERC-mandated congestion relief are piloting ACCR and ACSS alternatives at scale. This technology is virtualizing the conventional build-new-towers paradigm, allowing grid operators to defer capital-intensive right-of-way acquisition.
The EU's F-Gas Regulation is accelerating SF6 phase-down across gas-insulated transmission lines and substations. Manufacturers must reformulate switchgear with fluoronitrile or vacuum interruption technologies to maintain market access. German and French transmission system operators are front-loading procurement of clean-air GIS to avoid compliance cliffs.
Performance-based service contracts are displacing traditional equipment-only sales in offshore wind interconnector projects. Developers in the United Kingdom and Taiwan now bundle cable supply with installation, monitoring, and availability guarantees. EPC firms with marine construction capabilities are capturing margin pools previously reserved to pure-play cable manufacturers.
Power Transmission Lines and Towers Market Segmentation
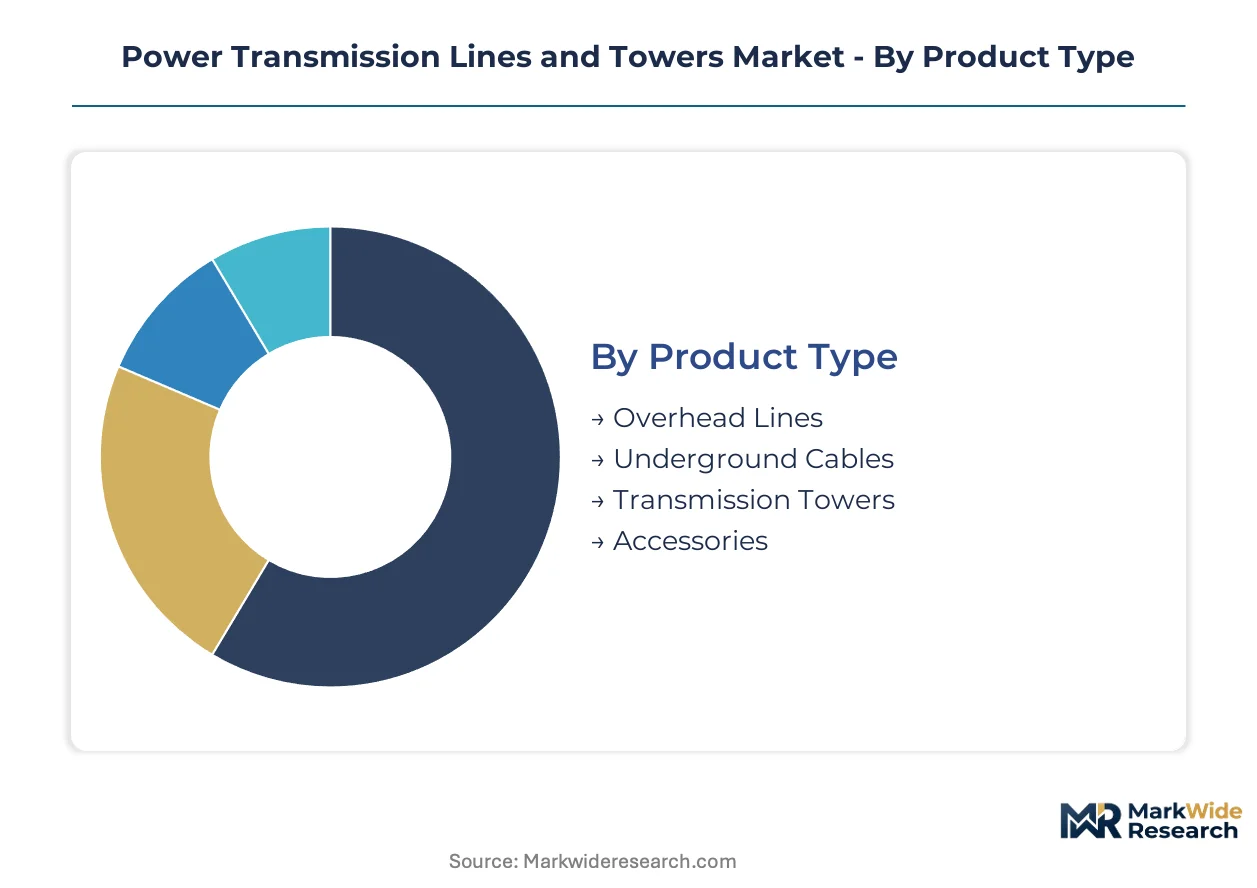
Power transmission infrastructure serves radically different deployment contexts—from desert solar fields to dense urban corridors. Segmentation reveals how material specifications, voltage classes, and installation modes diverge across these use cases, shaping supplier capabilities and margin structures.
Product Type:
Product selection tracks the tension between right-of-way availability and capital efficiency, with overhead and underground solutions serving mutually exclusive deployment environments.
- Overhead Lines:Aluminum-conductor steel-reinforced and composite-core designs dominate, carrying 66 kV to 800 kV across rural and semi-urban corridors. India's green energy corridor build-out concentrates procurement for extra-high-voltage spans connecting Rajasthan solar parks to load centers.
- Transmission Towers:Steel lattice structures and monopoles provide mechanical support, with galvanizing quality determining service life in coastal and industrial atmospheres. China's MIIT efficiency standards are accelerating demand for optimized tower geometries that reduce conductor sag.
- Underground Cables:Cross-linked polyethylene and gas-insulated lines penetrate dense urban zones where overhead routing faces regulatory prohibition.
- Accessories:Insulators, dampers, and hardware complete system integrity for termination and tension points.
The dominant share belongs to Overhead Lines, while Underground Cables is closing the gap fastest.
Technology:
Voltage class and current type selection hinge on distance-to-load and converter economics, with DC systems commanding premium pricing for ultra-long spans.
- AC Transmission:Alternating current retains installed base dominance through transformer compatibility and lower capital cost for sub-600 km spans. US utilities under FERC Order 881 are retrofitting AC corridors with dynamic line rating to extract latent capacity without reconductoring.
- DC Transmission:High-voltage direct current minimizes losses across 800+ km desert-to-coast links, with voltage source converters enabling asynchronous grid interconnection. Saudi Arabia and Morocco are procuring ultra-long-distance DC for solar export.
- High Voltage:230 kV to 800 kV classes handle bulk power transfer between generation hubs and metropolitan demand.
- Medium Voltage:11 kV to 132 kV serves distribution feeders and industrial interconnections with lower insulation requirements.
AC Transmission maintains the largest installed footprint, though DC Transmission exhibits the steepest expansion trajectory for renewable integration.
End Use Industry:
Customer type determines procurement scale, technical specification authority, and contract structure, from regulated rate-base investments to merchant renewable offtake.
- Utilities:State and investor-owned transmission operators deploy rate-based capital for grid expansion and reliability mandates. India's Central Electricity Authority procurement guidelines standardize tower specifications for national grid corporation projects.
- Renewable Energy:Wind and solar developers commission collector systems and export lines under independent power producer structures, often bundling EPC and O&M.
- Industrial:Mining, smelting, and petrochemical facilities procure captive transmission for remote generation access.
- Commercial:Data centers and large campuses negotiate dedicated feeder capacity with local distribution utilities.
Utilities command the dominant procurement volume, while Renewable Energy developers are gaining share fastest as greenfield project pipelines expand.
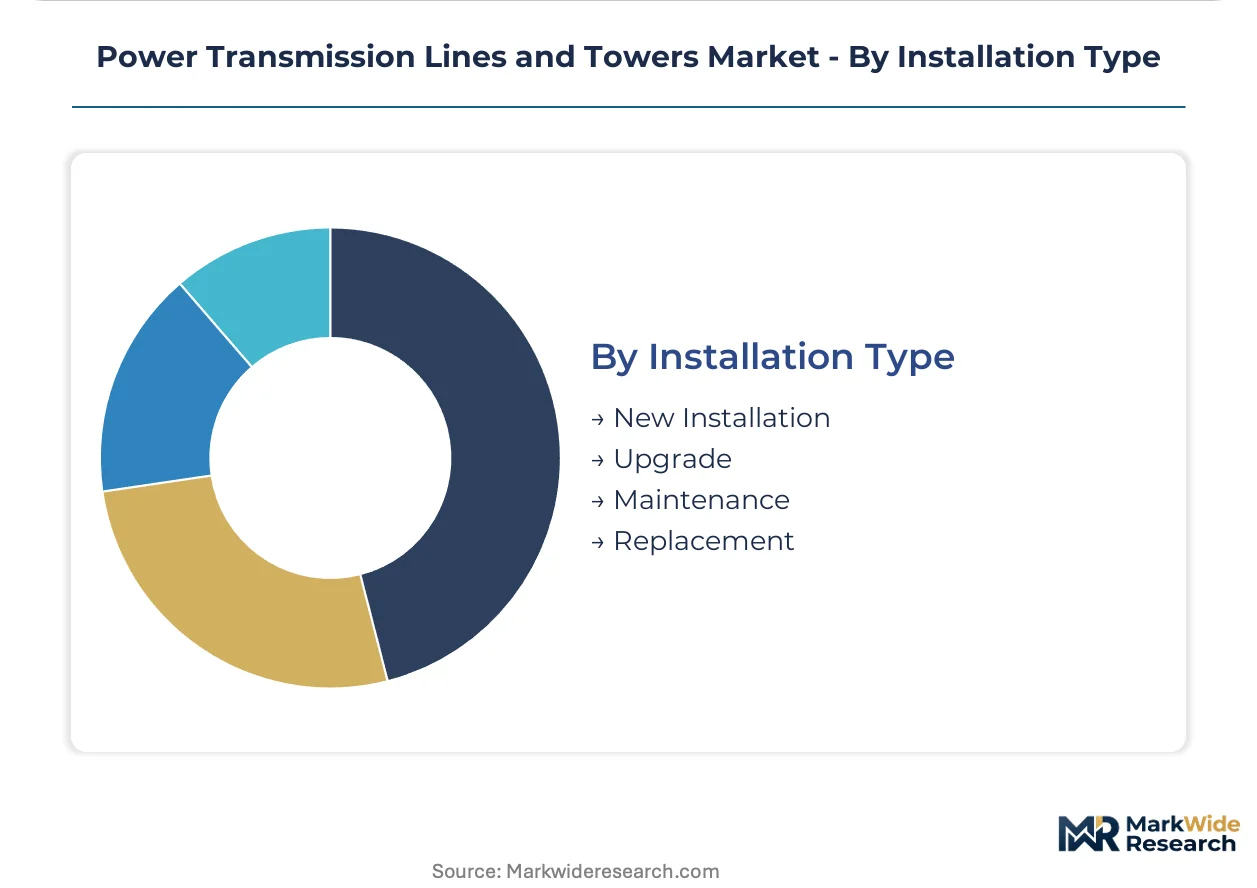
Installation Type:
Project modality reflects asset age, regulatory pressure, and technology obsolescence cycles, with reconductoring emerging as a capital-efficient alternative to greenfield construction.
- New Installation:Greenfield corridors for generation interconnection and load growth require full right-of-way acquisition and tower erection. Germany's offshore wind build-out is driving North Sea cable-lay demand.
- Upgrade:Existing tower reinforcement and conductor replacement with high-temperature low-sag alternatives doubles ampacity without structural expansion. US utilities facing FERC congestion mandates are prioritizing ACCR and ACSS retrofits.
- Maintenance:Vegetation management, hot-spot remediation, and hardware replacement preserve reliability indices.
- Replacement:End-of-life asset retirement and storm damage reconstruction restore system integrity.
New Installation retains the largest project value, though Upgrade activity is expanding most quickly as reconductoring compresses permitting timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through conductor efficiency mandates that cascade across supplier certification requirements worldwide.
China
MIIT's tightened aluminum alloy specifications accelerate demand for ACAR and high-temperature low-sag conductors. GB standards constrain insulator material selection and tower geometry optimization. Jiangsu and Zhejiang provinces concentrate domestic fabrication capacity for export-oriented conductor manufacturers.
India
Green corridor projects drive extra-high-voltage tower procurement as Rajasthan solar parks interconnect to national load centers. Central Electricity Authority procurement guidelines standardize specifications for state transmission utilities. Gujarat and Maharashtra host the densest clustering of domestic tower fabricators with captive galvanizing operations.
United States
FERC Order 881 mandates dynamic line rating adoption, creating sensor and analytics demand across transmission operators. Vegetation management standards tighten product certification for hardware suppliers. Texas and California concentrate utility procurement for renewable interconnection and wildfire-hardening retrofits.
Germany
North Sea offshore wind build-out expands addressable market for submarine cable-lay specialists. EU F-Gas Regulation accelerates SF6 phase-down across gas-insulated transmission infrastructure. Northern coastal states front-load procurement of converter station and interconnector capacity.
Saudi Arabia
Ultra-long-distance DC links for desert solar export favor suppliers with integrated converter and cable capabilities. National renewable targets mandate transmission expansion across the Arabian Peninsula. Riyadh and the Eastern Province concentrate procurement authority for grid-scale interconnection projects.
Power Transmission Lines and Towers Market Vendor Landscape
Capability concentration sits with specialized conductor and cable technology developers; scale advantage sits with integrated tower fabricators and EPC contractors. The market structures around three tiers: multinational cable specialists with submarine expertise, domestic tower fabricators with captive steel processing, and composite conductor technology licensors. Consolidation pressure runs through backward integration into high-strength steel rolling and forward integration into installation services.
Within the multinational cable tier, Prysmian Group and Nexans occupy positions anchored by submarine interconnector credentials. ZTT International exemplifies Asia-Pacific vertical integration across conductor and optical ground wire operations. KEC International represents the domestic fabricator archetype with integrated galvanizing and logistics infrastructure. These three patterns—submarine specialization, regional supply integration, and captive fabrication—define competitive positioning across procurement cycles.
| Leading Market Players |
|---|
| Prysmian Group |
| Skipper Limited |
| ZTT International |
| Bekaert |
| Lamifil |
| Sumitomo Electric Industries |
| KEC International |
| CTC Global |
| Nexans |
| Others |
Supply Flow & Price Mechanics
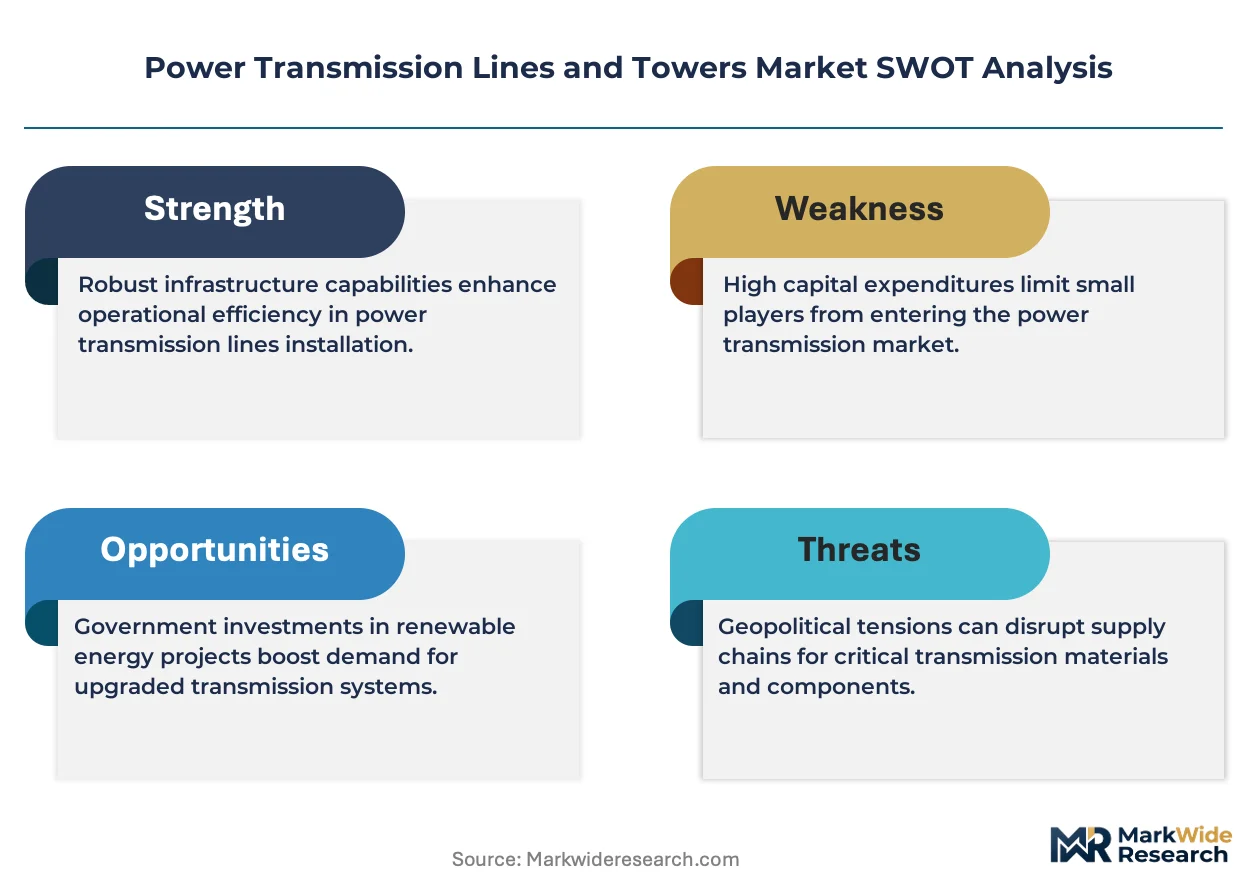
China's Jiangsu and Zhejiang provinces concentrate global conductor fabrication capacity, anchoring margin capture for high-performance aluminum alloys while downstream tower assembly disperses across India and the Middle East. This geographic split between upstream metal processing and downstream structural fabrication shapes where pricing power accumulates and where cost pressure transmits.
Pricing Analysis
Chinese-origin ACAR conductors command 12-18% premiums over standard ACSR in European procurement, with price differentiation tracking MIIT certification tiers and galvanizing quality grades. Project-based long-term offtake contracts dominate utility procurement, though spot purchasing resurges during green corridor build-outs. Cost compression in standard lattice towers intensifies as Indian fabricators expand captive galvanizing capacity. Renewable energy developers exhibit highest price sensitivity, while national grid corporations absorb premium tiers for reliability guarantees.
Supply Chain Analysis
KEC International and Skipper Limited control contract-manufacturing capacity for extra-high-voltage towers across Gujarat and Maharashtra. Geographic supply concentrates in China for aluminum alloy smelting, India for structural fabrication, and Germany for converter station engineering. Raw material dependencies rest on high-strength angle steel from limited rolling mills, zinc for hot-dip galvanizing, and rare-earth elements for composite conductor cores. Single-source vulnerability concentrates in specialized steel production. Distribution runs through EPC contractors bundling installation with hardware supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with reconductoring services and digital instrumentation, as FERC Order 881 and equivalent mandates splinter demand across sensor integrators and analytics platforms rather than concentrating with traditional equipment suppliers.
For Market Incumbents: Entrench position through backward integration into high-strength steel rolling and captive galvanizing capacity expansion in coastal India. Composite conductor technology licensors threaten premium product margins; defend by accelerating ACSS and ACCR certification pipelines for US utility procurement cycles. Channel control through railway logistics integration remains the priority lever against domestic fabricators. For New Entrants and Emerging Players: Offshore wind interconnector installation in the North Sea and Taiwan Strait represents the most penetrable entry point, with performance-based service contracts displacing equipment-only sales. Desert solar DC links for Saudi and Moroccan export projects offer second white-space target. Go-to-market through marine construction EPC partnerships bypasses established cable manufacturer relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed tower fabricators lacking conductor technology access. Five-to-ten year viability favors suppliers with integrated converter station and submarine cable capabilities as renewable interconnection scales. Acquisition target archetype: regional tower fabricators with captive galvanizing and logistics infrastructure but absent composite conductor licensing. Watch F-Gas Regulation compliance timelines as inflection indicator for switchgear technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Captive high-strength angle supply secures tower fabrication margins against mill bottlenecks. |
| Dynamic Line Rating Sensor Deployment | FERC Order 881 compliance creates aftermarket demand across US transmission operators. |
| SF6-Free Switchgear Development | EU F-Gas Regulation phase-down mandates vacuum-interrupter technology for market access. |
| Submarine Cable-Lay Capability Buildout | North Sea offshore wind interconnectors expand addressable market for marine construction specialists. |
| Composite Conductor Technology Licensing | ACCR and ACSS patents enable double ampacity within existing tower clearances for US utilities. |
Methodological Framework
Desk research of FERC filings, Central Electricity Authority procurement guidelines, and MIIT efficiency standards preceded structured interviews with utility planning officers, EPC contractors, and grid operators. Secondary validation drew from EIA transmission project databases, IEA renewable integration reports, and customs trade data for aluminum alloy and steel angle imports. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate quantification.
Assumptions held fixed include current F-Gas Regulation phase-down schedules, FERC Order 881 implementation timelines, and existing green corridor procurement commitments; variables included zinc price volatility bands and converter station delivery schedules. Segmentation modeling spanned product type, voltage class, installation mode, and end-use industry across the projection horizon. CAGRs derived from regression against historical transmission capital expenditure patterns and renewable capacity addition forecasts, with sensitivity testing for right-of-way permitting delays.
Macroeconomic conditions sit as an overlay; deviation in steel and aluminum commodity prices, currency fluctuation in India and China, or acceleration in carbon-border adjustment mechanisms would shift the trajectory. Forecasts reflect documented assumptions about regulatory continuity and technology cost curves. Cross-checking against IEA World Energy Outlook transmission investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market