
 Middle East Pipeline Maintenance Market | 2026-2036
Middle East Pipeline Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Pipeline Maintenance Market Outlook
Asset-light contracting and performance-based service agreements are narrowing the competitive field in Middle East pipeline maintenance. T D Williamson Inc leverages its specialized hot-tapping and isolation technology to sustain premium positioning in high-risk operations. Halliburton Company anchors its regional presence through integrated wellbore and pipeline service bundles across Saudi Arabia and Kuwait. STATS Group differentiates through proprietary pipeline isolation and pressure-testing systems that command technical specification roles in major projects.
Middle East pipeline maintenance encompasses the inspection, repair, cleaning, and integrity management of crude oil, natural gas, and refined product transmission systems operating at pressures typically ranging from 600 to 1,440 psi and temperatures exceeding 60°C in desert environments. The discipline prevents catastrophic failure, ensures continuous hydrocarbon flow, and extends asset life across thousands of kilometers of buried and subsea infrastructure. Inspection Services and Robotic Inspection represent the fastest-expanding technology-service intersection, driven by operator demands for non-destructive evaluation without production shutdowns. Predictive Maintenance is displacing reactive Corrective Maintenance as the dominant contracting model, concentrating margin pools with vendors capable of real-time acoustic monitoring and data analytics integration.
Saudi Aramco's internal engineering standards, the UAE's civil defense fire and safety codes, and Iraq's ministry of oil pipeline integrity directives collectively mandate systematic pressure testing and corrosion monitoring across national transmission networks. These frameworks elevate compliance costs for foreign entrants while creating protected demand cycles for certified local service providers. Stakeholders must weigh the trade-off between investing in autonomous robotic platforms and building indigenous technician capacity as regulatory enforcement tightens and labor localization requirements expand.
Market Dynamics
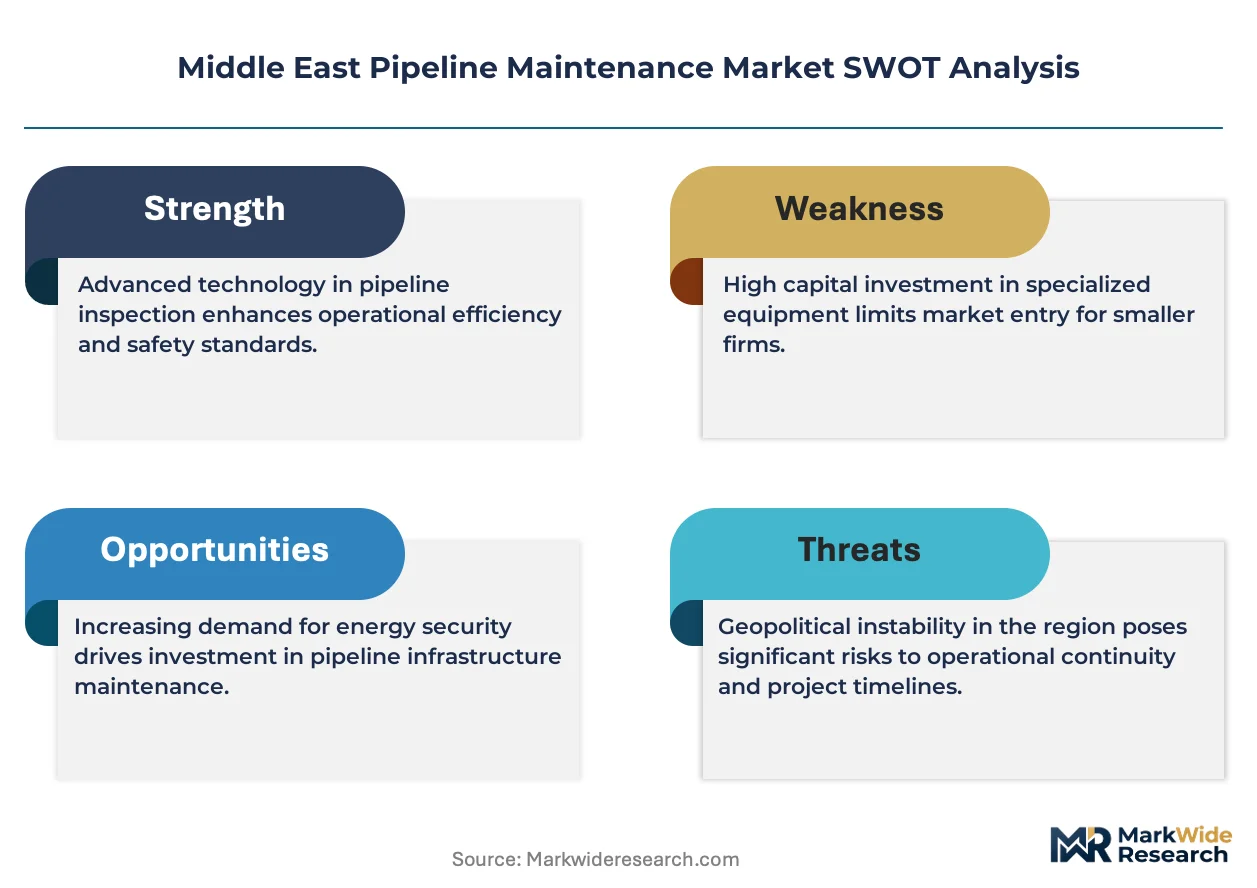
Asset integrity mandates from Saudi Aramco and ADNOC are compressing inspection cycles and forcing vendor consolidation around predictive analytics capabilities. National operators now require real-time corrosion monitoring across high-pressure transmission corridors.
Growth Catalysts
- SFDA Pipeline Safety Directives:Saudi Arabia's national regulator mandates ultrasonic testing intervals for sour gas lines, creating recurring demand for certified inspection providers.
- Robotic Crawler Deployment:In-line inspection tools with magnetic flux leakage sensors now traverse live pipelines without flow interruption, eliminating revenue loss from shutdowns.
- Iraqi Infrastructure Rehabilitation:Decades of deferred maintenance across Basra and Kirkuk fields generates concentrated repair contracts for weld remediation and coating replacement.
Market Restraints
- Specialized Alloy Supply Concentration:High-grade chromium-molybdenum steel for hot-tap fittings sources primarily from East Asian mills, exposing contractors to freight volatility and customs delays.
- Desert Thermal Cycling:Extreme diurnal temperature swings exceeding 40°C induce fatigue cracking in external pipeline coatings, accelerating re-coating frequency beyond standard design life.
- MOHAP Fire Code Compliance:UAE civil defense regulations require redundant isolation verification before maintenance, extending mobilization timelines and inflating standby labor costs.
Strategic Opportunities
- Kuwait Offshore Expansion:KNPC's Al-Zour refinery integration with marine terminals creates demand for subsea inspection robotics and cathodic protection systems.
- AI-Driven Anomaly Detection:Machine learning models trained on acoustic emission data now predict crack propagation 18 months before visual detection, enabling preemptive intervention scheduling.
- Local Content Requirements:Saudi Aramco's In-Kingdom Total Value Add program mandates 70% local workforce participation, rewarding joint ventures with indigenous engineering firms.
Industry Challenges
- API 1169 Certification Bottlenecks:Pipeline inspector credentialing through the American Petroleum Institute faces 6-month backlogs, constraining crew mobilization for urgent repair windows.
- Legacy SCADA Integration:Analog control systems from 1980s installations resist interoperability with modern digital twin platforms, forcing expensive retrofit or parallel infrastructure builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Pipeline Maintenance Market |
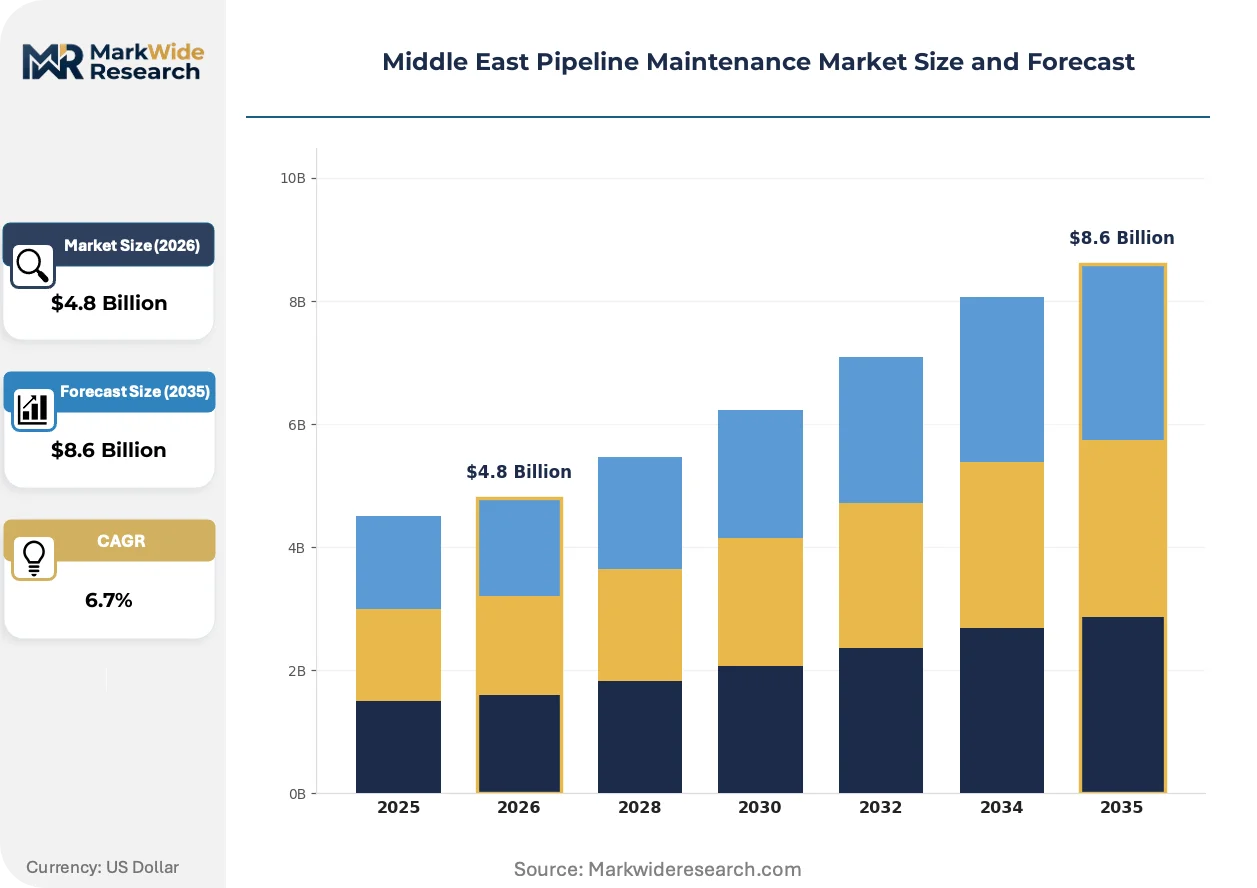
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection Services, Repair Services, Cleaning Services, Maintenance Services Technology: Hydrostatic Testing, Ultrasonic Testing, Acoustic Monitoring, Robotic Inspection End User: Oil & Gas Companies, Utilities, Municipalities, Industrial Facilities Maintenance Type: Predictive Maintenance, Preventive Maintenance, Corrective Maintenance, Emergency Maintenance |
| Companies Covered | Saudi Aramco, Rezayat Group, EEW Group, T D Williamson Inc, ExxonMobil Corporation, BP PLC, Halliburton Company, Arabian Pipes Company, STATS Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Pipeline Maintenance Market Strategic Shifts
Digital thread architectures now connect field sensor networks to cloud-based integrity management systems, collapsing the latency between defect detection and maintenance dispatch. This convergence is redrawing competitive boundaries between hardware specialists and software platforms.
Magnetic flux leakage combined with ultrasonic phased array is digitizing corrosion mapping across Saudi Aramco's East-West crude pipeline. Field technicians deploy tethered robotic crawlers transmitting wall-thickness data to centralized dashboards within minutes rather than weeks. The compression of diagnostic cycles is digitizing how operators prioritize dig sites and allocate rehabilitation budgets.
MOHAP's 2023 update to the UAE Fire and Life Safety Code mandates continuous pressure monitoring for all hydrocarbon transmission lines within 500 meters of population centers. Operators must install redundant sensor networks and submit quarterly integrity reports to civil defense authorities. The regulation is accelerating replacement of mechanical gauges with wireless transmitters across Dubai and Abu Dhabi emirate pipeline corridors.
Service unbundling is fragmenting long-term maintenance contracts into discrete task orders awarded through competitive tender. Saudi Aramco now separates inspection, cleaning, and repair scopes rather than bundling under single-source agreements. This procurement evolution favors specialized contractors with narrow technical certifications over integrated service conglomerates, particularly visible in the Eastern Province pipeline cluster.
Middle East Pipeline Maintenance Market Segmentation
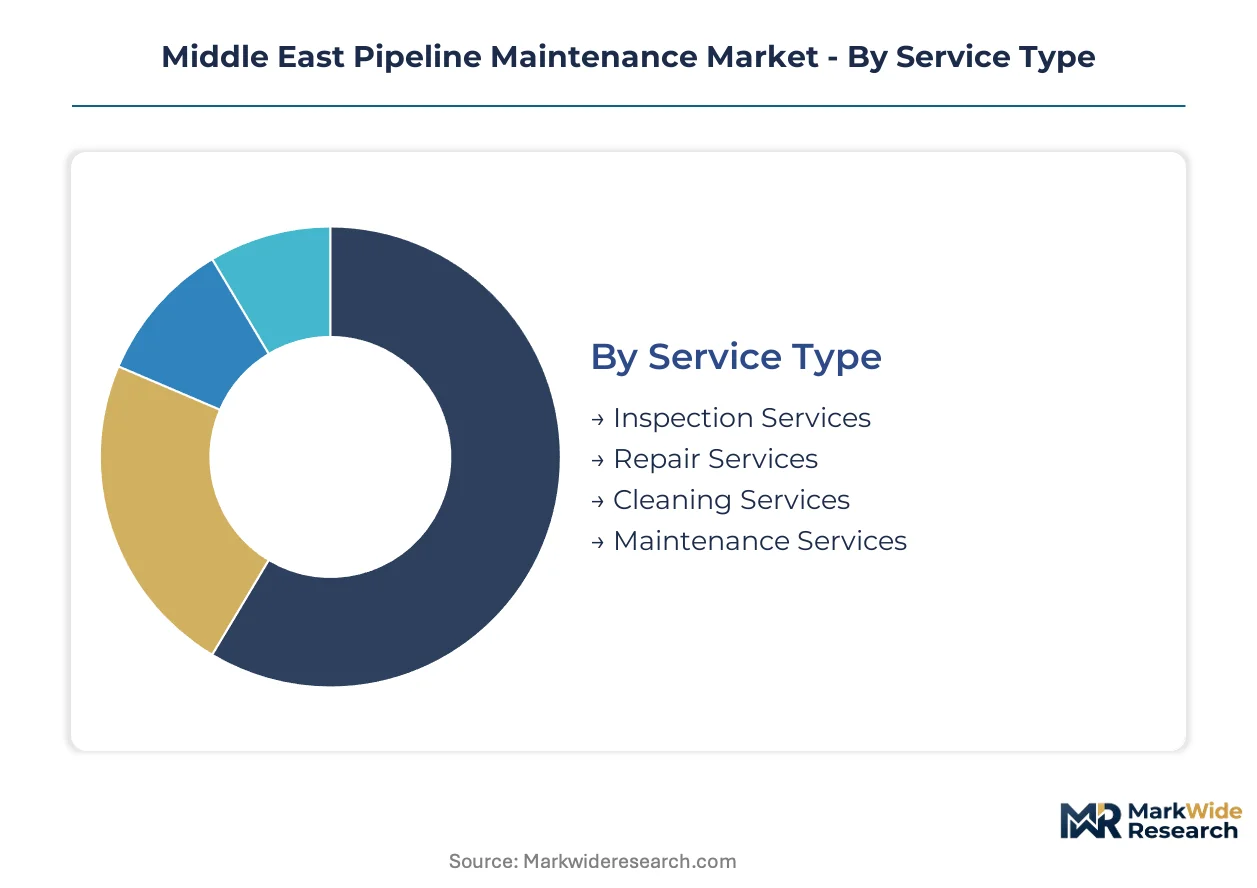
Segmentation in Middle East pipeline maintenance reveals how capital allocation priorities differ across service models, technology readiness, and operator risk tolerance. Understanding these divisions exposes where vendor margins concentrate versus where commoditization pressures intensify.
Service Type:
Inspection Services turn over fastest with quarterly regulatory cycles, while Repair Services concentrate around episodic integrity failures with multi-year intervals between major campaigns.
- Inspection Services:Non-destructive evaluation using magnetic flux leakage and ultrasonic methods dominates recurring revenue streams. Saudi Aramco's East-West crude corridor and ADNOC's Habshan-Fujairah line generate continuous demand for in-line inspection tool runs without flow interruption.
- Repair Services:Weld remediation, sleeve installation, and hot-tapping operations address corrosion-induced wall loss. Iraq's Basra field cluster and Iran's aging Ahvaz network create concentrated demand for emergency clamp deployment and composite reinforcement systems.
- Cleaning Services:Pigging operations remove wax, scale, and debris from crude and product lines. The service commands premium pricing in heavy oil corridors where paraffin deposition accelerates.
- Maintenance Services:Integrated integrity management contracts span cathodic protection, coating rehabilitation, and valve maintenance. These multi-year agreements favor established contractors with SFDA and MOHAP certification portfolios.
Inspection Services dominates installed base. Repair Services is where expansion concentrates.
Technology:
Cost tiering separates established methods from emerging platforms, with legacy hydrostatic testing anchoring budget segments while robotic systems capture technology premiums.
- Hydrostatic Testing:Pressure verification using water or nitrogen remains mandatory for new construction and post-repair validation. The method requires pipeline shutdowns, creating revenue loss that operators increasingly resist.
- Ultrasonic Testing:Phased-array systems deliver sub-millimeter crack detection accuracy across Saudi Aramco's sour gas infrastructure. SFDA mandates for high-pressure H2S lines sustain demand for certified ultrasonic technicians.
- Acoustic Monitoring:Real-time leak detection via fiber-optic or sensor arrays enables continuous surveillance without excavation. Kuwait's KNPC deploys these systems across populated corridor segments near Ahmadi refinery complexes.
- Robotic Inspection:Tethered crawlers and autonomous platforms traverse live pipelines transmitting wall-thickness data to centralized dashboards. The technology eliminates shutdown revenue loss and commands technical specification roles in ADNOC and Saudi Aramco tenders.
Ultrasonic Testing anchors compliance-driven procurement. Robotic Inspection is climbing the fastest as operators prioritize production continuity.
End User:
Volume concentration aligns with hydrocarbon export scale, with national oil companies dwarfing municipal and utility demand in absolute spending.
- Oil & Gas Companies:National operators across Saudi Arabia, UAE, Kuwait, and Qatar account for dominant maintenance expenditure. Their internal engineering standards and localization mandates reshape vendor qualification requirements.
- Utilities:Power sector operators maintain fuel gas delivery infrastructure feeding combined-cycle plants. Dubai Electricity and Water Authority contracts for pipeline integrity support generation reliability targets.
- Municipalities:City-level operators manage localized distribution networks for natural gas and refined products. Their procurement favors standardized maintenance packages over customized engineering solutions.
- Industrial Facilities:Petrochemical complexes and fertilizer plants operate dedicated feedstock pipelines requiring specialized corrosion monitoring. SABIC's Jubail complex generates recurring demand for inspection services tailored to high-temperature hydrocarbon streams.
Oil & Gas Companies dominate installed base. Industrial Facilities is where expansion concentrates.
Maintenance Type:
Maturity differentiation separates predictive platforms with data analytics integration from reactive models triggered by failure events.
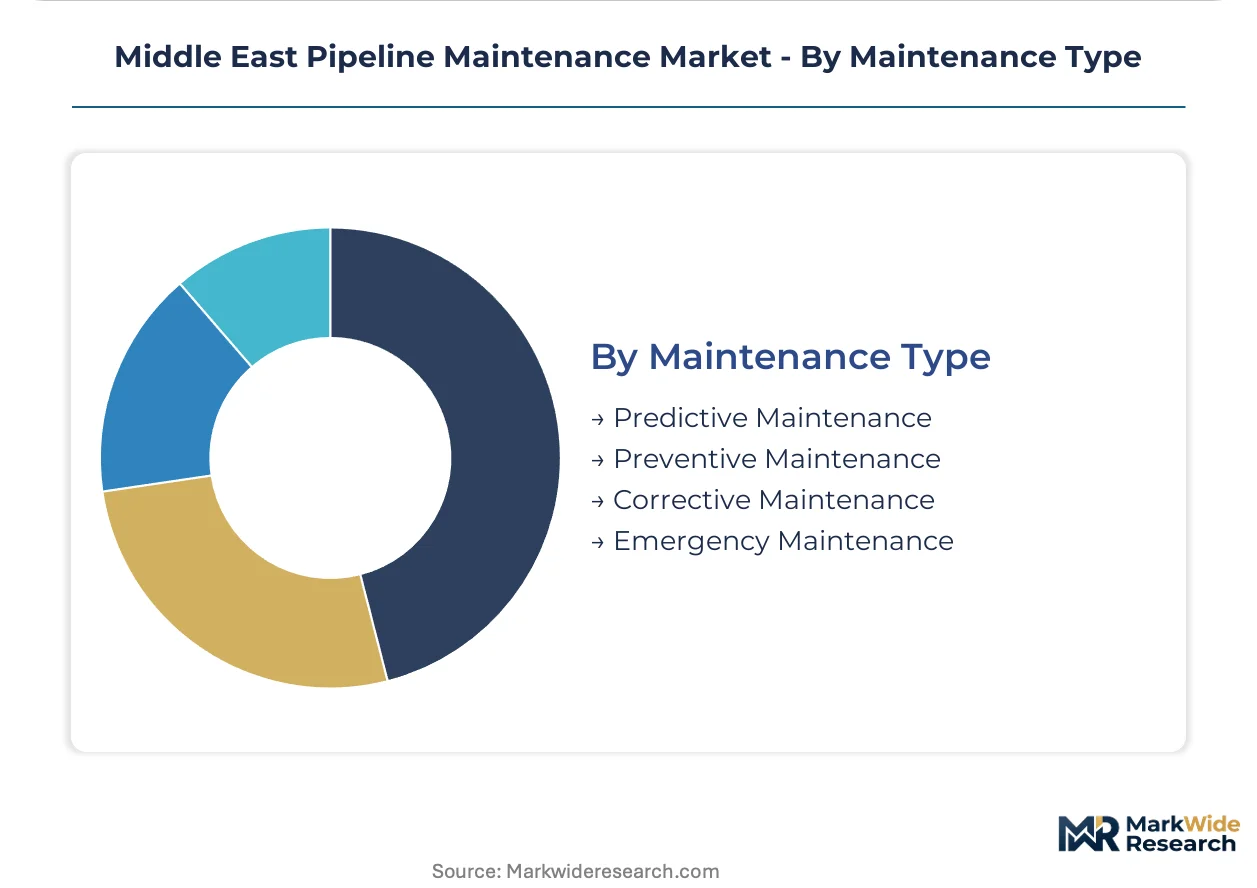
- Predictive Maintenance:Machine learning models trained on acoustic emission and corrosion rate data enable preemptive intervention scheduling. Saudi Aramco's digital twin initiatives embed predictive capabilities across high-pressure transmission corridors.
- Preventive Maintenance:Scheduled inspection and component replacement based on time or throughput intervals. The model retains dominance in older facilities lacking sensor infrastructure for condition-based monitoring.
- Corrective Maintenance:Post-failure repair responding to leaks, ruptures, or pressure anomalies. Iraqi infrastructure deferred maintenance has elevated corrective spending as a share of total maintenance outlays.
- Emergency Maintenance:Unplanned mobilization for containment, isolation, and repair following catastrophic failure. MOHAP fire code mandates for redundant isolation verification extend emergency response timelines and inflate standby costs.
Preventive Maintenance dominates installed base. Predictive Maintenance is gaining share fastest as national operators compress inspection cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium pricing for robotic inspection services while Iraq's deferred maintenance backlog forces contractors toward commodity-rate corrective repairs. This asymmetry shapes vendor deployment strategies across the Gulf.
Saudi Arabia
Saudi Aramco's East-West crude corridor and Habshan-Fujairah line generate continuous demand for in-line inspection tools. SFDA mandates ultrasonic testing intervals for sour gas infrastructure, compressing vendor certification cycles. The Eastern Province pipeline cluster concentrates robotic crawler deployment and predictive analytics integration.
United Arab Emirates
ADNOC's Habshan-Fujairah line and offshore marine terminals sustain demand for subsea inspection robotics. MOHAP's 2023 Fire and Life Safety Code mandates continuous pressure monitoring within 500 meters of population centers. Dubai and Abu Dhabi emirate corridors accelerate wireless transmitter installation across transmission networks.
Iraq
Decades of deferred maintenance across Basra and Kirkuk fields generate concentrated weld remediation and coating replacement contracts. The Ministry of Oil pipeline integrity directives mandate systematic pressure testing without established certification frameworks. Basra field cluster contractors face extended mobilization timelines due to security and customs constraints.
Kuwait
KNPC's Al-Zour refinery integration with marine terminals creates demand for subsea robotics and cathodic protection systems. Kuwait's national oil company requires real-time corrosion monitoring across Ahmadi refinery corridor segments. Ahmadi complex operators deploy acoustic monitoring arrays near populated zones.
Qatar
North Field expansion sustains demand for high-pressure pipeline integrity services across offshore and onshore infrastructure. QatarEnergy's engineering standards emphasize hot-tap isolation and pressure-testing protocols for sour gas lines. Ras Laffan industrial city concentrates maintenance contracting for LNG feedstock pipelines.
Middle East Pipeline Maintenance Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base concentrates around three strata: international oilfield service conglomerates with bundled offerings, regional engineering contractors with localization credentials, and niche technology providers with proprietary isolation or inspection systems. Strategic consolidation centers on predictive analytics capability acquisition and joint venture formation with indigenous firms to satisfy local content mandates.
Within the specialized technology tier, T D Williamson Inc and STATS Group exemplify narrow technical positioning. Halliburton Company anchors the integrated service vector. Saudi Aramco operates as both client and internal service provider, compressing available contract scope for external vendors. Rezayat Group and EEW Group represent regional fabrication and construction interests with proximity advantages. The competitive calculus rewards certification depth over geographic breadth, particularly for SFDA and MOHAP compliance credentials.
| Leading Market Players |
|---|
| Saudi Aramco |
| Rezayat Group |
| EEW Group |
| T D Williamson Inc |
| ExxonMobil Corporation |
| BP PLC |
| Halliburton Company |
| Arabian Pipes Company |
| STATS Group |
| Others |
Value Chain & Pricing Dynamics
East Asian mill concentration for high-grade chromium-molybdenum steel creates simultaneous pricing tier compression and supply chain fragility across Middle East pipeline maintenance. SFDA certification requirements for sour gas inspection services widen spreads between certified premium providers and uncertified commodity competitors while forcing contractors into single-source alloy dependencies.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with project-based supplements for emergency mobilization. Price differentiation separates SFDA-certified ultrasonic technicians from uncertified competitors, with volume scale and after-sales service bundling as secondary tiering factors. Pricing pressure stems from service unbundling by Saudi Aramco, which fragments bundled maintenance contracts into discrete competitive tenders. National oil companies exhibit lowest price sensitivity due to production continuity premiums, while municipal utilities and small industrial facilities drive commodity-tier competition.
Supply Chain Analysis
Upstream chromium-molybdenum steel production concentrates in China, Japan, and South Korea, with specialized hot-tap fittings fabrication tethered to East Asian mill output. Robotic crawler components, magnetic flux leakage sensors, and ultrasonic phased array equipment draw from German, Japanese, and US precision manufacturing bases. Single-source vulnerability runs through high-grade alloy supply, where customs delays and freight volatility disrupt contractor mobilization timelines. Distribution runs through regional engineering contractors with SFDA and MOHAP certification portfolios, who subcontract specialized inspection and isolation services from international technology providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of API 1169-certified inspectors and robotic systems engineers concentrates margin capture with credential-rich incumbents while constraining expansion velocity for aspirants. This capability gap shapes competitive dynamics across all stakeholder positions.
For Market Incumbents: Entrench through backward integration into robotic crawler manufacturing and predictive analytics software development to capture technology premiums eroding from hardware commoditization. Deepen SFDA and MOHAP certification depth to exploit regulatory chokepoints that constrain foreign competitor access. Defend against service unbundling by Saudi Aramco through modular service packaging that preserves relationship continuity across discrete tender scopes. For New Entrants and Emerging Players: Pursue white-space positioning in Iraqi corrective maintenance markets, where deferred infrastructure backlogs and absent certification frameworks reduce incumbent advantages. Target Kuwait offshore subsea inspection robotics, where KNPC's Al-Zour refinery integration creates demand without established vendor relationships. Enter through joint venture structures with indigenous engineering firms to satisfy Saudi Aramco's In-Kingdom Total Value Add mandates. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors predictive analytics platforms over legacy inspection hardware. Long-term viability hinges on software-enabled recurring revenue models displacing episodic project contracting. Acquisition candidates with machine learning-trained anomaly detection capabilities and established national operator data integration represent priority targets. Monitor Saudi Aramco procurement unbundling velocity as inflection signal for platform consolidation versus fragmentation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Acquisition | Machine learning integration with Saudi Aramco digital twin initiatives captures recurring revenue streams. |
| SFDA Certification Investment | Regulatory credentialing creates protected demand cycles for sour gas inspection services. |
| Joint Venture with Indigenous Engineering Firms | In-Kingdom Total Value Add compliance unlocks Saudi Aramco contract access for foreign technology providers. |
| Robotic Crawler Manufacturing Scale-Up | In-house production of magnetic flux leakage platforms reduces East Asian supply dependency. |
| Iraq Market Entry Partnership | Basra field cluster rehabilitation contracts offer first-mover positioning in deferred maintenance backlog. |
Study Parameters
Desk research of trade customs data, national oil company procurement disclosures, and SFDA regulatory filings preceded structured interviews with pipeline integrity managers, robotic inspection technology directors, and EPC contractors. Primary fieldwork with maintenance operations executives at Saudi Aramco, ADNOC, and KNPC validated service demand assumptions. Secondary triangulation incorporated API certification databases, ultrasonic equipment manufacturer shipment records, and regional engineering contractor financial disclosures. Bottom-up segment sizing across service type, technology, and end-user dimensions was cross-checked against top-down hydrocarbon transmission infrastructure investment forecasts.
Forecast assumptions held fixed the current regulatory enforcement trajectory for SFDA and MOHAP mandates while varying robotic inspection adoption rates and predictive maintenance penetration across national operator fleets. The analytical framework modeled service type, technology readiness tier, end-user scale category, and maintenance model maturity across the projection horizon. CAGRs were derived from segment-level demand build-ups incorporating inspection cycle compression, infrastructure age profiles, and localization requirement intensification. Industry-specific inputs included Saudi Aramco East-West pipeline integrity spending patterns and Iraqi Ministry of Oil rehabilitation priority rankings.
Sensitivities concentrate around regulatory enforcement variance, East Asian alloy supply disruption scenarios, and national operator procurement unbundling velocity. Forecasts reflect assumptions regarding SFDA certification backlog resolution and robotic crawler interoperability with legacy SCADA infrastructure. Cross-checking against IEA Middle East hydrocarbon export capacity investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Pantograph Disconnector Market