
 Asia Pacific LNG Infrastructure Market | 2026-2036
Asia Pacific LNG Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific LNG Infrastructure Market Outlook
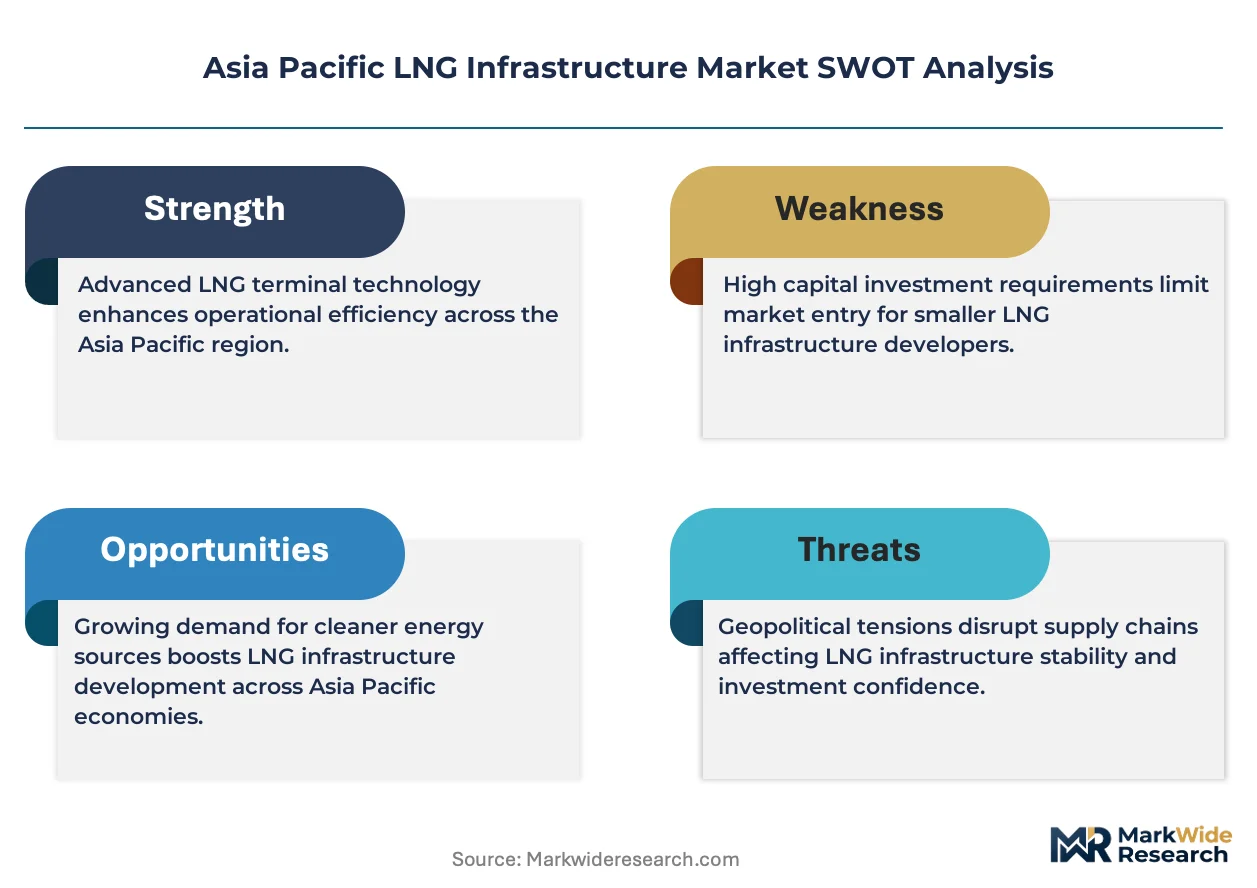
Capital-intensity divergence between integrated EPC consortia and specialized fabricators is unwinding traditional procurement hierarchies in LNG terminal development. Bechtel Corporation leverages its modular construction expertise to compress project schedules for Australian brownfield expansions. Chiyoda Corporation anchors its competitive position through proprietary cryogenic storage technology and longstanding relationships with Japanese trading houses. JGC Holdings Corporation specializes in floating LNG solutions that reduce capex exposure for resource-constrained national oil companies.
Asia Pacific LNG infrastructure encompasses the physical systems for liquefying, transporting, storing, and regasifying natural gas at temperatures below minus 162 degrees Celsius, primarily serving baseload power generation and industrial feedstock substitution. Floating LNG installations are capturing share from land-based terminals where coastal land scarcity and environmental permitting create bottlenecks, particularly along Japan's densely populated Pacific seaboard. Regasification terminals remain the margin-dominant segment due to long-term take-or-pay contracts and tariff-regulated returns, while storage facilities face pressure from spot-market volatility and working-capital intensity.
Japan's METI enforces stringent seismic design standards for onshore LNG facilities through its technical ordinance on high-pressure gas safety, directly elevating engineering costs and favoring experienced Japanese contractors. Australia's NOPSEMA and China's MEE impose divergent environmental assessment protocols for offshore LNG projects, fragmenting contractor qualification requirements across the region. Stakeholders must weigh carbon border adjustment exposure against brownfield asset life extensions when committing capital to new import capacity.
Market Dynamics
Floating LNG technology is compressing project timelines and capital requirements for island nations lacking deepwater port infrastructure, fundamentally altering how regasification capacity enters service across Southeast Asia.
Growth Catalysts
- Coal phase-out mandates:Power generation utilities in Indonesia, Vietnam, and the Philippines face binding emissions reduction targets under national energy transition frameworks, accelerating LNG offtake for baseload replacement.
- SKK Migas domestic gas obligations:Indonesia's upstream regulator enforces minimum domestic market requirements that redirect supply toward power sector conversion programs and industrial zone development.
- Modular fabrication methods:Standardized cryogenic module production is reducing site construction duration and labor exposure for Australian brownfield expansions and greenfield terminals in Papua New Guinea.
Market Restraints
- Nickel alloy supply concentration:Cryogenic storage tank fabrication depends on specialized 9% nickel steel supply dominated by Japanese and Korean mills, creating input cost volatility and delivery uncertainty.
- Seismic engineering premiums:Japan's METI technical ordinance on high-pressure gas safety mandates earthquake-resistant design standards that elevate structural steel requirements and foundation costs for onshore facilities.
- Electrification substitution:Grid-scale battery storage and renewable hydrogen pilot programs are capturing utility capex allocations that previously flowed to LNG import infrastructure.
Strategic Opportunities
- Small-scale LNG distribution:Island provinces in Indonesia and the Philippines lack pipeline connectivity, creating demand for ISO containerized delivery networks serving remote industrial clusters and power barges.
- Carbon capture integration:Australia's NOPSEMA environmental assessment protocols now recognize post-combustion capture retrofits as mitigating factors in offshore project approvals, enabling asset life extensions.
- Bio-LNG blending infrastructure:Singapore's maritime regulator is mandating lower-carbon fuel standards for bunkering that require terminal modifications to handle biomethane and synthetic methane co-streams.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified technicians for 9% nickel steel and aluminum alloy joining remain concentrated in Japan, Korea, and Australia, constraining workforce deployment for regional projects.
- Environmental permitting timelines:China's MEE and Australia's NOPSEMA operate divergent assessment protocols for offshore LNG facilities, fragmenting contractor qualification requirements and extending front-end engineering phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific LNG Infrastructure Market |
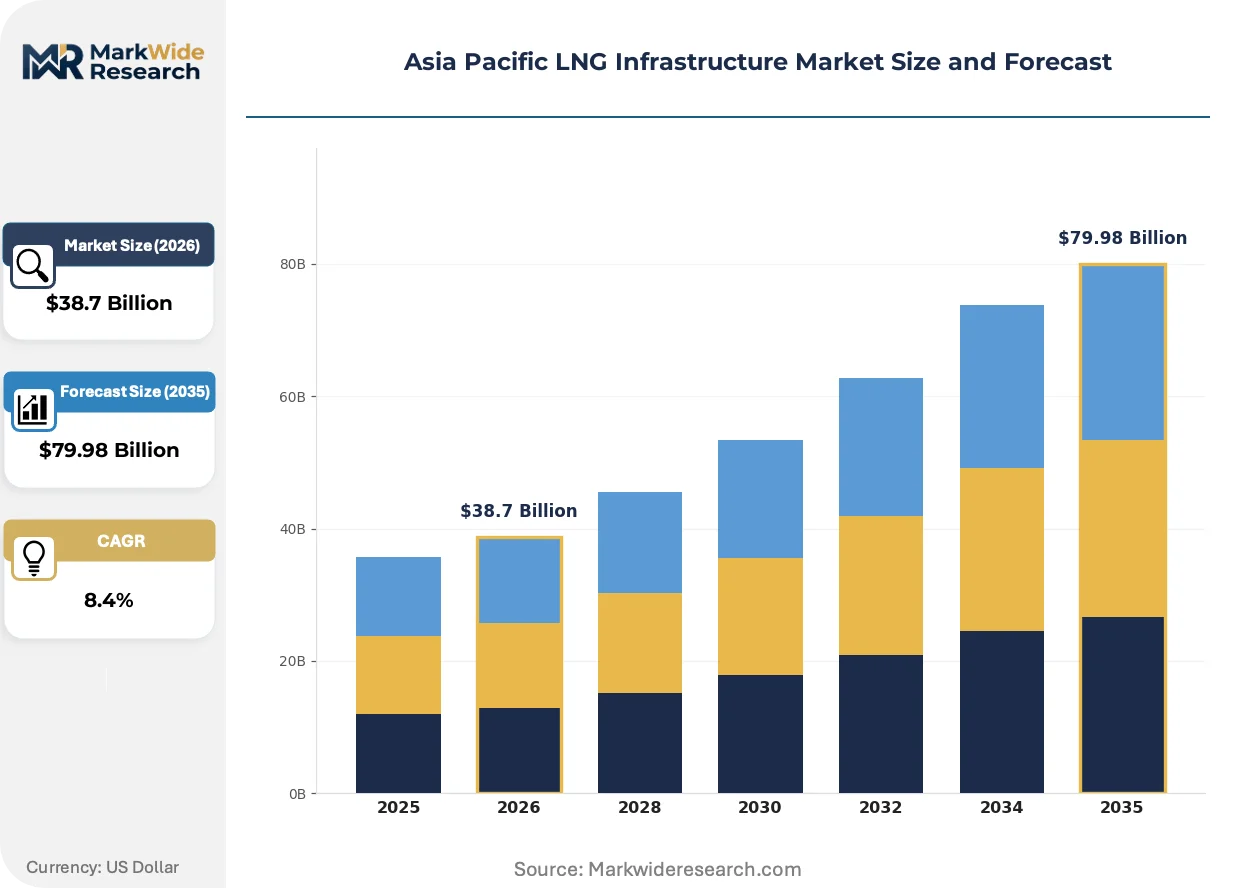
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Floating LNG, Land-based LNG, Regasification Terminals, Storage Facilities Application: Power Generation, Industrial Use, Transportation, Residential Heating End User: Utilities, Oil & Gas Companies, Manufacturers, Commercial Entities Deployment: Onshore, Offshore, Integrated Systems, Modular Installations |
| Companies Covered | Fluor Corporation, Saipem SpA, JGC Holdings Corporation, Petroliam Nasional Berhad (PETRONAS), Technip Energies, Chiyoda Corporation, Chevron Corporation, China Harbour Engineering Company, Bechtel Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific LNG Infrastructure Market Strategic Shifts
Technology convergence and regulatory stringency are compressing traditional procurement hierarchies while opening white space for specialized fabricators and floating solutions providers across the Asia Pacific basin.
Modular cryogenic storage systems are bifurcating project delivery models between integrated EPC consortia and specialized fabricators. Japanese trading houses are contracting directly with tank module suppliers to compress construction schedules for urban regasification sites. This technology is bifurcating competitive positioning between full-service contractors and component specialists.
Australia's NOPSEMA and China's MEE are tightening environmental assessment protocols for offshore LNG projects, extending front-end timelines but creating differentiation for contractors with established regulatory track records. The industrial consequence is elevated pre-FEED expenditure and earlier stakeholder engagement requirements. Regasification terminals in Japan and Korea face the most pronounced compliance cost inflation and are responding with integrated environmental management systems.
Power utilities are consolidating procurement authority at national holding company levels, displacing plant-level contracting autonomy. This concentration is disrupting traditional equipment vendor relationships and favoring framework agreements with multi-site service obligations. The shift is most visible in Indonesia, where PLN's central procurement directorate now controls LNG offtake negotiations for generation assets across the archipelago.
Asia Pacific LNG Infrastructure Market Segmentation
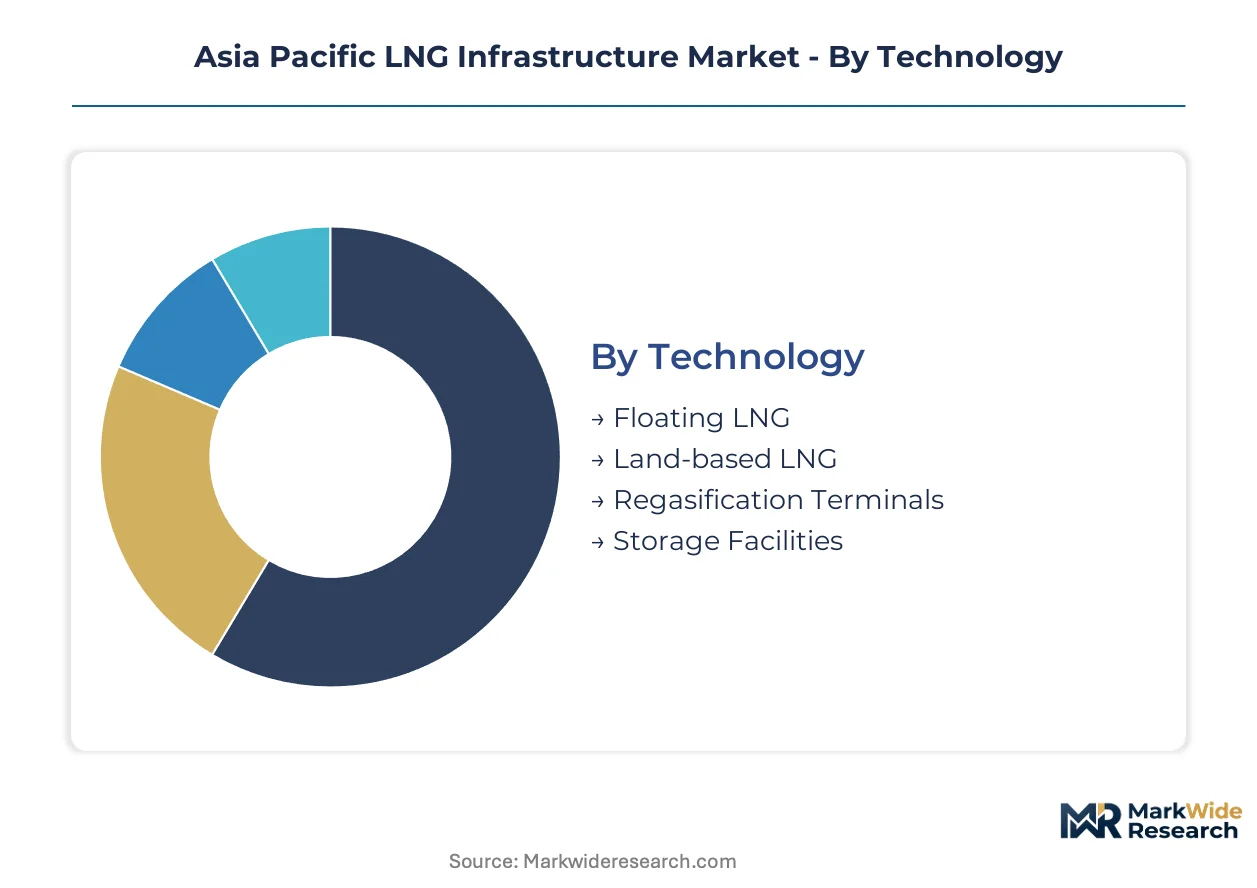
LNG infrastructure investment flows through distinct technology and deployment channels that reshape contractor qualification requirements across the Asia Pacific basin. Procurement patterns diverge sharply between floating solutions for island nations and land-based systems for industrial corridor development.
Technology:
Floating LNG modules and land-based terminals move through fundamentally different contracting channels, with specialized fabricators capturing share in modular deployment while integrated consortia dominate complex regasification projects.
- Floating LNG:Offshore production and regasification vessels eliminate deepwater port requirements for archipelagic nations. Indonesia and the Philippines are deploying FSRU solutions where coastal land scarcity and environmental permitting bottlenecks block conventional terminal development.
- Land-based LNG:Permanent liquefaction trains and receiving terminals anchor supply security for major demand centers. Japanese utilities favor these systems for baseload power security despite METI-mandated seismic engineering premiums that elevate structural steel requirements.
- Regasification Terminals:Long-term take-or-pay contracts and tariff-regulated returns dominate margin structures.
- Storage Facilities:Spot-market volatility pressures working-capital intensity for merchant operators.
Regasification terminals dominate installed base. Floating LNG is where expansion concentrates.
Application:
Cost tier differentiation separates baseload power contracts from spot-responsive industrial offtake, with transportation and residential segments commanding premium infrastructure specifications.
- Power Generation:Baseload electricity production drives the majority of regional LNG demand as coal phase-out mandates tighten across Southeast Asia. PLN's conversion program in Indonesia and Vietnam's national energy transition framework are redirecting utility capex toward gas-fired capacity.
- Industrial Use:Petrochemical feedstock and process heat applications require consistent supply quality and pressure specifications. Manufacturing clusters in Thailand and Malaysia are substituting fuel oil and coal with pipeline gas delivered through dedicated industrial zone infrastructure.
- Transportation:Marine bunkering and heavy-duty trucking create distributed demand patterns.
- Residential Heating:Limited penetration outside Japan and Korea due to pipeline network gaps.
Power generation commands the largest capacity commitments. Industrial use is climbing the fastest as feedstock substitution accelerates.
End User:
Customer type determines contracting structure, with national utilities consolidating procurement authority while oil and gas companies retain project development autonomy.
- Utilities:State-owned power generators are centralizing LNG offtake negotiations at holding company levels, displacing plant-level contracting autonomy. This concentration favors framework agreements with multi-site service obligations across generation portfolios.
- Oil & Gas Companies:Integrated energy majors and national oil companies control upstream supply and midstream infrastructure development. These entities balance domestic market obligations against export economics under divergent regulatory frameworks.
- Manufacturers:Industrial consumers seek direct terminal access to bypass utility markups.
- Commercial Entities:Distributed energy users drive small-scale LNG containerization demand.
Utilities anchor contracted capacity volumes. Oil and gas companies control greenfield development decisions.
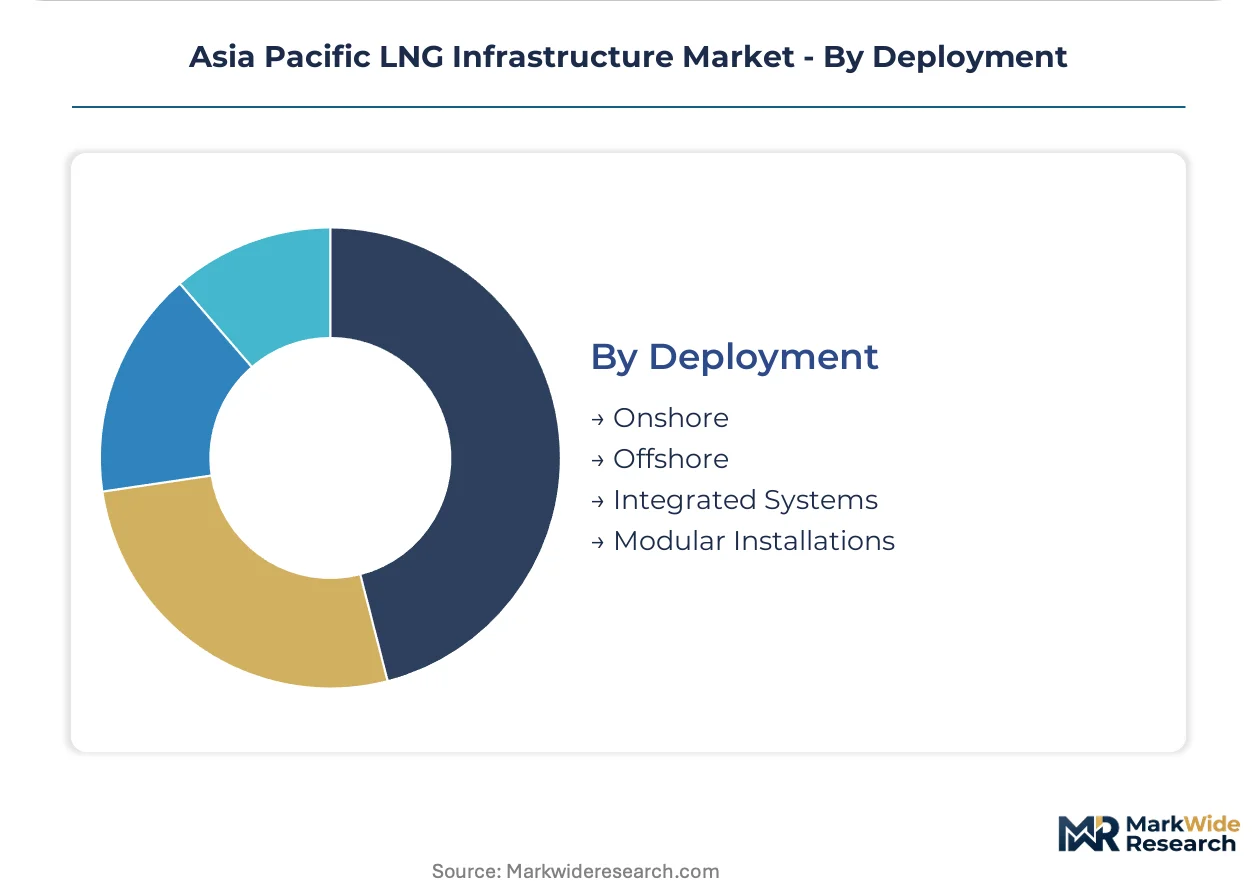
Deployment:
Supply concentration in cryogenic module fabrication creates divergent margin structures between onshore site construction and offshore integrated systems.
- Onshore:Fixed installations with permanent foundations and extensive civil works dominate established demand centers. Japan's Pacific seaboard and Australia's eastern coast concentrate these assets where grid connectivity and industrial load density justify capital intensity.
- Offshore:Floating production and regasification systems compress project timelines for resource-constrained developers. Papua New Guinea and Indonesian frontier basins deploy these solutions where onshore construction logistics prove prohibitive.
- Integrated Systems:Combined liquefaction, storage, and export functionality reduces interface risk.
- Modular Installations:Standardized cryogenic module production reduces site labor exposure.
Onshore systems retain the deepest installed base. Modular installations are gaining share fastest as fabrication standardization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia exhibits the highest demand elasticity as PLN negotiates spot cargoes against contracted volumes, while Japan's utility buyers absorb premium pricing for supply security under METI's energy security mandates.
Indonesia
PLN's power sector conversion program and domestic gas obligations under SKK Migas regulations are accelerating import terminal development across the archipelago. The regulator enforces minimum domestic market requirements that redirect supply toward industrial zone development in Java and Sumatra. Tangguh and Bontang anchor liquefaction capacity while Java's northern coast concentrates new FSRU deployments.
Japan
Baseload power security requirements sustain contracted offtake despite grid-scale battery storage expansion. METI's technical ordinance on high-pressure gas safety mandates earthquake-resistant design standards that elevate structural steel requirements. Tokyo Bay and Osaka Bay industrial corridors concentrate regasification terminals where land scarcity favors floating solutions.
Australia
Brownfield expansion programs and carbon capture retrofits under NOPSEMA protocols extend asset life for eastern basin operators. The environmental regulator recognizes post-combustion capture as a mitigating factor in offshore project approvals. Queensland's Curtis Island and Western Australia's Pilbara region anchor liquefaction export capacity.
Vietnam
National energy transition framework commitments are redirecting utility capex from coal toward gas-fired baseload capacity. The Ministry of Industry and Trade oversees power development planning that mandates LNG import infrastructure for southern generation clusters. Ba Ria-Vung Tau province concentrates terminal development near the Phu My industrial zone.
Singapore
Maritime bunkering demand and lower-carbon fuel standards are driving terminal modifications for bio-LNG blending. The Maritime and Port Authority mandates progressive carbon intensity reductions for vessel refueling operations. Jurong Island anchors storage and bunkering infrastructure serving regional shipping lanes.
Asia Pacific LNG Infrastructure Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that captures share in modular fabrication and cryogenic component supply. Japanese and Korean trading houses consolidate procurement authority through framework agreements with multi-site service obligations. Two strategic archetypes dominate: full-service EPC consortia delivering integrated liquefaction trains, and specialized fabricators supplying standardized storage modules. Competitive moves center on modular construction partnerships and carbon capture integration capabilities.
Among integrated EPC consortia, Bechtel Corporation and Fluor Corporation represent the scale-driven tier with multi-decade track records in Australian brownfield expansions. Chiyoda Corporation and JGC Holdings Corporation anchor the Japanese specialist segment, with the latter exemplifying floating LNG solution providers that reduce capex exposure for resource-constrained national oil companies. Technip Energies and Saipem SpA occupy positions within the European engineering tier focused on offshore integrated systems.
| Leading Market Players |
|---|
| Fluor Corporation |
| Saipem SpA |
| JGC Holdings Corporation |
| Petroliam Nasional Berhad (PETRONAS) |
| Technip Energies |
| Chiyoda Corporation |
| Chevron Corporation |
| China Harbour Engineering Company |
| Bechtel Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term take-or-pay contracts anchor LNG terminal economics across the Asia Pacific basin, locking in supply access for power utilities while capping price volatility exposure under METI-mandated tariff structures in Japan and PLN's centralized procurement frameworks in Indonesia.
Pricing Analysis
After-sales service contracts for cryogenic maintenance and seismic retrofitting drive lifetime value for Japanese and Korean EPC providers. Three-tier pricing structure across premium, standard, and economy levels separates integrated consortium bids from modular fabricators and spot-market equipment suppliers. Cost compression in standardized storage modules is intensifying because Indonesian and Philippine developers prioritize capex reduction over customization. Industrial zone offtakers in Thailand and Malaysia exhibit the highest price sensitivity, while Japanese utilities absorb premium engineering costs for baseload security.
Supply Chain Analysis
Japan and South Korea anchor specialized 9% nickel steel production for cryogenic storage tanks, while Australia and Papua New Guinea concentrate modular fabrication yards for brownfield expansions. LNG infrastructure draws from aluminum alloy welding consumables, seismic-grade structural steel, and subsea pipeline coatings. Single-source vulnerability in cryogenic welding certification creates workforce deployment bottlenecks for regional projects. Distribution runs through Japanese trading house procurement networks and Australian EPC consortium direct contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in floating LNG deployment, as archipelagic nations lacking deepwater port infrastructure create demand niches outside the reach of integrated EPC consortia optimized for land-based megaprojects.
For Market Incumbents: Secure cryogenic welding certification pipelines through partnerships with Japanese and Korean technical institutes to defend against workforce scarcity threatening project schedules. Anchor backward integration into modular fabrication yards in Australia and Papua New Guinea to compress delivery timelines for brownfield expansions. METI's escalating seismic engineering premiums favor contractors with established regulatory track records over price-competitive challengers. For New Entrants and Emerging Players: ISO 9001 and ASME certification fast-tracks open procurement access for specialized tank module suppliers serving Indonesia's FSRU rollout and Vietnam's southern generation clusters. Target small-scale LNG containerization networks for remote industrial zones in the Philippines and eastern Indonesian islands where pipeline gaps persist. Partner with local construction firms to bypass established EPC consortium relationships in PLN's centralized procurement system. For Investors and Strategic Acquirers: Cryogenic component specialists with proprietary aluminum alloy joining techniques and established NOPSEMA regulatory track records command acquisition premiums as environmental assessment timelines extend. Long-term viability hinges on carbon capture integration capabilities enabling Australian asset life extensions under tightening emissions protocols. Watch for inflection when Singapore's maritime bio-LNG blending mandates trigger terminal modification capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Floating LNG Deployment | FSRU solutions bypass coastal land scarcity and environmental permitting bottlenecks in Indonesia and the Philippines. |
| Modular Fabrication Partnership | Standardized cryogenic module production compresses site construction duration for Australian brownfield expansions. |
| Carbon Capture Integration | NOPSEMA recognition of post-combustion capture retrofits enables asset life extensions for eastern basin operators. |
| Cryogenic Certification Pipeline | Japanese and Korean welding technician training partnerships secure workforce deployment for regional project backlogs. |
| Bio-LNG Terminal Modification | Singapore Maritime and Port Authority mandates drive infrastructure adaptation for lower-carbon bunkering standards. |
Study Parameters
Desk research of EIA country energy balances, IEA gas market reports, and SKK Migas regulatory filings preceded structured interviews with utility planning officers, EPC project directors, cryogenic fabrication specialists, and maritime bunkering operators. Primary fieldwork with Japanese trading house procurement teams and Australian NOPSEMA compliance officers validated secondary data on environmental assessment timelines. Bottom-up terminal capacity modeling triangulated against top-down national energy transition framework targets across the analysis window.
Variance-decomposition framing separated volume drivers by technology deployment mode, application segment, and national regulatory cluster throughout the forecast period. Segmentation dimensions encompassed floating versus land-based systems, power generation versus industrial offtake, and centralized utility procurement versus oil company-led development. CAGRs derived from project pipeline aggregation and contracted capacity roll-forward analysis. Forecast inputs incorporated PLN's power sector conversion program timelines and METI's seismic engineering cost inflation assumptions.
Decision-makers should treat outputs as directional under sustained coal phase-out policy commitment and nickel alloy supply stability; material deviation in either assumption would warrant model refresh. Recalibration cycles align with material shifts in national energy transition framework revisions and floating LNG technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market