
 Submarine Batteries Market | 2026-2036
Submarine Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Batteries Market Intelligence
The direct-to-defense procurement model for naval contracts is reshaping competitive positioning among submarine battery manufacturers. EnerSys leverages its extensive industrial battery portfolio to serve diverse naval requirements. GS Yuasa specializes in advanced lithium-ion technologies for next-generation platforms. HBL Power Systems Ltd. occupies a strategic role within defense supply chains in key Asian markets, providing customized power solutions for regional naval forces.
Submarine batteries are specialized energy storage systems engineered for underwater propulsion and auxiliary power. These systems must deliver sustained electrical output under extreme hydrostatic pressure and ensure operational silence for military applications. The lithium-ion battery type represents the fastest-growing segment due to its superior energy density, while traditional lead-acid batteries maintain a significant installed base in older fleets. Within applications, military submarines constitute the largest market, but demand for power sources in autonomous underwater vehicles is accelerating rapidly.
Naval classification society standards, such as those from DNV or Lloyd's Register, dictate performance and safety requirements for all onboard systems. Concurrently, environmental regulations like the EU's Battery Regulation and international maritime laws influence material choices and end-of-life disposal protocols. Stakeholder decisions will increasingly balance the reliability of established battery chemistries against the strategic advantages offered by emerging high-density power solutions.
Market Dynamics
The fundamental dynamic shaping the submarine battery market is the technological transition from conventional lead-acid chemistries to advanced lithium-ion systems. This shift is driven by naval demands for greater underwater endurance, speed, and stealth capabilities.
Growth Catalysts
- Naval Modernization Programs:National defense strategies, particularly in countries like India, are accelerating the procurement of new submarines and the retrofitting of existing fleets, directly boosting battery demand.
- Lithium-Ion Adoption:The superior energy density and longer cycle life of lithium-ion batteries enable extended mission durations for both military submarines and autonomous underwater vehicles.
- Autonomous Systems Growth:The expanding use of AUVs for maritime surveillance, scientific research, and commercial exploration creates a new, fast-growing demand vector for compact, high-endurance power sources.
Market Restraints
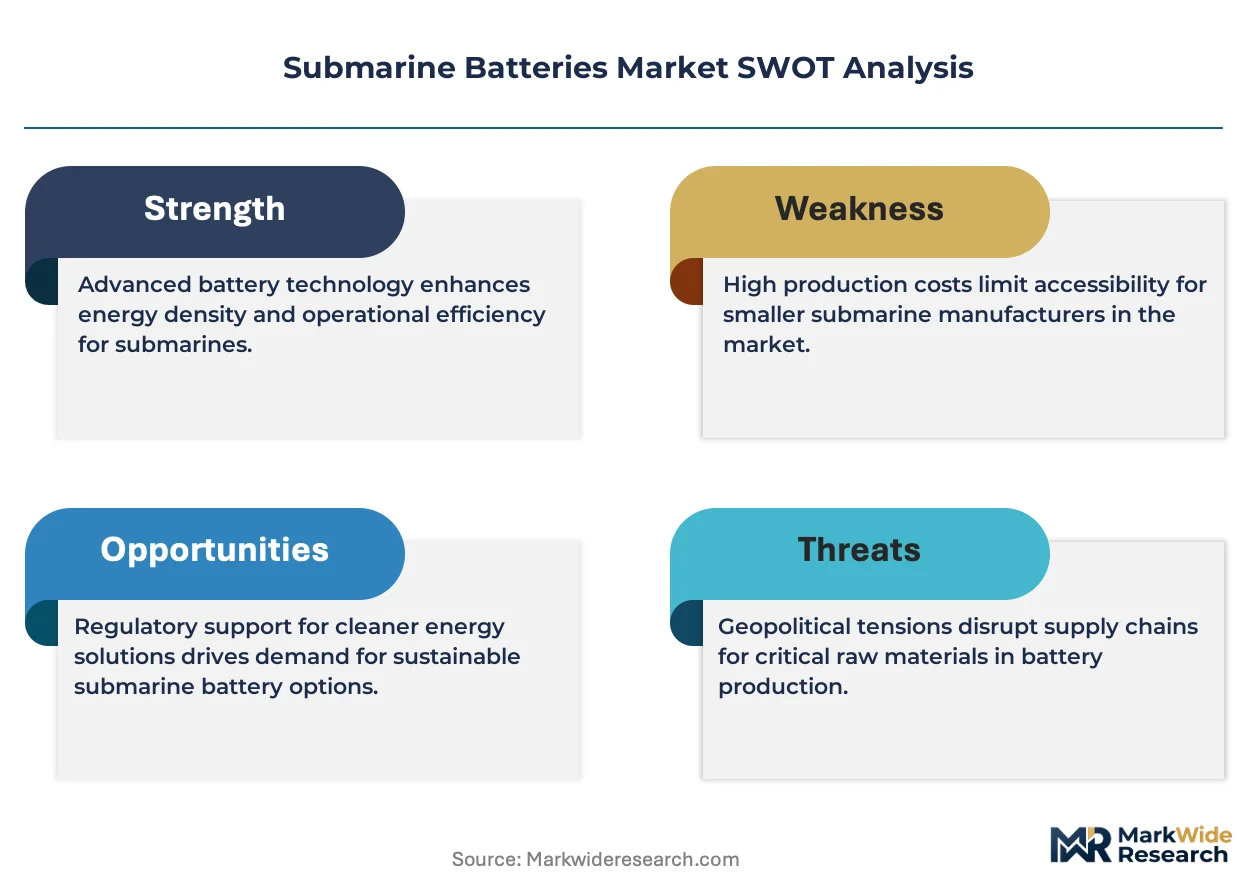
- High Capital Costs:The initial investment for lithium-ion battery systems, including associated cooling and safety infrastructure, is significantly higher than for traditional lead-acid technologies, slowing fleet-wide adoption.
- Stringent Qualification Standards:Naval classification societies like DNV and Lloyd's Register impose rigorous and lengthy testing protocols, creating high barriers to entry for new battery chemistries and suppliers.
- Thermal Management Complexity:High-density lithium-ion batteries generate substantial heat, requiring sophisticated and failure-proof thermal management systems to prevent catastrophic failure in a confined, submerged environment.
Strategic Opportunities
- Solid-State Battery Development:Investing in the maturation of solid-state battery technology offers a pathway to circumvent the safety and thermal risks of current liquid-electrolyte lithium-ion batteries.
- Commercial UUV Markets:Expanding into non-military applications, such as deep-sea mining exploration and offshore wind farm maintenance, provides a significant avenue for market diversification and volume growth.
- End-of-Life Services:Developing certified recycling and second-life repurposing services for large-format naval batteries aligns with regulations like the EU Battery Regulation and creates new revenue streams.
Industry Challenges
- Legacy Fleet Integration:Retrofitting older submarine classes, originally designed for the dimensions and weight of lead-acid batteries, with modern lithium-ion systems presents major engineering and structural modification hurdles.
- Critical Material Supply Chains:Dependence on a concentrated global supply of raw materials like cobalt and high-purity lithium introduces significant geopolitical risk and price volatility for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Batteries Market |
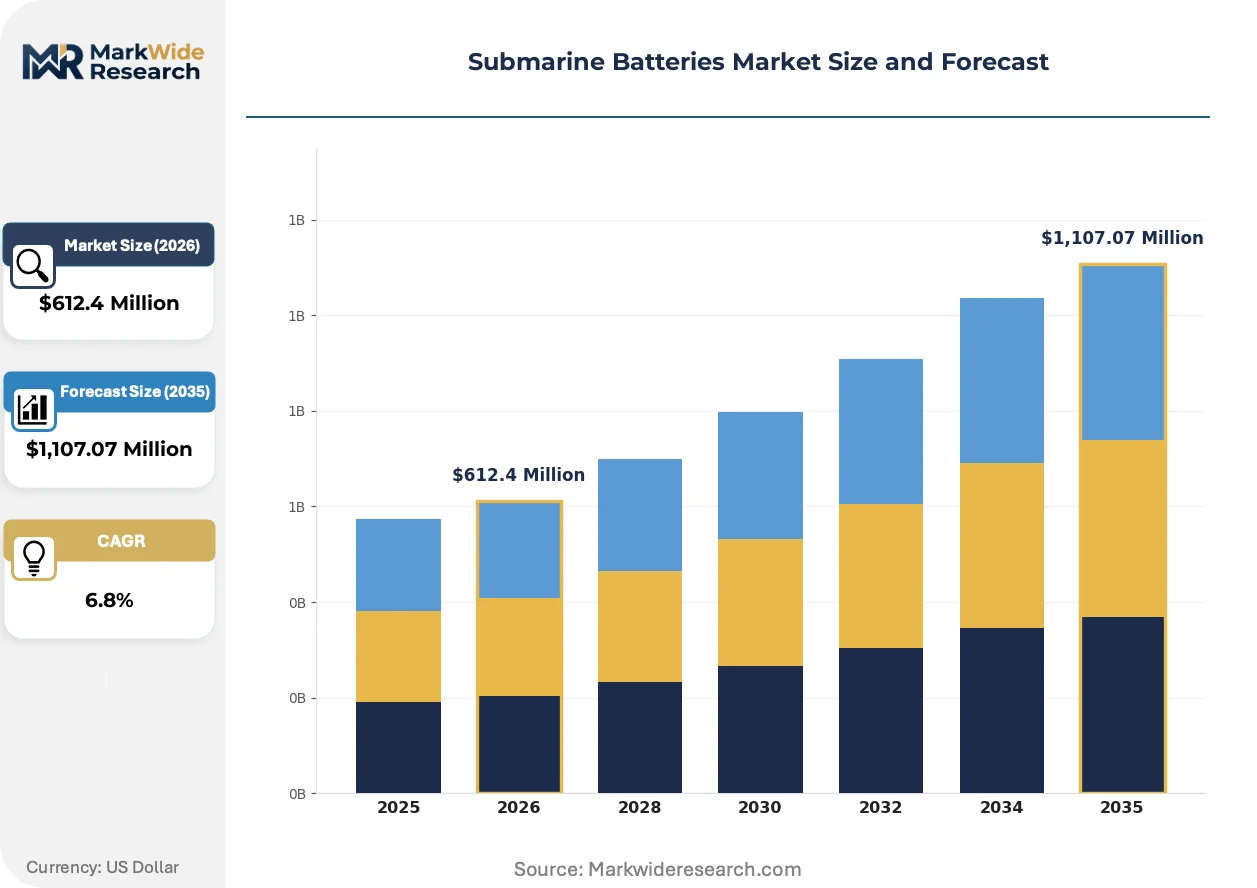
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium-Ion, Silver-Zinc, Nickel-Cadmium, Sodium Nickel Chloride Application: Military Submarines, Research Vessels, Autonomous Underwater Vehicles, Commercial Submersibles, Deep-Sea Exploration Deployment Mode: Internal Mounting, External Mounting, Modular Units, Integrated Systems, Retrofit Solutions End User: Naval Forces, Oceanographic Institutes, Marine Research Organizations, Specialty Contractors, Salvage Companies |
| Companies Covered | Systems Sunlight S.A., Exide Technologies, EnerSys, Zibo Torch Energy Co., Ltd., Epsilor, HBL Power Systems Ltd., GS Yuasa, Kokam, Champion Storage Battery Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Batteries Market Strategic Shifts & Innovations
A primary focus is on integrating digital oversight with advanced material science to enhance operational safety and longevity. This push balances the pursuit of higher energy density against the non-negotiable reliability demanded in submerged naval platforms.
Digital twin technology provides a real-time, physics-based simulation of a submarine battery's operational health and state of charge. Naval operators and defense contractors are adopting this for predictive maintenance, mission planning, and crew training. This advanced modeling is virtualizing the battery's lifecycle, allowing for failure prediction and optimized power management strategies without subjecting physical assets to undue stress.
The EU's Battery Regulation establishes strict rules for lifecycle management, including minimum recycled content and end-of-life collection targets. This directive compels manufacturers to design batteries for easier disassembly and material recovery, influencing system architecture and supply chain partnerships. While military applications may have specific clauses, suppliers are adapting product lines to meet these sustainability benchmarks across their portfolios.
Buyer behavior is evolving from purchasing standalone battery units to acquiring fully integrated power management and energy storage systems. This model favors suppliers who can deliver a complete solution encompassing thermal controls, safety monitoring, and power distribution electronics. This change is most evident in new-build submarine programs and the AUV sector, where system-level performance is critical.
Submarine Batteries Market Segmentation
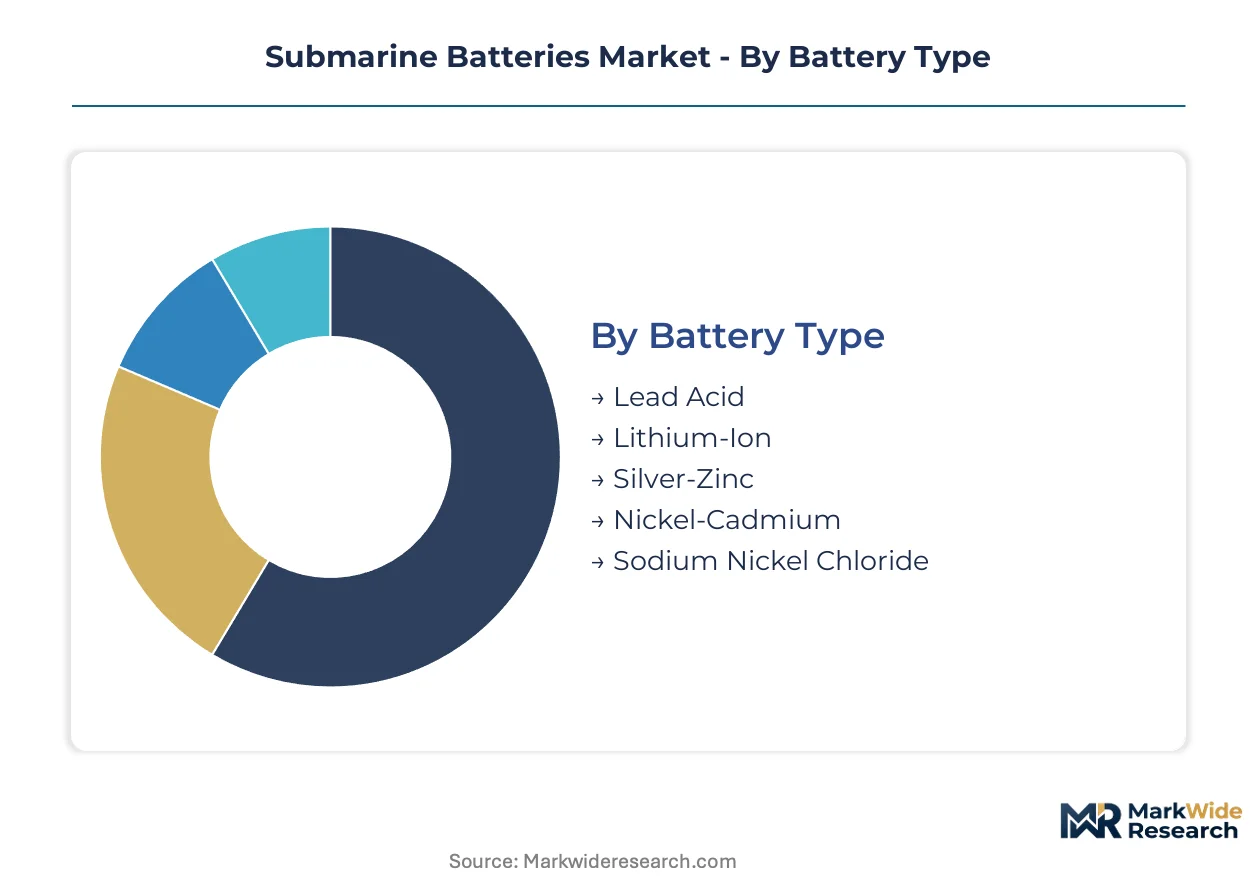
The submarine batteries market is segmented to reflect the diverse technological requirements and end-use applications across the underwater domain. Understanding these distinctions is critical for manufacturers to tailor solutions for specific operational demands and procurement models. This segmentation highlights areas of established demand and emerging growth within the global market.
Battery Type:
The battery type segment showcases a clear maturity spectrum, ranging from established chemistries to advanced power solutions. Traditional lead-acid batteries maintain a significant installed base, while lithium-ion technologies represent the leading edge of performance.
- Lithium-Ion:These advanced batteries offer superior energy density and longer cycle life, enabling extended mission durations for military submarines and autonomous underwater vehicles. Demand is concentrating in new naval platform procurements and AUV development due to their performance advantages.
- Lead Acid:These conventional batteries represent a mature technology with a significant installed base, particularly in older submarine fleets requiring reliable, proven power sources. Naval modernization programs in nations like India continue to support demand for these systems in retrofitted vessels.
- Silver-Zinc:Silver-zinc batteries provide high power density for specialized applications where space is at a premium and burst power is critical. Their use is often limited by higher cost and shorter cycle life compared to other chemistries.
- Nickel-Cadmium:Nickel-cadmium batteries offer robust performance and tolerance to overcharge, finding use in specific auxiliary power systems within military and research submersibles.
- Sodium Nickel Chloride:Sodium nickel chloride batteries provide a safer high-temperature alternative, suitable for certain niche applications requiring stable energy storage.
Lead Acid handles the majority of throughput; Lithium-Ion is the fastest mover on share.
Application:
This segment delineates the primary operational contexts where submarine batteries are deployed, reflecting varying power and endurance requirements. Each application demands specific battery characteristics to ensure mission success and operational safety.
- Military Submarines:These platforms require sustained electrical output for propulsion and auxiliary systems, alongside stringent operational silence and endurance capabilities. Naval modernization programs globally drive the largest portion of demand.
- Autonomous Underwater Vehicles:AUVs require compact, high-energy-density power sources to enable extended maritime surveillance, scientific research, and commercial exploration missions. This application is expanding most quickly due to technological advancements and new use cases.
- Research Vessels:Batteries for research vessels power various scientific instrumentation and propulsion systems for oceanographic studies. These applications prioritize reliability and long operational periods.
- Commercial Submersibles:Commercial submersibles utilize batteries for exploration, tourism, and underwater maintenance tasks. These systems balance performance with cost-effectiveness and safety.
- Deep-Sea Exploration:Batteries in deep-sea exploration vehicles must withstand extreme hydrostatic pressures and provide reliable power for imaging and data collection. These specialized systems require robust and durable designs.
Military Submarines represent the largest volume; Autonomous Underwater Vehicles are gaining share fastest.
Deployment Mode:
The deployment mode segment illustrates how battery systems are physically integrated into underwater platforms, impacting design, maintenance, and upgrade pathways. This category highlights the engineering considerations for various vessel types.
- Integrated Systems:These solutions involve batteries designed as an integral part of a new submarine or AUV platform, optimizing space, cooling, and power management from the outset. New-build submarine programs primarily leverage integrated systems for optimal performance.
- Retrofit Solutions:These involve adapting modern battery technologies, such as lithium-ion, into existing submarine classes originally designed for older chemistries. Legacy fleet integration presents significant engineering and structural modification hurdles.
- Internal Mounting:Batteries are housed within the pressure hull of the vessel, requiring compact designs and robust thermal management. This is the predominant deployment method for military submarines.
- External Mounting:Batteries are placed outside the pressure hull, often in specialized pods, typically for AUVs or smaller submersibles. This mode offers flexibility for payload and mission customization.
- Modular Units:These systems consist of standardized battery modules that can be easily interchanged or expanded, offering flexibility in power capacity and maintenance. Modular units are gaining traction for their ease of scalability.
Internal Mounting remains the standard approach; Integrated Systems are experiencing the steepest expansion trajectory.
End User:
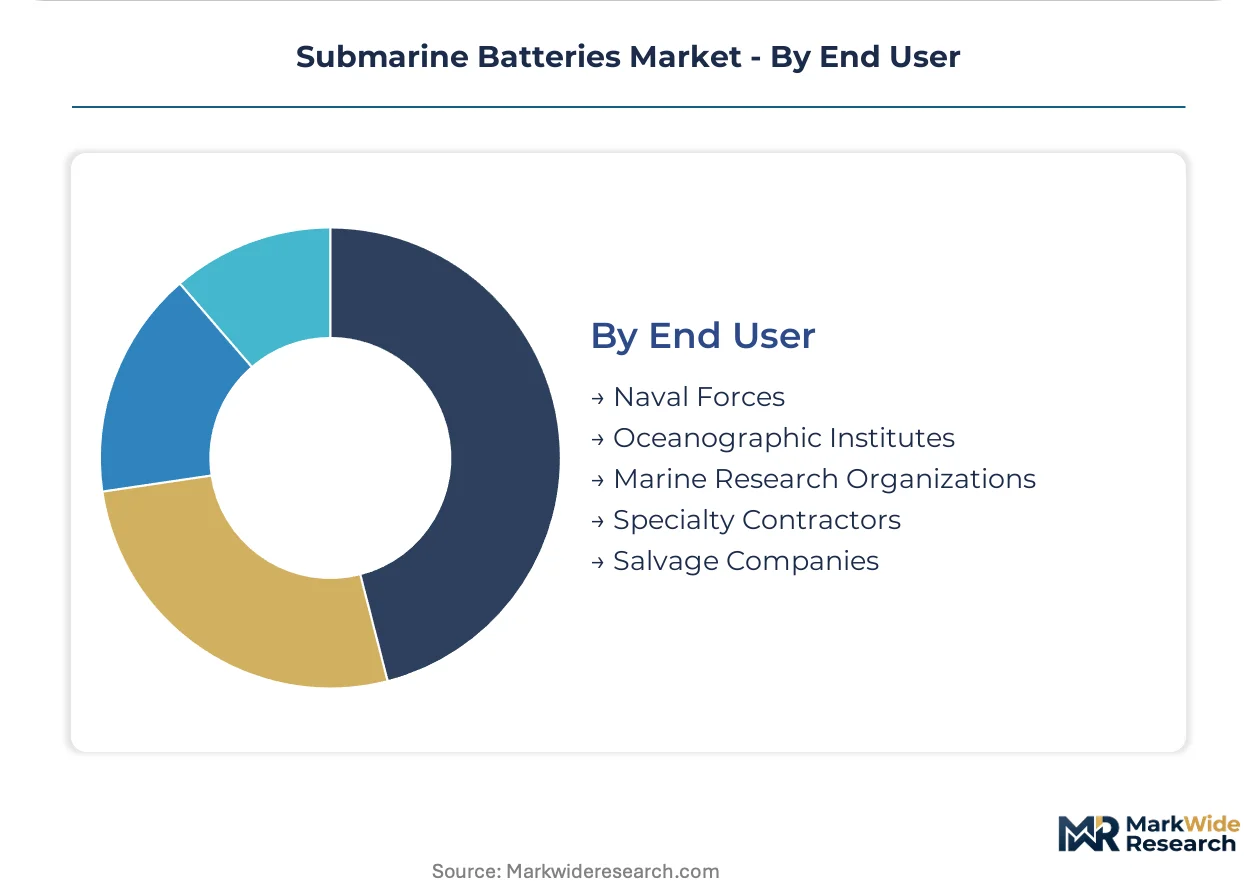
This segment identifies the primary organizations and entities that procure and operate submarine battery systems, reflecting distinct procurement processes and operational requirements. Naval forces represent the largest direct buyers.
- Naval Forces:These government entities acquire batteries for military submarines and other naval platforms, often through direct-to-defense procurement models. National defense strategies, particularly in countries like India, drive significant demand.
- Oceanographic Institutes:These organizations utilize batteries for powering research vessels and autonomous underwater vehicles used in marine science and environmental monitoring. Their procurement focuses on reliability and long-term data collection capabilities.
- Marine Research Organizations:Similar to oceanographic institutes, these groups require specialized battery systems for underwater exploration and data acquisition. Their demand often involves custom power solutions for unique research objectives.
- Specialty Contractors:These firms provide specialized services for underwater construction, inspection, and maintenance, using batteries for their submersibles and ROVs. They prioritize robust and dependable power sources for challenging environments.
- Salvage Companies:Salvage operations employ underwater vehicles that rely on batteries for power during recovery missions. These end-users require resilient battery systems capable of operating under demanding conditions.
Naval Forces constitute the largest end-user segment; Oceanographic Institutes are climbing the fastest in terms of new procurements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry exists where India's naval modernization programs create significant demand, yet established Western and East Asian battery manufacturers often hold higher pricing power. This dynamic arises from stringent qualification standards and the specialized technological expertise required for submarine systems. Naval forces prioritize long-term reliability and performance over initial cost in critical sub-surface power solutions.
India
India's naval modernization programs and ongoing fleet retrofits significantly boost demand for submarine batteries. The country's Production Linked Incentive (PLI) scheme encourages domestic manufacturing and technology transfer in defense sectors. Visakhapatnam's naval dockyard and Hyderabad's defense electronics cluster drive significant demand for customized power solutions.
United States
The United States drives demand through new nuclear submarine procurements and advanced Autonomous Underwater Vehicle (AUV) development for maritime security. US Navy standards impose rigorous testing protocols for all battery systems, ensuring mission-critical reliability. Groton, Connecticut, and Newport News, Virginia, lead submarine construction, fostering advanced battery integration and testing.
Japan
Japanese naval forces prioritize advanced conventional submarines, driving demand for high-performance lithium-ion batteries. METI (Ministry of Economy, Trade and Industry) actively supports research into next-generation energy storage solutions for defense applications. Kyoto's industrial base, including GS Yuasa, focuses on developing cutting-edge battery chemistries for underwater platforms.
Germany
Germany's robust shipbuilding industry, particularly for conventional submarines, fuels demand for specialized battery systems for both domestic and export markets. DNV (Det Norske Veritas) standards heavily influence the design and certification of naval battery components. Kiel's shipyards are central to integrating innovative power solutions into sophisticated underwater vessels.
Submarine Batteries Market Key Industry Players
Established industrial battery suppliers and specialized advanced technology providers split the market for submarine batteries. The market exhibits a tiered structure, with a few large players dominating traditional segments and numerous niche innovators focusing on advanced chemistries. Strategic partnerships are common, allowing companies to combine legacy expertise with cutting-edge material science. Portfolio diversification into commercial UUV markets is also a prevalent competitive move.
Within the established industrial battery tier, EnerSys exemplifies a broad portfolio approach, leveraging its extensive industrial battery experience for diverse naval requirements. Japanese-based GS Yuasa represents the advanced technology segment, focusing on high-density lithium-ion solutions for next-generation platforms. HBL Power Systems Ltd., an India-based manufacturer, occupies a strategic role by providing customized power solutions within Asian defense supply chains, showcasing regional specialization and strong defense procurement ties. These entities anchor distinct market segments through their respective technological strengths and market access strategies.
| Leading Market Players |
|---|
| Systems Sunlight S.A. |
| Exide Technologies |
| EnerSys |
| Zibo Torch Energy Co., Ltd. |
| Epsilor |
| HBL Power Systems Ltd. |
| GS Yuasa |
| Kokam |
| Champion Storage Battery Company Limited |
| Others |
Cost & Logistics Intelligence
Commodity price volatility, particularly for cobalt and high-purity lithium, determines pricing tier spreads for advanced battery systems and shapes supply chain resilience. This dependency forces manufacturers to balance cost-effectiveness with geopolitical risk.
Pricing Analysis
Configured-to-order pricing for specialized naval battery systems commands a premium over more standardized industrial battery offerings. The dominant pricing structure is project-based, reflecting the bespoke nature of military contracts and AUV integration. Price differentiation stems from rigorous naval classification standards like DNV and the level of after-sales service and long-term support. Pricing pressure stems from the high capital costs associated with lithium-ion systems, particularly for retrofit solutions. Naval forces exhibit low price sensitivity for mission-critical systems, prioritizing reliability, while commercial AUV operators are more cost-conscious.
Supply Chain Analysis
Extended payment terms are common in defense procurement, influencing supplier financial planning within the submarine battery market. Geographic supply concentration for critical raw materials, such as cobalt and high-purity lithium, centers on countries like China and Australia. Manufacturers depend on these inputs for advanced lithium-ion battery production. Single-source vulnerability for specialized components represents a significant supply chain risk, especially for military-grade systems. Distribution runs through direct-to-defense contractors and specialized integrators, particularly for new-build programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The submarine batteries market is an early-cycle expansion story, driven by the accelerating penetration of lithium-ion technology into naval platforms and autonomous underwater vehicles. This technological shift enables extended mission durations and enhanced operational capabilities.
For Market Incumbents:Harden strategic partnerships with naval classification societies to streamline qualification processes for new battery chemistries. Incumbents should also invest in advanced thermal management R&D to mitigate the safety risks associated with high-density lithium-ion systems, addressing the threat from emerging solid-state battery technologies. Deepen vertical integration into critical material processing to reduce dependency on volatile global supply chains. Expand geographical manufacturing footprints in key naval modernization markets like India to secure long-term contracts.
For New Entrants and Emerging Players:Build out specialized battery solutions for the rapidly expanding autonomous underwater vehicle (AUV) market, which represents a penetrable segment due to its diverse applications. Focus on developing compact, high-energy-density power sources optimized for extended maritime surveillance and scientific research missions. A go-to-market angle involves direct collaboration with AUV manufacturers for integrated system design. Target commercial deep-sea exploration and offshore wind farm maintenance sectors for diversification and volume growth.
For Investors and Strategic Acquirers:The market sits at an early growth phase that favors specialized technology developers with proven lithium-ion expertise or solid-state battery patents. Long-term viability over the next 5-10 years is strong, driven by sustained naval modernization and AUV proliferation. Acquisition targets should be niche innovators with proprietary thermal management or safety systems. A signal to watch as an inflection indicator is the successful deployment of next-generation lithium-ion or solid-state batteries in a new-build submarine program.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production scale for high-demand lithium-ion battery systems. |
| Technology Licensing | Accelerates adoption of advanced battery chemistries for diverse naval platforms. |
| Joint Venture | Combines expertise for complex system integration in new submarine programs. |
| Green Manufacturing Transition | Aligns production with environmental regulations like the EU Battery Regulation. |
| Certification Investment | Secures compliance with stringent naval classification standards for market access. |
Research Approach
A standing panel of naval procurement officers, battery R&D directors, AUV design engineers, and marine classification experts provided ongoing calibration for primary data validation. This involved combining in-depth interviews with extensive secondary validation from defense white papers, maritime technology journals, and national naval strategy documents. The approach ensured robust bottom-up and top-down triangulation of market insights.
Scenario-bracketing provided a range of potential market outcomes, accounting for varying technological adoption rates and geopolitical influences over the projection horizon. The analytical framework modeled segmentation across battery type, application, deployment mode, and end-user, alongside specific naval modernization timelines. Compound annual growth rates were derived from historical trends and projected future demand catalysts. Key forecast inputs included defense budget allocations and AUV development roadmaps.
Stress conditions across raw material supply stability and naval procurement cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technological maturation and geopolitical stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Industrial Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Atomic Battery Market
Batteries
Elastic Battery Binders Market
Batteries
Floor Scrubber Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Europe Battery Cell Market
Batteries
Lithium Battery Testing System Market
Batteries
North Europe Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Liquid Metal Battery Market
Batteries
Modular Battery Pack Market
Batteries
Portable Battery Pack Market
Batteries
Modular Battery Market