
 South America City Gas Distribution Market | 2026-2036
South America City Gas Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
South America City Gas Distribution Market Analytics
The capital-intensity divergence between integrated pipeline operators and standalone city gas retailers is redrawing competitive boundaries across South America. Petroleo Brasileiro S.A. leverages its upstream-to-last-mile infrastructure to sustain below-market connection tariffs in priority concession zones. Comgás anchors the largest metropolitan distribution footprint in Brazil, while Naturgy Energy Group S.A. competes through specialized industrial metering and pressure-regulation technology in Argentina and Chile.
City gas distribution comprises the construction, operation, and maintenance of localized pipeline networks that depressurize transmission-grade natural gas to 0.02–0.5 bar for safe delivery to end users through polyethylene or steel service lines. Its primary commercial purpose is replacing higher-cost liquid fuels and bottled LPG with continuous-flow methane supply in densified urban zones. Residential users represent the most mature revenue pool across most concessions, while smart metering infrastructure is capturing disproportionate capital allocation as utilities seek to reduce non-technical losses and enable time-of-use billing. Industrial consumers generate the highest per-connection margins but face competition from direct pipeline access where transmission proximity permits.
Brazil's ANP mandates open-access rules for distribution networks, while Argentina's Enargas sets technical standards for pressure regulation and odorization. Chile's SEC certification requirements for polyethylene pipe fusion and Colombia's CREG tariff methodologies collectively shape capital-recovery timelines and connection-density targets. Stakeholders must weigh concession-renewal terms against the pace of biomethane injection standards now under review by national energy regulators.
Market Dynamics
ANP's gas market liberalization framework is dissolving Petrobras's historical monopoly over transmission access, forcing third-party distributors to build independent procurement capabilities and renegotiate concession economics.
Growth Catalysts
- LPG-to-piped gas substitution:São Paulo's metropolitan households are abandoning cylinder refills for continuous methane supply, eliminating delivery logistics and price volatility.
- Smart metering mandates:Brazil's ANP technical standards for advanced metering infrastructure are accelerating capital deployment into time-of-use billing systems.
- Industrial belt densification:Buenos Aires's manufacturing corridor is consolidating thermal demand around centralized distribution nodes to reduce fuel switching costs.
Market Restraints
- Polyethylene resin import dependency:Distribution network expansion relies on dollar-denominated feedstock subject to currency fluctuation and supply lead times.
- Transmission pipeline concentration:Bolivia-to-Brazil trunk line capacity constraints limit upstream supply flexibility for interior concession zones.
- Biomethane injection uncertainty:Pending ANP renewable gas certification timelines delay green hydrogen blending investments.
Strategic Opportunities
- Colombia's underserved Andean cities:Bogotá's elevated terrain and dispersed settlement patterns have delayed pipeline network penetration versus coastal competitors.
- Compressed natural gas vehicle corridors:Heavy freight routes linking Argentina's Vaca Muerta production to Chilean port terminals lack integrated refueling infrastructure.
- Pressure-regulation as-a-service:Industrial clusters are outsourcing odorization and custody-transfer maintenance to specialized metering providers.
Industry Challenges
- Certified polyethylene fusion technician scarcity:Chile's SEC welding qualification requirements exceed current vocational training pipeline output.
- Legacy LPG distributor conversion:Existing cylinder logistics operators lack pipeline construction competencies and capital access for concession bidding.
- Cross-border tariff harmonization:Brazilian CREG methodologies and Argentine Enargas pricing frameworks create accounting complexity for integrated operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America City Gas Distribution Market |
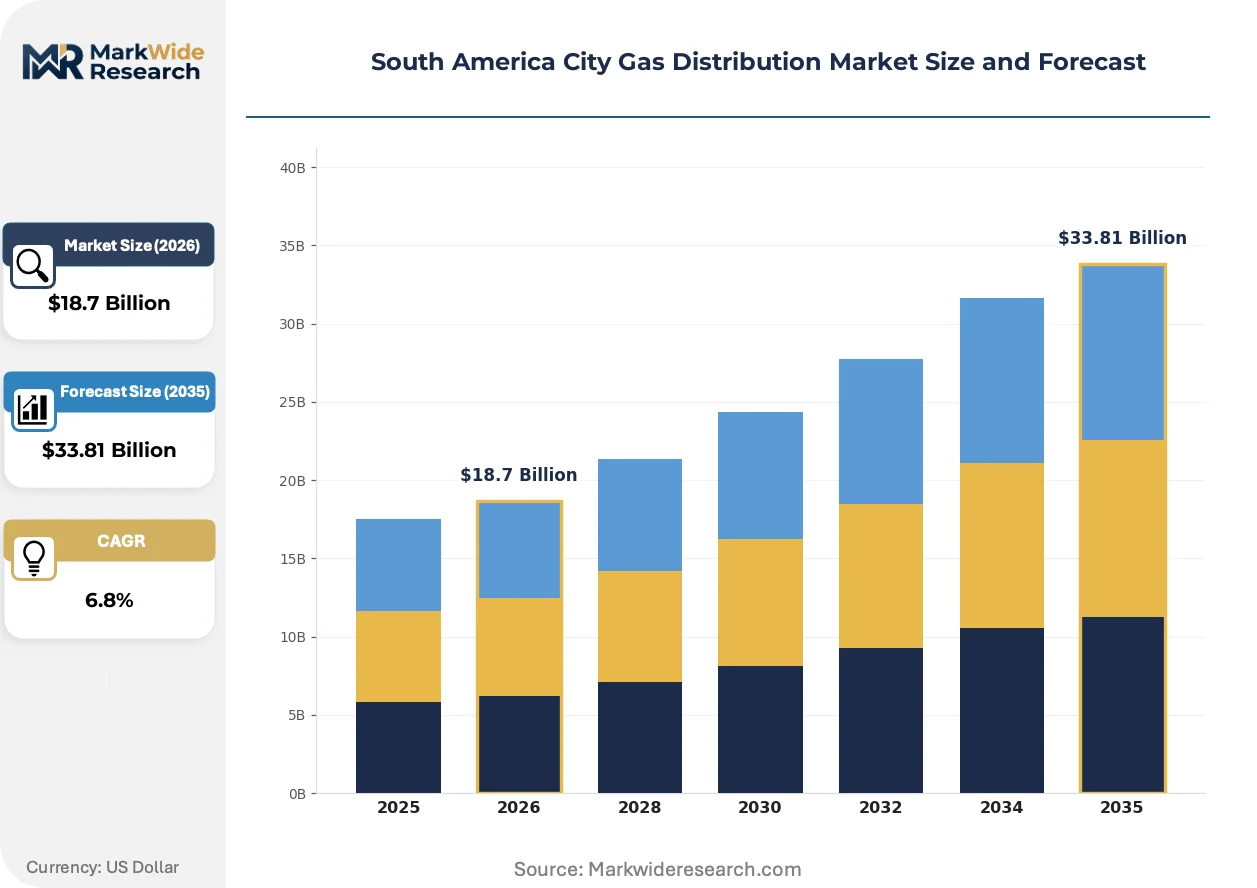
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Transmission Lines, Distribution Pipelines, Metering Stations, Pressure Regulating Stations End User Type: Residential Users, Commercial Users, Industrial Consumers, Power Generation Service Type: Supply Services, Maintenance Services, Installation Services, Consultation Services Technology: Smart Metering, SCADA Systems, Pipeline Monitoring, Data Analytics |
| Companies Covered | Petroleo Brasileiro S.A., Companhia de Gás de São Paulo (Comgás), Ipiranga, Naturgy Energy Group S.A., Tecpetrol, YPF, YPFB, Eneva, GasAndes Pipeline, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America City Gas Distribution Market Evolving Landscape
Digital pressure monitoring and automated leak detection are compressing maintenance cycles across South American distribution networks. Utilities are reallocating capital from physical inspection crews to centralized telemetry platforms.
Advanced metering infrastructure is decomposing the traditional monthly manual read cycle into granular consumption data streams. Residential distributors in São Paulo and Curitiba are deploying cellular-enabled diaphragm meters to eliminate estimated billing disputes. The technology is decomposing revenue leakage from tampering and meter degradation into recoverable technical losses.
Argentina's Enargas is tightening odorant concentration requirements for distribution-grade methane to enhance leak detection sensitivity. The regulatory revision mandates automated injection monitoring systems at city gate stations. Industrial consumers in Rosario's petrochemical cluster are upgrading pressure regulation skids to comply with the revised technical standards.
Time-of-use billing is restructuring residential contract structures away from flat volumetric rates toward peak-demand pricing models. Brazilian distributors are piloting dynamic tariffs that penalize winter heating spikes during morning demand windows. The behavioral shift is most visible in Porto Alegre's temperate climate zone where seasonal load variation exceeds thirty percent.
South America City Gas Distribution Market Segmentation
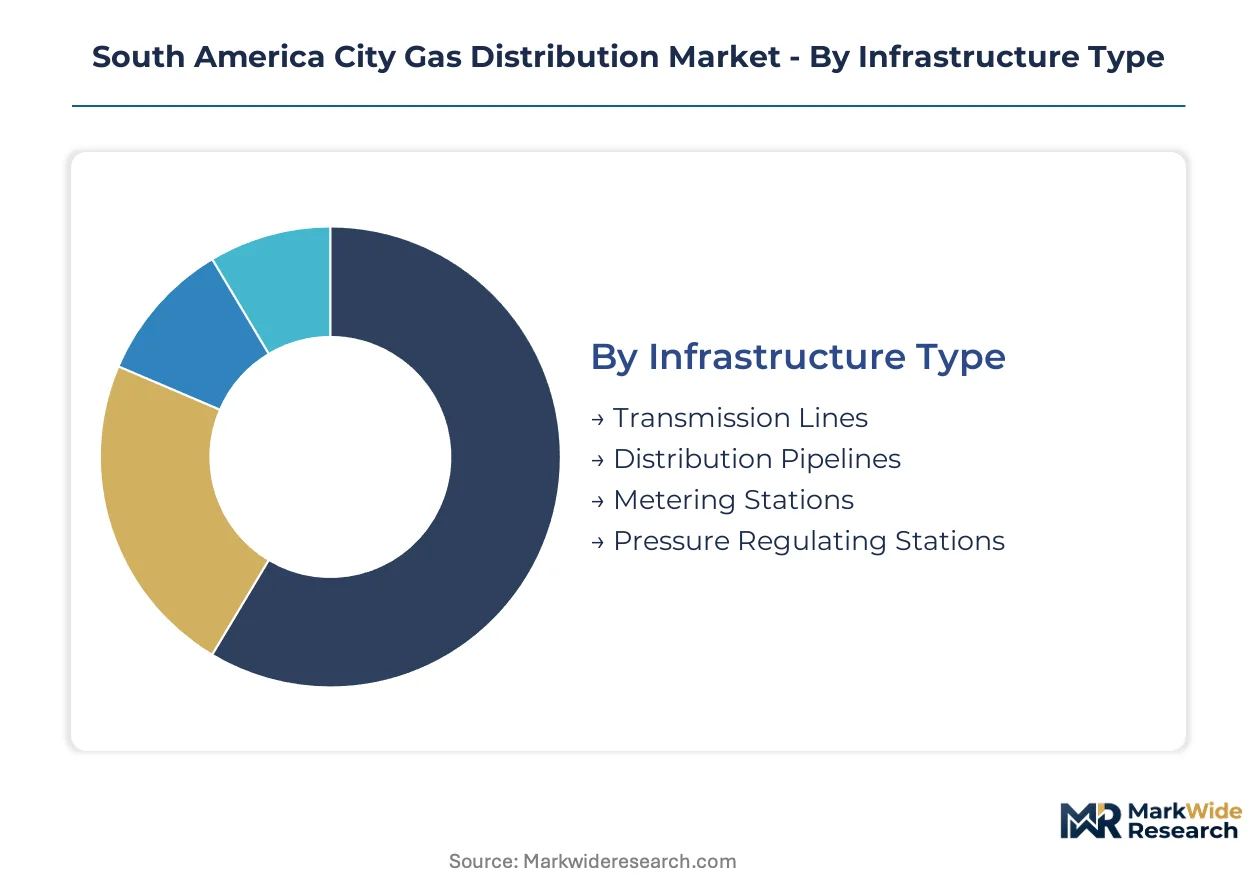
Segmentation in South American city gas distribution reveals how capital flows differentially across infrastructure layers and customer tiers. Each dimension exposes distinct margin profiles and regulatory exposure that shape concession bidding strategies.
Infrastructure Type:
Transmission lines feed distribution networks through city gate stations, while metering and pressure regulation assets determine revenue capture precision at the customer edge.
- Transmission Lines:High-pressure steel pipelines transport processed natural gas from processing facilities to urban gate stations at 40-70 bar. Bolivia-to-Brazil trunk capacity constraints force Argentine distributors to prioritize Vaca Muerta sourcing for Buenos Aires industrial belt expansion.
- Distribution Pipelines:Medium and low-pressure polyethylene networks depressurize gas to 0.02-4 bar for safe delivery through densely populated urban corridors. São Paulo's metropolitan concession zones concentrate replacement demand as legacy steel mains approach end-of-life.
- Metering Stations:City gate facilities measure bulk custody transfer and odorize gas for distribution-grade safety compliance. ANP mandates automated injection monitoring systems are accelerating capital redeployment from manual sampling infrastructure.
- Pressure Regulating Stations:Skid-mounted regulation equipment maintains stable outlet pressure across fluctuating upstream supply conditions. Industrial clusters in Rosario's petrochemical corridor outsource odorization maintenance to specialized service providers.
Distribution pipelines dominate installed base. Smart metering integration at city gate stations is where expansion concentrates.
End User Type:
Customer segmentation separates stable residential revenue from volatile industrial margins, with each tier demanding distinct connection density and pressure specifications.
- Residential Users:Household connections for cooking and heating applications generate predictable demand curves with low per-unit margins but high connection volumes. Porto Alegre's temperate climate zone exhibits seasonal load variation exceeding thirty percent, driving time-of-use tariff pilots.
- Commercial Users:Restaurants, hotels, and retail establishments require medium-pressure service lines with higher consumption per connection than residential. Curitiba's commercial district conversions from LPG cylinders are accelerating as piped gas eliminates delivery logistics.
- Industrial Consumers:Manufacturing facilities and thermal process users generate the highest per-connection margins but face competition from direct transmission access. Buenos Aires industrial belt densification is consolidating thermal demand around centralized distribution nodes.
- Power Generation:Cogeneration and simple-cycle gas turbines require dedicated high-pressure laterals with interruptible supply contracts. Brazilian distributors are negotiating priority dispatch agreements with grid operators amid hydropower reservoir volatility.
Residential users anchor revenue stability. Industrial consumers represent the steepest expansion trajectory for margin per connection.
Service Type:
Service segmentation tracks the shift from capital-heavy installation toward recurring maintenance revenue as networks mature across South American concessions.
- Supply Services:Continuous methane delivery contracts with take-or-pay minimums and volumetric pricing structures. ANP's open-access rules are forcing third-party distributors to build independent procurement capabilities.
- Maintenance Services:Scheduled inspection, leak detection, and pressure regulation calibration to ensure safety compliance. Digital pressure monitoring is compressing maintenance cycles across Brazilian distribution networks.
- Installation Services:New connection construction including service line trenching, meter set assembly, and pressure testing. Colombia's Andean cities present delayed pipeline penetration versus coastal competitors.
- Consultation Services:Engineering studies for industrial pressure regulation design and concession bidding support. Chile's SEC certification requirements for polyethylene pipe fusion exceed current vocational training pipeline output.
Supply services dominate revenue contribution. Maintenance services are gaining share fastest as network maturity extends asset replacement cycles.
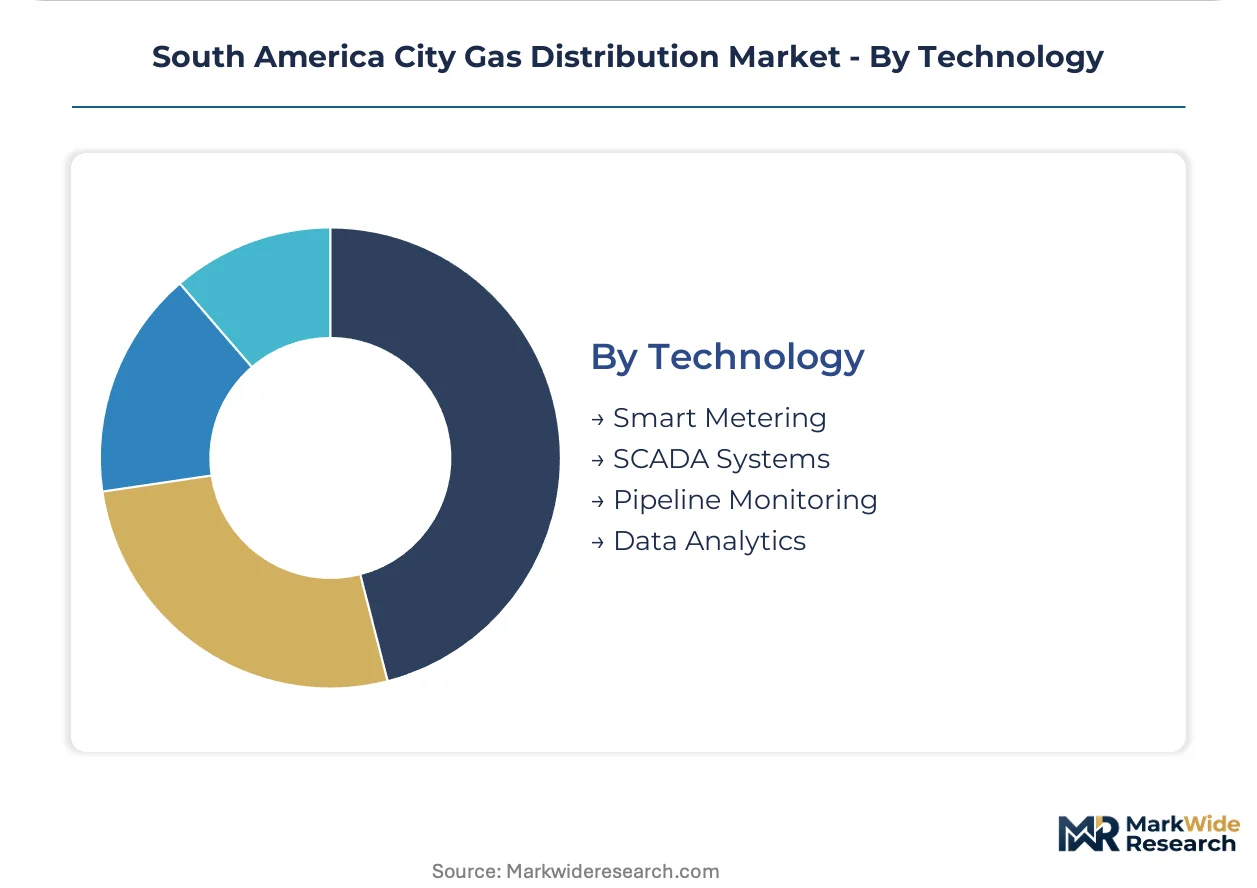
Technology:
Technology deployment separates utilities capturing granular consumption data from those reliant on estimated billing and physical inspection regimes.
- Smart Metering:Cellular-enabled diaphragm meters with remote read capability and tamper detection algorithms. São Paulo and Curitiba distributors are eliminating estimated billing disputes through AMI deployment.
- SCADA Systems:Supervisory control platforms monitoring pressure, flow, and odorant concentration across distribution zones. Argentina's Enargas tightening of odorant requirements mandates automated injection monitoring at city gates.
- Pipeline Monitoring:Acoustic leak detection and cathodic protection surveillance for integrity management. Utilities are reallocating capital from physical inspection crews to centralized telemetry platforms.
- Data Analytics:Consumption pattern analysis for demand forecasting and non-technical loss identification. Time-of-use billing pilots in Brazil rely on granular data streams to structure peak-demand pricing models.
SCADA systems anchor operational control infrastructure. Smart metering is where capital deployment concentrates most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing leverage through Petrobras's integrated infrastructure, while Argentine distributors absorb volatility from Vaca Muerta sourcing imbalances. This asymmetry shapes concession economics across the continent.
Brazil
São Paulo's metropolitan corridor drives LPG-to-piped gas substitution as households abandon cylinder logistics. ANP's open-access rules dissolve historical transmission monopolies and force independent procurement capabilities. Curitiba's commercial district conversions accelerate as piped gas eliminates delivery uncertainty for restaurants and hotels.
Argentina
Buenos Aires's industrial belt consolidates thermal demand around centralized distribution nodes to reduce fuel switching costs. Enargas tightens odorant concentration requirements and mandates automated injection monitoring at city gate stations. Rosario's petrochemical cluster upgrades pressure regulation skids to comply with revised technical standards.
Chile
Santiago's manufacturing zones outsource odorization and custody-transfer maintenance to specialized metering providers. SEC certification requirements for polyethylene pipe fusion exceed current vocational training pipeline output. Antofagasta's mining corridor presents compressed natural gas vehicle refueling gaps on heavy freight routes.
Colombia
Bogotá's elevated terrain and dispersed settlement patterns delay pipeline network penetration versus coastal competitors. CREG tariff methodologies shape capital-recovery timelines and connection-density targets for concession operators. Medellín's Andean valley geography complicates pressure regulation design for medium-density residential zones.
South America City Gas Distribution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South American city gas distribution. The market structure concentrates around integrated national oil companies with captive upstream supply and specialized regional distributors with metering expertise. Three archetypes dominate: pipeline-integrated incumbents leveraging below-market connection tariffs, standalone metropolitan retailers optimizing last-mile density, and industrial-focused specialists capturing high-margin pressure-regulation contracts. Competitive moves center on concession renewal positioning and smart metering infrastructure deployment.
Within the integrated infrastructure tier, Petroleo Brasileiro S.A. and YPF exemplify upstream-to-last-mile control over priority concession zones. Among standalone metropolitan specialists, Companhia de Gás de São Paulo occupies a position defined by São Paulo's densest distribution footprint, while Naturgy Energy Group S.A. anchors specialized industrial metering capabilities across Argentina and Chile. These three represent the dominant competitive positions shaping regional market access.
| Leading Market Players |
|---|
| Petroleo Brasileiro S.A. |
| Companhia de Gás de São Paulo (Comgás) |
| Ipiranga |
| Naturgy Energy Group S.A. |
| Tecpetrol |
| YPF |
| YPFB |
| Eneva |
| GasAndes Pipeline |
| Others |
Value Network & Pricing Analysis
Take-or-pay contracts with minimum volume commitments anchor supply access for Brazilian distributors while locking in price visibility against Bolivian trunk line volatility. ANP's open-access rules force third-party retailers to secure independent procurement terms, embedding dollar-denominated feedstock exposure into concession economics.
Pricing Analysis
Configured-to-order pricing for industrial pressure-regulation skids commands substantial premiums over standardized residential connection tariffs. Three-tier pricing structure across premium, standard, and economy levels stratifies by connection density and after-sales service bundling, with industrial clusters in Buenos Aires least sensitive to unit rates. Cost compression in residential tariffs is intensifying because Petrobras leverages integrated infrastructure to sustain below-market connection fees in priority zones.
Supply Chain Analysis
Strategic stockpiling of polyethylene resin dominates inventory strategy among Brazilian distributors hedging against currency-driven feedstock volatility. Geographic supply concentration centers on Saudi Arabia, South Korea, and the United States for high-density polyethylene pipe resin. Raw material dependencies include odorant chemical blends, steel for high-pressure laterals, and cathodic protection anodes. Single-source vulnerability runs through Bolivia-to-Brazil trunk line capacity constraints. Distribution runs through specialized fusion contractors certified under Chile's SEC welding standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American city gas distribution represents an early-cycle expansion story, justified by accelerating LPG-to-piped gas substitution across São Paulo's metropolitan corridor where household penetration remains below saturation thresholds.
For Market Incumbents: Shield concession renewal economics by deepening backward integration into biomethane injection infrastructure ahead of ANP certification timelines. Secure exclusive channel control over certified polyethylene fusion technicians in Chile and Colombia, where SEC and CREG welding qualification requirements exceed vocational training output. Vertical integration into smart metering manufacturing reduces procurement exposure to cellular module supply constraints.
For New Entrants and Emerging Players: ANP's fast-track certification for renewable gas injection creates immediate positioning leverage against legacy distributors awaiting regulatory clarity. White-space targets concentrate in Colombia's Andean cities where Bogotá's elevated terrain has delayed pipeline penetration, and in compressed natural gas vehicle corridors linking Argentina's Vaca Muerta production to Chilean port terminals. Go-to-market execution should anchor on pressure-regulation-as-a-service contracts for industrial clusters outsourcing odorization maintenance.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized metering providers with demonstrated industrial custody-transfer expertise across multiple regulatory jurisdictions. Long-term viability over the next decade hinges on concession portfolio diversification spanning Brazilian open-access zones and Argentine Vaca Muerta sourcing corridors. The signal to watch as inflection indicator is ANP's final biomethane injection certification timeline, which would unlock green hydrogen blending investments and revalue renewable-ready distribution assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Metering Infrastructure Deployment | ANP technical standards for AMI accelerate capital redeployment from manual billing systems toward cellular-enabled diaphragm meters. |
| Biomethane Injection Certification | Pending ANP renewable gas timelines delay green hydrogen blending investments but position first-movers for regulatory preference. |
| Pressure-Regulation-as-a-Service | Industrial clusters in Rosario's petrochemical corridor outsource odorization maintenance to specialized metering providers. |
| Polyethylene Fusion Technician Certification | Chile's SEC welding requirements exceed current vocational training output, creating certified labor scarcity for network expansion. |
| Concession Renewal Positioning | CREG tariff methodologies in Colombia and Enargas pricing frameworks in Argentina shape capital-recovery timeline negotiations. |
Research Methodology
Cross-validation between primary interviews with distribution network operators and secondary validation through ANP regulatory filings anchors the qualitative findings. Stakeholder engagement encompassed concession planning officers at metropolitan utilities, procurement leads at industrial thermal users, EPC contractors specializing in polyethylene network deployment, and regulatory affairs specialists navigating CREG and Enargas frameworks. Secondary sources included ANP technical standards documentation, Enargas odorant concentration revisions, SEC certification requirements for pipe fusion, customs data on polyethylene resin imports, and utility concession financial disclosures. Bottom-up connection density modeling and top-down macroeconomic demand projections were triangulated against regional hydrocarbon consumption trends.
Sensitivity analysis around Bolivian trunk line capacity constraints and currency volatility scenarios informs the analytical framework. Segmentation dimensions modeled include infrastructure type, end-user tier, service category, and technology deployment intensity across the projection horizon. CAGRs were derived from regression analysis of historical connection growth rates against urbanization and fuel substitution elasticities. Industry-specific forecast inputs incorporate ANP gas market liberalization implementation pace and Vaca Muerta production ramp assumptions.
Decision-makers should treat outputs as directional under stable regulatory implementation and hydrocarbon supply continuity assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without claiming predictive certainty. Specific risk factors that could revise projections include ANP biomethane certification delays, polyethylene resin import tariff shocks, and cross-border pipeline capacity rationing. Revision becomes warranted when Bolivian supply contract renegotiations or Argentine export policy shifts cross threshold levels of disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Cables Market