
 Electrical Transmission Azimuth Thruster Market | 2026-2036
Electrical Transmission Azimuth Thruster Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Transmission Azimuth Thruster Market Insights
Market Context
China's shipyard expansion is narrowing the historical European dominance in azimuth thruster fabrication. Brunvoll leverages its Norwegian heritage to sustain premium positioning in ice-class electric propulsion. KONGSBERG anchors integrated vessel control systems that bundle thrusters with automation software. SCHOTTEL GROUP competes through modular electric drive architectures that reduce installation complexity for retrofit projects.
Technical Definition and Segment Structure
An electrical transmission azimuth thruster is a steerable marine propulsion unit where electric motors transmit torque through a Z-drive or L-drive gearbox to a propeller capable of 360-degree rotation, typically delivering 500 kW to 30 MW for dynamic positioning and main propulsion duties. Dynamic positioning thrusters command the largest margin pool as offshore vessels require redundant electric azimuth units for station-keeping in harsh environments. Electric drives lead technology adoption while hybrid systems attract interest from operators seeking fuel flexibility under tightening IMO carbon intensity regulations. Offshore platforms represent the fastest-growing application segment driven by floating wind foundation installation and subsea construction campaigns.
Regulatory Environment and Outlook
IMO Energy Efficiency Existing Ship Index rules and EU Emissions Trading System maritime provisions are forcing operators to retire mechanical drivelines in favor of electric propulsion architectures. Classification societies including DNV and Bureau Veritas have issued updated notations for battery-hybrid azimuth installations that influence insurance and charter premiums. Stakeholders must monitor how green financing criteria from institutions like the European Investment Bank reshape vessel newbuild specifications and thruster supplier qualification requirements.
Market Dynamics
Offshore wind foundation installation vessels are forcing a generational shift from mechanical to electric azimuth architectures, compressing supplier lead times and rewiring procurement relationships around torque density specifications rather than gearbox longevity.
Growth Catalysts
- EU Green Deal maritime provisions:The framework mandates carbon intensity reductions that eliminate mechanical drivelines from newbuild specifications, creating mandatory demand for electric propulsion systems in North Sea offshore fleets.
- Floating wind installation surge:Turbine foundation vessels require redundant dynamic positioning thrusters capable of station-keeping in harsh environments, expanding the addressable fleet for high-torque electric azimuth units.
- DNV battery-hybrid notations:Classification society certifications for hybrid electric installations influence insurance premiums and charter rates, steering capital toward electrified propulsion packages.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet electric motors depend on neodymium processing concentrated in China, exposing thruster manufacturers to input cost volatility and geopolitical supply risk.
- High-voltage marine certification timelines:Bureau Veritas and Lloyd's Register extended type-approval processes for megawatt-class electric drives delay vessel commissioning and tie up working capital.
- Mechanical driveline installed base:Existing offshore support vessels with Z-drive gearboxes face retrofit economics that favor engine rebuilds over full electric conversion, slowing replacement cycles.
Strategic Opportunities
- US Gulf of Mexico offshore wind lease rounds:Bureau of Ocean Energy Management auctions are activating Jones Act-compliant vessel construction, creating first-mover positioning for electric azimuth suppliers in a nascent market.
- Japan floating offshore wind commercialization:METI feed-in tariffs for floating turbine projects are stimulating specialized installation vessel orders that specify ice-class electric thrusters for harsh North Pacific conditions.
- Port electrification infrastructure mandates:Shore power requirements at Rotterdam and Hamburg are pushing harbor tug operators toward fully electric or battery-hybrid propulsion architectures with steerable thrusters.
Industry Challenges
- Marine electrical engineering talent scarcity:The crossover skill set spanning high-voltage power electronics and saltwater corrosion engineering commands premium wages and extends recruitment cycles for thruster OEMs.
- Legacy vessel control system integration:Electric azimuth retrofits must interface with existing Kongsberg or Wärtsilä automation platforms, creating software compatibility risks and commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Transmission Azimuth Thruster Market |
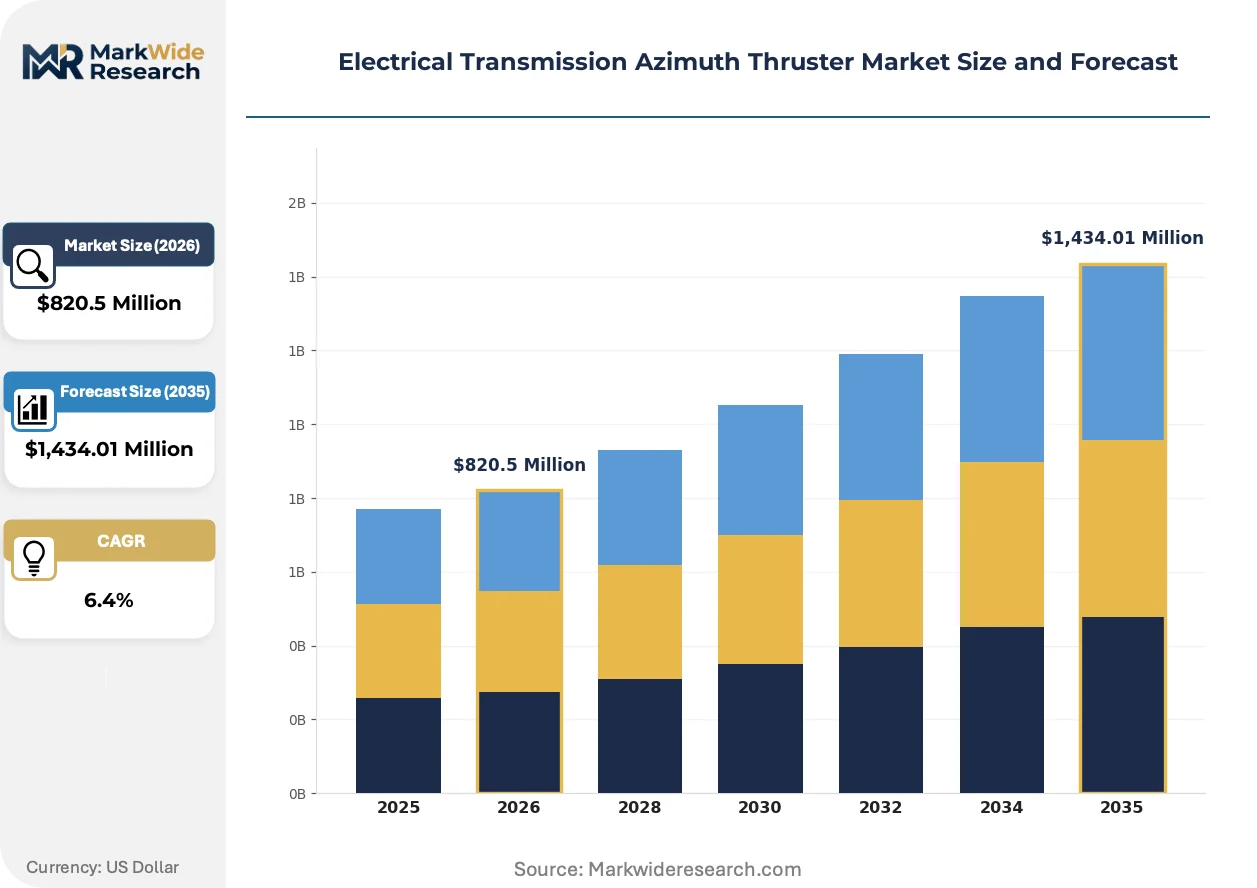
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,434.01 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Thrusters, Dynamic Positioning Thrusters, High-Power Thrusters, Voith Thrusters Technology: Electric Drives, Hybrid Systems, Direct Current Systems, Alternating Current Systems Application: Marine Vessels, Offshore Platforms, Research Vessels, Commercial Ships End User: Shipping Companies, Offshore Operators, Research Institutions, Government Agencies |
| Companies Covered | ABB, Brunvoll, KONGSBERG, SCHOTTEL GROUP, Voith Turbo, Wartsila Corporation, Steerprop, Veth Propulsion, IHI Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Transmission Azimuth Thruster Market Trends and Innovations
Permanent magnet synchronous motor architectures are compressing the physical envelope of electric azimuth units while raising thermal management complexity, forcing a simultaneous evolution in cooling systems and vessel hull integration practices.
Axial-flux motor topologies are collapsing the axial length of electric drive trains by eliminating traditional gearbox stages, enabling thruster installations in vessels with constrained machinery space. Offshore wind turbine installation vessels are specifying these compact configurations to maximize cargo deck area. The structural consequence is a compression in supplier differentiation around gearbox engineering expertise.
EU Emissions Trading System maritime provisions are extending carbon pricing to offshore vessels above 5,000 gross tonnage, imposing operating cost penalties on mechanical propulsion that accelerate electric conversion business cases. Operators in the North Sea cluster are responding by bundling thruster electrification with battery-hybrid retrofits to optimize ETS compliance costs. The regulation is concentrating procurement decisions among fleet managers with sustainability-linked financing covenants.
Charterers are unbundling propulsion system performance guarantees from vessel day-rate contracts, creating direct commercial relationships between offshore operators and thruster manufacturers for uptime commitments. This disintermediation is visible in Norway's North Sea cluster where Equinor and Aker BP are negotiating power-by-the-hour arrangements separate from shipyard contracts. The shift transfers operational risk to thruster OEMs while compressing margins on hardware-only sales.
Electrical Transmission Azimuth Thruster Market Segmentation
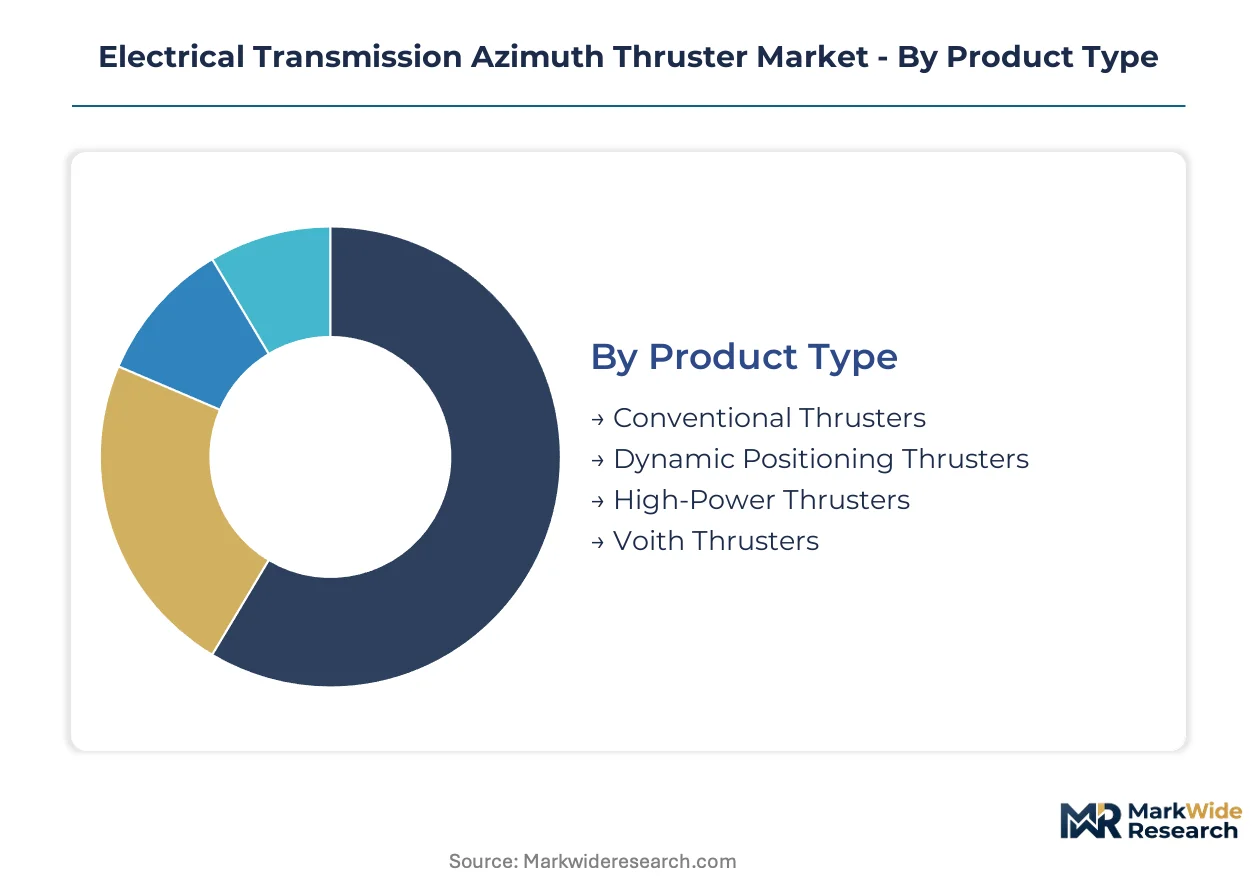
Segmentation in electrical transmission azimuth thrusters reveals how torque density requirements, certification standards, and vessel mission profiles fragment procurement patterns across marine propulsion applications. Understanding these dimensions clarifies why offshore wind installation vessels command premium electric architectures while harbor tugs prioritize compact hybrid configurations.
Product Type:
Cost tier stratification across thruster categories separates premium dynamic positioning units from standardized main propulsion alternatives.
- Dynamic Positioning Thrusters:Redundant electric azimuth units deliver 360-degree thrust vectoring for station-keeping in harsh North Sea environments. Offshore wind foundation vessels in Norway's cluster specify these for turbine installation campaigns where millimeter-precision positioning prevents foundation damage.
- High-Power Thrusters:Megawatt-class electric drives transmit torque through compact Z-drive gearboxes for ice-class vessel propulsion. Japanese floating wind projects under METI feed-in tariffs are stimulating orders for these units capable of breaking through seasonal ice.
- Conventional Thrusters:Standard electric azimuth configurations serve harbor tug and coastal ferry fleets where operational profiles do not justify redundant dynamic positioning investment.
- Voith Thrusters:Cycloidal propeller variants from this specific engineering tradition offer thrust vectoring without azimuth rotation, occupying niche applications in maneuverability-critical vessels.
Dynamic Positioning Thrusters hold installed capacity. High-Power Thrusters is rotating up the share rankings.
Technology:
Application context determines whether pure electric or hybrid architectures satisfy IMO carbon intensity regulations and port electrification mandates.
- Electric Drives:Permanent magnet synchronous motors eliminate gearbox stages in axial-flux configurations, compressing machinery space for offshore wind turbine installation vessels. EU Emissions Trading System maritime provisions are accelerating adoption in North Sea fleets above 5,000 gross tonnage.
- Hybrid Systems:Battery-electric architectures with diesel backup provide fuel flexibility for vessels operating under varying load profiles. Harbor tug operators at Rotterdam and Hamburg are specifying these to comply with shore power infrastructure mandates while maintaining operational range.
- Direct Current Systems:DC bus architectures simplify battery integration and reduce conversion losses for fully electric short-sea shipping routes.
- Alternating Current Systems:AC induction motor drives persist in cost-sensitive retrofit applications where existing vessel electrical infrastructure cannot accommodate DC distribution upgrades.
Electric Drives dominates newbuild specifications. Hybrid Systems is climbing the fastest as retrofit economics improve.
Application:
Volume concentration in offshore platforms is displacing historical marine vessel dominance as floating wind commercialization accelerates.
- Offshore Platforms:Floating wind foundation installation and subsea construction campaigns require redundant thruster configurations for dynamic positioning in harsh environments. Bureau of Ocean Energy Management lease rounds in the US Gulf of Mexico are activating Jones Act-compliant vessel construction with electric azimuth specifications.
- Marine Vessels:Deep-sea shipping and coastal ferry fleets are converting to electric propulsion under EU Green Deal maritime provisions that eliminate mechanical drivelines from newbuild specifications.
- Research Vessels:Scientific mission profiles demand low-noise electric propulsion for acoustic survey operations and sensitive marine ecosystem monitoring.
- Commercial Ships:Container and bulk carrier segments show slower electrification due to long replacement cycles and charter rate structures that do not yet reward carbon intensity performance.
Marine Vessels holds installed capacity. Offshore Platforms is gaining share fastest.
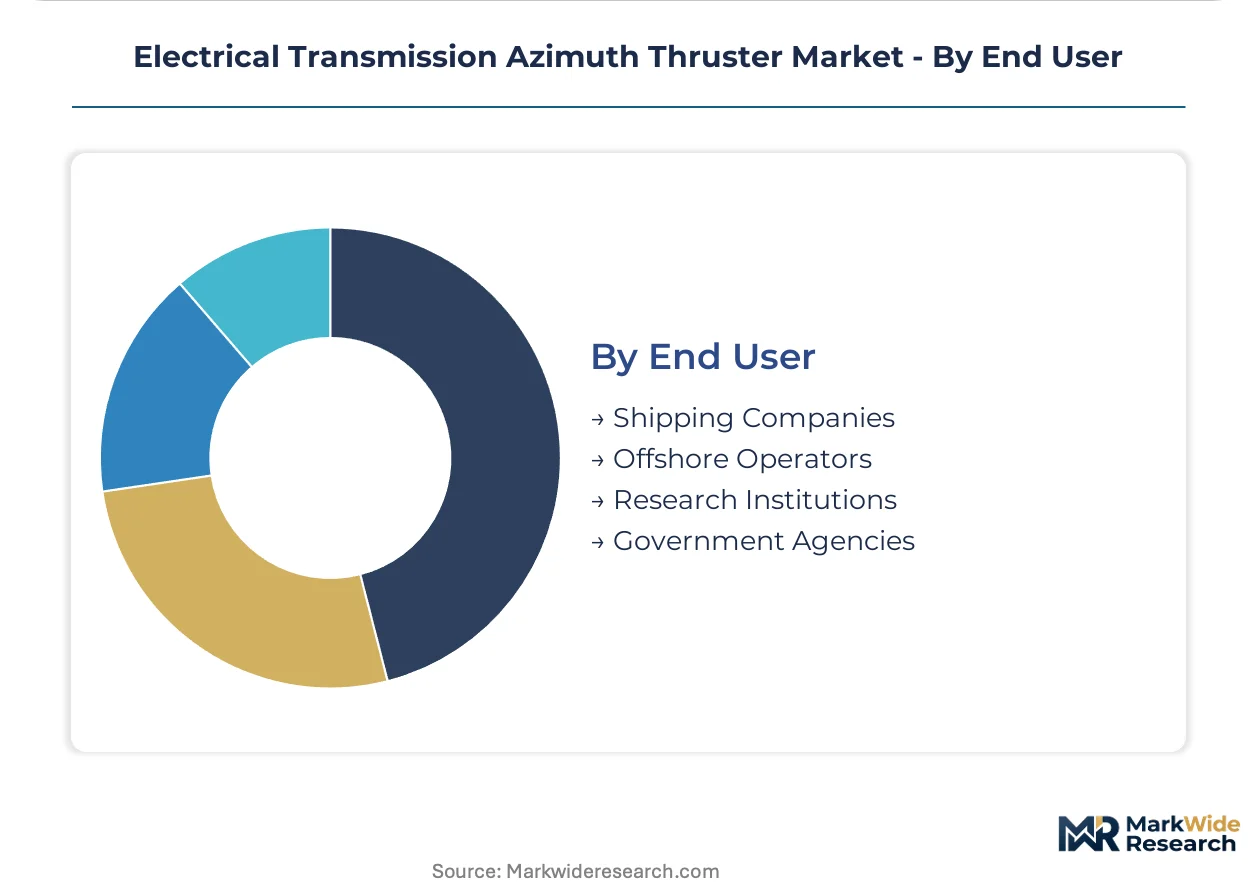
End User:
Customer type determines whether procurement emphasizes total cost of ownership or upfront capital constraints.
- Offshore Operators:Equinor and Aker BP in Norway's North Sea cluster are negotiating power-by-the-hour arrangements directly with thruster OEMs, transferring operational risk from shipyards to component suppliers.
- Shipping Companies:Container line fleet managers prioritize ETS compliance cost optimization through battery-hybrid retrofits bundled with thruster electrification.
- Government Agencies:Naval and coast guard procurement emphasizes ice-class certification and redundancy for sovereignty patrol missions in Arctic and Antarctic waters.
- Research Institutions:Academic and governmental science operators specify low-noise electric propulsion for acoustic research, though contract values remain limited by public budget cycles.
Shipping Companies holds installed capacity. Offshore Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal maritime provisions anchor European demand, while IMO decarbonization rules reshape procurement across coastal economies. Norway's North Sea cluster concentrates floating wind vessel construction. China's shipyard expansion challenges historical fabrication dominance.
Norway
Equinor and Aker BP drive power-by-the-hour contracting for offshore installation fleets. The Norwegian Maritime Authority enforces stringent zero-emission harbor regulations for vessels operating in fjord zones. Stavanger and Bergen anchor the North Sea cluster where turbine foundation vessels specify redundant dynamic positioning thrusters.
Germany
Port electrification mandates at Hamburg and Bremen push harbor tug operators toward battery-hybrid architectures. KBA certification requirements for high-voltage marine systems extend type-approval timelines for megawatt-class drives. The northern coastal states concentrate shipyard retrofit activity around Elbe River facilities.
China
State-owned shipbuilders expand azimuth thruster fabrication capacity for domestic offshore wind programs. MIIT dual carbon goals accelerate electric propulsion adoption in coastal ferry fleets. Jiangsu and Guangdong provinces host manufacturing clusters supplying Z-drive components to regional vessel constructors.
United States
Bureau of Ocean Energy Management lease rounds activate Jones Act-compliant vessel construction for Gulf of Mexico floating wind. EPA marine engine standards tighten allowable emissions for harbor craft operating in port zones. Texas and Louisiana Gulf Coast shipyards specify electric azimuth units for specialized installation vessels.
Japan
METI feed-in tariffs stimulate floating offshore wind projects requiring ice-class propulsion for North Pacific conditions. Classification society Nippon Kaiji Kyokai updates notations for battery-hybrid installations. Nagasaki and Yokohama manufacturing bases produce compact axial-flux drive configurations for constrained machinery spaces.
Electrical Transmission Azimuth Thruster Market Competitive Landscape
Integrated system architects and specialized drive fabricators split the market along control-system bundling versus component-modularity lines. Norwegian and German engineering heritage concentrates premium-tier positioning. Chinese scale producers challenge on delivery timelines. Competitive moves center on strategic partnerships for battery integration and geographic expansion through regional service networks.
Among Nordic integrated solution providers, KONGSBERG anchors vessel automation bundling while Brunvoll occupies Norwegian heritage positioning in ice-class propulsion. SCHOTTEL GROUP exemplifies modular electric drive architectures that reduce installation complexity for retrofit projects. These three represent distinct strategic archetypes: automation-integrated, heritage-premium, and modularity-focused.
| Leading Market Players |
|---|
| ABB |
| Brunvoll |
| KONGSBERG |
| SCHOTTEL GROUP |
| Voith Turbo |
| Wartsila Corporation |
| Steerprop |
| Veth Propulsion |
| IHI Power Systems |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Hamburg barge freight corridors transmit cost volatility from neodymium processing hubs in China directly into thruster landed costs, amplifying price spreads between Norwegian heritage suppliers and Chinese scale producers while forcing buyers toward long-term offtake contracts.
Pricing Analysis
European-North Asian price spreads of 15-25% separate Brunvoll and KONGSBERG premium positioning from Chinese scale alternatives. Three-tier pricing structure across ice-class premium, dynamic positioning standard, and harbor tug economy levels reflects certification grade and after-sales bundling intensity. Pricing pressure stems from rare earth magnet cost volatility and extended Bureau Veritas type-approval timelines. Offshore operators with power-by-the-hour contracts show lowest price sensitivity; independent harbor tug fleets exhibit highest.
Supply Chain Analysis
Contract manufacturing concentrates among Jiangsu and Guangdong shipyard clusters, with Stavanger and Hamburg anchoring European final assembly. Permanent magnet motors draw from Chinese neodymium processing; Z-drive gearboxes source from German and Japanese precision machining; high-voltage inverters rest on South Korean semiconductor supply. Single-source vulnerability in rare earth magnet supply creates tariff exposure and geopolitical risk. Distribution runs through shipyard integration contracts and direct OEM procurement for retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where IMO decarbonization rules and EU Green Deal provisions lock in incumbent positioning through certification notations that new entrants cannot rapidly replicate.
For Market Incumbents: Build switching-cost moats through deeper software integration with Kongsberg and Wärtsilä automation platforms. Expand service network density in the US Gulf of Mexico to capture Jones Act vessel construction. Invest in axial-flux motor R&D to defend against Chinese scale producers entering the premium tier. Counter emerging threat from modular retrofit specialists by tightening shipyard partnership exclusivity. For New Entrants and Emerging Players: US Gulf of Mexico Jones Act vessel construction represents the most penetrable entry point for electric azimuth suppliers lacking European heritage certification. Japanese floating wind projects under METI feed-in tariffs offer second-mover positioning for ice-class compact drive configurations. Target harbor tug battery-hybrid retrofits at Rotterdam and Hamburg through port electrification mandate alignment. Go-to-market angle: shore power integration bundling with local electrical contractors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-modular specialists with axial-flux motor IP and established classification society notations. Long-term viability hinges on regulatory entrenchment duration and rare earth magnet supply diversification progress. Acquisition archetype: mid-cap thruster OEMs with DNV battery-hybrid certifications and regional service networks in nascent offshore wind markets. Signal to watch: Bureau of Ocean Energy Management lease round velocity as US demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Axial-Flux Motor R&D Investment | Compresses machinery space for offshore wind turbine installation vessels, eliminating gearbox stages. |
| DNV Battery-Hybrid Certification | Enables insurance premium advantages and charter rate premiums in North Sea fleets. |
| US Gulf Service Network Expansion | Captures Jones Act vessel construction triggered by Bureau of Ocean Energy Management auctions. |
| Rare Earth Magnet Supply Diversification | Reduces neodymium concentration risk from Chinese processing exposure. |
| Power-by-the-Hour Contracting | Transfers operational risk from shipyards to thruster OEMs while securing recurring revenue. |
Research Methodology
Operator-level perspectives from offshore platform engineers, shipyard procurement directors, classification society surveyors, and port electrification planners anchored the qualitative base. Primary interviews with KONGSBERG automation specialists, Brunvoll ice-class propulsion engineers, and SCHOTTEL retrofit project managers combined with secondary validation from Lloyd's Register type-approval databases, DNV certification notations, and IMO MEPC submission records. Customs data from Hamburg and Rotterdam tracked component import flows. Bottom-up vessel orderbook analysis triangulated against top-down offshore wind capacity projections.
Scenario-bracketing around EU Green Deal implementation pace and IMO carbon intensity index enforcement stringency shaped the analytical framework. Segmentation modeling spanned product type, technology architecture, application mission profile, and end-user procurement sophistication across the projection horizon. CAGRs derived from vessel orderbook velocity, offshore wind foundation installation campaign schedules, and electrification retrofit economics. Industry-specific inputs included rare earth magnet price trajectory assumptions and high-voltage marine certification timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in offshore oil capital expenditure cycles, floating wind auction clearing prices, or China-EU trade policy would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology substitution rates. Cross-checking against Lloyd's Register and DNV newbuild order databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Global Overhead Line Conductors Market