
 Ring Main Unit Market | 2026-2036
Ring Main Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Ring Main Unit Market Intelligence
The capital-intensity divergence between integrated manufacturers and assembly-focused suppliers is rotating competitive advantage toward firms with in-house casting and testing facilities. ABB Ltd. leverages its European factory footprint to sustain margin control on gas-insulated variants. Siemens AG anchors its position through vacuum interruption specialization across German and Chinese production lines. Eaton Corporation PLC competes on utility channel density in North American distribution markets.
A ring main unit is a factory-assembled, metal-enclosed switchgear assembly rated for medium-voltage distribution networks, typically incorporating load-break switches, circuit breakers, and protective relays within a compact, sealed housing designed for ring-topology feeder reliability. Its primary purpose is to enable sectionalized power restoration without full network shutdown, reducing outage duration in urban and industrial distribution grids. Gas insulated ring main units command premium positioning due to space constraints in dense European and Asian substations, while solid dielectric variants are gaining fastest traction where SF6 environmental restrictions apply. Vacuum circuit breaker technology leads replacement cycles across aging oil-breaker installations, concentrating margin pools in retrofit-driven utility procurement.
IEC 62271-200, IEEE C37.20.3, and EU F-Gas Regulation collectively dictate insulation medium choices, enclosure integrity testing, and phased SF6 phaseout timelines across major markets. These frameworks compel manufacturers to redesign product portfolios around vacuum and solid-dielectric architectures while recertifying existing platforms. Stakeholders must weigh stranded asset risk in SF6-dependent installed bases against the capital requirements of dual-technology production lines.
Market Dynamics
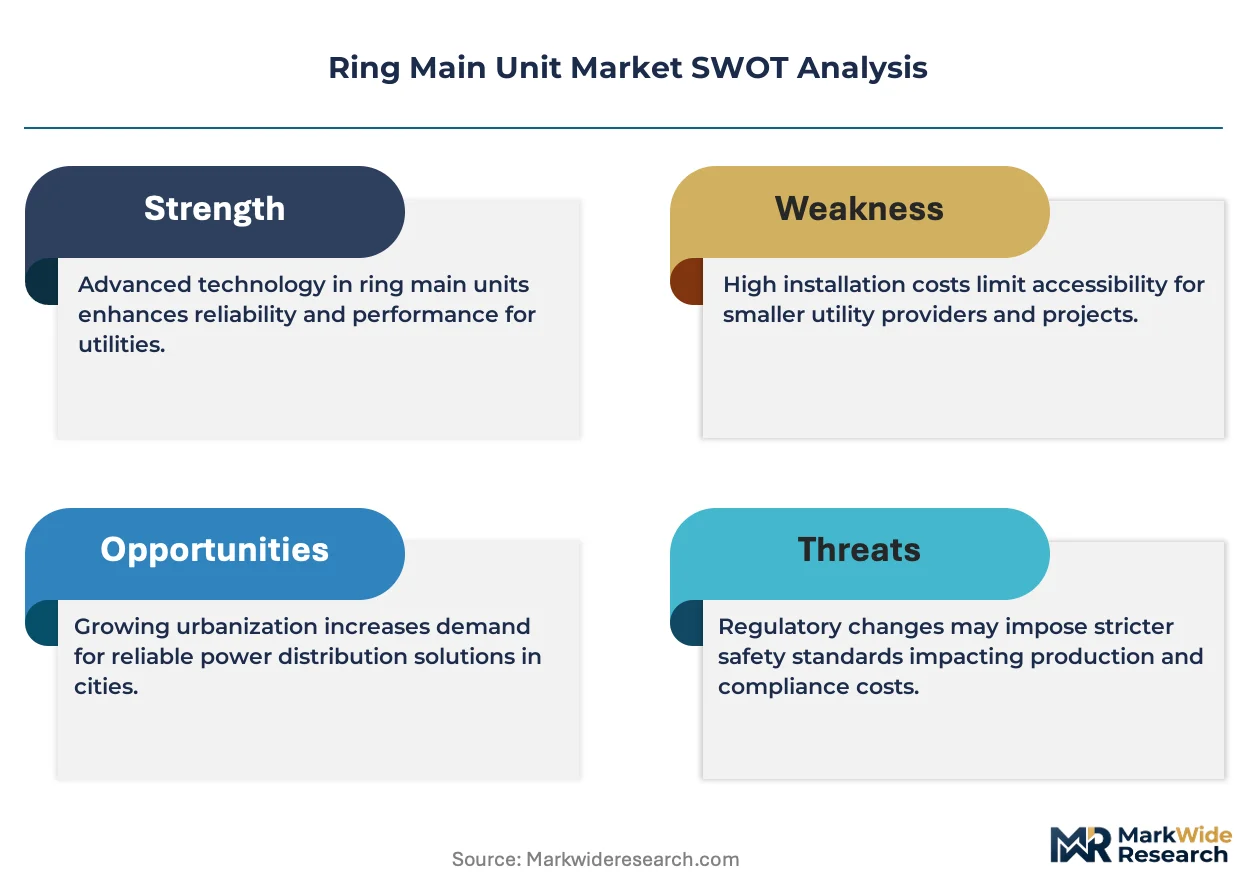
The EU F-Gas Regulation's phased SF6 phaseout is compressing product development cycles, forcing manufacturers to recertify portfolios around vacuum and solid-dielectric architectures while managing stranded asset exposure in gas-insulated installed bases.
Growth Catalysts
- Urban electrification mandates:India's urban infrastructure programs are driving medium-voltage distribution network expansion, creating concentrated procurement volume for compact switchgear solutions.
- Environmental compliance frameworks:The EU F-Gas Regulation is accelerating technology transitions by establishing binding timelines for SF6 reduction across European utility procurement specifications.
- Retrofit replacement cycles:Aging oil-breaker installations across Southeast Asian distribution grids are generating replacement demand for vacuum interruption technology.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings in conductor metals are compressing margins for assembly-focused suppliers lacking captive casting capacity.
- Testing infrastructure concentration:In-house high-voltage testing facilities cluster among integrated European and Japanese manufacturers, creating certification bottlenecks for regional challengers.
- Solid dielectric performance ceilings:Thermal runaway risks in compact solid-insulation designs limit application range in high-load-density urban substations.
Strategic Opportunities
- Secondary city penetration in Vietnam:Provincial utility expansion outside Hanoi and Ho Chi Minh City presents underpenetrated demand for standardized ring main unit configurations.
- Digital twin integration:Convergence of switchgear hardware with asset monitoring software enables predictive maintenance service contracts in Scandinavian utility markets.
- India's PLI scheme for electrical equipment:Production-linked incentives are attracting component localization investments that reduce import dependency for domestic switchgear assemblers.
Industry Challenges
- Shortage of medium-voltage switchgear design engineers:Specialized expertise in arc quenching and insulation coordination is concentrating among aging workforces in Germany and Japan.
- Dual-technology production line capex:Simultaneous SF6 and vacuum platform manufacturing requires redundant testing bays and cleanroom assembly zones.
- IEC 62271-200 recertification timelines:Revised enclosure integrity testing protocols are extending product launch schedules by 8-14 months for platform redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ring Main Unit Market |
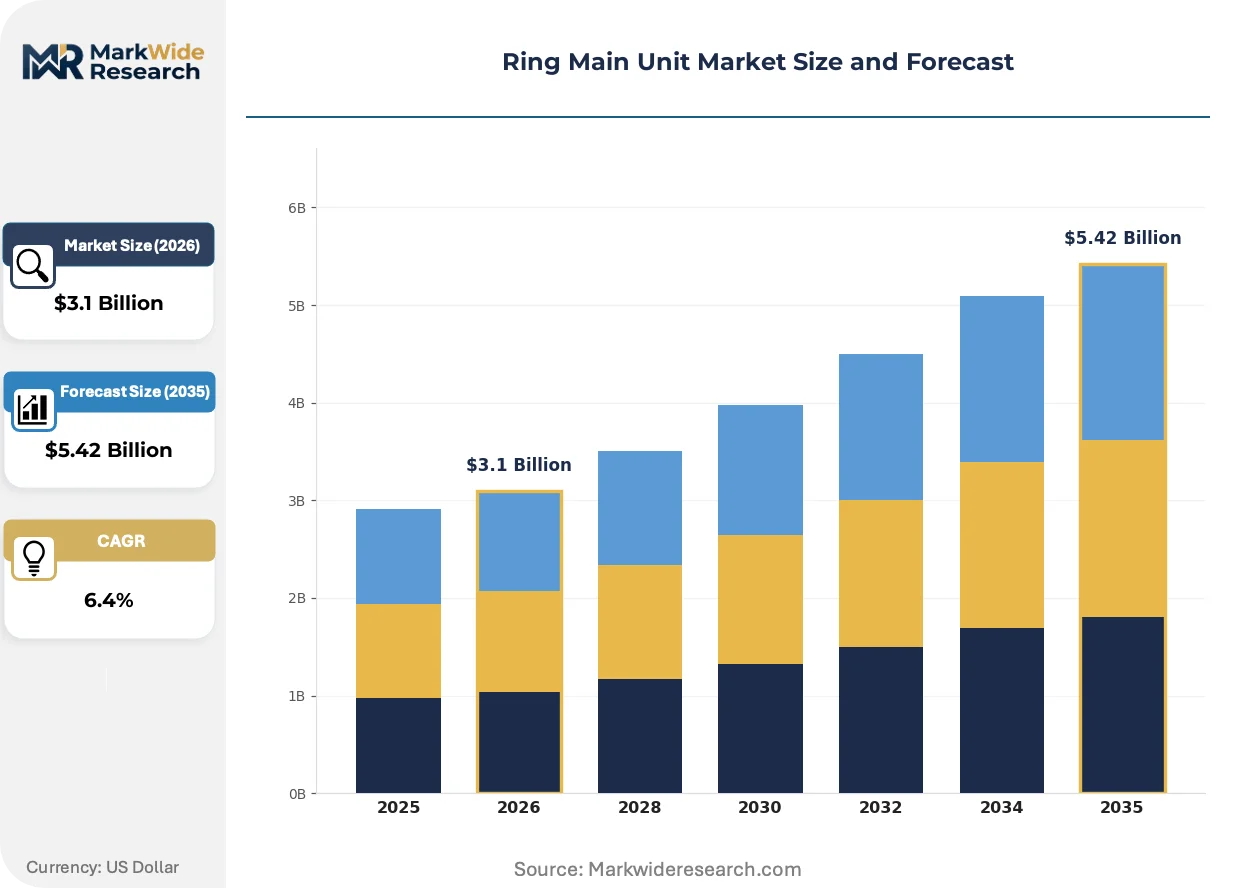
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Air Insulated, Gas Insulated, Vacuum Interruption, SF6 Insulated, Solid Dielectric Technology: Sulfur Hexafluoride Circuit Breakers, Vacuum Circuit Breakers, Oil Circuit Breakers, Air Blast Circuit Breakers, Hybrid Circuit Breakers Application: Power Distribution, Substations, Industrial Power Supply, Commercial Complexes, Urban Infrastructure End User: Utility Companies, Government Facilities, Industrial Plants, Commercial Enterprises, Renewable Energy Operators |
| Companies Covered | Eaton Corporation PLC, LS Electric Co., Ltd., Schneider Electric SE, CHINT Group, Toshiba Corporation, ABB Ltd., Lucy Electric, GE Vernova, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ring Main Unit Market Strategic Shifts & Innovations
Vacuum interruption technology is bifurcating competitive positioning across the ring main unit landscape, separating manufacturers with proprietary contact material science from those dependent on external component sourcing.
Solid dielectric insulation is bifurcating product architectures into sealed-for-life urban designs versus modular field-serviceable units, with German utilities favoring maintenance-free configurations while Indian distributors prioritize component accessibility for remote site conditions.
The EU F-Gas Regulation is compressing technology roadmaps by prohibiting new SF6-based equipment in medium-voltage distribution after 2026, compelling manufacturers to accelerate vacuum and dry air platform launches while managing residual service obligations for existing gas-insulated installations across France and Italy.
Utility procurement departments are unbundling switchgear supply from engineering-procurement-construction contracts, with state-owned distributors in Thailand and Malaysia establishing direct vendor qualification programs that bypass traditional EPC intermediaries and compress pricing negotiation cycles.
Ring Main Unit Market Segmentation
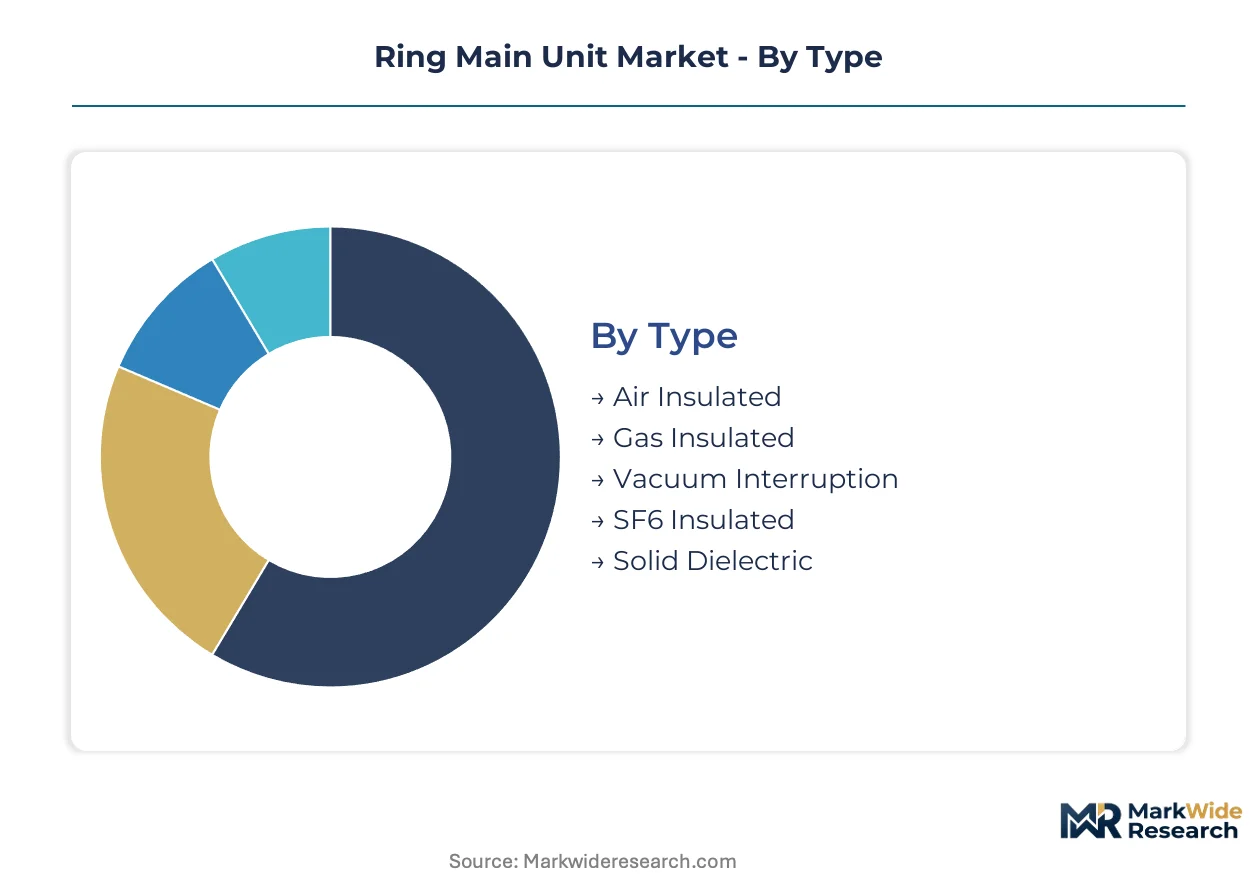
Technology substitution pressures and regulatory phaseouts are fragmenting demand across insulation mediums and interruption mechanisms. Procurement specifications now diverge sharply between markets with binding environmental deadlines and those prioritizing capital cost minimization.
Type:
Substitution pressure from environmental regulations concentrates most intensely on gas-dependent insulation formats, while vacuum and solid-dielectric architectures capture displaced procurement volume.
- Gas Insulated:Sealed SF6-filled enclosures deliver superior dielectric strength in minimal footprint for dense European and East Asian substations. German utilities and French distribution operators remain the core demand concentration despite tightening EU F-Gas Regulation timelines that now prohibit new installations post-2026.
- Vacuum Interruption:Contact separation in high-vacuum chambers eliminates arc medium entirely, eliminating environmental compliance exposure. Indian state electricity boards and Southeast Asian provincial utilities are concentrating replacement procurement here as aging oil-breaker fleets reach end-of-life.
- Air Insulated:Open-air conductor spacing suits rural distribution with ample right-of-way.
- SF6 Insulated:Legacy installed base across Italy and Spain generates residual service and retrofit demand.
- Solid Dielectric:Epoxy-resin insulation targets maintenance-free urban deployments in Scandinavian markets.
Gas insulated retains volume leadership; solid dielectric holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium vacuum platforms from economy oil-breaker replacements, with hybrid architectures emerging at mid-tier price points.
- Vacuum Circuit Breakers:Ceramic-brazed vacuum interrupters with copper-chromium contacts withstand 10,000+ mechanical operations. Demand concentrates in Thailand and Malaysia where state-owned distributors bypass EPC intermediaries for direct vendor qualification.
- Sulfur Hexafluoride Circuit Breakers:SF6 arc quenching maintains highest interrupting ratings for high-load-density applications. European procurement specifications are phasing out this technology, compressing residual demand into Middle Eastern and African markets without equivalent regulatory deadlines.
- Oil Circuit Breakers:Aging installed base across Vietnam and Indonesia drives replacement cycles.
- Air Blast Circuit Breakers:Compressed-air interruption persists in legacy Indian substations.
- Hybrid Circuit Breakers:Combined vacuum-SF6 designs target transitional compliance strategies.
Vacuum circuit breakers command the premium tier; hybrid configurations are climbing fastest as interim compliance solutions.
Application:
Application maturity varies by electrification stage, with urban infrastructure exhibiting highest specification intensity and substation deployments showing strongest volume scale.
- Power Distribution:Ring-topology feeder sectionalization enables outage isolation without full network shutdown. India's urban infrastructure electrification programs concentrate procurement volume for compact switchgear in secondary cities and industrial corridors.
- Urban Infrastructure:Underground distribution networks in dense metropolitan zones demand space-optimized switchgear with sealed-for-life insulation. German utilities favor maintenance-free configurations while Indian distributors prioritize component accessibility.
- Substations:Primary and secondary transformation points require highest reliability ratings.
- Industrial Power Supply:Manufacturing clusters in Vietnam's northern provinces drive standardized unit demand.
- Commercial Complexes:Shopping centers and office districts specify compact indoor installations.
Power distribution anchors volume; urban infrastructure shows the most rapid specification escalation.
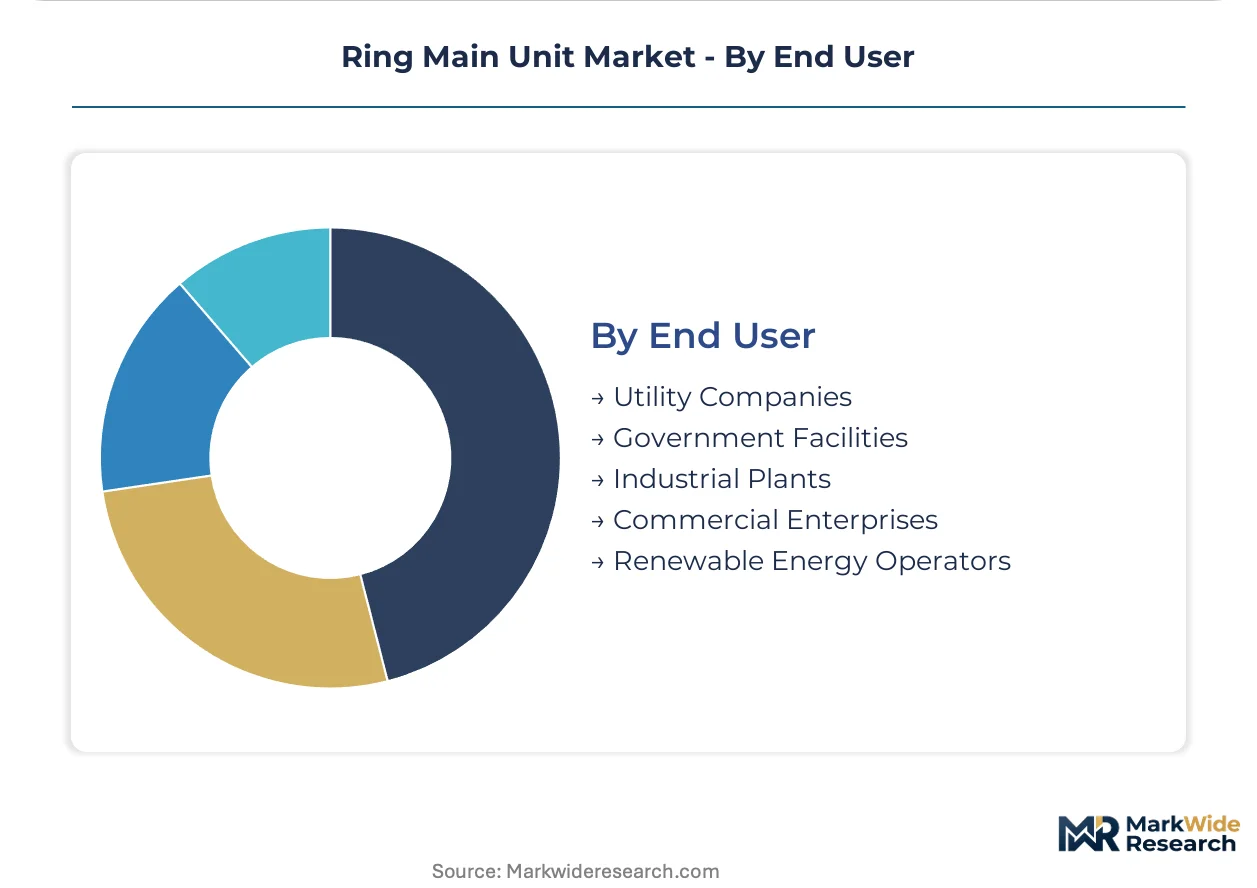
End User:
Customer type determines procurement channel structure, with utility direct-buy programs displacing traditional EPC intermediaries in fastest-growing markets.
- Utility Companies:State-owned distribution operators in Thailand, Malaysia, and Vietnam establish direct vendor qualification programs that compress pricing negotiation cycles and unbundle switchgear supply from engineering-procurement-construction contracts.
- Industrial Plants:Manufacturing facilities require customized protection coordination for process-critical loads. Steel and cement producers in India's western states specify vacuum interruption for reliability-sensitive operations.
- Government Facilities:Public infrastructure projects favor standardized configurations with domestic content requirements.
- Commercial Enterprises:Private developers prioritize capital cost minimization over lifecycle value.
- Renewable Energy Operators:Solar and wind farm interconnection demands compact collector substation designs.
Utility companies dominate procurement volume; renewable energy operators are expanding most quickly as grid interconnection backlogs clear.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement departments in India demonstrate the highest price elasticity, squeezing margins on standardized configurations, while German distributors absorb premiums for sealed-for-life maintenance-free designs. Southeast Asian markets occupy a mid-tier position, balancing specification intensity against capital constraints.
Germany
Distribution network operators prioritize space-optimized switchgear for dense urban substations in Berlin and Hamburg. The EU F-Gas Regulation prohibits new SF6-based equipment installations after 2026, compressing technology transition timelines. Bavarian utilities favor maintenance-free solid dielectric configurations over field-serviceable alternatives.
India
State electricity boards concentrate procurement volume for secondary city electrification programs across Maharashtra and Gujarat. The PLI scheme for electrical equipment attracts component localization investments that reduce import dependency. Tamil Nadu's industrial corridors generate concentrated demand for vacuum interruption technology in manufacturing clusters.
Thailand
Provincial utilities outside Bangkok expand medium-voltage distribution networks with standardized ring main unit specifications. State-owned distributors establish direct vendor qualification programs that bypass traditional EPC intermediaries. Manufacturing zones in the Eastern Economic Corridor drive reliability-sensitive procurement for process-critical loads.
Vietnam
Secondary city electrification in Da Nang and Hai Phong presents underpenetrated demand for compact switchgear configurations. Aging oil-breaker installations across northern provinces generate replacement cycles for vacuum interruption platforms. Provincial power corporations prioritize capital cost minimization over lifecycle value in remote site conditions.
France
Distribution operators Enedis and local grid managers face binding SF6 phaseout deadlines under EU F-Gas Regulation timelines. The country's national energy regulator enforces accelerated decarbonization mandates for medium-voltage infrastructure. Industrial clusters around Lyon and Marseille concentrate residual service demand for legacy gas-insulated installations.
Ring Main Unit Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with European and Japanese manufacturers commanding certification advantages through captive high-voltage testing infrastructure. Assembly-focused suppliers compete on channel density and regional logistics rather than proprietary technology. Two strategic archetypes dominate: vertically integrated foundry-to-finished-goods producers, and component-assembly specialists sourcing vacuum interrupters externally. Competitive moves center on dual-technology production line investments and direct utility qualification programs that displace EPC intermediaries.
Within the integrated European tier, ABB Ltd. and Siemens AG anchor positions through proprietary manufacturing footprints and established certification pathways. Eaton Corporation PLC occupies a position among North American channel-dense suppliers competing on utility relationships rather than captive component production. LS Electric Co., Ltd. exemplifies the Korean specialist archetype, leveraging regional manufacturing scale for Southeast Asian procurement volumes. These three represent distinct competitive vectors: European integration, North American distribution density, and Asian manufacturing scale.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| LS Electric Co., Ltd. |
| Schneider Electric SE |
| CHINT Group |
| Toshiba Corporation |
| ABB Ltd. |
| Lucy Electric |
| GE Vernova |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
IEC 62271-200 recertification timelines gate both supplier qualification and price differentiation simultaneously, compressing product launch schedules while segmenting manufacturers into premium certified tiers versus unqualified challengers. The EU F-Gas Regulation's SF6 phaseout accelerates this bifurcation by forcing dual-technology production investments that concentrate margin control among integrated European and Japanese producers.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value differentiation beyond initial equipment sales. Three-tier pricing structure across premium certified, standard compliant, and economy unqualified levels separates ABB and Siemens from regional assemblers sourcing vacuum interrupters externally. Pricing pressure stems from copper and aluminum volatility squeezing assembly-focused suppliers lacking captive casting capacity. Indian state electricity boards exhibit highest price elasticity, while German utilities absorb premiums for sealed-for-life maintenance-free configurations.
Supply Chain Analysis
Germany and Japan anchor proprietary vacuum interrupter production and high-voltage testing infrastructure. China and South Korea feed component assembly lines with epoxy resin housings and ceramic brazed chambers. Raw material dependencies on copper-chromium contact materials, conductor-grade aluminum, and sulfur hexafluoride for residual service obligations create exposure. Single-source vulnerability concentrates in vacuum interrupter supply from aging workforces in Stuttgart and Nagoya. Distribution runs through direct vendor qualification programs that state-owned utilities in Thailand and Malaysia use to bypass traditional EPC intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against solid dielectric and dry air architectures displacing residual SF6 demand. Vacuum interruption specialization now separates viable incumbents from stranded asset risk.
For Market Incumbents: Fortify proprietary vacuum interrupter production through backward integration into copper-chromium contact material science. Expand captive high-voltage testing bay capacity to compress recertification timelines for IEC 62271-200 platform redesigns. Lock in direct utility qualification relationships before regional challengers replicate channel-bypass strategies. For New Entrants and Emerging Players: Predictive maintenance software integration presents underexploited white space where incumbent hardware manufacturers under-serve Scandinavian utility asset management needs. Target Vietnam's provincial power corporations outside Hanoi and Ho Chi Minh City with field-serviceable modular designs prioritizing component accessibility over sealed-for-life configurations. Anchor go-to-market through EPC contractor partnerships before direct qualification programs mature. For Investors and Strategic Acquirers: The EU F-Gas Regulation's 2026 SF6 installation prohibition reshapes the acquisition landscape toward vacuum and solid-dielectric platform readiness. Five-to-ten year viability favors vertically integrated manufacturers with in-house foundry and testing infrastructure over assembly-dependent specialists. Watch for accelerated provincial utility direct-buy program adoption across Southeast Asia as inflection signal for channel structure permanence.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Technology Production Line Investment | Simultaneous SF6 and vacuum platform manufacturing captures transitional compliance demand across French and Italian residual service markets. |
| Direct Utility Qualification Program | State-owned distributors in Thailand and Malaysia bypass EPC intermediaries to compress pricing negotiation cycles. |
| Predictive Maintenance Software Integration | Digital twin convergence enables recurring revenue contracts in Scandinavian utility asset management procurement. |
| Component Localization Under PLI Scheme | India's production-linked incentives reduce import dependency for domestic switchgear assemblers in Maharashtra and Gujarat. |
| Proprietary Vacuum Interrupter Development | Ceramic-brazed chamber production with captive copper-chromium contact science separates integrated manufacturers from external sourcing dependence. |
Research Approach
Cross-validation between utility procurement officer interviews and secondary regulatory filings anchors the qualitative findings. Primary fieldwork engaged distribution planning directors at state electricity boards, switchgear engineering managers at integrated manufacturers, EPC contractor procurement leads, and high-voltage testing facility operators. Secondary sources incorporated IEC standards documentation, EU F-Gas Regulation compliance databases, and customs trade records for conductor metal flows. Bottom-up demand modeling triangulated against top-down infrastructure investment forecasts.
Sensitivity analysis across copper price volatility bands and recertification timeline scenarios stress-tested projection robustness. Segmentation dimensions spanned insulation medium, interruption technology, application intensity, and end-user procurement channel structure. CAGRs derived from infrastructure electrification program commitments and replacement cycle dynamics for aging oil-breaker installations. Forecast inputs incorporated utility capital expenditure disclosures and provincial grid expansion timelines.
Material uncertainties — commodity price swings, regulatory deadline acceleration, and workforce retirement concentration — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution velocity and direct-buy program adoption rates. Recalibration cycles align with material shifts in F-Gas Regulation enforcement and medium-voltage switchgear design engineer availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Electrical Substation Management Market