
 Electric Insulator Market | 2026-2036
Electric Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Insulator Market Analysis
Multi-sourcing of raw alumina and silicone rubber is rebalancing procurement patterns across the electric insulator supply base. NGK Insulators Ltd anchors ceramic substrate production through captive mining interests in Japan. Siemens AG leverages polymer formulation partnerships to extend its composite insulator footprint in European transmission upgrades. Aditya Birla Insulators dominates domestic porcelain supply for India's state electricity boards through integrated manufacturing at multiple plant locations.
An electric insulator is a non-conductive material engineered to resist electrical current flow, typically rated for dielectric strength exceeding 10 kV/mm and surface resistivity above 10^12 ohm-cm, serving to mechanically support and electrically isolate conductors in power infrastructure. Suspension insulators and polymer-composite variants now capture the fastest expansion as utilities replace legacy glass strings in contaminated environments and coastal corridors. Porcelain retains volume leadership in distribution networks where decades of field-proven reliability outweighs weight penalties, while bushings command premium pricing in transformer and switchgear integration.
IEC 60383 and ANSI C29 standards govern dimensional and electrical performance benchmarks, with CEA technical regulations in India mandating pollution-specific creepage distances for regional grid operators. REACH restrictions in Europe constrain certain flame-retardant additives in polymer housings, redirecting formulation R&D toward halogen-free silicone compounds. Stakeholders must track evolving material certification requirements across multiple jurisdictions to secure long-term procurement contracts and avoid retrofit liabilities.
Market Dynamics
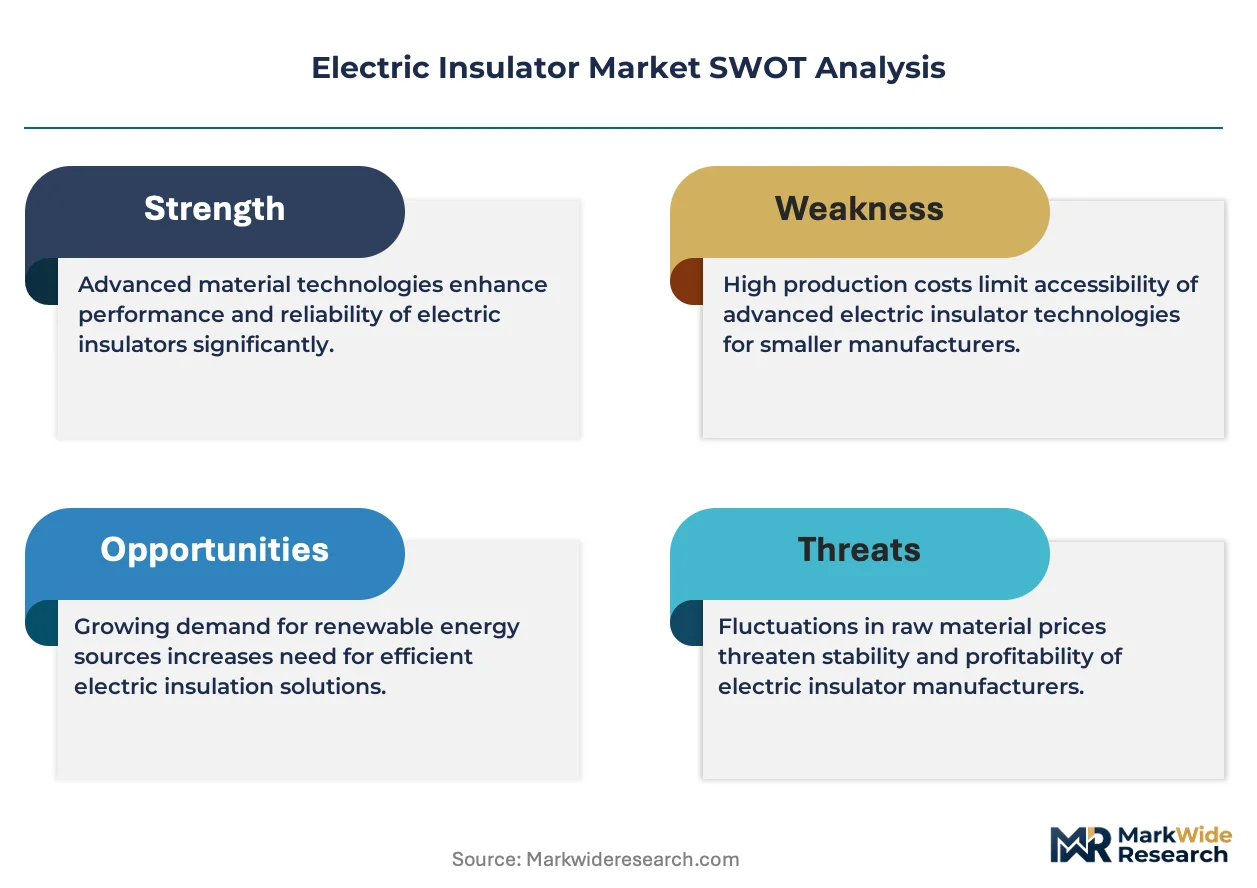
Polymer composite insulators are compressing replacement cycles across high-pollution transmission corridors, forcing utilities to revalue total cost of ownership against legacy porcelain reliability metrics.
Growth Catalysts
- CEA Grid Modernization Mandates:India's Central Electricity Authority mandates accelerated transmission infrastructure expansion, creating sustained procurement pull for suspension and tension insulator assemblies.
- Silicone Rubber Formulation Advances:Improved hydrophobicity in polymer housings extends service intervals in coastal and industrial contamination zones, reducing maintenance expenditure for regional grid operators.
- Renewable Integration Load Profiles:Solar and wind farms require specialized insulation rated for variable voltage fluctuations, generating specification demand distinct from baseload transmission standards.
Market Restraints
- Alumina Supply Concentration:Captive mining interests in East Asia control high-purity ceramic substrate feedstock, exposing porcelain insulator manufacturers to input cost volatility and allocation risk.
- REACH Flame-Retardant Restrictions:European ECHA constraints on halogenated additives force reformulation of polymer housings, extending R&D timelines and certification costs for composite insulator suppliers.
- Glass String Inventory Inertia:Decades of field-proven reliability data for legacy glass suspension strings create specification stickiness among conservative procurement committees at established utilities.
Strategic Opportunities
- HVDC Bushing Specialization:Converter station expansion for submarine cable interconnectors creates premium demand for high-voltage direct current bushings with enhanced thermal cycling tolerance.
- Smart Grid Sensor Integration:Embedding partial discharge monitoring into composite insulator cores unifies insulation and diagnostics functions, opening specification channels with digitally advanced transmission operators.
- PLI-Linked Manufacturing Scale:India's production-linked incentive schemes for electrical equipment attract capacity expansion for export-competitive insulator production serving Middle East and African markets.
Industry Challenges
- IEC 60383 Certification Timelines:Multi-jurisdictional type-testing protocols for new polymer formulations delay product launch windows by 18-24 months, compressing effective revenue recognition periods.
- Legacy Glass String Retrofit Coordination:Transmission line live-line replacement procedures require specialized tooling and crew certification, constraining deployment velocity even where composite alternatives demonstrate superior performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Insulator Market |
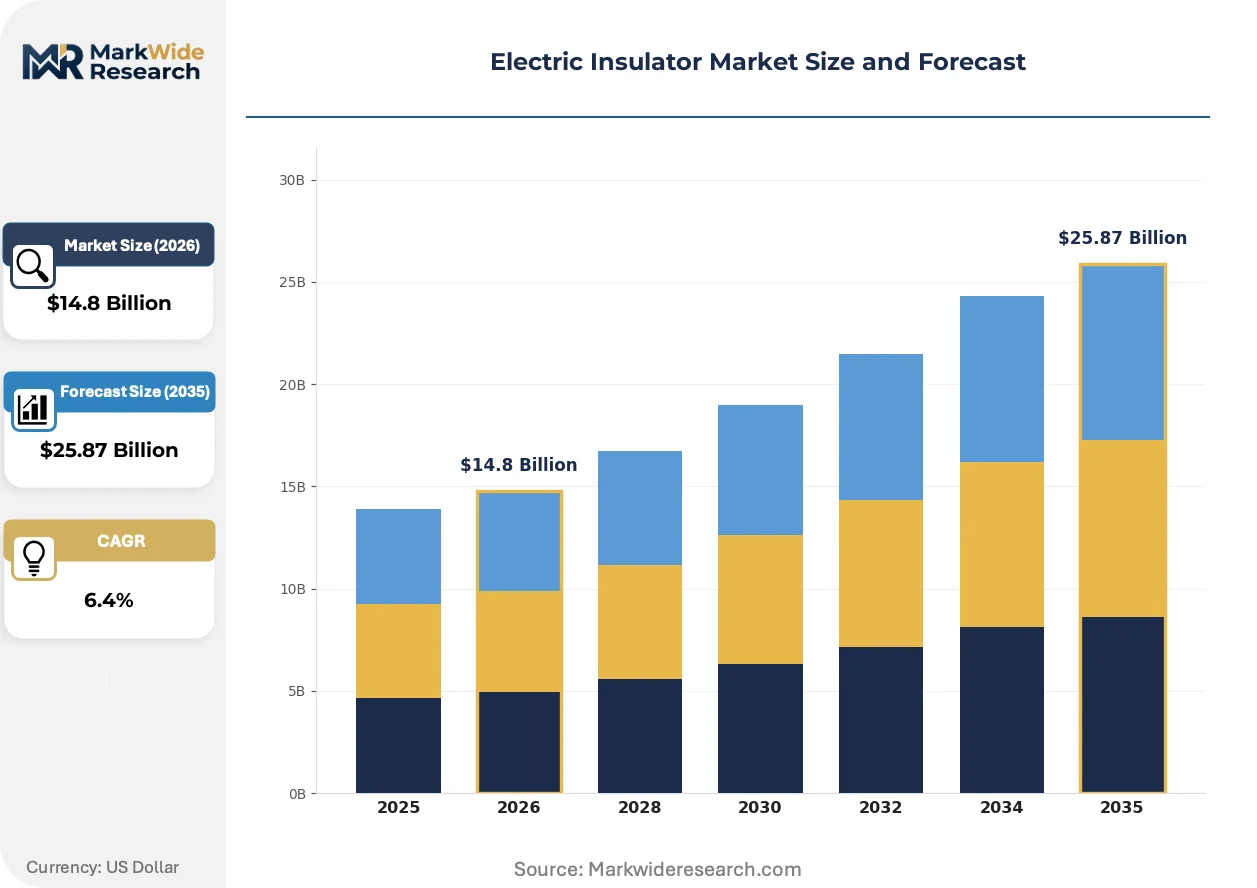
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suspension Insulators, Pin Insulators, Line Post Insulators, Bushings Material: Porcelain, Glass, Polymer, Composite Application: Transmission Lines, Distribution Networks, Substations, Renewable Energy End User: Utilities, Construction, Manufacturing, Telecom |
| Companies Covered | NGK Insulators Ltd, Hitachi Energy, ABB Ltd, PFISTERER, Aditya Birla Insulators, Siemens AG, Hubbell Incorporated, Seves Group, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Insulator Market Emerging Trajectories
Material science convergence with digital monitoring capabilities is redefining insulator value propositions beyond dielectric performance alone. Specification criteria now weight total lifecycle telemetry and predictive maintenance integration.
Silicone rubber housing technology with nano-structured surface coatings is unifying contamination resistance and self-cleaning functionality in a single material system. Transmission utilities in coastal Gujarat and Maharashtra have accelerated adoption for 220 kV and 400 kV lines. This unification is compressing the traditional trade-off between polymer weight advantages and porcelain contamination endurance.
REACH restrictions on halogenated flame retardants are redirecting European polymer formulation R&D toward bio-based silicone compounds and mineral-filled alternatives. Insulator manufacturers serving EEA markets must resubmit technical files under updated safety data sheet protocols. The composite housing segment bears the heaviest compliance burden, with smaller formulation houses exiting rather than absorbing retesting costs.
Utility procurement committees are consolidating supplier relationships around integrated insulation-transformer-switchgear packages rather than discrete component bidding. Original equipment manufacturers with full portfolio coverage capture preference in European transmission upgrades and Indian state electricity board tenders. This concentration is most visible in Germany's TenneT corridor projects and Mahatransco's 765 kV expansion programs.
Electric Insulator Market Segmentation
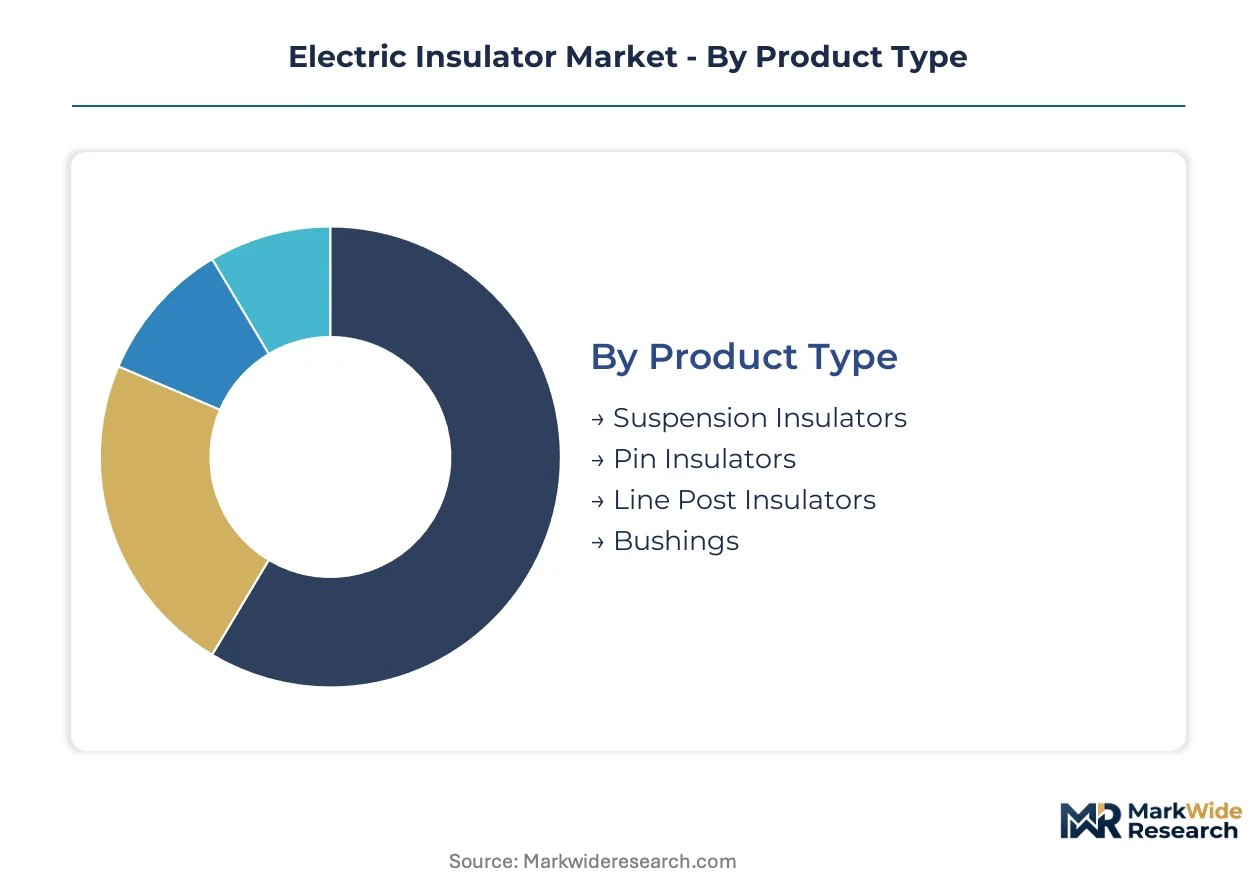
Segmentation in electric insulators reveals how specification requirements diverge across contamination exposure, voltage ratings, and grid modernization priorities. Procurement committees weight IEC 60383 certification tiers differently depending on whether installations serve coastal transmission corridors or inland distribution networks.
Product Type:
IEC 60383 type-testing protocols impose distinct certification timelines across product categories, with suspension strings requiring extended mechanical load cycling validation.
- Suspension Insulators:These string assemblies link multiple disc units to achieve high-voltage ratings for overhead transmission. Gujarat and Maharashtra utilities specify polymer-composite variants for 220 kV and 400 kV lines in high-pollution zones, driven by CEA mandates for grid modernization in contaminated environments.
- Bushings:Transformer and switchgear integration requires these cylindrical insulators to manage high electric field gradients at conductor entry points. HVDC converter station expansion for submarine cable interconnectors generates premium demand for bushings with enhanced thermal cycling tolerance.
- Pin Insulators:Compact single-unit designs mount directly on cross-arms for low-voltage distribution feeders.
- Line Post Insulators:Rigid vertical supports replace pin types in compact substation layouts and urban distribution.
Suspension insulators sit at the top of the volume ranking, with bushings climbing the fastest.
Material:
Cost tiers separate legacy ceramics from advanced polymers, with procurement committees revaluing total cost of ownership against field-proven reliability metrics.
- Polymer:Silicone rubber housings with nano-structured surface coatings unify contamination resistance and self-cleaning functionality. Coastal utilities in India specify these for variable load conditions at solar and wind farms.
- Composite:Fiberglass core rods with polymer sheds deliver weight advantages for live-line replacement procedures. European REACH restrictions on halogenated flame retardants force reformulation toward bio-based silicone compounds.
- Porcelain:Alumina-based ceramics retain specification preference where decades of field data outweigh weight penalties.
- Glass:Legacy suspension strings maintain procurement stickiness among conservative utility committees.
Polymer sits at the top of the volume ranking, with composite expanding most quickly.
Application:
Customer maturity determines whether procurement prioritizes proven reliability or integrated monitoring capabilities.
- Transmission Lines:High-voltage corridors above 66 kV require contamination-specific creepage distances under CEA technical regulations. Silicone rubber formulation advances extend service intervals in coastal and industrial zones.
- Renewable Energy:Solar and wind farms need insulation rated for voltage fluctuations distinct from baseload standards. Variable load profiles generate specification demand for specialized composite designs.
- Distribution Networks:Low-voltage feeders prioritize porcelain reliability where maintenance access is routine.
- Substations:Equipment integration demands bushings with partial discharge monitoring compatibility.
Transmission lines sit at the top of the volume ranking, with renewable energy gaining share fastest.
End User:
Supply concentration patterns align with customer scale, with integrated manufacturers capturing preference from large procurement committees.
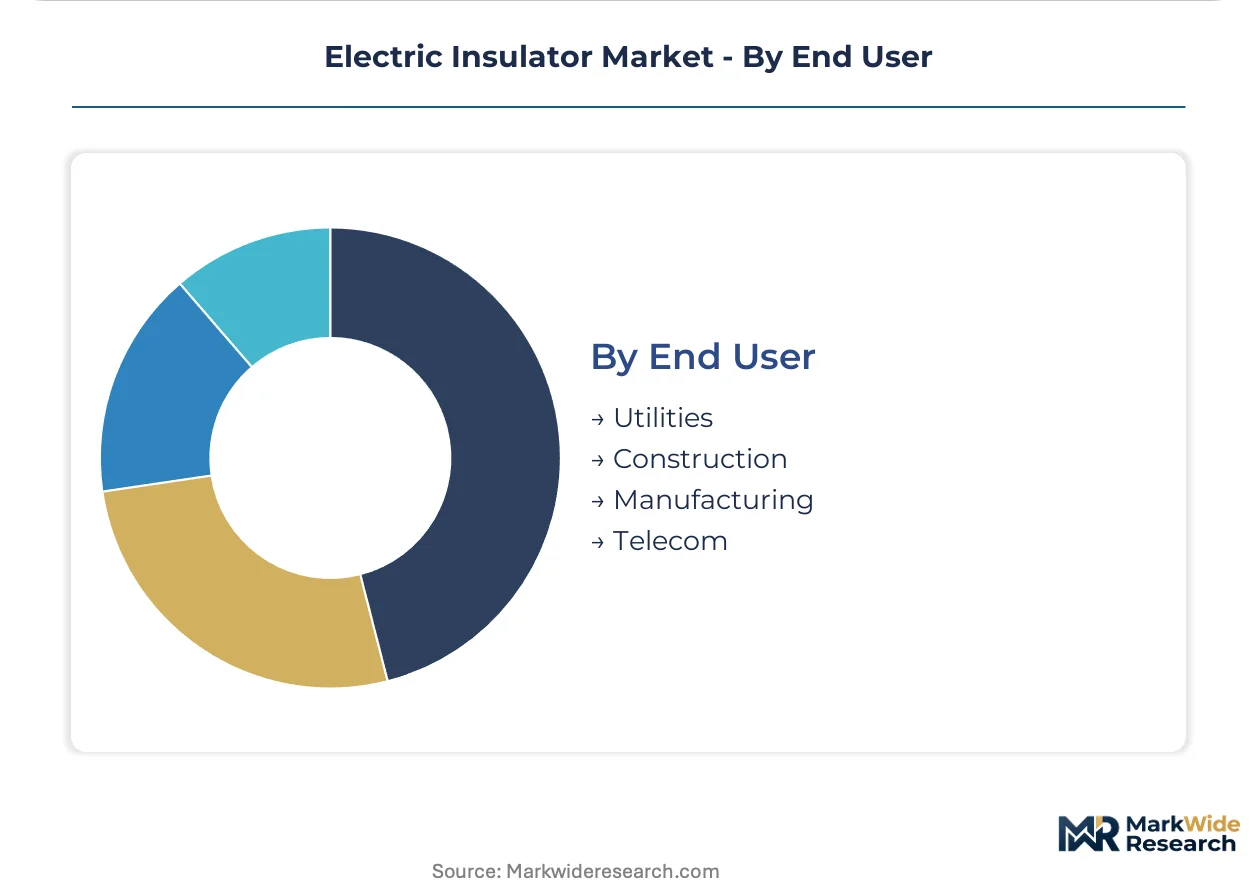
- Utilities:State electricity boards and transmission operators drive volume through tender-based procurement of suspension and tension assemblies. India's PLI schemes for electrical equipment attract capacity expansion for export-competitive production.
- Construction:Infrastructure contractors specify standard distribution-grade insulators for greenfield substation projects.
- Manufacturing:Industrial captive power plants require medium-voltage bushings for transformer integration.
- Telecom:Communication tower grounding systems use specialized low-voltage line post designs.
Utilities sit at the top of the volume ranking, with construction climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's transmission corridor expansion anchors regional demand growth for polymer-composite insulators rated for high-pollution environments. India's CEA mandates are accelerating procurement cycles across state electricity boards. Utility procurement committees in coastal Maharashtra specify silicone rubber formulations for 400 kV lines.
India
State electricity boards in Maharashtra and Gujarat drive suspension insulator procurement for 765 kV corridor upgrades under CEA technical regulations. The PLI scheme for electrical equipment attracts manufacturing capacity expansion toward export-competitive production. Mundra and Hazira industrial clusters host integrated porcelain and polymer composite fabrication facilities serving Middle East and African markets.
China
Ultra-high voltage transmission buildout generates demand for bushings and suspension assemblies rated above 800 kV. MIIT industrial standards govern dielectric performance certification for domestic grid operators. Yangtze River Delta manufacturing bases concentrate glass string and composite insulator production for Belt and Road infrastructure exports.
United States
FERC interconnection queue backlogs are forcing transmission utilities to accelerate line refurbishment with polymer alternatives to legacy glass strings. EPA regional haze regulations indirectly pressure utilities toward reduced maintenance-interval solutions. Texas ERCOT corridor projects and California ISO renewable integration drive specification demand for variable-load insulation systems.
Germany
TenneT corridor upgrades specify integrated insulation-transformer-switchgear packages from full-portfolio OEMs. ECHA REACH restrictions on halogenated flame retardants force polymer housing reformulation toward bio-based silicone compounds. Bavaria and North Rhine-Westphalia transmission operators consolidate supplier relationships around lifecycle telemetry capabilities.
Japan
METI grid resilience directives prioritize earthquake-resistant composite designs for substation integration. JIS standards maintain stringent mechanical load cycling requirements for suspension string certification. Nagoya industrial corridor retains ceramic substrate specialization through captive alumina supply chains.
Electric Insulator Market Vendor Landscape
Global majors compete with regional champions across formulation technology and certification depth. The vendor base stratifies into three tiers: integrated electrical equipment OEMs with full switchgear portfolios, specialized insulator fabricators with captive material supply, and regional champions serving single-country procurement committees. Two dominant competitive moves are reshaping positioning: backward integration into high-purity alumina mining and silicone rubber formulation partnerships, plus portfolio diversification into smart grid sensor-embedded composite designs.
Within the integrated equipment tier, NGK Insulators Ltd and Siemens AG exemplify divergent material strategies. NGK anchors ceramic substrate production through East Asian mining interests. Siemens leverages polymer formulation partnerships for European transmission upgrade positioning. Among regional specialists, Aditya Birla Insulators occupies a position as a domestic champion for Indian state electricity board tenders through multi-plant manufacturing scale.
| Leading Market Players |
|---|
| NGK Insulators Ltd |
| Hitachi Energy |
| ABB Ltd |
| PFISTERER |
| Aditya Birla Insulators |
| Siemens AG |
| Hubbell Incorporated |
| Seves Group |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
High-purity alumina spot indices from East Asian mining corridors cascade through ceramic substrate fabrication into three distinct pricing tiers for porcelain insulator procurement committees.
Pricing Analysis
Input-cost pass-through from silicone rubber formulation and alumina ceramic feedstock compresses margins for mid-tier composite and porcelain suppliers serving Indian state electricity boards and European transmission operators. Three-tier pricing structure across premium IEC 60383-certified, standard ANSI C29-compliant, and economy-grade distribution tiers separates procurement committees by contamination exposure and voltage rating. Pricing pressure stems from REACH-mandated reformulation costs for halogen-free polymer housings. Distribution utilities exhibit highest price sensitivity, while HVDC converter station operators absorb premiums for thermal-cycling-tolerant bushings.
Supply Chain Analysis
Regional distribution centers in Mundra and Hazira industrial clusters anchor hub-and-spoke patterns for Middle East and African export markets. Manufacturing gravity centers on Japan, China, and India for ceramic substrates and polymer composite fabrication. Raw material dependencies span high-purity alumina from East Asian captive mines, silicone rubber from European formulation houses, and fiberglass core rods from Yangtze River Delta suppliers. Single-source vulnerability concentrates in East Asian alumina allocation. Distribution runs through integrated electrical equipment OEMs consolidating insulation-transformer-switchgear packages for TenneT and Mahatransco corridor projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric insulator market functions as a regulatory compounder where CEA grid modernization mandates in India generate sustained procurement velocity across transmission infrastructure expansion cycles.
For Market Incumbents: Anchor market position through backward integration into high-purity alumina supply chains and captive silicone rubber formulation partnerships. NGK Insulators Ltd's East Asian mining interests demonstrate defensive moat construction against input cost volatility. Siemens AG's polymer formulation alliances illustrate channel control leverage for European transmission upgrade positioning. Certification investment in IEC 60383 type-testing protocols creates switching costs for procurement committees evaluating alternative suppliers. For New Entrants and Emerging Players: Launch via PLI-linked manufacturing scale targeting export-competitive production from Mundra and Hazira clusters for Middle East and African markets. Renewable energy integration projects in Gujarat and Maharashtra present the most penetrable specification demand, with solar and wind farms requiring insulation rated for variable load conditions distinct from baseload standards. Smart grid sensor-embedded composite designs offer differentiation for digitally advanced transmission operators consolidating supplier relationships around lifecycle telemetry capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized insulator fabricators possessing captive material supply and certification depth rather than undifferentiated component assemblers. Long-term viability hinges on formulation R&D capabilities for REACH-compliant halogen-free silicone compounds and HVDC bushing thermal cycling specialization. Watch for inflection signals in live-line replacement tooling adoption velocity, which constrains composite insulator deployment even where performance superiority is established.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Mining | NGK Insulators Ltd's captive East Asian supply chains insulate against ceramic substrate feedstock allocation risk. |
| Silicone Rubber Formulation Partnership | Siemens AG leverages European polymer alliances to extend composite insulator positioning in TenneT corridor upgrades. |
| PLI-Linked Manufacturing Scale-Up | Aditya Birla Insulators' multi-plant expansion captures Indian state electricity board tenders and export competitiveness. |
| Smart Grid Sensor Integration | Embedded partial discharge monitoring unifies insulation and diagnostics for digitally advanced transmission operators. |
| HVDC Bushing Specialization | Converter station expansion for submarine cable interconnectors creates premium demand for thermal cycling tolerance. |
Methodological Framework
Multiple input streams — primary interviews with utility procurement managers, transmission planning engineers, and polymer formulation specialists; secondary validation through CEA technical regulations, IEC 60383 certification databases, and FERC interconnection queue filings; plus customs and trade data from India, China, and Germany — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product type, material grade, application voltage tier, and end-user procurement scale dimensions enabled segmentation-level modeling throughout the forecast period. CAGRs were derived from utility capital expenditure trajectories, renewable integration project pipelines, and regulatory mandate implementation schedules specific to CEA grid modernization directives and REACH reformulation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alumina supply disruption scenarios or accelerated REACH restriction expansion. Forecasts reflect documented assumptions regarding PLI scheme continuation and live-line replacement tooling adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market