
 Pipeline Services Market | 2026-2036
Pipeline Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Services Market Outlook
The EU Green Deal and its methane reduction targets for energy infrastructure is recalibrating how operators budget for pipeline integrity across European corridors. Baker Hughes leverages its digital inspection portfolio to capture demand for continuous monitoring systems. Schlumberger Limited sustains its position through integrated subsurface-to-surface technology chains. Michels Corporation anchors its competitive stance with specialized construction capabilities across North American gathering and transmission networks.
Pipeline services encompass the technical assessment, repair, construction, and decommissioning of tubular infrastructure transporting hydrocarbons, water, or chemicals under pressures typically ranging from 200 to 1,440 psi depending on material grade and service class. These services ensure structural integrity, flow assurance, and regulatory compliance across thousands of miles of installed infrastructure. Inspection services command the largest revenue share due to mandatory integrity management programs, while smart pigging technology within that segment attracts the fastest investment as operators replace conventional tool runs with multi-sensor platforms. Construction services retain mature margin pools tied to large-diameter transmission projects, though decommissioning is gaining structural attention as aging networks in mature basins require systematic retirement.
The US PHMSA enforces integrity management rules under 49 CFR Part 195 and 192, compelling operators to prioritize high-consequence area assessments and documented repair timelines. The EPA's methane performance standards and emerging state-level climate mandates in Colorado and New Mexico further tighten operational requirements for leak detection and repair frequency. ISO 13628 and API 1160 standards shape international equipment specifications and inline inspection tool certification. Stakeholders must monitor how regulatory convergence on methane intensity and pipeline safety reshapes procurement criteria for service providers across operating regions.
Market Dynamics
The US PHMSA's integrity management mandates under 49 CFR Part 195 are compressing inspection cycles and forcing operators to retire aging carbon steel infrastructure faster than replacement schedules originally planned.
Growth Catalysts
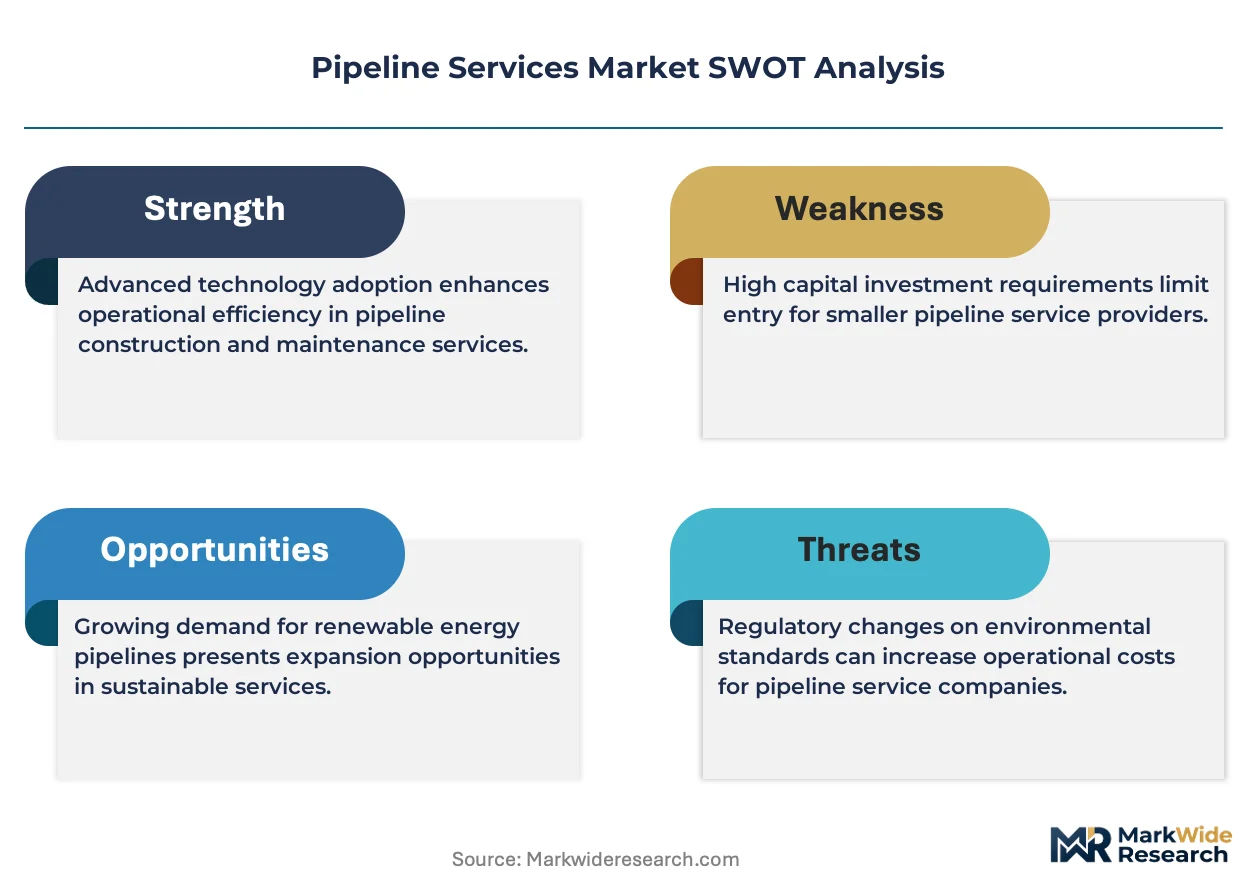
- EU Green Deal methane targets:The framework compels European midstream operators to deploy continuous monitoring systems across high-pressure transmission corridors, expanding recurring service contracts.
- Permian Basin gathering network expansion:Shale producers in West Texas and New Mexico are commissioning new lateral lines to connect pad sites to processing facilities, sustaining construction demand.
- Multi-sensor smart pigging:Magnetic flux leakage combined with ultrasonic testing now delivers crack detection and wall-thickness mapping in single tool runs, reducing outage windows.
Market Restraints
- Specialized steel alloy shortages:API 5L X80 grade pipe and CRA cladding materials face extended lead times from limited electric arc furnace capacity in North America and Europe.
- Skilled welder scarcity:Pipeline construction contractors report 18-24 month backlogs for certified API 1104 welders, constraining project velocity regardless of capital availability.
- Alternative transport modes:Rail and barge operators capture incremental volumes on shorter-haul routes where pipeline permitting delays exceed 36 months.
Strategic Opportunities
- Offshore decommissioning in the Gulf of Mexico:Federal lease expirations and platform retirement obligations create systematic demand for pipeline abandonment and removal services through 2035.
- Hydrogen blending infrastructure:European transmission operators are retrofitting compressor stations and evaluating composite pipe compatibility for hydrogen-natural gas mixtures.
- Drone-based leak detection:Methane-sniffing UAVs paired with satellite verification are emerging as a lower-cost alternative to helicopter patrols for right-of-way surveillance.
Industry Challenges
- Inline inspection tool calibration:Multi-diameter pipelines with tight-radius bends require customized pig configurations that extend pre-run engineering timelines by 8-12 weeks.
- Legacy SCADA integration:Digital twin deployments for predictive maintenance must interface with 1990s-era control systems that lack standardized data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Services Market |
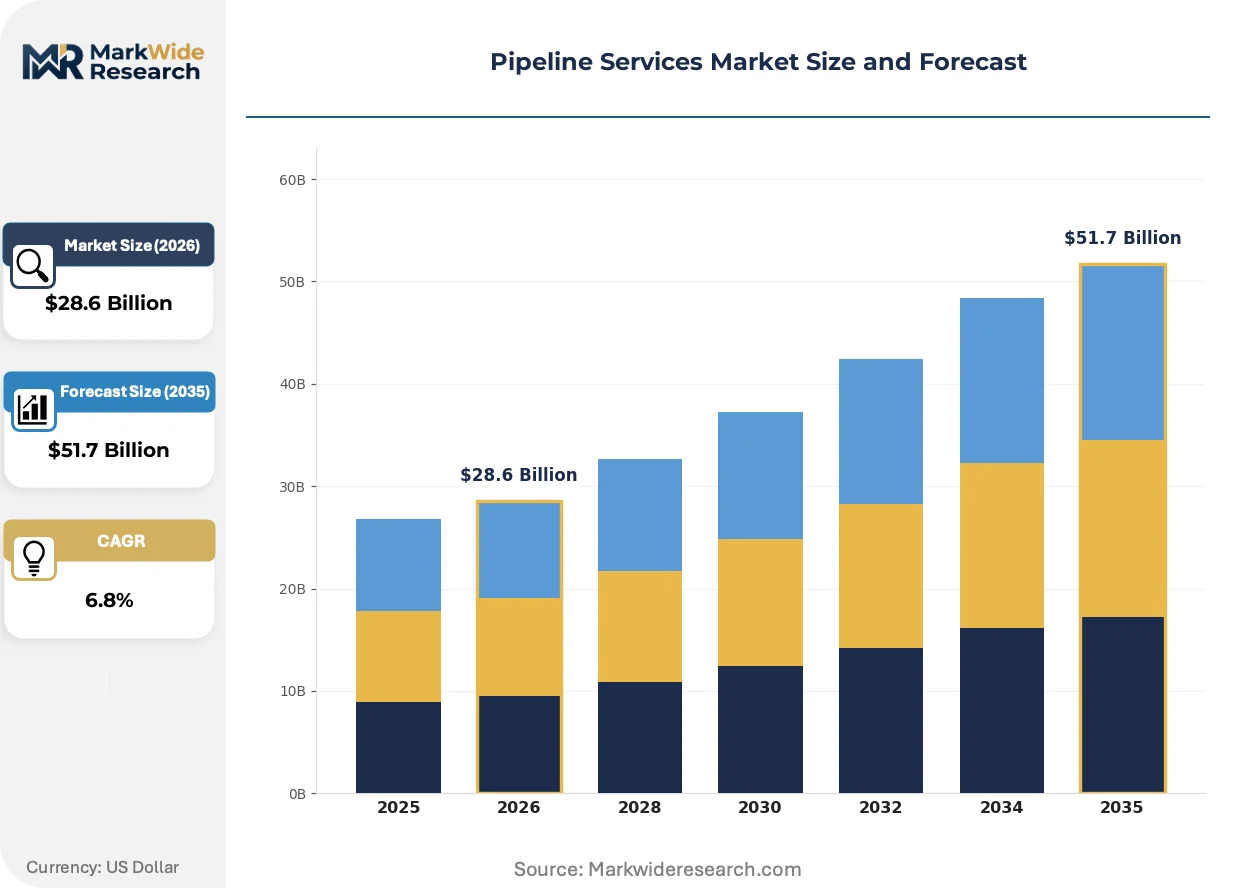
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Construction, Decommissioning Technology: Smart Pigging, Hydrotesting, Non-Destructive Testing, Flow Measurement Application: Crude Oil, Natural Gas, Water, Chemicals End User: Oil & Gas Companies, Utility Providers, Industrial Users, Government Agencies |
| Companies Covered | ROSEN Group, Mastec, Baker Hughes, Kiewit Corporation, Michels Corporation, Schlumberger Limited, T.D. Williamson, Weatherford International, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Services Market Strategic Shifts
Pipeline service providers are reconfiguring around real-time data streams and predictive asset management, shifting from scheduled interventions to condition-based operating models.
Composite repair systems using carbon fiber reinforced polymer wraps are modularizing field rehabilitation workflows. Midstream operators in the Marcellus and Utica shales are adopting these systems for temporary Class 3 repairs, reducing excavation requirements and enabling faster return-to-service timelines than welded sleeves.
The EPA's methane performance standards under the Clean Air Act are mandating quarterly leak surveys and documented repair timelines for gathering and boosting stations. This regulatory pressure is accelerating investment in continuous emissions monitoring hardware, particularly across the Denver-Julesburg and San Juan basins where state-level oversight in Colorado and New Mexico adds supplemental inspection frequency requirements.
Asset owners are unbundling integrity management from bundled construction contracts, creating discrete procurement categories for inspection data analytics and repair execution. North American master limited partnerships now separately contract inline inspection vendors, data interpretation specialists, and direct assessment crews, compressing vendor margins but expanding addressable spend for pure-play service providers.
Pipeline Services Market Segmentation
Pipeline service procurement splits between recurring integrity obligations and discrete capital projects. Operators calibrate vendor selection across technical capability, geographic coverage, and regulatory compliance depth. Understanding segment boundaries clarifies where margins concentrate and where commoditization pressures intensify.
Service Type:
Standardized inspection protocols contrast with highly customized construction scopes across this dimension.
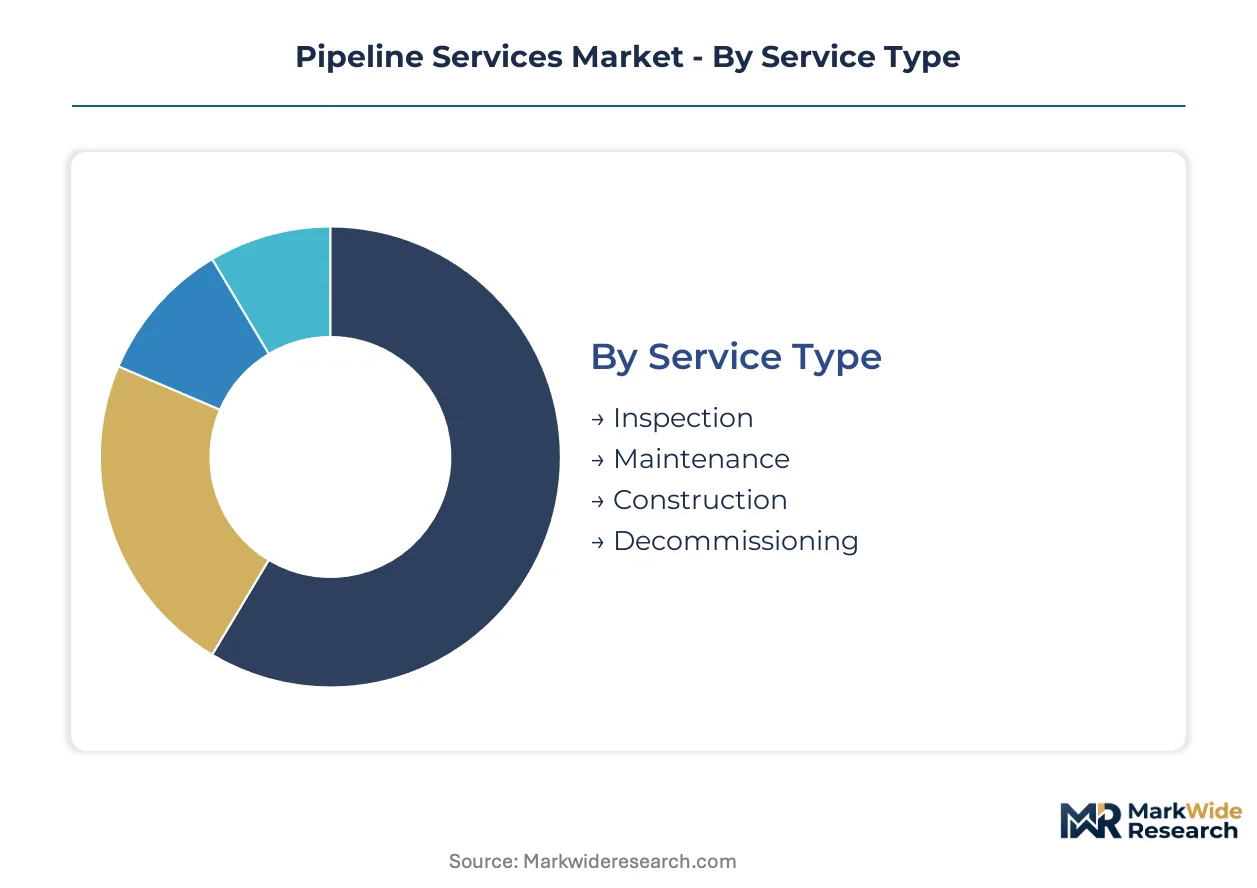
- Inspection:Mandatory integrity assessments under 49 CFR Part 195 drive recurring revenue streams. US PHMSA mandates compress assessment cycles in high-consequence areas spanning the Permian Basin and Gulf Coast export corridors. Multi-sensor smart pigging platforms displace conventional tool runs as operators prioritize crack detection and wall-thickness mapping in single outages.
- Maintenance:Leak repair, valve replacement, and cathodic protection sustain field service deployments. Colorado and New Mexico state-level climate mandates supplement EPA methane performance standards, tightening repair timelines across the Denver-Julesburg basin. Composite repair systems using carbon fiber reinforced polymer wraps reduce excavation requirements for temporary Class 3 rehabilitations.
- Construction:Large-diameter transmission projects retain mature margin pools. API 5L X80 grade pipe shortages and certified API 1104 welder scarcity constrain project velocity regardless of capital availability.
- Decommissioning:Systematic pipeline retirement accelerates as mature basins face federal lease expirations. Gulf of Mexico platform obligations create structural demand for abandonment and removal services.
Most installed capacity flows through Inspection. Expansion is steepest in Decommissioning.
Technology:
Capital intensity varies sharply between hardware-dependent inspection platforms and labor-intensive verification methods.
- Smart Pigging:Magnetic flux leakage combined with ultrasonic testing delivers crack detection and wall-thickness mapping in single tool runs. Multi-diameter pipelines with tight-radius bends require customized pig configurations that extend pre-run engineering timelines. Tight-radius bend customization requirements compress margins on complex geometries.
- Non-Destructive Testing:Radiographic and ultrasonic weld verification underpins construction quality assurance. Field crews deploy portable equipment across gathering network expansion projects in West Texas and New Mexico shale plays.
- Hydrotesting:Pressure validation protocols verify structural integrity post-construction or repair. Water sourcing and disposal logistics dominate cost structures in arid operating environments.
- Flow Measurement:Custody transfer accuracy and leak detection integration drive meter upgrade cycles. Ultrasonic and Coriolis technologies displace mechanical meters on new-build infrastructure.
Smart Pigging commands the highest equipment investment per deployment. Flow Measurement is climbing the fastest as digital integration requirements intensify.
Application:
Fluid characteristics dictate pressure regimes, material specifications, and regulatory oversight stringency.
- Crude Oil:Sour crude corrosivity demands enhanced metallurgy and frequent wall-thickness monitoring. Gathering systems in North American shale basins concentrate replacement cycles for aging carbon steel infrastructure.
- Natural Gas:Methane intensity scrutiny under EPA performance standards and EU Green Deal targets accelerates continuous monitoring adoption. Transmission corridors face the tightest leak detection and repair frequency requirements.
- Water:Lower pressure ratings and reduced corrosion exposure permit thinner-wall specifications. Produced water disposal pipelines in Permian Basin plays sustain construction demand.
- Chemicals:Specialized alloy requirements and batch sequencing complexity elevate engineering margins. Industrial corridors along the US Gulf Coast concentrate project activity.
Natural Gas dominates service contract value. Crude Oil gathering network replacement is expanding most quickly as shale production matures.
End User:
Procurement sophistication diverges between integrated majors with captive engineering capabilities and fragmented industrial accounts.
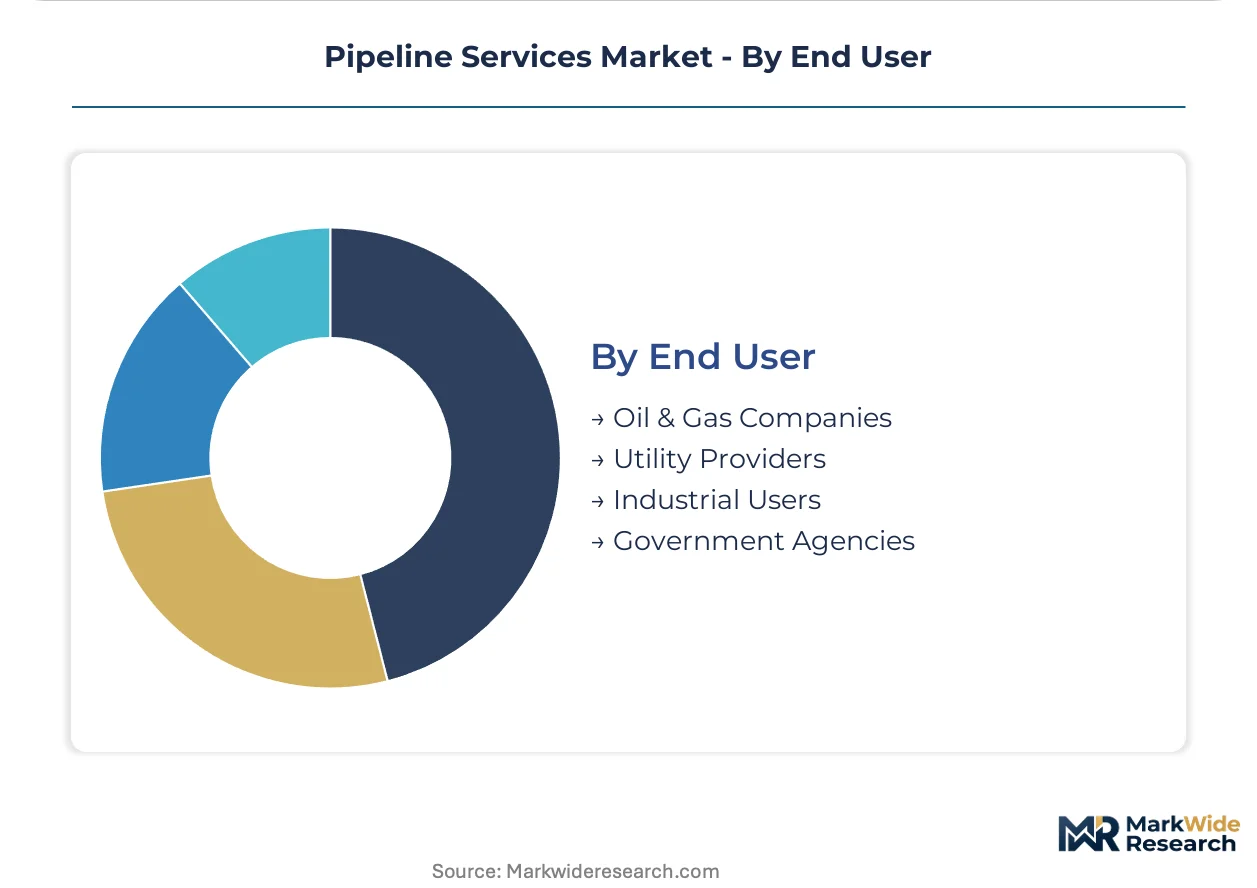
- Oil & Gas Companies:Midstream operators unbundle integrity management from bundled construction contracts, creating discrete procurement categories for inspection data analytics and repair execution. Master limited partnerships separately contract inline inspection vendors, data interpretation specialists, and direct assessment crews.
- Utility Providers:Municipal water and gas distribution systems prioritize regulatory compliance over technology advancement. Aging cast iron replacement programs sustain steady maintenance demand.
- Industrial Users:Petrochemical complexes and refineries operate captive pipeline networks with specialized metallurgy requirements. Turnaround scheduling drives concentrated service procurement.
- Government Agencies:Federal and state transportation authorities oversee interjurisdictional transmission corridors. Permitting timelines exceeding 36 months push volumes toward rail and barge alternatives on shorter-haul routes.
Oil & Gas Companies anchor vendor revenue. Industrial Users are gaining share fastest as petrochemical capacity expands along the US Gulf Coast.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline services originated in the United States during the mid-20th century midstream buildout, with technology diffusion following hydrocarbon production corridors into Canada, Mexico, and later European North Sea developments.
United States
The Permian Basin and Gulf Coast export corridors concentrate the heaviest inspection and construction demand. US PHMSA integrity mandates under 49 CFR Part 195 compress assessment cycles in high-consequence areas. Houston anchors the largest contractor ecosystem, with Midland-Odessa serving as the operational hub for Permian gathering network expansions.
Canada
Alberta's oil sands and British Columbia's LNG export projects sustain large-diameter construction demand. The Canada Energy Regulator enforces pipeline safety standards that align with US protocols but add supplemental environmental assessment requirements. Calgary hosts the headquarters of major inspection technology providers serving North American corridors.
Mexico
Energy reform implementation has opened midstream investment to private operators, expanding pipeline integrity obligations across existing Pemex infrastructure. The country's national hydrocarbons regulator oversees safety compliance for cross-border transmission corridors. Tamaulipas and Veracruz concentrate new-build activity connecting US supply to Mexican demand centers.
Germany
EU Green Deal methane reduction targets are recalibrating integrity budgets for the Central European transmission network. ECHA chemical safety regulations and national implementation of the F-Gas Regulation shape material specifications for pipeline rehabilitation. The Ruhr industrial corridor and Bavarian chemical clusters drive specialized service demand for hydrogen blending infrastructure preparation.
Saudi Arabia
Aramco's master gas system expansion and offshore field developments sustain construction and inspection demand across the Eastern Province. The country's national petroleum regulator enforces pipeline safety standards aligned with API specifications. Jubail Industrial City and the Ghawar field periphery concentrate maintenance and integrity management activity.
Pipeline Services Market Competitive Environment
Capital-heavy equipment owners compete with asset-light service integrators across the pipeline services value chain. The market structures around three tiers: integrated oilfield technology conglomerates with captive manufacturing, specialized inspection technology vendors with proprietary sensor platforms, and regional construction contractors with welder certification depth. Consolidation pressures intensify as operators unbundle integrity management into discrete procurement categories. Strategic moves concentrate on M&A for technology access and geographic expansion into Permian and Gulf Coast corridors.
Among North American construction specialists, Michels Corporation and Kiewit Corporation exemplify the contractor archetype with specialized capabilities across gathering and transmission networks. Within the integrated technology tier, Baker Hughes and Schlumberger Limited anchor positions through subsurface-to-surface technology chains and digital inspection portfolios. ROSEN Group and T.D. Williamson represent the pure-play inspection technology segment with focus on inline assessment platforms.
| Leading Market Players |
|---|
| ROSEN Group |
| Mastec |
| Baker Hughes |
| Kiewit Corporation |
| Michels Corporation |
| Schlumberger Limited |
| T.D. Williamson |
| Weatherford International |
| Halliburton Company |
| Others |
Value Chain & Pricing Dynamics
Midstream master limited partnerships concentrate procurement power across North American shale basins, forcing service providers toward performance-based contracts where pricing ties to inspection cycle completion and repair turnaround metrics rather than hourly rates.
Pricing Analysis
Project-based contracting with outcome-linked fee structures dominates the pipeline services market. Price differentiation rests on API certification tier and smart pigging technology sophistication, with multi-sensor platforms commanding premiums over conventional magnetic flux leakage tools. Cost compression in construction services is intensifying because certified API 1104 welder scarcity extends project timelines regardless of capital availability. Small regional contractors exhibit highest price sensitivity due to thin margin buffers on fixed-bid transmission work, while integrated technology conglomerates with captive manufacturing show lowest sensitivity given bundled solution pricing power.
Supply Chain Analysis
API 5L X80 grade pipe certification and CRA cladding qualification requirements gate supplier entry, concentrating certified mill capacity in the United States, Germany, and Japan. Raw material dependencies center on high-strength steel plate, nickel-based alloy feedstock, and specialized sensor components for inline inspection platforms. Single-source vulnerability runs through electric arc furnace capacity constraints in North America and Europe. Distribution feeds from mill-direct relationships for large-diameter transmission projects, while maintenance and repair materials flow through regional distributor networks serving field service contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipeline services function as a geographic-arbitrage play where European operators facing EU Green Deal methane compliance costs subsidize technology development that North American shale basins later adopt at lower marginal cost.
For Market Incumbents: Acquire smart pigging sensor technology platforms to offset margin compression from unbundled integrity procurement. Baker Hughes and Schlumberger Limited already anchor positions through subsurface-to-surface chains; regional contractors must secure API 1160 certification depth to defend against integrated technology conglomerates capturing inspection data analytics contracts. Backward integration into specialized alloy distribution mitigates X80 grade pipe shortage risks. For New Entrants and Emerging Players: Launch via drone-based methane detection services targeting the Denver-Julesburg and San Juan basins where Colorado and New Mexico state mandates supplement EPA quarterly survey requirements. Offshore decommissioning in the Gulf of Mexico represents the most penetrable white-space segment given federal lease expiration timelines. Partner with satellite verification providers to offer lower-cost alternatives to helicopter patrols for right-of-way surveillance. For Investors and Strategic Acquirers: Oilfield technology conglomerates are the most active acquirers in this space, seeking pure-play inspection technology vendors with proprietary multi-sensor platforms. Long-term viability hinges on hydrogen blending infrastructure retrofit capabilities as European transmission operators evaluate composite pipe compatibility. Watch for PHMSA rulemaking on methane intensity standards as the inflection indicator for continuous monitoring hardware investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Pigging Technology Acquisition | Multi-sensor platforms displace conventional tools in Permian Basin integrity programs. |
| Hydrogen Blending Infrastructure Certification | Ruhr corridor operators in Germany evaluate composite pipe compatibility for gas mixtures. |
| Offshore Decommissioning Capability Buildout | Gulf of Mexico federal lease expirations create systematic demand through 2035. |
| Continuous Emissions Monitoring Partnership | EPA methane standards in Denver-Julesburg basin accelerate hardware deployment. |
| API 1104 Welder Training Program | 18-24 month certification backlogs constrain project velocity regardless of capital availability. |
Study Parameters
Multiple input streams — primary interviews with midstream integrity managers, PHMSA compliance officers, and smart pigging technology engineers; secondary validation through DOT pipeline safety databases, API standards documentation, and FERC infrastructure filings — were reconciled through bottom-up service contract aggregation and top-down operator capex allocation analysis.
Data-stream reconciliation across the projection horizon applied segment-specific modeling for inspection technology, construction services, maintenance execution, and decommissioning removal. Modeled dimensions span service type, application fluid, pressure class, and regional regulatory cluster. CAGRs derived from operator disclosed integrity spend patterns and PHMSA-mandated assessment cycle frequencies. Forecast inputs incorporate steel alloy pricing volatility and certified welder labor pool constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt PHMSA rulemaking acceleration or electric arc furnace capacity disruptions. A model refresh is warranted upon material change in methane performance standard enforcement intensity or hydrogen blending infrastructure mandate timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market