
 Water Storage System Market | 2026-2036
Water Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Water Storage System Market Intelligence
India's accelerating investment in municipal water infrastructure is reshaping competitive dynamics across the water storage system value chain. CST Industries Inc. leverages its bolted steel tank expertise to dominate North American agricultural and industrial contracts. McDermott International Inc. anchors large-scale energy sector projects through integrated engineering and fabrication capabilities. AG Growth International extends its grain handling heritage into liquid storage through specialized tank and silo product lines.
Water storage systems comprise engineered vessels and reservoirs designed to capture, retain, and distribute potable, process, or stormwater across commercial, industrial, and municipal applications. Steel bolted tanks typically utilize factory-coated carbon steel panels with gasketed joints to achieve capacities exceeding ten million gallons while resisting corrosion in aggressive environments. Fiberglass tank systems command premium positioning in chemical processing and wastewater segments due to superior corrosion resistance and extended service life. Concrete underground reservoirs retain dominant share in municipal drinking water applications where structural longevity and thermal stability outweigh initial capital costs. Plastic polyethylene tanks compete aggressively in residential and light commercial rainwater harvesting where ease of transport and field installation drive procurement decisions.
The EPA enforces Safe Drinking Water Act standards that dictate tank material certifications and coating specifications for potable water contact surfaces. India's Central Public Health and Environmental Engineering Organisation issues guidelines under the Ministry of Housing and Urban Affairs that mandate storage capacity ratios for urban water supply schemes. China's Ministry of Ecology and Environment enforces dual carbon goals that restrict energy-intensive concrete production while promoting recycled steel and composite alternatives. Stakeholders must monitor evolving material compliance thresholds as regulators in multiple jurisdictions tighten embodied carbon accounting and end-of-life recycling requirements for large-format storage assets.
Market Dynamics
Material compliance thresholds are tightening across multiple jurisdictions as regulators embed embodied carbon accounting and end-of-life recycling requirements into storage asset specifications, forcing manufacturers to requalify product lines.
Growth Catalysts
- EPA Lead and Copper Rule Revision:The updated rule accelerates tank material upgrades nationwide across municipal utilities, driving replacement cycles for aging potable water infrastructure.
- China's dual carbon goals:MEE restrictions on energy-intensive concrete production redirect procurement toward recycled steel and composite alternatives in industrial corridor cities.
- Underground reservoir mandates:India's Central Public Health and Environmental Engineering Organisation storage capacity ratios compel urban water supply scheme expansions.
Market Restraints
- Concrete production constraints:Cement input cost volatility and carbon intensity penalties compress margins for municipal drinking water reservoir contractors.
- Specialized fabrication concentration:Large-diameter steel panel coating capacity clusters in select manufacturing geographies, creating supply bottlenecks for bolted tank orders.
- Polyethylene substitution ceiling:Material temperature limitations and UV degradation restrict residential rainwater harvesting systems to below-ground installations.
Strategic Opportunities
- Industrial water recycling quotas:State-directed tightening in China's manufacturing hubs creates demand for closed-loop process water storage systems.
- Smart monitoring convergence:IoT sensor integration with composite tank systems enables predictive maintenance contracts in chemical processing facilities.
- Direct-to-municipal channel expansion:Bypassing traditional distributor networks lets specialized fabricators capture specification authority in Indian urban water security projects.
Industry Challenges
- Coating certification timelines:NSF/ANSI 61 potable water contact surface approvals require 18-24 month validation cycles, delaying product launches.
- Legacy system integration:Retrofitting bolted steel tanks into existing SCADA-controlled distribution networks demands specialized controls engineering.
- Weld inspection skill scarcity:Qualified ultrasonic testing technicians for field-erected storage vessels command premium wages, constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Storage System Market |
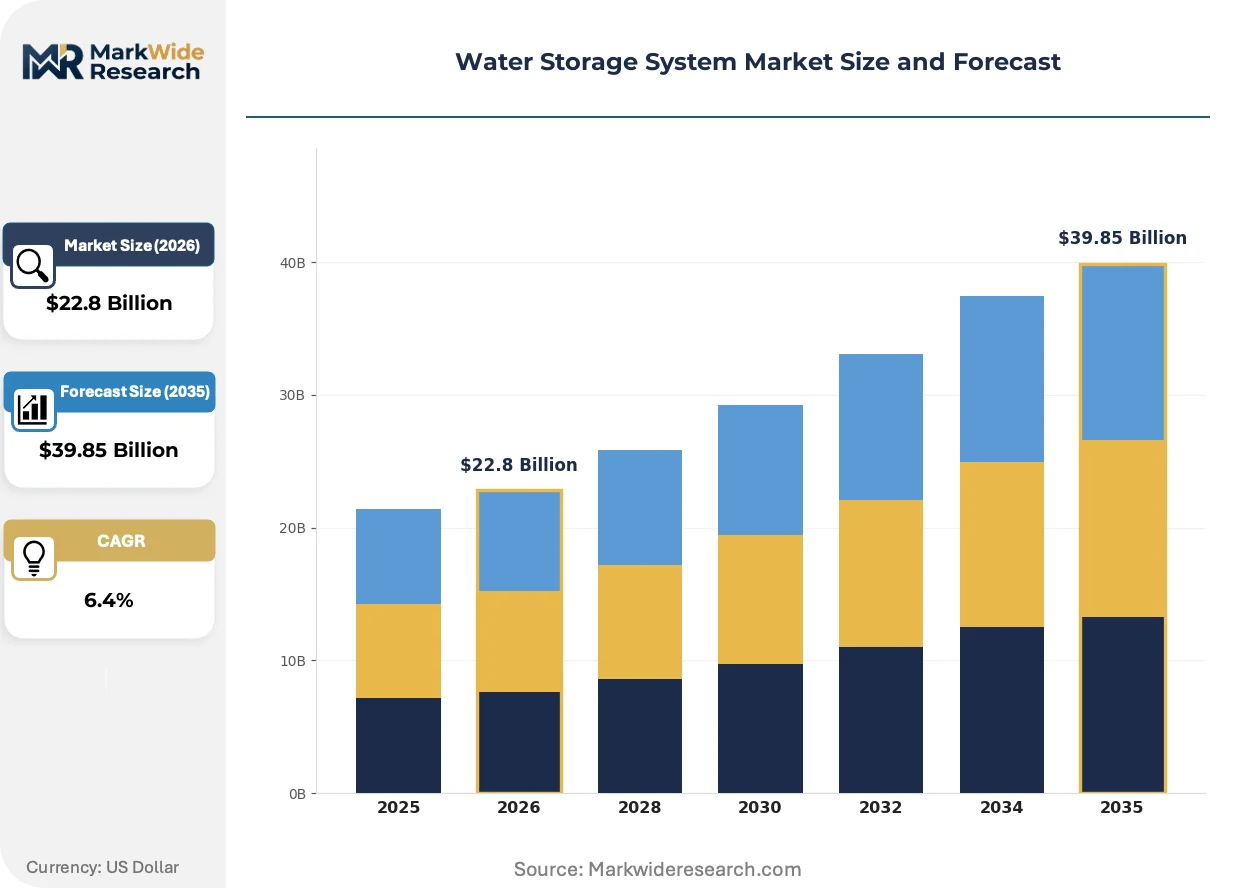
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tank Systems, Bladder Tanks, Underground Reservoirs, Elevated Tanks Material: Steel, Plastic, Fiberglass, Concrete Application: Agricultural, Residential, Industrial, Commercial Distribution Channel: Direct Sales, Retail, Online Marketplaces, Wholesalers |
| Companies Covered | CST Industries Inc., McDermott International Inc., AG Growth International, Synalloy Corporation, DN Tanks, Caldwell Tanks, Containment Solutions Inc., ZCL Composites Inc., Balmoral Tanks Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Storage System Market Strategic Shifts & Innovations
Digital specification tools and modular fabrication methods are compressing project timelines while material science advances enable thinner-walled, higher-capacity vessels. These shifts favor suppliers with integrated engineering capabilities over pure manufacturing plays.
Glass-reinforced polymer lining systems for steel bolted tanks deliver superior corrosion resistance in aggressive wastewater environments. Municipal utilities in coastal India and chemical processors in Germany's Rhine-Ruhr corridor specify these hybrid constructions for 40-year service life requirements. The technology is hybridizing traditional steel tank economics with composite performance benchmarks.
REACH restrictions on hexavalent chromium coatings force European fabricators to accelerate zinc-aluminum-magnesium alloy adoption for potable water contact surfaces. German KBA-equivalent material certification bodies have shortened approval windows for these alternatives. Steel tank manufacturers serving EU municipal markets must reformulate coating specifications or exit potable applications.
Buyers increasingly unbundle after-sales inspection and maintenance from initial capital contracts, creating standalone service revenue pools. Indian municipal corporations now tender tank cleaning and recertification separately from construction awards. This pattern concentrates recurring revenue with firms possessing localized technician networks rather than distant original equipment manufacturers.
Water Storage System Market Segmentation
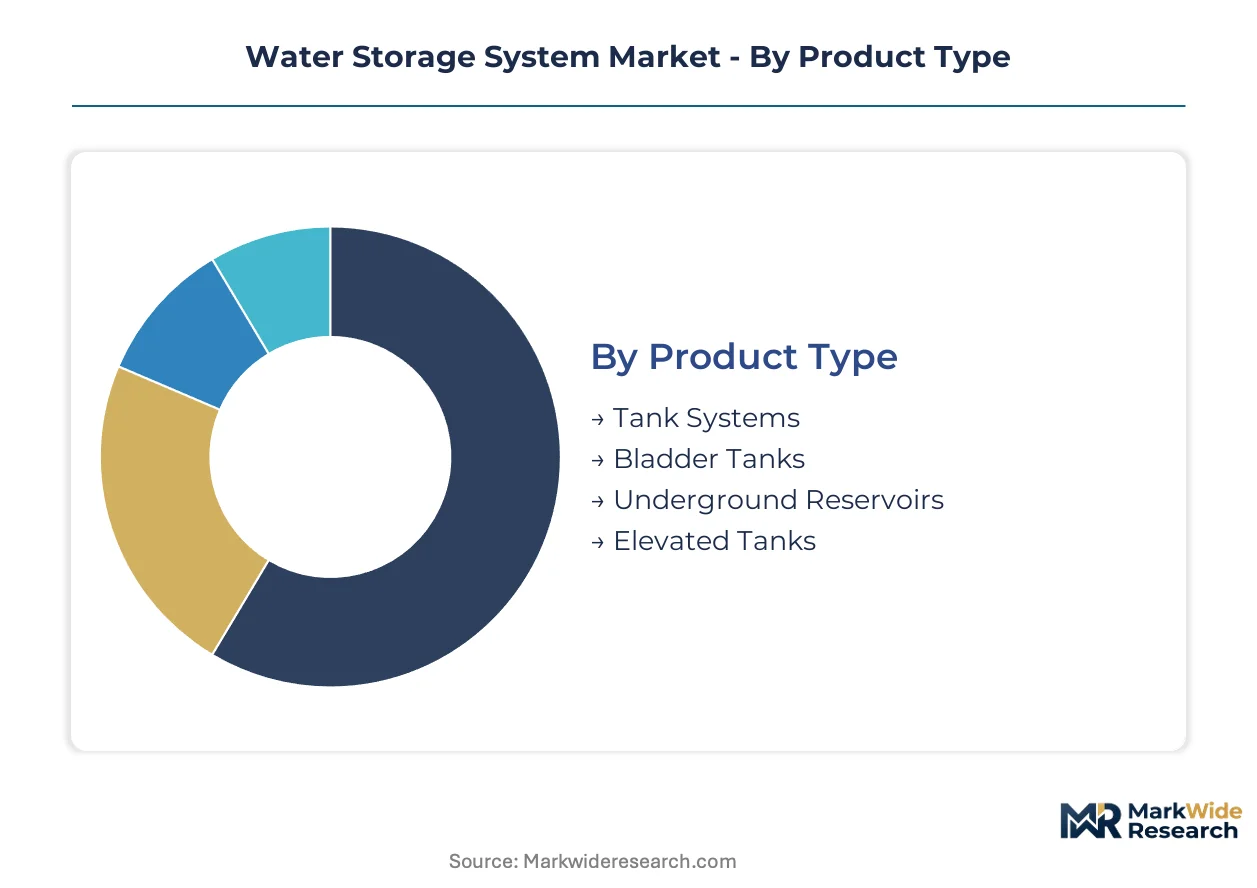
Water storage system procurement patterns diverge sharply across product configurations, material specifications, and end-use requirements. Understanding these dimensional splits reveals where specification authority concentrates and which technical attributes command premium positioning.
Product Type:
Cost tier separation in water storage systems correlates directly with installation complexity and permanence of the asset.
- Tank Systems:Factory-fabricated vessels in bolted steel or welded configurations dominate commercial and industrial procurement. Agricultural irrigation districts in India's Maharashtra state specify these for rapid deployment under Jal Jeevan Mission timelines.
- Underground Reservoirs:Reinforced concrete structures with waterproof membranes anchor municipal drinking water security investments. Urban utilities across Germany's Ruhr region deploy these for thermal stability and seismic resilience in dense settlement patterns.
- Bladder Tanks:Flexible membrane systems in reinforced polymer fabrics serve temporary military and emergency relief applications.
- Elevated Tanks:Steel or composite standpipe configurations maintain distribution pressure in flat terrain without pumping infrastructure.
Underground reservoirs hold installed capacity. Tank systems are rotating up the share rankings.
Material:
Application severity dictates material selection, with corrosion exposure and potable water contact requirements driving specification divergence.
- Steel:Factory-coated carbon steel panels with gasketed joints achieve capacities exceeding ten million gallons. China's industrial corridor cities specify recycled steel alternatives under MEE dual carbon enforcement.
- Concrete:Reinforced cast-in-place or precast structures deliver structural longevity exceeding fifty years. Municipal utilities in coastal India favor these for thermal mass and fire resistance despite embodied carbon penalties.
- Fiberglass:Glass-reinforced polymer composites command premium positioning in chemical processing and aggressive wastewater environments.
- Plastic:Rotationally molded polyethylene competes in residential rainwater harvesting where transport weight and field installation simplicity drive decisions.
Concrete dominates municipal installed base. Fiberglass is climbing the fastest among industrial replacement cycles.
Application:
Customer type segmentation reveals divergent procurement authority structures and specification complexity thresholds.
- Industrial:Process water, cooling, and fire suppression systems demand engineered vessels with corrosion-resistant linings. Chemical processors along China's Yangtze River Delta specify closed-loop recycling infrastructure under tightening state water quotas.
- Municipal:Drinking water security and wastewater containment drive large-diameter steel and concrete investments. India's Central Public Health and Environmental Engineering Organisation mandates storage capacity ratios that compel urban scheme expansions.
- Agricultural:Irrigation storage and livestock watering utilize lower-specification bolted steel and polyethylene configurations.
- Residential:Rainwater harvesting and private well storage concentrate demand in below-ground plastic tank formats.
Municipal holds legacy infrastructure lock-in. Industrial is gaining share fastest through recycling mandate compliance.
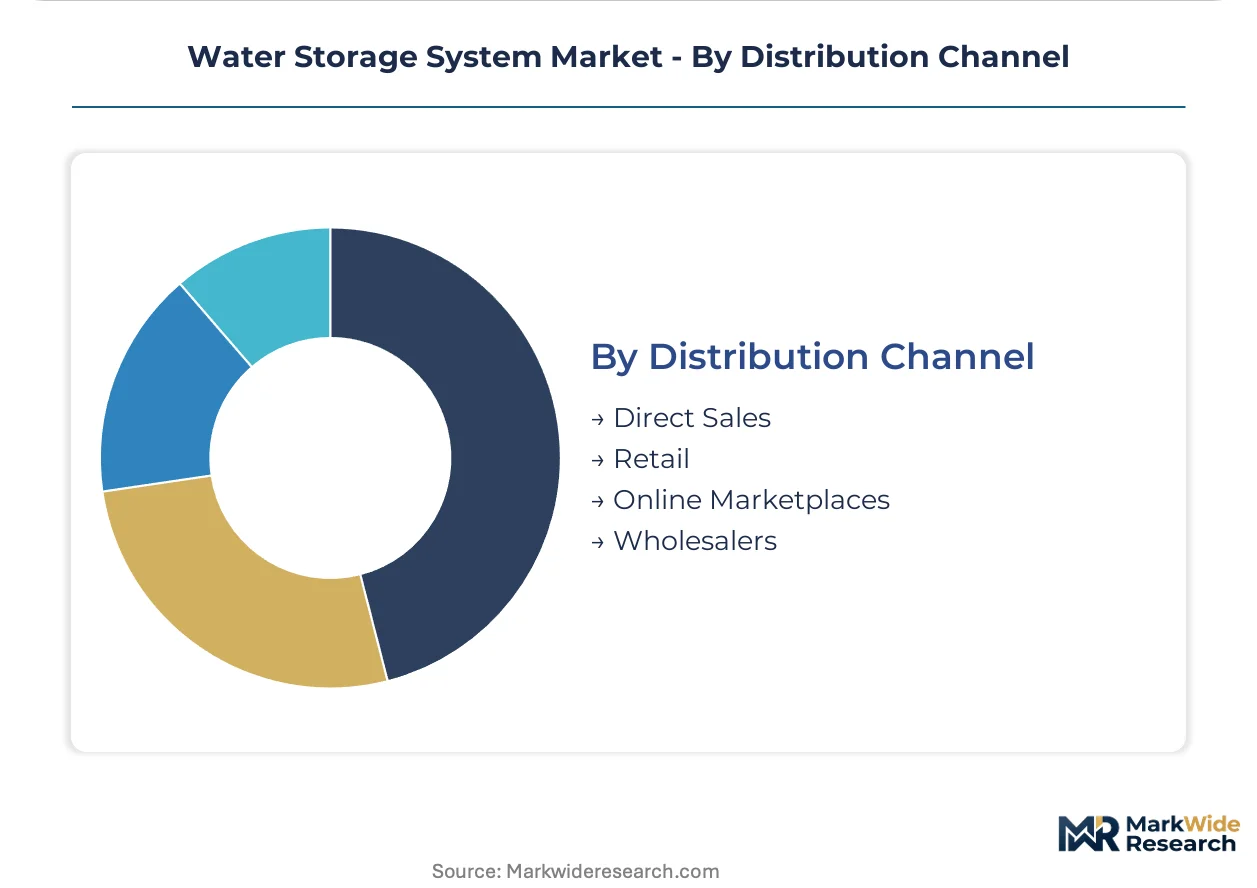
Distribution Channel:
Supply concentration patterns vary dramatically by transaction scale and specification involvement requirements.
- Direct Sales:Large-scale municipal and industrial projects route through manufacturer specification teams. German KBA-equivalent certification requirements for potable water contact surfaces favor direct technical engagement.
- Wholesalers:Regional distributors aggregate demand from agricultural contractors and commercial developers. Inventory pooling reduces lead times for standardized bolted steel configurations.
- Retail:Big-box and agricultural supply outlets serve residential and small-scale agricultural replacement demand.
- Online Marketplaces:E-commerce platforms capture price-sensitive residential rainwater harvesting specifications with transparent comparison tools.
Direct sales commands specification authority. Online marketplaces are expanding most quickly in residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water storage system deployment patterns diverge sharply by geography. India's municipal utilities prioritize underground concrete reservoirs for thermal stability. China's industrial corridor cities favor recycled steel bolted tanks under carbon quotas. Germany's chemical processors specify glass-reinforced polymer linings for aggressive wastewater environments.
United States
Municipal utilities accelerate tank material upgrades under the EPA's Lead and Copper Rule Revision. The Safe Drinking Water Act enforces NSF/ANSI 61 coating certifications for potable water contact surfaces. Texas and California water districts drive replacement cycles for aging steel and concrete infrastructure.
China
Industrial corridor cities expand closed-loop process water storage under tightening state recycling quotas. The Ministry of Ecology and Environment enforces dual carbon goals that restrict energy-intensive concrete production. Yangtze River Delta chemical processors specify recycled steel alternatives for new capacity.
India
Urban water security mandates compel underground reservoir installations across metropolitan utilities. The Central Public Health and Environmental Engineering Organisation mandates storage capacity ratios for municipal supply schemes. Maharashtra and Gujarat lead deployment under Jal Jeevan Mission timelines.
Germany
Chemical processors in the Rhine-Ruhr corridor specify hybrid glass-reinforced polymer lining systems for 40-year service life requirements. REACH restrictions on hexavalent chromium coatings accelerate zinc-aluminum-magnesium alloy adoption. KBA-equivalent certification bodies shorten approval windows for alternative coating specifications.
Water Storage System Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. Specialized fabricators with integrated engineering teams capture specification authority in large municipal and industrial projects. Volume-driven manufacturers compete on lead time and standardized configurations for agricultural and residential segments. Strategic moves center on coating technology licensing partnerships and direct-to-municipal channel bypass of traditional distributors.
Among North American fabricators, CST Industries Inc. and McDermott International Inc. occupy positions on the integrated engineering vector. AG Growth International represents the diversification archetype, extending heritage capabilities into adjacent liquid storage applications. These three exemplify how technical specification authority and geographic footprint combine to secure recurring municipal and industrial contracts.
| Leading Market Players |
|---|
| CST Industries Inc. |
| McDermott International Inc. |
| AG Growth International |
| Synalloy Corporation |
| DN Tanks |
| Caldwell Tanks |
| Containment Solutions Inc. |
| ZCL Composites Inc. |
| Balmoral Tanks Limited |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's steel panel coating sector is compressing margins for bolted tank fabricators while simultaneously accelerating procurement shifts toward recycled steel alternatives under MEE dual carbon enforcement. This utilization imbalance forces suppliers to absorb coating certification costs while municipal buyers in India and Germany exploit competitive tension to extend payment terms.
Pricing Analysis
Long-term offtake contracts dominate municipal and industrial procurement, insulating specialized fabricators from spot volatility in steel and cement inputs. Price differentiation rests on NSF/ANSI 61 certification tier and after-sales service bundling, with certified potable water contact surfaces commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from concrete production carbon penalties squeezing reservoir contractors. Agricultural buyers exhibit highest price sensitivity, while municipal utilities prioritize lifecycle cost over upfront capital.
Supply Chain Analysis
Upstream feedstock concentration in China, India, and Germany anchors global tank fabrication capacity, with specialty steel panel coating clustered in the Yangtze River Delta and Ruhr industrial corridor. Manufacturing draws from carbon steel coils, glass-reinforced polymer resins, and Portland cement clinker. Single-source vulnerability runs through German KBA-equivalent certification bodies for alternative coating approvals. Distribution runs through direct specification teams for large projects and regional wholesalers for standardized agricultural configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart monitoring convergence is transforming water storage from passive infrastructure into connected service platforms, with IoT-enabled predictive maintenance contracts redefining vendor-customer relationships across municipal and industrial segments.
For Market Incumbents: Harden specification authority by deepening captive coating certification capabilities to circumvent 18-24 month NSF/ANSI 61 validation bottlenecks. Acquire localized technician networks in Indian metropolitan utilities to capture recurring tank cleaning and recertification revenue pools now unbundled from construction awards. Defend against polyethylene substitution in residential segments by emphasizing thermal performance and structural longevity.
For New Entrants and Emerging Players: Establish a beachhead in China's industrial corridor cities by offering recycled steel bolted tanks purpose-built for state-directed water recycling quotas. Target Maharashtra and Gujarat municipal markets under Jal Jeevan Mission timelines with rapid-deployment factory-fabricated configurations. Pursue direct-to-municipal channel strategies that bypass traditional distributor networks to capture specification authority early in project development cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fabricators with integrated IoT-enabled predictive maintenance platforms and localized service technician networks. Long-term viability over the next decade favors suppliers with glass-reinforced polymer lining expertise serving chemical processing and aggressive wastewater applications. Monitor REACH-compliant coating adoption curves as signal for European market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Licensing Partnership | Accelerates zinc-aluminum-magnesium alloy adoption under REACH hexavalent chromium restrictions in EU municipal markets. |
| Direct-to-Municipal Channel Expansion | Bypasses distributor networks to capture specification authority in Indian urban water security projects. |
| Smart Monitoring Platform Integration | Enables predictive maintenance contracts with chemical processors in Germany's Rhine-Ruhr corridor. |
| Recycled Steel Supply Agreement | Secures MEE-compliant feedstock for industrial corridor city contracts under dual carbon enforcement. |
| Localized Service Network Acquisition | Captures recurring tank cleaning revenue from Indian municipal corporations unbundling maintenance from construction. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across municipal utilities, chemical processors, agricultural irrigation districts, and tank fabrication facilities. Primary interviews with EPA compliance officers, India's Central Public Health and Environmental Engineering Organisation technical staff, MEE regional inspectors, and German KBA-equivalent certification body representatives were cross-validated against secondary sources including EPA Safe Drinking Water Act filings, MEE dual carbon policy documents, REACH restriction updates, and municipal procurement tender databases. Bottom-up project pipeline analysis and top-down macroeconomic calibration were triangulated to ensure consistency.
Calibration against historical deployment patterns and regulatory milestone timelines anchored projections across the analysis window. Segmentation dimensions modeled include product configuration, material specification, application severity, and distribution channel structure. CAGRs were derived from regression analysis of installed capacity trends against policy enforcement intensity. Forecast inputs incorporated MEE concrete production restriction timelines and NSF/ANSI 61 certification queue lengths.
Sensitivities concentrate around coating certification approval delays, cement input cost volatility, and municipal budget cycle disruptions. Forecasts reflect assumptions regarding regulatory enforcement continuity and recycled steel supply scaling. Quarterly review of MEE policy bulletins, EPA infrastructure grant disbursements, and Indian Jal Jeevan Mission milestone achievements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Middle East Pipeline Maintenance Market