
 Israel Solar Energy Market | 2026-2036
Israel Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Solar Energy Market Foresight
Utility-scale developers is reorganizing procurement priorities, shifting capacity awards toward agrivoltaic and storage-hybrid configurations. Doral Energy leverages its project development pipeline to secure land agreements in the Negev Desert. SolarEdge Technologies anchors Israel's inverter and power optimizer segment through sustained R&D investment in module-level electronics. Enlight Renewable Energy competes across wind-solar hybrid development, extending its domestic construction capabilities into neighboring markets.
Israel solar energy encompasses photovoltaic systems, concentrated solar power installations, building-integrated photovoltaics, and solar thermal collectors that convert electromagnetic radiation into electrical or thermal output for grid supply, self-consumption, or industrial process heat. Crystalline silicon modules dominate utility-scale deployments, with bifacial designs gaining traction for enhanced rear-side energy yield in high-albedo desert conditions. Photovoltaic technology leads installed capacity, while concentrated solar power occupies a niche role in dispatchable renewable generation through molten-salt thermal storage integration. Utility-scale application commands the largest project pipeline, though residential segment growth accelerates as net metering reforms improve homeowner payback periods.
The Electricity Authority and the Ministry of Energy regulate grid interconnection, tariff structures, and renewable energy certificate mechanisms that determine project economics and market access timelines. BIS-equivalent standards and the Israeli Standards Institute shape module certification requirements, influencing supplier qualification and procurement specifications for domestic developers. Stakeholders must monitor storage mandate expansions and land-use policy shifts that will determine site availability and project returns in the southern districts.
Market Dynamics
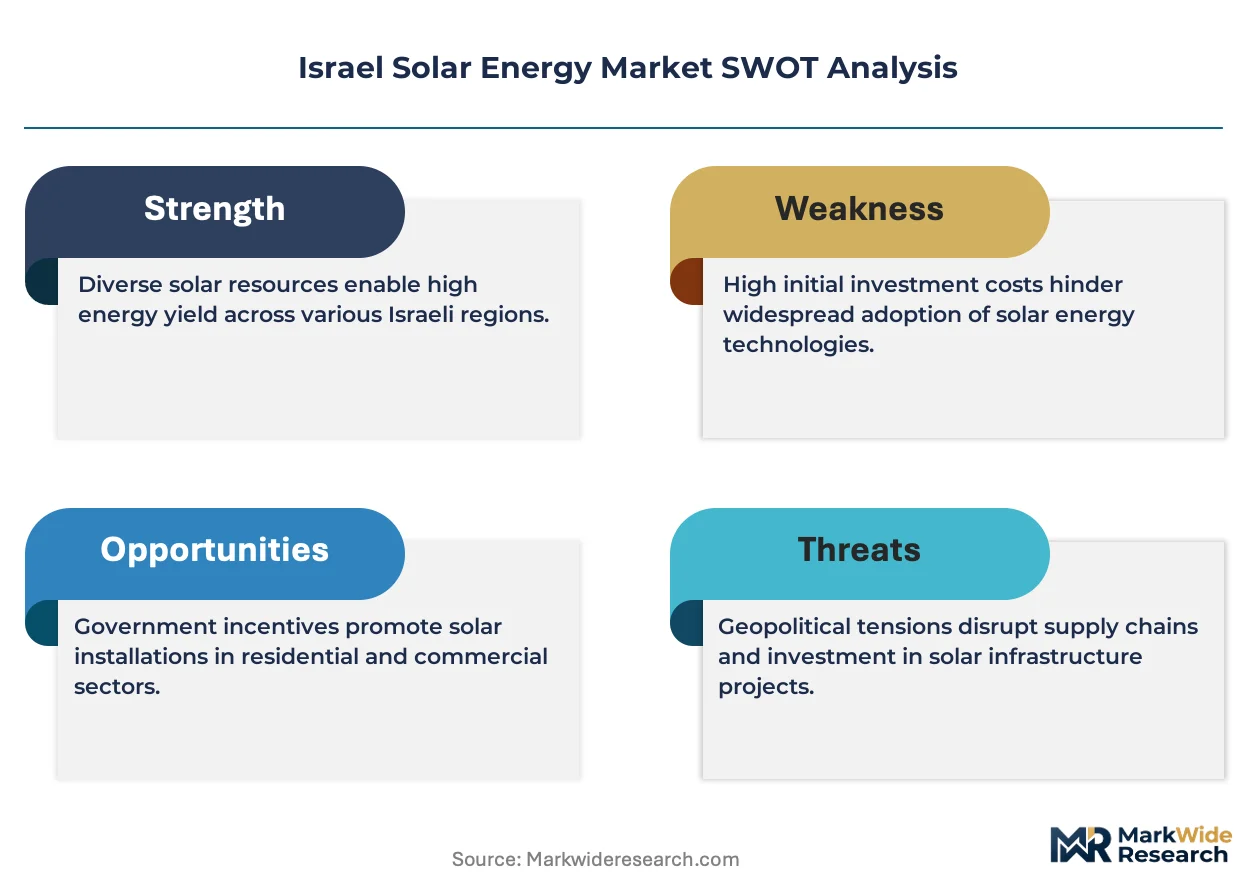
The Israel Electricity Authority's revised grid interconnection standards are compressing project timelines while bifacial module procurement reorganizes developer capital allocation across the Negev Desert pipeline.
Growth Catalysts
- Agrivoltaic Land-Use Framework:Dual-use solar installations on agricultural plots unlock site availability constraints that previously bottlenecked utility-scale deployment in central districts.
- Storage Mandate Expansion:Co-location requirements for battery systems improve grid stability metrics and extend revenue capture into evening peak pricing windows.
- Net Metering Reform:Revised tariff structures shorten residential payback periods and accelerate distributed generation adoption in suburban municipalities.
Market Restraints
- Polysilicon Input Volatility:Crystalline silicon module costs fluctuate with upstream metallurgical-grade silicon supply concentration in East Asian refining corridors.
- Land-Use Competition:Military zone buffers and nature reserve boundaries restrict developable acreage in high-irradiance southern districts.
- Grid Absorption Ceiling:Distribution network capacity limits in rural transmission nodes delay commercial operation dates for completed projects.
Strategic Opportunities
- Eilat-Aqaba Cross-Border Corridor:Regional interconnection infrastructure could unlock export capacity for surplus generation from southern installations.
- Industrial Process Heat Integration:Solar thermal collectors displace natural gas consumption in desalination and food processing facilities.
- Building-Integrated Photovoltaic Mandates:Revised construction codes in Tel Aviv and Haifa metropolitan areas create embedded demand for facade-integrated systems.
Industry Challenges
- Electrical Engineer Shortage:Specialized grid integration expertise for inverter configuration and protection relay programming extends commissioning timelines.
- Israeli Standards Institute Certification Lag:Module testing protocols and BIS-equivalent documentation requirements add months to supplier qualification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Solar Energy Market |
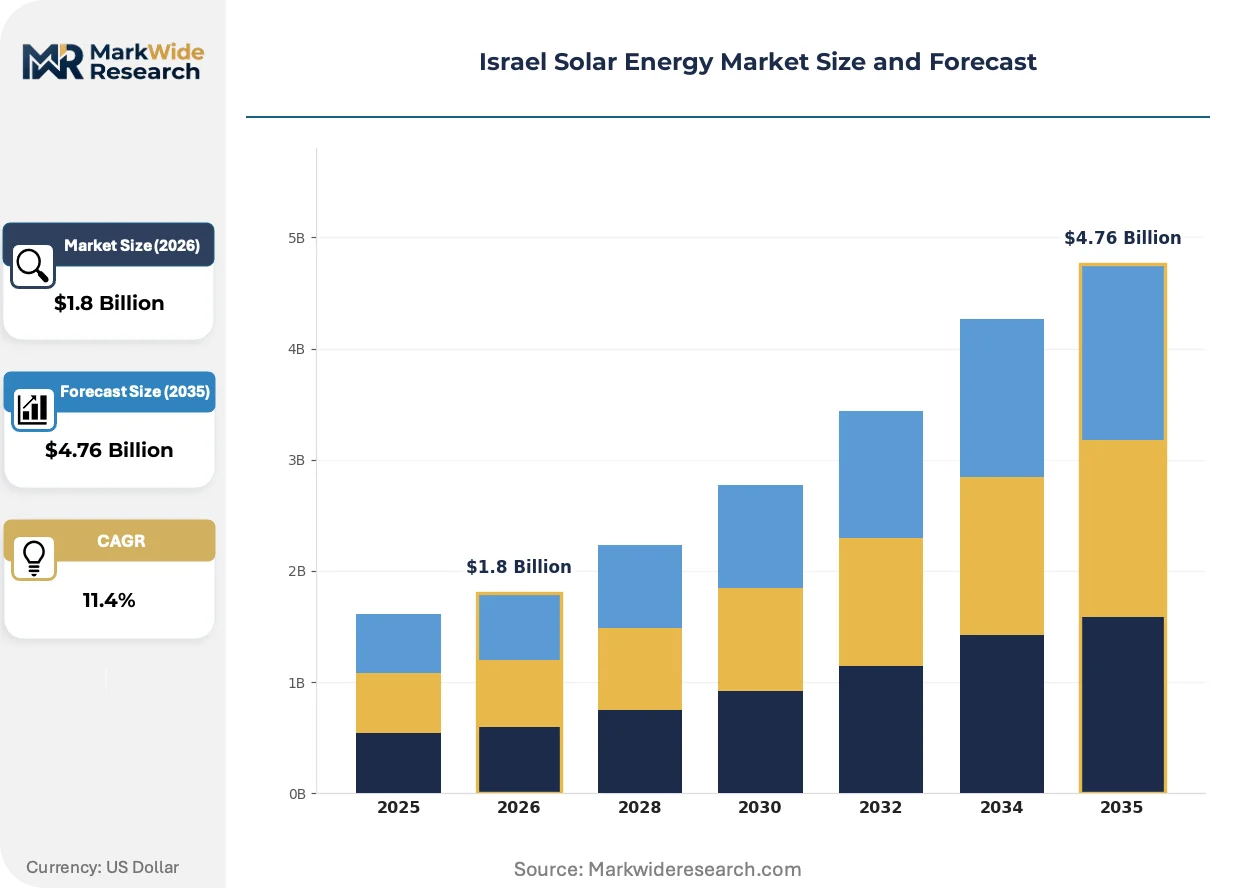
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, BIPV, Solar Thermal Application: Residential, Commercial, Utility-Scale, Off-Grid Installation Type: Roof-mounted, Ground-mounted, Solar Farms, Hybrid Systems End User: Energy Providers, Homeowners, Government, Industrial Users |
| Companies Covered | Shikun & Binui Ltd, Doral Energy, SolarEdge Technologies, Inc., Rapac Energy, Solaer Renewable Energies Ltd, O.Y. Nofar Energy Ltd, EDF Renewables, Shamir Energy, Enlight Renewable Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Solar Energy Market Shifts & Advancements
Technology trajectories in Israeli solar deployment center on module-level power electronics advancement, regulatory compression of interconnection timelines, and procurement model evolution toward energy-as-a-service structures.
Bifacial photovoltaic module architecture is fragmenting procurement specifications across the utility-scale pipeline. High-albedo desert conditions in the Negev enable rear-side energy yield capture that mono-facial designs cannot match. Developers now specify bifacial glass-glass configurations as baseline requirements, compressing margin structures for legacy single-sided suppliers.
The Electricity Authority's streamlined grid connection protocols reduce technical study phases from multiple quarters to single-quarter windows. Industrial and commercial applicants benefit most from parallel-track permitting that overlaps environmental review with electrical engineering assessment. Distributed generation projects in Haifa and Beersheba metropolitan zones are responding with accelerated construction mobilization.
Power purchase agreement structures are unbundling hardware ownership from energy delivery obligations. Industrial offtakers in chemicals and desalination verticals now contract for kilowatt-hour supply without balance-sheet recognition of underlying asset depreciation. This shift concentrates in the southern district industrial zones where creditworthy anchor tenants anchor project finance structures.
Israel Solar Energy Market Segmentation
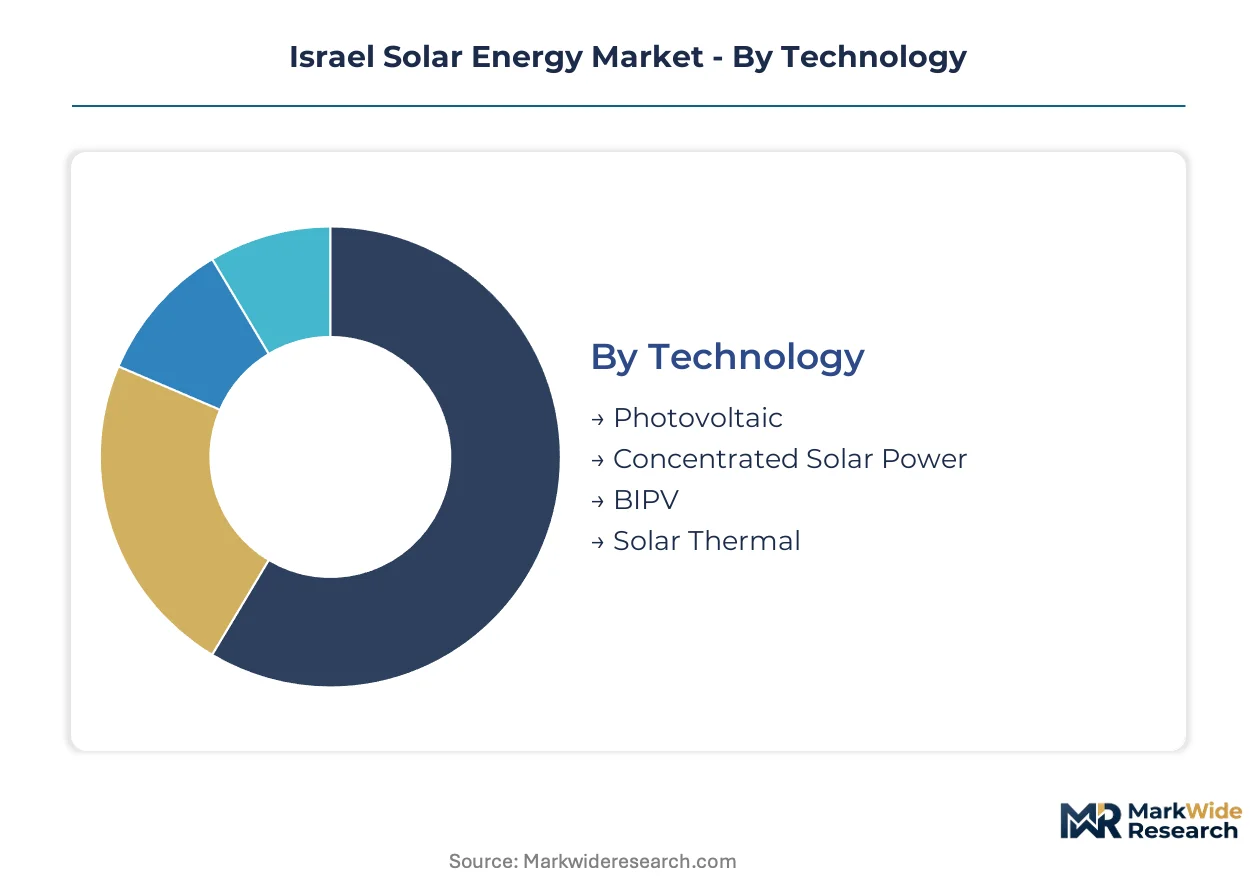
Technology and application boundaries in the Israel solar energy market are shifting as bifacial modules and agrivoltaic configurations reorganize procurement priorities. Understanding segment substitution pressures enables developers to anticipate where capital allocation will concentrate across the Negev Desert pipeline and central district installations.
Technology:
Photovoltaic technology faces intensifying internal substitution as bifacial designs displace mono-facial modules in high-albedo desert conditions, while concentrated solar power contends with battery-hybrid alternatives for dispatchable renewable generation.
- Photovoltaic:Crystalline silicon modules dominate utility-scale deployments through proven bankability and standardized installation protocols. Demand concentrates in the Negev Desert where land availability and irradiance levels attract concentrated project development from utility-scale developers.
- Concentrated Solar Power:Molten-salt thermal storage integration enables dispatchable renewable generation with evening peak supply capability. The technology occupies a niche role as battery storage mandates expand and photovoltaic-plus-storage configurations capture grid stability contracts.
- BIPV:Facade-integrated systems embed photovoltaic generation into building envelopes for metropolitan construction codes. Revised mandates in Tel Aviv and Haifa create embedded demand for architectural solar solutions.
- Solar Thermal:Collectors convert electromagnetic radiation into thermal output for industrial process heat applications. Desalination and food processing facilities in southern industrial zones displace natural gas consumption through thermal integration.
Photovoltaic retains volume leadership; BIPV holds the steepest expansion curve.
Application:
Cost tier stratification separates utility-scale projects with institutional financing access from distributed segments dependent on net metering economics and residential payback period sensitivity.
- Residential:Distributed generation adoption accelerates as net metering reforms improve homeowner payback periods in suburban municipalities. SolarEdge Technologies anchors module-level electronics supply for rooftop installations through sustained R&D investment.
- Utility-Scale:The largest project pipeline commands procurement priority reorganization toward bifacial modules and agrivoltaic configurations. Enlight Renewable Energy extends domestic construction capabilities into neighboring markets through wind-solar hybrid development.
- Commercial:Industrial offtakers in chemicals and desalination verticals contract for kilowatt-hour supply without balance-sheet asset recognition. Power purchase agreement structures unbundle hardware ownership from energy delivery obligations.
- Off-Grid:Remote installations serve military outposts and agricultural operations beyond distribution network reach. Battery storage integration addresses intermittency constraints in rural transmission nodes.
Utility-Scale dominates capital deployment; Residential is expanding most quickly through regulatory reform.
Installation Type:
Geography dictates installation selection as ground-mounted solar farms claim Negev Desert acreage while roof-mounted systems penetrate Tel Aviv and Haifa metropolitan zones with limited land availability.
- Ground-mounted:Fixed-tilt and tracking structures optimize land-intensive deployment across high-irradiance southern districts. Doral Energy leverages project development pipelines to secure land agreements in the Negev Desert.
- Roof-mounted:Distributed generation integration on residential and commercial buildings addresses central district site constraints. Net metering reform shortens payback periods for suburban municipality adoption.
- Solar Farms:Large-scale arrays concentrate generation capacity for grid supply through centralized interconnection infrastructure. The Electricity Authority's revised standards compress technical study phases from multiple quarters to single-quarter windows.
- Hybrid Systems:Co-located battery storage satisfies mandate expansions and extends revenue capture into evening peak pricing windows. Storage-hybrid configurations reorganize developer capital allocation across procurement priorities.
Ground-mounted retains volume leadership; Hybrid Systems hold the steepest expansion curve.
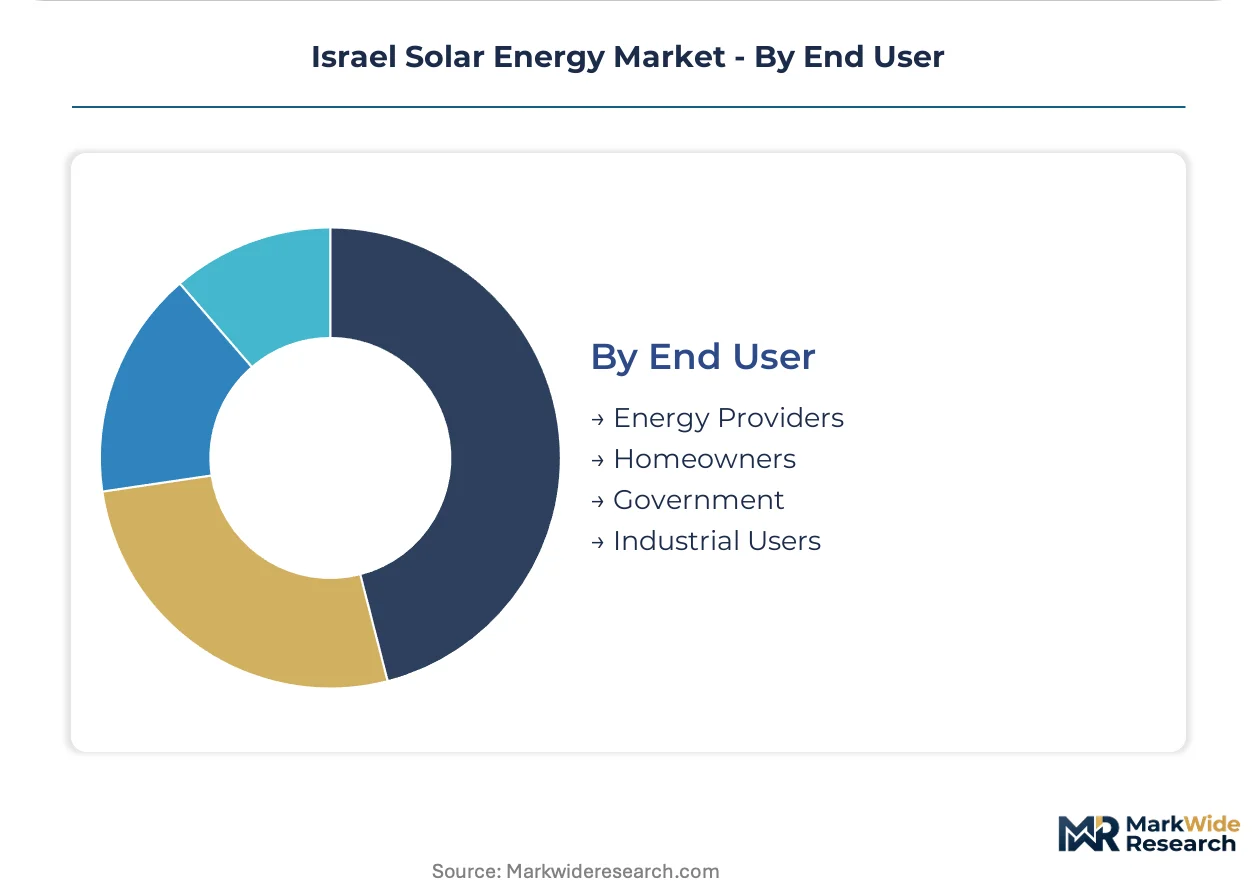
End User:
Customer type determines project finance structure as energy providers access institutional capital while industrial users drive energy-as-a-service contract innovation.
- Energy Providers:Grid interconnection standards and renewable energy certificate mechanisms determine project economics and market access timelines. The Electricity Authority regulates tariff structures that shape utility-scale development returns.
- Industrial Users:Chemicals and desalination verticals anchor project finance structures through creditworthy offtake agreements. Process heat integration displaces natural gas consumption in southern district industrial zones.
- Homeowners:Distributed generation adoption responds to net metering reform and suburban municipality permitting efficiency. Residential segment growth accelerates as payback periods compress.
- Government:Public procurement supports agrivoltaic land-use frameworks and dual-use solar installations on agricultural plots. Policy shifts determine site availability and project returns in southern districts.
Energy Providers retain volume leadership; Industrial Users hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Israel Electric Corporation's national grid infrastructure underwrites solar deployment potential across the country's diverse topography. Transmission capacity expansion in southern districts unlocks utility-scale development in high-irradiance zones. Interconnection protocols determine project economics regionally.
Negev Desert
Land availability and irradiance levels attract concentrated project development from utility-scale developers. The Electricity Authority's revised grid interconnection standards compress technical study phases for installations in this region. Doral Energy leverages project development pipelines to secure land agreements across southern acreage.
Central District
Agrivoltaic dual-use solar installations on agricultural plots unlock site availability constraints that previously bottlenecked deployment. The Ministry of Energy regulates tariff structures that shape development returns in this mixed-use zone. Suburban municipalities accelerate distributed generation adoption through streamlined permitting.
Haifa Metropolitan Zone
Industrial offtakers in chemicals and desalination verticals anchor project finance structures through creditworthy agreements. The Israeli Standards Institute shapes module certification requirements influencing supplier qualification. Revised construction codes create embedded demand for building-integrated photovoltaic systems.
Beersheba Metropolitan Area
Net metering reforms improve homeowner payback periods and accelerate residential segment growth. SolarEdge Technologies anchors module-level electronics supply for rooftop installations through sustained investment. Distributed generation projects respond with accelerated construction mobilization.
Eilat-Aqaba Corridor
Regional interconnection infrastructure could unlock export capacity for surplus generation from southern installations. Cross-border energy trade frameworks remain under negotiation between national regulators. Industrial process heat integration displaces natural gas consumption in desalination facilities.
Israel Solar Energy Market Competitive Landscape
Concentration sits with integrated project developers and technology specialists rather than pure component suppliers. The competitive structure fragments across development, electronics, and engineering service archetypes. Tier-one players combine land access with financing capability; mid-tier specialists focus on inverter technology or hybrid system integration. Dominant competitive moves include strategic land banking in southern districts and technology licensing for module-level power electronics.
Among Israel-based developers, Shikun & Binui Ltd and Doral Energy exemplify the integrated project developer archetype with land aggregation capabilities. SolarEdge Technologies, Inc. occupies a position representing the module-level electronics specialization tier. Enlight Renewable Energy sits within the renewable energy developer archetype extending construction capabilities across technology types. These three anchors illustrate the market's tripartite structure: development execution, power electronics manufacturing, and multi-technology project delivery.
| Leading Market Players |
|---|
| Shikun & Binui Ltd |
| Doral Energy |
| SolarEdge Technologies, Inc. |
| Rapac Energy |
| Solaer Renewable Energies Ltd |
| O.Y. Nofar Energy Ltd |
| EDF Renewables |
| Shamir Energy |
| Enlight Renewable Energy |
| Others |
Supply & Pricing Matrix
Fourteen-week module delivery windows from East Asian polysilicon refiners compress developer procurement calendars while concentrating price-setting power among crystalline silicon suppliers serving the Negev Desert pipeline. Inventory buffers at Israeli port terminals rarely exceed thirty days, tethering project economics to upstream metallurgical-grade silicon volatility and freight rate fluctuations through the Suez Canal corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified bifacial glass-glass modules from BIS-equivalent standard tiers and uncertified economy imports. Price differentiation hinges on Israeli Standards Institute certification status and volume procurement scale, with utility-scale developers capturing steepest discounts through multi-hundred-megawatt offtake commitments. Cost compression in the standard tier is intensifying because East Asian polysilicon oversupply has eroded supplier margins. Residential rooftop buyers exhibit highest price sensitivity due to payback period calculations, while industrial offtakers prioritize performance warranties over unit economics.
Supply Chain Analysis
Inventory buffers at Israeli port terminals rarely exceed thirty days, reflecting just-in-time delivery discipline across crystalline silicon module procurement. Supply concentrates in China, Vietnam, and Malaysia for cell and module assembly, with polysilicon feedstock drawing from Chinese and German metallurgical-grade refining corridors. Raw material dependencies center on high-purity silicon ingots, silver paste for metallization, and aluminum framing extrusions. Single-source vulnerability pervades the polysilicon tier where three Chinese producers control majority global output. Distribution runs through EPC contractors with direct manufacturer relationships, bypassing traditional distributor networks for utility-scale volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated project developers with land-banking capabilities and long-term PPA pipelines, fragmenting procurement leverage across smaller IPPs and commercial offtakers. This consolidation among developers with Negev Desert acreage positions reshapes supplier negotiation dynamics.
For Market Incumbents: Fortify land-position moats through accelerated option agreements in southern districts ahead of Electricity Authority transmission expansion announcements. Deepen backward integration into energy storage system assembly to capture co-location mandate premiums and defend margin structures against pure-play battery suppliers entering the hybrid configuration segment.
For New Entrants and Emerging Players: Anchor in agrivoltaic EPC services for Central District agricultural cooperatives, the most penetrable white-space where incumbent developers lack specialized dual-use installation expertise. Target industrial process heat integration contracts at southern desalination facilities, leveraging solar thermal collector deployment as a beachhead for subsequent photovoltaic-plus-storage expansion.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across residential distributed generation as module-level electronics commoditization reduces balance-of-system costs, improving project IRRs for rooftop-focused platforms. Acquisition target archetype: regional EPC contractors with Israeli Standards Institute certification relationships and active grid interconnection queue positions. Signal to watch is Electricity Authority storage mandate expansion announcements that would revalue hybrid development pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Agrivoltaic Land Banking | Dual-use solar configurations unlock Central District site constraints previously blocking utility-scale deployment. |
| Storage-Hybrid Development | Co-located battery systems satisfy Electricity Authority mandate expansions and capture evening peak pricing premiums. |
| Bifacial Module Procurement | Rear-side yield capture in high-albedo Negev conditions displaces mono-facial designs from developer specifications. |
| Building-Integrated Photovoltaic Certification | Tel Aviv and Haifa construction code revisions create embedded demand for facade-integrated architectural solar systems. |
| Cross-Border Interconnection Development | Eilat-Aqaba corridor infrastructure could unlock export capacity for surplus southern generation into Jordanian markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA international energy statistics, IEA renewable energy market analysis, and Electricity Authority regulatory filings. Primary interviews incorporated utility planning officers at the Israel Electric Corporation, IPP project developers active in Negev Desert pipelines, EPC contractors with grid interconnection experience, and module procurement leads at integrated developers. Secondary validation drew from Israeli Standards Institute certification databases, Ministry of Energy policy announcements, and customs import records for crystalline silicon equipment. Bottom-up project pipeline aggregation was cross-checked against top-down national renewable capacity targets.
Segmentation dimensions modeled span photovoltaic technology variants, utility-scale versus distributed application categories, ground-mounted and roof-mounted installation types, and energy provider through government end-user classifications. Revenue projections across the analysis window were derived from capacity deployment forecasts multiplied by benchmark system cost trajectories, with technology-specific CAGRs reflecting module efficiency improvement curves and balance-of-system learning rates. Key inputs included bifacial module penetration assumptions, storage co-location mandate compliance schedules, and net metering tariff reform implementation pacing.
Material uncertainties — polysilicon supply disruptions, Electricity Authority interconnection standard revisions, and land-use policy shifts affecting nature reserve buffers — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding module cost decline trajectories and grid absorption capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Dual Axis Solar Tracker Market