
 Asia Pacific Load Break Switches Market | 2026-2036
Asia Pacific Load Break Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Load Break Switches Market Outlook
Multi-sourced procurement of vacuum interrupter assemblies is rebalancing toward captive in-house production among established switchgear manufacturers. Eaton leverages its regional manufacturing footprint to anchor supply security across Southeast Asian project pipelines. Schneider Electric sustains technology leadership through dedicated R&D centers in India and China. Siemens competes on system integration breadth, bundling load break switches with digital protection relays.
Asia Pacific load break switches are electromechanical devices rated for making and breaking load currents in medium-voltage distribution circuits, typically operating at 12–36 kV with fault-making capacity up to 20 kA. They isolate feeder sections during maintenance while withstanding transient recovery voltages across their contact gap. Vacuum technology leads installed base value due to superior arc quenching and minimal maintenance requirements across tropical climates. Outdoor installations dominate utility procurement, though compact modular designs for commercial rooftop substations represent the fastest-expanding configuration segment. SF6-insulated variants retain niche positions in coastal zones requiring compact footprint despite environmental scrutiny.
India's CEA mandates IEC 62271-103 compliance for all new utility switchgear, while China's GB 1984 standards enforce stricter short-circuit withstand tests under SAMR supervision. Australia's TGA-equivalent electrical safety regulators impose additional certification burdens on imported assemblies. Stakeholders must monitor evolving F-Gas Regulation analogs across ASEAN jurisdictions that could restrict SF6-insulated product lines without early transition planning.
Market Dynamics
Vacuum interrupter technology is consolidating supply chains across Southeast Asia, with manufacturers retreating from multi-sourced procurement toward captive in-house production to secure project pipelines against lead-time volatility.
Growth Catalysts
- India's rural feeder modernization:State electricity boards are replacing oil-insulated switchgear under CEA mandates, creating sustained tender volumes for 12–36 kV vacuum load break switches.
- China's dual carbon goals:MEE oversight is accelerating phase-out of SF6-insulated legacy assets, redirecting utility procurement toward vacuum alternatives with superior arc quenching.
- Urbanization-driven network expansion:Utilities across Vietnam, Indonesia, and the Philippines are extending medium-voltage distribution to serve rapidly densifying metropolitan peripheries.
Market Restraints
- Copper and silver contact material volatility:Price swings in precious metal inputs compress margin buffers for interrupter assembly producers.
- SF6 regulatory friction:Evolving F-Gas Regulation analogs across ASEAN jurisdictions threaten stranded inventory for manufacturers without early transition planning.
- Technical limitation in coastal corrosion:Salt-laden tropical atmospheres degrade outdoor terminal connections, forcing premium sealing specifications that inflate unit costs.
Strategic Opportunities
- Vietnam's underpenetrated commercial rooftop segment:Compact modular switchgear designs for urban substations remain nascent against utility-scale deployment.
- Digital protection relay convergence:Integration of load break switches with IEC 61850-compliant monitoring creates bundled system value.
- Australia's certification-driven replacement cycle:TGA-equivalent electrical safety regulators are imposing renewal burdens on aging 1980s-era installed base.
Industry Challenges
- Vacuum interrupter technician scarcity:Specialized skills for ceramic-to-metal sealing and contact geometry tuning concentrate in legacy industrial clusters.
- IEC 62271-103 compliance timelines:India's CEA mandates are compressing certification windows for imported assemblies.
- Legacy oil switchgear integration friction:Retrofit compatibility with existing bus configurations extends project engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Load Break Switches Market |
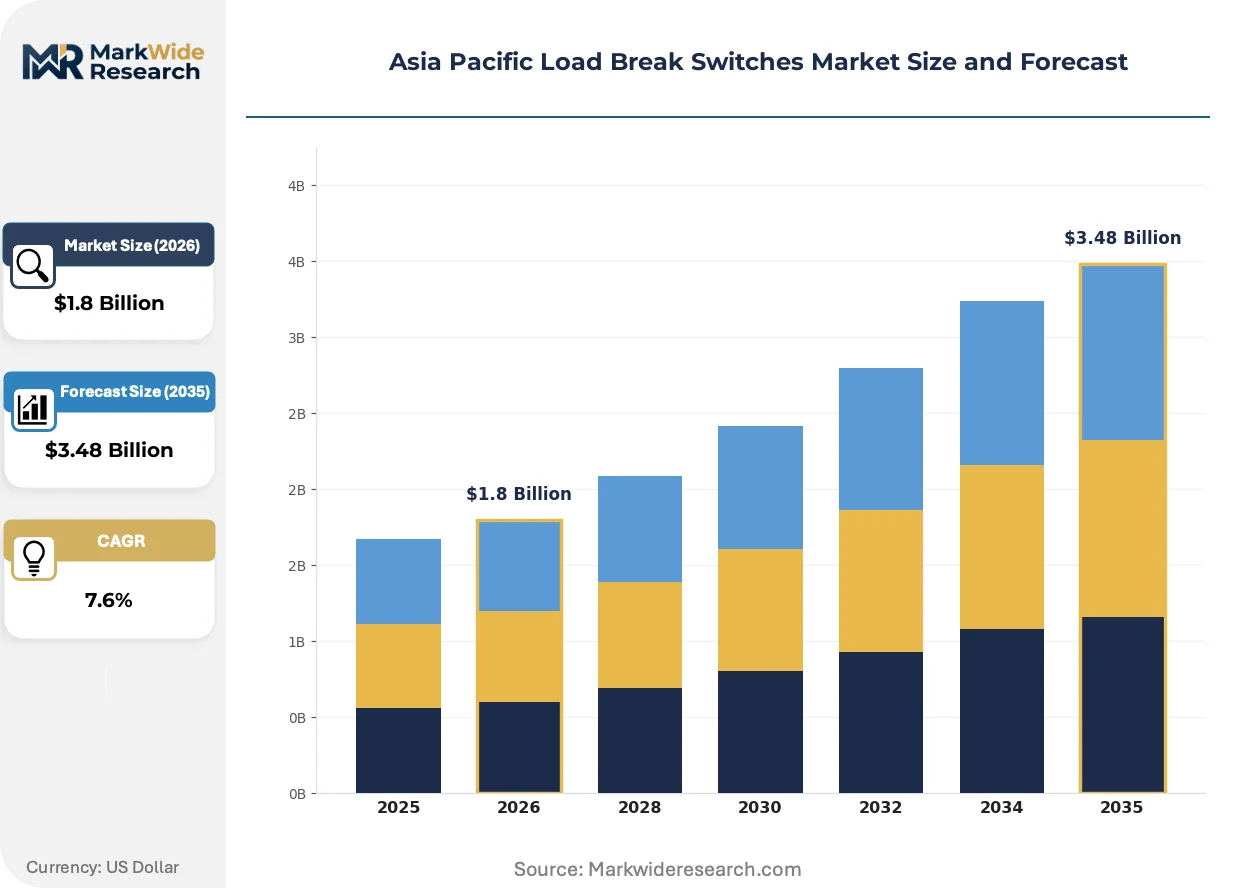
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor, Indoor, Compact, Modular Technology: Vacuum, Air-insulated, SF6, Oil-insulated End User: Utilities, Industrial, Commercial, Residential Installation Type: Fixed, Portable, Automated, Manual |
| Companies Covered | Eaton, Safvolt, ABB, SOCOMEC, Fuji Electric FA Components, Schneider Electric, Rockwell Automation, Powell Industries, Siemens, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Load Break Switches Market Strategic Shifts
Digitalization is penetrating electromechanical switchgear, converting passive isolation devices into sensor-enabled grid assets that feed real-time telemetry to distribution management systems.
Modular vacuum interrupter assemblies are unifying breaker and disconnector functions into single compact enclosures. Commercial rooftop substation operators across Bangkok, Jakarta, and Ho Chi Minh City are specifying these integrated units to minimize footprint constraints. This unification is compressing traditional procurement categories that previously separated switching and protection equipment.
China's GB 1984 standards under SAMR supervision are enforcing stricter short-circuit withstand test protocols. Domestic manufacturers must retest legacy designs, while importers face extended homologation timelines. Vacuum-insulated product lines are absorbing this compliance burden more readily than SF6 alternatives facing parallel environmental scrutiny.
State electricity boards in India are consolidating vendor panels, reducing approved supplier lists from fragmented regional rosters toward pre-qualified national frameworks. Distribution utilities in Maharashtra, Gujarat, and Tamil Nadu are piloting this concentration. The shift privileges manufacturers with captive testing facilities and multi-state service networks over import-dependent distributors.
Asia Pacific Load Break Switches Market Segmentation
Load break switch procurement patterns diverge sharply across installation environments, insulation technologies, and buyer sophistication levels. Understanding these fault lines reveals where margin pools concentrate and which specifications command pricing premiums.
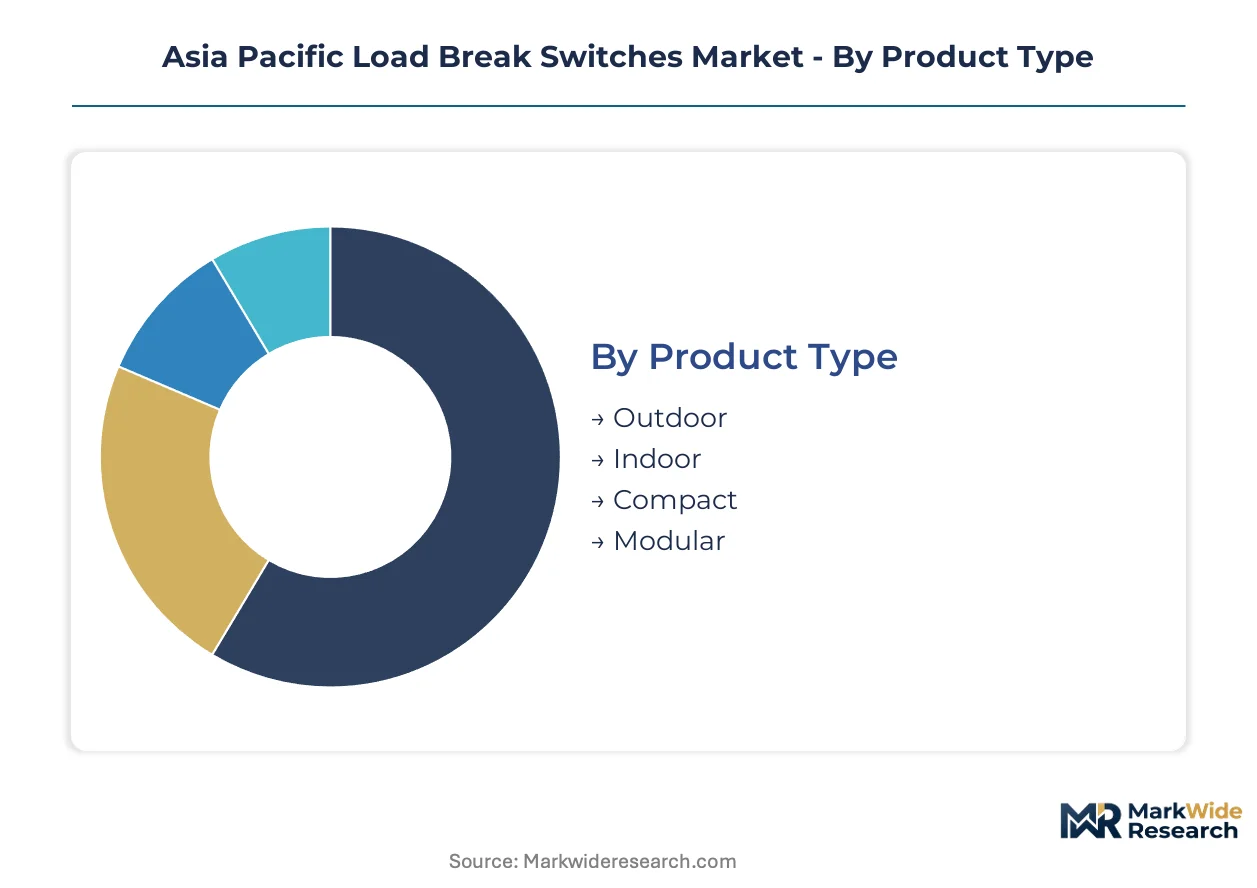
Product Type:
Utility procurement teams prioritize environmental sealing ratings and thermal cycling endurance over unit cost when selecting enclosure formats.
- Outdoor:Weather-resistant housings with IP54+ ratings dominate utility distribution feeder applications across India's state electricity boards and China's provincial grid companies. Salt fog corrosion resistance commands premium specifications in coastal Vietnam and Philippines deployments.
- Indoor:Compact footprint designs serve commercial substation operators in Bangkok and Jakarta where real estate constraints drive specification priorities. These installations emphasize arc flash containment and reduced clearance requirements.
- Compact:Footprint-optimized units for urban rooftop substations.
- Modular:Field-expandable configurations allowing future capacity augmentation.
Outdoor leads volumes today; compact designs are gaining share fastest.
Technology:
Insulation medium selection now hinges on regulatory compliance velocity rather than pure technical performance.
- Vacuum:Ceramic-to-metal sealed interrupter assemblies deliver maintenance-free operation across 20+ year lifecycles. China's MEE oversight and India's CEA mandates are redirecting procurement away from legacy alternatives toward vacuum's superior arc quenching and zero greenhouse gas footprint.
- SF6:Compact footprint advantages persist in space-constrained coastal substations despite environmental scrutiny. ASEAN jurisdictions are drafting F-Gas Regulation analogs that threaten stranded inventory without transition planning.
- Air-insulated:Cost-effective for low-fault-current rural feeders with adequate installation clearances.
- Oil-insulated:Phase-out accelerated by India's rural modernization mandates and China's dual carbon goals.
Vacuum dominates installed base value; air-insulated variants are expanding most quickly in price-sensitive rural segments.
End User:
Buyer technical sophistication determines specification complexity and service attachment rates.
- Utilities:State electricity boards in Maharashtra, Gujarat, and Tamil Nadu consolidate vendor panels toward pre-qualified national frameworks. These buyers demand IEC 62271-103 compliance documentation and multi-state service networks.
- Industrial:Manufacturing campuses and petrochemical complexes specify integrated protection relay bundles. Siemens competes aggressively here on system integration breadth.
- Commercial:Bangkok and Ho Chi Minh City rooftop substation operators prioritize footprint minimization over fault-making capacity.
- Residential:Low-voltage secondary distribution with minimal switching duty requirements.
Utilities anchor procurement volumes; commercial installations are climbing the fastest.
Installation Type:
Operational labor availability and grid automation roadmaps determine mechanism selection.
- Fixed:Permanent pole-mounted or substation installations constitute the utility standard across Southeast Asian distribution networks.
- Portable:Temporary feeder sectionalization for maintenance operations.
- Automated:Motorized operators with SCADA integration serve smart grid pilots in Singapore and advanced Chinese provincial grids. IEC 61850 protocol compliance is becoming mandatory for new automated specifications.
- Manual:Cost-minimized solutions for rural feeders with limited maintenance access.
Fixed installations lead volumes today; automated variants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors regional manufacturing capacity for vacuum interrupter assemblies, with provincial grid companies driving procurement volumes under MEE oversight of dual carbon compliance timelines.
China
Provincial grid operators in Jiangsu and Zhejiang are replacing oil-insulated legacy assets with vacuum alternatives. SAMR-enforced GB 1984 standards mandate retesting of existing designs, extending homologation timelines for imported assemblies. Shanghai and Suzhou industrial clusters concentrate ceramic-to-metal sealing expertise for interrupter production.
India
State electricity boards in Maharashtra, Gujarat, and Tamil Nadu are consolidating vendor panels toward pre-qualified national frameworks. CEA mandates IEC 62271-103 compliance for all new utility switchgear, compressing certification windows. Bangalore and Pune host captive testing facilities serving multi-state distribution networks.
Vietnam
Utilities are extending medium-voltage distribution to metropolitan peripheries around Hanoi and Ho Chi Minh City. Draft F-Gas Regulation analogs threaten SF6-insulated inventory positions without transition planning. Da Nang coastal installations command premium corrosion-resistant specifications for salt-laden tropical atmospheres.
Indonesia
Perusahaan Listrik Negara is expanding feeder networks to serve urbanizing populations across Java and Sumatra. The national utility prioritizes IP54+ outdoor enclosures for tropical humidity endurance. Jakarta and Surabaya commercial rooftop substations are specifying compact modular designs for footprint-constrained installations.
Australia
TGA-equivalent electrical safety regulators are imposing renewal burdens on aging 1980s-era installed base across New South Wales and Victoria. Certification-driven replacement cycles favor vacuum-insulated alternatives with documented lifecycle compliance. Sydney and Melbourne distribution utilities are piloting automated motorized operators with SCADA integration.
Asia Pacific Load Break Switches Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital integration and modular system bundling. The vendor base clusters around three strategic archetypes: integrated electrical conglomerates with captive interrupter production, specialized switchgear fabricators with regional service networks, and automation specialists converging on protection relay bundling. Dominant competitive moves include backward integration into vacuum interrupter manufacturing and geographic expansion through multi-state service franchise agreements.
Among integrated electrical conglomerates, Eaton and Schneider Electric exemplify archetypes with differentiated regional footprints. Eaton leverages manufacturing presence across Southeast Asian project pipelines. Schneider Electric sustains technology positioning through dedicated R&D centers in India and China. Siemens occupies a system integration position, bundling load break switches with digital protection relays for industrial campus specifications.
| Leading Market Players |
|---|
| Eaton |
| Safvolt |
| ABB |
| SOCOMEC |
| Fuji Electric FA Components |
| Schneider Electric |
| Rockwell Automation |
| Powell Industries |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
India's CEA-mandated IEC 62271-103 compliance for all new utility switchgear is forcing manufacturers to absorb retesting costs and extend homologation timelines, which compresses margin buffers and redirects procurement toward suppliers with captive certification facilities.
Pricing Analysis
Copper and silver contact material volatility passes through directly to interrupter assembly pricing, with precious metal swings compressing margins for producers lacking long-term offtake contracts. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified vacuum units from legacy SF6 alternatives and basic air-insulated rural feeders. Cost compression in the economy tier is intensifying because state electricity boards are consolidating vendor panels and squeezing unit costs. Industrial buyers bundling digital protection relays show least price sensitivity; rural utilities under central government budget constraints exhibit highest.
Supply Chain Analysis
Vacuum interrupter ceramic-to-metal sealing expertise rests on industrial clusters in China's Yangtze River Delta, India's Bangalore-Pune corridor, and Japan's legacy manufacturing bases. Critical inputs include high-purity copper-silver contact alloys, alumina ceramic insulators, and precision-machined stainless steel bellows. Single-source vulnerability concentrates in Japanese specialty ceramic producers for ultra-high-voltage interrupter applications. Distribution runs through direct utility procurement frameworks in India and China, supplemented by regional switchgear fabricators serving Southeast Asian project pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: India's rural feeder modernization and China's dual carbon asset replacement are elevating specification thresholds toward vacuum-insulated, digitally integrated premium units.
For Market Incumbents: Extend captive vacuum interrupter production capacity across Southeast Asian manufacturing footprints to secure project pipelines against lead-time volatility from multi-sourced procurement retreat. Deepen backward integration into ceramic-to-metal sealing processes, as technician scarcity for this specialized craft threatens output scalability. Defend against emerging modular switchgear bundlers by anchoring multi-state service networks under India's consolidating vendor panel frameworks. For New Entrants and Emerging Players: F-Gas Regulation analogs across ASEAN jurisdictions open a window for vacuum-insulated product lines to displace stranded SF6 inventory positions. Target Vietnam's underpenetrated commercial rooftop substation segment, where compact modular designs remain nascent against utility-scale deployment. Pursue go-to-market partnerships with Bangkok and Jakarta electrical contractors specifying footprint-optimized units for urban real estate constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap switchgear fabricators possessing captive testing facilities and multi-state service franchises under India's consolidating procurement frameworks. Long-term viability centers on manufacturers with demonstrated IEC 62271-103 compliance velocity and vacuum interrupter production depth. Watch for inflection when China's SAMR announces retesting completion timelines for GB 1984 standard enforcement, which will clarify homologation bottlenecks and reorder competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Production | Captive ceramic-to-metal sealing secures supply against Japanese specialty producer bottlenecks. |
| Multi-State Service Franchise Expansion | Pre-qualified national frameworks in Maharashtra and Gujarat privilege vendors with geographic coverage depth. |
| Digital Protection Relay Convergence | IEC 61850-compliant bundling with load break switches creates system-level value for industrial campuses. |
| Corrosion-Resistant Specification Development | Premium IP54+ and salt fog ratings command pricing premiums in Vietnam and Philippines coastal zones. |
| CEA Certification Fast-Track Investment | Captive testing facilities compress India's compressed homologation windows for imported assemblies. |
Study Parameters
Direct dialogue with utility procurement officers at India's state electricity boards, vacuum interrupter production engineers in China's Yangtze River Delta, Southeast Asian EPC contractors, and switchgear aftermarket service heads grounded qualitative findings. Secondary validation drew from CEA tender documentation, SAMR GB standard enforcement notices, ASEAN customs trade data, and IEC certification registries. Bottom-up unit shipment estimates triangulated against top-down utility capex disclosures across the analysis window.
Segmentation outputs modeled installation environment, insulation technology, end-user sophistication, and mechanism automation level throughout the forecast period. CAGRs derived from utility modernization pipeline tracking, rural electrification budget allocations, and commercial rooftop substation permitting velocity. Model inputs incorporated MEE dual carbon compliance timelines, CEA vendor panel consolidation progress, and evolving ASEAN F-Gas regulatory drafting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SF6 phase-out scenarios or prolonged precious metal price spikes. Assumptions reflect documented utility procurement patterns, regulatory enforcement cadence, and technology transition timelines. A small set of named triggers warrants ongoing watch: China's SAMR retesting schedule announcements, India's vendor panel consolidation completion, and ASEAN F-Gas Regulation analog finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Underground Cabling EPC Market