
 High Temperature Overhead Conductor Market | 2026-2036
High Temperature Overhead Conductor Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Overhead Conductor Market Insights
Power purchase agreement-backed project finance is reshaping how transmission developers procure high temperature overhead conductors, shifting capital burdens from utilities to specialized infrastructure funds. Nexans leverages its European manufacturing footprint to anchor long-term supply contracts with grid operators facing renewable integration deadlines. CTC Global Corporation specializes in composite core technology that differentiates its offering against conventional steel-reinforced alternatives. KEC International competes on EPC bundling, combining conductor supply with installation services across South Asian markets.
High temperature overhead conductors carry elevated current loads at temperatures exceeding standard aluminum conductor ratings, typically utilizing annealed aluminum strands around a high-strength composite or alloy core to minimize thermal sag. The Aluminum Conductor Composite Reinforced product category leads value generation as utilities prioritize ampacity gains without right-of-way expansion. Composite Core technology commands premium positioning due to its strength-to-weight ratio, while Electric Transmission applications dominate volume as inter-regional renewable evacuation projects multiply across developing grids. Annealing Process improvements continue to reduce manufacturing energy intensity, broadening addressable markets for cost-sensitive procurement frameworks.
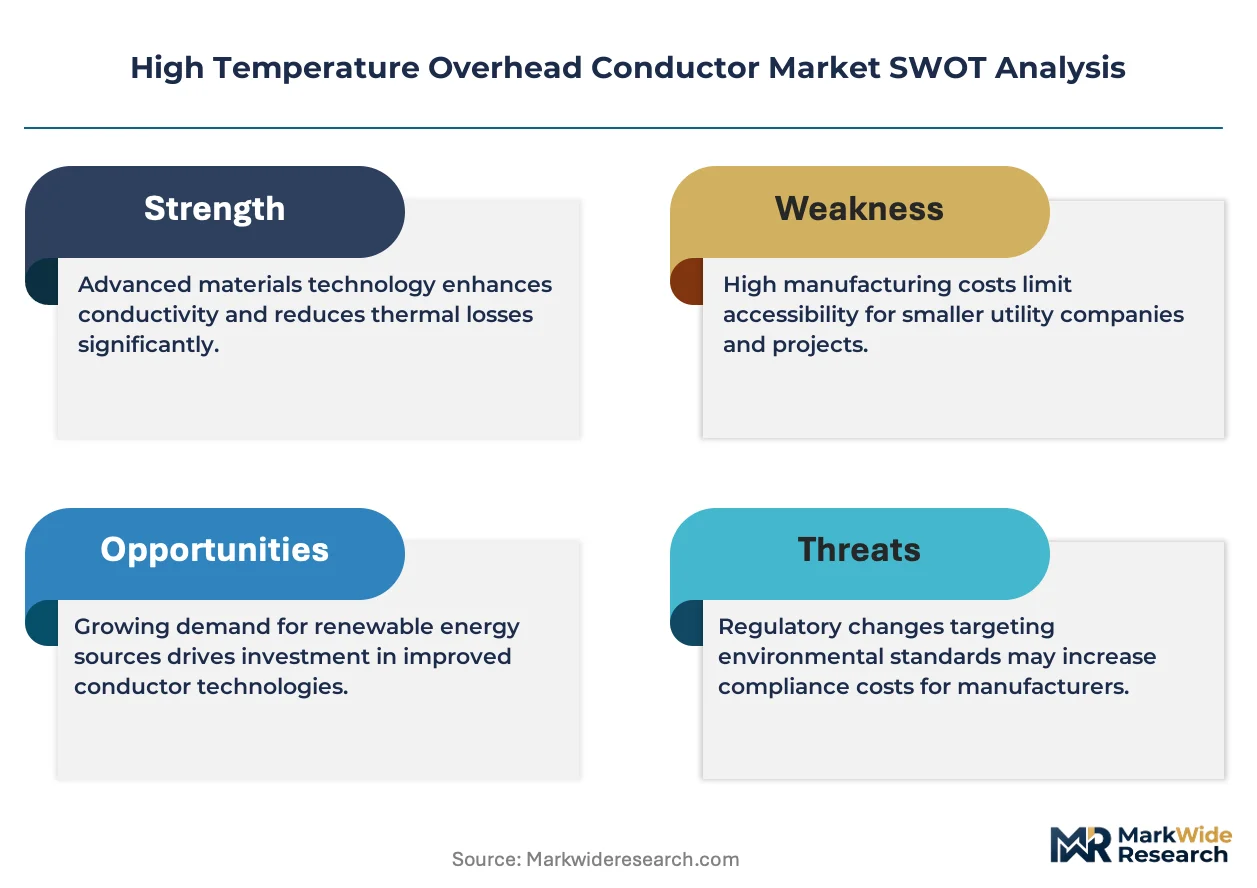
CEA guidelines in India mandate thermal performance benchmarks for new transmission corridors, directly shaping conductor specification requirements for domestic tenders. REACH compliance in Europe restricts certain coating chemistries, pushing suppliers toward halogen-free thermal resistant formulations. The EU Green Deal carbon border adjustments will increasingly filter import competitiveness for non-European manufacturers. Stakeholders must monitor evolving metallurgical standards and localized content rules as procurement authorities balance cost, performance, and supply security objectives across divergent regulatory environments.
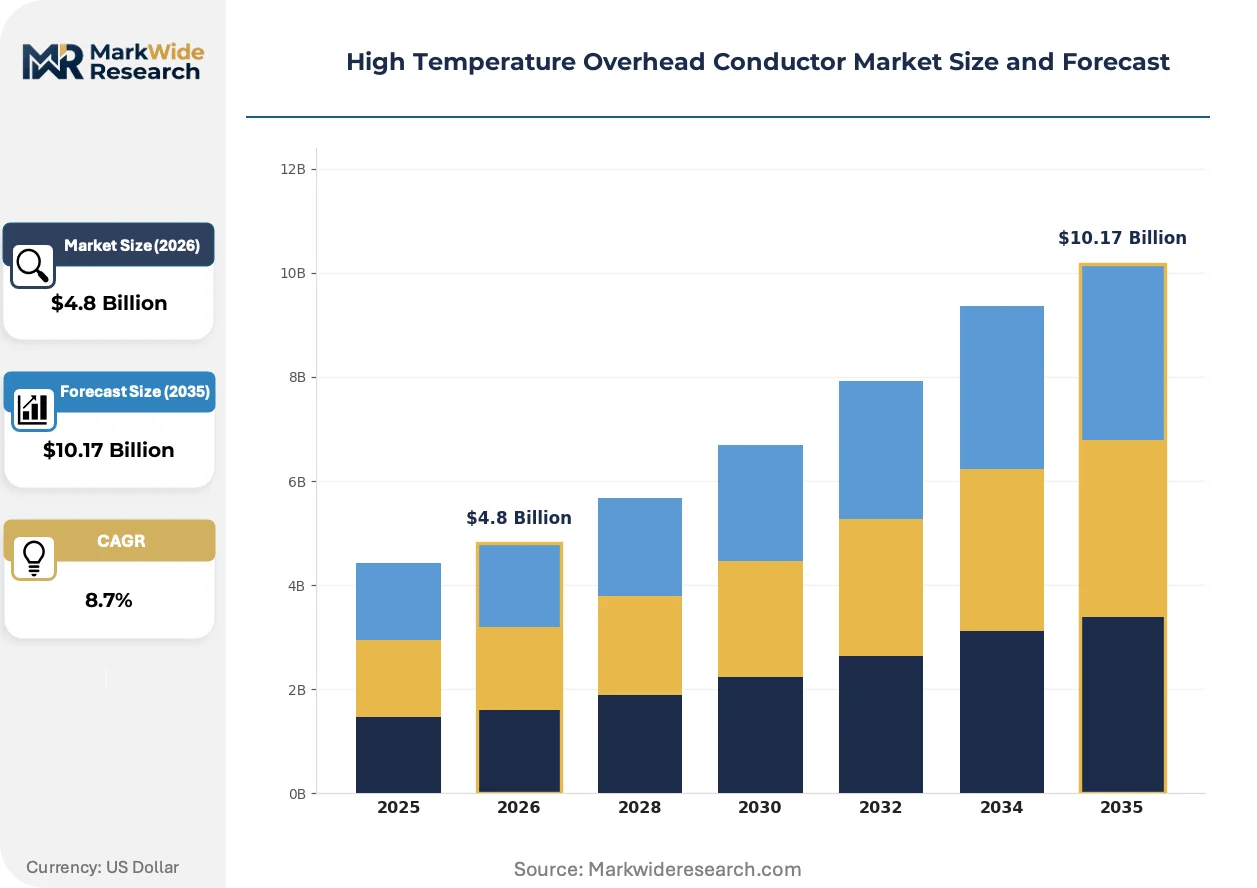
Market Dynamics
Composite core manufacturing scale-up is compressing per-kilometer conductor costs while CEA mandates in India force immediate procurement decisions without waiting for full steel-reinforced alternatives to depreciate.
Growth Catalysts
- CEA Grid Modernization Mandates:India's Central Electricity Authority requires thermal performance benchmarks for new transmission corridors, directly accelerating HTLS conductor specification in domestic tenders.
- Renewable Evacuation Projects:Inter-regional transmission buildouts to accommodate solar and wind farms in Rajasthan and Gujarat create sustained demand for ampacity upgrades without right-of-way expansion.
- Composite Core Technology Maturation:Carbon fiber reinforced polymer cores achieve production consistency that eliminates earlier field reliability concerns, unlocking utility procurement at scale.
Market Restraints
- Raw Material Concentration:Carbon fiber precursor supply concentrates among Japanese and US petrochemical producers, exposing conductor manufacturers to acrylonitrile price volatility and export licensing friction.
- REACH Compliance Costs:ECHA restrictions on halogenated flame retardants force European suppliers to reformulate thermal-resistant coatings, adding certification lag and formulation R&D overhead.
- Steel-Reinforced Incumbency:Existing ACSR inventory and installation contractor familiarity create switching friction even where lifecycle cost economics favor composite alternatives.
Strategic Opportunities
- Sub-Saharan Africa Greenfield Grids:Nations including Kenya and Ethiopia are specifying HTLS conductors for initial transmission backbone construction, bypassing legacy infrastructure constraints entirely.
- EU Carbon Border Adjustment Mechanism:The phased implementation of CBAM creates competitive shelter for European manufacturers against carbon-intensive Asian imports in tender evaluations.
- Digital Twin Integration:Real-time thermal monitoring systems combined with dynamic line rating algorithms enable utilities to extract additional ampacity from existing HTLS installations without physical upgrade.
Industry Challenges
- Specialized Installation Workforce Scarcity:Composite core conductors require tensioning protocols and handling procedures distinct from conventional steel-reinforced products, limiting contractor pool depth in emerging markets.
- Multi-Jurisdictional Certification Burden:Manufacturers must navigate divergent national testing standards for thermal cycling, creep performance, and corona loss, fragmenting product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Overhead Conductor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Conductor Steel-Reinforced, All Aluminum Alloy Conductor, Aluminum Conductor Composite Reinforced, Aluminum Conductor Alloy Reinforced Technology: Thermal Resistant Coating, Composite Core, Aluminum Stranding, Annealing Process, High Strength Alloy Application: Electric Transmission, Railway Electrification, Industrial Power, Urban Distribution, Telecommunication Lines End User: Electric Utilities, Industrial Facilities, Construction Companies, Transportation Authorities |
| Companies Covered | Prysmian Group, Nexans, CTC Global Corporation, Southwire Company, Sumitomo Electric Industries, APAR Industries, Lamifil, ZTT Group, KEC International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Overhead Conductor Market Trends and Innovations
Material science advances and regulatory carbon accounting are converging to redefine procurement criteria, with performance guarantees and embedded emissions now weighted equally with unit cost in transmission developer evaluations.
Hybrid aluminum-zirconium alloy strands paired with carbon fiber composite cores are rendering obsolete conventional thermal-resistant aluminum designs in high-ampacity applications. European transmission system operators including TenneT and National Grid are specifying these conductors for North Sea offshore wind connection corridors. The technology is rendering obsolete the engineering trade-off between thermal rating and mechanical sag that constrained corridor capacity planning for decades.
EU Green Deal carbon border adjustments are restructuring competitive positioning for non-European manufacturers supplying European tenders. The mechanism phases in embodied carbon reporting requirements that disadvantage producers relying on coal-intensive aluminum smelting. Composite core suppliers with verified low-carbon supply chains are capturing preference in German and French transmission procurement frameworks.
Power purchase agreement sponsors are displacing traditional utility capital budgeting as the dominant conductor procurement decision-maker. Infrastructure funds including Copenhagen Infrastructure Partners and Masdar are directly specifying conductor technologies in EPC contracts to accelerate renewable project energization timelines. This pattern concentrates most visibly in India's renewable-rich states where state transmission utilities lack balance sheet capacity to self-finance grid expansion.
High Temperature Overhead Conductor Market Segmentation
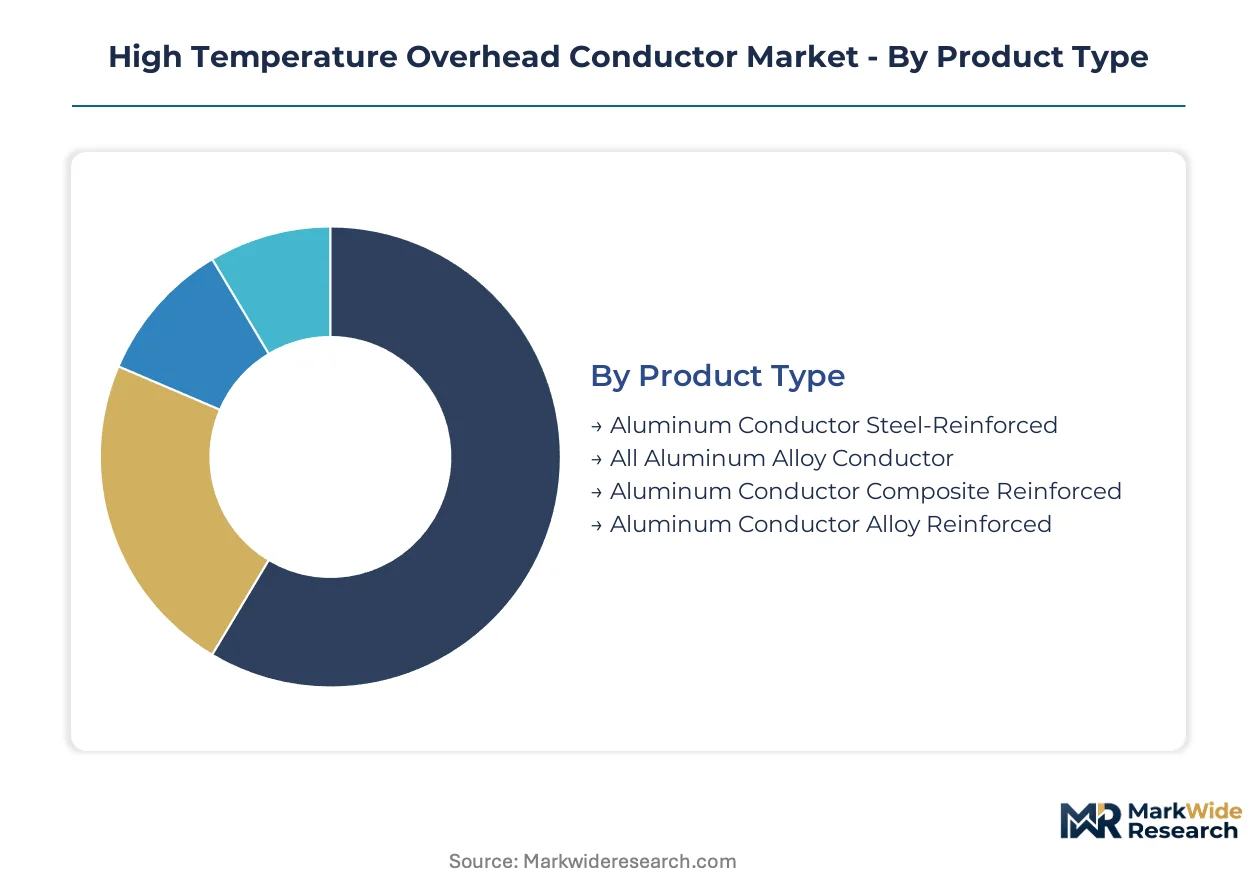
Segmentation in the High Temperature Overhead Conductor Market reveals how technical specifications, deployment contexts, and procurement authority shape purchasing decisions. Utilities prioritize ampacity gains and thermal performance benchmarks over initial capital expenditure, while industrial and transportation end users weight installation speed and corridor footprint constraints differently.
Product Type:
Use cases span legacy grid reinforcement through greenfield renewable evacuation, with core material selection determining thermal rating ceilings and structural load profiles.
- Aluminum Conductor Composite Reinforced:Carbon fiber reinforced polymer cores deliver strength-to-weight ratios enabling 2x ampacity over conventional designs without tower modifications. Demand concentrates in India's Rajasthan and Gujarat renewable corridors where CEA mandates force immediate procurement decisions.
- Aluminum Conductor Steel-Reinforced:Galvanized steel cores provide proven mechanical performance at lower unit cost for standard temperature ratings. Established inventory and contractor familiarity sustain volume in North American utility maintenance programs despite lifecycle cost disadvantages.
- All Aluminum Alloy Conductor:Heat-treatable aluminum alloys achieve moderate thermal resistance without composite core complexity. European TSOs specify these for medium-distance reinforcement where full HTLS performance is unnecessary.
- Aluminum Conductor Alloy Reinforced:High-strength aluminum alloy cores bridge performance gaps between steel-reinforced and composite alternatives. Southeast Asian markets favor this category for cost-sensitive ampacity upgrades.
Established volume favors Aluminum Conductor Steel-Reinforced; emerging adoption favors Aluminum Conductor Composite Reinforced.
Technology:
Manufacturing process selection determines thermal ceiling, sag performance, and supply chain exposure to carbon fiber precursor markets.
- Composite Core:Carbon fiber reinforced polymer manufacturing achieves production consistency that eliminates earlier field reliability concerns. Indian renewable evacuation projects and North Sea offshore wind corridors specify this technology exclusively.
- Annealing Process:Controlled thermal treatment of aluminum strands reduces electrical resistance and improves thermal cycling endurance. Cost-sensitive procurement frameworks in South Asia favor this approach for incremental gains without composite core premiums.
- Thermal Resistant Coating:Halogen-free formulations address REACH compliance requirements while extending conductor lifespan in corrosive environments. ECHA restrictions are forcing reformulation R&D overhead.
- Aluminum Stranding:Conventional multi-wire construction patterns balance flexibility and current carrying capacity. Railway electrification projects specify trapezoidal stranding for reduced ice and wind loading.
- High Strength Alloy:Zirconium-aluminum compositions enable continuous operation at elevated temperatures. German and French transmission procurement frameworks specify these alloys for carbon-accounting compliance.
Procurement at scale concentrates on Composite Core; incremental upgrade paths favor Annealing Process improvements.
Application:
Deployment context dictates conductor specification priorities, from inter-regional bulk power transfer to constrained urban corridors.
- Electric Transmission:High-voltage corridors require maximum ampacity within existing right-of-way constraints. Sub-Saharan greenfield grids in Kenya and Ethiopia specify HTLS conductors for initial backbone construction.
- Urban Distribution:Dense load centers demand thermal performance without structural tower expansion. Indian metropolitan utilities face acute land scarcity for corridor widening.
- Railway Electrification:Overhead catenary systems prioritize mechanical tension stability and aerodynamic performance. European high-speed networks specify composite core conductors for reduced sag at high temperatures.
- Industrial Power:Heavy manufacturing facilities require dedicated high-capacity feeds with minimal voltage drop. Aluminum Conductor Alloy Reinforced dominates this segment for cost-performance balance.
- Telecommunication Lines:Fiber-optic ground wire integration creates hybrid power-communication infrastructure. This application represents the fastest-growing trajectory as grid digitalization accelerates.
Volume leadership sits with Electric Transmission; steepest expansion trajectory belongs to Telecommunication Lines integration.
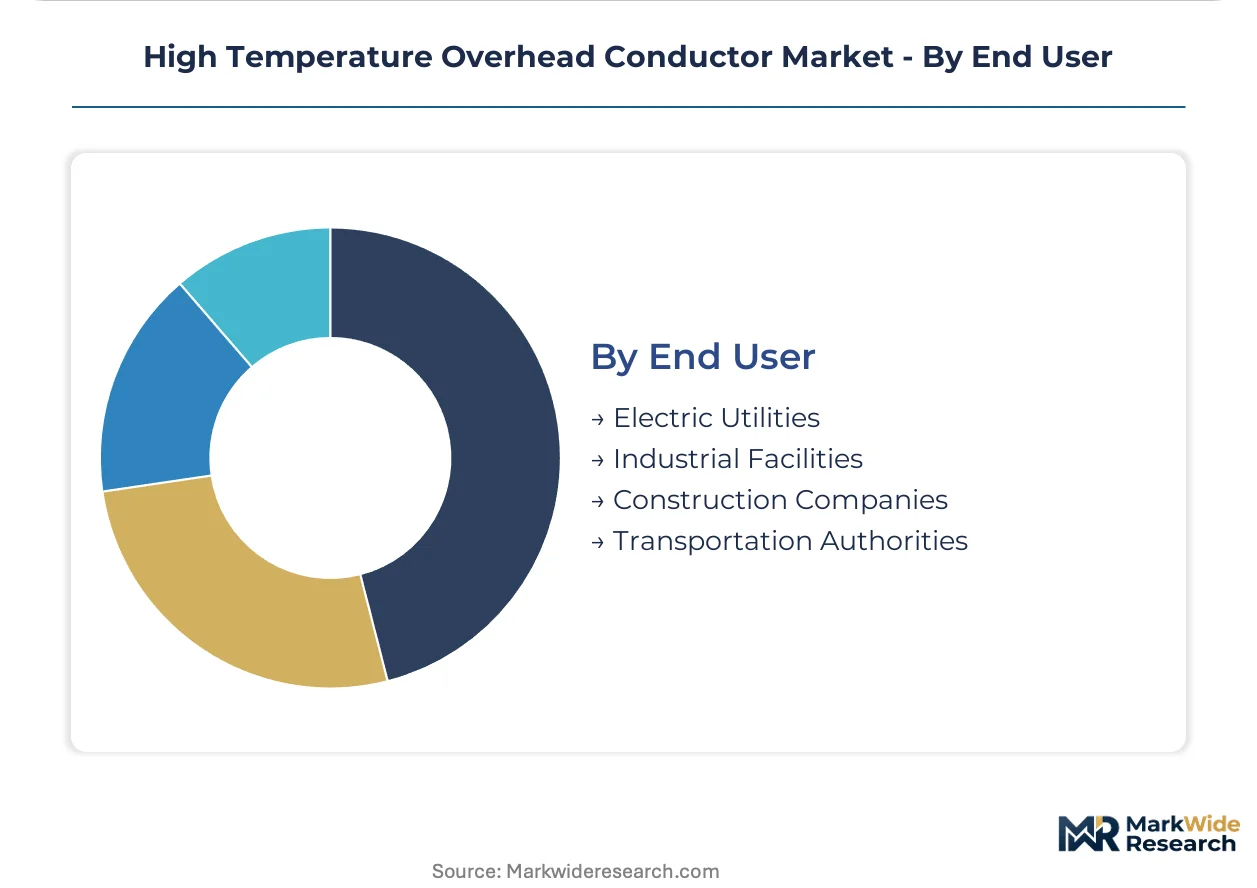
End User:
Procurement authority structures determine specification control, financing mechanisms, and contractor selection criteria.
- Electric Utilities:Vertically integrated grid operators balance regulatory compliance, asset lifecycle costs, and reliability obligations. India's state transmission utilities lack balance sheet capacity for self-financed expansion.
- Industrial Facilities:Captive power consumers prioritize rapid energization and predictable capital expenditure. Infrastructure funds are displacing traditional utility budgeting in procurement decision-making.
- Transportation Authorities:Railway and metro operators specify conductors for electrification timelines tied to fleet procurement schedules. Installation workforce scarcity limits contractor pool depth in emerging markets.
- Construction Companies:EPC contractors bundle conductor supply with installation services across South Asian markets. KEC International competes on this integrated offering.
Procurement volume concentrates with Electric Utilities; specification control is shifting toward Industrial Facilities and infrastructure fund sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State transmission utilities and infrastructure funds concentrate procurement authority in markets where renewable evacuation deadlines force immediate conductor decisions. Buyer archetypes split between vertically integrated grid operators lacking balance sheet capacity and project finance sponsors controlling EPC specifications.
India
CEA grid modernization mandates require thermal performance benchmarks for new transmission corridors in Rajasthan and Gujarat renewable zones. The Central Electricity Authority directive accelerates HTLS conductor specification without waiting for steel-reinforced alternatives to depreciate. State transmission utilities in Maharashtra and Karnataka face acute land scarcity for corridor widening, prioritizing ampacity gains within existing right-of-way.
Germany
TenneT and other transmission system operators specify hybrid aluminum-zirconium composite core conductors for North Sea offshore wind connection corridors. EU Green Deal carbon border adjustments filter import competitiveness for non-European manufacturers with coal-intensive aluminum smelting. Manufacturing clusters in North Rhine-Westphalia and Bavaria anchor European supply chain reconfiguration toward verified low-carbon supply chains.
United States
FERC interconnection queue reforms and state renewable portfolio standards drive ampacity upgrades across Texas and California transmission networks. Established ACSR inventory and contractor familiarity create switching friction despite lifecycle cost disadvantages for composite alternatives. Southwest utility procurement patterns favor maintenance programs over greenfield HTLS deployment.
China
Dual carbon goals and ultra-high voltage transmission expansion prioritize domestic composite core manufacturing scale-up for inter-regional renewable evacuation. MIIT industrial policy supports carbon fiber precursor supply chain localization to reduce Japanese and US petrochemical import dependence. Yangtze River Delta manufacturing clusters achieve production consistency that eliminates earlier field reliability concerns.
Brazil
National grid operator ONS specifications for Amazon basin renewable integration create demand for high-ampacity conductors without right-of-way expansion through dense forest corridors. ANEEL regulatory frameworks emphasize lifecycle cost economics over initial capital expenditure in transmission concession tenders. Industrial clusters in São Paulo and Minas Gerais state compete on EPC bundling for regional infrastructure funds.
High Temperature Overhead Conductor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement frameworks that weight performance guarantees and embedded emissions equally with unit cost. The vendor base organizes around three strategic archetypes: European manufacturers leveraging carbon-accounting compliance, Asian fabricators competing on EPC integration, and composite core technology specialists. Consolidation pressure concentrates among steel-reinforced incumbents facing switching friction from utility procurement inertia. Dominant competitive moves include backward integration into carbon fiber precursor supply and geographic expansion through infrastructure fund partnerships.
Within the technology-specialist tier, CTC Global Corporation exemplifies composite core positioning against conventional alternatives, while Nexans anchors European manufacturing footprint advantages in tender evaluations. KEC International occupies the EPC-integrated archetype bundling conductor supply with installation services. Prysmian Group and Southwire Company represent scale-driven multinational positioning across multiple regional procurement frameworks. Sumitomo Electric Industries and APAR Industries exemplify Asia-Pacific supply chain configurations serving cost-sensitive and premium segments respectively.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| CTC Global Corporation |
| Southwire Company |
| Sumitomo Electric Industries |
| APAR Industries |
| Lamifil |
| ZTT Group |
| KEC International |
| Others |
Pricing and Supply Chain Analysis
Japanese and US petrochemical producers' concentration in carbon fiber precursor supply anchors margin capture upstream, while downstream conductor manufacturers face volatile acrylonitrile pricing and export licensing friction that compresses fabrication economics.
Pricing Analysis
Performance tier certification (CE marking for European tenders, CEA thermal benchmarks for Indian procurement) creates the primary spread between premium composite core conductors and standard steel-reinforced alternatives. Project-based long-term offtake contracts dominate utility procurement, with price differentiation hinging on embedded carbon verification and installation service bundling. Cost compression in the standard tier is intensifying because Indian state transmission utilities lack balance sheet capacity to absorb lifecycle-cost premiums. Industrial facility sponsors show least price sensitivity, prioritizing rapid energization timelines over unit cost.
Supply Chain Analysis
Export controls on carbon fiber manufacturing technology limit precursor flow from US and Japanese suppliers to Chinese fabricators, fragmenting global composite core production networks. Manufacturing concentrates in China, India, and Germany, with raw material dependencies on acrylonitrile, high-purity aluminum, and zirconium alloying agents. Single-source vulnerability in Japanese carbon fiber feedstock exposes conductor makers to supply disruption. Distribution runs through EPC contractors bundling installation with conductor supply across South Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration and dynamic line rating services are expanding faster than hardware sales as utilities seek to extract additional ampacity from existing HTLS installations without physical upgrade.
For Market Incumbents: Insulate core technology positions through backward integration into carbon fiber precursor supply and captive manufacturing of high-strength aluminum alloys. CEA mandates in India accelerate procurement cycles that favor established suppliers with proven field reliability records. Certification investment in REACH-compliant halogen-free coating formulations defends European tender access against reformulation-lagged competitors.
For New Entrants and Emerging Players: Sub-Saharan African greenfield grids in Kenya and Ethiopia offer the most penetrable entry points, bypassing legacy steel-reinforced incumbency entirely. Railway electrification corridors in Southeast Asia present secondary white-space for composite core conductors requiring distinct handling protocols. Partner with infrastructure funds specifying conductor technologies directly in EPC contracts to circumvent utility procurement inertia.
For Investors and Strategic Acquirers: Capital is best deployed toward composite core technology specialists with verified low-carbon supply chains and established utility reference installations. The five-to-ten-year viability window favors manufacturers achieving production consistency at scale over laboratory-stage material innovators. Watch for EU Carbon Border Adjustment Mechanism enforcement tightening as the inflection signal reshaping import competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive acrylonitrile sourcing insulates CTC Global and Nexans from Japanese petrochemical export licensing friction. |
| CEA Certification Fast-Track Program | Accelerated thermal benchmark approval captures Rajasthan and Gujarat renewable corridor procurement ahead of competitors. |
| Digital Twin Service Layer Launch | Real-time thermal monitoring subscriptions extract recurring revenue from existing HTLS installations at TenneT and National Grid. |
| Sub-Saharan EPC Partnership | Joint ventures with Kenyan and Ethiopian transmission developers bypass legacy contractor pools unfamiliar with composite handling protocols. |
| Halogen-Free Coating Reformulation | REACH-compliant thermal resistant formulations maintain European tender eligibility as ECHA restrictions phase in. |
Research Methodology
Desk research of customs trade data, CEA tender documentation, and FERC interconnection queue filings preceded structured interviews with utility planning officers, EPC contractor procurement leads, composite core manufacturing engineers, and grid operator asset managers. Primary fieldwork across Indian state transmission utilities, German TSOs, and Chinese MIIT industrial policy units combined with secondary validation from IEC standards documentation and IEA transmission investment databases. Bottom-up project pipeline aggregation triangulated against top-down regulatory mandate analysis.
The analytical framework held carbon border adjustment implementation schedules and CEA thermal benchmark enforcement as fixed conditions across the projection horizon, varying renewable evacuation project timelines and composite core manufacturing scale-up rates. Segmentation modeling spanned product type, core technology, application voltage class, and procurement authority archetype. CAGRs derived from unit demand projections weighted by corridor length and ampacity upgrade intensity, with aluminum alloy pricing and carbon fiber precursor supply elasticity as key variable inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by steel-reinforced specialists would shift competitive outcomes. Material shifts in EU CBAM carbon intensity thresholds or Indian PLI scheme extensions for domestic composite manufacturing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Oil Pipeline Infrastructure Market