
 High Voltage Distribution Substation Market | 2026-2036
High Voltage Distribution Substation Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Distribution Substation Market Insights
Data center load growth is decoupling from traditional utility-led substation procurement patterns. ABB leverages its gas-insulated portfolio to capture premium contracts in urban density zones. Siemens sustains technology leadership through digital twin integration for substation automation. Hitachi Energy anchors its position in renewable interconnection projects across multiple voltage tiers.
A high voltage distribution substation steps down transmission-level voltages for regional distribution networks, typically handling 69 kV to 500 kV through transformer arrays, switchgear assemblies, and protection relay systems designed for continuous thermal cycling. Gas insulated substations command margin premiums where land scarcity and environmental constraints limit footprint expansion, while air insulated configurations retain cost advantages in rural and semi-urban deployments. Circuit breakers and transformers absorb the largest component spend shares, with surge arrester demand tracking lightning exposure geography and grid reliability standards.
The EU Green Deal and F-Gas Regulation constrain sulfur hexafluoride deployment, compelling manufacturers to accelerate fluoronitrile and vacuum interrupter alternatives. India's CEA mandates and BIS certification requirements shape product qualification pathways for equipment suppliers entering that procurement pipeline. Stakeholders must monitor regulatory phase-out timelines against their existing SF6 inventory positions and alternative technology readiness levels.
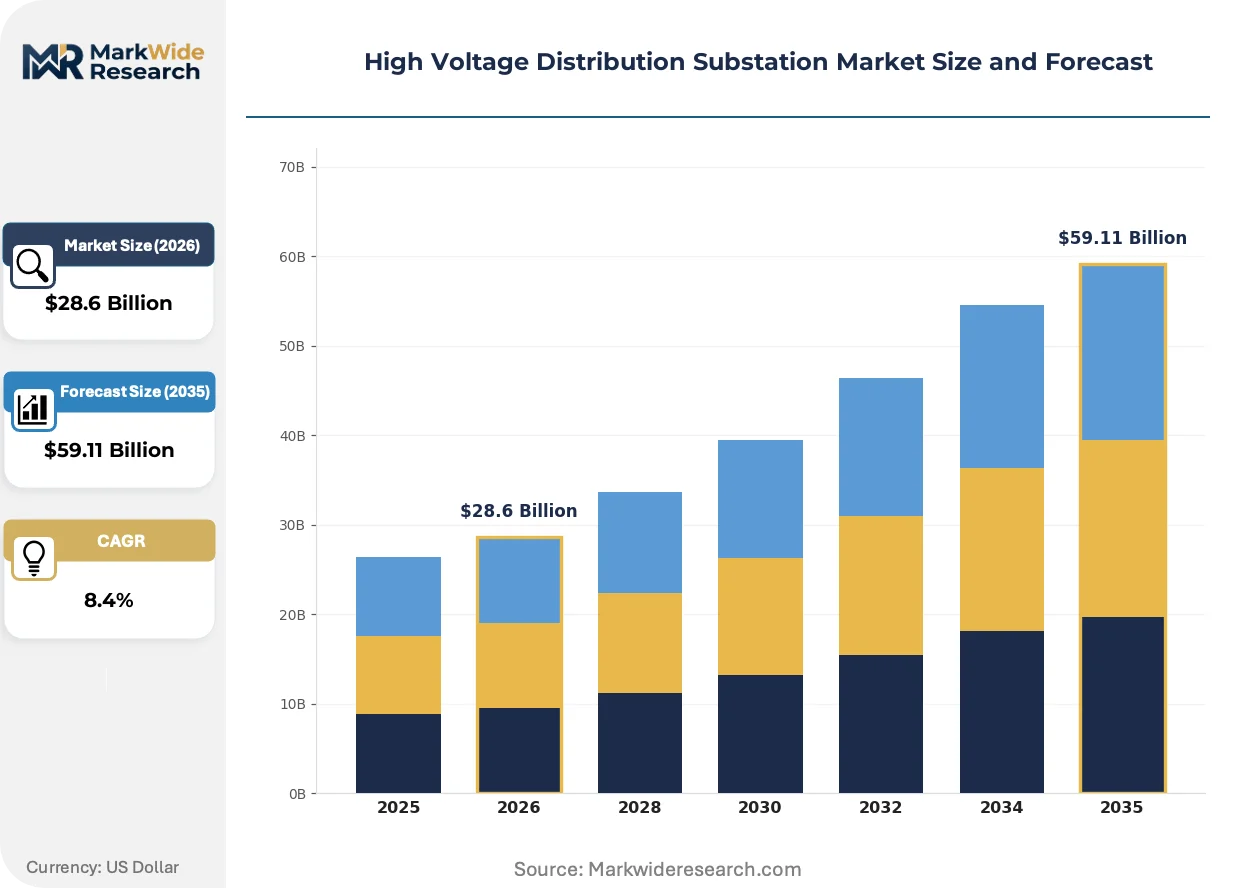
Market Dynamics
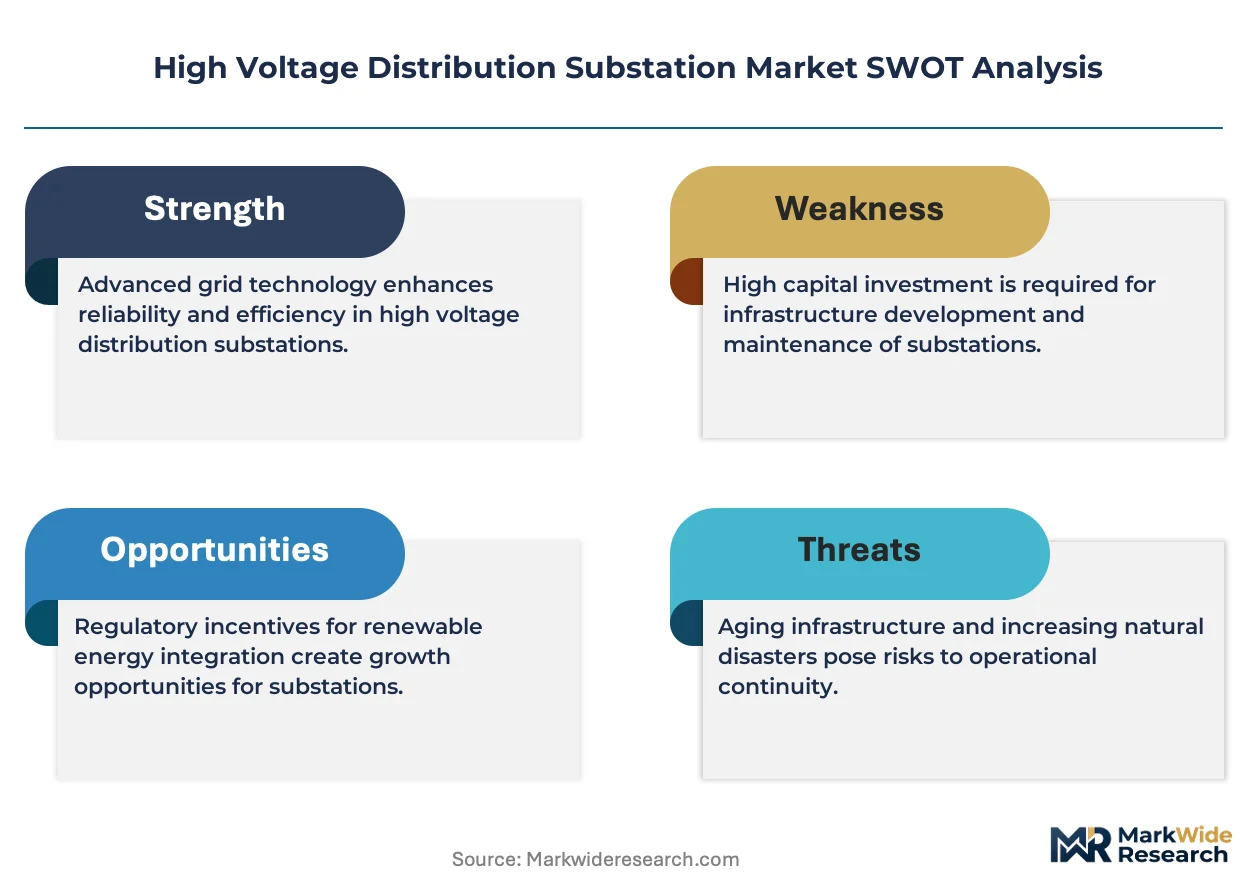
SF6 phase-out mandates under the EU F-Gas Regulation are forcing immediate technology transitions across transformer and switchgear portfolios, compressing product development cycles while opening premium positioning for fluoronitrile and vacuum interrupter alternatives.
Growth Catalysts
- Data center power density escalation:Hyperscale operators in Virginia, Singapore, and Frankfurt are procuring dedicated 345 kV substations to support AI training clusters exceeding 100 MW per facility.
- India's rural electrification pipeline:CEA-mandated smart grid integration under the RDSS scheme requires thousands of new 33 kV and 66 kV substations across Bihar, Uttar Pradesh, and Madhya Pradesh.
- EU Green Deal grid modernization:Member state NREAP targets for 2030 renewable interconnection are accelerating replacement of air-insulated substations with compact gas-insulated configurations in urban density zones.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Transformer core material costs fluctuate with energy-intensive smelting economics, squeezing OEM margins on fixed-price utility contracts.
- SF6 inventory stranding risk:European utilities face accelerated write-downs on existing sulfur hexafluoride switchgear as fluoronitrile alternatives remain supply-constrained from single-source chemical producers.
- Skilled substation commissioning engineer scarcity:Specialized protection relay programming and high-voltage testing expertise concentrates in aging workforces across Germany, Japan, and the US Northeast.
Strategic Opportunities
- Modular substation standardization:Factory-integrated 145 kV GIS skids are penetrating mining and oil sands operations in Western Australia and Alberta where site construction windows are compressed.
- Digital twin integration:Siemens and ABB are converging asset performance management platforms with SCADA architectures, creating recurring software revenue streams alongside hardware procurement.
- India PLI scheme localization:Component manufacturing incentives for power transformers and circuit breakers are attracting joint ventures to Gujarat and Tamil Nadu industrial corridors.
Industry Challenges
- IEC 61850 implementation complexity:Multi-vendor interoperability testing for process bus architectures extends commissioning timelines by 4-8 months on greenfield substation projects.
- High-voltage cable termination skill gaps:220 kV and 400 kV XLPE jointing expertise remains concentrated among a shrinking pool of certified technicians in France, South Korea, and California.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Distribution Substation Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Substation Type: Gas Insulated, Air Insulated, Hybrid, Compact, Mobile Voltage Level: 69 kV, 132 kV, 230 kV, 345 kV, 500 kV End User Industry: Electric Utilities, Renewable Projects, Data Centers, Mining Facilities, Manufacturing Plants Component: Transformers, Circuit Breakers, Isolators, Surge Arresters, Control Panels |
| Companies Covered | ABB, Siemens, Schneider Electric, Hitachi Energy, General Electric, Mitsubishi Electric, Eaton, Toshiba, Hyundai Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Distribution Substation Market Trends and Innovations
Electrification intensity across heavy industry and digital infrastructure is compressing substation procurement cycles while elevating automation and footprint efficiency as primary design criteria.
Fluorinated gas alternatives are expanding into transmission-class switchgear portfolios as manufacturers accelerate vacuum interrupter scaling for 145 kV and 245 kV ratings. European utilities in Denmark and the Netherlands are piloting these configurations ahead of 2030 F-Gas bans. The technology is expanding into premium urban substation contracts where land scarcity and environmental permitting constrain conventional air-insulated designs.
The EU F-Gas Regulation mandates 80% SF6 emissions reduction by 2030, forcing immediate R&D redirection toward fluoronitrile-diluted mixtures and pure air insulation. Equipment manufacturers face dual-track certification requirements under CENELEC and IEC frameworks. GIS suppliers with mature alternative gas portfolios capture disproportionate share in German and French utility tenders where environmental scoring dominates award criteria.
Utility procurement departments are consolidating vendor relationships around full-lifecycle service agreements spanning installation, digital monitoring, and predictive maintenance. Equipment suppliers displace traditional EPC intermediaries in Scandinavian and Benelux markets. Data center operators in Northern Virginia and Amsterdam Schiphol corridor increasingly specify 20-year service bundles with guaranteed availability metrics over capital-purchase models.
High Voltage Distribution Substation Market Segmentation
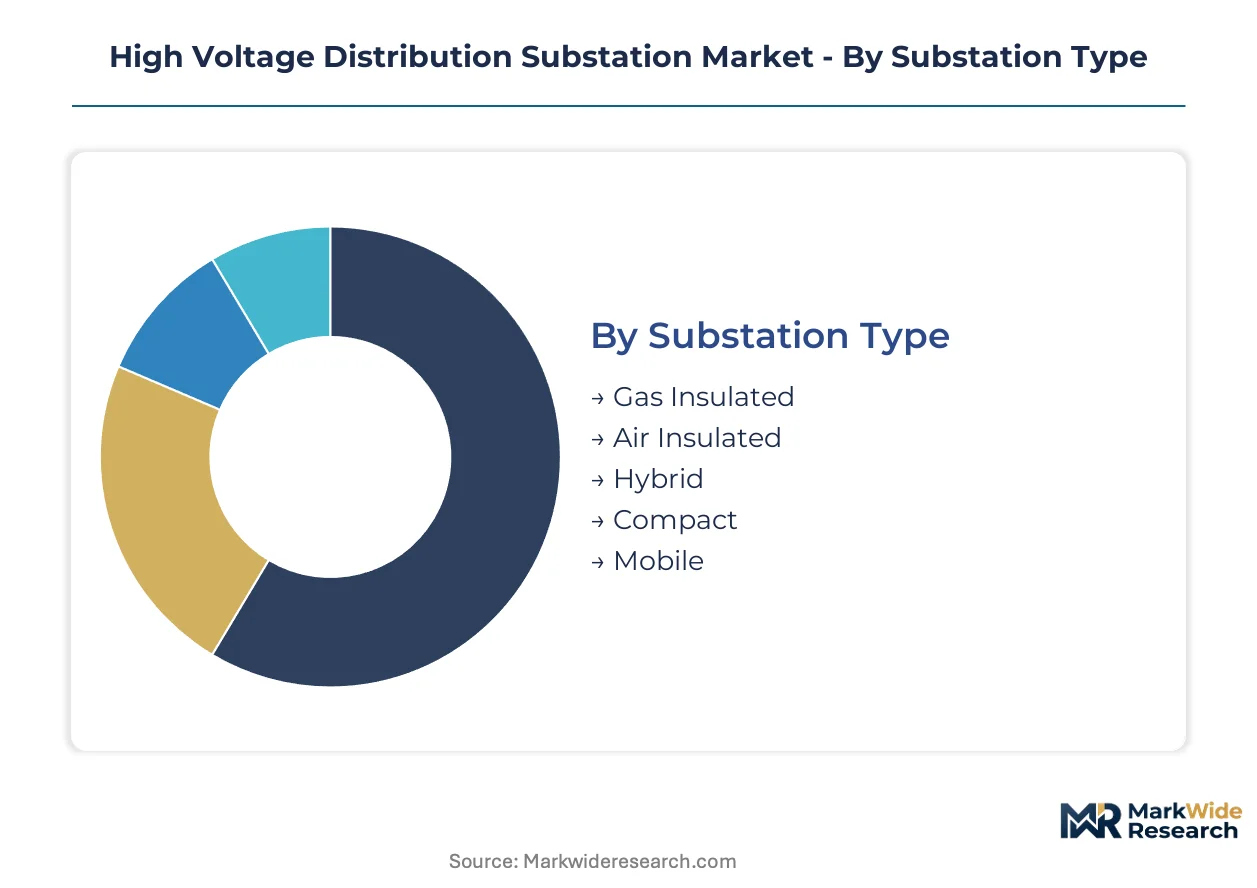
Segmentation in high voltage distribution substations reveals how technology choices, voltage requirements, and end-use applications create distinct procurement ecosystems. Equipment specifications diverge sharply between urban density constraints and rural expansion projects. Component-level decisions on transformers versus switchgear drive fundamentally different supplier relationships and lifecycle economics.
Substation Type:
Volume concentration favors established air-insulated configurations, while premium positioning accrues to gas-insulated systems where land scarcity commands technology premiums.
- Gas Insulated:Sulfur hexafluoride or fluoronitrile-filled enclosures compress footprint by 90% versus air-insulated equivalents. Demand clusters in Frankfurt, Singapore, and Northern Virginia data center corridors where substation land costs exceed equipment capital expenditure. EU F-Gas Regulation mandates are accelerating fluoronitrile adoption ahead of 2030 phase-out deadlines.
- Air Insulated:Open-air busbar and breaker arrangements dominate rural electrification programs across Bihar and Uttar Pradesh under India's RDSS scheme. Copper busbar and porcelain insulator supply chains remain localized to control logistics costs on distributed projects.
- Hybrid:Combines gas-insulated switchgear with air-insulated transformers to balance footprint and capital efficiency.
- Compact:Factory-integrated skids target mining operations in Western Australia with compressed construction windows.
- Mobile:Trailer-mounted configurations serve emergency restoration and temporary load scenarios.
Today's leader: Air Insulated. Tomorrow's challenger: Gas Insulated.
Voltage Level:
Application intensity determines tiering — bulk transmission interfaces versus distribution handoff points create divergent equipment specifications and supplier qualifications.
- 69 kV:Distribution network entry points for municipal utilities and industrial parks. Demand concentrates in India's rural electrification pipeline where 33/66 kV stepping dominates.
- 132 kV:Regional sub-transmission backbone standard across European and Indian grid architectures. Procurement volume reflects renewable interconnection mandates under EU member state NREAP targets.
- 230 kV:Metropolitan ring networks and large industrial complex supply. German utilities specify these ratings for urban density zone reinforcement.
- 345 kV:Hyperscale data center operators in Virginia and Amsterdam Schiphol corridor procure dedicated substations at this tier to support AI training clusters exceeding 100 MW per facility.
- 500 kV:Bulk power transfer interfaces between transmission and distribution territories. Equipment qualification cycles extend 18-24 months due to specialized insulation coordination requirements.
Mid-voltage tiers anchor current procurement volume. Upper tiers capture steepest expansion trajectory from data center electrification.
End User Industry:
Customer archetype segmentation exposes divergent buying behaviors — regulated utilities prioritize lifecycle cost, while private infrastructure operators emphasize speed-to-energization.
- Electric Utilities:Traditional regulated entities with standardized specifications and extended vendor qualification processes. Grid modernization mandates under EU Green Deal are compressing replacement cycles.
- Renewable Projects:Wind and solar interconnection requires specialized transformer tap configurations for variable generation profiles. Offshore wind clusters in Denmark and the Netherlands specify compact GIS configurations for platform space constraints.
- Data Centers:Hyperscale operators are decoupling from traditional utility-led procurement, specifying dedicated substations with 20-year service agreements and guaranteed availability metrics.
- Mining Facilities:Remote operations in Western Australia and Alberta favor modular skid-mounted solutions with minimal site construction.
- Manufacturing Plants:Heavy industrial electrification in Gujarat and Tamil Nadu industrial corridors drives demand for high-reliability configurations.
Data centers are displacing utilities as the fastest-growing customer segment. Renewables represent the most technically demanding application set.
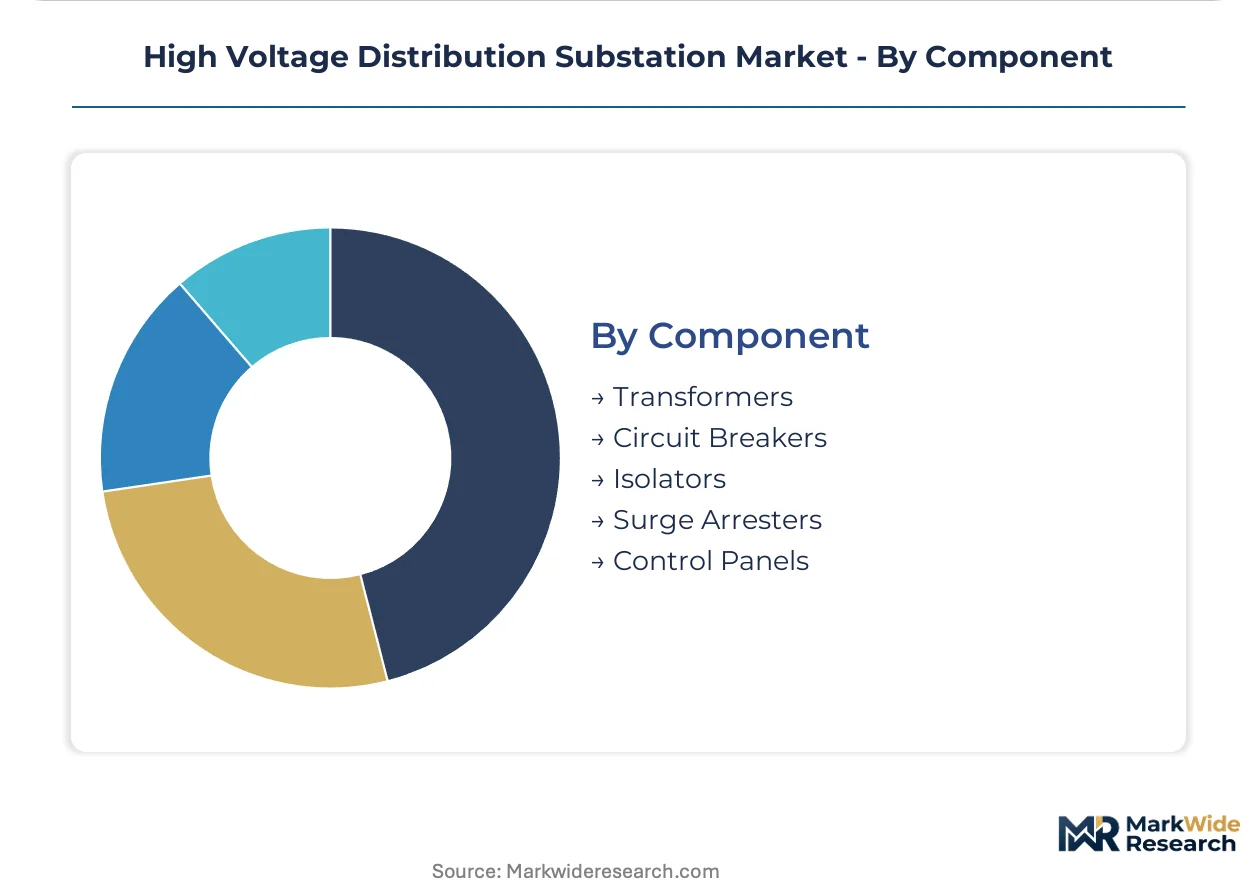
Component:
Capital allocation patterns concentrate spend on energy conversion and interruption functions, with protection and control systems capturing incremental value through digitalization.
- Transformers:Grain-oriented electrical steel cores with mineral oil or ester fluid insulation absorb the largest single component share. Copper winding costs fluctuate with smelting energy economics, squeezing OEM margins on fixed-price contracts.
- Circuit Breakers:Vacuum interrupters and SF6 alternatives dominate 145 kV and below ratings. European manufacturers accelerate fluoronitrile scaling ahead of F-Gas Regulation deadlines.
- Isolators:Mechanical disconnect switches provide visible isolation points for maintenance operations.
- Surge Arresters:Metal-oxide varistor demand tracks lightning exposure geography and grid reliability standards in tropical and subtropical installations.
- Control Panels:IEC 61850-compliant protection relay assemblies are converging with asset performance management platforms for predictive maintenance revenue streams.
Transformers and circuit breakers command parallel primacy in capital allocation. Control panels are gaining share fastest through digital twin integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting high voltage substation manufacturing toward jurisdictions with phased environmental compliance timelines, as European F-Gas mandates accelerate production migration to India and Southeast Asia where certification pathways remain more permissive.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are procuring dedicated 345 kV substations to support AI training clusters exceeding 100 MW per facility. FERC Order 2222 and state-level interconnection queue reforms are compressing utility procurement cycles. Dominion Energy and Duke Energy service territories anchor the fastest-growing substation procurement corridor.
Germany
Grid modernization mandates under the EU Green Deal are accelerating replacement of aging air-insulated substations with compact gas-insulated configurations in urban density zones. The F-Gas Regulation compels immediate technology transitions toward fluoronitrile alternatives. TenneT and 50Hertz transmission zones concentrate GIS deployment in Hamburg and Frankfurt metropolitan rings.
India
Rural electrification and renewable integration projects require thousands of new 33 kV and 66 kV substations across Bihar, Uttar Pradesh, and Madhya Pradesh. CEA mandates and BIS certification requirements shape product qualification pathways for equipment suppliers. Gujarat and Tamil Nadu industrial corridors attract joint ventures under PLI scheme localization incentives.
China
State Grid Corporation's ultra-high voltage expansion program sustains domestic demand for 500 kV and 1000 kV substation components. Dual carbon goals under the 14th Five-Year Plan are accelerating SF6 alternative R&D investments. Yangtze River Delta manufacturing clusters supply transformer and switchgear assemblies for Belt and Road infrastructure exports.
Netherlands
Offshore wind interconnection projects in the North Sea require compact GIS configurations for platform space constraints. The F-Gas Regulation mandates 80% SF6 emissions reduction by 2030, forcing immediate pilot deployments of vacuum interrupters at 145 kV and 245 kV ratings. Rotterdam and Eindhoven anchor the Benelux smart grid modernization pipeline.
High Voltage Distribution Substation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical conglomerates commanding premium positioning in gas-insulated systems while regional fabricators capture cost-sensitive air-insulated procurement in emerging markets. The vendor base clusters around three strategic archetypes: diversified industrial technology groups with full-lifecycle service capabilities, pure-play power equipment specialists focused on transformer or switchgear verticals, and state-affiliated national champions serving protected domestic procurement pipelines. Competitive dynamics center on M&A activity consolidating digital twin and predictive maintenance software assets, alongside capacity expansion into India and Vietnam to exploit regulatory-arbitrage manufacturing advantages.
Within the diversified technology group tier, ABB, Siemens, and Hitachi Energy exemplify the integrated service model converging hardware procurement with recurring software revenue streams. These Switzerland-based, Germany-based, and Japan-based entities occupy positions where environmental scoring and full-lifecycle contracting dominate utility tender award criteria. Their archetype represents the premium-tier positioning that data center operators increasingly specify for 20-year availability guarantees.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Hitachi Energy |
| General Electric |
| Mitsubishi Electric |
| Eaton |
| Toshiba |
| Hyundai Electric |
| Others |
Pricing and Supply Chain Analysis
Certified high-voltage cable termination engineers concentrated in France, South Korea, and California command wage premiums that compress margins on 220 kV and 400 kV XLPE jointing contracts, widening the spread between premium GIS configurations and standard AIS deployments. Labor-cost differentials between these specialized technicians and general commissioning crews in India or Southeast Asia feed directly into three-tier pricing stratification across global procurement.
Pricing Analysis
Distributor margins on transformer and switchgear assemblies typically absorb 8-12 points before utility or data center offtake, with direct-to-OEM channels for hyperscale buyers compressing this layer through 20-year service bundling. Pricing stratifies across fluoronitrile-filled GIS premiums, conventional SF6 legacy systems, and air-insulated rural configurations, with certification grade under EU F-Gas Regulation timelines and volume scale driving tier separation. Cost compression in standard AIS tiers is intensifying because copper and grain-oriented electrical steel volatility squeezes fixed-price OEM contracts. Data center operators exhibit lowest price sensitivity, prioritizing guaranteed availability metrics over capital expenditure, while Indian rural electrification programs under RDSS scheme procurement show highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center demand in Northern Virginia and Amsterdam Schiphol corridor, bypassing traditional utility procurement intermediaries. Manufacturing concentrates in China for transformer core assemblies, Germany for precision switchgear components, and India for copper busbar fabrication under PLI scheme localization. Raw material dependencies rest on grain-oriented electrical steel from Nippon Steel and POSCO mills, copper cathodes from Chilean and Indonesian smelters, and fluoronitrile gas mixtures from single-source chemical producers. Single-source vulnerability in alternative SF6 gas supply creates procurement risk for European GIS manufacturers facing 2030 F-Gas Regulation deadlines. Distribution runs through EPC contractors for utility projects, factory-direct skids for mining operations, and integrated service agreements for data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where data center load growth is displacing traditional utility procurement toward premium GIS configurations with 20-year availability guarantees.
For Market Incumbents: Cement technology leadership in fluoronitrile and vacuum interrupter portfolios ahead of EU F-Gas Regulation phase-out deadlines, while capturing recurring software revenue through digital twin integration with SCADA architectures. Capacity expansion into Gujarat and Tamil Nadu industrial corridors exploits regulatory-arbitrage manufacturing advantages against European compliance costs. Threat of stranded SF6 inventory across aging European utility fleets creates urgency for alternative gas certification investment. For New Entrants and Emerging Players: Modular skid-mounted substation buyers in Western Australian mining and Albertan oil sands operations represent underserved demand with compressed construction windows and limited incumbent service presence. White-space exists in 145 kV factory-integrated GIS for remote industrial electrification, and in predictive maintenance software layering atop third-party hardware installations. Go-to-market through EPC contractor partnerships bypasses direct utility qualification barriers. For Investors and Strategic Acquirers: Electrical conglomerates with full-lifecycle service capabilities are the most active acquirer in this space, consolidating digital twin and asset performance management software assets to displace traditional hardware margins with recurring revenue streams. Long-term viability over a 5-10 year horizon rests on exposure to data center electrification intensity and India rural grid expansion rather than mature European replacement cycles. Acquisition target archetype: mid-cap specialists with IEC 61850-compliant protection relay platforms and established utility qualification pathways. Signal to watch: hyperscale data center announcements exceeding 100 MW per facility in new geographies.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorinated Gas Alternative R&D Acceleration | EU F-Gas Regulation mandates 80% SF6 emissions reduction by 2030, forcing immediate technology transitions. |
| India PLI Scheme Localization | Component manufacturing incentives for power transformers attract joint ventures to Gujarat and Tamil Nadu corridors. |
| Digital Twin Platform Integration | Siemens and ABB converge asset performance management with SCADA architectures for recurring software revenue. |
| Modular Substation Standardization | Factory-integrated 145 kV GIS skids penetrate mining operations in Western Australia with compressed construction windows. |
| Full-Lifecycle Service Agreement Expansion | Equipment suppliers displace EPC intermediaries in Scandinavian markets through 20-year availability guarantees. |
Research Methodology
Multiple input streams — substation procurement officer interviews, EPC contractor project databases, and equipment manufacturer order backlogs — were reconciled against secondary validation from FERC interconnection queue filings, CEA RDSS scheme disbursement records, and EU Green Deal NREAP target documentation. Primary discussions with utility planning officers, data center infrastructure heads, protection relay programmers, and grid modernization consultants informed demand-side assumptions. Bottom-up unit economics on transformer and switchgear assemblies were triangulated with top-down grid investment forecasts across the analysis window.
Historical capital expenditure patterns were cross-referenced against panel input from transmission planners and OEM sales directors to anchor growth trajectories. Segmentation modeling spanned substation type, voltage tier, end-use industry, and component category, with CAGRs derived from regression against electrification intensity indicators and regulatory compliance timelines. Forecast inputs incorporated data center power density escalation curves and India rural electrification pipeline visibility under CEA mandates.
Underlying measurement precision varies by segment; data center and utility procurement carry tighter precision than mining and industrial project pipelines subject to commodity price volatility. Forecasts reflect assumptions on F-Gas Regulation enforcement timelines, fluoronitrile supply scaling, and skilled technician workforce expansion. Periodic stress-testing of base assumptions is recommended against regulatory acceleration or supply chain disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Electricity Transmission Infrastructure Market