
 Norway Renewable Energy Market | 2026-2036
Norway Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Renewable Energy Market Analytics
A capital-intensity divergence between integrated energy majors and pure-play developers is bifurcating competitive dynamics in Norwegian renewables. Equinor ASA leverages its offshore engineering heritage to dominate floating wind pre-development. Statkraft sustains its position through vertical control over hydropower cascades and grid balancing services. Nel ASA specializes in electrolyzer manufacturing, anchoring the hydrogen export corridor to continental Europe.
Norway renewable energy encompasses electricity and heat derived from naturally replenishing sources including hydropower, wind, solar photovoltaic, and biomass conversion systems, typically harnessed through turbines, photovoltaic cells, or thermal collectors with capacities ranging from residential kilowatt-scale to utility-scale gigawatt installations. Hydropower turbines constitute the historical backbone, supplying baseline load through reservoir-fed systems with rapid ramping capability. Wind turbines represent the fastest-expanding technology segment, driven by deep-water floating platforms off Norway's western coast. Solar panels occupy a niche but growing position in distributed commercial rooftops, while energy storage systems command emerging margin pools as grid balancing requirements intensify.
EU Green Deal implementation through the EEA agreement shapes Norwegian renewable deployment timelines, while the Norwegian Water Resources and Energy Directorate (NVE) governs concession licensing and grid access tariffs. BIS-aligned technical standards for offshore substations and the country's dual carbon goals under the Climate Change Act are tightening domestic content requirements. Stakeholders must monitor floating wind lease round outcomes against hydrogen pipeline routing decisions to calibrate capital allocation between electrons and molecules.
Market Dynamics
Floating offshore wind technology is decomposing Norway's historical hydropower-centric generation stack, forcing capital reallocation toward Vestland county's deep-water lease zones and electrolyzer-linked export infrastructure.
Growth Catalysts
- EU Green Deal via EEA:Binding renewable targets transmitted through the European Economic Area agreement mandate Norwegian grid interconnection upgrades, accelerating offshore wind concession timelines.
- Floating platform engineering:Proprietary semi-submersible foundation designs unlock water depths exceeding 60 meters, expanding exploitable seabed area off Norway's western fjord coastline.
- Green hydrogen export corridors:German and Dutch offtake agreements for renewable hydrogen molecules pull electrolyzer capacity buildout along Norway's North Sea pipeline routes.
Market Restraints
- Grid reinforcement bottlenecks:Statnett's transmission upgrade backlog delays floating wind farm energization, extending project cash conversion cycles.
- Specialized vessel scarcity:Heavy-lift installation ships for floating foundation deployment concentrate among Asian yards, creating Norwegian project timeline vulnerability.
- Domestic content thresholds:NVE concession licensing increasingly mandates local supply chain participation, inflating procurement costs for developers without established Norwegian industrial partnerships.
Strategic Opportunities
- Northern Norway onshore wind:Finnmark and Troms counties hold untapped wind resource potential with lower seabed competition than southern lease zones.
- Power-to-X industrial integration:Ammonia and e-fuel offtake contracts from German chemical conglomerates create anchor demand for electrolyzer clusters at Mongstad and Kollsnes.
- Battery storage arbitrage:Intraday price volatility in the Nord Pool spot market rewards grid-connected battery systems for frequency regulation services.
Industry Challenges
- Subsea cable installation expertise:Floating wind export cable burial requires specialized marine engineering skills scarce in the Norwegian labor market.
- Environmental impact assessment duration:NVE's mandatory seabed ecosystem reviews and reindeer herding corridor consultations extend pre-construction phases unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Renewable Energy Market |
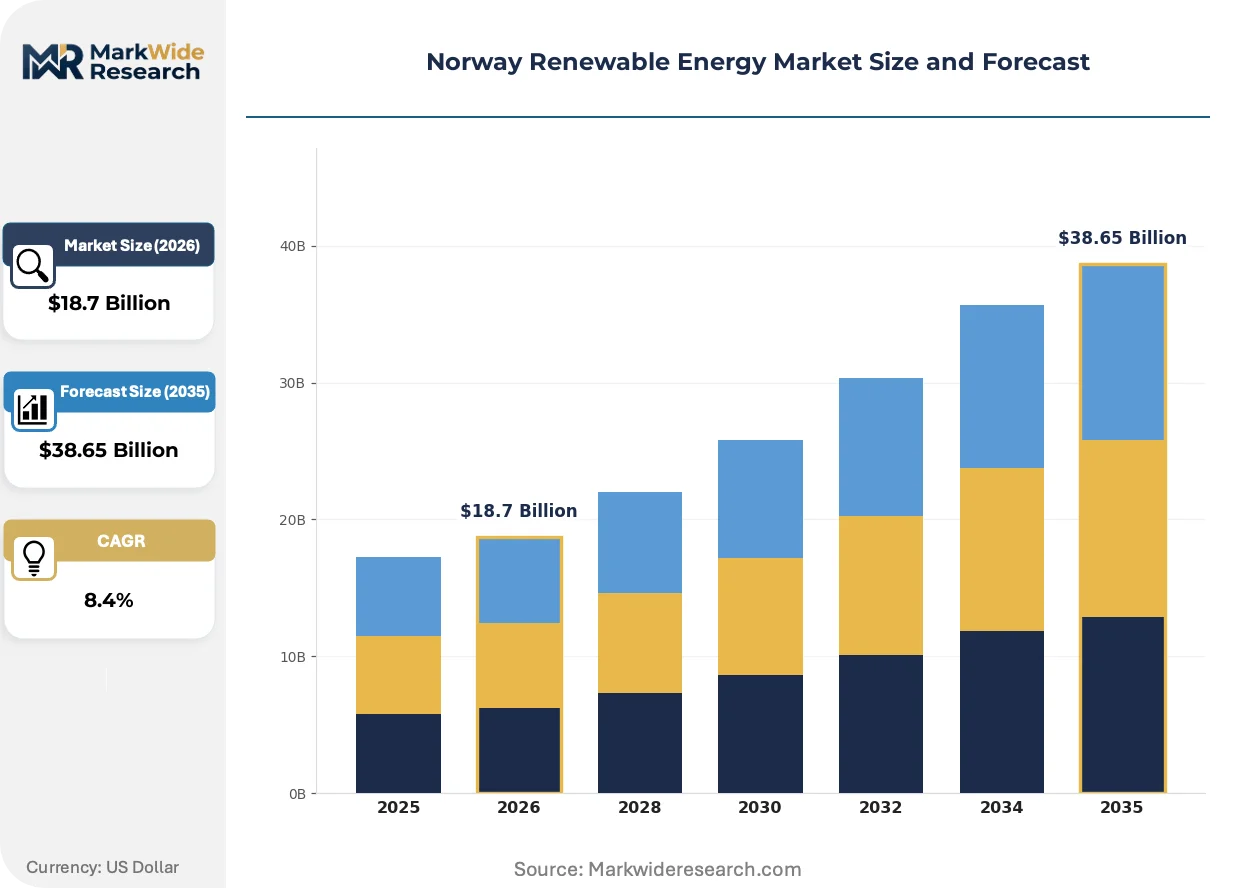
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Hydropower, Wind Power, Solar Power, Biomass Technology: Hydropower Turbines, Wind Turbines, Solar Panels, Energy Storage Systems Application: Electricity Generation, Heating, Transportation, Industrial Use End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Aker Horizons, Siemens Gamesa Renewable Energy S.A., Statkraft, Agder Energi AS, Scatec ASA, Equinor ASA, Berkshire Hathaway Energy Co, Nel ASA, Norsk Hydro ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Renewable Energy Market Evolving Landscape
Technology convergence between offshore wind and hydrogen electrolysis is restructuring project finance models around integrated molecule-electron export platforms rather than pure power generation assets.
Concrete-based floating substructures are decomposing the steel-dominated cost structure of offshore wind foundations. Equinor's Hywind installations demonstrate mass-producible concrete hulls that reduce fabrication expenditure and enable local casting yards in Ålesund and Stavanger. This technology is compressing foundation delivery schedules from 24 months to 14 months while opening supplier participation to civil engineering contractors without marine steel fabrication heritage.
NVE's revised offshore licensing framework tightens seabed ecosystem protection mandates, requiring developers to submit cumulative impact assessments spanning multiple adjacent lease blocks. The regulation forces coordinated environmental monitoring across competing project consortia, increasing pre-development overhead but reducing litigation risk from fishing industry challengers. Vestland county developers now pool marine biology survey resources through joint industry working groups.
Corporate power purchase agreements displace traditional utility offtake contracts as the dominant revenue structure for new Norwegian renewable capacity. Data center operators in Oslo and Stavanger municipalities now contract directly with wind and solar developers, bypassing Statkraft's historical merchant intermediation role. This bilateral contracting trend concentrates in Rogaland county where hyperscale server facility load growth outpaces grid transmission expansion.
Norway Renewable Energy Market Segmentation
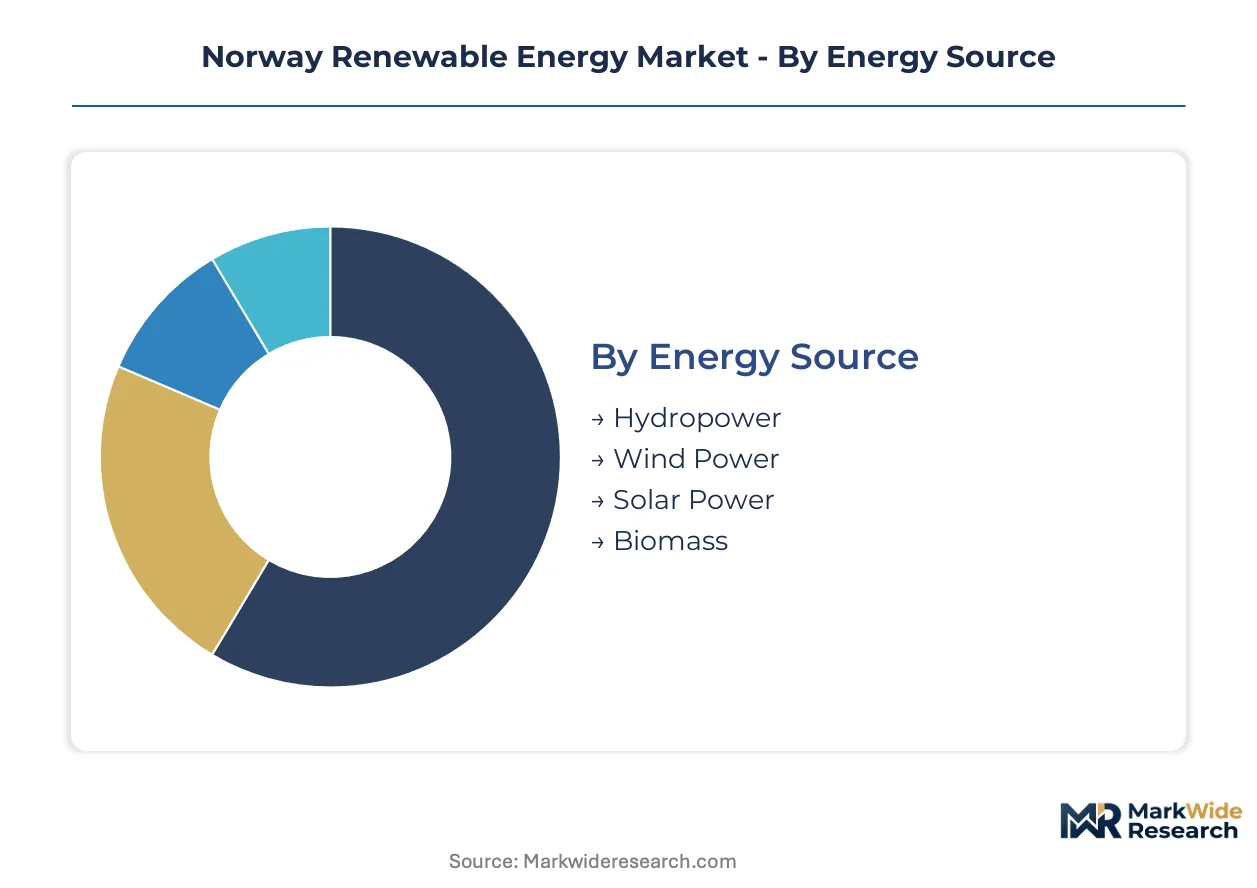
Segmentation in Norwegian renewables reveals how capital flows bifurcate between mature hydropower infrastructure and emerging floating offshore wind platforms. Understanding these divisions exposes where grid interconnection bottlenecks concentrate and where hydrogen export corridors anchor demand.
Energy Source:
Channel distribution varies sharply by source maturity — hydropower flows through regulated utility procurement while wind and solar attract corporate PPAs and export-linked offtake.
- Hydropower:Reservoir-fed turbine cascades deliver baseline load with rapid ramping capability for grid balancing. Demand concentrates in domestic industrial supply contracts and Nordic spot market arbitrage, constrained by NVE concession renewal timelines and environmental flow requirements.
- Wind Power:Floating offshore platforms in Vestland county exploit water depths exceeding 60 meters through semi-submersible foundations. Development clusters around Mongstad and Kollsnes industrial zones where electrolyzer integration enables molecule export to German chemical offtakers.
- Solar Power:Distributed commercial rooftop installations in Oslo and Stavanger municipalities serve data center load growth bypassing Statkraft merchant intermediation.
- Biomass:Forest residue conversion systems supply district heating networks in Trøndelag and Innlandet counties with stable feedstock from managed spruce stands.
Hydropower dominates installed base. Wind power is where expansion concentrates.
Technology:
Cost tier stratification separates proven turbine hardware from emerging storage and floating foundation systems requiring specialized marine engineering.
- Hydropower Turbines:Francis and Pelton turbine designs optimized for Norway's steep reservoir head differentials. Procurement flows through Statkraft's vertical supply chain and long-term service agreements with Voith and Andritz.
- Wind Turbines:15MW+ offshore units mounted on concrete-based floating substructures fabricated in Ålesund and Stavanger casting yards. Deployment schedules compress from 24 months to 14 months through mass-producible hull designs.
- Solar Panels:Utility-scale and commercial rooftop photovoltaic arrays with inverter integration for Nord Pool spot market participation.
- Energy Storage Systems:Grid-connected battery installations arbitraging intraday price volatility in frequency regulation markets. Lithium-ion and emerging iron-air chemistries compete for Rogaland county data center backup contracts.
Wind turbine technology commands the steepest expansion trajectory as floating platforms unlock previously inaccessible seabed. Hydropower turbines retain the largest cumulative installed capacity.
Application:
Application mix reflects Norway's dual carbon goals — electricity generation serves export markets while heating and industrial use drive domestic electrification.
- Electricity Generation:Bulk power production for Nordic grid export and continental interconnection via North Sea Link and NorNed cables. Floating wind and hydropower cascades compete for merchant and contracted offtake structures.
- Heating:Electrification of building stock through heat pumps and district biomass networks in Trøndelag municipalities. Demand pulls from building efficiency retrofit mandates under the Climate Change Act.
- Transportation:Shore power for maritime vessels and electrolytic hydrogen for heavy road freight corridors between Oslo and Bergen.
- Industrial Use:Direct renewable supply to aluminum smelters, fertilizer plants, and data centers seeking Scope 2 emissions reduction. Power-to-X ammonia and e-fuel production at Mongstad anchors offtake from German chemical conglomerates.
Electricity generation dominates revenue flows. Industrial use is where capacity additions concentrate.
End User:
Customer type determines contracting structure — industrial offtakers drive bilateral PPAs while residential and government segments rely on regulated utility tariffs.
- Residential:Distributed solar and heat pump adoption through net metering schemes and building efficiency subsidies. Load growth constrained by grid connection queues in Oslo municipality expansion zones.
- Commercial:Hyperscale data center operators in Rogaland county contract directly with wind and solar developers, bypassing traditional merchant intermediation. Corporate PPA structures displace utility offtake as dominant revenue model.
- Industrial:Aluminum smelters, chemical producers, and maritime fuel suppliers anchor demand for renewable electrons and molecules. German and Dutch hydrogen offtake agreements pull electrolyzer buildout along North Sea pipeline routes.
- Government:Public building electrification and defense facility microgrids procured through NVE concession frameworks with domestic content thresholds.
Industrial end users dominate capacity absorption. Commercial segments are where contract innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vestland county's floating wind cluster show the least price elasticity, absorbing premium infrastructure costs for electrolyzer-linked export contracts. Oslo municipality data centers demonstrate moderate sensitivity, negotiating corporate PPAs that bypass traditional utility tariffs. Residential segments in Trøndelag exhibit highest elasticity, delaying heat pump adoption until subsidy thresholds trigger.
Vestland County
Floating offshore wind development and green hydrogen export corridors anchor demand in this western Norway cluster. The Norwegian Water Resources and Energy Directorate (NVE) governs concession licensing with tightening domestic content thresholds. Mongstad and Kollsnes industrial zones host electrolyzer buildout serving German chemical offtakers through North Sea pipeline routes.
Oslo Municipality
Hyperscale data center load growth drives direct bilateral contracting with wind and solar developers. The Climate Change Act mandates building efficiency retrofits that pull distributed commercial rooftop solar adoption. Rogaland county server facilities bypass Statkraft merchant intermediation through corporate PPA structures.
Trøndelag County
Forest residue conversion systems supply district heating networks with stable feedstock from managed spruce stands. NVE environmental flow requirements constrain hydropower cascade expansion while biomass networks fill supply gaps. Municipal building stock electrification concentrates in Trondheim metropolitan efficiency retrofit zones.
Finnmark County
Untapped onshore wind resource potential attracts developers seeking lower seabed competition than southern lease zones. Reindeer herding corridor consultations under NVE mandatory reviews extend pre-construction timelines unpredictably. Coastal industrial zones explore power-to-X ammonia production for maritime fuel supply chains.
Troms County
Northern Norway wind development targets industrial electrification and grid export capacity through Nordic interconnection. Statnett transmission upgrade backlogs delay project energization, extending cash conversion cycles for developers. Tromsø municipal microgrids procure through NVE frameworks with domestic content participation mandates.
Norway Renewable Energy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in Norwegian renewables. Integrated energy majors leverage offshore engineering heritage and hydropower cascade control to dominate floating wind pre-development and grid balancing services. Pure-play developers and equipment specialists compete on electrolyzer manufacturing and floating foundation fabrication speed. Competitive moves concentrate on vertical control over supply chains and strategic partnerships for domestic content compliance.
Among Norway-based energy majors, Equinor ASA and Statkraft occupy positions that exemplify the integrated archetype through offshore platform deployment and hydropower infrastructure control. Nel ASA represents the equipment specialization tier, anchoring electrolyzer manufacturing for hydrogen export corridors. Scatec ASA sits within the pure-play developer category, pursuing renewable project development without legacy fossil fuel infrastructure.
| Leading Market Players |
|---|
| Aker Horizons |
| Siemens Gamesa Renewable Energy S.A. |
| Statkraft |
| Agder Energi AS |
| Scatec ASA |
| Equinor ASA |
| Berkshire Hathaway Energy Co |
| Nel ASA |
| Norsk Hydro ASA |
| Others |
Value Network & Pricing Analysis
Long-term corporate power purchase agreements lock in supply access for Norwegian renewable developers while anchoring price visibility across multi-year offtake windows. These bilateral structures tie Vestland county floating wind projects to electrolyzer-linked export contracts, compressing financing risk premiums for capital-intensive foundation deployment.
Pricing Analysis
After-sales service revenue from turbine maintenance and grid balancing contracts drives lifetime value for Norwegian renewable asset operators. Project finance structures stratify across merchant spot exposure, regulated utility tariffs, and corporate PPA tiers, with price differentiation resting on certification grade and volume scale. Cost compression in floating foundation fabrication intensifies as concrete-based hull designs displace steel-dominated supply chains. Industrial offtakers in Mongstad and Kollsnes zones show least price sensitivity, absorbing green hydrogen premiums for export-linked molecules, while residential heat pump segments in Trøndelag exhibit highest elasticity pending subsidy thresholds.
Supply Chain Analysis
Strategic stockpiling of heavy-lift vessel capacity dominates Norwegian floating wind procurement, contrasting with just-in-timematerial flows for onshore component assembly. Supply concentrates in South Korean and Chinese shipyards for semi-submersible foundation deployment, while concrete hull casting feeds from Ålesund and Stavanger civil engineering yards. Critical dependencies include rare earth magnet supply for 15MW+ turbine generators and specialized marine cable insulation. Single-source vulnerability in Asian heavy-lift installation vessels creates project timeline exposure. Distribution runs through Statnett's transmission queue and direct bilateral contracting channels to industrial offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
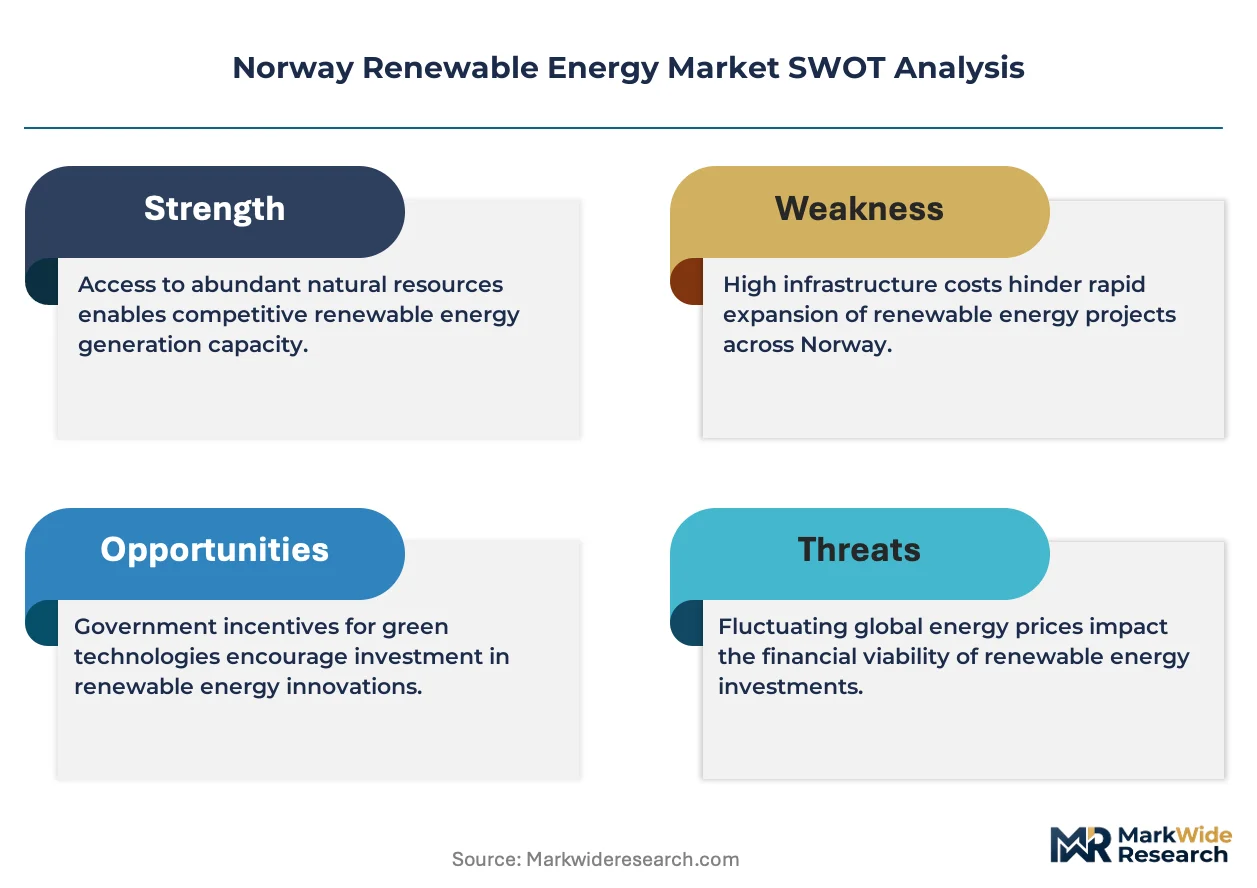
Norwegian renewable energy exhibits fragmentation opportunity as corporate PPA demand from data center operators displaces traditional utility intermediation, creating niche openings for specialized developers without legacy hydropower infrastructure.
For Market Incumbents: Compound offshore engineering heritage into floating wind pre-development dominance through exclusive semi-submersible foundation partnerships with Ålesund casting yards. Secure Statnett transmission queue priority to defend against pure-play developers lacking grid access leverage. Deepen backward integration into electrolyzer manufacturing via hydrogen export corridor joint ventures. For New Entrants and Emerging Players: Differentiate on Northern Norway onshore wind development in Finnmark and Troms counties where seabed competition remains muted and reindeer herding consultations create incumbent delay vulnerability. Target battery storage arbitrage in Rogaland county data center backup contracts where lithium-ion and iron-air chemistry competition remains unsettled. Pursue direct municipal microgrid procurement in Tromsø bypassing NVE concession backlog through below-threshold capacity exemptions. For Investors and Strategic Acquirers: Equipment specialists with electrolyzer manufacturing scale and floating foundation casting capabilities present acquisition targets with asymmetric upside from German hydrogen offtake contract acceleration. Long-term viability hinges on EU Green Deal implementation continuity through EEA agreement ratification. Watch for NVE lease round outcomes against hydrogen pipeline routing decisions as inflection signal for capital reallocation between electrons and molecules.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Wind Capacity Buildout | Vestland county lease zones anchor electrolyzer-linked export infrastructure to German chemical offtakers. |
| Corporate Power Purchase Agreement | Direct bilateral contracting with Rogaland data centers displaces Statkraft merchant intermediation. |
| Concrete Foundation Technology Licensing | Mass-producible hull designs compress delivery schedules from 24 months to 14 months. |
| Backward Integration into Electrolyzer Manufacturing | Nel ASA's specialist position anchors hydrogen export corridor molecule supply. |
| Green Certification Program | NVE's tightening domestic content thresholds mandate local supply chain participation for concession compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NVE concession databases, Statnett transmission planning documents, and EU EEA agreement implementation records. Primary interviews captured utility planning officers, IPP project developers, EPC contractors, and grid operators across Vestland, Rogaland, and Trøndelag counties. Secondary validation drew from Norwegian Water Resources and Energy Directorate licensing data, Nord Pool spot market records, and project finance disclosure filings. Bottom-up capacity addition tracking triangulates against top-down macroeconomic demand modeling.
Segmentation dimensions modeled span energy source, technology type, application, and end user across the analysis window. The analytical framework incorporates hydropower cascade control, floating offshore wind platform deployment, electrolyzer manufacturing scale, and corporate PPA contracting velocity. CAGRs derive from installed capacity buildout trajectories, grid interconnection queue progression, and hydrogen export corridor offtake contract execution rates.
Forecasts assume regulatory continuity in EU Green Deal implementation through EEA agreement mechanisms and NVE concession licensing frameworks; material policy shifts would require re-modeling. Revision becomes warranted when Statnett transmission upgrade backlogs or specialized vessel scarcity crosses thresholds that compress project cash conversion cycles beyond financing viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market