
 Surge Tank Market | 2026-2036
Surge Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Surge Tank Market Insights
The surge tank supply chain is recalibrating around a widening gap between engineered-to-order pressure vessels for critical infrastructure and standardized atmospheric tanks for municipal water systems. Pentair plc leverages its filtration and flow control integration to dominate specification-driven procurement in North American power utilities. Wheeler Tank Manufacturing anchors its position through ASME-certified fabrication capacity serving regional water authorities. Alpha Tanks specializes in composite pressure application tanks, differentiating on corrosion resistance for offshore oil and gas installations.
A surge tank is a pressurized or unpressurized vessel installed in fluid transmission systems to absorb hydraulic shock, prevent water hammer, and stabilize flow rates during rapid pump or valve transitions; typical specifications include design pressures ranging from atmospheric to several hundred psi, with wall thicknesses governed by ASME Boiler and Pressure Vessel Code Section VIII for pressure-rated units. Its primary industrial purpose is protecting pipeline integrity and pumping equipment in water distribution networks, thermal power plants, and hydrocarbon processing facilities. Steel remains the dominant material for high-pressure installations due to established welding protocols and code familiarity, while fiberglass is gaining share in corrosive environments such as offshore platforms and chemical processing plants. Above-ground installation types command the largest volume pool, though underground configurations are expanding in urban water supply projects where land constraints and aesthetic requirements limit surface infrastructure.
ASME standards, EPA Safe Drinking Water Act provisions, and EU Pressure Equipment Directive frameworks collectively shape fabrication certification, material traceability, and market access requirements across major demand centers. China's NMPA-equivalent pressure vessel administration and GB standards impose additional compliance layers for imported equipment, creating localized certification barriers. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal and China's dual carbon goals, as embodied emissions in steel and concrete tank fabrication increasingly influence procurement scoring in public infrastructure tenders.
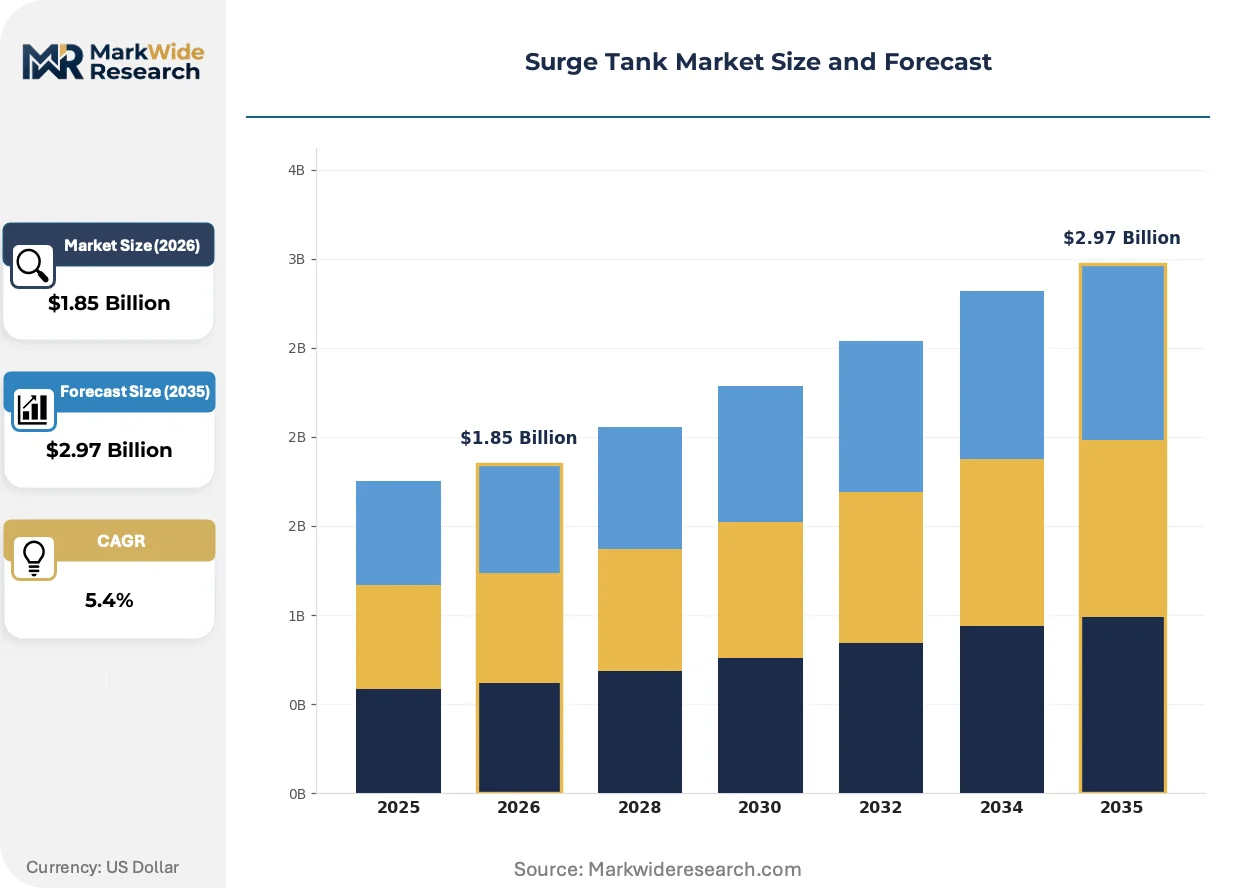
Market Dynamics
ASME Section VIII certification requirements and China's GB standard enforcement are compressing the supplier base, forcing regional fabricators to consolidate or exit as state-backed utilities in China and North America consolidate procurement around certified tier-one vendors.
Growth Catalysts
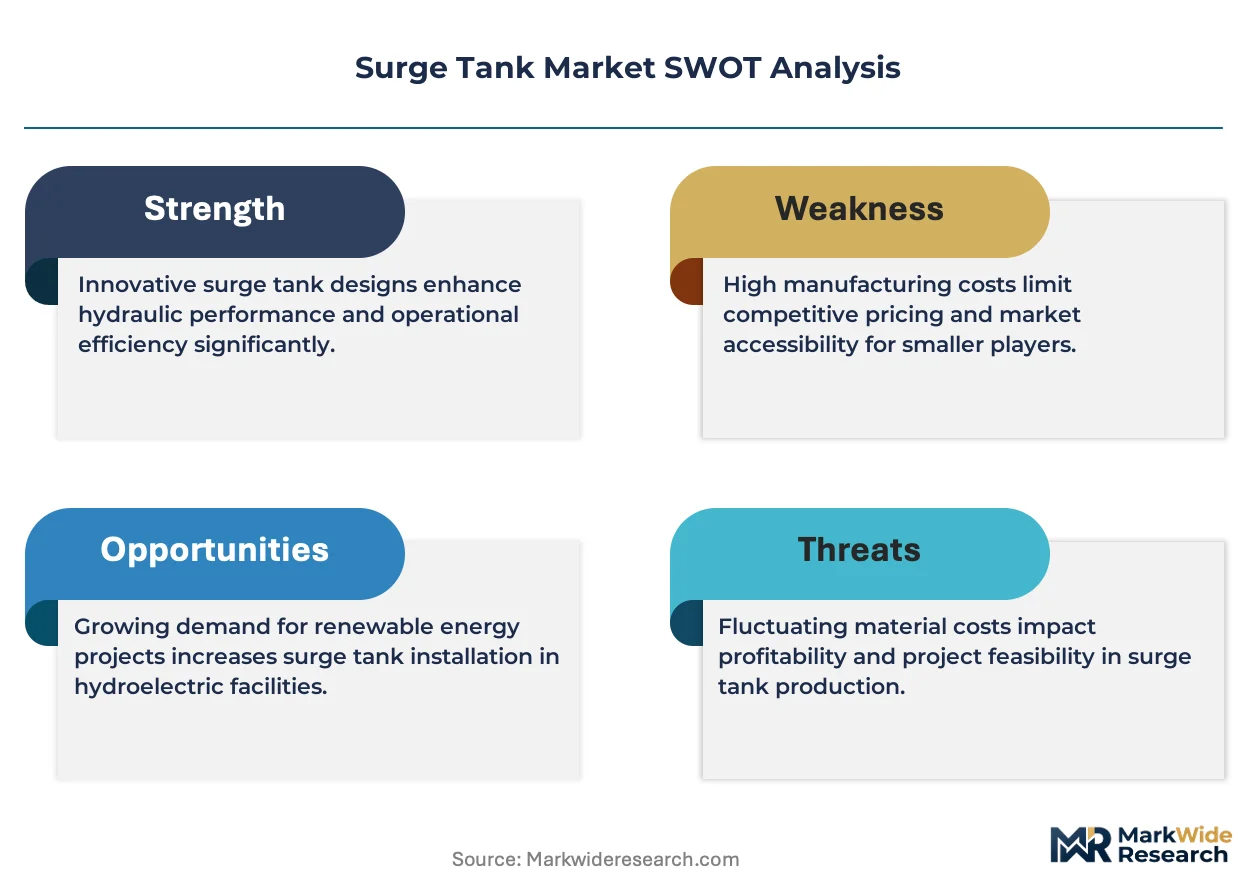
- Hydropower modernization mandates:China's state-backed dam retrofit programs and India's Central Electricity Authority directives are accelerating replacement cycles for aging surge protection infrastructure.
- EPA Safe Drinking Water Act amendments:Tighter water quality standards in US municipal systems are mandating upgraded surge tank specifications for distribution network integrity.
- Composite material advancement:Fiberglass-reinforced polymer fabrication protocols are extending tank service life in corrosive offshore oil and gas environments.
Market Restraints
- Steel price volatility:Input cost swings for carbon steel plate and welding consumables compress margins for ASME-certified fabricators locked into fixed-price utility contracts.
- Certification concentration:ASME stamp capacity concentrates in US Gulf Coast and Great Lakes fabrication clusters, limiting geographic supplier diversity.
- Concrete surge chamber substitution:Large-scale hydropower developers in China and Brazil increasingly specify cast-in-place concrete surge chambers for high-head installations.
Strategic Opportunities
- EU Green Deal carbon accounting:Embodied emissions scoring in public infrastructure tenders creates first-mover advantage for fabricators with verified low-carbon steel sourcing.
- Urban water infrastructure densification:Underground surge tank configurations are penetrating land-constrained municipalities in Japan and South Korea.
- Digital twin integration:Sensor-embedded smart surge tanks enabling predictive maintenance contracts are opening recurring revenue streams beyond equipment sale.
Industry Challenges
- ASME welder certification scarcity:Qualified pressure vessel welders and NDE technicians command premium wages, constraining fabrication capacity expansion.
- Legacy system integration complexity:Retrofit installations in century-old water distribution networks require custom manifold designs that extend engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surge Tank Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Surge Tanks, Pressure Application Tanks, Atmospheric Tanks, Composite Surge Tanks End User: Power Generation, Water Supply, Oil & Gas, Industrial Manufacturing Installation Type: Onshore, Offshore, Underground, Above-Ground Material: Steel, Concrete, Fiberglass, Others |
| Companies Covered | Young Engineering & Manufacturing, Wheeler Tank Manufacturing, Alpha Tanks, Pentair plc, Veolia Environnement, Squibb Tank, TransTech Fabrication, Xylem Inc., RothLochston, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surge Tank Market Trends and Innovations
Modular fabrication methods and digital monitoring integration are compressing project delivery timelines while enabling performance-based service models that shift revenue recognition from equipment sale to operational uptime guarantees.
Composite pressure vessel technology incorporating fiberglass-reinforced thermoset resins is decentralizing surge tank deployment patterns. Offshore platform operators in the North Sea and Gulf of Mexico specify these units for seawater ballast and firewater systems. The shift is decentralizing maintenance logistics by eliminating corrosion-related dry-docking requirements.
China's NMPA-equivalent pressure vessel administration and updated GB 150 standards are tightening material traceability and third-party inspection protocols. Domestic fabricators must now document mill test reports through digital platforms. The enforcement is compressing import market share for uncertified foreign suppliers while elevating compliance costs across the supply base.
Specification-driven buyers in power utilities and municipal water authorities are unbundling engineering, procurement, and construction contracts. Tier-one fabricators now compete for design-build packages rather than component supply. The restructuring concentrates in North American independent system operators and Chinese provincial water investment groups where consolidated procurement offices centralize vendor qualification.
Surge Tank Market Segmentation
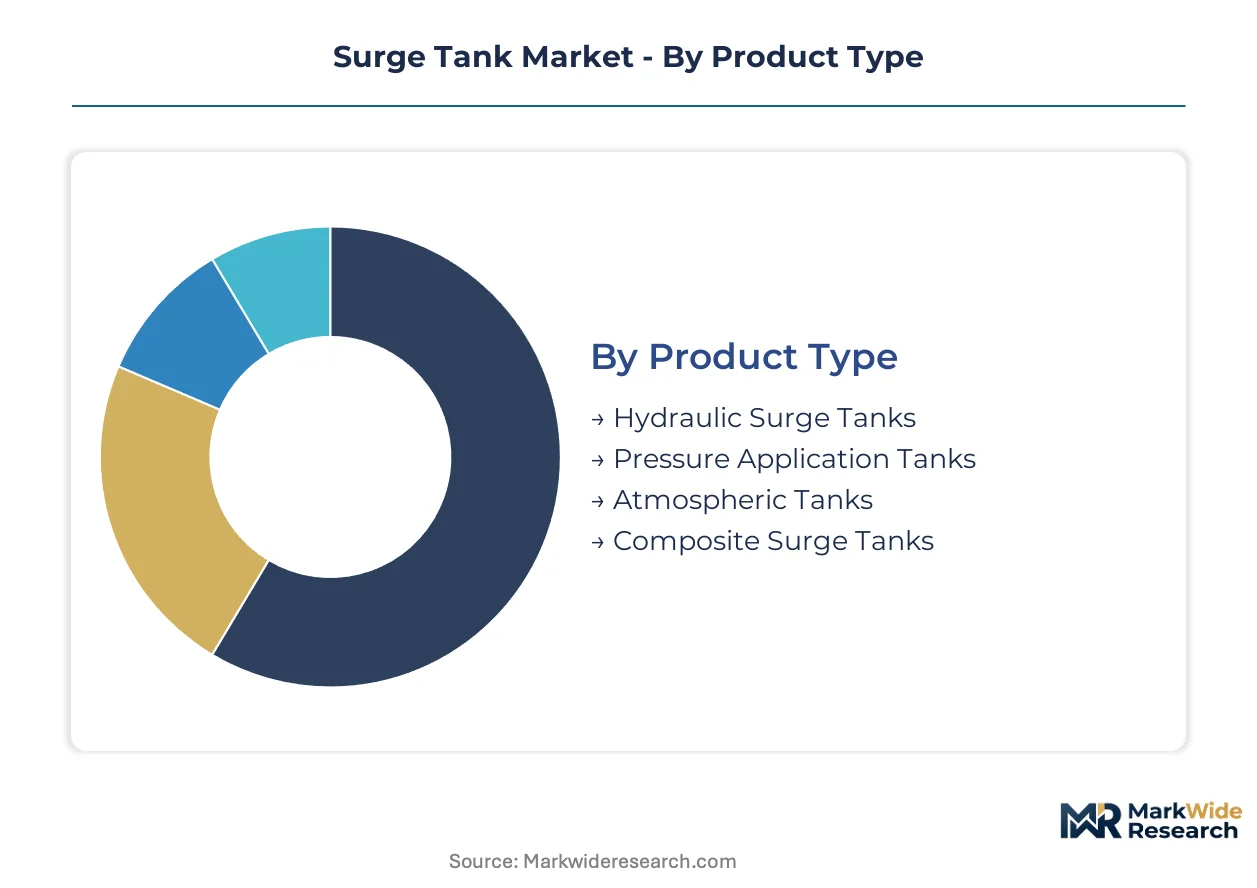
Surge tank procurement splits sharply between engineered pressure vessels requiring ASME certification and commodity atmospheric tanks for municipal networks. Specification intensity varies tenfold across segments, dictating vendor qualification barriers and margin structures.
Product Type:
Capital intensity peaks in pressure-rated vessels demanding certified fabrication capacity, while atmospheric configurations run through standardized manufacturing.
- Pressure Application Tanks:ASME Section VIII vessels rated for sustained internal pressure above 15 psi, requiring radiographic weld inspection and third-party certification. Procurement concentrates in North American independent system operators and Chinese provincial power grids where hydropower modernization mandates are accelerating replacement cycles.
- Hydraulic Surge Tanks:Specialized vessels designed to absorb water hammer in high-head penstock systems, typically specified with surge anticipation valve integration. Demand clusters in China's state-backed dam retrofit programs and India's Central Electricity Authority directives for aging infrastructure.
- Atmospheric Tanks:Unpressurized vessels for municipal water distribution, governed by EPA Safe Drinking Water Act amendments rather than pressure codes.
- Composite Surge Tanks:Fiberglass-reinforced polymer vessels displacing steel in corrosive offshore environments.
Most installed capacity flows through Pressure Application Tanks. Expansion is steepest in Composite Surge Tanks.
End User:
Application requirements diverge between continuous-process industries demanding 99.9% uptime assurance and intermittent municipal operations with seasonal demand peaks.
- Power Generation:Hydropower facilities, thermal plants, and pumped-storage installations requiring surge protection for turbine wicket gate transients. China's state-backed dam retrofits and India's Central Electricity Authority directives are accelerating specification upgrades for aging infrastructure protection.
- Oil & Gas:Offshore platforms and pipeline terminals specifying corrosion-resistant vessels for seawater ballast and firewater systems. North Sea and Gulf of Mexico operators are displacing steel with composite fabrication to eliminate dry-docking maintenance cycles.
- Water Supply:Municipal distribution networks governed by EPA Safe Drinking Water Act amendments mandating upgraded surge protection.
- Industrial Manufacturing:Process plants with intermittent pump cycling requiring smaller-capacity vessels.
Power Generation commands the largest specification-driven procurement volume. Oil & Gas is expanding most quickly as offshore composite adoption accelerates.
Installation Type:
Site constraints and land economics determine whether vessels deploy above grade, below grade, or on marine structures with specialized foundation requirements.
- Above-Ground:Standard configuration for power plants and industrial facilities with available surface area, enabling simplified inspection access and maintenance logistics. The segment dominates volume across Chinese hydropower stations and North American municipal treatment plants.
- Underground:Land-constrained urban deployments in Japan and South Korea where aesthetic requirements and surface scarcity drive specification. Tokyo and Seoul water authorities are standardizing buried composite vessels for seismic resilience.
- Onshore:Conventional ground-level installation for pipeline terminals and process plants.
- Offshore:Platform-mounted vessels requiring marine-grade coatings and dynamic load certification.
Above-Ground installations carry the majority of cumulative capacity. Underground configurations are gaining share fastest in dense Asian municipalities.
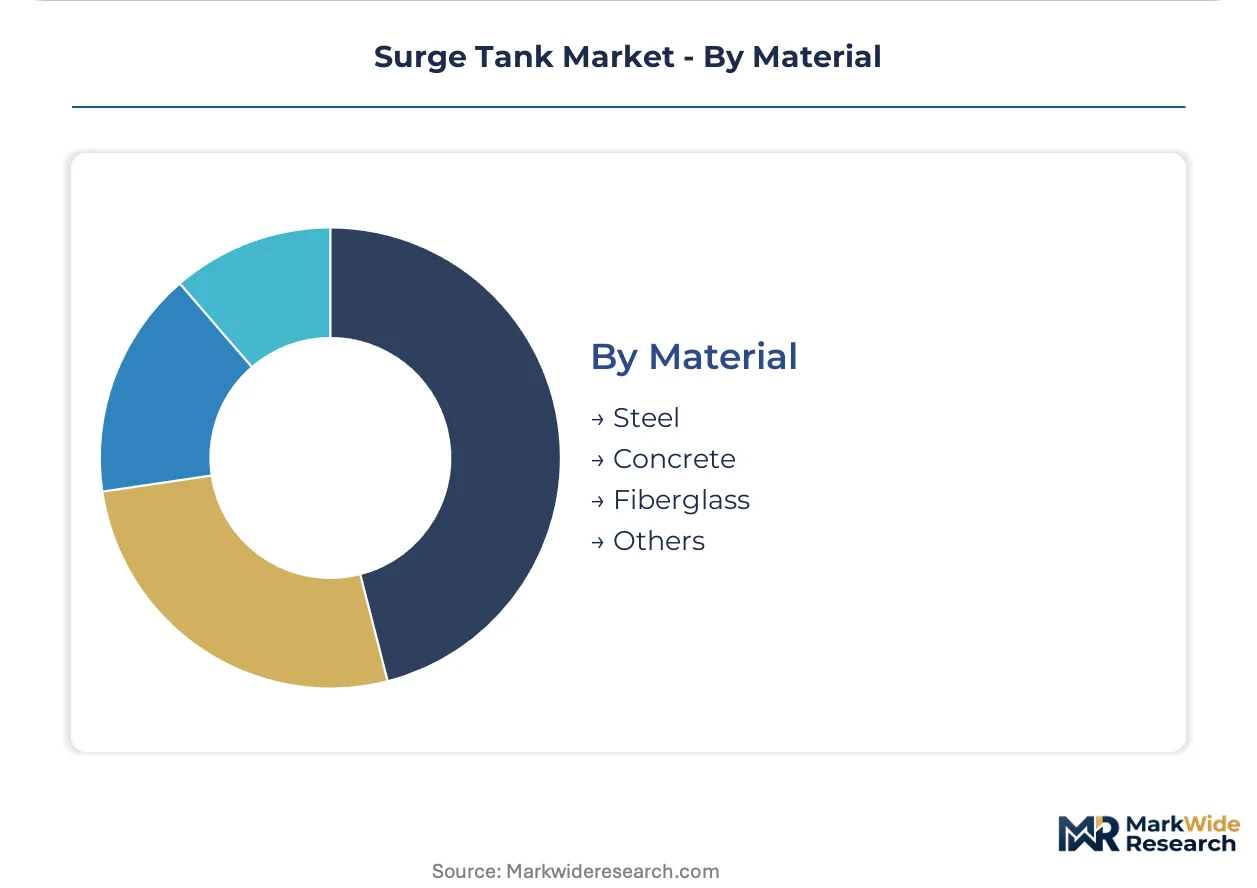
Material:
Fabrication economics and service environment dictate material selection, with code familiarity and supply chain maturity creating path dependencies in specification.
- Steel:Carbon and alloy plate construction dominating high-pressure applications through established ASME welding protocols and inspector familiarity. Chinese fabricators and US Gulf Coast clusters maintain concentrated certified capacity.
- Fiberglass:Reinforced thermoset polymer vessels extending service life in corrosive offshore oil and gas environments. North Sea operators specify these for seawater systems to eliminate corrosion-related platform shutdowns.
- Concrete:Cast-in-place surge chambers specified for high-head hydropower in China and Brazil where unit scale exceeds fabricated vessel transport limits.
- Others:Stainless steel and specialized alloys for chemical process applications.
Steel accounts for the dominant share of installed base. Fiberglass is climbing the fastest as offshore platform specifications shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welders and pressure vessel engineers cluster around Houston, Pittsburgh, and the Ruhr Valley, anchoring fabrication capacity for critical infrastructure procurement.
United States
EPA Safe Drinking Water Act amendments mandate upgraded surge protection for municipal distribution networks. ASME Section VIII certification requirements compress supplier eligibility to Gulf Coast and Great Lakes fabrication clusters. Houston-based fabricators dominate specification-driven procurement for independent system operators.
China
State-backed dam retrofit programs and provincial water infrastructure upgrades accelerate replacement cycles for aging surge protection. NMPA-equivalent pressure vessel administration and GB 150 standards tighten material traceability through digital platform documentation. Yangtze River Delta fabricators capture procurement centralization by state-owned utilities.
Germany
EU Green Deal carbon accounting rules elevate embodied emissions scoring in public infrastructure tenders. EU Pressure Equipment Directive frameworks govern fabrication certification and third-party inspection protocols. Ruhr Valley fabrication clusters defend position through verified low-carbon steel sourcing for Green Deal compliance.
India
Central Electricity Authority directives accelerate specification upgrades for aging hydropower infrastructure protection. BIS pressure vessel standards and state-level water authority procurement centralization reshape vendor qualification. Gujarat and Maharashtra fabrication clusters expand ASME-certified capacity to serve regional power grid modernization.
Japan
Land-constrained municipalities in Tokyo and Osaka standardize underground surge tank configurations for seismic resilience. METI industrial standards and JIS pressure equipment codes govern material selection and weld inspection protocols. Kansai region water authorities pioneer buried composite vessel specifications for urban densification projects.
Surge Tank Market Competitive Landscape
Top-tier vendors anchor specification-driven procurement for power utilities and municipal water authorities, while regional fabricators compete on ASME-certified capacity proximity. The supplier base stratifies around three archetypes: integrated flow control specialists, certified pressure vessel fabricators, and composite material specialists. Consolidation pressure intensifies as procurement offices centralize vendor qualification. Competitive moves concentrate on geographic certification expansion and low-carbon steel sourcing verification.
Among North American fabricators, Wheeler Tank Manufacturing and Young Engineering & Manufacturing exemplify the certified fabrication archetype, while Pentair plc occupies a position representing integrated flow control and filtration capability. Alpha Tanks sits within the composite specialization tier. These three anchors illustrate how vendor positioning diverges between code-certified metal fabrication, system integration, and corrosion-resistant material science.
| Leading Market Players |
|---|
| Young Engineering & Manufacturing |
| Wheeler Tank Manufacturing |
| Alpha Tanks |
| Pentair plc |
| Veolia Environnement |
| Squibb Tank |
| TransTech Fabrication |
| Xylem Inc. |
| RothLochston |
| Others |
Pricing and Supply Chain Analysis
State-owned utilities in China and North American independent system operators concentrate procurement around ASME-certified fabricators, locking in project-based pricing with long-term offtake structures for critical infrastructure. This buyer consolidation amplifies pricing power for Gulf Coast and Yangtze River Delta fabrication clusters while squeezing regional competitors without certification proximity.
Pricing Analysis
Engineering-procurement-construction bundling versus component-only supply splits the pricing landscape. Premium tiers attach to ASME Section VIII certification with radiographic inspection protocols, while standard tiers cover atmospheric municipal tanks under EPA guidelines. Cost compression in carbon steel plate and welding consumables intensifies margin pressure for fixed-price utility contracts. Municipal water authorities exhibit highest price sensitivity; offshore oil and gas operators prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Certified welder and NDE technician scarcity in Houston, Pittsburgh, and the Ruhr Valley constrains fabrication capacity expansion. Steel plate supply draws from domestic mills in China and US Great Lakes regions, with welding consumables and composite resin systems feeding from specialty chemical producers. Single-source vulnerability concentrates in ASME stamp capacity clustered around US Gulf Coast fabrication yards. Distribution runs through direct specification-driven procurement by state-backed utilities and consolidated municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hydropower modernization mandates and EPA Safe Drinking Water Act amendments shift specification intensity toward premium ASME-certified vessels.
For Market Incumbents: Hedge against concrete surge chamber substitution in high-head hydropower by deepening composite pressure vessel capabilities for offshore platform specifications. Secure ASME-certified welder pipelines through apprenticeship partnerships in Houston and Pittsburgh clusters to defend fabrication capacity against labor scarcity. For New Entrants and Emerging Players: Digital specification platforms and remote engineering collaboration tools offer low-friction entry into municipal atmospheric tank segments underserved by incumbent EPC bundling. Target India's state-level water authority procurement centralization where BIS standards are displacing informal fabricators. For Investors and Strategic Acquirers: Integrated flow control specialists are the most active acquirer in this space, consolidating specification-driven procurement relationships with power utilities. Five-to-ten-year viability hinges on verified low-carbon steel sourcing for EU Green Deal compliance. Watch carbon accounting scoring adoption in Chinese provincial infrastructure tenders as inflection indicator for procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Expansion | Unlocks specification-driven procurement from Chinese provincial power grids and North American independent system operators. |
| Composite Material Scale-Up | Captures offshore platform specifications in North Sea and Gulf of Mexico corrosion-resistant deployments. |
| Low-Carbon Steel Sourcing Verification | Secures EU Green Deal tender eligibility and Chinese dual carbon goals procurement scoring advantage. |
| Digital Twin Integration | Shifts revenue recognition from equipment sale to predictive maintenance contracts with power generation utilities. |
| Underground Configuration Engineering | Penetrates land-constrained municipalities in Tokyo and Seoul densification projects. |
Research Methodology
Bottom-up power generation and municipal water utility modeling reconciled against top-down fabrication capacity tracking forms the analytical core. Primary interviews with ASME-certified welders, pressure vessel procurement officers at state-owned utilities, EPC contract managers, and municipal water authority engineers combined with secondary validation against EPA enforcement databases, NMPA-equivalent pressure vessel administration filings, and EU Pressure Equipment Directive certification registries. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of hydropower retrofit cycles and municipal infrastructure replacement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include pressure rating tier, installation type, material composition, and end-use vertical. CAGRs derive from regression against capital expenditure trajectories in Chinese dam retrofit programs and US water infrastructure grant disbursements. Composite material adoption curves and carbon accounting scoring implementation timelines serve as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for composite pressure vessel fabrication or concrete surge chamber specifications would alter the outlook. Forecasts reflect assumptions around ASME certification enforcement continuity, steel price volatility moderation, and regulatory carbon accounting adoption schedules. Material deviation in Chinese state procurement centralization or EPA Safe Drinking Water Act amendment timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Global Virtual Pipeline Systems Market