
 Mexico Pipeline Services Market | 2026-2036
Mexico Pipeline Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Pipeline Services Market Foresight
Northeast Mexico is tilting toward expanded pipeline integrity capacity as shale-adjacent basins require deeper contractor involvement. MasTec Inc. leverages its cross-border construction scale to dominate Texas-Mexico interconnect projects. SGS SA sustains leadership in non-destructive testing protocols across Pemex-operated trunk lines. Intertek Group PLC anchors its position through certified inspection laboratories in Tampico and Reynosa.
Pipeline services encompass the engineering, construction, inspection, maintenance, and logistical support of tubular infrastructure systems transporting hydrocarbons and industrial fluids, typically operating at pressures ranging from 200 to 1,440 psi depending on diameter and terrain classification. These services ensure mechanical integrity, regulatory compliance, and continuous throughput for energy distribution networks. Construction services command the largest revenue pool given Mexico's midstream expansion mandates, while inspection services represent the fastest-growing category as inline inspection tool deployment accelerates across aging Pemex gathering systems. Natural gas fluid-type assignments attract disproportionate capital allocation relative to crude oil corridors due to CFE power generation commitments and export-oriented LNG feedstock requirements.
ASEA, the Mexican energy regulator, enforces pipeline safety standards through mandatory integrity management programs that dictate inspection frequency and repair timelines for operators above specified throughput thresholds. SEMARNAT environmental clearances constrain route selection and construction windows, particularly in protected coastal zones of Veracruz and Tabasco. NOM-001-SECRE standards govern welding procedures and material specifications for carbon steel transmission lines. Stakeholders must monitor how Mexico's hydrocarbon law amendments reshape third-party access rules and contractor qualification thresholds for strategic energy infrastructure.
Market Dynamics
Pemex infrastructure modernization mandates are compressing contractor qualification timelines while accelerating smart pigging deployment across the Burgos Basin and Southeast production corridors.
Growth Catalysts
- ASEA integrity management programs:Mandatory inspection frequency rules for high-throughput operators create recurring revenue streams for certified service providers across trunk line networks.
- Natural gas power generation commitments:CFE's feedstock requirements for combined-cycle plants drive capital allocation toward gas transmission corridors over crude oil infrastructure.
- Shale-adjacent basin development:Northeast Mexico's Burgos Basin expansion requires deeper contractor involvement in gathering system construction and maintenance.
Market Restraints
- SEMARNAT environmental clearances:Protected coastal zone designations in Veracruz and Tabasco constrain route selection and compress construction windows.
- Specialized welding equipment scarcity:NOM-001-SECRE compliance requirements limit supplier pools for carbon steel transmission line projects.
- Inline inspection tool calibration bottlenecks:Tool availability constraints create scheduling conflicts for aging Pemex gathering system assessments.
Strategic Opportunities
- Southeast production corridor underpenetration:Tabasco and Campeche offshore tieback infrastructure offers expansion scope for integrated service providers.
- Third-party access rule amendments:Hydrocarbon law revisions reshape contractor qualification thresholds for strategic energy infrastructure assignments.
- Smart pigging-NDT convergence:Real-time data fusion between inline inspection tools and non-destructive testing protocols enables predictive maintenance offerings.
Industry Challenges
- Certified welding inspector scarcity:NOM-001-SECRE qualification requirements outpace training program throughput in Tamaulipas and Veracruz labor markets.
- Legacy pipeline documentation gaps:Incomplete as-built records for Pemex-operated trunk lines complicate integrity baseline assessments and repair prioritization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Pipeline Services Market |
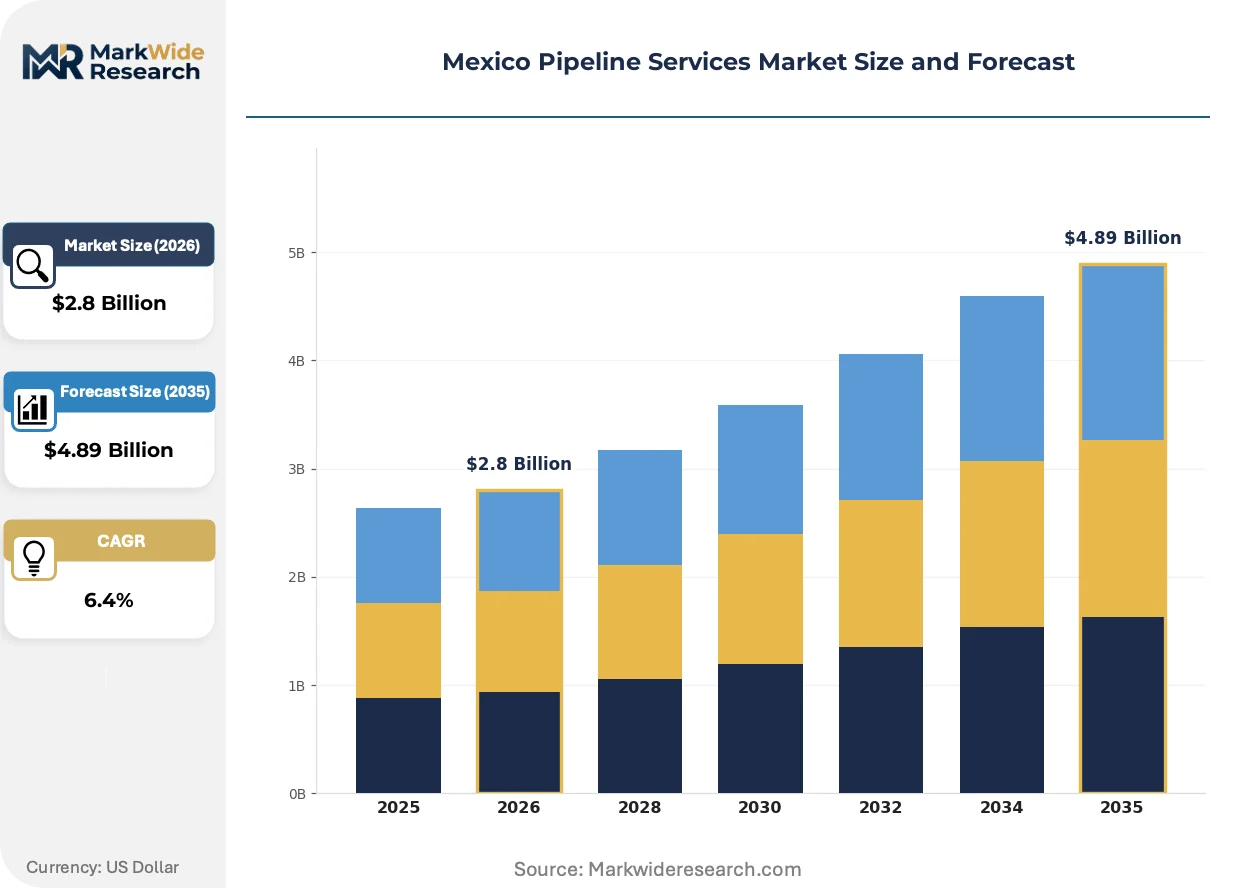
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Inspection, Maintenance, Logistics Pipeline Diameter: Small, Medium, Large, Extra-Large Fluid Type: Crude Oil, Natural Gas, Water, Chemicals End User: Petroleum Companies, Utilities, Industrial Plants, Government |
| Companies Covered | MasTec Inc., SGS SA, OCA Global, Intertek Group PLC, Fluor Corporation, Bonatti, GDI Sicim Pipelines, TC Energy Corporation, Pemex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Pipeline Services Market Shifts & Advancements
Digital inspection technologies are compressing assessment cycles while regulatory enforcement tightens around documented traceability. Service differentiation increasingly hinges on real-time data delivery capabilities.
Ultrasonic testing is hybridizing with electromagnetic acoustic transducer arrays to detect crack anomalies in high-pressure gas lines. Midstream operators in the Burgos Basin are piloting these combined modalities for unpiggable pipeline segments. The convergence is hybridizing contractor technical requirements and compressing vendor qualification timelines.
ASEA's 2024 amendments to pipeline safety standards mandate real-time pressure monitoring integration with integrity management systems. Operators above specified throughput thresholds must upgrade SCADA architectures or face operational suspension. Gathering system contractors in Tamaulipas are absorbing compliance costs into multi-year service agreements.
Buyer consolidation among natural gas utilities is compressing vendor panels and extending contract durations. CFE and private offtakers are consolidating inspection, maintenance, and emergency response under single-source frameworks. This concentration is most visible in Reynosa-Tampico corridor assignments where integrated service capabilities determine award outcomes.
Mexico Pipeline Services Market Segmentation
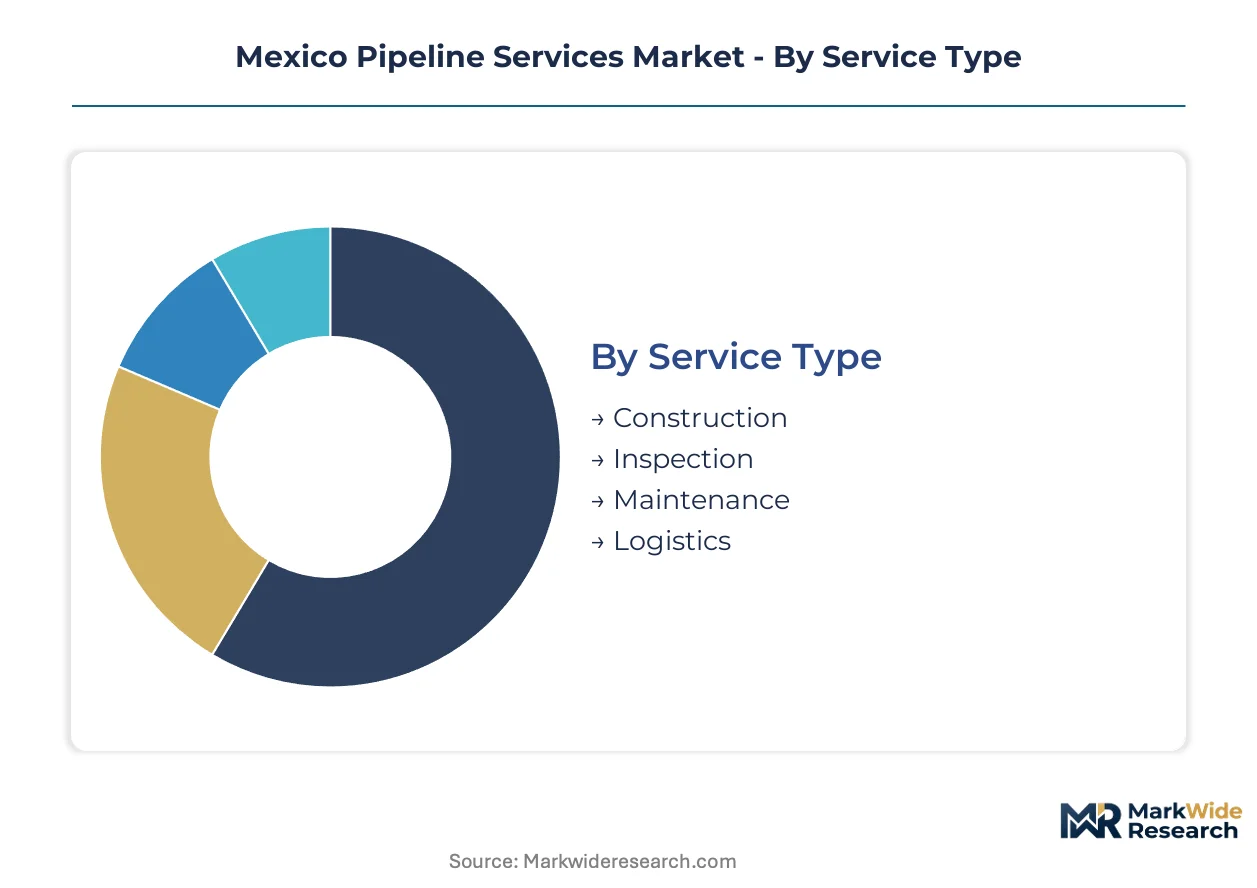
Service differentiation in Mexico's pipeline market hinges on recurring maintenance intensity and inspection frequency mandates. After-sales service obligations create divergent margin profiles across contractor portfolios, with integrity management programs locking in multi-year revenue streams for specialized providers.
Service Type:
After-sales service intensity varies dramatically by service category, with inspection protocols demanding continuous calibration support and construction services tapering sharply post-commissioning.
- Construction:Engineering, procurement, and installation of carbon steel transmission lines across the Burgos Basin and Southeast production corridors. Pemex midstream expansion mandates concentrate demand in Tamaulipas and Veracruz, where route complexity and SEMARNAT clearance timelines compress project windows. Contractors absorb extended warranty obligations into lump-sum agreements.
- Inspection:Deployment of inline inspection tools, non-destructive testing, and integrity baseline assessments for aging Pemex gathering systems. ASEA mandatory frequency rules create recurring revenue streams. Smart pigging technology convergence accelerates tool calibration requirements and data fusion capabilities.
- Maintenance:Scheduled repair programs, cathodic protection upgrades, and emergency response retainers across trunk line networks.
- Logistics:Coating application, welding material supply chain management, and specialized equipment mobilization for remote corridor assignments.
Construction holds the largest share; momentum sits with Inspection.
Pipeline Diameter:
Cost tier differentiation separates commodity gathering systems from high-pressure transmission infrastructure, with diameter dictating welding procedure complexity and inspection tool compatibility.
- Large:Transmission lines exceeding 30 inches in diameter operating at pressures up to 1,440 psi for CFE power generation feedstock corridors. NOM-001-SECRE welding standards and specialized equipment requirements constrain supplier pools. Demand concentrates in Texas-Mexico interconnect projects and Burgos Basin trunk line expansions.
- Extra-Large:Cross-border export infrastructure and strategic energy corridor assignments requiring advanced material specifications and automated welding protocols.
- Small:Gathering system laterals in mature production fields with standardized construction techniques and higher contractor competition.
- Medium:Distribution networks serving industrial offtakers and regional utility interconnections.
Large diameter commands premium pricing; Small diameter segments face margin compression.
Fluid Type:
Application-specific requirements create divergent integrity management protocols, with natural gas systems demanding more frequent pressure monitoring and leak detection investments.
- Natural Gas:High-pressure transmission infrastructure feeding CFE combined-cycle plants and LNG export facilities. Real-time SCADA integration requirements intensify under ASEA's amended safety standards. The Burgos Basin and Reynosa-Tampico corridor concentrate capital allocation.
- Crude Oil:Gathering and trunk line systems across mature Pemex production fields with established maintenance regimes and documented corrosion patterns.
- Water:Produced water disposal and injection lines serving enhanced recovery operations in Southeast production corridors.
- Chemicals:Specialty product pipelines with material compatibility specifications and concentrated industrial plant offtake.
Natural Gas attracts disproportionate capital allocation; Chemicals remains a niche specialization.
End User:
Customer type determines contract structure, with petroleum companies favoring integrated service frameworks and utilities consolidating vendor panels under extended duration agreements.
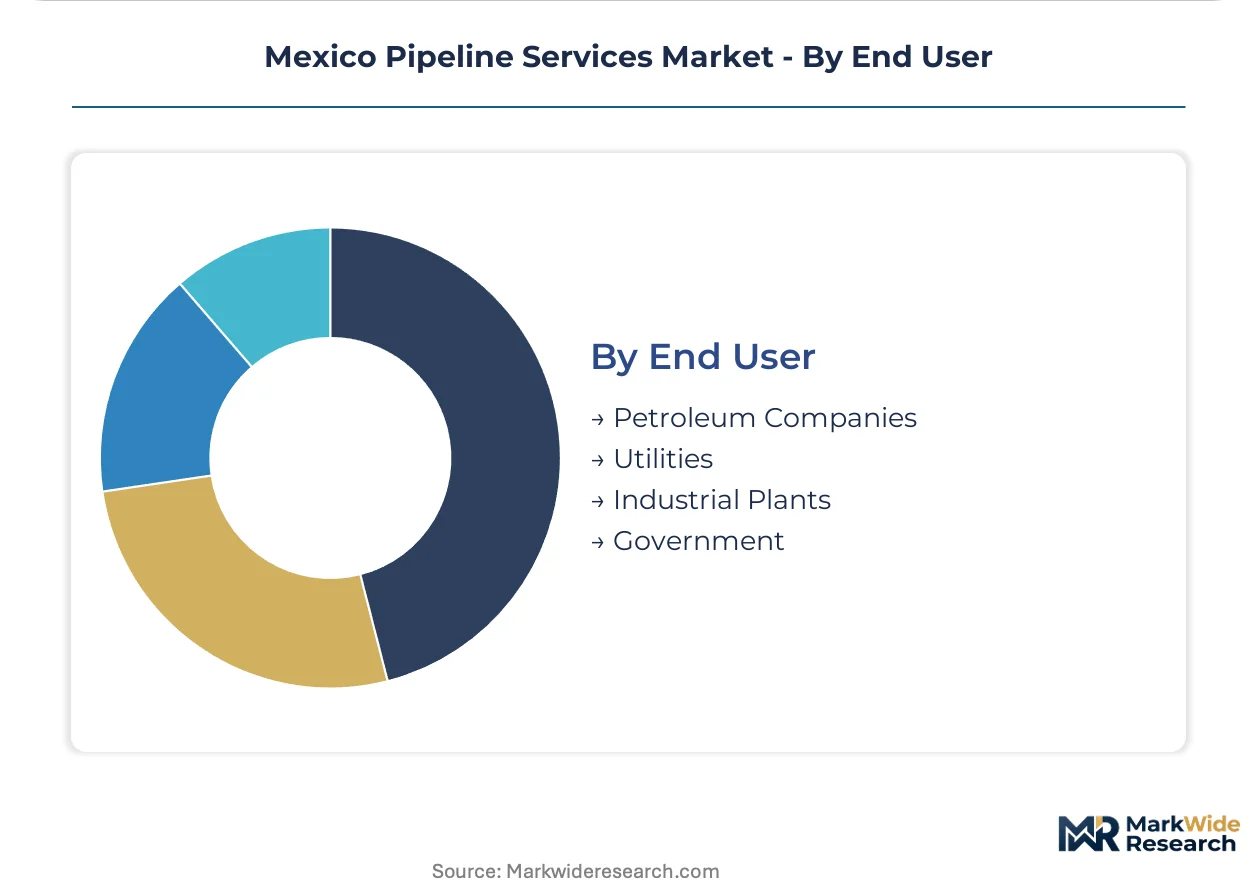
- Petroleum Companies:Pemex-operated trunk lines and third-party upstream operators requiring full-lifecycle service integration from construction through integrity management. Legacy documentation gaps complicate baseline assessments and repair prioritization across aging gathering systems.
- Utilities:CFE and private natural gas offtakers consolidating inspection, maintenance, and emergency response under single-source frameworks in the Reynosa-Tampico corridor.
- Industrial Plants:Refinery and petrochemical facility tie-ins with specialized material specifications and turnaround-scheduled maintenance windows.
- Government:Strategic energy infrastructure assignments with contractor qualification thresholds shaped by hydrocarbon law amendments.
Petroleum Companies anchor volume demand; Utilities are extending contract durations fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline service capacity concentrates in Mexico's hydrocarbon-producing basins where Pemex modernization mandates intersect with private midstream expansion. Contractor mobilization patterns track closely to Burgos Basin shale development and Southeast corridor offshore tieback requirements.
Nuevo León
The Burgos Basin anchors the highest concentration of smart pigging deployment and gathering system construction. ASEA integrity management programs enforce mandatory inspection frequencies across high-throughput operators. Reynosa and Monterrey industrial clusters absorb specialized welding labor for Texas-Mexico interconnect projects.
Tamaulipas
Cross-border transmission corridors drive demand for large-diameter construction and cathodic protection upgrades. NOM-001-SECRE welding standards constrain qualified supplier pools for carbon steel lines. Matamoros and Ciudad Victoria service hubs coordinate emergency response retainers for trunk line networks.
Veracruz
Southeast production corridor infrastructure requires deeper contractor involvement in offshore tieback systems. SEMARNAT environmental clearances compress construction windows in protected coastal zones. Tampico inspection laboratories anchor non-destructive testing protocols for Pemex-operated trunk lines.
Tabasco
Offshore platform pipeline connections and produced water disposal lines attract integrated service providers. Hydrocarbon law amendments reshape third-party access rules for strategic energy infrastructure. Ciudad del Carmen contractors specialize in subsea tieback maintenance and turnaround-scheduled repair programs.
Campeche
Mature offshore fields demand integrity baseline assessments for aging gathering systems with incomplete as-built documentation. Legacy pipeline records complicate repair prioritization and inline inspection tool calibration. Campeche City service bases support emergency response for Cantarell and Ku-Maloob-Zaap production complexes.
Mexico Pipeline Services Market Competitive Landscape
Cross-border construction specialists and certified inspection laboratories split the market between project-based awards and recurring integrity mandates. The vendor base organizes around three strategic archetypes: integrated engineering-procurement-construction firms, specialized non-destructive testing providers, and regional maintenance contractors. Consolidation pressures favor multi-service capabilities over single-point offerings. Capacity expansion and technology licensing dominate competitive positioning as ASEA compliance requirements tighten.
Among North American integrated service providers, MasTec Inc. and Fluor Corporation exemplify the cross-border construction archetype with scale advantages in Texas-Mexico interconnect assignments. Within the inspection and certification tier, SGS SA and Intertek Group PLC occupy positions anchored by accredited laboratory networks and real-time data delivery capabilities. These four entities represent the competitive core where contract durations extend and vendor panels compress.
| Leading Market Players |
|---|
| MasTec Inc. |
| SGS SA |
| OCA Global |
| Intertek Group PLC |
| Fluor Corporation |
| Bonatti |
| GDI Sicim Pipelines |
| TC Energy Corporation |
| Pemex |
| Others |
Supply & Pricing Matrix
The Laredo-Matamoros freight corridor's diesel cost dynamics compress margins for welding equipment suppliers while amplifying price differentiation between NOM-001-SECRE certified contractors and uncertified competitors across Tamaulipas and Nuevo León project sites.
Pricing Analysis
ASEA integrity management programs dictate the pricing tier structure for pipeline services across Mexico's energy corridors. Three-tier pricing structure across premium, standard, and economy levels separates ASEA-certified inspection providers with real-time SCADA integration from basic maintenance contractors and uncertified regional operators. Cost compression in the economy tier intensifies because surplus labor from Veracruz and Tabasco migrates northward, while petroleum companies demonstrate the lowest price sensitivity due to regulatory non-compliance penalties. Utilities and industrial plants concentrate procurement volume to extract standard-tier discounts.
Supply Chain Analysis
US export controls on electromagnetic acoustic transducer arrays and high-resolution ultrasonic testing modules constrain equipment flows to Mexican inspection contractors. Manufacturing concentration rests on the United States, Germany, and China for inline inspection tool fabrication, with carbon steel line pipe drawing from domestic Altamira mills and US Gulf Coast producers. Supply chain risk centers on single-source vulnerability for smart pigging calibration services, which distribution runs through Houston and Monterrey technical centers to Burgos Basin and Southeast corridor assignments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's pipeline services market rewards regulatory entrenchment as a defensive moat, where ASEA certification requirements and NOM-001-SECRE welding protocols create switching costs that lock petroleum companies into established contractor relationships.
For Market Incumbents: Harden multi-year integrity management program penetration by embedding predictive maintenance algorithms into Pemex service agreements, countering emerging digital-native inspection platforms. Expand captive welding training capacity in Reynosa and Tampico to offset certified inspector scarcity, securing labor arbitrage against regional competitors.
For New Entrants and Emerging Players: Southeast production corridor offshore tieback infrastructure in Tabasco and Campeche represents the most penetrable entry point, given underdeveloped local contractor density and hydrocarbon law amendment uncertainties delaying incumbent commitment. Position through subsea maintenance specialization and rapid SEMARNAT environmental clearance capabilities as differentiated go-to-market angle.
For Investors and Strategic Acquirers: Regional maintenance contractors with established emergency response retainers and cathodic protection expertise anchor acquisition value, given their recurring revenue streams and regulatory relationship depth. Monitor ASEA enforcement intensity around real-time pressure monitoring mandates as inflection indicator for compliance-driven consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Pigging Technology Licensing | Accelerates inline inspection deployment across aging Pemex gathering systems in Burgos Basin. |
| Backward Integration into Welding Training | Captures certified labor pipeline scarcity premium in Tamaulipas and Veracruz markets. |
| ASEA Certification Program Investment | Locks multi-year revenue streams under mandatory inspection frequency enforcement rules. |
| Joint Venture with SCADA Platform Providers | Enables real-time data fusion offerings for predictive maintenance contract expansion. |
| Geographic Expansion to Ciudad del Carmen | Positions for Southeast corridor offshore tieback infrastructure growth under hydrocarbon law revisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ASEA regulatory filings, Pemex procurement disclosures, and customs import records for specialized welding equipment. Conversations with pipeline integrity managers at natural gas utilities, procurement leads at integrated service providers, and technical directors at non-destructive testing laboratories informed demand-side validation. Secondary sources include SEMARNAT environmental clearance databases, NOM-001-SECRE certification registries, and cross-border trade statistics. Bottom-up project pipeline aggregation triangulates against top-down energy infrastructure investment tracking.
Forecast inputs incorporate service type segmentation by construction, inspection, maintenance, and logistics categories, alongside pipeline diameter tiers and fluid-type applications across the analysis window. CAGRs derive from regression against historical Pemex capital expenditure patterns and CFE power generation feedstock commitments. Modeling integrates hydrocarbon law amendment scenarios and smart pigging technology adoption curves as industry-specific variables.
Practitioners should monitor ASEA enforcement intensity, SEMARNAT clearance timeline volatility, and smart pigging equipment import availability for early signals of forecast deviation. Forecasts reflect assumptions around regulatory continuity and Pemex modernization funding stability. Material shifts in hydrocarbon law third-party access rules or Pemex financial restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market