
 Electric Power Transmission and Distribution Equipment Market | 2026-2036
Electric Power Transmission and Distribution Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Power Transmission and Distribution Equipment Market Intelligence
Direct utility procurement is rewriting how transmission and distribution equipment reaches end users, with long-term framework agreements displacing spot purchasing across major markets. ABB Ltd. leverages its digital substation portfolio to anchor premium positioning in European utility tenders. Siemens Energy AG competes through in-house production of gas-insulated switchgear, while Hitachi Energy specializes in high-voltage direct current interconnector systems.
Electric power transmission and distribution equipment encompasses transformers, switchgear, cables, and circuit breakers engineered to handle voltage levels from low through extra high voltage, typically operating at frequencies of 50–60 Hz with insulation classes rated up to 1,200 kV. This apparatus forms the backbone of grid infrastructure, enabling bulk power transfer from generation sources to load centers while maintaining voltage stability and fault isolation. Transformers represent the most mature margin pool, with replacement cycles driving steady aftermarket revenue, while extra high voltage switchgear captures the fastest growth trajectory as offshore wind and cross-border interconnection projects multiply. The voltage level dimension reveals a structural split: low and medium voltage equipment serves dense urban underground networks, whereas high and extra high voltage segments concentrate in overhead transmission corridors and substation installations.
FERC Order 2222 in the United States, the EU Green Deal's grid integration targets, and China's GB standards for ultra-high voltage equipment collectively shape product certification requirements and market access conditions across the three largest demand centers. India's CEA mandates and the PLI scheme for power equipment are tightening domestic content rules, redirecting supply chain localization for multinational vendors. Stakeholders must monitor how divergent grid codes and carbon-border adjustments reshape competitive access across these regulatory jurisdictions.
Market Dynamics
Grid modernization mandates and renewable integration targets are forcing utilities to replace aging infrastructure with digitally enabled high-voltage equipment, compressing traditional equipment replacement cycles and rewiring supplier-buyer relationships.
Growth Catalysts
- Offshore Wind Interconnection:North Sea and East Asian offshore wind clusters require extra high voltage submarine cables and converter stations. Developers in Germany, the United Kingdom, and China are tendering HVDC systems at accelerating frequency.
- FERC Order 2222:This US regulation mandates grid operators to accommodate distributed energy resources, driving substation automation and smart switchgear procurement across American utilities.
- Copper and Rare Earth Processing:Advanced magnetic materials and high-purity copper winding techniques are extending transformer efficiency ratings, enabling smaller footprint designs for urban underground substations.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:Six integrated steelmakers control 80% of transformer core material supply, with Japanese and South Korean producers dominating premium grades.
- SF6 Gas Regulatory Pressure:The EU F-Gas Regulation and parallel EPA scrutiny in the United States are phasing out sulfur hexafluoride insulation, forcing costly switchgear redesign before alternatives achieve scale.
- Ultra-High Voltage Certification Timelines:China's GB standards and IEC 62271 series require 18-36 month type-testing protocols for 800 kV+ equipment, freezing new entrants from fast-follower positions.
Strategic Opportunities
- India's PLI Localization Requirements:The Production Linked Incentive scheme for power equipment mandates 50% domestic value addition, creating joint-venture openings for component suppliers in transformer and switchgear sub-assemblies.
- Digital Twin Integration:Convergence of IoT sensors and physics-based modeling enables predictive maintenance contracts, shifting revenue from equipment sales to lifecycle service agreements.
- Urban Underground Network Expansion:Dense Asian megacities—Jakarta, Manila, Dhaka—are burying medium voltage distribution, opening demand for gas-insulated switchgear and dry-type transformers in space-constrained substations.
Industry Challenges
- HVDC Control Systems Engineering:Converter station projects face 12-18 month delays as utilities compete for scarce power electronics specialists capable of integrating modular multilevel converter topology.
- Legacy SCADA Integration:Brownfield substation upgrades require protocol translation between IEC 61850 digital systems and proprietary 1980s-era remote terminal units, inflating commissioning costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Power Transmission and Distribution Equipment Market |
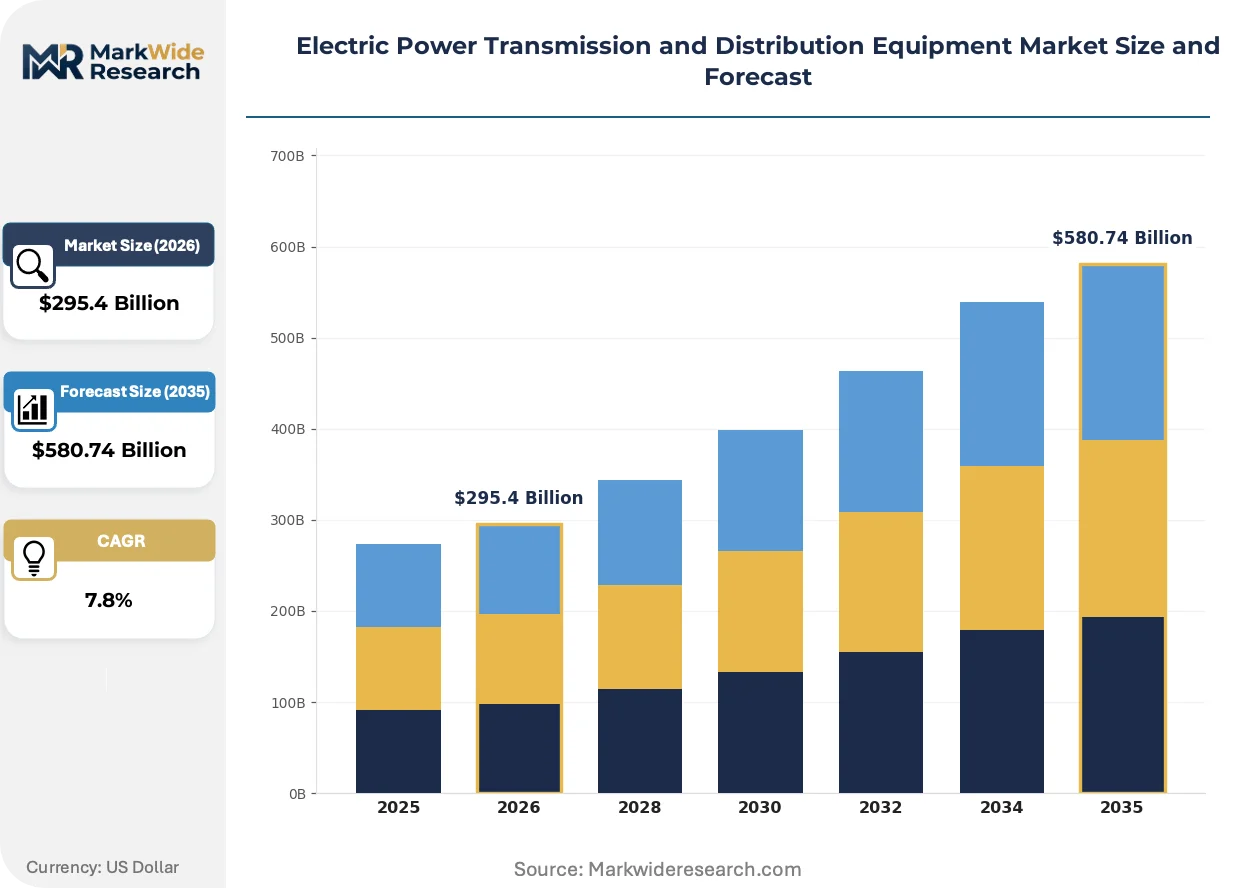
| Market Size in 2026 | $295.4 Billion |
| Market Size in 2035 | $580.74 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Switchgear, Cables, Circuit Breakers End User: Utilities, Industrial, Commercial, Residential Installation Type: Overhead, Underground, Hybrid, Substation Voltage Level: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | ABB Ltd., Schneider Electric SE, Siemens Energy AG, GE Vernova, Eaton Corporation plc, Mitsubishi Electric Corporation, Hitachi Energy, Bharat Heavy Electricals Limited, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Power Transmission and Distribution Equipment Market Strategic Shifts & Innovations
Solid-state power electronics and synthetic insulating media are displacing electromechanical and SF6-dependent architectures, while procurement centralization among national transmission operators compresses vendor margins and rewards integrated solution providers.
Silicon carbide power semiconductors is collapsing the physical footprint of medium-voltage power converters. Wind farm developers in Denmark and turbine OEMs are specifying SiC-based MVDC collection systems for offshore arrays. The technology eliminates bulky line-frequency transformers, enabling platform-mounted converter stations that halve installation vessel days.
China's GB/T 25020 series for ultra-high voltage equipment certification entered mandatory enforcement in 2023, requiring domestic testing laboratory accreditation for all 1,000 kV+ product registrations. Foreign manufacturers face 24-30 month requalification timelines, advantaging state-grid affiliated suppliers in domestic tenders while forcing multinationals to license core insulation designs to local partners.
Long-term framework agreements are displacing spot purchasing across European transmission system operators. TenneT, National Grid, and RTE have consolidated 70% of their 2024-2028 transformer procurement into four-year sole-source contracts with penalty clauses for delivery delays. Equipment vendors are accepting thinner margins in exchange for volume certainty, while redirecting engineering resources from tender response to manufacturing throughput optimization.
Electric Power Transmission and Distribution Equipment Market Segmentation
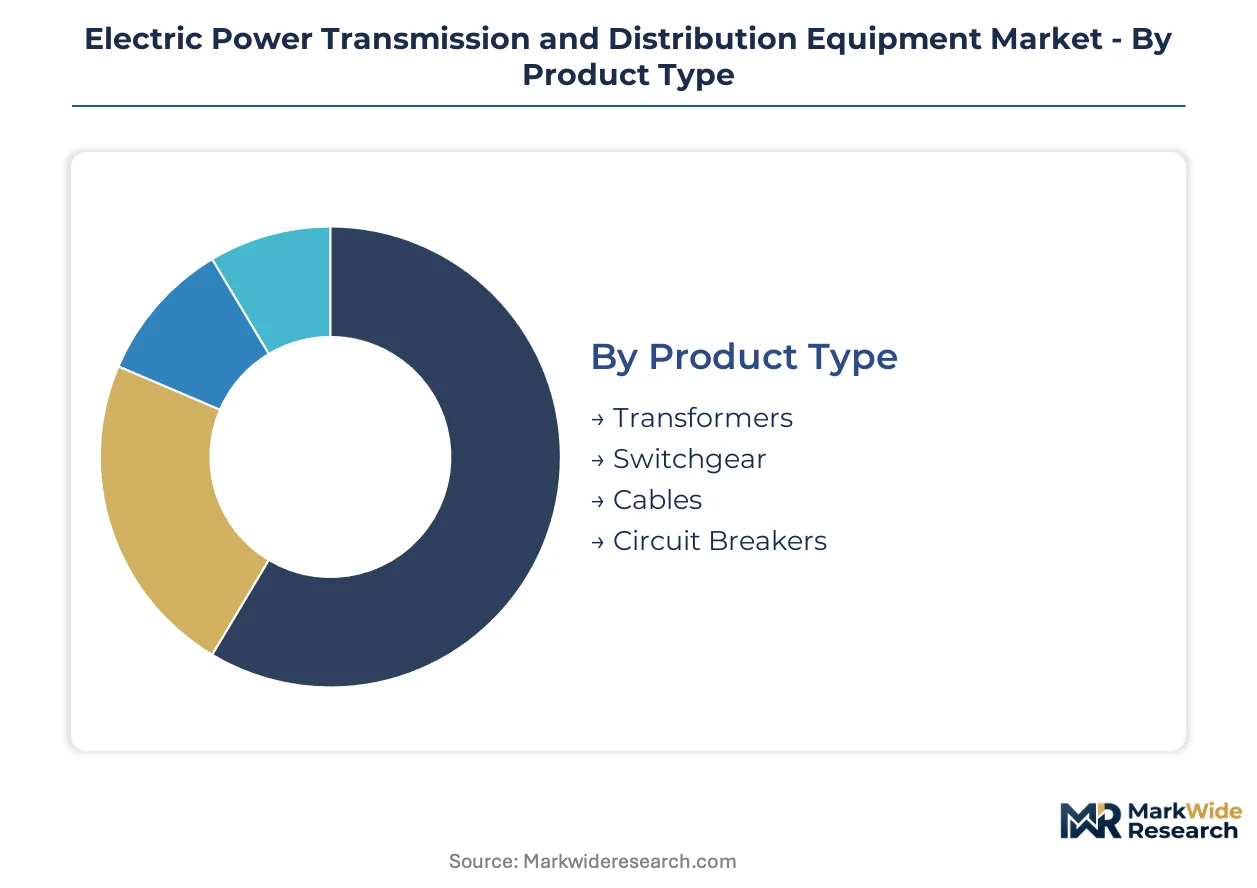
Equipment segmentation in this market tracks replacement cycles that range from 15-year cable overlays to 40-year transformer lifespans. Procurement strategies diverge sharply between utilities managing steady-state renewal and developers building new interconnection capacity.
Product Type:
Transformer assets turn over slowest at 30-40 year cycles, while circuit breaker refurbishment runs fastest at 10-15 year intervals, creating divergent revenue predictability across supplier portfolios.
- Transformers:Oil-immersed and dry-type designs step voltage across generation, transmission, and distribution stages. Replacement demand concentrates in North American utilities facing 1970s-era infrastructure retirement, constrained by grain-oriented electrical steel supply concentration among Japanese and South Korean producers.
- Switchgear:Gas-insulated and air-insulated assemblies enable circuit protection and load switching. Offshore wind developers in Germany and the United Kingdom are tendering extra high voltage gas-insulated switchgear at accelerating frequency for platform-mounted substations, though SF6 phase-out regulations are forcing costly redesign timelines.
- Cables:Underground and submarine conductors transmit power across land and water barriers.
- Circuit Breakers:Electromechanical and hybrid interruption devices isolate fault conditions.
Transformers dominate installed base. Switchgear is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive utility procurement from price-sensitive residential installations, with industrial buyers occupying a mid-tier position demanding performance guarantees.
- Utilities:Transmission system operators and distribution utilities procure equipment through multi-year framework agreements. State Grid Corporation of China and TenneT in the Netherlands anchor global procurement volume, consolidating transformer and switchgear demand into sole-source contracts with penalty clauses for delivery delays.
- Industrial:Manufacturing complexes, data centers, and mining operations require dedicated substations. Heavy industry in India is expanding captive power infrastructure under CEA mandates, redirecting medium voltage switchgear procurement toward domestic suppliers meeting PLI localization thresholds.
- Commercial:Office complexes, retail centers, and institutional buildings purchase distribution equipment.
- Residential:Single-family and multi-unit housing developments specify low voltage panels and service entrance equipment.
Utilities command pricing power through volume concentration. Industrial buyers are gaining negotiating leverage through standardization.
Installation Type:
Application context determines equipment specification, with urban density forcing underground solutions that carry 2-3x cost premiums over overhead alternatives.
- Overhead:Lattice towers and pole-mounted equipment carry transmission corridors across rural and suburban terrain. Utilities in the United States maintain extensive overhead networks, though storm hardening investments are accelerating replacement of wooden structures with steel monopoles.
- Underground:Buried cables and vault-mounted switchgear serve dense urban cores. Jakarta, Manila, and Dhaka are expanding medium voltage underground distribution, opening demand for gas-insulated switchgear and dry-type transformers in space-constrained substations.
- Hybrid:Mixed overhead-underground configurations optimize cost and reliability.
- Substation:Dedicated facilities house transformation and switching equipment.
Overhead retains cost advantage for greenfield corridors. Underground is climbing the fastest in revenue contribution.
Voltage Level:
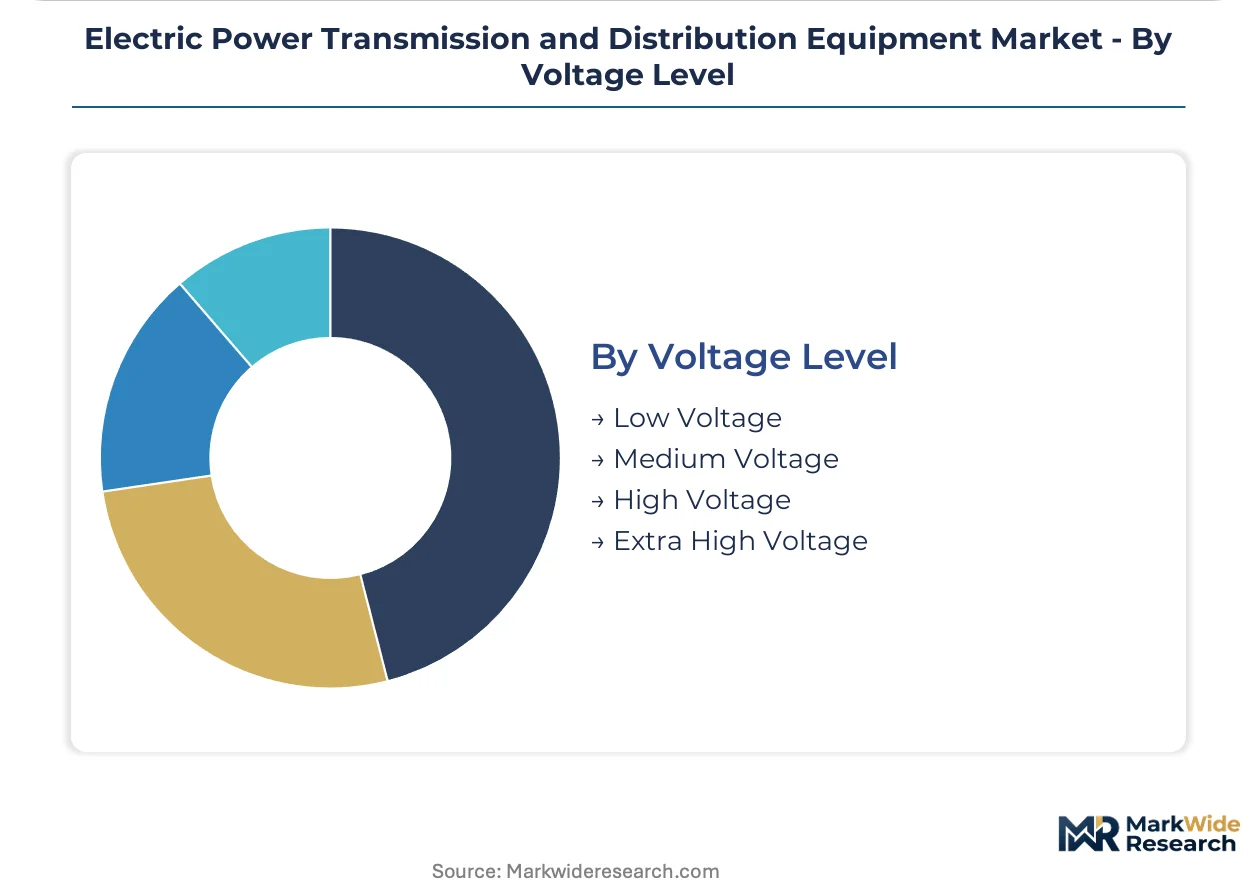
Margin structure inverts across the voltage spectrum, with extra high voltage equipment capturing technology premiums despite lower unit volumes.
- Low Voltage:Distribution equipment operating below 1 kV serves final customer connections. Residential and commercial building codes in the United States and European Union drive steady replacement demand, with smart meter integration requiring panel upgrades.
- Medium Voltage:Equipment rated 1-52 kV distributes power across urban networks. Distribution utilities in India are modernizing 11 kV and 33 kV infrastructure under the government's rural electrification program, creating sustained demand for ring main units and compact substations.
- High Voltage:Transmission equipment rated 52-245 kV interconnects regional grids.
- Extra High Voltage:Systems above 245 kV enable bulk power transfer over long distances.
Medium voltage anchors revenue volume. Extra high voltage is gaining share fastest on interconnection investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Three Gorges Dam-to-Shanghai ultra-high voltage corridor anchors China's position as the world's largest transmission equipment procurement market. State Grid Corporation of China operates the world's most extensive UHVDC network spanning over 30,000 kilometers. Grid interconnection projects across Germany, India, and the United States concentrate demand for high-voltage switchgear and converter stations.
China
State Grid Corporation tenders 1,000 kV transformer and gas-insulated switchgear contracts exceeding $15 billion annually through 2030. GB standards for ultra-high voltage equipment entered mandatory enforcement in 2023, requiring domestic laboratory accreditation for product registrations. The Yangtze River Delta corridor between Shanghai and Hefei hosts concentrated manufacturing clusters for converter station components serving offshore wind interconnection.
Germany
TenneT and 50Hertz tender HVDC submarine cable systems for North Sea offshore wind clusters at accelerating frequency. The EU F-Gas Regulation phases out SF6 insulation, forcing switchgear redesign timelines for domestic and multinational suppliers. The Hamburg-Bremen industrial corridor concentrates engineering capacity for platform-mounted converter stations serving the SuedLink interconnector.
India
Power Grid Corporation of India and state utilities modernize 765 kV and 400 kV corridors under the National Grid program. CEA mandates and the PLI scheme for power equipment require 50% domestic value addition, redirecting procurement toward joint-venture suppliers. The Gujarat-Maharashtra western region anchors manufacturing clusters for transformer and switchgear sub-assemblies meeting localization thresholds.
United States
Utilities face 1970s-era transformer replacement cycles while FERC Order 2222 mandates distributed energy resource accommodation. The EPA parallels EU F-Gas scrutiny on SF6 phase-out, compressing switchgear redesign windows. The Texas ERCOT interconnection and California ISO corridor concentrate procurement for smart substation automation and high-voltage circuit breakers.
United Kingdom
National Grid consolidates 2024-2028 transformer procurement into four-year framework agreements with penalty clauses for delivery delays. The North Sea offshore wind build-out drives demand for HVDC interconnector systems linking Scottish generation to English load centers. The Humber industrial cluster hosts converter station fabrication facilities serving Dogger Bank and Hornsea wind developments.
Electric Power Transmission and Distribution Equipment Market Key Industry Players
On the supply side, the industry is consolidating around integrated solution providers capable of delivering turnkey substation packages spanning transformers, switchgear, and control systems. Tiered competitive positioning separates premium digital substation vendors from commodity equipment fabricators. Two strategic archetypes dominate: European-Japanese engineering conglomerates with in-house UHVDC capability, and emerging-market state-affiliated manufacturers leveraging domestic content mandates. Competitive moves concentrate on joint-venture localization and technology licensing partnerships to circumvent certification barriers.
Within the premium-tier integrated solutions segment, ABB Ltd. and Siemens Energy AG exemplify archetypes combining digital substation portfolios with captive gas-insulated switchgear production. Hitachi Energy occupies a specialized position representing HVDC interconnector system capability. Among emerging-market fabricators, Bharat Heavy Electricals Limited anchors state-affiliated supply responding to India's PLI localization requirements. Larsen & Toubro represents diversified engineering conglomerates extending construction capability into electrical equipment fabrication.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| Siemens Energy AG |
| GE Vernova |
| Eaton Corporation plc |
| Mitsubishi Electric Corporation |
| Hitachi Energy |
| Bharat Heavy Electricals Limited |
| Larsen & Toubro |
| Others |
Cost & Logistics Intelligence
Japanese and South Korean integrated steelmakers dominate premium grain-oriented electrical steel supply, anchoring transformer core material costs and concentrating margin capture upstream of equipment fabricators. This concentration forces downstream pricing discipline across high-voltage transformer procurement, where long-term framework agreements now embed steel price escalation clauses that transfer commodity volatility to utility buyers.
Pricing Analysis
Volume-discount tiering structures separate sole-source framework agreements from spot procurement across European and Chinese transmission system operators. Premium pricing attaches to IEC 61850-certified digital substation packages bundling transformers with integrated control systems, while standard tiers cover commodity air-insulated switchgear. Cost compression in medium-voltage distribution equipment intensifies as Indian domestic suppliers exploit PLI localization thresholds to undercut multinational landed costs. Industrial captive power buyers exhibit highest price sensitivity, whereas national transmission operators absorb premiums for delivery certainty and penalty-backed performance guarantees.
Supply Chain Analysis
Export-control regimes restricting power electronics and wide-bandgap semiconductor technology limit converter station component flows from United States and Japanese suppliers to Chinese HVDC project developers. Manufacturing gravity centers on China, Germany, and India for transformer assembly, with South Korea and Japan feeding critical magnetic core materials. The supply chain rests on high-purity copper cathode and rare earth permanent magnet dependencies, exposing fabricators to single-source vulnerability in heavy rare earth processing. Distribution runs through direct utility procurement channels consolidating 70% of European transformer demand into four-year sole-source contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state power electronics and synthetic insulating media pose substitution threats to electromechanical transformer and SF6-dependent switchgear architectures, forcing incumbents to defend installed base relationships through technology transition roadmaps.
For Market Incumbents: Entrench digital substation capabilities through captive gas-insulated switchgear production and predictive maintenance service contracts that shift revenue from equipment sales to lifecycle agreements. Prioritize certification investment in China's GB/T 25020 ultra-high voltage standards to preserve access to State Grid Corporation tenders, while backward integration into grain-oriented electrical steel sourcing mitigates Japanese and South Korean supplier concentration risk.
For New Entrants and Emerging Players: Pursue joint-venture localization in India's Gujarat-Maharashtra manufacturing corridor to satisfy CEA mandates and PLI domestic value addition thresholds for transformer and switchgear sub-assemblies. Target medium-voltage underground distribution equipment for Jakarta, Manila, and Dhaka, where space-constrained substations demand compact gas-insulated switchgear and dry-type transformers with limited incumbent penetration.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated solution providers combining HVDC converter station capability with in-house power electronics engineering, as offshore wind interconnection projects multiply across the North Sea and East Asian clusters. Long-term viability hinges on technology licensing partnerships that circumvent China's 24-30 month requalification timelines for foreign manufacturers. Watch F-Gas Regulation enforcement intensity as the signal for SF6 alternative switchgear adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | India's PLI scheme mandates 50% domestic value addition, redirecting supply chain geography. |
| Digital Twin Integration | IoT sensor convergence enables predictive maintenance contracts shifting revenue to services. |
| SF6 Alternative Development | EU F-Gas Regulation phase-out forces switchgear redesign before alternatives achieve scale. |
| HVDC Control Systems Investment | Converter station projects face specialist scarcity in modular multilevel converter topology engineering. |
| Framework Agreement Consolidation | TenneT and National Grid tender structures compress vendor margins in exchange for volume certainty. |
Research Approach
The analysis maps transformer, switchgear, cable, and circuit breaker sub-sectors, each validated through utility procurement officers, EPC contractor project managers, power equipment manufacturing executives, and grid operator planning engineers. Primary interview findings triangulate against secondary sources including FERC filings, IEA grid integration reports, State Grid Corporation tender disclosures, and IEC standards documentation. Bottom-up equipment shipment tracking reconciles with top-down utility capital expenditure forecasts across voltage level and installation type segments.
Assumption sets held regulatory enforcement timelines and commodity price corridors fixed while varying renewable interconnection project commissioning rates and domestic content threshold stringency across the projection horizon. The analytical framework models product type, end user category, installation context, and voltage level dimensions, with CAGRs derived from replacement cycle analysis and greenfield capacity addition pipelines. Forecast inputs incorporate grain-oriented electrical steel supply concentration and HVDC converter station engineering capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in copper and rare earth price trajectories or cross-border project finance availability would shift the trajectory. Forecasts reflect documented assumptions on regulatory phase-out schedules and infrastructure investment continuity. Material shifts in China's GB standards enforcement intensity or EU F-Gas Regulation alternative technology approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Transmission Housing Demand Market