
 Power Transmission Component Market | 2026-2036
Power Transmission Component Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transmission Component Market Analysis
Modular substation packaging is broadening buyer choice across utility and industrial procurement channels. Hitachi Energy leverages integrated transformer-switchgear assemblies to anchor premium positions in HVDC corridors. Siemens Energy competes through digital twin-enabled transmission asset management, while ABB Ltd. dominates medium-voltage component bundling for distribution networks.
Power transmission components encompass mechanical and electromechanical devices engineered to transfer rotational or electrical energy between generation sources and end-use loads, typically operating at torque ratings from kilonewton-meters to meganewton-meters and voltage classes spanning 1 kV to 800 kV. These assemblies serve critical functions in maintaining grid stability, enabling variable-speed operation, and isolating fault conditions across generation, transmission, and distribution infrastructure. Gearbox assemblies for wind turbine drivetrains command substantial margin pools given precision manufacturing requirements and extreme reliability specifications under IEC 61400. Bearing applications across industrial machinery and renewable energy represent the fastest-expanding consumption vector as OEMs specify ceramic hybrid and tapered roller configurations for extended service intervals. Electromechanical technology is displacing purely mechanical solutions in precision motion control, though hydraulic systems retain dominance in heavy-lift marine and mining conveyance where shock loading exceeds electric motor torque density.
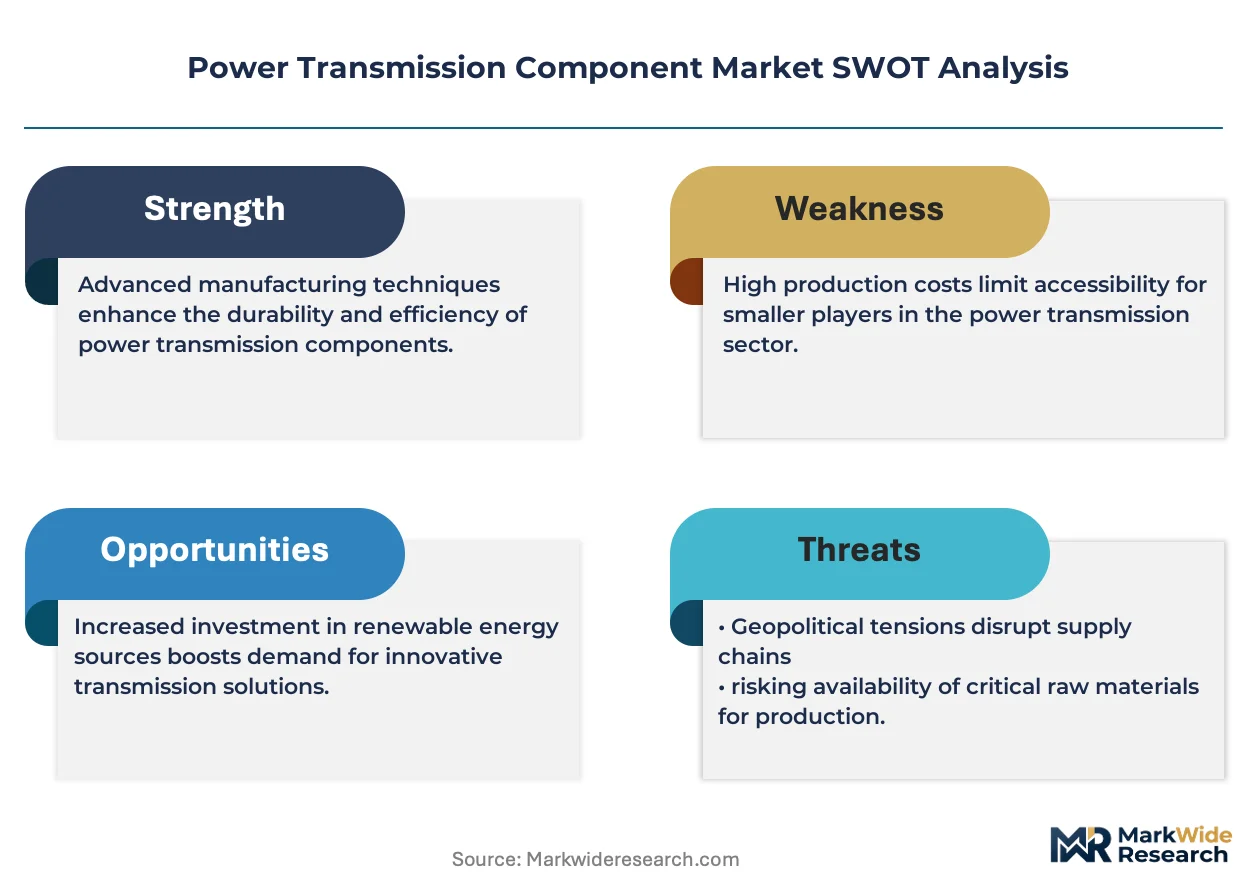
Grid codes issued by FERC and the EU's F-Gas Regulation are mandating sulfur hexafluoride phase-down in switchgear, redirecting R&D toward vacuum interrupter and solid insulation alternatives. China's GB standards and India's CEA technical specifications for transmission voltage levels are harmonizing product certification requirements, raising compliance costs for non-domestic suppliers. Stakeholders must monitor evolving material efficiency mandates and localized content rules as governments tie infrastructure subsidies to domestic manufacturing thresholds.
Market Dynamics
Offshore wind drivetrain specifications are forcing gearbox and bearing manufacturers to reconfigure production footprints around coastal assembly hubs, compressing lead times for multi-megawatt nacelle deliveries.
Growth Catalysts
- US Inflation Reduction Act Production Tax Credits:Domestic content bonuses for clean energy hardware are accelerating capital deployment into American gearbox and transformer manufacturing facilities.
- EU F-Gas Regulation phase-down mandates:Sulfur hexafluoride restrictions in switchgear are redirecting procurement toward vacuum interrupter and solid insulation alternatives across European transmission utilities.
- China's GB standards harmonization:Unified certification requirements for 800 kV class equipment are consolidating supplier qualification pools and favoring integrated component bundlers.
Market Restraints
- Specialized steel alloy supply concentration:Vacuum-degassed bearing steel production centers on a limited number of European and Japanese mills, exposing component makers to input volatility.
- IEC 61400-4 certification timelines:Wind turbine gearbox type certification requires 18-24 month validation cycles that delay revenue recognition for new platform introductions.
- Hydraulic torque density advantage:Electric drivetrains face substitution pressure in marine heavy-lift and mining conveyance applications where shock loading exceeds electromechanical limits.
Strategic Opportunities
- India transmission infrastructure buildout:Central Electricity Authority voltage specifications are creating demand for 765 kV class switchgear and transformer assemblies from qualified foreign suppliers.
- Digital twin-enabled asset management:Convergence of physics-based modeling with IoT sensor networks is opening recurring revenue streams in predictive maintenance services.
- Brazil renewable integration corridors:Grid interconnection mandates for remote wind and solar sites are driving demand for modular substation packaging with integrated protection systems.
Industry Challenges
- Precision grinding technician scarcity:Gearbox bearing raceway finishing requires specialized skills that outpace vocational training program output in established manufacturing regions.
- Legacy SCADA integration complexity:New electromechanical monitoring systems must interface with decades-old utility control architectures without disrupting fault protection logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transmission Component Market |
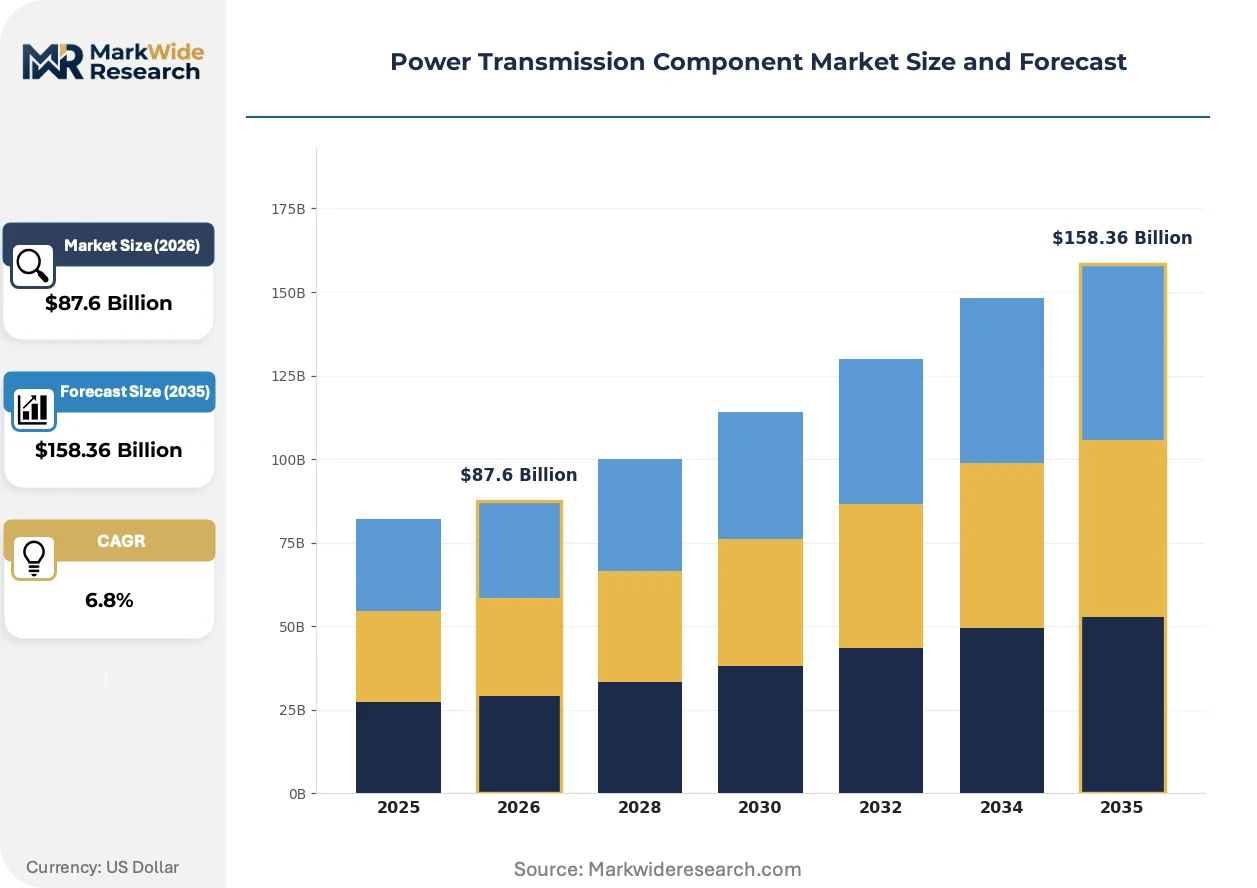
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gearbox, Coupling, Shaft, Bearing Application: Industrial Machinery, Renewable Energy, Automotive, Marine End User: Manufacturers, OEMs, Maintenance Providers, End Users Technology: Mechanical, Hydraulic, Pneumatic, Electromechanical |
| Companies Covered | Hitachi Energy, Schaeffler AG, Siemens Energy, Mitsubishi Electric Corporation, SKF AB, ABB Ltd., Eaton Corporation, Prysmian Group, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transmission Component Market Emerging Trajectories
Material science advances and digital instrumentation are compressing maintenance intervals while expanding operational envelopes for transmission hardware operating in extreme environments.
Ceramic hybrid bearing configurations combining silicon nitride rolling elements with steel raceways are overtaking conventional all-steel assemblies in wind turbine main shaft applications. OEMs specify these for 25-year design life requirements without intermediate replacement. The technology is compressing aftermarket service revenue pools while elevating upfront equipment margins.
EU F-Gas Regulation mandates are accelerating vacuum interrupter development for medium-voltage switchgear previously dependent on sulfur hexafluoride insulation. Manufacturers are redesigning chamber geometries to achieve comparable dielectric performance at higher mechanical stroke frequencies. Distribution network operators in Germany and France are piloting solid-insulation alternatives for underground urban installations.
Integrated transformer-switchgear assemblies are displacing site-commissioned component installations in utility procurement specifications. Buyers favor factory-tested modular packages that reduce field assembly duration and commissioning risk. This pattern is most visible in China's state-backed transmission infrastructure tenders and Middle Eastern greenfield industrial zone developments.
Power Transmission Component Market Segmentation
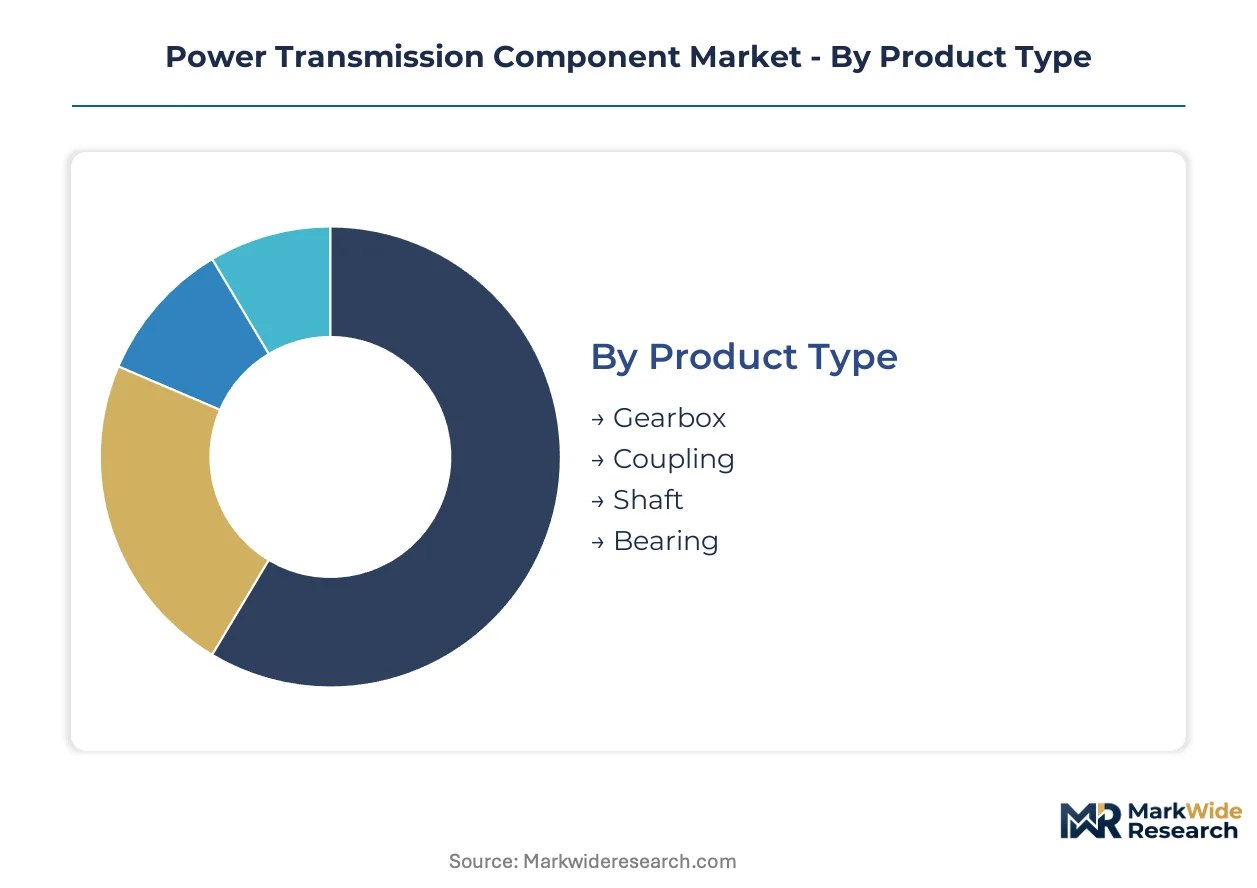
Component selection in power transmission hinges on torque density requirements, duty cycle intensity, and integration complexity with upstream generation assets. Procurement patterns diver sharply between capital-intensive renewable installations and maintenance-driven industrial replacement cycles.
Product Type:
Buyers differentiate primarily by precision tolerance thresholds and lifecycle cost projections rather than upfront unit economics.
- Gearbox:Multi-stage planetary and helical configurations dominate wind turbine drivetrains above 3 MW capacity. Offshore developers in China and Germany specify IEC 61400-4 certified units with 25-year design life. Gearbox assemblies command premium positioning due to vacuum-degassed alloy requirements and precision grinding labor scarcity.
- Bearing:Ceramic hybrid configurations combining silicon nitride rolling elements with steel raceways are displacing conventional all-steel assemblies in main shaft applications. Specifications from Vestas and Siemens Gamesa mandate these for extended service intervals without intermediate replacement.
- Coupling:Flexible disc and gear couplings accommodate misalignment in turbomachinery trains.
- Shaft:Hollow and solid forged shafts transmit torque in heavy industrial gearboxes and marine propulsion systems.
Gearbox leads volumes today; bearing is gaining share fastest.
Application:
Volume concentration tracks capital deployment cycles in energy infrastructure buildouts versus steady-state industrial maintenance.
- Renewable Energy:Wind turbine drivetrains and solar tracking systems absorb high-precision gearbox and bearing volumes. China's state-backed utilities execute the largest procurement programs for 5-8 MW offshore nacelles. EU Green Deal mandates accelerate HVDC corridor component qualification.
- Industrial Machinery:Mining conveyors, cement kilns, and steel rolling mills generate recurring demand for heavy-duty couplings and shaft assemblies. Replacement cycles dominate over greenfield installation.
- Automotive:Electric vehicle reduction gearboxes and differential assemblies require compact high-speed designs.
- Marine:Propulsion shafts and thruster gearboxes face hydraulic substitution pressure in heavy-lift cargo handling.
Industrial machinery leads volumes today; renewable energy is climbing the fastest.
End User:
Procurement authority splits between specification-setting OEMs and total-cost-optimizing maintenance operators.
- OEMs:Wind turbine manufacturers and industrial equipment builders lock in multi-year supply agreements for certified gearbox and bearing platforms. Siemens Energy and Hitachi Energy qualify suppliers against 18-24 month validation timelines.
- Maintenance Providers:Independent service contractors capture aftermarket bearing replacement and gearbox refurbishment revenue. Condition monitoring integration creates switching costs.
- Manufacturers:Tier-2 component fabricators source raw forgings and semi-finished bearing races.
- End Users:Utility and industrial asset owners specify integrated transformer-switchgear assemblies in direct procurement.
OEMs lead volumes today; maintenance providers are expanding most quickly.
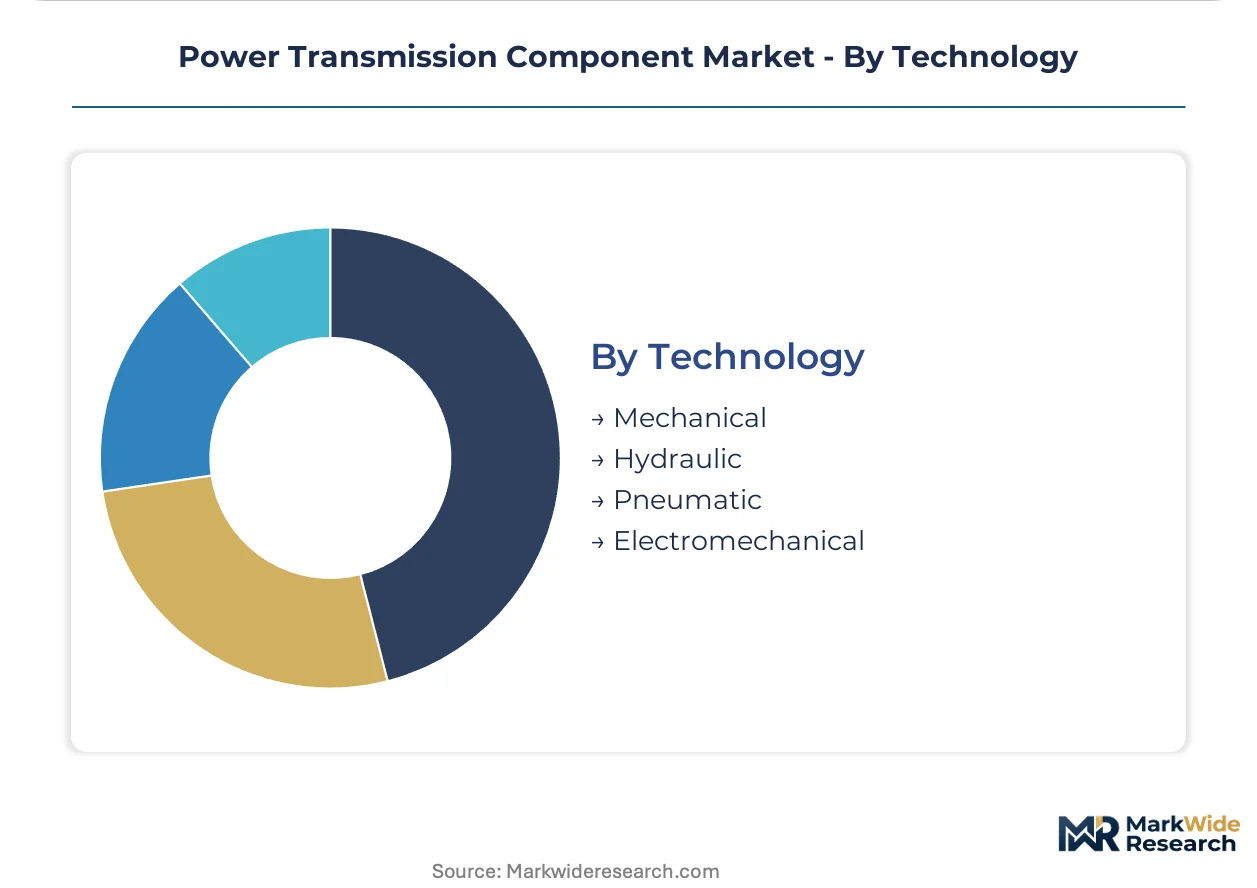
Technology:
Performance envelope and control precision determine technology selection against hydraulic torque density benchmarks.
- Electromechanical:Variable frequency drives and servo motor systems displace mechanical solutions in precision motion control. Digital twin integration enables predictive maintenance revenue streams.
- Mechanical:Gear trains and belt drives retain cost advantage in constant-speed applications with moderate torque requirements.
- Hydraulic:Piston pumps and motors dominate mining and marine applications where shock loading exceeds electric motor torque density.
- Pneumatic:Compressed air systems serve light-duty automation and hazardous environment actuation.
Mechanical leads volumes today; electromechanical shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision gearbox manufacturing for heavy industrial applications during the post-war industrial expansion. Japanese bearing specialists later established ceramic hybrid technologies that now dominate wind turbine specifications. Chinese state-backed infrastructure programs currently absorb the largest component volumes globally.
China
State Grid Corporation executes the world's largest transmission infrastructure buildout, procuring 800 kV class switchgear and transformer assemblies under harmonized GB standards. MIIT domestic content requirements favor qualified local suppliers for ultra-high-voltage corridors. Manufacturing clusters in Jiangsu and Shandong provinces supply precision bearing races and gearbox housings for offshore wind nacelles.
Germany
Offshore wind developers in the North Sea and Baltic specify IEC 61400-4 certified drivetrain components with 25-year design life. EU F-Gas Regulation mandates accelerate vacuum interrupter adoption across transmission utilities. Industrial gearbox fabricators in Baden-Württemberg and Bavaria serve both renewable energy OEMs and automotive electrification programs.
United States
Domestic content bonuses under the Inflation Reduction Act accelerate capital deployment into American gearbox and transformer manufacturing. FERC grid codes mandate enhanced monitoring capabilities for electromechanical transmission assets. Gulf Coast assembly hubs in Texas and Louisiana reconfigure production footprints to compress lead times for multi-megawatt offshore wind deliveries.
India
Central Electricity Authority voltage specifications for 765 kV class equipment create procurement opportunities for qualified foreign suppliers. PLI scheme incentives support domestic manufacturing of high-voltage switchgear and transformer components. Industrial corridors in Gujarat and Maharashtra concentrate bearing fabrication and precision machining capacity for power sector applications.
Japan
Wind turbine OEMs specify ceramic hybrid bearing configurations from domestic suppliers for main shaft applications in typhoon-prone installations. METI energy transition programs fund grid modernization with solid-insulation switchgear alternatives. Manufacturing clusters in Kansai and Chubu regions supply precision-ground gearbox components for industrial machinery and marine propulsion systems.
Power Transmission Component Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and precision tolerance thresholds. The supplier base stratifies into integrated system bundlers, specialized component fabricators, and aftermarket service operators. Three archetypes dominate: HVDC corridor specialists leveraging transformer-switchgear integration, digital twin-enabled asset managers, and precision bearing manufacturers with ceramic hybrid platforms. Capacity expansion into coastal assembly hubs and backward integration into vacuum-degassed alloy supply represent the dominant competitive vectors.
Within the integrated systems tier, Hitachi Energy and Siemens Energy occupy positions as archetype anchors for HVDC and digital-enabled service models respectively. Schaeffler AG exemplifies the precision component specialist archetype with ceramic hybrid bearing platforms. Among these named entities, geographic origins span Japanese-German-Swedish industrial heritage structures. Each represents distinct strategic positioning without overlapping core competence claims.
| Leading Market Players |
|---|
| Hitachi Energy |
| Schaeffler AG |
| Siemens Energy |
| Mitsubishi Electric Corporation |
| SKF AB |
| ABB Ltd. |
| Eaton Corporation |
| Prysmian Group |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Vacuum-degassed bearing steel index volatility cascades through three distinct pricing tiers, compressing margins for mid-market gearbox fabricators while amplifying premium capture for integrated suppliers with captive alloy supply. China's MIIT domestic content rules and the US Inflation Reduction Act procurement bonuses further stratify cost structures across regional supply bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 61400-4 certified offshore wind drivetrains from industrial replacement gearboxes and commodity bearing assemblies. Price differentiation hinges on certification grade and volume scale, with OEM procurement bundles commanding 40-60% premiums over spot aftermarket transactions. Cost compression in standard-tier mechanical components is intensifying because Chinese state-backed utilities consolidate qualification pools under harmonized GB standards. Maintenance providers exhibit highest price sensitivity due to condition monitoring switching costs, while offshore wind developers prioritize lifecycle cost over upfront unit economics.
Supply Chain Analysis
Single-source vulnerability sits with European and Japanese vacuum-degassed bearing steel mills that feed precision grinding operations across Germany, China, and the United States. Raw material dependencies draw from specialized steel alloys, silicon nitride ceramic powders, and copper winding conductors. Tariff exposure on alloy imports from Japan threatens input cost stability for North American gearbox manufacturers. Distribution runs through factory-tested modular packaging channels that displace site-commissioned installations in utility procurement specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Power Transmission Component Market functions as a stable compounder anchored by decade-long infrastructure replacement cycles and renewable energy capital deployment that resists cyclical downturns.
For Market Incumbents: Hedge against ceramic hybrid bearing commoditization by backward integration into silicon nitride powder supply and precision grinding technician training pipelines. Lock in multi-year OEM supply agreements before IEC 61400-4 certification timelines extend qualification windows for new entrants. Defensive consolidation of coastal assembly hub capacity protects market position as offshore wind nacelle deliveries compress lead time requirements. For New Entrants and Emerging Players: Capture white-space in India's 765 kV class switchgear qualification under CEA voltage specifications before domestic PLI scheme incentives mature. Target Brazil's renewable integration corridors for modular substation packaging with integrated protection systems. A digital twin-enabled predictive maintenance service model bypasses capital-intensive manufacturing barriers while generating recurring revenue streams. For Investors and Strategic Acquirers: Consolidation pressure builds where precision grinding labor scarcity intersects with extended IEC 61400-4 certification timelines that strand subscale competitors. Five-to-ten year viability favors integrated component bundlers with captive vacuum-degassed alloy supply and qualified positions in China's state-backed transmission tenders. Monitor F-Gas Regulation phase-down velocity in Europe as the signal indicating vacuum interrupter technology transition speed and stranded SF6 switchgear asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Degassed Alloy Supply | Captive steel supply insulates Hitachi Energy and Schaeffler AG from Japanese mill price volatility. |
| Coastal Assembly Hub Capacity Expansion | Texas and Louisiana facilities compress lead times for US Gulf Coast offshore wind nacelle deliveries. |
| Digital Twin Platform Development | Siemens Energy leverages physics-based modeling to anchor recurring predictive maintenance revenue streams. |
| Ceramic Hybrid Bearing Platform Scale-Up | Silicon nitride rolling element production secures 25-year design life positions in Vestas and Siemens Gamesa specifications. |
| Vacuum Interrupter Technology Transition | Solid insulation alternatives capture EU F-Gas Regulation-mandated procurement shifts away from sulfur hexafluoride switchgear. |
Methodological Framework
Bottom-up renewable energy and industrial machinery modeling reconciled against top-down transmission infrastructure tracking forms the analytical core of this study. Primary interviews with wind turbine OEM procurement directors, utility planning officers, gearbox plant managers, and aftermarket service contractors combined with secondary validation from FERC grid code filings, EIA capacity databases, IEA renewable integration reports, and customs trade data on vacuum-degassed steel alloy flows. Triangulation across supply-side capacity announcements and demand-side project development pipelines ensures cross-verified volume estimates.
Historical trendline analysis of gearbox and bearing shipment patterns across the projection horizon informs growth trajectory calibration. Segmentation dimensions span product type, application intensity, end-user procurement authority, and technology performance envelope. CAGRs derive from fitted growth curves adjusted for regulatory mandate implementation timelines and capital deployment cycle phasing. Forecast inputs incorporate offshore wind turbine capacity factor assumptions and grid modernization expenditure commitments under the EU Green Deal and US Inflation Reduction Act.
Raw material price volatility, certification timeline extensions, and regulatory harmonization delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about technology substitution rates and domestic content threshold enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Power Transmission Cables Market