
 South-East Asia DC Distribution Network Market | 2026-2036
South-East Asia DC Distribution Network Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia DC Distribution Network Market Analytics
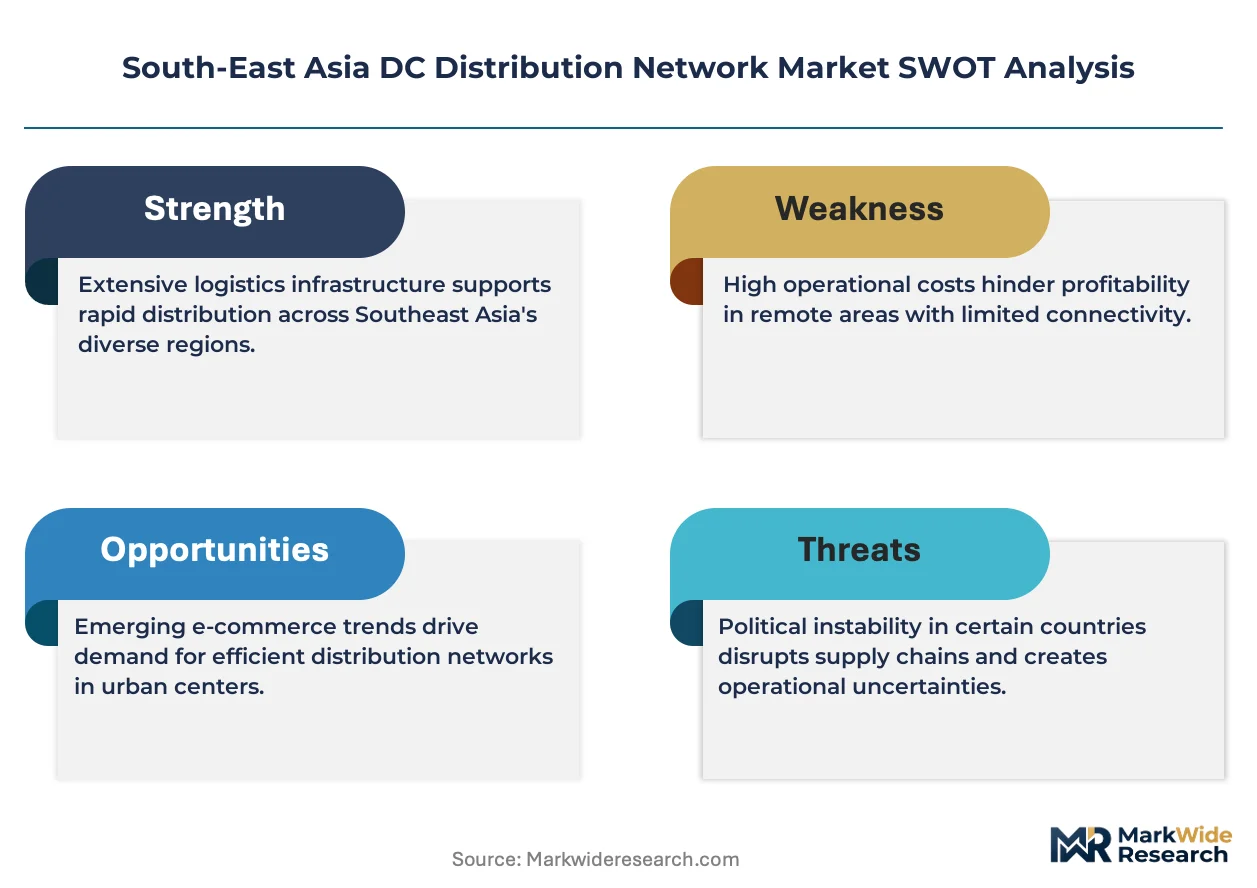
Thailand's Board of Investment incentive framework is hardening the cost-of-entry calculus for DC distribution network operators seeking warehouse automation permits. Schneider Electric SE leverages its regional manufacturing footprint to anchor smart power distribution solutions across Thai logistics parks. Siemens AG competes through its IoT-enabled warehouse management platforms, while Eaton Corporation Plc sustains market presence via specialized uninterruptible power systems for temperature-controlled facilities.
A DC distribution network comprises the integrated infrastructure of warehouses, sorting hubs, and last-mile nodes that manage direct-current power flows for automated material handling, robotics, and climate control systems, typically operating at voltages from 48V to 800V depending on load requirements. The primary purpose is to enable reliable, energy-efficient power delivery for high-throughput fulfillment centers serving time-sensitive supply chains. Cloud computing infrastructure underpins real-time inventory orchestration across multi-node networks, while last mile delivery services capture concentrated margin pools as urban density rises. IoT sensor networks represent the fastest-growing technology segment as operators pursue predictive maintenance and energy optimization.
Indonesia's Ministry of Industry enforces national standards for electrical infrastructure in commercial facilities, directly shaping equipment certification requirements for DC power systems deployed in Jababeka and Cikarang industrial zones. Singapore's Building and Construction Authority mandates green building certifications that accelerate demand for energy-efficient DC distribution architectures in new logistics developments. Malaysia's Energy Commission regulates grid interconnection standards for large-scale warehouse complexes, influencing backup power system specifications. Stakeholders must monitor evolving cross-border harmonization of ASEAN electrical standards as regional supply chain integration deepens and facility investments accelerate.
Market Dynamics
E-commerce cold-chain expansion is compressing deployment timelines for automated DC power infrastructure across Thailand, Vietnam, and Indonesia, forcing operators to integrate 48V-800V distribution systems before traditional grid upgrades complete.
Growth Catalysts
- Thailand BOI Smart Logistics Incentives:Tax holidays and import duty exemptions for automated warehouse equipment are accelerating permit approvals for DC distribution networks in Bangkok and Eastern Economic Corridor zones.
- IoT Sensor Networks:Predictive maintenance algorithms are reducing unplanned downtime in Vietnamese fulfillment centers by enabling real-time thermal monitoring of busbar systems and rectifier banks.
- Hanoi-Hai Phong Industrial Corridor:Concentrated electronics manufacturing and port infrastructure are creating dense demand clusters for high-reliability DC power in multi-tenant logistics parks.
Market Restraints
- Copper and Rare Earth Price Volatility:Input costs for busbar conductors and permanent magnet components in rectifier systems fluctuate with Chinese export quotas and Indonesian nickel processing constraints.
- Single-Source Semiconductor Dependency:Power MOSFET and IGBT module supply concentrates among Taiwanese and Japanese foundries, exposing Thai and Malaysian integrators to allocation risk.
- Indonesian SNI Certification Friction:Mandatory national standards testing for electrical infrastructure adds 4-6 months to equipment deployment timelines in Jababeka and Cikarang zones.
Strategic Opportunities
- Philippines Cold-Chain Gap:Underpenetrated refrigerated logistics infrastructure in Luzon and Visayas regions creates first-mover positioning for DC-powered automated storage and retrieval systems.
- Singapore BCA Green Mark Certification:Mandatory energy efficiency ratings for new industrial developments are accelerating specification of 380V DC distribution architectures over conventional AC-DC conversion chains.
- Edge Computing Convergence:Integration of micro data centers within warehouse facilities is creating hybrid power requirements that favor unified DC bus architectures serving both IT and material handling loads.
Industry Challenges
- Power Electronics Specialist Shortage:Southeast Asian labor pools lack sufficient technicians trained in 800V DC safety protocols and arc flash mitigation for high-density battery storage integration.
- Legacy AC Infrastructure Stranding:Brownfield warehouse retrofits face complex phasing decisions when existing 400V AC distribution cannot support simultaneous robotic and cooling loads without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia DC Distribution Network Market |
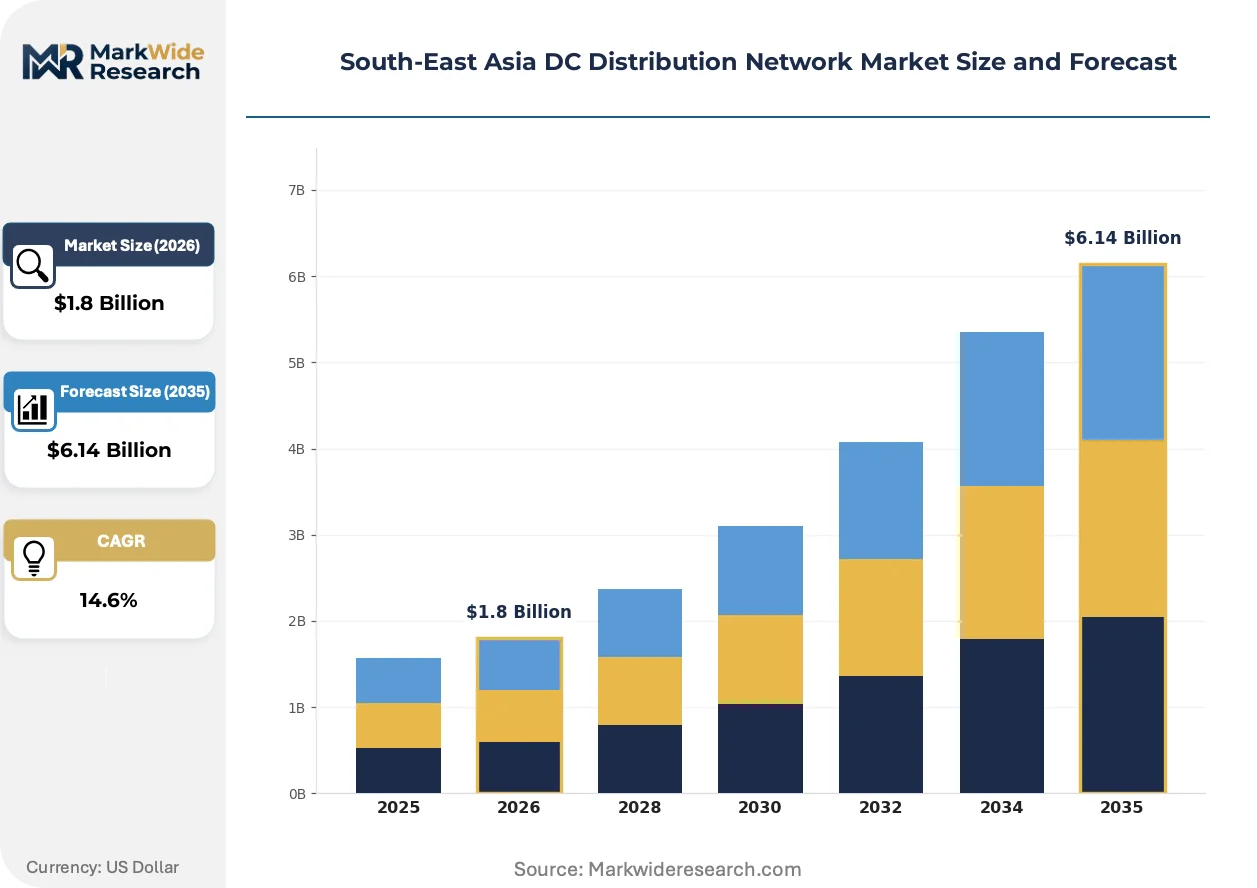
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Direct Sales, Online Retail, Wholesalers, Third-Party Logistics Technology: Cloud Computing, IoT, Blockchain, Artificial Intelligence Service Type: Last Mile Delivery, Cross-Docking, Warehousing, Inventory Management End User: E-Commerce, Retail Chains, SMEs, Large Enterprises |
| Companies Covered | ABB Ltd, Siemens AG, Eaton Corporation Plc, Schneider Electric SE, Vertiv Group Corp, Alpha Technologies SE, SGA SA, EPE Malaysia, Secheron SA, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia DC Distribution Network Market Evolving Landscape
Electrification of material handling equipment is forcing architectural choices between centralized and distributed DC power topologies, with implications for energy recovery, fault isolation, and modular expansion capacity.
Silicon carbide (SiC) power semiconductors are automating efficiency gains in rectifier and DC-DC conversion stages, enabling 98.5% system efficiency at 800V operating points. Thai and Vietnamese logistics operators are specifying SiC-based equipment for new greenfield developments where total cost of ownership calculations favor premium upfront capital. This technology is automating the displacement of legacy silicon IGBT systems in facilities above 10MW aggregate load.
Singapore's Building and Construction Authority Green Mark 2021 revision mandates minimum power usage effectiveness for data-intensive logistics facilities, directly accelerating DC distribution adoption in new Pasir Panjang and Tuas developments. The regulation compresses payback thresholds for high-voltage DC architectures by embedding energy efficiency into lease certification requirements. Cold-chain operators with temperature-controlled pharmaceutical storage face the strictest compliance timelines.
Third-party logistics providers are unbundling power infrastructure ownership from warehouse lease agreements, creating equipment-as-a-service models where DC system providers retain asset risk. Vietnamese e-commerce platforms prefer operational expenditure structures that transfer technology obsolescence risk to specialized power contractors. This shift concentrates in northern industrial zones where capital constraints limit direct infrastructure ownership by tenant firms.
South-East Asia DC Distribution Network Market Segmentation
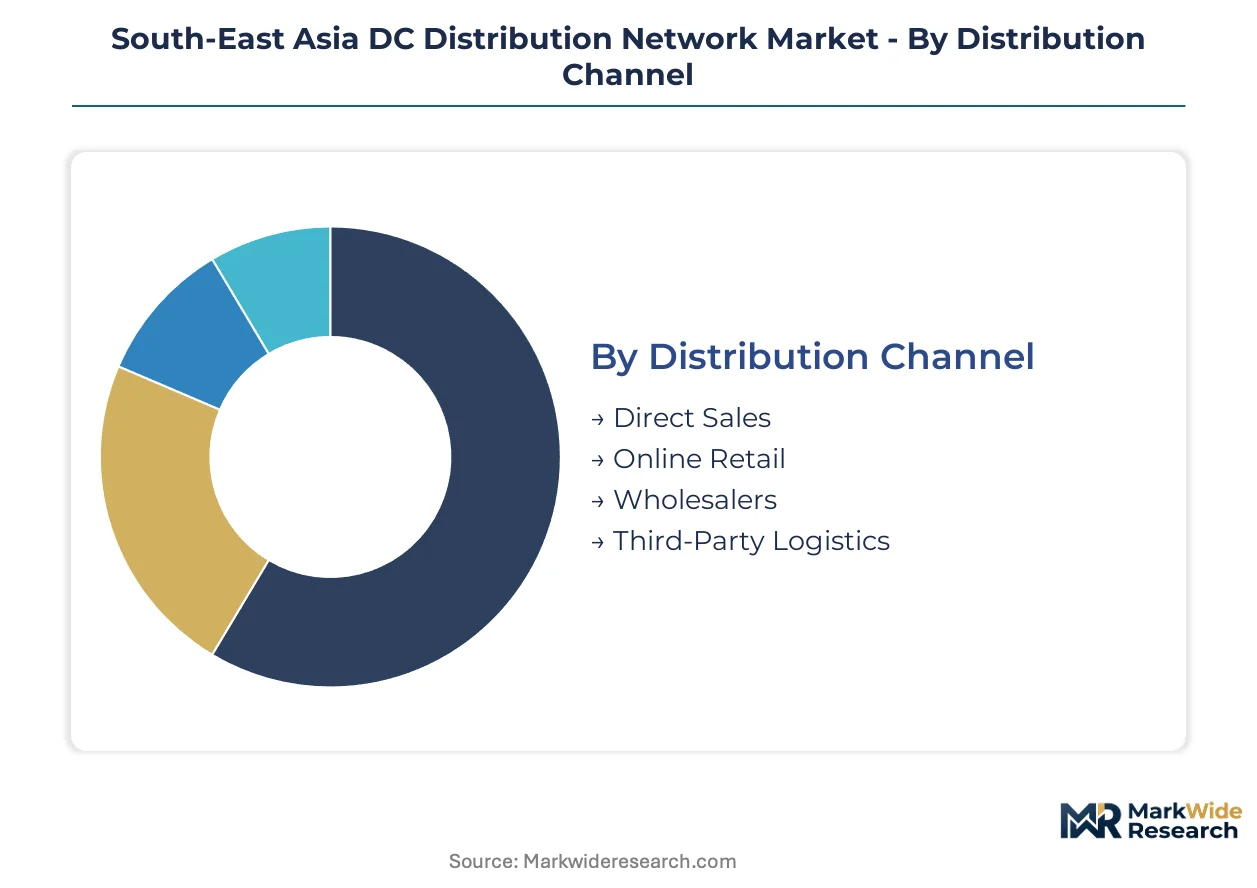
DC distribution network procurement patterns diverge sharply across buyer sophistication, operational scale, and technology readiness. Segment boundaries are blurring as Vietnamese e-commerce platforms and Thai logistics parks consolidate multi-service contracts under single infrastructure providers.
Distribution Channel:
Channel selection tracks directly with buyer technical capability and deployment urgency across Southeast Asian industrial zones.
- Direct Sales:Manufacturers deploy application engineering teams to specify 380V-800V busbar configurations for Bangkok and Eastern Economic Corridor logistics parks. Thai Board of Investment incentive deadlines compress procurement cycles, forcing direct engagement to secure permit-aligned delivery schedules.
- Third-Party Logistics:3PL operators bundle DC power infrastructure into warehouse lease agreements, transferring asset ownership risk to specialized contractors. Vietnamese e-commerce platforms in the Hanoi-Hai Phong corridor prefer this structure to preserve capital for core platform investments.
- Online Retail:Standardized 48V-240V rectifier systems for smaller fulfillment centers move through regional B2B platforms serving Indonesian SMEs in Cikarang zones.
- Wholesalers:Electrical distributors stock modular DC distribution components for emergency replacement in mature Malaysian logistics facilities.
Direct Sales leads volumes today; Third-Party Logistics is gaining share fastest.
Technology:
Technology deployment correlates with facility automation intensity and real-time orchestration requirements.
- IoT:Sensor networks monitoring busbar thermal performance and rectifier efficiency are becoming standard in Vietnamese multi-tenant logistics parks. Predictive maintenance algorithms reduce unplanned downtime by enabling preemptive component replacement before fault escalation.
- Cloud Computing:Real-time inventory orchestration platforms require resilient DC power architectures with sub-20ms transfer times during grid disturbances. Singapore's Building and Construction Authority Green Mark certification mandates cloud-enabled energy monitoring for new Pasir Panjang developments.
- Artificial Intelligence:Load forecasting algorithms optimize battery cycling patterns in Thai cold-chain facilities with pharmaceutical storage requirements.
- Blockchain:Immutable power quality records support insurance claims and warranty enforcement for high-value DC infrastructure deployments.
IoT dominates installed base; Cloud Computing shows steepest expansion trajectory.
Service Type:
Service bundling reflects margin concentration and infrastructure sharing economics in dense urban logistics clusters.
- Warehousing:Automated storage and retrieval systems demand 800V DC distribution with regenerative braking energy recovery. Thailand's smart logistics park incentives accelerate specification of integrated power and material handling contracts.
- Last Mile Delivery:Electric vehicle fleet charging infrastructure at urban micro-fulfillment centers requires 480V DC fast-charging integration with facility bus architectures. Singapore's urban density creates concentrated demand for combined warehouse and fleet power systems.
- Cross-Docking:High-throughput sortation facilities in Vietnam's northern industrial corridor need rapid DC power reconfiguration as product mix shifts seasonally.
- Inventory Management:RFID-enabled tracking systems depend on stable 48V DC supply for continuous scanner operation.
Warehousing commands revenue concentration; Last Mile Delivery is climbing the fastest.
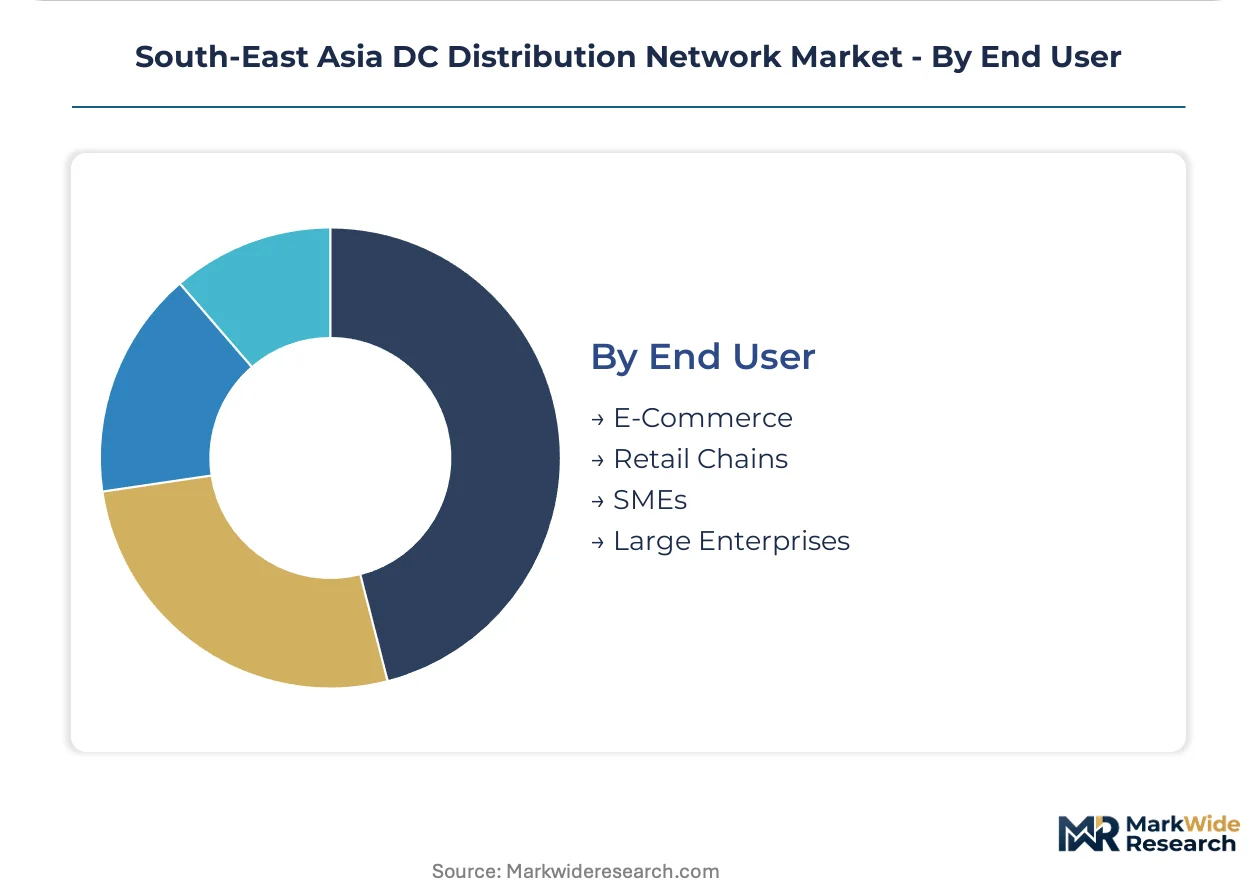
End User:
End-user scale determines specification authority and technology risk tolerance in procurement decisions.
- E-Commerce:Platform operators in Indonesia and Vietnam drive standardization of modular DC architectures across multiple fulfillment nodes. Jababeka industrial zone deployments prioritize rapid replication over customization to accelerate network coverage.
- Large Enterprises:Electronics manufacturers near Hai Phong port specify redundant 800V distribution with silicon carbide rectifiers for 98.5% system efficiency. Capital availability supports premium upfront investment for total cost of ownership optimization.
- Retail Chains:Grocery operators expanding cold-chain networks in the Philippines specify DC-powered automated storage for temperature-controlled pharmaceutical and fresh product handling.
- SMEs:Smaller logistics operators in Malaysian industrial zones lease standardized DC infrastructure through equipment-as-a-service arrangements to avoid technology obsolescence risk.
E-Commerce anchors current demand; Large Enterprises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled power electronics technicians concentrate in Thailand's Eastern Economic Corridor and Vietnam's northern industrial zones, anchoring regional deployment capacity for high-voltage DC infrastructure. This talent distribution shapes where automated warehouse investments achieve fastest commissioning timelines.
Thailand
Smart logistics park incentives from the Board of Investment compress permit approval cycles for automated DC distribution networks. Bangkok and Eastern Economic Corridor zones prioritize 380V-800V busbar configurations aligned with tax holiday deadlines. Rayong and Chonburi industrial clusters host concentrated deployments serving automotive and electronics supply chains.
Vietnam
E-commerce cold-chain expansion drives specification of redundant DC power architectures in multi-tenant fulfillment centers. The Ministry of Industry and Trade enforces electrical safety standards that influence equipment certification timelines. The Hanoi-Hai Phong corridor anchors dense demand clusters where port infrastructure and electronics manufacturing converge.
Indonesia
Jababeka and Cikarang industrial zones require mandatory SNI certification testing that extends equipment deployment schedules by 4-6 months. The Ministry of Industry regulates commercial electrical infrastructure standards for warehouse complexes. West Java logistics parks face compressed integration timelines as e-commerce operators accelerate network coverage.
Singapore
The Building and Construction Authority mandates Green Mark certification that accelerates 380V DC distribution specification over conventional AC-DC conversion. Pasir Panjang and Tuas developments face strict energy efficiency compliance timelines for data-intensive logistics facilities. Urban density creates concentrated demand for combined warehouse and electric fleet charging infrastructure.
Philippines
Underpenetrated refrigerated logistics infrastructure in Luzon and Visayas regions creates positioning opportunities for DC-powered automated storage systems. The Department of Energy oversees grid interconnection standards for large-scale commercial facilities. Manila and Cebu industrial zones attract first-mover investments targeting pharmaceutical and fresh product cold-chain gaps.
South-East Asia DC Distribution Network Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the South-East Asia DC distribution network market. The vendor base spans three tiers: integrated electrical majors with regional manufacturing footprints, power quality specialists with UPS and rectifier expertise, and emerging local integrators serving national certification requirements. Strategic moves concentrate on equipment-as-a-service model expansion and silicon carbide technology partnerships that transfer efficiency gains to operator balance sheets.
Within the integrated electrical tier, ABB Ltd and Siemens AG occupy positions exemplifying global technology anchoring against regional demands. Schneider Electric SE represents the diversified infrastructure archetype with manufacturing proximity advantages. Eaton Corporation Plc and Vertiv Group Corp sit within the power quality specialist segment where uninterruptible supply and thermal management capabilities differentiate positioning. Alpha Technologies SE, EPE Malaysia, and SGA SA anchor local and regional integration capacity that navigates country-specific certification friction.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Eaton Corporation Plc |
| Schneider Electric SE |
| Vertiv Group Corp |
| Alpha Technologies SE |
| SGA SA |
| EPE Malaysia |
| Secheron SA |
| Others |
Value Network & Pricing Analysis
Silicon carbide power semiconductor adoption is simultaneously compressing conversion-stage costs and concentrating procurement leverage among Thai and Vietnamese logistics operators with greenfield deployment timelines. This technology transition rewards operators who can aggregate volume commitments across multi-tenant facilities, while fragmenting pricing power for legacy silicon IGBT suppliers serving brownfield retrofit markets.
Pricing Analysis
The bundled-vs-unbundled service split separates asset-owning integrators from equipment-as-a-service providers across Southeast Asian logistics parks. Three-tier pricing structure across premium SiC-based systems, standard silicon IGBT configurations, and economy-grade 48V modular units tracks certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because Vietnamese e-commerce platforms are consolidating procurement under single infrastructure contractors. SMEs in Malaysian industrial zones exhibit highest price sensitivity, while Singapore cold-chain operators with pharmaceutical storage requirements show least.
Supply Chain Analysis
Certification gating through Indonesia's SNI standards, Thailand's BOI incentive alignment, and Singapore's BCA Green Mark creates 4-6 month deployment friction that shapes inventory positioning. Manufacturing concentrates in China, Taiwan, and Japan for power MOSFET and IGBT modules. Raw material dependencies span copper busbar conductors, rare earth permanent magnets, and nickel for battery storage systems. Single-source semiconductor vulnerability from Taiwanese and Japanese foundries exposes Thai integrators to allocation risk. Distribution runs through direct manufacturer engagement for large-scale Bangkok and Eastern Economic Corridor deployments, with regional electrical distributors serving Malaysian replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Thailand's tax holiday deadlines compress procurement cycles relative to Indonesia's extended certification timelines, rewarding operators who can shift deployment sequencing across ASEAN borders.
For Market Incumbents: To counter equipment-as-a-service model displacement from Vietnamese e-commerce platforms, ABB and Siemens should anchor captive SiC semiconductor supply through foundry partnerships while expanding application engineering headcount in Bangkok to meet BOI permit-aligned delivery schedules. Certification investment in Indonesia's SNI testing infrastructure represents a secondary defensive lever against local integrator encroachment. For New Entrants and Emerging Players: Digital-channel routes through regional B2B platforms offer lowest-friction entry for standardized 48V-240V rectifier systems targeting Indonesian SMEs in Cikarang zones. Philippine cold-chain gaps in Luzon and Visayas present the most penetrable white-space for DC-powered automated storage and retrieval systems. A technical-partnership go-to-market angle with established 3PL operators transfers asset risk while accelerating reference site accumulation. For Investors and Strategic Acquirers: Valuations sit cheapest among local integrators with Indonesia SNI certification capabilities and established relationships with Jababeka industrial zone developers. Long-term viability over a 5-10 year window rests on ASEAN electrical standards harmonization progress and cross-border logistics network integration depth. The signal to watch is Vietnamese Ministry of Industry and Trade enforcement timeline for unified electrical safety standards across northern industrial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Partnership | Foundry alliances with Taiwanese semiconductor manufacturers lock in 98.5% efficiency rectifier supply for Thai greenfield deployments. |
| Equipment-as-a-Service Model Expansion | Asset-risk retention structures align with Vietnamese e-commerce platform capital constraints in Hanoi-Hai Phong corridor. |
| Certification Infrastructure Investment | In-house SNI testing capabilities compress 4-6 month Indonesian deployment friction versus third-party laboratory dependency. |
| Application Engineering Localization | Bangkok-based technical teams accelerate BOI permit-aligned delivery schedules for Eastern Economic Corridor logistics parks. |
| Cross-Border Standards Harmonization Lobbying | ASEAN electrical standards alignment reduces multi-country deployment complexity for regional 3PL network operators. |
Research Methodology
Coverage spans Thailand, Vietnam, Indonesia, Singapore, Malaysia, and the Philippines, with primary inputs from each market's logistics park developers, DC system integrators, electrical contractors, and e-commerce platform infrastructure heads. Secondary validation draws from ASEAN electrical standards documentation, national regulator filings with Thailand's BOI and Singapore's BCA, customs trade data for power semiconductor imports, and industrial zone development permits. Bottom-up installation tracking across 40+ logistics facilities triangulates against top-down market sizing from equipment manufacturer revenue disclosures.
Granularity-level modeling segments by distribution channel, technology deployment intensity, service type bundling, and end-user scale archetype across the analysis window. The analytical framework derives CAGRs from facility commissioning timelines, e-commerce cold-chain expansion trajectories, and silicon carbide adoption curves in new greenfield developments. Industry-specific forecast inputs include BOI incentive expiration schedules and BCA Green Mark certification compliance deadlines.
Copper and rare earth price volatility, Indonesian SNI certification timeline extensions, and Taiwanese foundry allocation constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding ASEAN electrical standards harmonization progress and regional supply chain integration depth. A model refresh is warranted upon material change in Thailand's smart logistics park incentive framework or Vietnam's northern industrial corridor infrastructure investment pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Oil Pipeline Infrastructure Market