
 United States High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
United States High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States High-Voltage Direct Current (HVDC) Transmission Systems Market Analytics
Cross-linked polyethylene is repositioning oil-filled paper as the dominant submarine cable insulation for HVDC projects, cutting installation weight and extending route feasibility. Siemens Energy leverages its converter platform scale to anchor large-scale offshore wind tie-ins along the Eastern Seaboard. GE Vernova competes through integrated turbine-to-grid offerings that bundle HVDC terminals with renewable generation packages. Hitachi Energy specializes in voltage source converter topology, differentiating on dynamic grid support capabilities for weak AC networks.
High-voltage direct current transmission systems convert alternating current to direct current for bulk power transfer across distances exceeding conventional AC economic limits, typically operating at ±320 kV to ±800 kV with power ratings from several hundred megawatts to gigawatt scale. Line commutated converter technology retains cost advantages for point-to-point bulk links, while voltage source converter installations are expanding fastest due to black-start capability and compact footprint advantages in congested corridors. Underground installation types command premium pricing in urban substation approaches, though overhead segments sustain volume leadership across rural interstate spans.
FERC interconnection reforms and NERC reliability standards shape converter station commissioning timelines, with compliance costs filtering into procurement budgets for utilities and independent developers. The EPA's power plant emissions rules indirectly accelerate HVDC deployment by forcing remote renewable siting distant from load centers. Stakeholders must monitor state-level renewable portfolio standard escalation and offshore wind lease round schedules to align converter manufacturing capacity with project pipeline density.
Market Dynamics
Offshore wind lease rounds along the Atlantic seaboard are compressing converter station procurement timelines, forcing developers to pre-position manufacturing capacity before interconnection agreements finalize.
Growth Catalysts
- State renewable portfolio standards:California and Texas mandates require gigawatt-scale remote renewable integration, necessitating long-distance bulk power corridors that only HVDC economics can justify.
- FERC Order 2023:The interconnection queue reform accelerates converter station approvals by standardizing impact studies and shifting cost allocation frameworks.
- Cross-linked polyethylene insulation:This material is displacing oil-filled paper in submarine cables, reducing installation weight and extending feasible route lengths for subsea projects.
Market Restraints
- Converter valve supply concentration:Semiconductor-grade thyristor and IGBT sourcing concentrates among Asian foundries, exposing projects to geopolitical supply disruptions.
- Copper and rare earth price volatility:Cable conductor and permanent magnet costs fluctuate with commodity markets, eroding project IRR predictability during development.
- Line commutated converter technical limitations:LCC topology requires strong AC grid support, excluding weak-grid remote renewable sites without synchronous condenser additions.
Strategic Opportunities
- Great Lakes offshore wind:Untapped freshwater sites in Michigan and Wisconsin waters lack transmission infrastructure, creating first-mover advantages for HVDC system integrators.
- Inflation Reduction Act manufacturing credits:Domestic content bonuses for converter station assembly incentivize reshoring of voltage source converter module production.
- Multi-terminal HVDC mesh networks:Convergence of modular converter platforms with advanced DC circuit breakers enables meshed offshore grids connecting multiple lease areas.
Industry Challenges
- Specialized commissioning engineer scarcity:Voltage source converter control system tuning requires expertise combining power electronics and grid dynamics that utilities struggle to staff.
- NERC CIP cybersecurity certification:Converter station digital asset compliance timelines extend project schedules by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States High-Voltage Direct Current (HVDC) Transmission Systems Market |
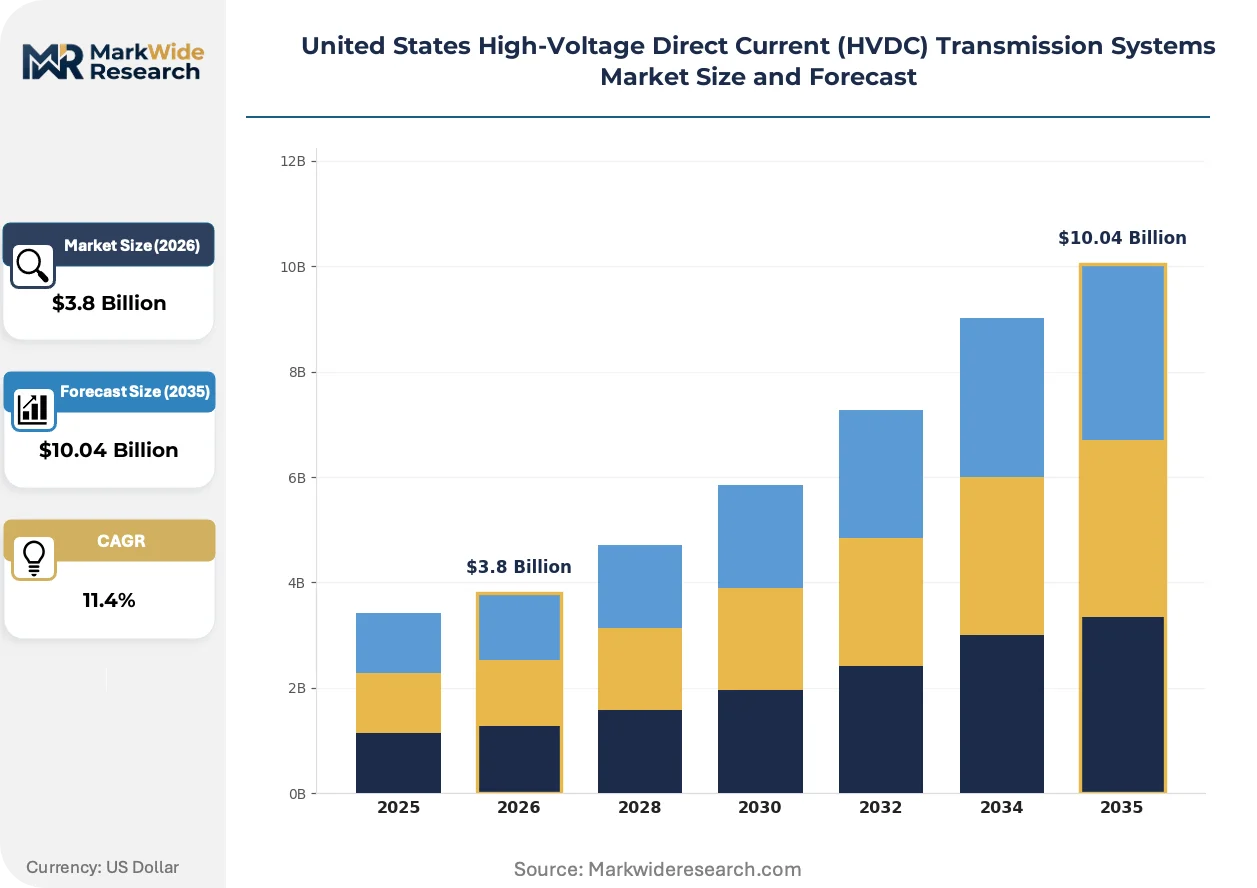
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Line Commutated Converter, Voltage Source Converter, Hybrid Systems, Others Application: Interconnection, Renewable Integration, Grid Stability, Power Export Installation Type: Onshore, Offshore, Underground, Overhead End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Siemens Energy, GE Vernova, Hitachi Energy, Toshiba Corporation, NKT A/S, LS Electric, Mitsubishi Electric, Prysmian Group, Nexans, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States High-Voltage Direct Current (HVDC) Transmission Systems Market Evolving Landscape
Voltage source converter technology is compressing project footprints and enabling weaker grid connections, while procurement models evolve toward integrated turbine-to-grid packages. These shifts are reconfiguring supplier relationships and technical risk allocation across the value chain.
Modular multilevel converter (MMC) architecture is modularizing converter station design, replacing centralized valve halls with standardized submodules that ship pre-tested. Offshore wind developers in Massachusetts and New Jersey waters are specifying MMC platforms for their compact offshore platform compatibility. This topology is modularizing project execution, allowing parallel manufacturing streams that compress delivery schedules by eight to fourteen months versus conventional LCC builds.
The EPA's power plant emissions rules are indirectly accelerating HVDC deployment by forcing coal retirements and mandating replacement generation from remote wind and solar zones distant from coastal load centers. Utilities in the PJM and ERCOT footprints are responding by advancing converter station pre-development to maintain resource adequacy timelines. The regulation most affects voltage source converter procurements, where black-start capability addresses grid stability concerns from synchronous generator retirements.
Integrated procurement bundling HVDC terminals with offshore wind turbine supply agreements is displacing discrete converter station tenders among Atlantic Coast developers. Engineering-procurement-construction contractors are consolidating vendor management under single-point accountability structures. This pattern is most visible in New York Bight lease areas, where developers prioritize schedule certainty over component-level cost optimization.
United States High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
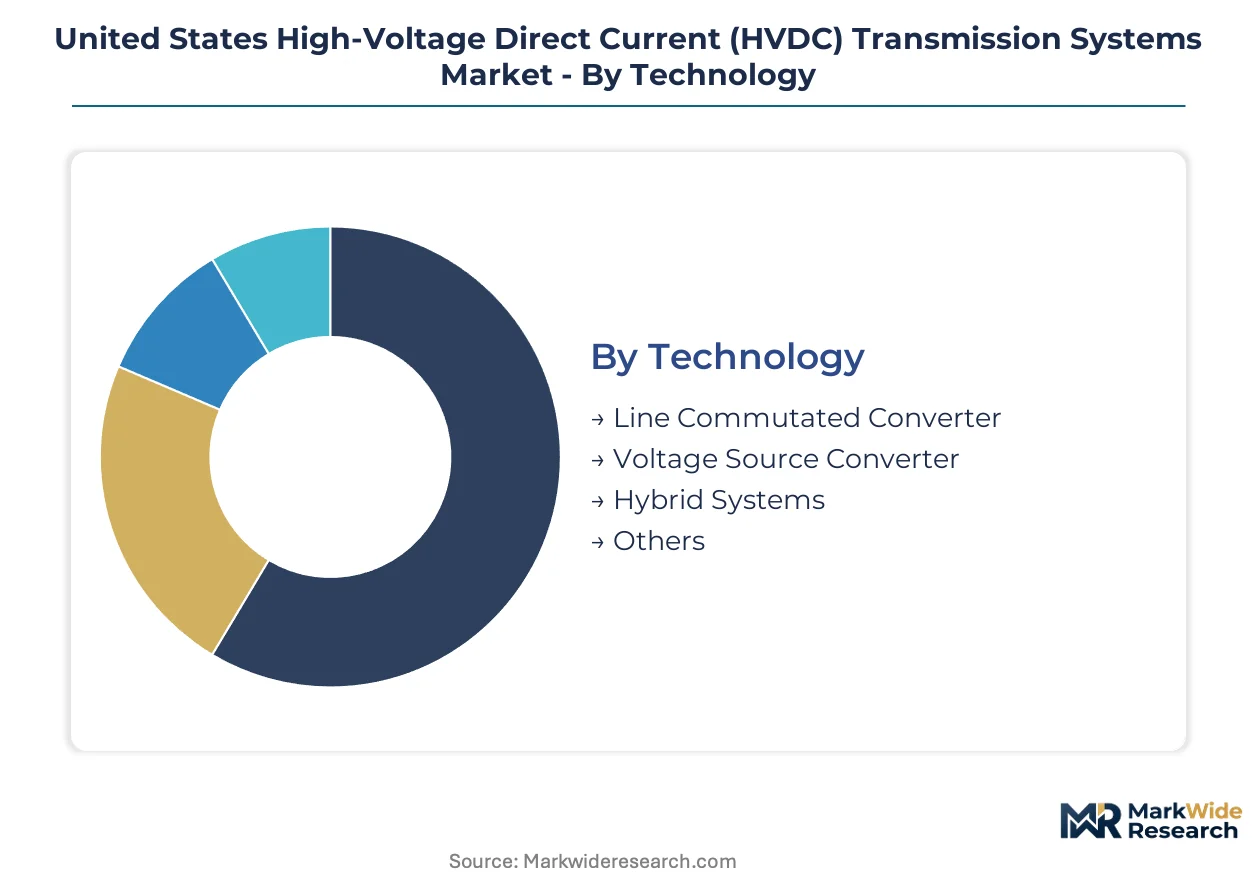
HVDC system architecture varies sharply across technical specifications, deployment contexts, and customer procurement patterns. Segmentation reveals where converter technology investments concentrate and which installation constraints dominate project economics.
Technology:
Converter topology determines grid interaction capabilities, footprint requirements, and semiconductor sourcing strategies.
- Line Commutated Converter:Thyristor-based switching enables gigawatt-scale bulk power transfer with minimal conversion losses. Texas utilities deploy LCC stations for point-to-point renewable corridors from West Texas wind zones to Gulf Coast demand centers.
- Voltage Source Converter:IGBT switching with black-start capability supports weak-grid connections and compact offshore platform installations. Atlantic Coast offshore wind developers specify VSC platforms for their dynamic reactive power support.
- Hybrid Systems:Combines LCC efficiency at bulk scale with VSC flexibility for grid support functions.
- Others:Emerging topologies including current source converters and alternate multilevel architectures.
Mature deployment sits with Line Commutated Converter. Newer deployment is concentrated in Voltage Source Converter.
Application:
End-use purpose shapes converter station sizing, control system complexity, and interconnection queue positioning.
- Interconnection:Links asynchronous AC grids or connects regional transmission organizations across seams. PJM-ERCOT intertie proposals and seam-strengthening projects in the Mountain West drive procurement volumes.
- Renewable Integration:Collects remote wind and solar generation for delivery to coastal load centers. California ISO interconnection requests for desert solar zones dominate this segment's project pipeline.
- Grid Stability:Provides frequency regulation and voltage support through synthetic inertia emulation.
- Power Export:Enables electricity sales across state or national boundaries through dedicated transmission corridors.
Renewable Integration commands the steepest expansion trajectory as state mandates force remote resource siting. Grid Stability applications are gaining share fastest following synchronous generator retirements.
Installation Type:
Physical deployment method determines cable specification, permitting complexity, and capital cost structure.
- Onshore:Converter stations and terrestrial cable routes across private and federal lands. Permitting through Bureau of Land Management and state environmental review processes shapes Texas and California project timelines.
- Offshore:Subsea cable systems connecting offshore wind arrays to onshore substations. Massachusetts and New Jersey lease areas specify cross-linked polyethylene insulated cables for reduced platform loading.
- Underground:Urban and environmentally sensitive corridor installations commanding premium trenching and thermal management costs.
- Overhead:Rural interstate spans utilizing lattice tower structures with conventional conductor configurations.
Overhead installations sustain volume leadership across rural transmission corridors. Underground and Offshore segments are climbing the fastest as urban congestion and offshore wind deployment accelerate.
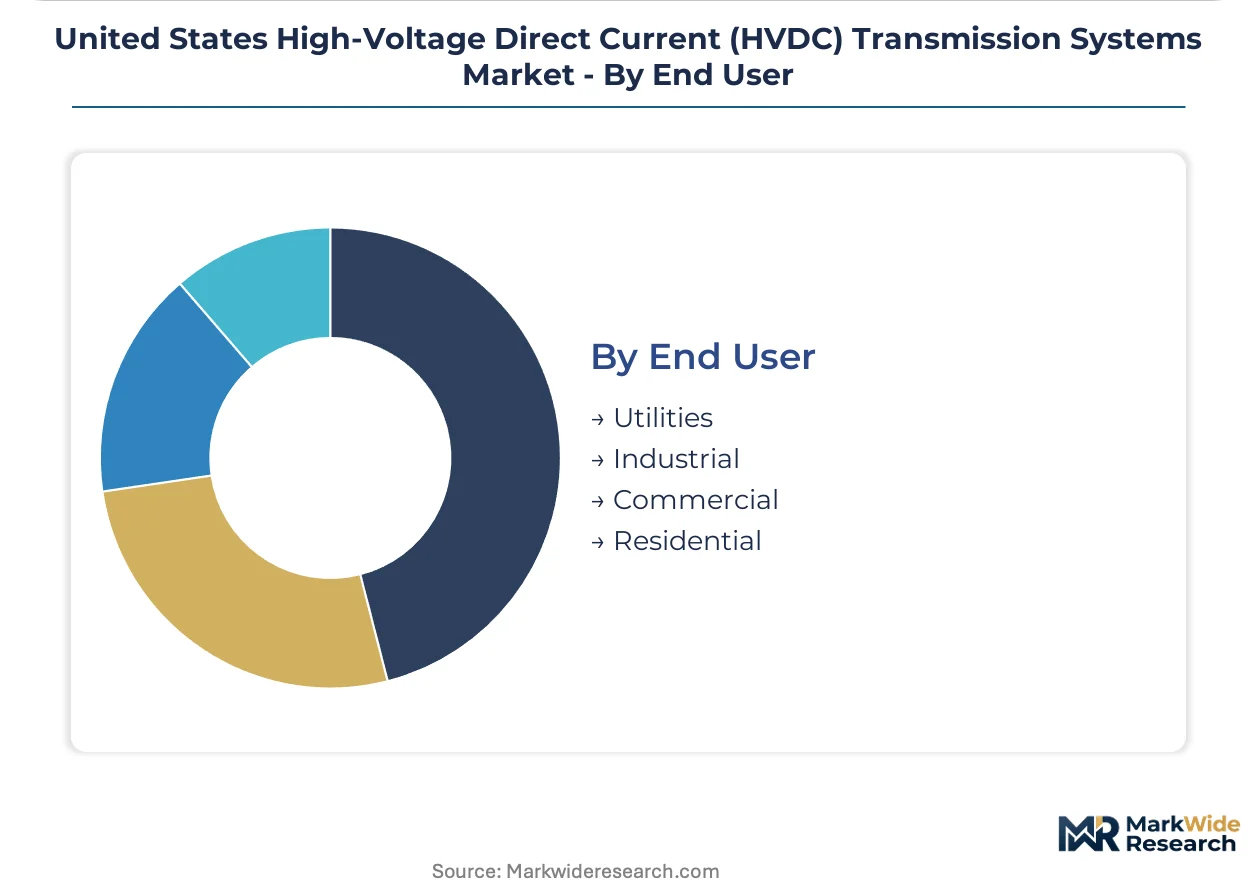
End User:
Customer type determines procurement scale, financing structures, and technical specification authority.
- Utilities:Investor-owned and public power entities with FERC-jurisdictional transmission ownership. Southern California Edison and ERCOT utilities dominate converter station procurement through integrated resource plan mandates.
- Industrial:Large-load customers seeking dedicated transmission for data centers, hydrogen production, or mining operations.
- Commercial:C&I aggregators and corporate renewable energy buyers contracting for delivered clean power.
- Residential:Community choice aggregators and municipal utilities serving distributed load pockets.
Utilities anchor procurement volume through rate-base financing and FERC Order 1000 compliance obligations. Industrial end users are expanding most quickly as data center load growth in Virginia and Texas outstocks local generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Texas and California concentrate HVDC converter station development through tax-advantaged capital deployment. State renewable mandates and FERC interconnection reforms accelerate project timelines across both coastal and inland corridors.
Texas
West Texas wind zones and Permian Basin solar arrays drive demand for gigawatt-scale bulk power corridors to Gulf Coast demand centers. ERCOT interconnection queue reforms compress converter station approvals by standardizing impact studies. Houston and Dallas-Fort Worth anchor manufacturing and engineering clusters for LCC platform assembly.
California
Desert solar zones in Imperial and Riverside counties require long-distance transmission to coastal load centers under CPUC resource adequacy mandates. Inflation Reduction Act manufacturing credits incentivize domestic converter module production. Los Angeles Basin and San Francisco Bay Area concentrate engineering procurement for VSC offshore platform integration.
New York
New York Bight offshore wind lease rounds compress procurement timelines for subsea cable and converter platform packages. State Climate Leadership and Community Protection Act mandates 70% renewable electricity by 2030. Long Island and Hudson Valley host pre-development engineering for multi-terminal HVDC mesh configurations.
Massachusetts
Vineyard Wind and Mayflower Wind developments specify cross-linked polyethylene insulated cables for reduced offshore platform loading. Massachusetts Department of Energy Resources offshore wind solicitations mandate HVDC interconnection for lease areas beyond 50 nautical miles. Greater Boston anchors control system engineering and specialized commissioning expertise.
New Jersey
Atlantic Shores and Ocean Wind projects drive procurement of compact VSC platforms for shallow-water converter stations. New Jersey Board of Public Utilities offshore wind mandates require 11,000 MW installed capacity by 2040. Port of Paulsboro and Camden cluster cable manufacturing and heavy-lift assembly for subsea installation campaigns.
United States High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated turbine-to-grid bundling displacing discrete converter tenders among Atlantic Coast developers. Siemens Energy, GE Vernova, and Hitachi Energy anchor the top tier through converter platform scale and voltage source converter specialization. Strategic consolidation concentrates semiconductor-grade thyristor and IGBT sourcing control, while engineering-procurement-construction contractors consolidate vendor management under single-point accountability structures.
Within the integrated solutions tier, Siemens Energy leverages its converter platform scale to anchor large-scale offshore wind tie-ins, while GE Vernova competes through bundled HVDC terminals with renewable generation packages. Hitachi Energy occupies a position specializing in voltage source converter topology for dynamic grid support capabilities. These three exemplify the shift toward schedule-certain procurement models where developers prioritize delivery reliability over component-level cost optimization.
| Leading Market Players |
|---|
| Siemens Energy |
| GE Vernova |
| Hitachi Energy |
| Toshiba Corporation |
| NKT A/S |
| LS Electric |
| Mitsubishi Electric |
| Prysmian Group |
| Nexans |
| Others |
Value Network & Pricing Analysis
Offshore wind developers specifying cross-linked polyethylene insulation for subsea cables are forcing cable manufacturers to retool extrusion capacity and absorb qualification costs, compressing margins on standard oil-filled paper alternatives while commanding premiums for certified submarine-grade material.
Pricing Analysis
Short-lead-time premiums for voltage source converter modules now reach substantial multiples over standard-schedule procurement, as Atlantic Coast lease round deadlines compress manufacturing windows. Three-tier pricing structure across premium certified, standard qualified, and economy grade tiers reflects NERC CIP cybersecurity certification status and factory acceptance testing rigor. Pricing pressure stems from semiconductor-grade thyristor and IGBT sourcing concentration among Asian foundries, exposing projects to geopolitical supply disruptions. Independent developers show highest price sensitivity due to non-recourse financing constraints, while integrated utilities with rate-base recovery exhibit lowest sensitivity.
Supply Chain Analysis
NERC CIP cybersecurity qualification and subsea cable pressure-testing certification gate entry for converter station component suppliers, filtering the vendor base to firms with sustained capital investment in testing infrastructure. Semiconductor-grade thyristor and IGBT production concentrates in Japan, Germany, and China, while cross-linked polyethylene compound manufacturing anchors in South Korea and the United States. Copper conductor and rare earth permanent magnet inputs draw from Chilean mining operations and Chinese processing facilities. Single-source vulnerability in IGBT wafer fabrication represents the dominant structural risk. Distribution runs through engineering-procurement-construction contractors consolidating vendor management under single-point accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States HVDC market sits in a technology-transition phase as voltage source converter topology with black-start capability displaces legacy line commutated converter installations for offshore wind integration.
For Market Incumbents: Deploy modular multilevel converter platform standardization to defend against integrated turbine-to-grid bundling by GE Vernova and Siemens Energy. Accelerate domestic voltage source converter module assembly capacity in Texas and California to capture Inflation Reduction Act manufacturing credits. Threat substitution comes from emerging Asian entrants with state-backed semiconductor fabrication. For New Entrants and Emerging Players: Voltage source converter control system software specialization offers entry wedge against hardware-dominant incumbents. Target Great Lakes offshore wind pre-development in Michigan and Wisconsin waters, where transmission infrastructure gaps create first-mover advantages. Go-to-market through engineering-procurement-construction contractor partnerships rather than direct utility sales. For Investors and Strategic Acquirers: Re-rating potential sits with specialized commissioning engineering firms given NERC CIP cybersecurity certification bottlenecks extending project timelines. Long-term viability favors asset-light control system and software providers over capital-intensive converter manufacturing. Signal to watch is FERC Order 2023 implementation pace accelerating interconnection queue clearance rates.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Multilevel Converter Platform Deployment | Compresses delivery schedules by enabling parallel manufacturing streams for Atlantic Coast offshore wind projects. |
| Domestic Voltage Source Converter Module Assembly | Captures Inflation Reduction Act manufacturing credits while reducing exposure to Asian semiconductor foundry concentration. |
| Integrated Turbine-to-Grid Procurement Bundling | Consolidates vendor accountability for developers prioritizing schedule certainty over component-level cost optimization. |
| Multi-Terminal HVDC Mesh Network Development | Enables interconnection of multiple New York Bight lease areas through advanced DC circuit breaker integration. |
| Specialized Commissioning Engineer Capability Buildout | Addresses scarcity of expertise combining power electronics and grid dynamics for voltage source converter tuning. |
Research Methodology
Multi-period observation of FERC interconnection queue filings, NERC reliability standard compliance timelines, and offshore wind lease round schedules anchored the trend analysis, supplemented by interviews with utility transmission planning officers, independent power producer project developers, engineering-procurement-construction contractors, and converter station control system engineers. Secondary validation drew from EIA electricity transmission data, FERC docket filings, Bureau of Ocean Energy Management lease round records, and state renewable portfolio standard regulatory texts. Bottom-up project pipeline aggregation triangulated against top-down market sizing from equipment procurement disclosures.
Input-output matrix modeling connected converter station manufacturing capacity, semiconductor wafer supply, and cable insulation material production to deployment across technology segments, application types, installation categories, and end-user archetypes throughout the forecast period. CAGRs derived from segment-level deployment trajectories weighted by interconnection queue depth and state mandate enforcement timelines. Forecast inputs incorporated FERC Order 2023 implementation pace and Inflation Reduction Act domestic content bonus utilization rates.
Several conditions sit outside the modeled scope, including specific project financing close dates, unannounced offshore wind lease round schedules, and potential NERC cybersecurity standard revisions. Forecasts reflect assumptions about regulatory implementation continuity and commodity price stability. A model refresh is warranted upon material change in FERC interconnection reform enforcement or semiconductor trade policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market