
 Bulk Terminals Market | 2026-2036
Bulk Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Terminals Market Analysis
Project finance through long-term throughput agreements is tilting competitive access toward operators with sovereign-backed credit profiles. COSCO Shipping Ports leverages its state-linked balance sheet to secure concession-backed debt for greenfield deepwater terminals. DP World Ltd. anchors its competitiveness through asset-light joint ventures that limit capital-at-risk in volatile commodity corridors. Hutchison Ports differentiates by controlling integrated inland logistics networks that extend terminal catchment areas beyond traditional port hinterlands.
Bulk terminals are specialized maritime facilities engineered for high-volume transfer of unpackaged commodities, typically featuring draft depths exceeding 15 meters, conveyor systems rated above 5,000 tonnes per hour, and covered storage domes exceeding 100,000 tonnes capacity to mitigate moisture degradation. Their primary purpose is to minimize vessel turnaround time while maintaining cargo quality integrity across grain, coal, mineral, and liquid commodity streams. Liquid terminals command premium margins due to specialized fire suppression and vapor recovery infrastructure requirements, while grain terminals face margin compression from fumigation compliance and pest control protocols. Extra-large facilities dominate throughput volumes but medium-sized terminals in emerging mining regions represent the fastest capacity expansion pipeline.
IMO 2020 sulfur cap enforcement through port state control inspections shapes fuel switching demand at liquid bulk terminals, while national environmental regulators in China and the EU mandate shore power connectivity and dust suppression systems for coal and mineral handling. ISO 28000 security management certification increasingly gates insurance pricing and customer qualification for terminal operators. Stakeholders must monitor how carbon border adjustment mechanisms redirect commodity flow patterns before committing to multi-decade concession investments.
Market Dynamics
Terminal electrification mandates under the EU Green Deal are forcing capital reallocation across European facilities while Asian power utilities drive coal and LNG throughput expansion through dedicated import infrastructure.
Growth Catalysts
- IMO 2020 Sulfur Cap:Enforcement through port state control inspections accelerates fuel switching demand at liquid bulk terminals, requiring upgraded storage and blending infrastructure.
- China State Port Consolidation:Centralized ownership structures in coastal provinces streamline concession approvals and unlock economies of scale for deepwater coal and ore handling.
- Dual Carbon Goals:China's MEE mandates for shore power connectivity and dust suppression systems trigger retrofit investment cycles across mineral and coal terminals.
Market Restraints
- Steel Price Volatility:Conveyor systems, storage domes, and quay wall construction face input cost swings that compress project returns during procurement phases.
- Specialized Labor Scarcity:Marine civil engineers and bulk materials handling specialists concentrate in legacy port cities, constraining greenfield development timelines in emerging mining regions.
- Substation Grid Capacity:Terminal electrification retrofits compete with urban demand for utility connections, delaying commissioning in constrained coastal zones.
Strategic Opportunities
- Carbon Border Adjustment Mechanisms:EU CBAM implementation redirects commodity flow patterns, creating throughput arbitrage potential for terminals with verified low-carbon handling protocols.
- Integrated Logistics Control:Operators capturing inland rail and barge networks extend catchment areas beyond traditional port hinterlands, locking in captive volume flows.
- ISO 28000 Certification Gates:Security management certification increasingly determines insurance pricing and customer qualification, favoring early adopters in risk-sensitive commodity corridors.
Industry Challenges
- Legacy System Integration:Retrofitting vapor recovery and fire suppression infrastructure into aged liquid terminals requires phased shutdowns that disrupt throughput commitments.
- Fumigation Compliance Timelines:Grain terminals face extended vessel quarantine periods and pest control protocol complexity that compress effective berth utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Terminals Market |
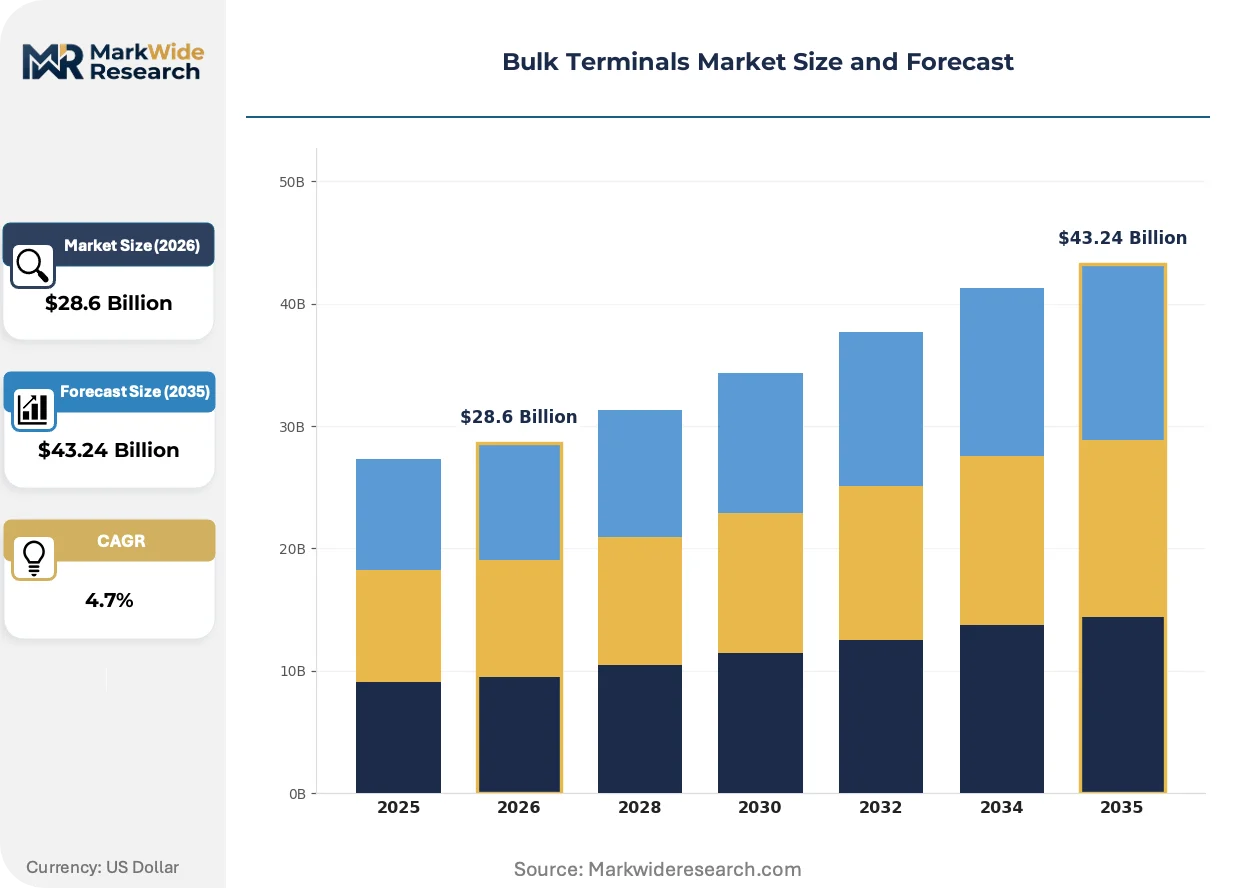
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Grain, Coal, Mineral, Liquid Facility Size: Small, Medium, Large, Extra Large Loading Method: Bulk Loader, Conveyor, Hopper, Ship Loader End User: Agriculture, Mining, Energy, Manufacturing |
| Companies Covered | PSA International, COSCO Shipping Ports, DP World Ltd., HES International B.V., Euroports Holdings, APM Terminals, Hutchison Ports, Global Ports Investments PLC, China Merchants Port Holdings Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Terminals Market Emerging Trajectories
Automation and environmental compliance technologies are restructuring capital deployment patterns across terminal development, with digital twin systems and electrified material handling emerging as decisive competitive differentiators.
Autonomous stacking and reclaiming systems are collapsing labor cost structures at high-throughput coal and iron ore terminals. Australian and Brazilian mining majors deploy these systems at greenfield sites, eliminating operator cabins and reducing staffing ratios by over half. The technology is collapsing traditional OPEX advantages that manual operations held in lower-wage jurisdictions.
The EU Green Deal's terminal electrification mandates force simultaneous shore power installation and conveyor system upgrades. Operators must coordinate grid connection timelines with vessel retrofit cycles, creating interdependency risks. Liquid bulk terminals in Rotterdam and Hamburg face the steepest compliance curves due to aged infrastructure and constrained substation capacity.
Power generation utilities now specify terminal performance through availability-based contracts rather than throughput guarantees. This transfers operational risk to terminal operators while rewarding reliability metrics. The shift is most visible in Asia-Pacific LNG import terminals, where buyers prioritize send-out consistency over nominal capacity.
Bulk Terminals Market Segmentation
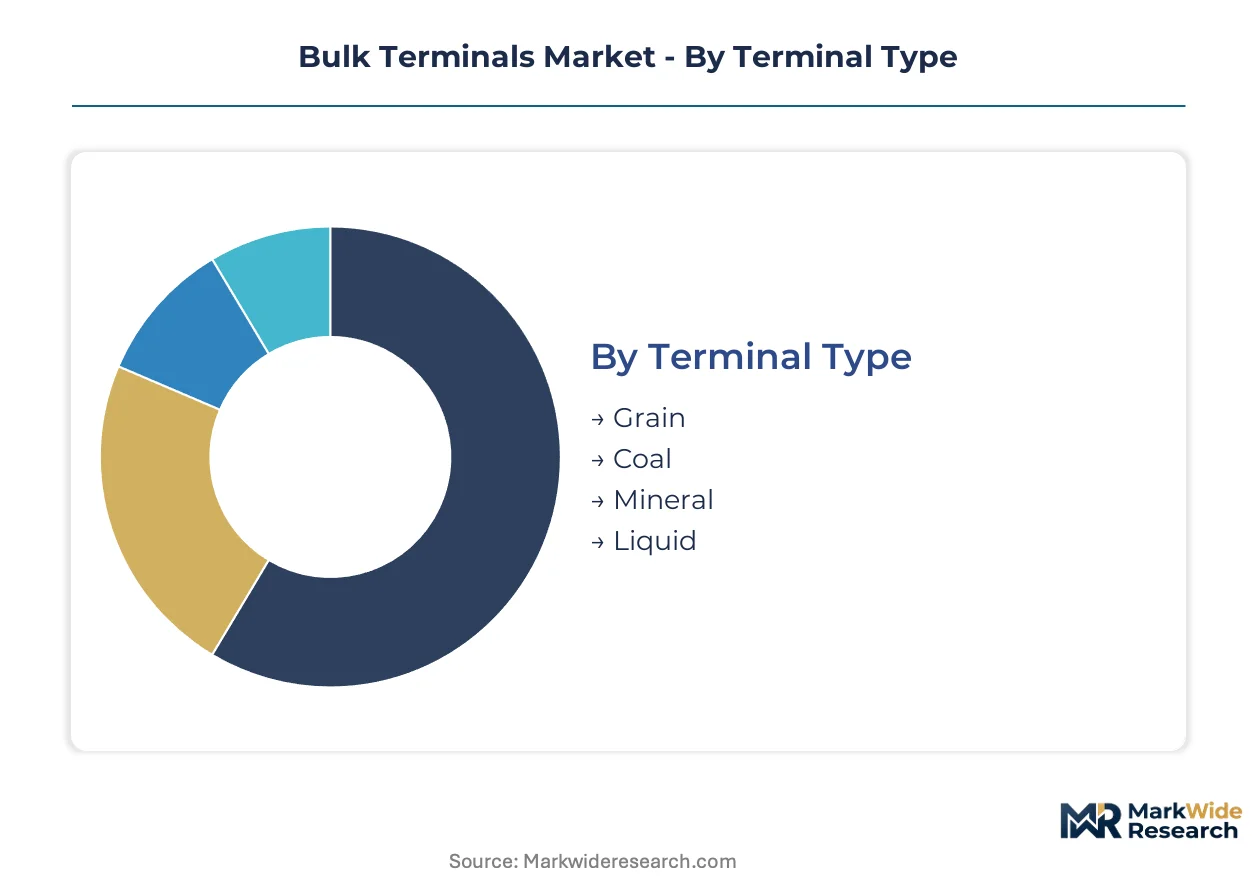
Terminal operators configure asset portfolios across four intersecting dimensions. Each segmentation axis carries distinct capital intensity profiles and regulatory exposure, shaping concession bidding strategies and equipment procurement cycles.
Terminal Type:
Mature infrastructure categories dominate installed capacity while emerging segments attract electrification-focused greenfield investment.
- Liquid:Specialized tankage with vapor recovery systems and fire suppression infrastructure handles petroleum products, chemicals, and LNG. Rotterdam and Houston facilities command premium margins due to IMO 2020 blending demand and cryogenic handling requirements.
- Coal:Deepwater berths with dust suppression and shore power connectivity serve power generation utilities. Coastal China terminals expand fastest under state port consolidation, though EU Green Deal electrification mandates constrain European asset utilization.
- Mineral:High-capacity conveyors and covered storage domes manage iron ore and bauxite flows. Australian and Brazilian mining majors specify autonomous stacking systems at greenfield sites.
- Grain:Silo complexes with fumigation protocols and pest control systems face margin compression from extended vessel quarantine periods. Black Sea and Mississippi River terminals handle seasonal harvest surges.
Liquid terminals handle the majority of throughput; coal terminals are the fastest mover on share.
Facility Size:
Cost tier stratification separates mega-scale deepwater investments from flexible medium-scale deployments in emerging mining regions.
- Extra Large:Draft depths exceeding 20 meters accommodate Capesize and VLOC vessels at single-berth facilities. These assets concentrate in established ore export corridors where mining majors anchor long-term throughput agreements.
- Large:Multi-berth configurations with 15-20 meter draft serve Panamax and Post-Panamax fleets. Operators balance utilization across diversified commodity streams to mitigate single-cargo volatility.
- Medium:Scalable designs with modular conveyor expansion capability target greenfield mining developments in West Africa and Southeast Asia. These facilities represent the steepest capacity expansion pipeline.
- Small:Shallow-draft installations with barge-fed logistics serve niche agricultural and coastal manufacturing supply chains. Limited economies of scale restrict competitive positioning to captive hinterland volumes.
Extra-large facilities anchor volume concentration; medium terminals are expanding most quickly.
Loading Method:
Application-specific equipment selection determines vessel turnaround efficiency and labor cost structures across commodity handling operations.
- Ship Loader:Rail-mounted gantries with telescopic chutes achieve 10,000+ tonnes per hour loading rates for iron ore and coal exports. Australian terminals deploy these systems for Capesize vessel optimization.
- Conveyor:Continuous belt systems with tripper car distribution feed storage domes and direct vessel loading. Integrated conveyor networks dominate grain and mineral terminals where dust containment is critical.
- Bulk Loader:Mobile units with weighbridge integration serve multipurpose berths handling diverse cargo mixes. Port authorities in developing markets favor this flexibility for concession revenue diversification.
- Hopper:Fixed and mobile hopper configurations with grab crane feeding manage breakbulk and parcel cargo streams. These systems persist in legacy terminals where full automation retrofit is capital-prohibitive.
Ship loaders dominate high-volume export corridors; conveyor systems are gaining share fastest through integrated terminal automation.
End User:
Customer type concentration shapes contract structures, with availability-based terms displacing throughput guarantees in risk-sensitive segments.
- Energy:Power generation utilities and LNG importers specify send-out consistency metrics over nominal capacity. Asia-Pacific buyers drive dedicated import terminal development through sovereign-backed project finance.
- Mining:Iron ore and bauxite producers anchor long-term concession agreements with vertically integrated terminal operators. Brazilian and Australian majors deploy autonomous systems to collapse OPEX differentials.
- Agriculture:Grain traders and food processors face fumigation compliance complexity that compresses effective berth utilization. Black Sea terminals navigate seasonal volatility through multi-cargo flexibility.
- Manufacturing:Steel mills and chemical plants require just-in-time raw material delivery with quality integrity protocols. Coastal China facilities serve state-owned manufacturing conglomerates under centralized procurement.
Energy sector contracts anchor revenue stability; mining terminals are climbing the fastest on capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal terminal electrification mandates and China's state port consolidation program are redirecting capital toward coastal deepwater facilities with sovereign-backed financing access.
China
State-owned power utilities drive coal and LNG import terminal expansion through centralized procurement under the MEE's dual carbon goals. Coastal provinces accelerate concession approvals for deepwater berths serving manufacturing conglomerates. The Yangtze River Delta cluster concentrates autonomous stacking system deployments at iron ore handling facilities.
Australia
Mining majors specify availability-based contracts for iron ore export terminals rather than throughput guarantees. The Pilbara region anchors greenfield autonomous system installations that collapse labor cost structures. Brisbane-based engineering firms concentrate marine civil expertise for regional greenfield developments.
Germany
The EU Green Deal forces simultaneous shore power installation and conveyor electrification at Hamburg and Rotterdam corridor facilities. Grid substation capacity constraints delay commissioning timelines in constrained coastal zones. North Rhine-Westphalia steel mills demand just-in-time raw material delivery with quality integrity protocols.
Brazil
Vale and mining majors anchor long-term concession agreements with vertically integrated terminal operators in the iron ore export corridor. ANVISA-equivalent environmental regulators mandate dust suppression systems at Pará state mineral handling facilities. The Itaqui port complex in Maranhão expands capacity for bauxite and iron ore flows.
United States
Gulf Coast LNG export terminals command premium margins due to cryogenic handling requirements and FERC permitting timelines. Houston Ship Channel facilities upgraded storage and blending infrastructure for IMO 2020 fuel switching demand. Louisiana petrochemical clusters drive liquid bulk terminal utilization through captive manufacturing supply chains.
Bulk Terminals Market Vendor Landscape
Channel-controlling players compete with product-specialist players across concession-backed and asset-light operating models. The market structure consolidates around sovereign-linked operators with project finance access and independent port groups with geographic diversification. Three archetypes dominate: state-backed national champions, diversified global terminal operators, and specialized bulk handlers with commodity focus. Competitive moves concentrate on concession bidding for greenfield deepwater sites and electrification retrofit partnerships with power utilities.
Among state-backed operators, COSCO Shipping Ports and China Merchants Port Holdings Co. Ltd. exemplify the sovereign-credit archetype that secures long-term concession debt. DP World Ltd. and Hutchison Ports occupy positions within the diversified global operator tier, anchoring competitiveness through joint venture structures and integrated inland logistics networks. PSA International represents the specialized bulk handling archetype with deep automation expertise.
| Leading Market Players |
|---|
| PSA International |
| COSCO Shipping Ports |
| DP World Ltd. |
| HES International B.V. |
| Euroports Holdings |
| APM Terminals |
| Hutchison Ports |
| Global Ports Investments PLC |
| China Merchants Port Holdings Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cluster concentrates autonomous stacking system deployments, and its capacity expansion dynamics directly shape pricing power for terminal electrification retrofits across coastal China. State port consolidation accelerates concession approvals, compressing procurement timelines while sovereign-backed credit profiles tilt competitive access toward operators with balance sheet depth.
Pricing Analysis
Certification level (ISO 28000 security management) creates the primary spread between premium and standard terminal operators, with early adopters commanding favorable insurance pricing and customer qualification in risk-sensitive commodity corridors. Contract-based long-term throughput agreements dominate, with availability-based terms displacing throughput guarantees as power generation utilities prioritize send-out consistency. Pricing pressure stems from steel price volatility in conveyor systems and storage dome construction, compressing project returns during procurement phases. Mining majors and LNG importers exhibit lowest price sensitivity due to captive volume requirements, while grain traders face acute margin compression from fumigation compliance and extended vessel quarantine periods.
Supply Chain Analysis
Export-control restrictions on autonomous stacking and reclaiming systems limit technology flows to greenfield mining developments in West Africa and Southeast Asia, constraining capacity expansion timelines. Equipment manufacturing concentrates in Germany, Japan, and South Korea, with marine civil engineering expertise clustering in Australia and legacy European port cities. Raw material dependencies include high-grade steel for conveyor structures, specialized electrical components for shore power connectivity, and cryogenic handling equipment for LNG infrastructure. Single-source vulnerability in substation grid capacity creates commissioning delays in constrained coastal zones. Distribution runs through vertically integrated terminal operators with captive inland rail and barge networks that extend catchment areas beyond traditional port hinterlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's terminal electrification mandates and China's dual carbon goals constitute a dual regulatory inflection, forcing simultaneous capital reallocation across European retrofit cycles and Asian greenfield development. This structural disruption rewards operators with sovereign-backed financing access and integrated logistics control.
For Market Incumbents: Entrench competitive positioning through backward integration into inland rail and barge networks that lock in captive volume flows beyond traditional port hinterlands. Prioritize ISO 28000 certification investment to capture insurance pricing advantages as security management gates tighten customer qualification. Defend against asset-light joint venture structures by leveraging state-linked balance sheets for concession-backed debt at greenfield deepwater sites.
For New Entrants and Emerging Players: Establish a beachhead in medium-scale terminal deployments targeting greenfield mining developments in West Africa and Southeast Asia, where scalable designs with modular conveyor expansion capability represent the steepest capacity expansion pipeline. Target grain terminal segments facing acute margin compression from fumigation compliance complexity, where operational excellence in pest control protocols creates differentiation. Pursue availability-based contract structures with power generation utilities that transfer operational risk while rewarding reliability metrics.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because state port consolidation programs and carbon border adjustment mechanisms concentrate throughput flows toward terminals with verified low-carbon handling protocols and sovereign-credit access. Acquisition target archetype: specialized bulk handlers with deep automation expertise and established concession relationships in emerging mining corridors. Signal to watch: IMO enforcement intensity through port state control inspections and EU CBAM implementation timelines redirecting commodity flow patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Electrification Retrofit | EU Green Deal mandates force simultaneous shore power and conveyor upgrades at Hamburg and Rotterdam corridor facilities. |
| Autonomous System Deployment | Australian and Brazilian mining majors specify stacking systems that collapse labor cost structures by eliminating operator cabins. |
| Integrated Logistics Acquisition | Control of inland rail and barge networks extends terminal catchment areas beyond traditional port hinterlands. |
| ISO 28000 Certification Program | Security management certification gates insurance pricing and customer qualification in risk-sensitive commodity corridors. |
| Long-term Throughput Agreement | Project finance through availability-based contracts transfers operational risk while rewarding reliability metrics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with terminal operations directors, marine civil engineers, bulk materials handling specialists, and power utility procurement officers. Secondary validation drew from port authority concession databases, IMO regulatory filings, EU Green Deal implementation trackers, and customs trade data for bulk commodity flows. Bottom-up capacity assessments across terminal type, facility size, and loading method segments were triangulated against top-down macroeconomic indicators for commodity trade volumes.
Calibration anchored volume and value outputs across the analysis window through multi-dimensional segmentation modeling across terminal type (liquid, coal, mineral, grain), facility size tier, loading method, and end-user contract structure. CAGRs were derived from regression analysis of historical throughput data against projected commodity flow shifts under carbon border adjustment mechanisms and state port consolidation programs. Industry-specific inputs included vessel size deployment trends for Capesize and VLOC optimization, and grid connection timelines for electrification retrofit interdependencies.
Macroeconomic conditions sit as an overlay; deviation in commodity price volatility, steel input costs, or sovereign credit availability would shift the trajectory of greenfield development timelines. Forecasts reflect documented assumptions regarding IMO enforcement intensity, EU CBAM implementation scope, and China MEE mandate adherence. Material shifts in regulatory compliance timelines or mining major capital allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market