
 Germany High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market Foresight
Silicon carbide semiconductor modules are restructuring converter station economics by cutting switching losses and shrinking footprint requirements. Siemens Energy leverages in-house wafer sourcing to control module costs across North Sea projects. ABB Ltd anchors European supply chains through its Swiss-German manufacturing corridor for HVDC valves and transformers. Hitachi Energy competes on multilevel voltage-source converter architectures optimized for offshore collector platforms.
High-voltage direct current transmission systems transfer bulk electrical power over long distances or submarine cables using converter stations that rectify alternating current to direct current and invert it back, typically operating at ±320 kV to ±525 kV with power ratings exceeding 500 MW per bipole link. These systems primarily interconnect asynchronous grids, deliver remote renewable generation to load centers, and stabilize meshed networks against cascading failures. Voltage source converter technology leads new project awards due to superior reactive power control and black-start capability, while line-commutated systems retain share in ultra-high-capacity bulk corridors where mature thyristor stacks offer proven reliability. Offshore installation commands premium margins driven by submarine cable laying complexity and salt-resistant converter platform engineering, whereas onshore grid expansion segments compete on standardized converter hall delivery timelines.
Germany's Federal Network Agency (Bundesnetzagentur) enforces Ten-Year Network Development Plans that mandate specific HVDC corridor completions, while EU F-Gas Regulation phases down sulfur hexafluoride use in switchgear and compels gas-insulated system redesigns. CE marking under EU machinery and electromagnetic compatibility directives governs converter station market access, with German Institute for Standardization (DIN) norms layering national testing protocols atop harmonized standards. Stakeholders must monitor converter station standardization progress under the EU Clean Energy Package, as interoperability mandates reshape procurement specifications and vendor qualification criteria.
Market Dynamics
Silicon carbide semiconductor modules are compressing converter station footprints while elevating switching frequencies, forcing incumbent suppliers to retool manufacturing lines around wide-bandgap architectures or cede offshore wind procurement to specialized entrants.
Growth Catalysts
- North Sea offshore wind buildout:Schleswig-Holstein and Lower Saxony cluster converter stations at coastal grid connection points, anchoring bipole link demand through 2035.
- NABEG corridor streamlining:Germany's Network Expansion Acceleration Act truncates permitting timelines for HVDC priority routes, accelerating project financial close.
- Voltage source converter maturation:Multilevel architectures now deliver black-start capability and reactive power control that line-commutated thyristor stacks cannot match.
Market Restraints
- EU F-Gas Regulation phase-down:Sulfur hexafluoride restrictions compel gas-insulated switchgear redesigns, extending converter station engineering cycles.
- Submarine cable supply concentration:Specialized XLPE-insulated cable manufacturing concentrates among Nordic and Japanese producers, creating procurement bottlenecks for Baltic Sea projects.
- Thyristor stack path dependency:Ultra-high-capacity bulk corridors retain line-commutated technology where decades of operational data outweigh unproven VSC reliability at 800 kV+ ratings.
Strategic Opportunities
- Converter platform standardization:DIN norms layered atop EU machinery directives create openings for modular offshore substation designs that slash installation vessel days.
- Cross-border interconnectors:Norway-Germany and Denmark-Germany links remain underpenetrated relative to domestic corridor saturation, offering bipole link vendors diversification.
- SiC wafer captive supply:In-house semiconductor fabrication capabilities are expanding into converter station economics, compressing module cost structures for vertically integrated suppliers.
Industry Challenges
- Specialized commissioning engineer scarcity:HVDC converter hall startup and harmonic filtering calibration require expertise concentrated among retiring utility veterans and a thin pipeline of power electronics graduates.
- Legacy AC grid synchronization:Meshed network integration demands phased energization protocols that complicate handover schedules between transmission system operators and converter station EPCs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany High-Voltage Direct Current (HVDC) Transmission Systems Market |
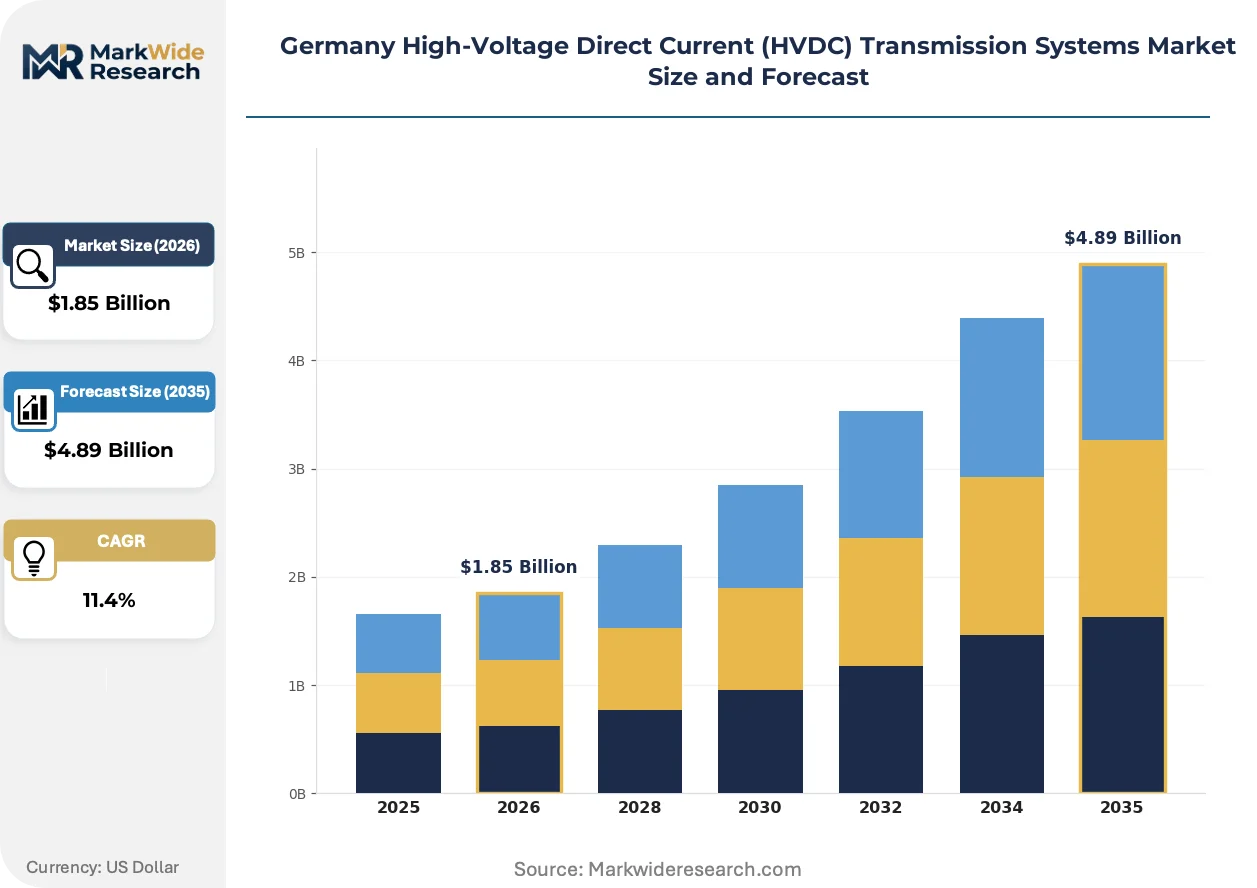
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
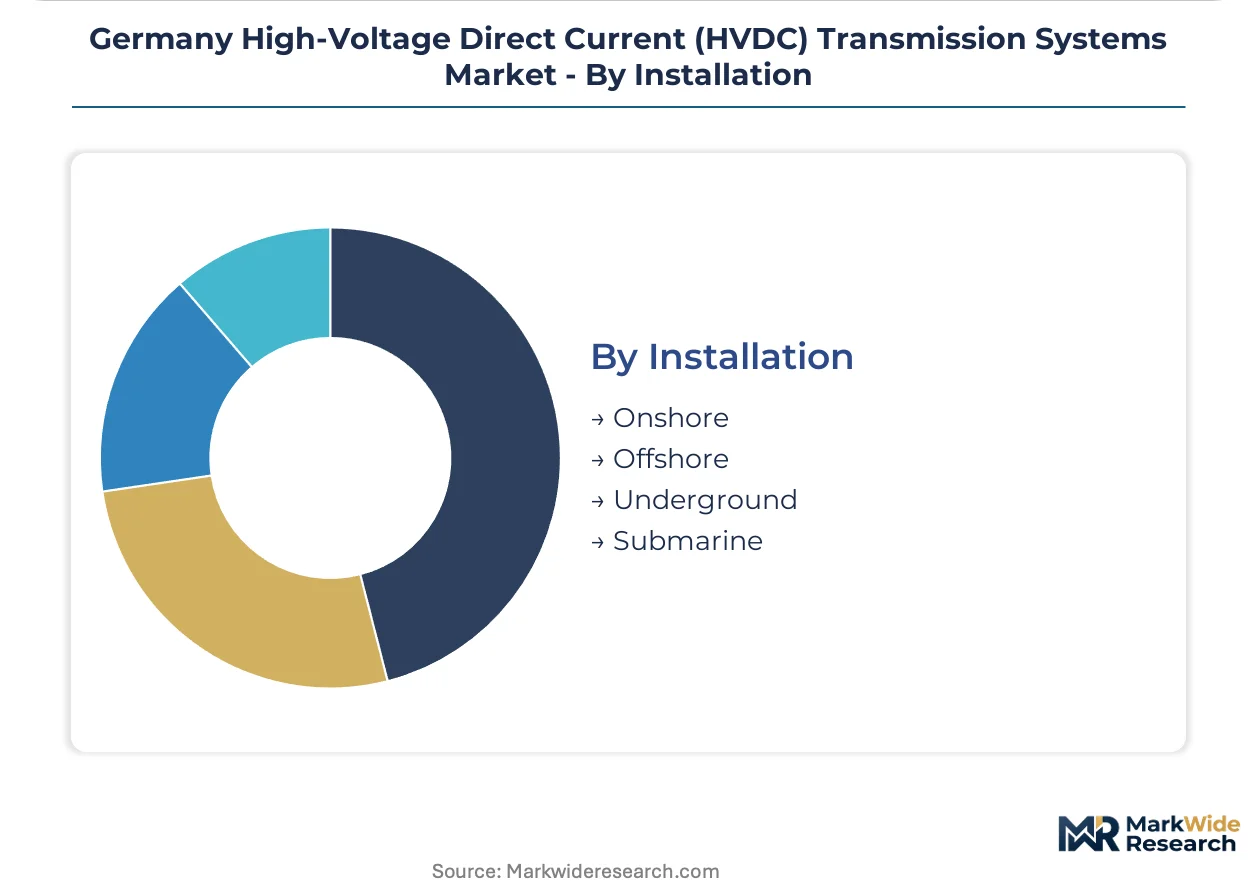
| Segmentation | Technology: Line Commutation, Voltage Source, Partial Discharge, Multiterminal End User: Utilities, Industrial, Renewable Energy, Offshore Wind Application: Interconnection, Bulk Power Transmission, Renewable Integration, Grid Expansion Installation: Onshore, Offshore, Underground, Submarine |
| Companies Covered | Mitsubishi Electric Corporation, General Electric Company, Siemens AG, Siemens Energy, Schneider Electric SA, ABB Ltd, Toshiba Corporation, Hitachi Ltd, Hitachi Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market Shifts & Advancements
Wide-bandgap semiconductors and modular offshore platform architectures are restructuring competitive economics, while regulatory pressure on insulating gases forces component-level redesigns across the supply base.
Silicon carbide power modules handle higher thermal loads and switching frequencies than silicon IGBTs, enabling compact converter valves that reduce offshore platform steel tonnage. Offshore wind developers in the German North Sea are specifying SiC-based collector platforms for 2028 commissioning windows. This technology is expanding into onshore grid reinforcement projects where land constraints and noise ordinances favor smaller converter hall footprints.
Germany's Federal Network Agency enforces Ten-Year Network Development Plans that mandate specific HVDC corridor completion deadlines, binding transmission system operators to disclosed capital schedules. The Bundesnetzagentur's binding nature eliminates regulatory discretion that previously delayed SuedLink and A-Nord routes. Converter station vendors now pre-qualify against DIN-embodying IEC standards to secure placement on framework agreements before corridor tenders release.
Utility procurement departments are unbundling converter station EPC contracts into separate cable, platform, and power electronics lots, fragmenting vendor relationships that once ran through single-source integrators. This disaggregation transfers interface risk to transmission system operators while opening power module and transformer niches to specialized suppliers. The pattern is most visible in Baltic Sea projects where Danish and German grid operators coordinate cross-border tendering under ENTSO-E harmonization guidelines.
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
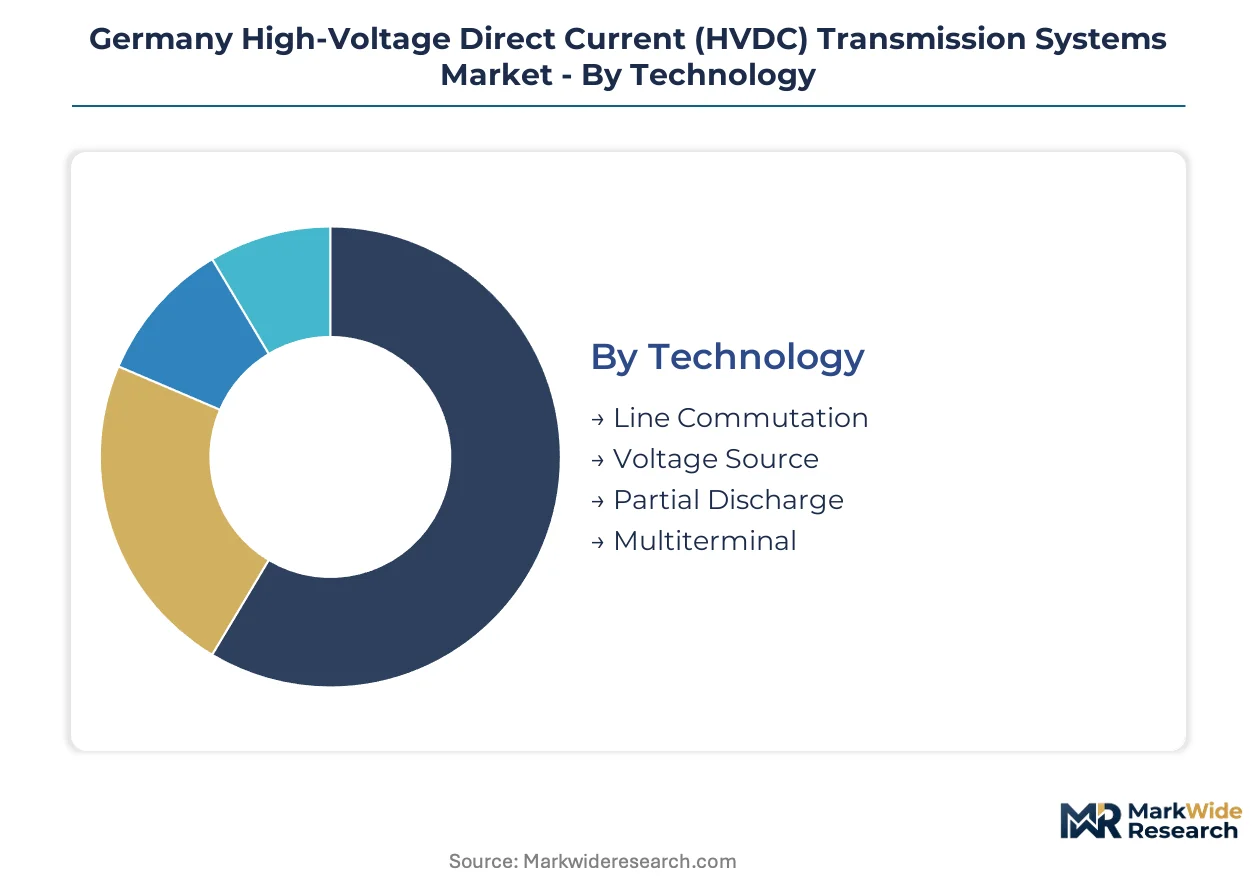
HVDC procurement patterns in Germany diverge sharply across technology generations and installation environments, with capital deployment ranging from standardized onshore converter halls to bespoke offshore platforms. Segment boundaries determine vendor qualification tiers, warranty structures, and commissioning timelines that shape project economics.
Technology:
Voltage source converter platforms demand the heaviest upfront engineering investment due to multilevel modular converter stacks and advanced control systems, while line-commutated thyristor architectures amortize development costs across decades of operational data.
- Voltage Source:Multilevel modular converters switch at frequencies above 1 kHz using insulated-gate bipolar transistors or silicon carbide power modules, enabling black-start capability and independent reactive power control. North Sea offshore wind clusters in Schleswig-Holstein specify this technology for grid-forming functionality at collector platforms.
- Line Commutation:Thyristor-based current-source converters operate at 500 kV and above with power ratings exceeding 1 GW per bipole, leveraging mature semiconductor stacks and proven harmonic filtering. Bundesnetzagentur-mandated bulk corridors including SuedLink deploy this architecture where reliability data outweighs VSC unprovenness at ultra-high voltage.
- Partial Discharge:Diagnostic monitoring systems detect insulation degradation in converter transformers and cable terminations through electromagnetic emission sensing.
- Multiterminal:Three-or-more-node HVDC networks enable power routing between multiple asynchronous grids without central dispatch.
Voltage source technology absorbs the bulk of installed capacity; multiterminal configurations are expanding most quickly.
End User:
Procurement scale and technical specification authority concentrate with transmission system operators, while industrial offtakers and renewable developers fragment into smaller lot sizes with divergent contracting norms.
- Utilities:TenneT, 50Hertz, and Amprion dominate converter station procurement through framework agreements covering multiple corridor projects, bundling cable, platform, and power electronics into single-source EPC contracts. Their technical specifications embed DIN-embodying IEC standards that pre-qualify vendors before tender release.
- Offshore Wind:Developers in the German North Sea and Baltic Sea anchor bipole link demand through mandatory grid connection obligations, specifying SiC-based collector platforms and modular offshore substation designs to compress installation vessel schedules.
- Industrial:Aluminum smelters and chemical complexes procure smaller-scale back-to-back HVDC links for asynchronous grid interconnection at plant boundaries.
- Renewable Energy:Onshore wind and solar farm clusters drive demand for compact converter stations where land constraints favor voltage source technology footprints.
Utilities absorb the bulk of installed capacity; offshore wind is climbing the fastest.
Application:
Project risk allocation and margin structures vary by application, with cross-border interconnectors transferring regulatory complexity to vendors and domestic grid expansion segments competing on standardized delivery timelines.
- Grid Expansion:Bundesnetzagentur-mandated priority corridors including A-Nord and SuedOstLink require converter stations that integrate with existing 380 kV AC networks through phased energization protocols. NABEG streamlining truncates permitting timelines, accelerating financial close for these projects.
- Renewable Integration:Remote onshore wind clusters in Lower Saxony and offshore platforms in the North Sea demand collector systems that aggregate generation at 155 kV AC and invert to ±320 kV DC for shoreward transmission.
- Interconnection:Cross-border links to Norway and Denmark remain underpenetrated relative to domestic corridor saturation, offering bipole vendors geographic diversification.
- Bulk Power Transmission:Ultra-high-capacity corridors exceeding 2 GW per bipole transmit lignite-phase-out replacement power from northern wind zones to southern load centers in Bavaria and Baden-Wuerttemberg.
Grid expansion absorbs the bulk of installed capacity; renewable integration is gaining share fastest.
Installation:
Marine construction premiums and salt-resistant engineering requirements concentrate profitability in offshore and submarine segments, while onshore installation competes on converter hall standardization and civil works efficiency.
- Offshore:Converter platforms stationed in the North Sea and Baltic Sea integrate switching equipment, transformers, and auxiliary systems on steel-jacket or gravity-base structures engineered for 25-year service lives in corrosive environments. Specialized vessel availability and weather window constraints compress installation schedules into summer months.
- Submarine:XLPE-insulated mass-impregnated cables rated to 525 kV traverse seabed corridors with burial depths exceeding 3 meters to avoid fishing gear interaction, with manufacturing concentrated among Nordic and Japanese producers creating procurement bottlenecks.
- Onshore:Converter halls in Schleswig-Holstein and Lower Saxony cluster at coastal grid connection points, standardizing around air-insulated switchgear and outdoor transformer arrangements.
- Underground:Urban corridor routing through densely populated regions employs gas-insulated switchgear and direct-buried cable systems to minimize right-of-way conflicts.
Offshore installation absorbs the bulk of installed capacity; submarine cable systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lower Saxony's coastal wind priority zones concentrate converter station procurement under NABEG streamlining provisions. Schleswig-Holstein clusters grid connection points where offshore platforms feed bipole links. Bavaria and Baden-Württemberg absorb transmitted capacity from northern generation zones.
Schleswig-Holstein
North Sea offshore wind clusters anchor bipole link demand through mandatory grid connection obligations. The Bundesnetzagentur enforces Ten-Year Network Development Plan deadlines that bind transmission system operators to corridor completion schedules. Converter stations cluster at Brunsbüttel and Büsum where coastal grid connection points aggregate offshore generation.
Lower Saxony
Onshore wind zones in East Frisia and the Emsland region drive demand for compact voltage source converter stations. NABEG provisions truncate permitting timelines for priority corridors including A-Nord and SuedLink. The converter hall concentration at Diele and Garrel/Ost integrates 155 kV AC collector systems with ±320 kV DC shoreward transmission.
Bavaria
Southern load centers absorb lignite-phase-out replacement power through ultra-high-capacity bulk corridors exceeding 2 GW per bipole. DIN-embodying IEC standards govern converter station pre-qualification for framework agreements covering SuedOstLink completion. The Grafenrheinfeld and Bergrheinfeld substation clusters handle phased energization protocols for meshed network integration.
Baden-Württemberg
Industrial load concentration around Stuttgart and Mannheim stabilizes demand for asynchronous grid interconnection. EU F-Gas Regulation phase-downs compel gas-insulated switchgear redesigns that extend converter station engineering cycles. The Kupferzell substation anchors Rhine corridor power distribution to southwestern manufacturing zones.
North Rhine-Westphalia
Ruhr industrial complexes and chemical clusters procure back-to-back HVDC links for plant-boundary grid synchronization. The state's central position in the German transmission network creates demand for multiterminal configurations enabling power routing between multiple asynchronous grids. Converter stations at Osterath and Werne integrate with the Dutch and Belgian interconnector network under ENTSO-E harmonization guidelines.
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power electronics vendors commanding premium positions in offshore platforms while component suppliers capture standardized onshore converter hall contracts. The vendor base concentrates among European and Japanese conglomerates with in-house semiconductor fabrication or transformer manufacturing capabilities. Three archetypes dominate: vertically integrated system integrators, specialized power module manufacturers, and cable-centric EPC consortiums. Competitive moves center on SiC wafer captive supply investments and modular offshore platform standardization.
Among Germany-based conglomerates, Siemens Energy and Siemens AG occupy positions spanning converter station EPC through power electronics manufacturing. ABB Ltd anchors European supply chain configurations for HVDC valves and transformers. Hitachi Energy represents the multilevel voltage-source converter architecture specialization visible in offshore collector platform specifications.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| General Electric Company |
| Siemens AG |
| Siemens Energy |
| Schneider Electric SA |
| ABB Ltd |
| Toshiba Corporation |
| Hitachi Ltd |
| Hitachi Energy |
| Others |
Supply & Pricing Matrix
Sovereign-backed transmission system operators anchor procurement volumes through multi-year framework agreements, compressing pricing discipline among converter station vendors while concentrating supply qualification around DIN-embodying IEC standards. This ownership pattern elevates long-term contract security over spot-market flexibility, shaping vendor investment in captive semiconductor fabrication and modular platform manufacturing.
Pricing Analysis
Premium pricing attaches to converter stations with sub-36-month delivery windows, while standardized onshore halls with extended lead times trade at contracted discounts. Three-tier pricing structure across premium offshore platforms, standard grid-expansion halls, and economy back-to-back links differentiates by certification grade and installation complexity. Cost compression in voltage source converter modules is intensifying because silicon carbide wafer supply expansion lags demand growth. Offshore wind developers demonstrate lowest price sensitivity due to mandatory grid connection obligations, whereas industrial offtakers negotiate aggressively on back-to-back link specifications.
Supply Chain Analysis
Dual-sourcing requirements embedded in Bundesnetzagentur framework agreements compel transmission system operators to qualify at least two vendors per converter station subsystem. Manufacturing concentrates in Germany, Switzerland, and Japan for HVDC valves and transformers, while XLPE-insulated submarine cable production rests on Nordic and Japanese producers. Critical dependencies include silicon carbide wafers, high-grade transformer steel, and sulfur hexafluoride alternatives for gas-insulated switchgear. Single-source vulnerability in semiconductor module supply creates procurement risk during offshore wind buildout waves. Distribution runs through EPC consortiums bundling cable, platform, and power electronics into integrated delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's HVDC transmission systems market is consolidating around vertically integrated suppliers capable of captive silicon carbide production, with EU F-Gas Regulation compliance costs forcing weaker component specialists toward exit or acquisition.
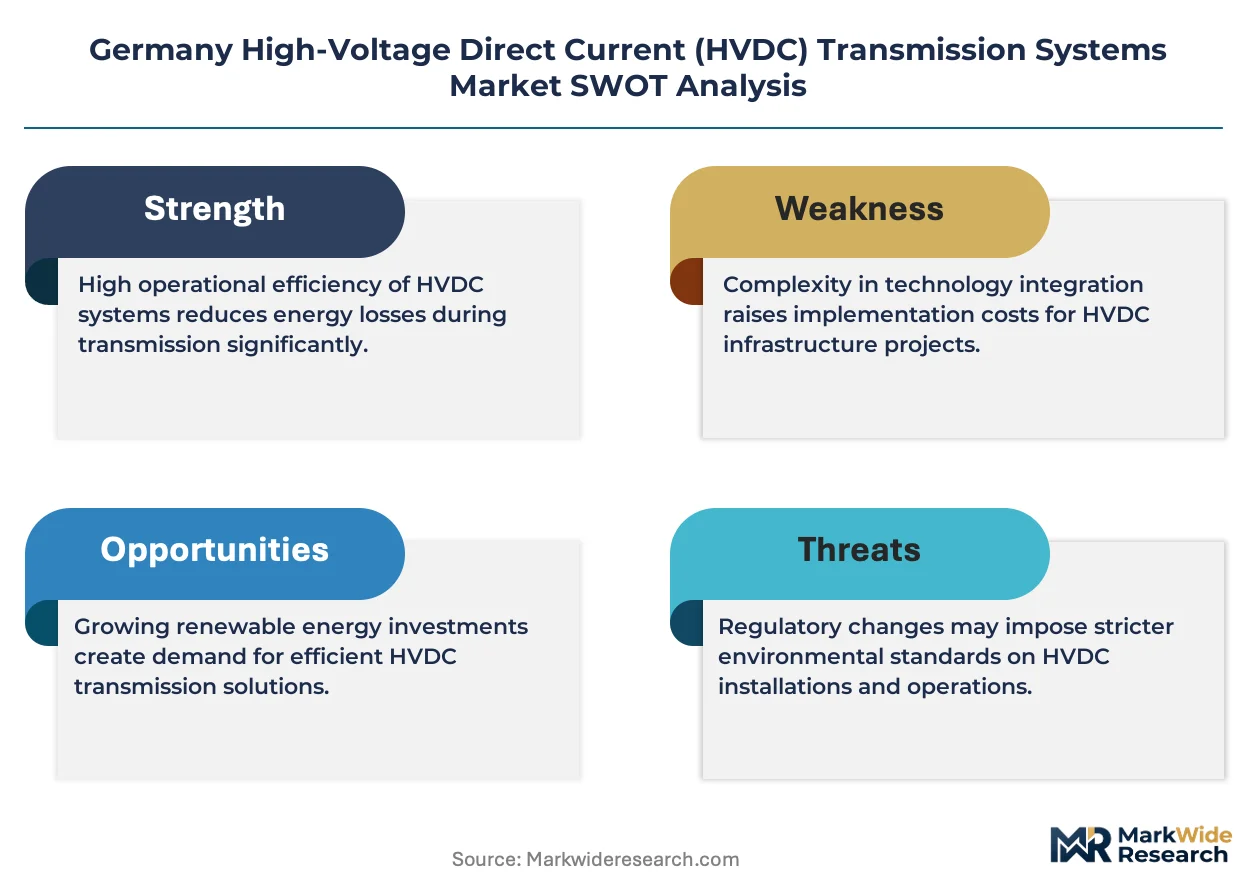
For Market Incumbents: Acquire offshore platform engineering capabilities to defend against specialized marine EPC entrants capturing North Sea collector substation contracts. Siemens Energy and ABB Ltd should expand in-house SiC wafer fabrication to compress module cost structures and lock supply security. Bundesnetzagentur-mandated corridor deadlines create demand visibility that rewards capacity pre-commitment in Schleswig-Holstein coastal zones. For New Entrants and Emerging Players: Direct-to-utility digital tendering platforms offer lowest-friction entry for power module specialists seeking bypass of incumbent EPC relationships. Baltic Sea cross-border interconnectors present the most penetrable segment, with Danish-German coordination under ENTSO-E guidelines fragmenting procurement into disaggregated cable and electronics lots. Target modular offshore substation designs that slash installation vessel days through standardized steel-jacket configurations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converter valve specialists in Switzerland and southern Germany facing working capital strain from NABEG-accelerated project timelines. Long-term viability hinges on semiconductor backward integration and DIN certification maintenance through the analysis window. Watch for Bundesnetzagentur standardization mandates on interoperability specifications as the inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Wafer Captive Supply | In-house semiconductor fabrication compresses module costs for vertically integrated suppliers competing on North Sea offshore platforms. |
| Modular Offshore Platform Standardization | DIN-embodying IEC norms enable steel-jacket designs that reduce installation vessel schedules and weather window exposure. |
| Cross-Border Interconnector Expansion | Norway-Germany and Denmark-Germany links diversify revenue beyond domestic corridor saturation under ENTSO-E harmonization. |
| F-Gas Compliant Switchgear Redesign | EU F-Gas Regulation phase-down compels gas-insulated system engineering cycles that extend project timelines and elevate R&D recovery. |
| Converter Hall EPC Disaggregation | Unbundled cable, platform, and power electronics lots transfer interface risk to transmission system operators while opening specialist niches. |
Research Methodology
Multi-period observation of converter station procurement awards, corridor completion schedules, and semiconductor supply allocations anchored the trend analysis, supplemented by interviews with transmission system operator planning officers, offshore wind project developers, EPC contractor engineering leads, and power electronics procurement managers. Secondary validation drew from Bundesnetzagentur Ten-Year Network Development Plan filings, ENTSO-E harmonization guidelines, EU Clean Energy Package regulatory texts, and DIN standardization committee disclosures. Bottom-up project pipeline aggregation triangulated against top-down market sizing from disclosed framework agreement values.
Segment-weighting approaches distributed capacity forecasts across voltage source and line-commutated technology generations, onshore and offshore installation environments, and utility versus offshore wind end-user categories throughout the projection horizon. CAGRs were derived from corridor-specific financial close schedules and disclosed converter station delivery timelines. Industry-specific inputs included NABEG permitting acceleration effects, SiC module adoption curves in offshore collector platforms, and F-Gas Regulation engineering cycle extensions.
Inputs from Bundesnetzagentur corridor status reports and transmission system operator procurement disclosures were available through the study window; gaps in proprietary semiconductor vendor cost structures and unannounced cross-border interconnector negotiations introduce uncertainty bands around vendor share projections. Forecasts reflect assumptions on NABEG implementation consistency, ENTSO-E standardization adherence timelines, and silicon carbide wafer supply expansion rates. Deviation in EU F-Gas Regulation enforcement stringency or offshore wind auction award volumes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Fuse Rails Market