
 Power Transmission Tower Market | 2026-2036
Power Transmission Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transmission Tower Market Analytics
Renewable energy integration is pivoting utility procurement toward higher-capacity lattice and monopole structures. KEC International Ltd. leverages its EPC footprint across Africa and the Middle East to secure turnkey transmission contracts. Valmont Industries sustains manufacturing scale through captive galvanizing and North American steel sourcing. Skipper Limited anchors its competitiveness on lattice tower specialization for 765 kV and ultra-high-voltage lines.
A power transmission tower is a steel, aluminum, concrete, or composite structure engineered to suspend conductors at prescribed clearances, with lattice designs typically fabricated from angular steel sections joined by bolted connections and hot-dip galvanized for corrosion resistance. Its primary purpose is to maintain electrical isolation and mechanical stability across spans ranging from 300 to 500 meters in high-voltage networks. Lattice towers dominate volume due to their strength-to-weight efficiency and established supply chains for 400 kV and above. Monopole structures capture premium positioning where right-of-way constraints or aesthetic requirements restrict lattice footprints. Steel remains the baseline material, though composite prototypes are gaining trial deployments in corrosive coastal zones.
FERC Order 2023 and the EU Green Deal are tightening embodied-carbon thresholds and mandating lifecycle assessments for new transmission infrastructure. India's CEA enforces stringent BIS IS 802 and IS 5613 standards for tower design, testing, and quality assurance. China's GB standards and dual carbon goals are pushing NMPA-aligned producers toward higher-grade steel and reduced galvanizing emissions. Stakeholders must monitor how evolving material certification regimes in Europe and North America reshape sourcing economics and supplier qualification timelines.
Market Dynamics
Grid modernization mandates from FERC and the EU Green Deal are forcing utilities to replace aging lattice infrastructure with higher-capacity designs capable of carrying renewable generation loads. Material certification regimes are tightening across North America and Europe, extending supplier qualification timelines and reshaping sourcing economics for tower fabricators.
Growth Catalysts
- Renewable integration mandates:India's CEA and state regulators are accelerating interstate corridor buildouts to evacuate solar and wind generation from Rajasthan and Gujarat. This utility procurement pivot requires 765 kV and ultra-high-voltage lattice structures.
- FERC Order 2023:The US Federal Energy Regulatory Commission's interconnection reforms are compressing queue timelines for transmission projects, directly expanding tower demand across Texas, California, and Midwest ISO regions.
- Hot-dip galvanizing advances:Improved zinc-alloy coatings are extending tower service life in corrosive coastal environments, opening replacement cycles in Florida, Louisiana, and Southeast Asian maritime zones.
Market Restraints
- Steel price volatility:Hot-rolled coil and structural angle steel input costs fluctuate with scrap metal and energy pricing, compressing fabrication margins for tier-two suppliers dependent on spot purchasing.
- Galvanizing capacity concentration:North American hot-dip galvanizing infrastructure clusters in the US Midwest and Ontario, creating logistics bottlenecks for western and southern tower projects.
- Right-of-way constraints:Urban densification and agricultural land preservation in the Netherlands and Germany restrict lattice tower footprints, forcing costlier monopole alternatives without equivalent load-bearing capacity.
Strategic Opportunities
- Composite material trials:Fiber-reinforced polymer prototypes are gaining test deployments in Saudi Arabia's coastal zones and Florida's hurricane corridors, offering corrosion immunity and reduced maintenance cycles.
- Turnkey EPC bundling:African and Middle Eastern utilities are consolidating tower supply with civil works and stringing contracts, favoring integrated contractors over component specialists.
- EU Green Deal embodied-carbon thresholds:Lifecycle assessment mandates are creating first-mover advantage for European fabricators with verified low-carbon steel sourcing and renewable-powered galvanizing operations.
Industry Challenges
- Welding certification bottlenecks:AWS D1.1 and EN 1090 welder qualification backlogs are extending production lead times for 400 kV and above lattice towers requiring full-penetration joint certification.
- Legacy grid interoperability:New high-capacity towers must interface with 1960s-era conductor hardware and foundation designs, complicating engineering review and increasing project-specific customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transmission Tower Market |
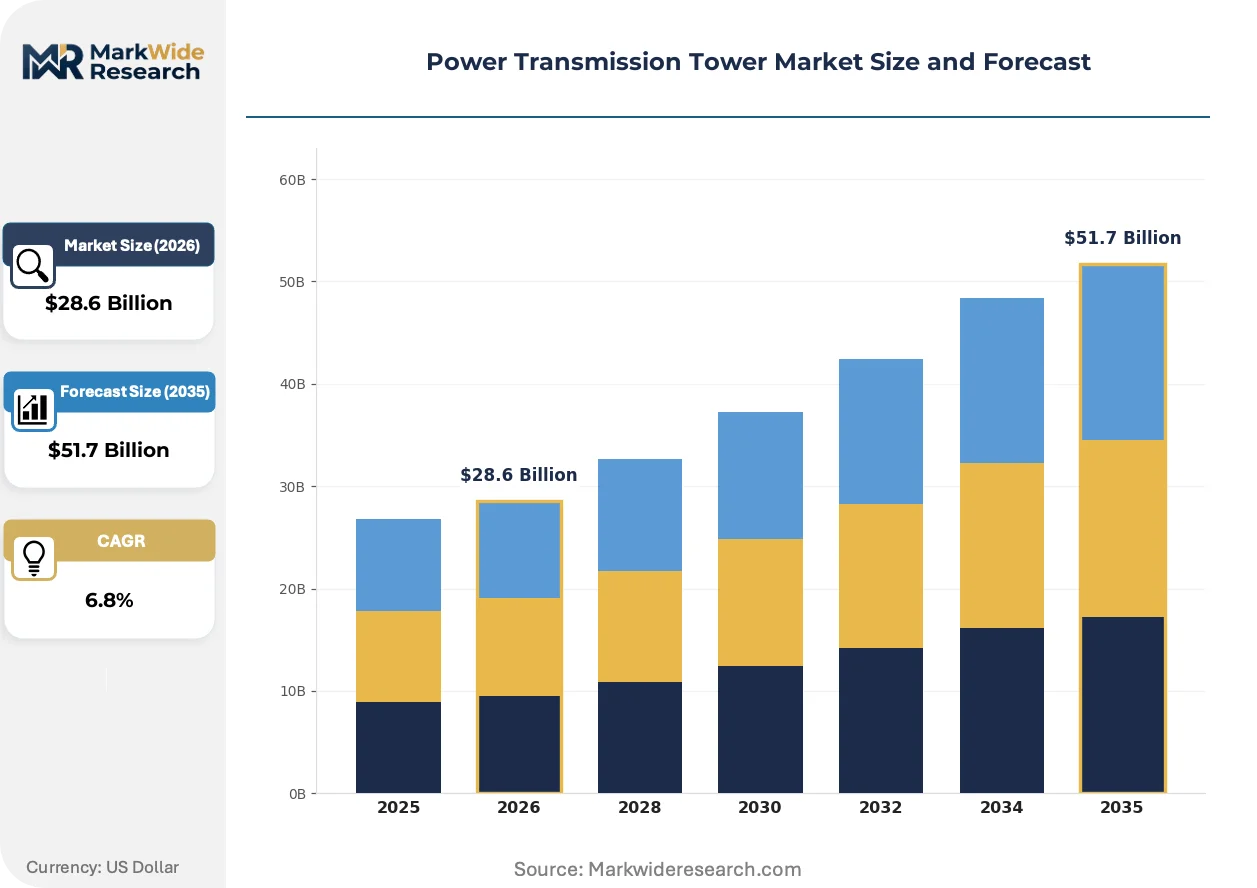
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tower Structure, Insulated, Lattice, Monopole Application: Utility, Renewable Energy, Industrial, Telecom Material: Steel, Aluminum, Reinforced Concrete, Composite End User: Public Utilities, Independent Power Producers, Government, Private Developers |
| Companies Covered | SAE Towers, Kalpataru Power Transmission Ltd., KEC International Ltd., Tata Projects, Nanjing Daji Iron Tower Manufacturing Co. Ltd, Skipper Limited, Valmont Industries, ZTT Group, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transmission Tower Market Evolving Landscape
Digital design tools and modular fabrication methods are compressing tower development cycles while regulatory pressure on embodied carbon is reshaping material selection protocols across high-voltage transmission procurement.
High-strength steel grades are consolidating market preference for lattice tower construction. These alloys reduce member cross-sections and overall structure weight while maintaining mechanical performance under ice and wind loading. Chinese and Indian utilities are specifying Q420 and Q460 grades for 765 kV corridors, displacing traditional Q345 specifications. This material transition is consolidating procurement around mills with certified high-strength production capacity.
The EU Green Deal's lifecycle assessment requirements are mandating environmental product declarations for transmission infrastructure. Tower fabricators must now document cradle-to-gate carbon intensity for steel sourcing, galvanizing, and transport. European TSOs are embedding these thresholds into technical specifications, favoring suppliers with renewable-powered production and scrap-based electric arc furnace steel.
Utility buyers are unbundling tower supply from traditional turnkey EPC contracts to access specialized fabricators directly. This disintermediation is fragmenting procurement channels in India and the United States, where state transmission utilities now issue separate steel structure tenders ahead of civil and stringing awards. The shift is most visible in India's Green Energy Corridor program, where PGCIL and state DISCOMs are qualifying discrete tower vendors outside consolidated EPC frameworks.
Power Transmission Tower Market Segmentation
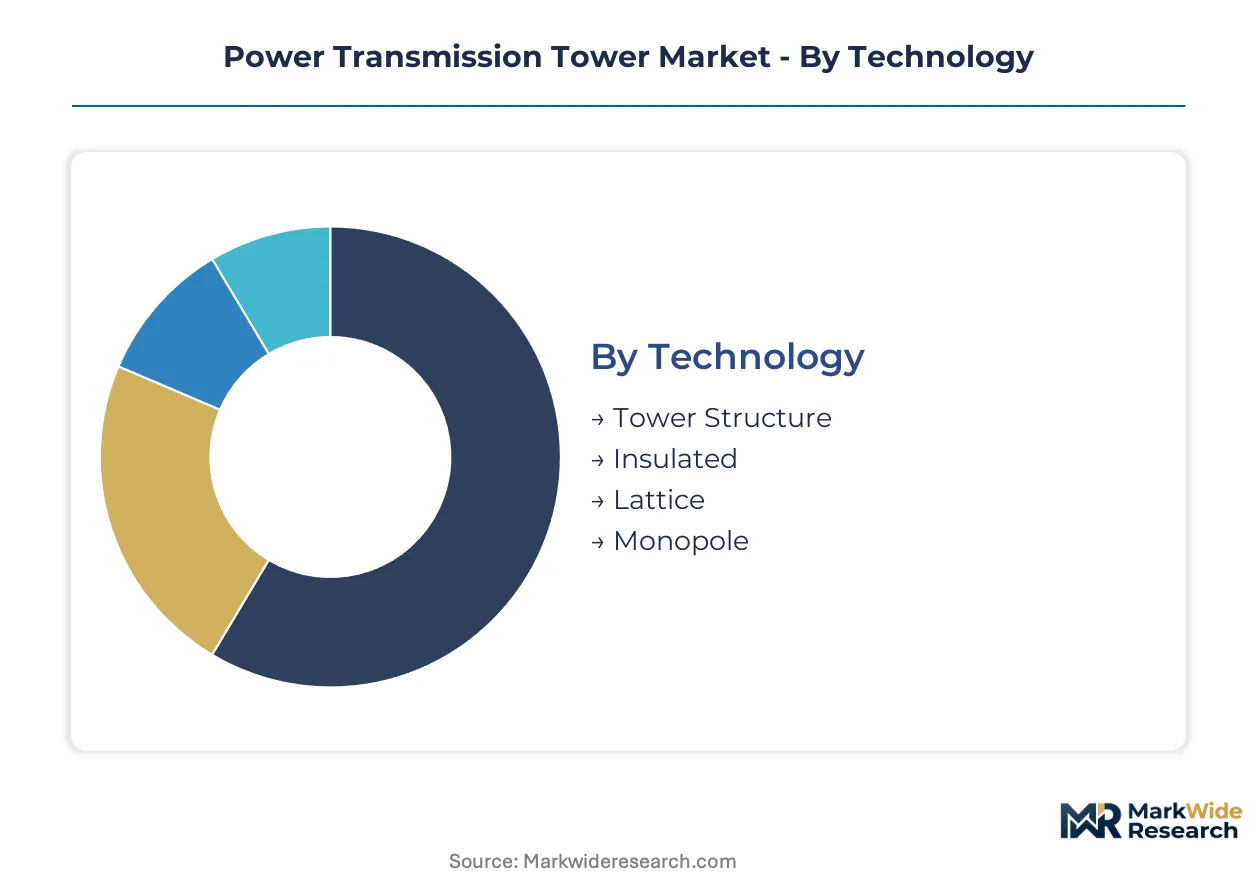
Segmentation in power transmission towers determines procurement pathways, certification burdens, and margin structures. Material choices and structural designs carry distinct regulatory requirements across voltage classes and geographies. Understanding these divisions reveals where supplier qualification timelines extend and where standardization compresses costs.
Technology:
Lattice towers require AWS D1.1 or EN 1090 welding certification for angular steel connections, while monopole structures demand thicker plate rolling certifications and specialized foundation engineering sign-offs. Insulated tower designs face additional dielectric testing protocols under IEC 60383 for live-line maintenance applications.
- Lattice:Angular steel sections joined by bolted connections dominate 400 kV and above corridors. Indian utilities specify these for 765 kV Rajasthan-Gujarat evacuation routes where strength-to-weight ratios offset transport costs across difficult terrain.
- Monopole:Tapered steel tubes suit right-of-way constrained urban corridors and aesthetic-sensitive zones. German and Dutch TSOs favor these where agricultural preservation limits lattice footprints, despite 15-25% cost premiums and reduced load-bearing capacity.
- Insulated:Live-line workable designs incorporate composite insulator integration points for maintenance access. These see concentrated deployment in Saudi Arabia and Florida where outage minimization justifies specialized engineering.
- Tower Structure:Generic classification covering hybrid and proprietary designs outside standard lattice-monopole binaries. Emerging markets trial these for rapid deployment in emergency restoration scenarios.
Lattice sits at the top of the volume ranking, with monopole climbing the fastest as urban densification spreads.
Application:
Cost tiers separate utility-scale procurement from specialized industrial and telecom deployments. Volume concentration and standardization levels determine which segments attract tier-one fabricator attention versus specialist niche players.
- Utility:Interstate and inter-regional transmission corridors constitute the core revenue base. FERC Order 2023 queue compression in Texas and Midwest ISO regions is accelerating procurement cycles for 345 kV and 500 kV structures.
- Renewable Energy:Solar and wind farm evacuation drives 765 kV and ultra-high-voltage demand. China's dual carbon goals and India's Green Energy Corridor program specify high-capacity towers for remote generation zones.
- Industrial:Captive power and heavy manufacturing connections require lower-voltage specialized designs. These contracts fragment across regional fabricators with proximity advantages to mining and petrochemical clusters.
- Telecom:Co-location on existing transmission infrastructure or standalone microwave relay towers. Regulatory separation of power and communications assets limits this segment in markets with strict unbundling regimes.
Utility commands the dominant procurement volume, with renewable energy expanding most quickly as generation buildouts outpace grid infrastructure.
Material:
Supply concentration and embodied-carbon accounting differentiate procurement economics. European lifecycle assessment mandates under EU Green Deal protocols favor scrap-based electric arc furnace steel, while coastal corrosion drives composite trials.
- Steel:Hot-rolled structural angles and plates remain the baseline, with Q420 and Q460 high-strength grades displacing Q345 in Chinese and Indian 765 kV specifications. Mills with certified high-strength capacity are consolidating procurement relationships.
- Composite:Fiber-reinforced polymer prototypes offer corrosion immunity in Saudi Arabia's coastal zones and Florida's hurricane corridors. Dielectric properties and reduced maintenance cycles justify 40-60% first-cost premiums in selected deployments.
- Aluminum:Lightweight alternatives for specialized transport-constrained installations. Limited penetration due to cost and mechanical performance gaps against high-strength steel.
- Reinforced Concrete:Foundation systems and hybrid lower sections for monopole designs. Precast concrete bases reduce field curing time in cold-climate Canadian and Nordic projects.
Steel maintains absolute volume dominance, with composite gaining share fastest in corrosive environment replacements.
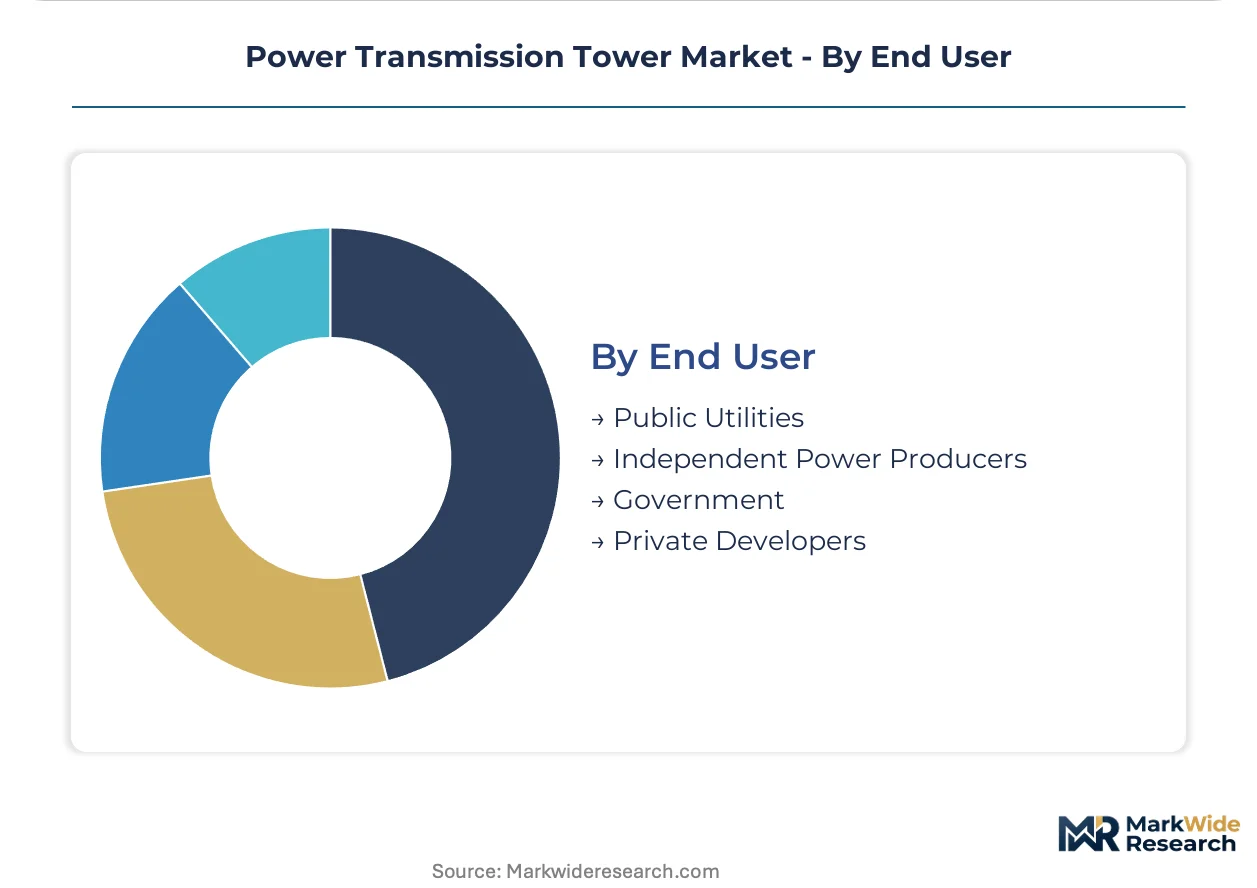
End User:
Customer type determines contract structure, risk allocation, and payment security. Public procurement cycles extend timelines but offer volume scale, while private developers prioritize speed-to-commissioning.
- Public Utilities:State transmission utilities and national TSOs issue formal tenders with BIS IS 802, GB standards, or EN 1090 compliance requirements. India's PGCIL and China's State Grid anchor regional demand through multi-year framework agreements.
- Independent Power Producers:Merchant generation developers require rapid grid connection for project financing milestones. These buyers prioritize fabrication speed over lowest unit cost, accepting modest premiums for delivery certainty.
- Government:Rural electrification and strategic corridor programs with sovereign-backed payment security. African and Southeast Asian ministries consolidate tower supply with civil works in turnkey EPC structures.
- Private Developers:Commercial and industrial microgrids, data center power infrastructure, and captive transmission. Fragmented demand with project-specific engineering and shorter relationship horizons.
Public utilities represent the deepest procurement base, with independent power producers showing the steepest expansion trajectory as renewable merchant generation proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's State Grid Corporation anchors transmission infrastructure deployment through its ultra-high-voltage corridor buildouts. Grid modernization mandates from FERC and the EU Green Deal are reshaping procurement patterns across multiple jurisdictions simultaneously.
United States
FERC Order 2023 compresses interconnection queue timelines for Texas and Midwest ISO regions. The Federal Energy Regulatory Commission mandates lifecycle assessments for new transmission infrastructure. Tower fabricators cluster in the industrial Midwest around Chicago and Detroit to access captive galvanizing capacity.
China
State Grid's dual carbon goals accelerate 765 kV and ultra-high-voltage lattice procurement for western renewable evacuation. GB standards and NMPA-aligned producers face tightening embodied-carbon thresholds. Manufacturing concentrates in Jiangsu and Shandong provinces where mills supply Q460 high-strength steel grades.
India
CEA-enforced interstate corridor buildouts evacuate solar generation from Rajasthan and Gujarat. The Central Electricity Authority mandates BIS IS 802 and IS 5613 compliance for tower design and testing. Fabrication clusters in Maharashtra and Tamil Nadu serve PGCIL's Green Energy Corridor program.
Germany
EU Green Deal lifecycle assessment requirements mandate environmental product declarations for transmission steel. TSOs embed embodied-carbon thresholds into technical specifications favoring renewable-powered production. Right-of-way constraints in Bavaria and North Rhine-Westphalia force monopole adoption despite cost premiums.
Saudi Arabia
NEOM and Red Sea coastal projects trial fiber-reinforced polymer towers for corrosion immunity in maritime zones. The kingdom's sovereign-backed payment security consolidates tower supply with civil works in turnkey structures. Demand concentrates in the Eastern Province where petrochemical clusters require specialized industrial connections.
Power Transmission Tower Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators add high-strength steel rolling and captive galvanizing lines. The vendor base separates into tier-one integrated EPC contractors, specialized lattice tower fabricators, and regional component suppliers. Strategic archetypes include turnkey bundlers capturing African and Middle Eastern utility contracts, premium monopole specialists serving European right-of-way constrained markets, and scale-driven steel structure vendors qualified for Indian and Chinese state utility frameworks. Geographic expansion and portfolio diversification represent the dominant competitive vectors as suppliers seek qualification across multiple regulatory regimes.
Among India-based integrated contractors, KEC International Ltd., Kalpataru Power Transmission Ltd., and Larsen & Toubro occupy positions exemplifying the turnkey EPC archetype. These entities represent the bundling strategy consolidating tower fabrication with civil works and stringing contracts. Chinese fabricators including Nanjing Daji Iron Tower Manufacturing Co. Ltd. and ZTT Group anchor the scale-driven tier serving State Grid's high-volume procurement. Valmont Industries exemplifies North American manufacturing with captive supply chain control, while Skipper Limited represents specialized lattice competency for ultra-high-voltage specifications.
| Leading Market Players |
|---|
| SAE Towers |
| Kalpataru Power Transmission Ltd. |
| KEC International Ltd. |
| Tata Projects |
| Nanjing Daji Iron Tower Manufacturing Co. Ltd |
| Skipper Limited |
| Valmont Industries |
| ZTT Group |
| Larsen & Toubro |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's embodied-carbon thresholds gate qualified supply and premium-tier pricing access, forcing fabricators with renewable-powered galvanizing and scrap-based steel sourcing into higher-margin procurement pools while relegating conventional producers to cost-competitive tenders.
Pricing Analysis
Direct-to-utility contract discounts compress distributor margins in India's PGCIL and China's State Grid frameworks, while monopole specialists serving German and Dutch TSOs command 15-25% premiums over lattice equivalents. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant fabricators with verified environmental product declarations from conventional suppliers and unqualified regional entrants. Cost compression in standard-grade lattice towers is intensifying because Indian and Chinese utilities consolidate procurement around mills with certified Q460 high-strength capacity. Independent power producers exhibit lowest price sensitivity, prioritizing delivery certainty for project financing milestones over unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with North American hot-dip galvanizing capacity clustering in the US Midwest and Ontario, creating logistics bottlenecks for western and southern tower projects. Manufacturing gravity centers on China, India, and the United States, with Jiangsu and Shandong provinces supplying Q460 grades, Maharashtra and Tamil Nadu serving PGCIL demand, and Chicago-Detroit clusters anchoring captive galvanizing. Raw material dependencies draw from hot-rolled structural angle steel, zinc-alloy coatings, and high-strength Q420-Q460 grades. Tariff exposure on steel imports threatens margin stability for tier-two fabricators dependent on spot purchasing. Distribution runs through direct utility tenders, consolidated EPC bundlers in Africa and the Middle East, and disintermediated specialist channels in India and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FERC Order 2023's interconnection queue compression directly expanding tower demand across Texas, California, and Midwest ISO regions.
For Market Incumbents: Deploy captive galvanizing capacity additions to defend against logistics chokepoints threatening western and southern project delivery. Secure multi-year framework agreements with State Grid and PGCIL before welding certification backlogs extend production lead times for 765 kV structures. Backward integration into high-strength steel rolling insulates margin compression from spot purchasing volatility. For New Entrants and Emerging Players: Launch via turnkey EPC bundling in African and Middle Eastern markets where sovereign-backed payment security consolidates tower supply with civil works. Target Saudi Arabia's NEOM coastal corridor for fiber-reinforced polymer trial deployments, exploiting corrosion immunity premiums in maritime zones. Penetrate through specialized lattice competency for ultra-high-voltage specifications where AWS D1.1 and EN 1090 welder qualification shortages constrain incumbent capacity. For Investors and Strategic Acquirers: Roll-up economics work for regional galvanizing specialists because North American infrastructure concentration creates scarcity value for geographically distributed coating capacity. Long-term viability hinges on qualification across multiple regulatory regimes spanning FERC, EU Green Deal, and CEA mandates. Monitor welding certification backlog durations as inflection indicator for fabrication capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | KEC International and Larsen & Toubro expand high-strength steel rolling to capture 765 kV corridor demand. |
| Backward Integration | Valmont Industries' captive galvanizing insulates margin pressure from Midwest capacity bottlenecks. |
| Green Certification Program | EU Green Deal lifecycle assessments favor European fabricators with renewable-powered production. |
| Long-term Supply Agreement | Chinese mills with Q460 capacity consolidate procurement relationships with State Grid. |
| Technology Licensing | Composite tower prototypes in Saudi Arabia and Florida open replacement cycles in corrosive environments. |
Research Methodology
Direct dialogue with utility planning officers, EPC contractors, tower fabrication executives, and grid operators combined with secondary validation from FERC filings, EIA project databases, IEA transmission reports, and national utility procurement records. Bottom-up and top-down triangulation cross-checks capacity announcements against actual deployment tracking.
Bottom-up modeling builds from individual project pipelines across voltage classes and geographies, while top-down analysis benchmarks against national transmission investment programs. Segmentation dimensions span structural technology, application type, material grade, and end-user procurement structure. CAGRs derive from installed base replacement cycles and renewable evacuation corridor buildouts over the analysis window. Forecast inputs incorporate steel price volatility indices and welding certification throughput constraints.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, abrupt commodity price shocks, and geopolitical disruptions to steel trade flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Energy Cable Market