
 Transmission and Distribution Fault Detection Market | 2026-2036
Transmission and Distribution Fault Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission and Distribution Fault Detection Market Analysis
The EU Green Deal is shifting procurement priorities across European utilities toward predictive fault detection platforms. ABB Ltd. leverages its digital substation portfolio to anchor contracts in Nordic grid modernization programs. Siemens AG competes through integrated SCADA-to-protection-relay architectures that reduce outage response times.
Transmission and distribution fault detection encompasses hardware and software systems that identify, locate, and isolate electrical anomalies in high-voltage networks, typically operating at detection speeds under 100 milliseconds to prevent cascade failures. These systems serve the primary commercial purpose of minimizing downtime penalties and protecting capital-intensive transformer assets. Smart grid technology captures the largest share of new investment as utilities prioritize two-way communication infrastructure, while IoT sensors represent the fastest-expanding product category due to declining unit costs and edge-computing capabilities. Protection relays remain the most mature segment with stable margins concentrated among established relay manufacturers.
FERC Order 2222 in the United States and the EU F-Gas Regulation shape equipment specifications and market access requirements for grid-connected detection systems. Compliance with IEC 61850 communication standards and IEEE 1547 interconnection rules now determines vendor eligibility in most OECD procurement tenders. Stakeholders must monitor how carbon-border adjustment mechanisms and domestic content requirements alter supplier qualification criteria across major utility markets.
Market Dynamics
The convergence of IEC 61850 digital substation standards with edge-computing architectures is compressing fault detection response windows below 50 milliseconds. This technical threshold is redefining procurement specifications across high-voltage networks and disqualifying legacy relay vendors from premium tender categories.
Growth Catalysts
- FERC Order 2222:The US mandate for distributed energy resource aggregation is forcing utilities to deploy synchronized phasor measurement units capable of islanding detection. Procurement volumes for these systems concentrate in Texas and California grid interconnection zones.
- Silicon carbide power electronics:Wide-bandgap semiconductors enable sub-cycle fault interruption in medium-voltage distribution feeders. Equipment manufacturers in Germany and Japan are integrating these devices into next-generation protection relays.
- Utility renewable integration timelines:Wind and solar interconnection queues in Spain, Australia, and Brazil require dynamic line rating systems with embedded fault location capability. Network operators are bundling these sensors with transformer monitoring platforms.
Market Restraints
- Copper and rare earth magnet cost volatility:Current transformer cores and relay actuator mechanisms depend on these inputs. Price swings in Chilean copper concentrate and Chinese neodymium processing are compressing hardware margins.
- Embedded firmware supply concentration:Real-time operating systems for protection relays source predominantly from US and German software houses. Licensing terms restrict second-source qualification timelines.
- IEC 61850 Edition 2.1 migration friction:The communication protocol upgrade requires simultaneous hardware and configuration tool replacement. Utilities with mixed-vendor substations face stranded asset risk during transition periods.
Strategic Opportunities
- India's rural electrification saturation:The country's distribution utility reform program is mandating smart meter-integrated fault passage indicators. Vendors with IEC 62056-21 compliant offerings can access state-level tender pipelines.
- EU F-Gas Regulation phase-down:The ban on SF6 switchgear is accelerating demand for vacuum interrupter-based fault isolation systems. Manufacturers with dry-air insulation technology secure preferential status in Nordic and German procurement.
- Digital twin convergence with physical sensors:Real-time electromagnetic transient simulation paired with IoT edge devices enables predictive fault classification. US and Chinese utilities are piloting these architectures in metropolitan distribution networks.
Industry Challenges
- Protection engineer scarcity:The specialized skill set combining power system analysis with cybersecurity protocol implementation is concentrated among aging utility workforces in OECD markets. Training pipelines have not scaled to replacement demand.
- Multi-vendor interoperability certification:IEC 61850 conformance testing for mixed-relay substations requires 18-24 month validation cycles. Project delays accumulate when firmware revisions trigger re-certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission and Distribution Fault Detection Market |
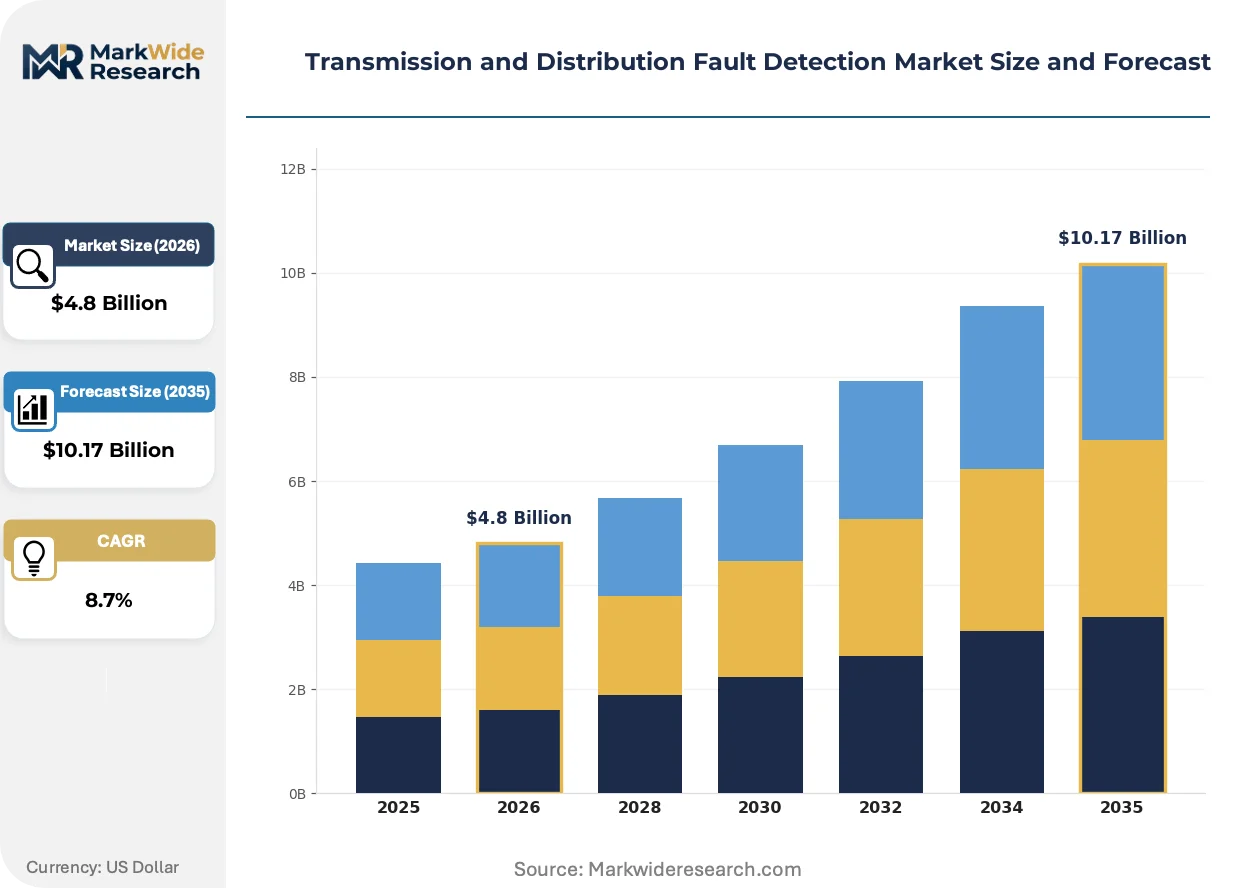
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Grid, SCADA Systems, Drones, IoT Sensors Product Type: Line Monitoring Devices, Fault Locator Systems, Protection Relays, Asset Management Tools End User: Utilities, Industrial Plants, Renewable Energy Providers, Data Centers Application: Voltage Regulation, Load Management, Equipment Protection, Grid Optimization |
| Companies Covered | Eaton Corporation PLC, Hitachi Energy Ltd., ABB Ltd., S&C Electric Company, Schweitzer Engineering Laboratories Inc., Schneider Electric SE, General Electric Company, Emerson Electric Co., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission and Distribution Fault Detection Market Emerging Trajectories
Artificial intelligence inference at the substation edge is displacing centralized SCADA-based fault classification. This architectural shift is compressing decision latency and enabling autonomous sectionalizing without control center intervention.
Optical fiber current sensors using Faraday effect measurement are electrifying protection system architectures. European ultra-high-voltage transmission operators in France and the UK are deploying these devices at 400kV substations to eliminate magnetic saturation errors. The technology is compressing substation footprint requirements and enabling double-circuit line protection with single-sensor redundancy.
The EU F-Gas Regulation's 2030 phase-down targets for sulfur hexafluoride are mandating alternative insulation media in switchgear-integrated fault interrupters. German and Italian manufacturers are accelerating vacuum interrupter and dry-air insulation development to maintain grid access qualification. Medium-voltage distribution segments in Northern Europe are witnessing the fastest product category transition as utilities front-load SF6 replacement programs.
Subscription-based hardware-as-a-service contracts are displacing capital purchase models for distribution fault detection systems. US municipal utilities and cooperative networks are adopting these arrangements to transfer obsolescence risk to vendors. The Southwest and Mountain West regions show highest penetration where rural system operators lack in-house protection engineering capacity.
Transmission and Distribution Fault Detection Market Segmentation
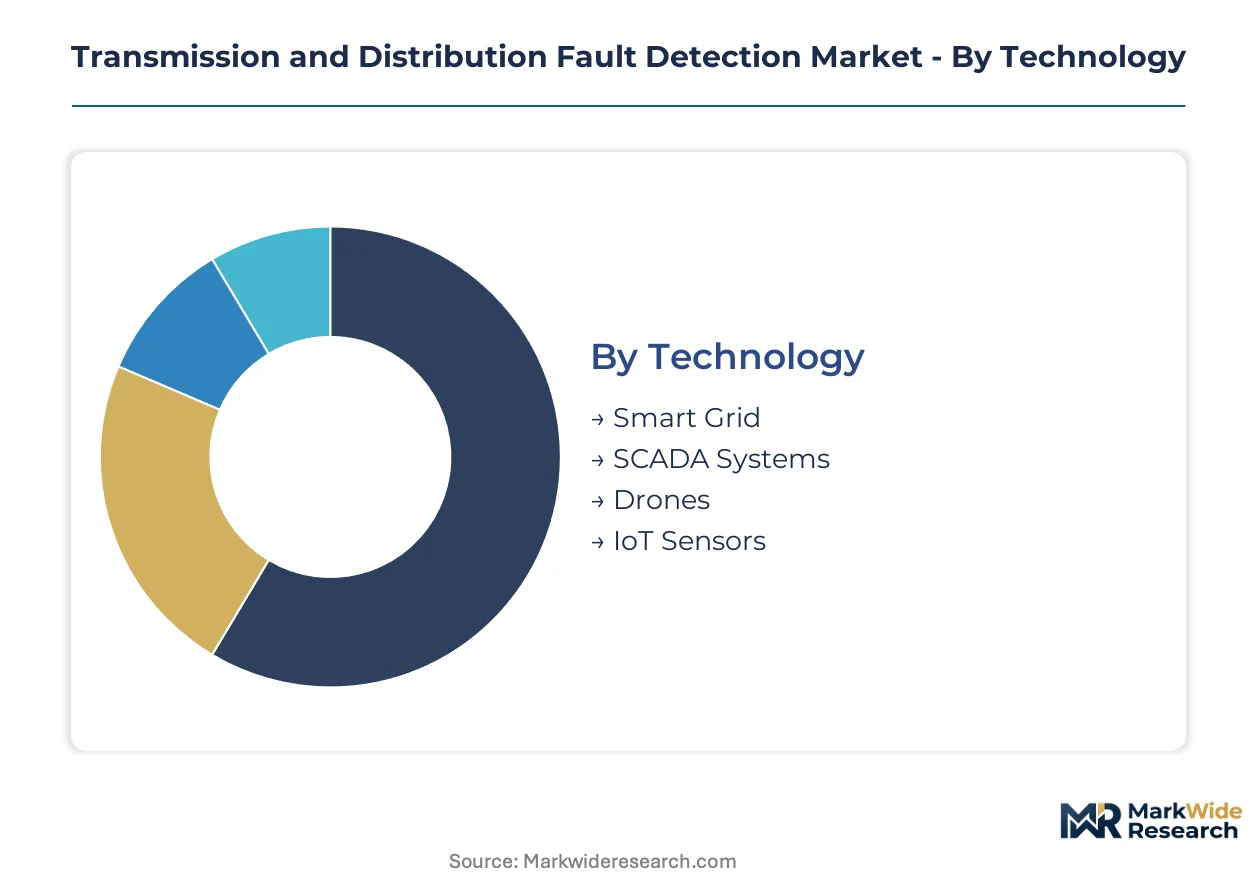
Technology and product architecture choices in fault detection determine response latency, interoperability compliance, and total cost of ownership across utility procurement cycles. Segmentation reveals where capital concentrates versus where subscription and edge-computing models are displacing traditional hardware sales.
Technology:
Standardization pressure from IEC 61850 digital substation protocols is compressing customization margins across this category, though edge-AI implementations retain project-specific engineering requirements.
- Smart Grid:Two-way communication infrastructure enabling real-time sectionalizing and automated feeder reconfiguration. Demand concentrates in United States municipal utilities modernizing aging distribution networks under FERC Order 2222 compliance timelines.
- SCADA Systems:Centralized supervisory platforms with millisecond-grade polling intervals for fault event logging. German and French transmission operators anchor procurement as they integrate renewable interconnection zones requiring synchronized phasor visibility.
- Drones:Aerial thermal inspection platforms for transmission corridor monitoring. Chinese state grid corporations deploy these for ultra-high-voltage line maintenance across remote western provinces.
- IoT Sensors:Distributed edge devices with embedded inference capability. Australian distribution networks are piloting these for bushfire-risk line rating in Victoria and New South Wales.
Most installed capacity flows through SCADA Systems. Expansion is steepest in IoT Sensors.
Product Type:
Cost tier stratification separates capital-intensive primary protection from software-layer analytics tools with recurring revenue profiles.
- Line Monitoring Devices:Distributed sensor arrays measuring conductor temperature, sag, and ice loading. Nordic utilities prioritize these for dynamic line rating in subarctic conditions.
- Fault Locator Systems:Traveling-wave and impedance-based algorithms pinpointing disturbance coordinates. Brazilian grid operators deploy these across Amazon basin transmission corridors where helicopter patrol access is limited.
- Protection Relays:Microprocessor-based tripping mechanisms with sub-cycle operating times. Japanese manufacturers dominate silicon carbide-integrated designs for medium-voltage feeder protection.
- Asset Management Tools:Predictive analytics platforms aggregating transformer dissolved gas analysis and partial discharge data. United States investor-owned utilities bundle these with digital twin initiatives in Texas and California.
Protection Relays carry the largest installed base. Asset Management Tools are climbing the fastest.
End User:
Customer type determines procurement modality—capital purchase versus performance contracting versus subscription hardware-as-a-service.
- Utilities:Vertically integrated and distribution-only grid operators with regulated rate-base treatment. Spanish and Italian transmission system operators are consolidating protection system procurement under framework agreements.
- Industrial Plants:Oil refineries, chemical complexes, and mining operations with captive medium-voltage infrastructure. Saudi Aramco and similar operators specify IEC 61850-compliant relays for process continuity.
- Renewable Energy Providers:Wind and solar developers requiring fault ride-through and anti-islanding protection. Indian solar parks under the country's renewable energy targets are mandating smart inverter-integrated detection.
- Data Centers:Hyperscale facilities with dual-feed substations demanding seamless transfer switching. Northern Virginia and Frankfurt clusters are specifying predictive arc-flash detection for uptime guarantees.
Utilities account for the dominant share of deployed systems. Data Centers are gaining share fastest.
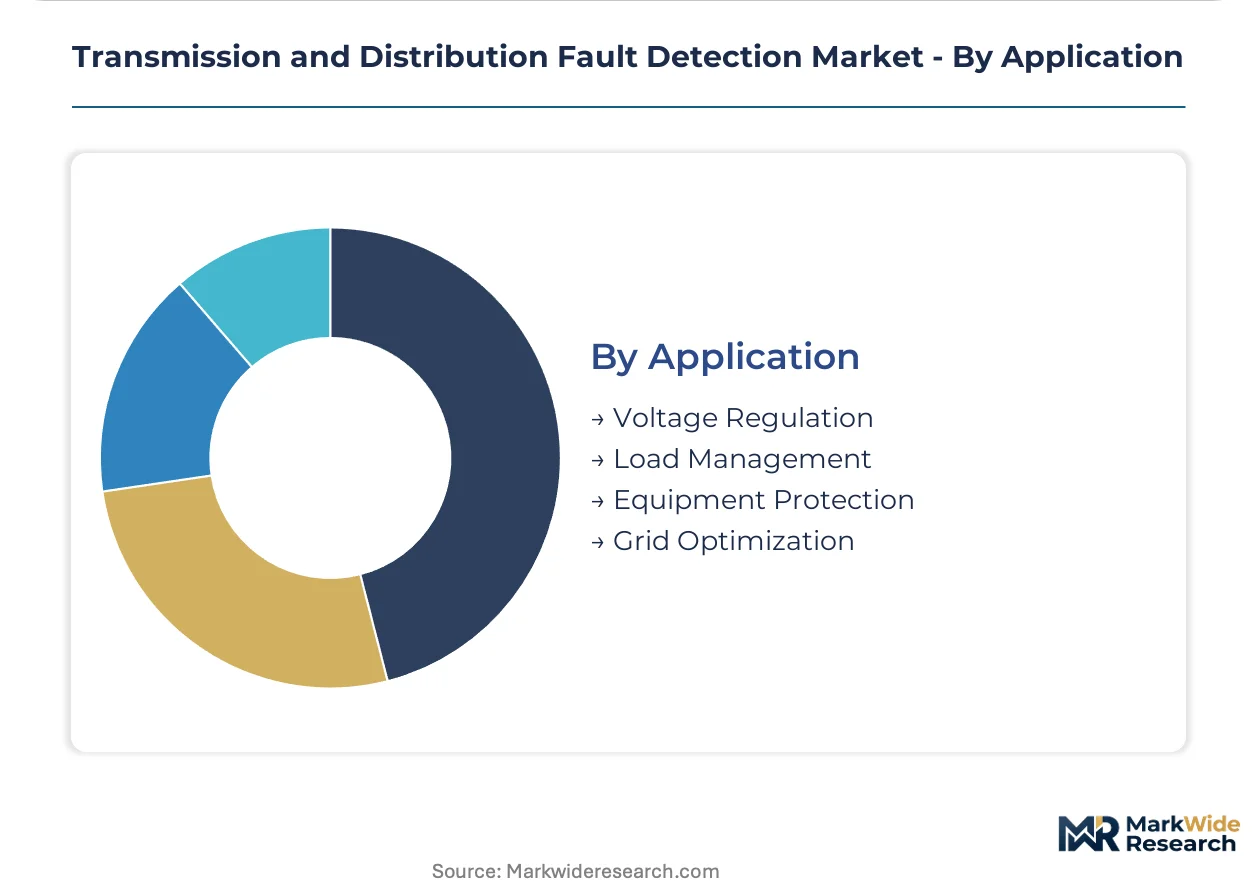
Application:
Functional priority varies by grid development stage—emerging markets emphasize voltage stability while mature networks optimize for renewable integration.
- Voltage Regulation:Tap changer control and reactive power compensation for flicker mitigation. United Kingdom distribution network operators deploy these for electric vehicle load growth in suburban London corridors.
- Load Management:Demand response signaling and peak shaving coordination. South Korean utilities integrate these functions with their advanced metering infrastructure rollout.
- Equipment Protection:Transformer differential protection and busbar zone coverage. South African Eskom prioritizes these for aging coal-fired generation step-up transformers.
- Grid Optimization:Power flow reconfiguration and loss minimization algorithms. Denmark's Energinet uses these for wind-dominated balancing area management.
Equipment Protection represents the most mature deployment base. Grid Optimization shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission and distribution fault detection technology first achieved commercial scale in Germany during the 1990s with the deployment of digital protection relays across the newly unified grid. The industry subsequently expanded through Nordic digital substation programs and US smart grid stimulus funding. Today, procurement concentrates in markets with aging infrastructure and renewable integration mandates.
United States
FERC Order 2222 drives synchronized phasor measurement unit deployment across Texas and California interconnection zones. The IRA's grid modernization tax credits accelerate municipal utility procurement timelines. Northern Virginia data center clusters specify predictive arc-flash detection for uptime guarantees in dual-feed substations.
Germany
The EU F-Gas Regulation's SF6 phase-down mandates vacuum interrupter adoption across medium-voltage distribution networks. E.ON and TenneT framework agreements consolidate protection system procurement under IEC 61850 Edition 2.1 compliance requirements. Bavarian manufacturers anchor dry-air insulation development for Nordic grid access qualification.
China
State Grid Corporation deploys drone-based thermal inspection across ultra-high-voltage corridors in remote western provinces. MIIT standards for smart substation communication protocols shape domestic vendor qualification criteria. Yangtze River Delta utilities pilot AI-edge fault classification in metropolitan distribution networks.
India
The country's distribution utility reform program mandates smart meter-integrated fault passage indicators for rural electrification saturation. CEA technical standards require IEC 62056-21 compliance for state-level tender access. Gujarat and Maharashtra solar parks mandate smart inverter-integrated detection under renewable energy targets.
Australia
Bushfire-risk line rating pilots in Victoria and New South Wales drive IoT sensor deployment across distribution networks. The country's energy market operator requires dynamic line rating systems with embedded fault location for wind interconnection queues. Queensland utilities bundle these sensors with transformer monitoring platforms.
Transmission and Distribution Fault Detection Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fault detection landscape, with integrated hardware-software vendors holding distinct advantages in digital substation tenders. The market structure tilts toward consolidation among relay manufacturers with century-long utility relationships, while sensor specialists fragment across application niches. Three archetypes dominate: diversified industrial conglomerates with grid automation portfolios, pure-play protection relay specialists, and emerging IoT-native sensor platforms. Strategic moves center on silicon carbide power electronics integration and subscription-based hardware-as-a-service contract structures.
Among diversified industrial conglomerates, Eaton Corporation PLC and Hitachi Energy Ltd. exemplify the integrated automation portfolio archetype, anchoring positions through digital substation and SCADA-to-protection-relay architectures. Schweitzer Engineering Laboratories Inc. occupies a distinct tier as a protection relay specialist with concentrated presence in North American utility procurement. These three represent the competitive spectrum from broad grid automation to focused protection engineering.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Hitachi Energy Ltd. |
| ABB Ltd. |
| S&C Electric Company |
| Schweitzer Engineering Laboratories Inc. |
| Schneider Electric SE |
| General Electric Company |
| Emerson Electric Co. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Chilean copper concentrate benchmarks cascade through protection relay manufacturing into three distinct procurement tiers: silicon carbide-integrated premium systems for high-voltage transmission, standard IEC 61850-compliant relays for distribution utilities, and economy-grade electromagnetic units for rural electrification programs in emerging markets. Wide-bandgap semiconductor costs and rare earth magnet pricing from Chinese neodymium processing compress hardware margins unevenly across these tiers, forcing vendors to bundle subscription-based firmware updates and predictive analytics to defend value capture.
Pricing Analysis
Subscription hardware-as-a-service contracts now anchor utility procurement, separating premium edge-AI platforms with autonomous sectionalizing capability from standard SCADA-integrated protection and economy-grade fault passage indicators. Price differentiation rests on IEC 61850 Edition 2.1 certification tier and embedded cybersecurity protocol implementation. Pricing pressure stems from copper and rare earth cost volatility in relay actuator mechanisms. Municipal utilities in the United States exhibit highest price sensitivity, while data center operators in Northern Virginia and Frankfurt tolerate premium tiers for uptime guarantees.
Supply Chain Analysis
Refurbishment flows for legacy electromechanical relays create secondary supply channels that compete with new equipment in price-sensitive segments. Manufacturing concentrates in Germany, Japan, and China for silicon carbide power electronics and precision relay assemblies. Supply chains draw from Chilean copper concentrate, Chinese rare earth processing, and German real-time operating system licensing. Single-source vulnerability in embedded firmware from US and German software houses poses structural risk. Distribution runs through direct utility framework agreements and EPC contractor bundling for greenfield substation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fault detection hinges on silicon carbide cost curves flattening and utilities migrating toward predictive analytics subscriptions that capture recurring revenue beyond hardware replacement cycles.
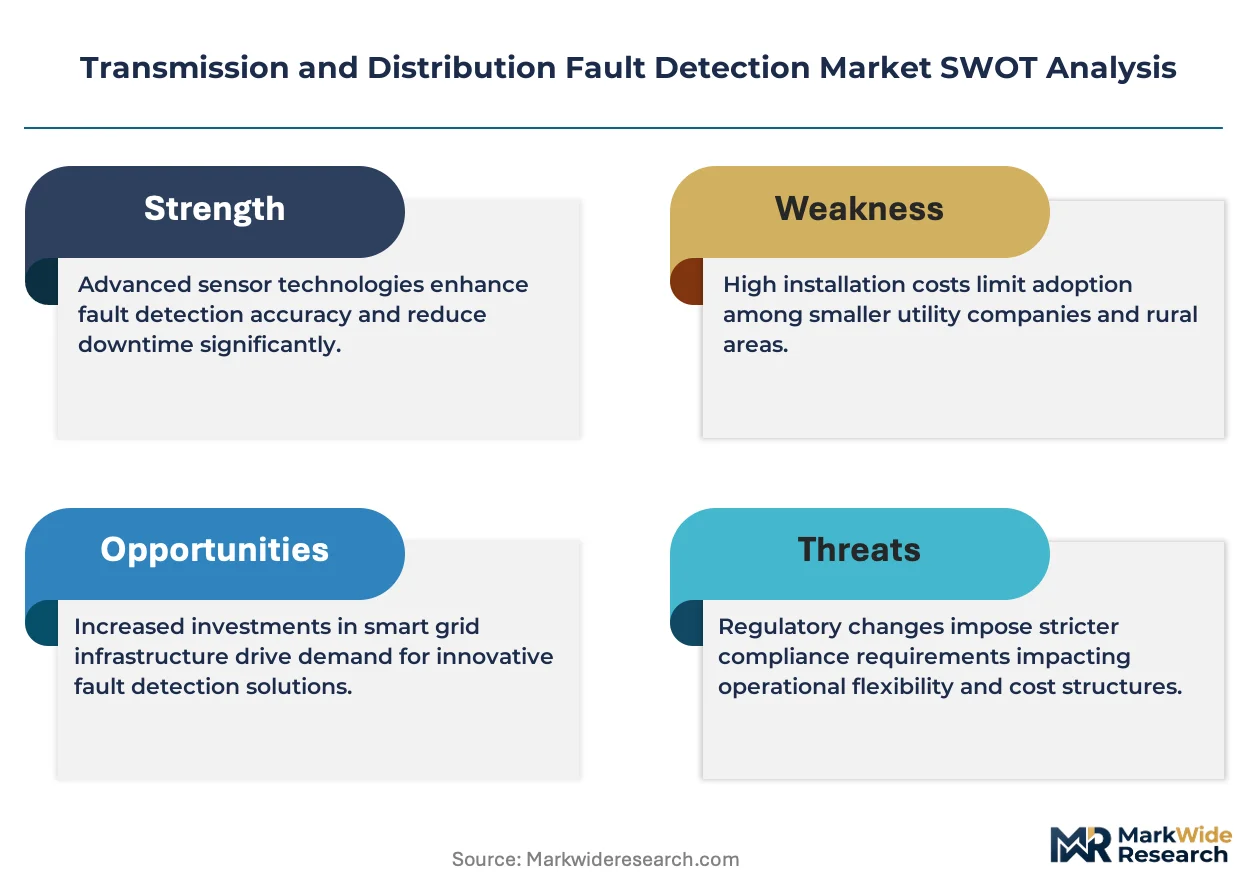
For Market Incumbents: Deepen backward integration into silicon carbide wafer supply to secure wide-bandgap semiconductor cost positions against Japanese and German competitors. Consolidate protection engineering talent pools through specialized training pipelines that address workforce aging in OECD utilities. Defend against IoT-native sensor platforms by embedding edge-AI inference directly into digital substation architectures. For New Entrants and Emerging Players: Rural electric cooperatives in the United States Southwest and Mountain West represent underserved buyer archetypes lacking in-house protection engineering capacity. India's state-level distribution utility reform tenders offer accessible procurement pipelines for IEC 62056-21 compliant fault passage indicators. Partner with transformer monitoring platform vendors to bundle detection sensors and bypass direct competition with established relay manufacturers. For Investors and Strategic Acquirers: Asymmetric upside sits with IoT-native sensor platforms possessing edge-computing firmware and hardware-as-a-service contract structures. Long-term viability favors vendors with demonstrated FERC Order 2222 compliance and EU F-Gas Regulation qualification for SF6-free switchgear integration. Watch for silicon carbide cost parity inflection that displaces legacy IGBT-based protection architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Integration | Wide-bandgap semiconductors enable sub-cycle fault interruption that disqualifies legacy relay vendors from premium tenders. |
| Digital Substation Certification | IEC 61850 Edition 2.1 compliance determines vendor eligibility in E.ON and TenneT framework agreements. |
| SF6-Free Switchgear Development | Vacuum interrupter and dry-air insulation technology secures preferential status under EU F-Gas Regulation phase-down mandates. |
| Edge-AI Firmware Deployment | Substation inference capability compresses response windows below 50 milliseconds without control center intervention. |
| Hardware-as-a-Service Contracts | Subscription models transfer obsolescence risk to vendors and penetrate rural cooperative utilities lacking capital budgets. |
Methodological Framework
Multiple input streams — utility protection engineering directors, substation automation procurement officers, EPC contractor project managers, and power system consultants — were reconciled against FERC filings, IEC standards documentation, and EU regulatory databases. Secondary validation drew from transmission operator annual reports, smart grid stimulus disbursement records, and silicon carbide supply chain disclosures. Bottom-up equipment shipment tallies and top-down grid modernization budget allocations were triangulated to anchor market sizing.
Historical deployment trajectories in Germany, the United States, and China were cross-referenced against panel input from grid operators on renewable integration timelines across the analysis window. Segmentation modeling incorporated technology architecture, product type cost tier, end-user procurement modality, and application functional priority. CAGRs were derived from utility capital expenditure forecasts and equipment replacement cycle analysis, with specific weighting for FERC Order 2222 compliance deadlines and EU F-Gas Regulation phase-down schedules.
Inputs from utility procurement databases and relay manufacturer order backlogs were available through the study window; gaps in real-time pricing data for silicon carbide substrates and rare earth magnet contracts introduce uncertainty bands around hardware margin projections. Forecasts reflect assumptions regarding IEC 61850 migration timelines and copper price stability. Periodic stress-testing of base assumptions against commodity index movements and regulatory revision schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Middle East Pipeline Maintenance Market