
 Malaysia Renewable Energy Market | 2026-2036
Malaysia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Renewable Energy Market Outlook
Multi-source equipment procurement is realigning how Malaysian solar developers manage supply risk and capital efficiency. Gentari Sdn Bhd leverages its Petronas-backed balance sheet to finance utility-scale photovoltaic plants across the peninsula. Tenaga Nasional Berhad anchors grid integration through its renewable energy subsidiary and transmission infrastructure control. Solarvest Holdings Berhad specializes in commercial and industrial rooftop engineering, procurement, and construction services.
Malaysia renewable energy encompasses electricity generation from solar photovoltaic, wind turbine, biomass combustion, and run-of-river hydropower systems with typical solar installations ranging from kilowatt-scale rooftops to 50-megawatt utility arrays feeding 33kV distribution networks. Solar technology dominates new capacity additions due to module cost declines and high irradiance levels exceeding 1,500 kilowatt-hours per square meter annually. Grid-tied generation type leads installation volume by connecting directly to TNB's distribution infrastructure, while distributed systems are gaining traction among industrial estates seeking energy cost hedging. Floating installation type remains nascent but attracts pilot funding for reservoirs and water treatment ponds.
The Sustainable Energy Development Authority administers feed-in tariff and net energy metering schemes that determine project revenue certainty and queue priority. BIS-equivalent standards and CEA technical guidelines shape equipment certification and grid code compliance for interconnecting generators. The Energy Commission regulates licensing under the Electricity Supply Act. Stakeholders must monitor auction pricing floors and domestic content requirements that will determine which technology suppliers retain viable project economics.
Market Dynamics
The Sustainable Energy Development Authority's auction mechanism is compressing developer margins while concentrating project pipelines in Peninsular Malaysia's high-irradiance zones. This regulatory pricing pressure is restructuring capital deployment toward vertically integrated engineering-procurement-construction capabilities.
Growth Catalysts
- Net Energy Metering 3.0:Industrial estates in Selangor and Johor are maximizing rooftop solar offsets under the revised quota allocation system.
- Biomass feedstock availability:Palm oil mill effluent and empty fruit bunches provide captive fuel sources for grid-connected cogeneration plants in Pahang and Sarawak.
- Grid parity achievement:Utility-scale photovoltaic installations now undercut gas-peaking tariffs without subsidy support.
Market Restraints
- Polysilicon supply concentration:Malaysian developers remain exposed to Xinjiang-sourced wafer pricing volatility and forced-labor scrutiny.
- Transmission interconnection queues:Tenaga Nasional Berhad's 33kV substation capacity constraints delay commercial operation dates by 8-14 months.
- Limited domestic module manufacturing:The absence of cell and wafer production forces complete reliance on imported panels from China and Vietnam.
Strategic Opportunities
- Floating solar pilots:Reservoirs at Sungai Selangor and Tasik Kenyir offer 500+ megawatts of untapped surface area for photovoltaic deployment.
- Green hydrogen offtake:Petronas-backed demand centers in Kerteh and Bintulu create anchor contracts for electrolyzer-linked renewable generation.
- Corporate power purchase agreements:Data center operators in Cyberjaya and Iskandar Malaysia are bypassing utility tariffs through direct solar contracting.
Industry Challenges
- Grid code compliance timelines:CEA technical guidelines for inverter fault-ride-through capabilities extend commissioning schedules by 4-6 months.
- Skilled installer scarcity:Bumiputera certification requirements under the Ministry of International Trade and Industry constrain qualified engineering workforce expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Renewable Energy Market |
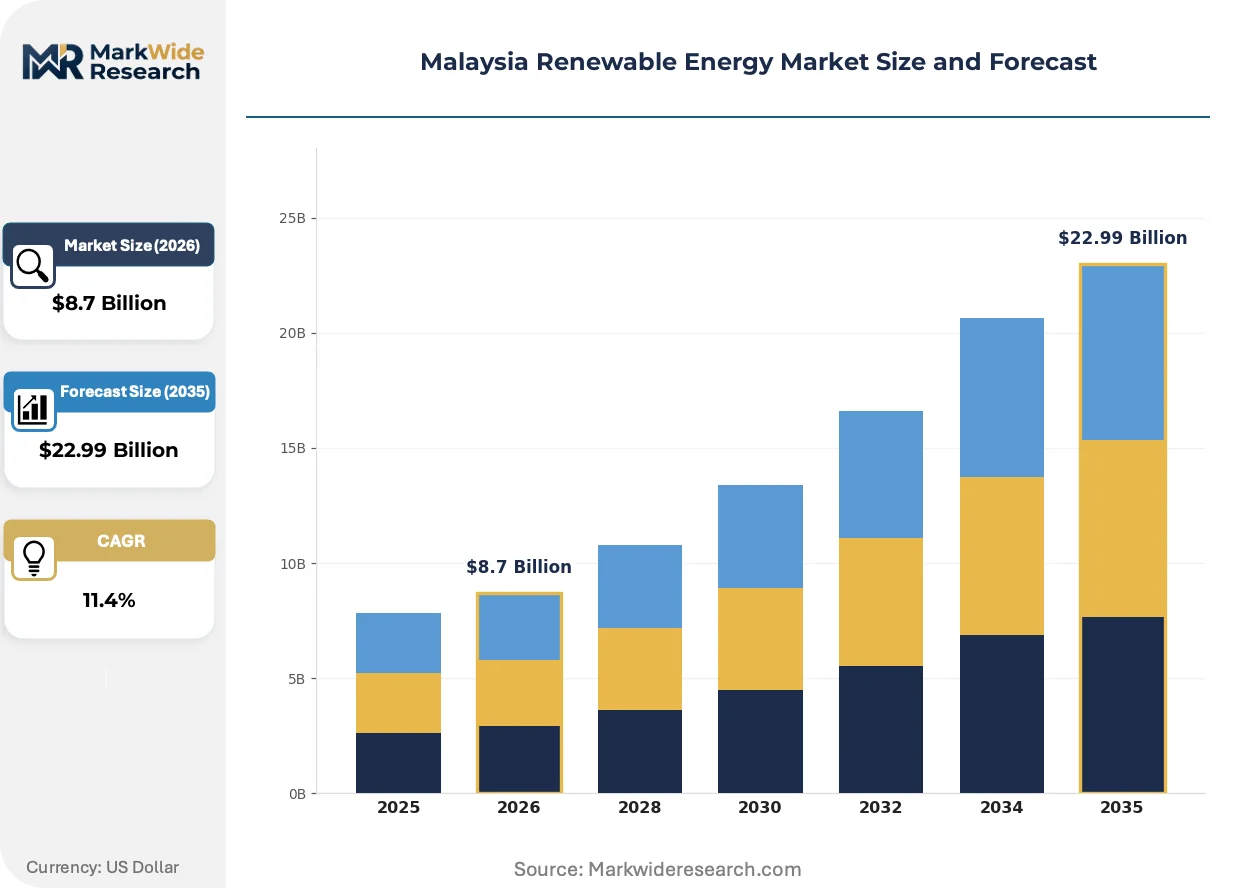
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower End User: Residential, Industrial, Commercial, Utilities Generation Type: Grid-Tied, Off-Grid, Hybrid, Distributed Installation Type: Ground-Mounted, Rooftop, Floating, Integrated |
| Companies Covered | Plus Xnergy Holding Sdn Bhd, Gentari Sdn Bhd, Tenaga Nasional Berhad (TNB), Malakoff Corporation Berhad, TotalEnergies Renewables Malaysia, Sarawak Energy Berhad, Cypark Resources Berhad, Trina Solar Co. Ltd, Solarvest Holdings Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Renewable Energy Market Strategic Shifts
Module efficiency gains and balance-of-system cost compression are enabling new installation geometries previously uneconomical at Malaysian irradiance levels. Developers are pivoting from standardized ground-mount designs toward site-adaptive configurations.
Passivated emitter and rear contact cell architecture is consolidating market share among utility-scale developers seeking higher energy yield per hectare. Large-solar auction winners in Perak and Kedah specify bifacial glass-glass modules with tracking systems. This technology stack is compressing levelized cost thresholds below conventional fixed-tilt monocrystalline alternatives.
The Energy Commission's embedded generation license reforms are accelerating industrial self-consumption models. Manufacturers in Shah Alam and Pasir Gudang are securing private wire arrangements that bypass distribution tariff components. Peninsular Malaysia's commercial and industrial segment is responding by consolidating energy management functions under dedicated procurement teams.
Long-term solar leasing is displacing upfront capital purchase among small and medium enterprises. Engineering firms in Penang and Ipoh are offering zero-downpower purchase structures with 15-20 year tenors. This financing innovation is most visible among precision manufacturing clusters seeking operating-expense treatment for energy assets.
Malaysia Renewable Energy Market Segmentation
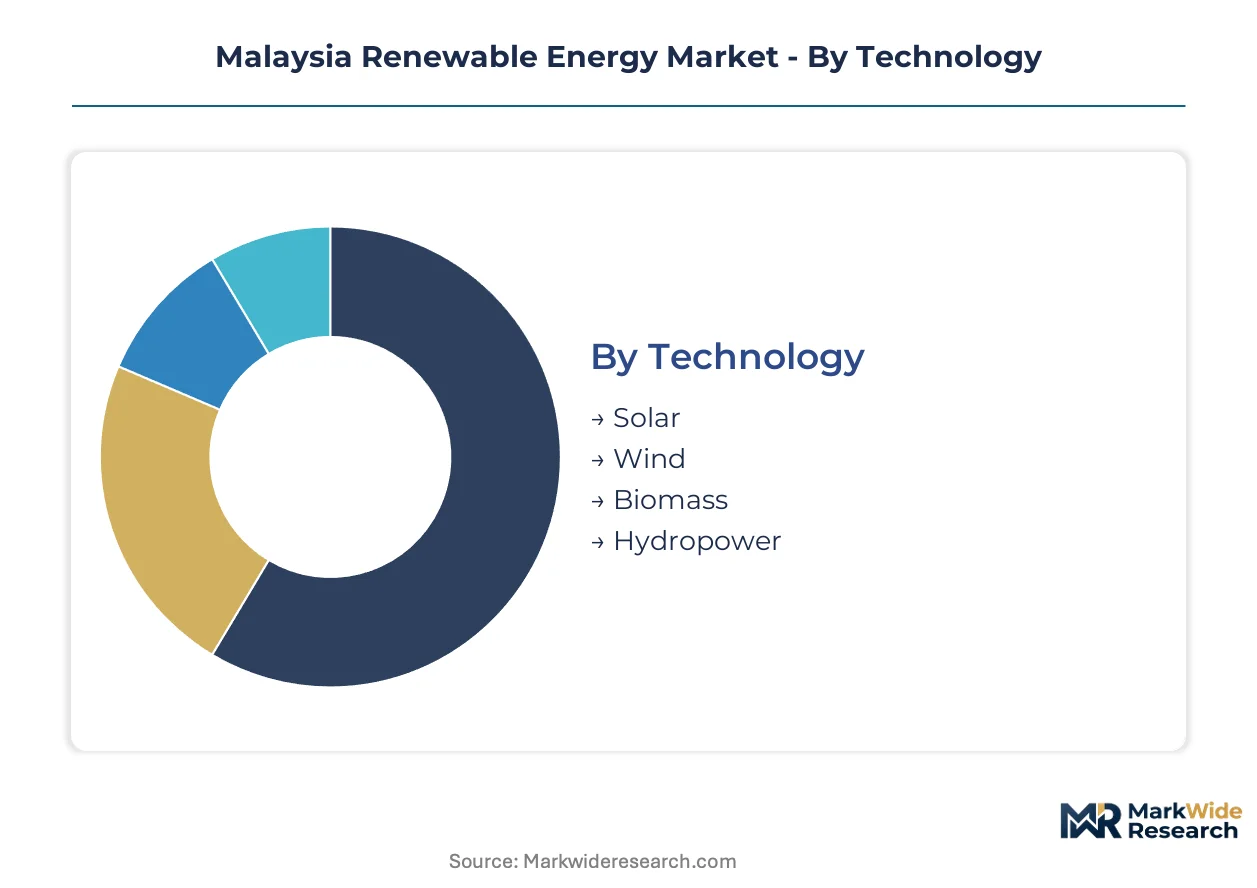
Technology and installation type choices in Malaysia's renewable energy sector determine capital efficiency, grid access pathways, and regulatory compliance requirements. Segment-specific supply chains channel equipment procurement toward distinct supplier bases across Chinese module manufacturers, European inverter specialists, and regional engineering contractors.
Technology:
Module and turbine supply concentrates in Chinese manufacturing clusters, exposing Malaysian developers to shipping cost volatility and forced-labor due diligence requirements.
- Solar:Photovoltaic systems deploy monocrystalline PERC and bifacial glass-glass modules across utility-scale auctions and commercial rooftop programs. Industrial estates in Selangor and Johor dominate procurement volumes under Net Energy Metering 3.0 quota allocations.
- Biomass:Cogeneration plants combust palm oil mill effluent and empty fruit bunches from Pahang and Sarawak processing facilities. Captive feedstock availability insulates project economics from fuel price volatility affecting grid-connected generators.
- Wind:Small-scale turbine installations concentrate in exposed coastal ridges and island territories with consistent monsoon patterns. Limited resource assessment data constrains project finance availability outside demonstration sites.
- Hydropower:Run-of-river schemes exploit Peninsular Malaysia's steep terrain gradients without reservoir construction. Sungai Perak and Sungai Pahang tributaries host the majority of operational capacity.
Solar absorbs the bulk of installed capacity; biomass is expanding most quickly among palm oil integrated producers seeking waste-to-energy valorization.
End User:
Customer type determines tariff structure exposure, with industrial offtakers capturing the steepest savings against regulated electricity rates.
- Industrial:Manufacturing facilities in Shah Alam and Pasir Gudang deploy rooftop solar and private wire arrangements to bypass distribution tariff components. Energy cost hedging motives dominate procurement decisions amid volatile natural gas-linked grid pricing.
- Utilities:Tenaga Nasional Berhad and Gentari Sdn Bhd develop utility-scale solar auctions and grid integration infrastructure. Large-scale solar program winners in Perak and Kedah supply bulk generation under 21-year power purchase agreements.
- Commercial:Retail and office buildings in Kuala Lumpur and Penang pursue solar leasing structures with zero-downpower purchase arrangements. Operating-expense treatment for energy assets appeals to small and medium enterprise balance sheet constraints.
- Residential:Single-family homes participate in net energy metering with kilowatt-scale rooftop installations. Quota limitations and lengthy interconnection queues suppress segment growth relative to commercial-industrial counterparts.
Industrial offtakers command the deepest tariff arbitrage; utilities anchor volume through auction mechanisms.
Generation Type:
Grid connection architecture shapes project revenue certainty and technical compliance burden under CEA technical guidelines.
- Grid-Tied:Direct interconnection to TNB's 33kV distribution network dominates utility-scale and commercial installations. Fault-ride-through capability requirements extend commissioning schedules by 4-6 months for inverter certification.
- Distributed:Behind-the-meter generation serves industrial estates seeking energy independence from centralized supply. Embedded generation license reforms accelerate private wire deployment across manufacturing clusters.
- Hybrid:Battery-coupled solar systems address grid instability and peak shaving requirements for critical facilities. Data center operators in Cyberjaya pilot lithium-ion integration with photovoltaic arrays.
- Off-Grid:Standalone systems serve remote communities in Sabah and Sarawak beyond TNB's transmission reach. Diesel displacement economics drive rural electrification programs with solar-diesel hybrid configurations.
Grid-tied generation claims the dominant share; distributed systems climb the fastest as industrial self-consumption accelerates.
Installation Type:
Site geometry selection responds to land availability constraints and water surface access across Peninsular Malaysia's varied topography.
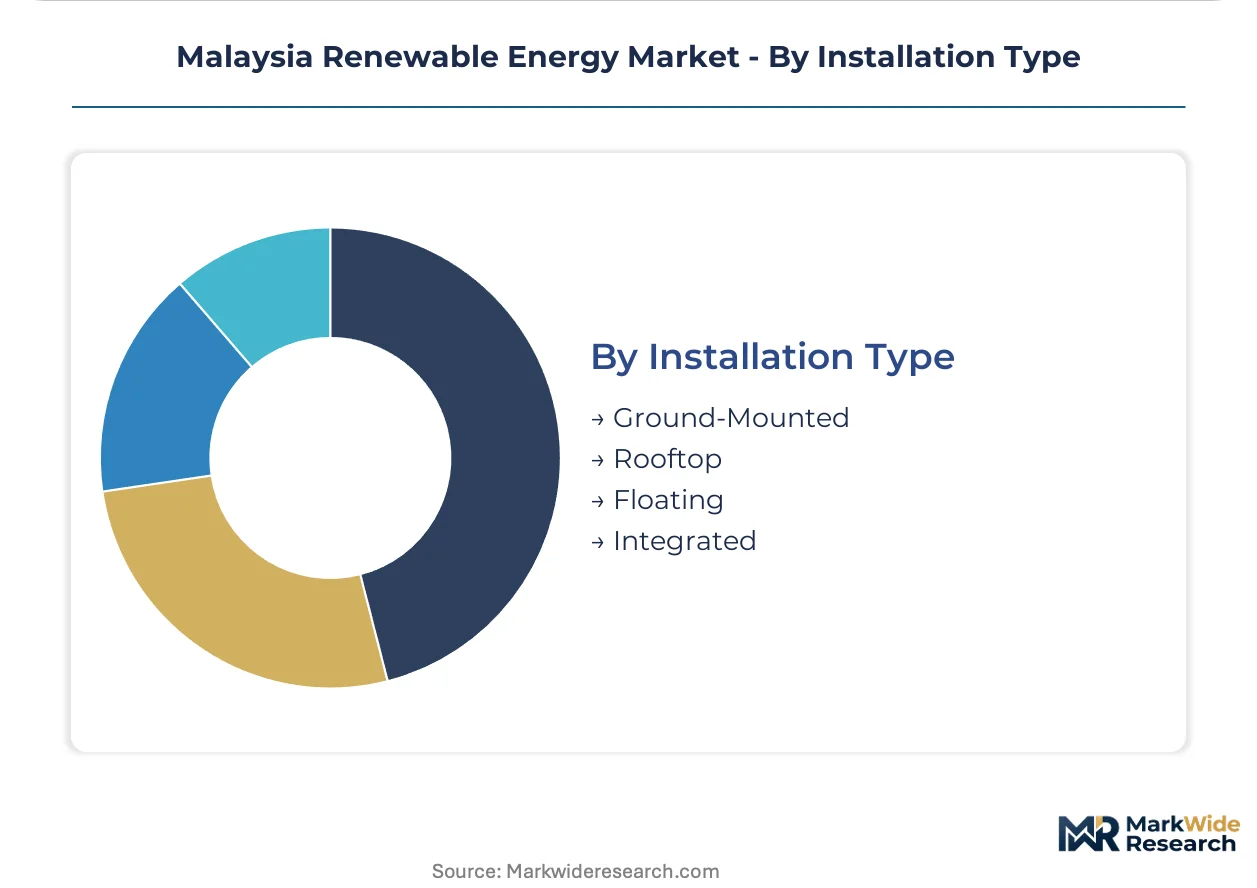
- Ground-Mounted:Fixed-tilt and tracking arrays occupy agricultural land and former mining sites in Perak and Kedah. Large-solar auction specifications increasingly mandate bifacial modules with single-axis tracking systems.
- Rooftop:Commercial and industrial building-integrated systems maximize existing structural footprints without land acquisition. Selangor's warehouse and factory stock provides the densest addressable surface area.
- Floating:Reservoir-mounted photovoltaic pilots target Sungai Selangor and Tasik Kenyir water bodies. Reduced evaporation and improved module cooling efficiency offset higher anchoring and cabling capital costs.
- Integrated:Building-integrated photovoltaics and agrivoltaic configurations merge generation with structural or agricultural functions. Limited domestic engineering expertise constrains deployment scale.
Ground-mounted arrays absorb prevailing capacity additions; floating installations gain share fastest from pilot-to-commercial scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial energy demand concentrates in Peninsular Malaysia's manufacturing corridors, where Selangor and Johor anchor procurement volumes under federal renewable programs. State-level irradiance variation and transmission infrastructure density determine project economics across the federation.
Selangor
Petrochemical complexes and electronics manufacturing in Shah Alam and Klang drive rooftop solar deployment under Net Energy Metering 3.0 quotas. The Sustainable Energy Development Authority prioritizes interconnection approvals for industrial estates in this corridor. Cyberjaya data centers are piloting corporate power purchase agreements with direct solar contracting.
Johor
Pasir Gudang's chemical processing and semiconductor packaging facilities pursue embedded generation licenses to bypass distribution tariff components. The Iskandar Malaysia special economic zone attracts foreign direct investment with renewable energy incentives. Port-linked manufacturing clusters are securing private wire arrangements for cost hedging.
Perak
Former tin mining sites and agricultural land host utility-scale solar auction winners with bifacial tracking systems. The Sungai Perak tributary system supports run-of-river hydropower integration with photovoltaic generation. Kedah-border project pipelines benefit from high irradiance and available transmission capacity.
Sarawak
Palm oil mill effluent and empty fruit bunches from Pahang-border processing facilities feed biomass cogeneration plants. The Sarawak Corridor of Renewable Energy framework channels capital toward hydropower and emerging solar-biomass hybrid configurations. Bintulu's liquefied natural gas complex creates anchor demand for green hydrogen offtake trials.
Penang
Precision manufacturing clusters in Bayan Lepas and Batu Kawan consolidate energy procurement under dedicated management teams. Long-term solar leasing structures with zero-downpower purchase arrangements penetrate small and medium enterprise segments. The state's limited land availability accelerates rooftop and floating installation pilots.
Malaysia Renewable Energy Market Competitive Environment
Capacity expansion dominates the current landscape as developers consolidate engineering-procurement-construction capabilities under vertically integrated structures. The market exhibits tiered concentration with national oil company subsidiaries and state utilities controlling utility-scale pipelines, while specialized engineering firms capture commercial and industrial rooftop volumes. Three archetypes define competitive positioning: balance-sheet-backed developers, grid infrastructure incumbents, and engineering specialists. Strategic differentiation runs through auction participation scale and net energy metering quota capture.
Among Petronas-linked developers, Gentari Sdn Bhd occupies the utility-scale financing tier with peninsula-wide project pipelines. State utility Tenaga Nasional Berhad anchors grid integration through its renewable energy subsidiary and transmission control infrastructure. Engineering specialists Solarvest Holdings Berhad and Cypark Resources Berhad exemplify the commercial-industrial rooftop and environmental engineering archetypes respectively, with Solarvest concentrating on engineering-procurement-construction services and Cypark integrating waste management with energy generation.
| Leading Market Players |
|---|
| Plus Xnergy Holding Sdn Bhd |
| Gentari Sdn Bhd |
| Tenaga Nasional Berhad (TNB) |
| Malakoff Corporation Berhad |
| TotalEnergies Renewables Malaysia |
| Sarawak Energy Berhad |
| Cypark Resources Berhad |
| Trina Solar Co. Ltd |
| Solarvest Holdings Berhad |
| Others |
Value Chain & Pricing Dynamics
The Sustainable Energy Development Authority's domestic content requirements gate qualified supply access and premium-tier pricing for engineering-procurement-construction contractors serving Malaysia's utility-scale solar auctions. Developers lacking Bumiputera-certified installation partnerships face exclusion from Net Energy Metering 3.0 quota allocations, compressing margins for foreign-technology-dependent bidders while concentrating pricing power among vertically integrated local consortia.
Pricing Analysis
Volume-vs-margin splits bifurcate sharply between auction-tariffed utility projects and commercial-industrial rooftop segments. Three-tier pricing structure across premium engineering-procurement-construction, standard balance-of-system procurement, and economy module-only supply governs developer procurement decisions. Cost compression in utility-scale fixed-tilt installations is intensifying because Large Scale Solar auction winners must absorb transmission interconnection delays of 8-14 months without tariff escalation. Industrial estates in Selangor and Johor exhibit lowest price sensitivity due to energy cost hedging motives against volatile natural gas-linked grid tariffs, while small and medium enterprises in Penang and Ipoh face acute capital constraints driving zero-downpower purchase arrangement uptake.
Supply Chain Analysis
Dual-sourcing requirements from Tenaga Nasional Berhad and Gentari Sdn Bhd mandate multi-supplier qualification for inverter and module procurement, yet Malaysian developers remain tethered to concentrated Chinese polysilicon and Vietnamese cell manufacturing. Raw material dependencies center on Xinjiang-sourced wafer supply, Jiangsu province module assembly, and European inverter power electronics. Single-source vulnerability in polysilicon refining exposes project economics to forced-labor scrutiny and shipping cost volatility. Distribution runs through Port Klang container terminals for equipment import, with Sungai Buloh and Pasir Gudang emerging as balance-of-system staging hubs for Peninsular Malaysia project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's renewable energy market reads as supply-constrained: Tenaga Nasional Berhad's 33kV substation capacity bottlenecks prop pricing power for developers holding secured interconnection queues. Capacity scarcity in grid infrastructure anchors returns for early-movers.
For Market Incumbents: Anchor auction pipeline dominance by securing embedded generation license pre-approvals ahead of Net Energy Metering 4.0 quota releases. Consolidate Bumiputera-certified installation workforce through targeted acquisition of Shah Alam and Johor-based engineering contractors, defending against emerging Chinese module manufacturers integrating downstream into engineering-procurement-construction services. Prioritize backward integration into balance-of-system procurement to offset polysilicon price volatility exposure. For New Entrants and Emerging Players: Engineering-procurement-construction subcontractors represent the most penetrable channel partner type for bypassing incumbent auction blockades. Target floating solar pilot opportunities at Sungai Selangor and Tasik Kenyir reservoirs, where 500+ megawatts of untapped surface area lacks established developer relationships. Pursue corporate power purchase agreement origination with Cyberjaya data center operators as a direct-contracting go-to-market angle circumventing utility-tariffed intermediation. For Investors and Strategic Acquirers: Grid code compliance timeline extensions beyond 4-6 months are the leading indicator that CEA technical guideline stringency is tightening project finance availability. Five-to-ten year viability favors developers with captive transmission interconnection queue positions and Petronas-linked offtake relationships. Target acquisition archetypes include engineering-procurement-construction specialists with Net Energy Metering 3.0 quota allocations and Bumiputera certification credentials. Monitor Sungai Perak tributary run-of-river hydropower integration projects as inflection signals for hybrid renewable asset class expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Transmission Interconnection Queue Securement | Tenaga Nasional Berhad's 33kV substation capacity constraints reward early queue position holders with 8-14 month commercial operation date advantages. |
| Bumiputera Certification Investment | Ministry of International Trade and Industry requirements gate Net Energy Metering quota access and utility-scale auction participation eligibility. |
| Corporate Power Purchase Agreement Origination | Direct solar contracting with Cyberjaya data center operators bypasses regulated utility tariffs and captures industrial energy cost hedging demand. |
| Floating Solar Pilot Development | Sungai Selangor and Tasik Kenyir reservoir deployments unlock 500+ megawatts of surface area with reduced land acquisition friction. |
| Biomass Cogeneration Feedstock Integration | Palm oil mill effluent and empty fruit bunch captive supply in Pahang and Sarawak insulates project economics from fuel price volatility. |
Study Parameters
Multi-period observation of Sustainable Energy Development Authority auction pricing floors, Tenaga Nasional Berhad interconnection queue lengths, and Net Energy Metering quota allocation velocity anchored the trend analysis, supplemented by interviews with utility planning officers, independent power producer project developers, engineering-procurement-construction contractors, grid operators, and polysilicon supply specialists. Secondary validation drew from Energy Commission licensing databases, Electricity Supply Act regulatory filings, BIS-equivalent equipment certification records, and customs import data for photovoltaic module and inverter shipments. Bottom-up project pipeline aggregation and top-down macroeconomic scenario triangulation cross-verified capacity expansion trajectories.
Input-output matrix framing mapped generation capacity additions against grid infrastructure expansion rates, regulatory framework evolution, and technology cost curves across the analysis window. Segmentation dimensions modeled encompass technology type, installation geometry, generation architecture, end-user category, and state-level irradiance and transmission density. CAGRs derived from regression analysis of historical auction tariff trends, module price decline trajectories, and industrial electricity demand elasticity. Forecast inputs incorporated Petronas green hydrogen offtake commitment signals and CEA technical guideline revision timelines.
Caveats apply where polysilicon supply chain disruption, forced-labor due diligence enforcement, or CEA grid code compliance timeline extensions could materially shift the outlook. Deviation in Tenaga Nasional Berhad transmission interconnection queue processing rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market