
 Transformer Oil Coolers Market | 2026-2036
Transformer Oil Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Oil Coolers Market Analytics
Modular cooler-heat exchanger bundling is hardening as the dominant procurement configuration, with utilities favoring pre-assembled skids over discrete component sourcing. Kelvion leverages its European manufacturing footprint to anchor large utility contracts across Scandinavia and Central Europe. SPX Corporation competes through specialized nuclear-grade cooling systems that sustain premium positioning in regulated generation markets. Wabtec Corporation differentiates via backward integration into fan and pump subsystems, controlling critical component supply for North American rail and utility customers.
Transformer oil coolers are heat exchange devices engineered to maintain dielectric fluid temperatures within 60-80°C operational bands, typically employing aluminum or copper fin-tube constructions with forced-air or liquid-cooled circulation loops to preserve insulating oil properties and prevent thermal degradation of cellulose winding insulation. Air-cooled systems dominate installed base economics due to lower auxiliary power draw and elimination of water treatment infrastructure, while water-cooled variants capture margin pools in high-load-density urban substations where ambient air capacity proves insufficient. Data center end users represent the fastest-growing demand cluster, as hyperscale facilities integrate medium-voltage transformers with dedicated cooling loops to manage harmonic heating from rectifier loads.
EPA efficiency regulations under the Clean Air Act constrain cooler fan motor specifications and noise emissions for US utility deployments, while IEC 60076-7 thermal loading guidelines shape international product certification requirements and OEM qualification protocols. China's GB standards and India's CEA technical regulations impose additional regional testing burdens that filter non-compliant suppliers from tender participation. Stakeholders must monitor evolving F-gas restrictions in Europe and emerging state-level efficiency mandates in the US, as these frameworks will increasingly determine which cooler architectures qualify for new-build transformer projects.
Market Dynamics
Grid operators are consolidating transformer procurement around pre-integrated cooling skids, compressing vendor margins while elevating thermal performance guarantees as the decisive tender criterion. This bundling dynamic is restructuring supplier relationships across electric utility supply chains.
Growth Catalysts
- EPA Clean Air Act mandates:US utilities must replace legacy fan motors with high-efficiency models, forcing cooler refresh cycles at aging substations.
- Data center buildouts:Hyperscale facilities in Northern Virginia and Frankfurt are specifying dedicated oil cooling loops for medium-voltage transformers serving rectifier loads.
- Copper fin-tube designs:Enhanced thermal conductivity is displacing aluminum in premium utility contracts where space constraints dominate site engineering.
Market Restraints
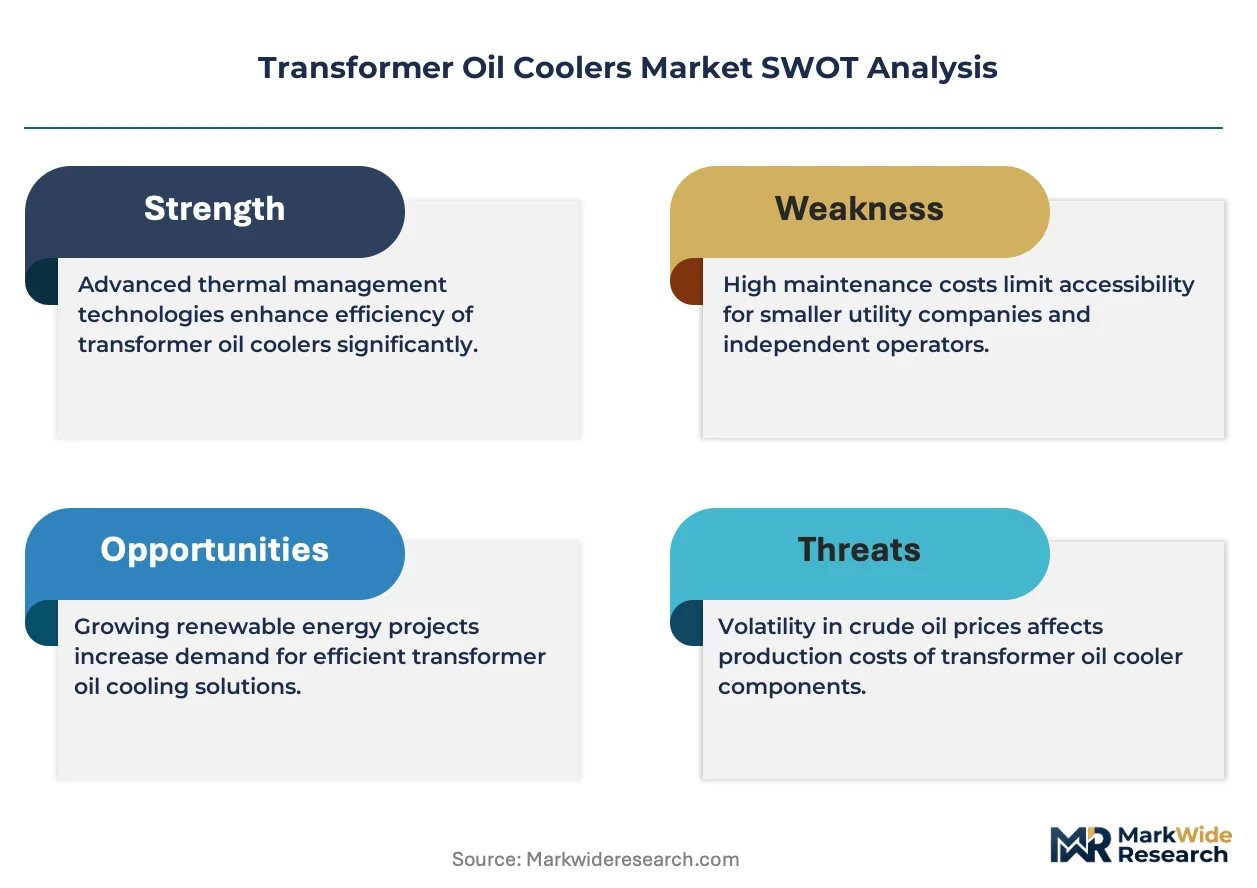
- Aluminum price volatility:Raw material swings compress margin predictability for air-cooled system manufacturers serving price-sensitive tender markets.
- European F-gas restrictions:Phasedown timelines for synthetic refrigerants constrain water-cooled variant development for urban substation retrofits.
- Water treatment infrastructure:Closed-loop liquid cooling requires chemical management systems that inflate total installed cost versus forced-air alternatives.
Strategic Opportunities
- India's CEA technical regulations:Stringent thermal testing protocols are filtering non-compliant suppliers, creating qualification headroom for certified OEMs.
- Digital twin integration:Predictive thermal modeling converges with cooler hardware to enable condition-based maintenance contracts.
- Rail electrification:Traction transformer cooling demand is accelerating across China's high-speed network expansion corridors.
Industry Challenges
- IEC 60076-7 certification timelines:Extended thermal qualification cycles delay product launches and tie up engineering resources.
- Legacy transformer integration:Retrofit cooler mounting configurations must accommodate decades-old tank geometries without structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Oil Coolers Market |
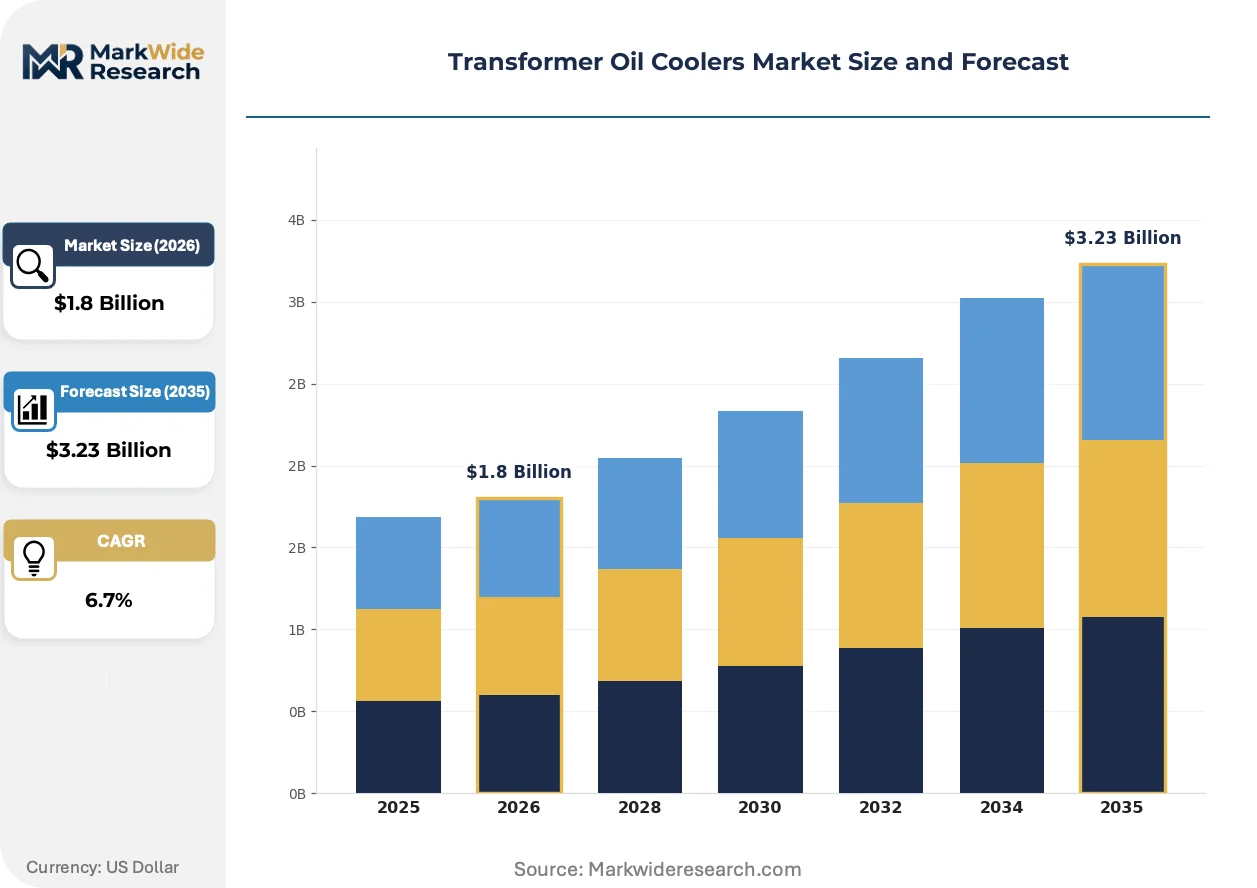
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Immersion, Portable Installation Type: Indoor, Outdoor, Modular, Skid-Mounted End User: Utilities, Manufacturing Plants, Renewable Energy, Data Centers Operational Efficiency: High Efficiency, Medium Efficiency, Low Efficiency, Custom Solutions |
| Companies Covered | Commercial Coils, Inc., Pro Dyne Corp., Kelvion, Kooltronic, Inc., Petro-Chem Industries, Wabtec Corporation, Quintel, Inc., SPX Corporation, Trantech Radiator Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Oil Coolers Market Evolving Landscape
Product architectures are compressing around intelligent thermal management systems that merge hardware with predictive analytics. This convergence is elevating software competence alongside metallurgical engineering in supplier capability matrices.
Phase-change material thermal buffers are consolidating emergency overload capacity into compact cooler footprints. European utilities are piloting these systems at urban substations where land scarcity prevents radiator bank expansion. The technology is consolidating vendor differentiation around transient thermal performance rather than steady-state ratings alone.
REACH chemical restrictions are tightening coating specifications for aluminum fin-tube surfaces exposed to coastal atmospheres. Manufacturers are reformulating corrosion protection layers to maintain IEC 60076 salt-spray certification. Scandinavian utilities operating North Sea substations are driving qualification demand for these enhanced surface treatments.
Performance-based service agreements are displacing discrete equipment sales at major US investor-owned utilities. Contractors now guarantee thermal compliance over 15-year contract terms, absorbing operational risk that previously rested with asset owners. This shift concentrates in Texas and California markets where grid stress events are accelerating cooler degradation curves.
Transformer Oil Coolers Market Segmentation
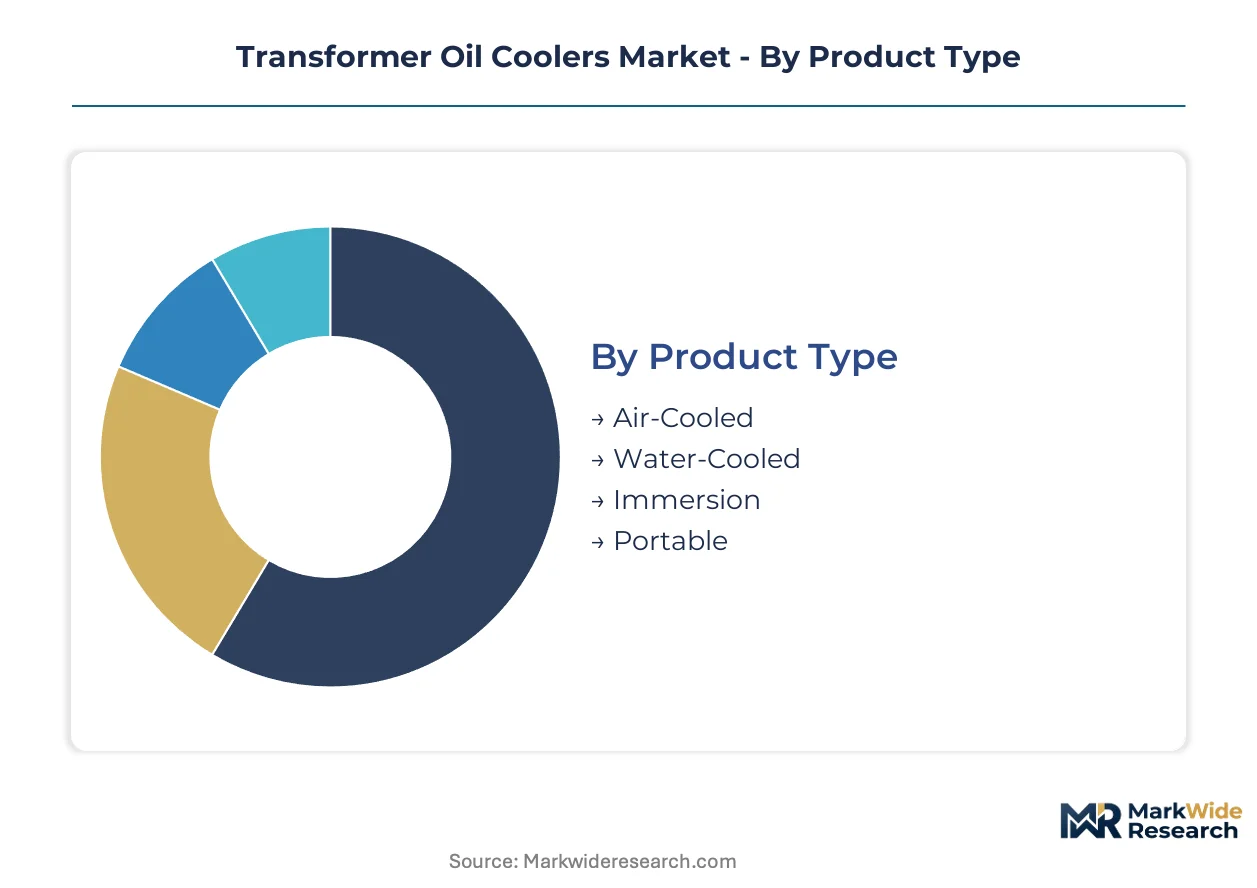
Transformer oil cooler procurement patterns diverge sharply across installation contexts and thermal load profiles. Segment boundaries reflect distinct engineering trade-offs between capital cost, auxiliary power consumption, and regulatory compliance burdens.
Product Type:
Upgrade cycles for aging substation infrastructure are driving differential replacement rates across cooling architectures, with efficiency mandates accelerating refresh timelines for legacy systems.
- Air-Cooled:Aluminum or copper fin-tube constructions with forced-air circulation dominate utility deployments due to elimination of water treatment infrastructure and lower auxiliary power draw. Demand concentrates in rural and semi-urban substations across India and the United States where ambient air capacity suffices for standard transformer loading profiles.
- Water-Cooled:Liquid-cooled circulation loops with shell-and-tube or plate heat exchanger configurations capture premium positioning in high-load-density urban substations. Frankfurt and Northern Virginia data center clusters are specifying these systems for medium-voltage transformers serving rectifier loads with elevated harmonic heating.
- Immersion:Direct dielectric fluid immersion coolers serve niche nuclear and high-reliability generation applications requiring minimal thermal gradient maintenance.
- Portable:Mobile cooling skids address emergency transformer overload scenarios and temporary grid reinforcement contracts.
Air-cooled systems sit at the top of the volume ranking, with water-cooled variants climbing the fastest as data center buildouts accelerate.
Installation Type:
Customer procurement preferences are hardening around pre-integrated configurations that compress site construction schedules and transfer integration risk to OEMs.
- Outdoor:Weather-hardened radiator banks and fan assemblies constitute the default specification for electric utility substations, with IEC 60076-7 thermal performance certification required for tender participation. Scandinavian utilities operating North Sea coastal infrastructure are driving demand for enhanced corrosion protection coatings compliant with REACH chemical restrictions.
- Skid-Mounted:Pre-assembled cooler-heat exchanger bundles on structural steel frames are displacing discrete component sourcing at major US investor-owned utilities. Texas and California grid operators favor these configurations for 15-year performance-based service agreements that absorb operational risk.
- Indoor:Compact footprint designs serve urban substation retrofits where land scarcity prevents radiator bank expansion, particularly in European city centers.
- Modular:Scalable cooling capacity blocks enable phased transformer upgrades without full system replacement, supporting China's high-speed rail electrification corridors.
Outdoor configurations retain the largest installed base, though skid-mounted procurement is expanding most quickly as utilities consolidate vendor relationships.
End User:
Thermal management requirements vary substantially across end-use sectors, with harmonic loading profiles and duty cycle intensity dictating cooler specification divergence.
- Utilities:Electric grid operators specify IEC 60076-compliant systems with 15-30 year design life for substation transformer fleets. EPA Clean Air Act mandates are forcing fan motor refresh cycles at aging US infrastructure.
- Data Centers:Hyperscale facilities represent the steepest expansion trajectory, with dedicated oil cooling loops for medium-voltage transformers managing rectifier harmonic heating.
- Renewable Energy:Wind and solar farm interconnection transformers require wide ambient temperature range operation and grid-code compliance for variable loading.
- Manufacturing Plants:Industrial power transformers in heavy process industries demand robust construction for contaminated atmospheres and continuous duty cycles.
Utilities anchor current volume, while data center deployments are gaining share fastest as cloud infrastructure investment accelerates.
Operational Efficiency:
Regulatory efficiency floors are segmenting supplier capabilities, with certification burdens filtering non-compliant participants from premium tender markets.
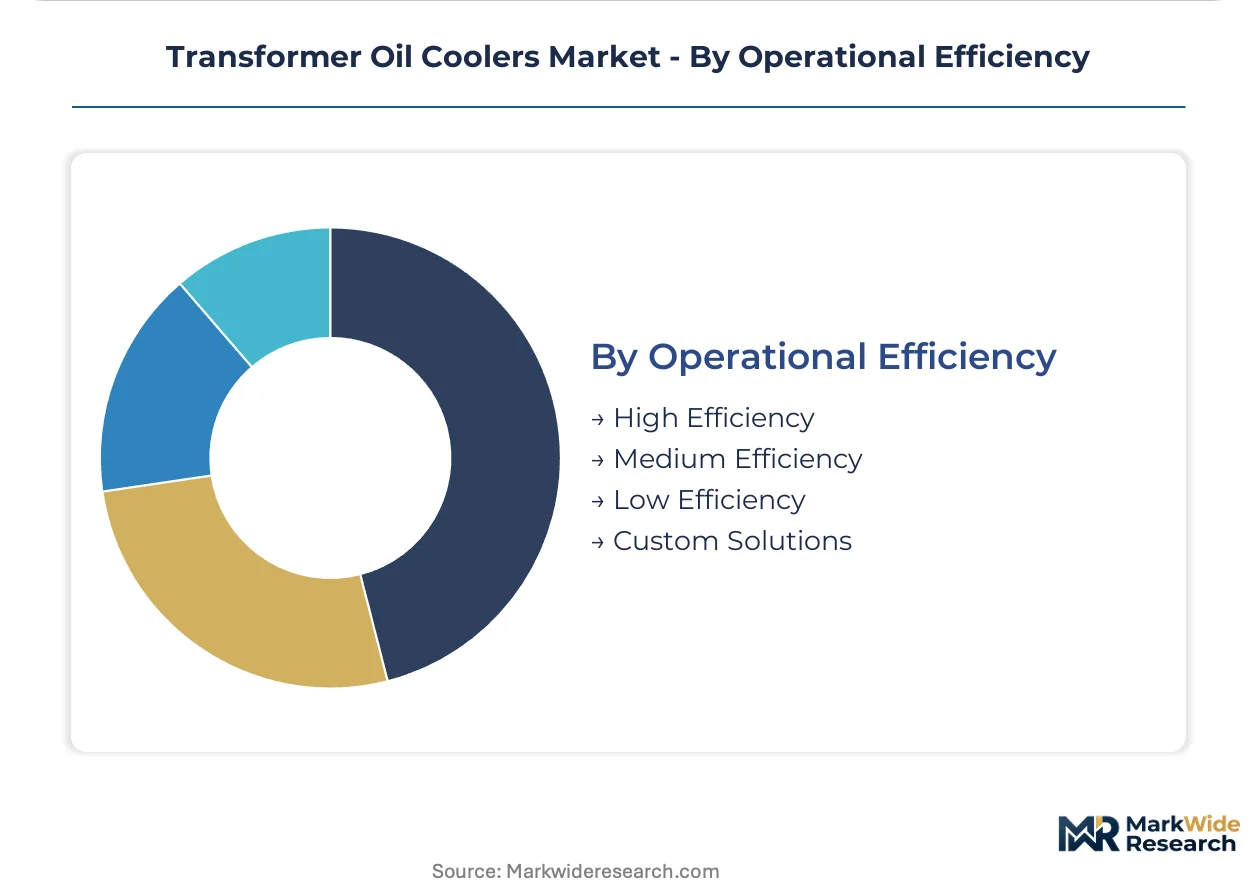
- High Efficiency:Advanced fan motor designs and optimized fin-tube geometries meet EPA efficiency regulations and EU F-Gas restrictions for lowest auxiliary power consumption. India's CEA technical regulations are creating qualification headroom for certified OEMs in this tier.
- Custom Solutions:Engineered-to-order thermal performance guarantees address site-specific constraints including seismic loading, altitude derating, and extreme ambient temperature ranges for specialized applications.
- Medium Efficiency:Standard utility specifications balance capital cost against operating expense for baseline substation deployments.
- Low Efficiency:Legacy replacement market serving price-sensitive maintenance budgets at aging infrastructure with minimal regulatory scrutiny.
High efficiency systems command premium positioning, with custom solutions expanding most rapidly as digital twin integration enables predictive thermal modeling contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transformer oil cooler industry traces its industrial lineage to early 20th-century European electrical engineering, with Siemens and AEG pioneering forced-air cooling systems for continental grid infrastructure. German metallurgical expertise established the copper fin-tube standards that still govern thermal performance benchmarks. Post-war electrification drives in North America and Asia subsequently scaled manufacturing capacity across multiple geographies.
United States
EPA Clean Air Act mandates are compelling utilities to replace legacy fan motors with high-efficiency models across aging substation infrastructure. FERC grid reliability standards reinforce thermal performance requirements for interconnection transformers. Northern Virginia data center clusters are specifying dedicated oil cooling loops for medium-voltage transformers managing rectifier harmonic loads.
Germany
Industrial transformer fleets in the Rhine-Ruhr manufacturing belt require cooler retrofits as efficiency regulations tighten. EU F-Gas Regulation phasedown timelines constrain water-cooled variant development for urban substation applications. Siemens Energy anchors advanced thermal management R&D in Erlangen, driving phase-change material pilot deployments at North Sea coastal substations.
China
High-speed rail electrification corridors are accelerating traction transformer cooling demand across the Yangtze River Delta. GB standards impose additional thermal testing burdens that filter non-compliant suppliers from state grid tenders. State Grid Corporation concentrates procurement in Beijing-Tianjin-Hebei for ultra-high voltage transformer infrastructure.
India
CEA technical regulations are filtering non-compliant suppliers from utility tenders, creating qualification headroom for certified OEMs. PLI scheme incentives support domestic manufacturing of high-efficiency cooling components. Maharashtra State Electricity Distribution Company leads substation modernization procurement in the Mumbai-Pune industrial corridor.
Japan
Grid operators are consolidating transformer procurement around pre-integrated cooling skids to compress vendor margins. METI efficiency guidelines shape product certification requirements for utility qualification protocols. Tokyo Electric Power Company drives demand for compact footprint designs in dense urban substation retrofits.
Transformer Oil Coolers Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive thermal engineering capabilities. Tiered supplier relationships persist, with premium positioning held by firms controlling critical component supply chains. Two strategic archetypes dominate: integrated heat exchange specialists and diversified transportation-industrial hybrids. Capacity expansion and backward integration into fan and pump subsystems represent the dominant competitive moves reshaping supplier positioning.
Within the diversified industrial tier, Wabtec Corporation and SPX Corporation exemplify archetypes blending transportation heritage with utility market penetration. Kelvion occupies a position as the European-anchored heat exchange pure-play. Commercial Coils, Inc. and Trantech Radiator Products represent North American fabrication specialists serving regional utility procurement networks. These named entities serve as structural anchors for understanding how geographic manufacturing footprints and component integration depth determine competitive positioning across tender markets.
| Leading Market Players |
|---|
| Commercial Coils, Inc. |
| Pro Dyne Corp. |
| Kelvion |
| Kooltronic, Inc. |
| Petro-Chem Industries |
| Wabtec Corporation |
| Quintel, Inc. |
| SPX Corporation |
| Trantech Radiator Products |
| Others |
Value Network & Pricing Analysis
EPA Clean Air Act mandates and EU F-Gas Regulation phasedown timelines gate qualified supply for premium-tier transformer oil cooler contracts, restricting tender participation to OEMs with certified high-efficiency fan motor designs and compliant thermal testing protocols. Utilities and data center operators now pay material premiums for pre-integrated skid-mounted configurations that transfer integration risk and absorb long-term operational liability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with IEC 60076-7 certification grade and copper versus aluminum fin-tube metallurgy driving tier placement. Cost compression in the economy tier intensifies because aluminum price volatility erodes margin predictability for air-cooled manufacturers serving price-sensitive Indian and Southeast Asian tenders. Data center operators exhibit lowest price sensitivity, prioritizing thermal performance guarantees and 15-year service agreements over capital expenditure minimization.
Supply Chain Analysis
Refurbishment flows for legacy transformer cooler fleets concentrate in Germany, China, and India, where aging substation infrastructure sustains aftermarket demand for fan motor replacements and radiator bank re-coring. Manufacturing draws from copper and aluminum sheet mills in China, precision fan motor suppliers in Germany, and corrosion-resistant coating formulators in Scandinavia. Single-source vulnerability runs through Chinese aluminum smelter concentration. Distribution runs through EPC contractors and utility procurement consortia rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transformer oil cooler market reads as a late-cycle quality story, with data center harmonic loading specifications and grid modernization thermal performance guarantees shifting procurement toward premium IEC 60076-certified systems with predictive maintenance integration.
For Market Incumbents: Acquire digital twin software capabilities and predictive thermal modeling assets to anchor 15-year performance-based service contracts. Kelvion and SPX Corporation should extend backward integration into fan and pump subsystems to defend margin position against Chinese OEMs exploiting aluminum cost advantages. CEA technical regulations in India and GB standards compliance in China represent critical certification moats requiring sustained engineering investment. For New Entrants and Emerging Players: India's CEA technical regulations open a window for certified European and Japanese OEMs to capture share from non-compliant local fabricators. Target data center cooling loops in Northern Virginia and Frankfurt, where rectifier harmonic heating specifications favor liquid-cooled expertise over legacy air-cooled incumbents. Pursue joint development agreements with hyperscale facility operators to embed cooling hardware within pre-integrated transformer skids. For Investors and Strategic Acquirers: Roll-up economics work for regional North American fabrication specialists with captive utility relationships because procurement consolidation around pre-integrated skids favors scaled service platforms over discrete component vendors. Five-to-ten-year viability hinges on software-thermal hardware convergence and condition-based maintenance contract penetration. Monitor EPA efficiency mandate enforcement intensity and F-gas restriction timeline acceleration as inflection indicators for cooler architecture preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fan and Pump Subsystems | Wabtec Corporation's captive supply control reduces component lead times for North American rail and utility customers. |
| Digital Twin Integration for Predictive Thermal Modeling | Condition-based maintenance contracts displace discrete equipment sales at Texas and California investor-owned utilities. |
| Phase-Change Material Thermal Buffer Deployment | European utilities pilot compact emergency overload capacity at land-constrained urban substations. |
| CEA Technical Regulation Certification Investment | Stringent Indian thermal testing protocols filter non-compliant suppliers from Maharashtra State Electricity Distribution Company tenders. |
| Skid-Mounted Pre-Integrated Configuration Expansion | Major US utilities consolidate vendor relationships around structural steel frame bundles that compress site construction schedules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, EPC contractor procurement leads, transformer OEM thermal engineering directors, and data center infrastructure executives with secondary validation against IEC 60076 certification databases, EPA Clean Air Act regulatory filings, FERC interconnection standards, and customs trade data for aluminum and copper heat exchange components. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Segment-weighting approaches modeled cooling architecture type, installation configuration, end-use sector, and operational efficiency tier across the analysis window. CAGRs derived from installed base replacement cycles, grid modernization capital expenditure trajectories, and data center power infrastructure buildout pipelines. Forecast inputs incorporated harmonic loading thermal profiles from rectifier-equipped medium-voltage transformers and regional regulatory compliance timeline shifts.
Revisions become necessary when EPA efficiency mandate enforcement accelerates, EU F-gas phasedown timelines compress, or aluminum price volatility exceeds historical bands. Forecasts reflect documented assumptions regarding utility procurement consolidation rates and hyperscale data center cooling specification standardization. Practitioners should monitor CEA technical regulation expansion to additional Indian states and METI efficiency guideline updates for early signals of qualification barrier elevation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Process Chillers Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Three Phase Cooling Fans Market