
 Global Overhead Line Conductors Market | 2026-2036
Global Overhead Line Conductors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Overhead Line Conductors Market Outlook
Power purchase agreement-backed project finance is reconfiguring how transmission developers procure conductor systems, shifting risk from balance sheets to long-term offtake structures. Prysmian Group leverages its vertically integrated aluminum smelting and stranding capacity to secure utility-scale contracts across multiple continents. Nexans sustains competitive positioning through specialized high-temperature conductor R&D programs focused on grid congestion relief. Sumitomo Electric Industries anchors its presence in Asian markets through dedicated manufacturing facilities serving national transmission operators.
Overhead line conductors are stranded metallic cables, typically aluminum alloy or copper with steel reinforcing cores, engineered to carry electrical current across transmission and distribution spans while maintaining mechanical tension under thermal and wind loading. ACSR (aluminum conductor steel reinforced) variants incorporate galvanized steel strands to achieve tensile strengths exceeding conventional aluminum designs for long-span river crossings and mountainous terrain. Composite technology segments incorporating carbon fiber cores are capturing premium margin pools as grid operators prioritize ampacity upgrades without tower replacement. Conventional conductor categories still dominate procurement volumes in emerging markets where cost sensitivity overrides performance specifications.
FERC interstate transmission rules in the United States, EU Green Deal grid interconnection mandates under the European Commission, and India's CEA technical standards for power system operation collectively enforce conductor performance benchmarks that determine market access. China's GB standards and NMPA-aligned quality certifications create additional compliance layers for suppliers targeting state grid tenders. Stakeholders must monitor evolving material substitution patterns as composite core validation data accumulates from multi-year field deployments.
Market Dynamics
Composite core conductor technology is compressing replacement cycles across transmission networks as grid operators seek ampacity gains without structural tower upgrades. Material substitution toward carbon fiber reinforced designs is redrawing competitive boundaries between conventional ACSR suppliers and advanced composite specialists.
Growth Catalysts
- EU Green Deal grid interconnection mandates:The European Commission's binding targets for cross-border transmission capacity are accelerating conductor procurement for interconnector projects spanning member states.
- India's CEA technical standards:India's Central Electricity Authority mandates for power system operation are forcing distribution utilities to replace aging conductor inventory with higher-efficiency alternatives.
- Utility-scale renewable integration:Wind and solar farm developers in China, India, and the United States are procuring high-temperature low-sag conductors to connect remote generation sites to load centers.
Market Restraints
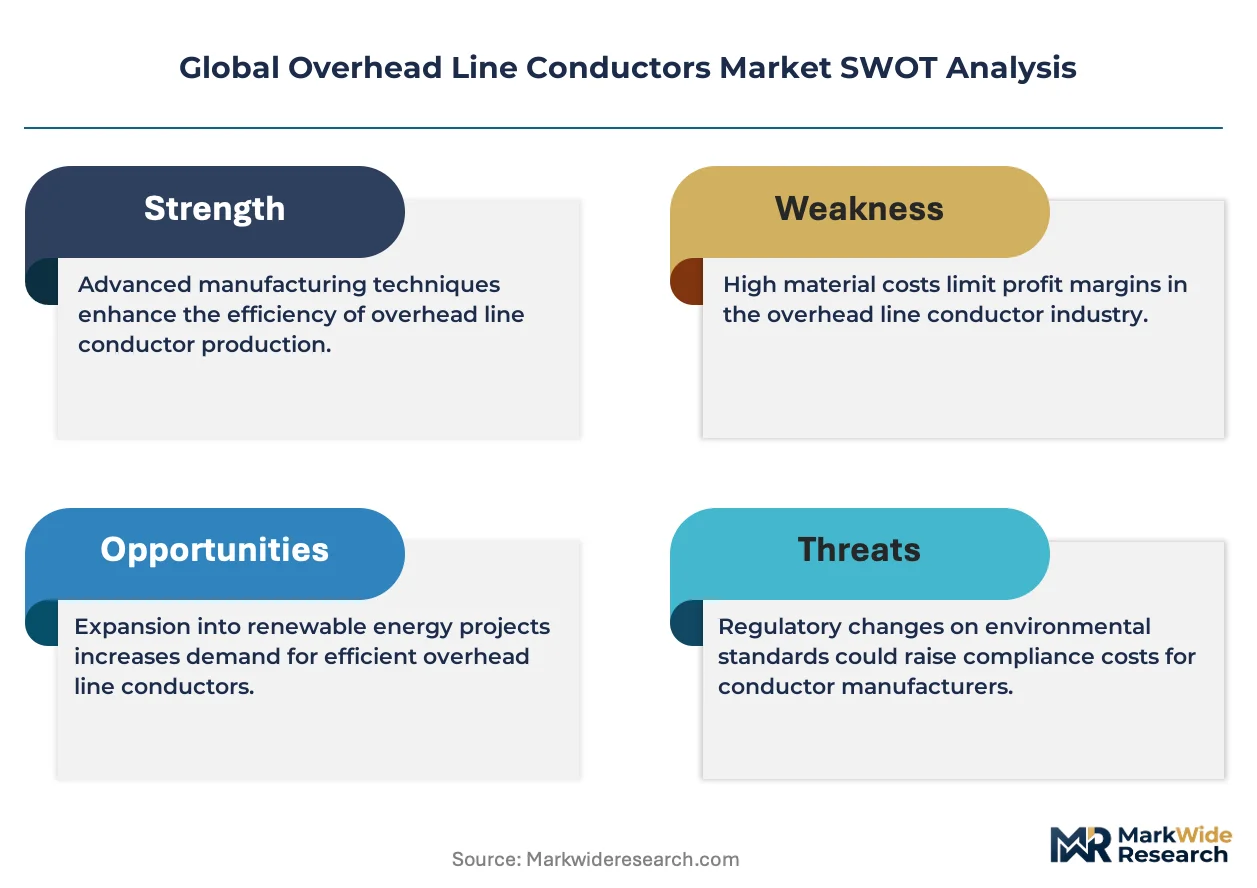
- Aluminum price volatility:Primary aluminum input costs fluctuate with energy pricing and smelter curtailments, compressing margins for stranded conductor manufacturers without backward integration into metal production.
- Composite core supply concentration:Carbon fiber and glass fiber core production concentrates among specialized Japanese and European suppliers, creating bottleneck risk for conductor assemblers scaling advanced product lines.
- ACSR technical ceiling:Conventional aluminum conductor steel reinforced designs face absolute ampacity limits that prevent their use on congested corridors requiring thermal upgrade without right-of-way expansion.
Strategic Opportunities
- Brazil transmission expansion:The country's national grid operator is tendering thousands of kilometers of new lines to connect Amazon basin hydroelectric projects to southeastern load centers.
- Power purchase agreement-backed procurement:Long-term offtake contracts are enabling developers to finance premium conductor specifications that balance-sheet-constrained utilities cannot justify.
- High-temperature conductor retrofit:Existing ACSR corridors in the United States and Germany present addressable upgrade potential where tower structures permit higher-temperature operation with composite core replacement.
Industry Challenges
- Composite core field validation:Multi-year performance data from operational deployments remains sparse, slowing utility adoption cycles and complicating warranty underwriting for manufacturers.
- Stranding equipment retooling:Conductor producers must reconfigure production lines to handle brittle composite cores, requiring capital outlays that strain mid-tier manufacturers.
- GB standards compliance complexity:China's national standards and NMPA-aligned quality certifications impose testing protocols that foreign suppliers struggle to navigate for state grid tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Overhead Line Conductors Market |
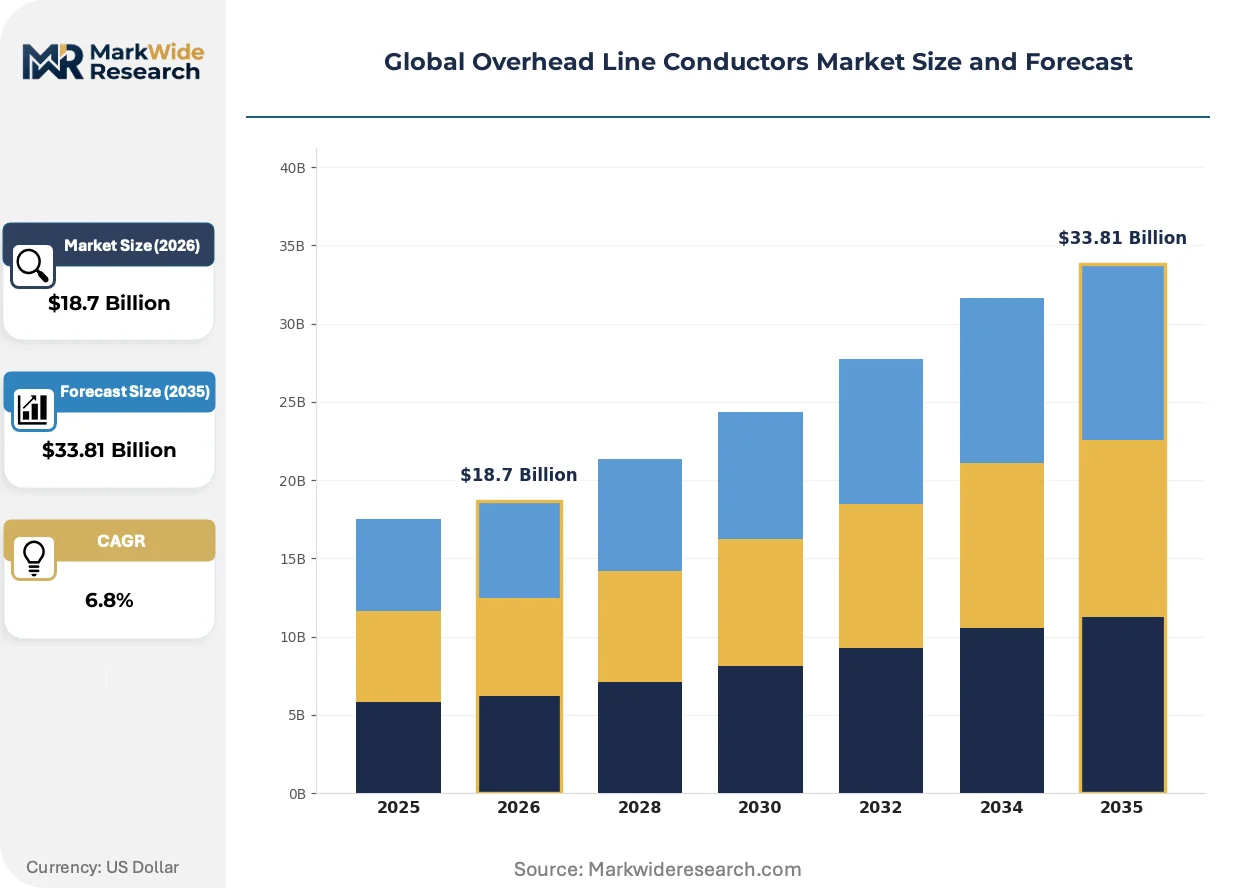
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Conductor, Copper Conductor, Steel Reinforced Conductor, ACSR Technology: Conventional, Composite, Superconducting, Smart Grid Installation Type: Overhead, Underground, Hybrid, Direct Burial End User: Utilities, Industrial, Residential, Commercial |
| Companies Covered | Prysmian Group, Nexans, Sumitomo Electric Industries, LS Cable & System, Southwire Company, KEI Industries, Lamifil, NKT A/S, Taihan Electric Wire & Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Overhead Line Conductors Market Strategic Shifts
Active material science development is reconfiguring conductor core options beyond traditional steel and emerging carbon fiber toward hybrid and recycled-content alternatives. These innovations intersect with tightening regulatory performance benchmarks and evolving procurement risk allocation models.
Carbon fiber composite core technology is migrating from niche demonstration projects to mainstream transmission corridor upgrades. Regional transmission organizations in Texas and the PJM interconnection are specifying ACCC and ACSS conductor variants for congestion relief projects. This technology is compressing the cost premium against reconductored routes by eliminating tower replacement expenses.
FERC interstate transmission rules in the United States are mandating cost allocation reforms that spread conductor investment across beneficiary ratepayers. The regulatory shift is unlocking previously stalled transmission projects by resolving stakeholder disputes over who pays for grid expansion. Merchant transmission developers in the Southwest Power Pool are responding with innovative financing structures that securitize conductor procurement against future congestion revenue.
Long-term service agreements are displacing transactional equipment sales as the dominant commercial model for high-performance conductor categories. European transmission system operators in Germany and France are bundling installation, monitoring, and thermal rating verification into decade-spanning contracts. This pattern is most visible in offshore wind connection projects where cable and conductor reliability directly affects generation revenue.
Global Overhead Line Conductors Market Segmentation
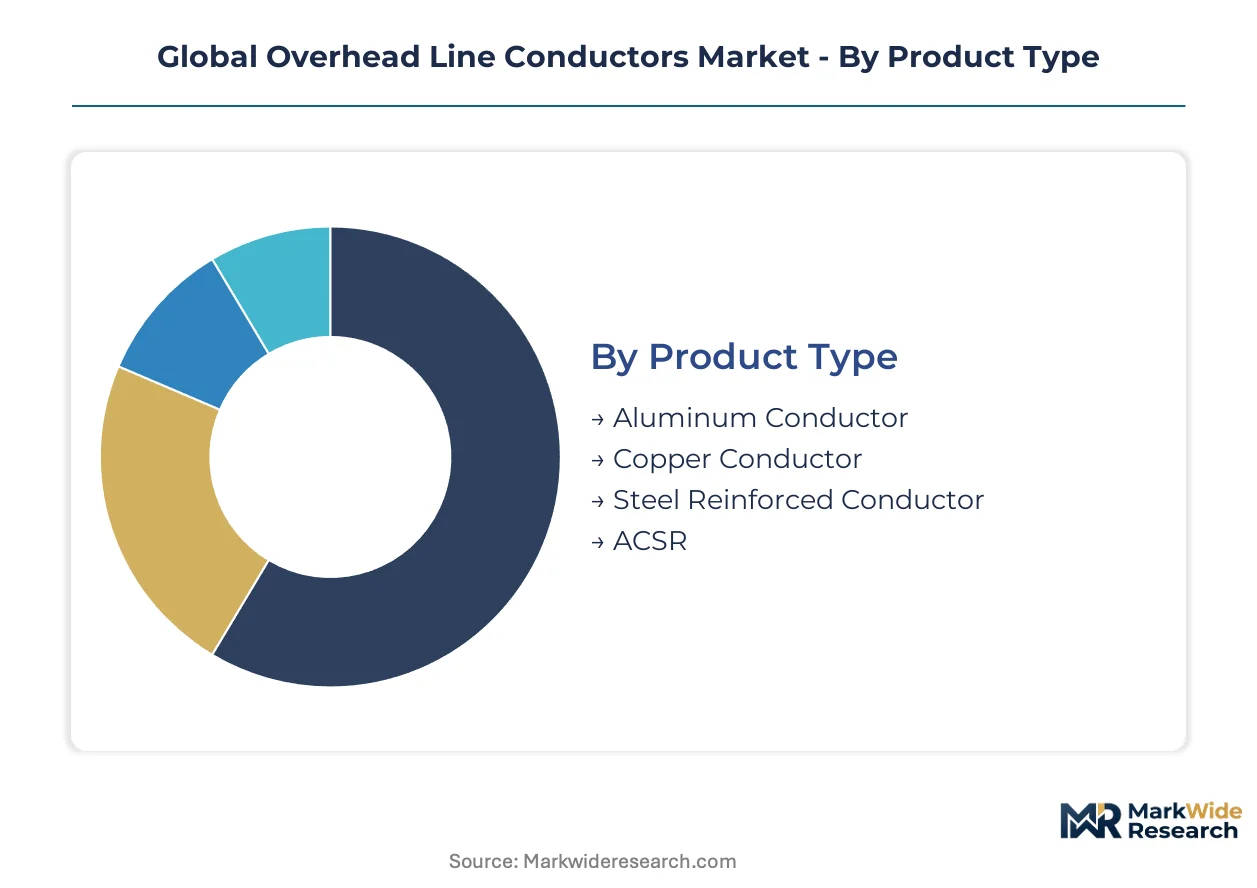
Overhead line conductor procurement diverges sharply across technical specifications and deployment contexts. Each segmentation axis reveals distinct margin structures, installation complexity, and aftermarket service requirements that shape supplier economics.
Product Type:
After-sales intensity varies dramatically by conductor metallurgy and core construction, with composite designs demanding specialized inspection protocols and steel-reinforced variants requiring corrosion monitoring over multi-decade service lives.
- Aluminum Conductor:Stranded aluminum alloy designs dominate transmission procurement due to favorable conductivity-to-weight ratios and cost positioning against copper alternatives. Chinese state grid tenders and Indian transmission expansions are absorbing the highest volumes as both countries prioritize cost-efficient bulk procurement for rural electrification corridors.
- Steel Reinforced Conductor:Galvanized steel core integration delivers tensile strength exceeding 200 ksi for long-span applications including river crossings and mountainous terrain. Brazil's Amazon basin interconnections and the Himalayan corridors in India specify these variants where mechanical loading constraints override pure conductivity optimization.
- ACSR:Aluminum conductor steel reinforced configurations balance conductivity and mechanical performance through concentric layer construction. Field-proven reliability sustains preference among conservative procurement specifications.
- Copper Conductor:Superior conductivity and corrosion resistance command premium positioning in distribution networks and specialized industrial feeds. Higher material costs restrict deployment to short-span, high-density urban applications.
Aluminum conductor holds the largest share; momentum sits with steel reinforced conductor as emerging market transmission spans lengthen.
Technology:
Technology selection directly determines capital recovery timelines, with conventional designs offering lowest first cost and composite variants trading upfront premium against avoided tower replacement expenses.
- Conventional:Established ACSR and all-aluminum designs rely on century-old stranding techniques and standardized core materials. Procurement concentrates in cost-sensitive emerging markets where utilities prioritize lowest evaluated price over lifecycle performance.
- Composite:Carbon fiber and glass fiber core technologies enable high-temperature low-sag operation at double conventional ampacity ratings. PJM and ERCOT congestion relief projects in the United States are specifying ACCC and GAP conductor variants where reconductoring without right-of-way expansion delivers the only viable upgrade path.
- Superconducting:Cryogenic cooling requirements and specialized termination hardware restrict deployment to urban density corridors and scientific installations. Demonstration projects in Germany and Japan validate technical feasibility.
- Smart Grid:Embedded fiber optic sensing and real-time thermal monitoring transform conductors into dynamic grid assets. European TSOs in France and Germany bundle these capabilities into long-term service agreements spanning installation through performance verification.
Conventional technology commands installed base dominance; composite designs are gaining share fastest as reconductoring economics improve.
Installation Type:
Installation methodology shapes logistics complexity, with overhead deployment requiring specialized stringing equipment and underground alternatives demanding trenching coordination with civil infrastructure.
- Overhead:Suspended conductor systems on lattice or monopole towers constitute the overwhelming majority of high-voltage transmission capacity. China's State Grid and India's Power Grid Corporation are deploying thousands of kilometers annually across challenging terrain.
- Underground:XLPE-insulated high-voltage cables substitute for overhead lines in urban corridors and environmentally sensitive areas. German cities and Swiss alpine regions mandate undergrounding for visual impact mitigation.
- Hybrid:Mixed overhead-underground configurations optimize cost and reliability for corridor segments with varying constraints. Coastal wind farm connections in the United Kingdom deploy hybrid architectures.
- Direct Burial:Unconventional for high-voltage transmission due to thermal dissipation challenges; limited to distribution voltage classes and specialized industrial feeds.
Overhead installation retains overwhelming volume leadership; underground approaches are expanding most quickly in European urban densification zones.
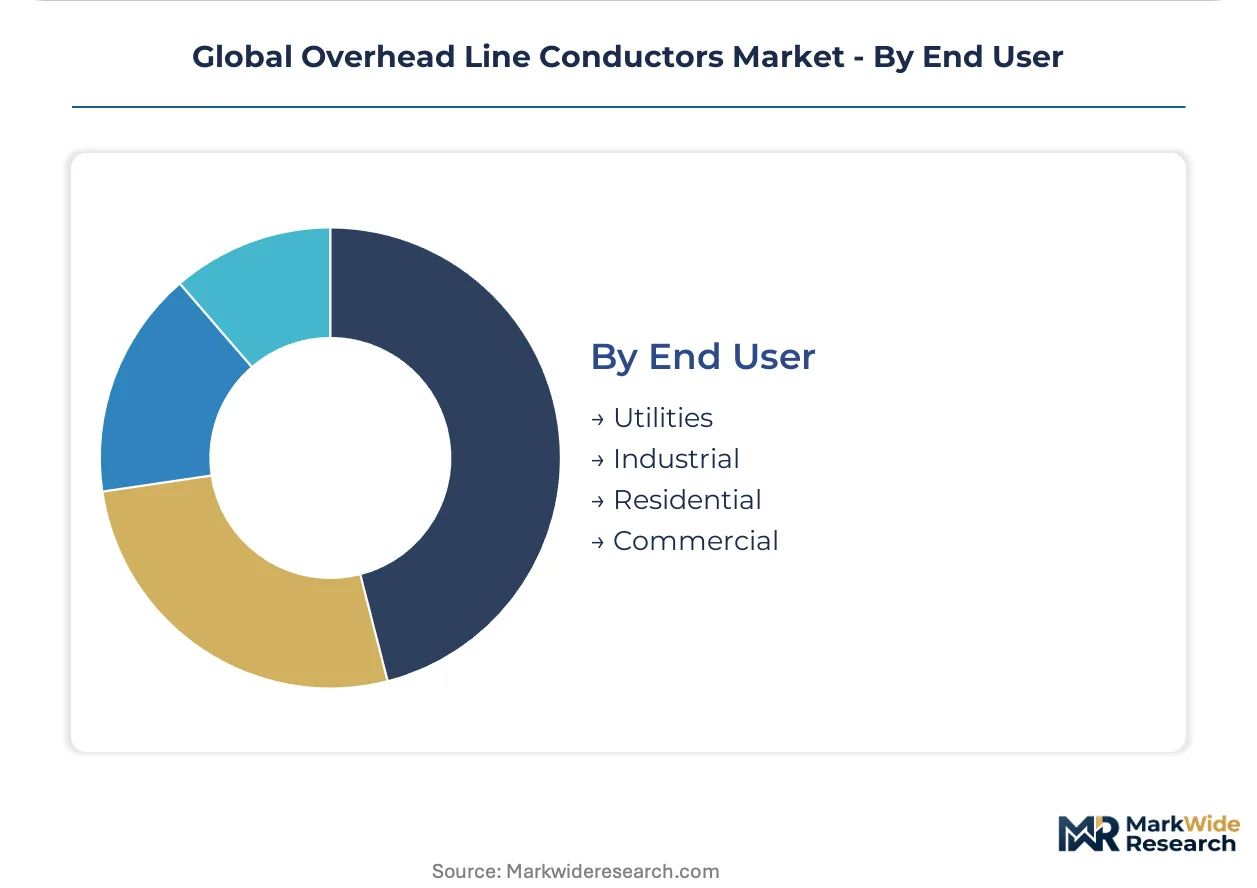
End User:
End user category determines procurement sophistication, with utilities operating centralized technical specifications and industrial buyers prioritizing reliability guarantees over standardized catalog offerings.
- Utilities:Transmission and distribution system operators specify conductor systems through formal tender processes with multi-year performance warranties. India's CEA mandates and FERC cost allocation rules in the United States shape procurement frameworks.
- Industrial:Mining, smelting, and petrochemical facilities procure dedicated feeder lines with customized ampacity and fault current specifications. Brazilian mining corridors and Middle Eastern desalination complexes represent concentrated demand.
- Residential:Distribution-level conductor procurement flows through utility intermediaries rather than direct consumer purchase. Rural electrification programs in sub-Saharan Africa and Southeast Asia drive aggregate volume.
- Commercial:Data centers, logistics hubs, and commercial developments require redundant feeder configurations with premium reliability specifications. Hyperscale cloud providers in Northern Virginia and Frankfurt specify conductor redundancy in campus designs.
Utilities absorb the dominant procurement volume; industrial end users are climbing the fastest as captive generation and direct grid connections proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese composite core supply chains while Chinese state grid tenders compress margins for conventional ACSR producers. Regulatory divergence between FERC cost allocation reforms and EU Green Deal mandates is fragmenting procurement standards across major demand centers.
China
State Grid Corporation tenders absorb the highest global procurement volumes for rural electrification corridors and ultra-high-voltage transmission. GB standards and NMPA-aligned quality certifications impose testing protocols that foreign suppliers struggle to navigate. Yangtze River Delta manufacturing clusters produce stranded aluminum for domestic grid expansion and Belt and Road export contracts.
United States
ERCOT and PJM regional transmission organizations specify ACCC conductor variants for congestion relief projects across Texas and Mid-Atlantic corridors. FERC interstate transmission rules mandate cost allocation reforms spreading conductor investment across beneficiary ratepayers. Merchant developers in the Southwest Power Pool securitize procurement against future congestion revenue streams.
Germany
Transmission system operators bundle installation, monitoring, and thermal rating verification into decade-spanning service agreements for offshore wind connections. EU Green Deal grid interconnection mandates accelerate conductor procurement for cross-border projects spanning member states. Industrial clusters in Bavaria and North Rhine-Westphalia anchor composite core R&D and stranding equipment manufacturing.
India
Power Grid Corporation deploys thousands of kilometers annually across Himalayan corridors and peninsula transmission networks. CEA technical standards for power system operation force distribution utilities to replace aging conductor inventory with higher-efficiency alternatives. Gujarat and Maharashtra state utilities lead procurement volumes for renewable integration projects connecting solar parks to load centers.
Brazil
National grid operator ONS tenders thousands of kilometers of new lines to connect Amazon basin hydroelectric projects to southeastern load centers. ANVISA-aligned quality protocols govern material certification for utility-scale procurement. São Paulo and Minas Gerais industrial corridors concentrate domestic stranding capacity serving mining and petrochemical feeder line demand.
Global Overhead Line Conductors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream feeding raw aluminum and carbon fiber cores into assembly operations. The vendor base organizes around three tiers: vertically integrated cable conglomerates with captive smelting capacity, mid-scale regional stranding specialists, and technology-focused composite core developers. Strategic moves concentrate on backward integration into aluminum production and licensing agreements for high-temperature conductor designs.
Among European cable conglomerates, Prysmian Group and Nexans occupy positions exemplifying the integrated platform archetype with captive metal production and multi-continent utility relationships. Sumitomo Electric Industries anchors the Asia-Pacific tier through dedicated manufacturing facilities serving national transmission operators. These three entities represent contrasting geographic anchoring strategies while competing for premium composite core contracts in deregulated procurement environments.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Sumitomo Electric Industries |
| LS Cable & System |
| Southwire Company |
| KEI Industries |
| Lamifil |
| NKT A/S |
| Taihan Electric Wire & Cable |
| Others |
Value Chain & Pricing Dynamics
Japanese and European carbon fiber core production concentrates among Toray, Teijin, and SGL Carbon, anchoring margin capture upstream while conductor assemblers downstream face margin compression from aluminum price volatility and utility procurement standardization.
Pricing Analysis
Configured-to-order pricing for composite core conductors commands spreads exceeding standard ACSR quotations by multiples, reflecting carbon fiber core premiums and specialized stranding labor. Three-tier pricing structure across premium composite, high-temperature steel-reinforced, and economy ACSR levels segments buyer archetypes, with merchant transmission developers least price-sensitive due to congestion revenue securitization and emerging market utilities most sensitive due to tender-based lowest-evaluated-price mandates. Pricing pressure stems from Chinese state grid procurement centralization compressing margins for conventional stranded products.
Supply Chain Analysis
Primary aluminum smelting concentrates in China, Russia, and Canada, with Chinese Yangtze River Delta clusters feeding both domestic grid expansion and Belt and Road export contracts. Carbon fiber cores draw from Japanese and European specialized suppliers, while galvanized steel strands rest on Indian and Turkish wire rod capacity. Single-source vulnerability sits with carbon fiber precursor acrylonitrile supply. Distribution runs through EPC contractors and national transmission operator tender processes, with long-term offtake agreements displacing spot procurement for high-performance categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in composite core retrofit corridors where incumbent ACSR suppliers lack technical capabilities and emerging specialists can capture reconductoring premiums without greenfield tower competition.
For Market Incumbents: Entrench through captive aluminum smelting integration and dedicated composite core R&D licensing agreements with Japanese carbon fiber suppliers. Prysmian Group's vertically integrated metal production and Nexans' high-temperature conductor programs exemplify defensive positioning against emerging composite specialists threatening premium segment share. Certification investment in China's GB standards compliance creates moats for state grid tender access.
For New Entrants and Emerging Players: United States PJM and ERCOT congestion relief corridors represent the most penetrable entry point for ACCC and GAP conductor specialists without incumbent utility relationships. Brazil's Amazon basin transmission expansion tenders offer second-mover opportunity for composite core assemblers with project finance backing. Direct engagement with merchant transmission developers bypasses utility procurement gatekeeping.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional stranding specialists in India and Southeast Asia lacking composite core capabilities but holding utility relationships. Long-term viability hinges on technology licensing access rather than scale economies. Watch composite core field validation data accumulation from operational deployments as inflection indicator for utility adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Prysmian Group's captive metal production secures cost positioning against volatile LME pricing. |
| Composite Core Technology Licensing | CTC Global's ACCC conductor patents enable specialized assemblers to bypass in-house R&D capital intensity. |
| Long-term Service Agreement Bundling | German TSOs decade-spanning installation and monitoring contracts transform transactional equipment sales. |
| GB Standards Compliance Investment | Foreign suppliers navigating China's NMPA-aligned certifications unlock State Grid tender participation. |
| Merchant Transmission Developer Partnership | Southwest Power Pool securitization structures enable premium conductor procurement without utility balance sheet constraints. |
Study Parameters
Operator-level perspectives from transmission planning officers at regional grid organizations, EPC contractor procurement leads, conductor manufacturer sales directors, and carbon fiber core supplier technical managers anchored the qualitative base. Secondary validation drew from FERC interstate transmission filings, EIA grid infrastructure databases, EU Green Deal implementation progress reports, and India's CEA technical standard notifications. Bottom-up project pipeline aggregation across announced transmission expansions triangulated against top-down macro grid investment forecasts.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product metallurgy, core technology, installation methodology, and end-user procurement sophistication. CAGRs derived from regression analysis against historical grid investment cycles and renewable integration policy intensity. Forecast inputs incorporated aluminum price trajectory assumptions and composite core cost-down curves from manufacturing scale effects.
Macroeconomic conditions sit as an overlay; deviation in energy pricing affecting smelter economics or trade policy disrupting carbon fiber core logistics would shift the trajectory. Material shifts in FERC cost allocation rule implementation or EU Green Deal grid interconnection mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Pantograph Disconnector Market